
 Asia Pacific Automotive Logistics Market | 2026-2036
Asia Pacific Automotive Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive Logistics Market Analysis
Real-time telematics integration across multimodal fleets is reshaping how automotive parts and finished vehicles move through Asia Pacific corridors. DHL leverages its Asia-Pacific air freight network to compress lead times for just-in-time component deliveries to Japanese and Korean assembly plants. Yusen Logistics anchors its competitiveness through dedicated vehicle processing centers at major Chinese and Southeast Asian ports. Nippon Express sustains dominance in domestic Japanese automotive logistics through rail-road intermodal solutions tied to OEM production schedules.
Asia Pacific automotive logistics encompasses the planning, execution, and control of vehicle and component flows across road, rail, sea, and air modes, typically operating within tolerance windows of 15-30 minutes for JIT assembly line feeds. Freight forwarding commands premium margins where ocean and air coordination complexity rises for cross-border component sourcing from ASEAN to China and India. Warehousing is expanding fastest around EV battery storage requirements, with temperature-controlled facilities and hazardous materials certifications becoming mandatory for lithium-ion cell inventories. Finished vehicle transportation retains the largest revenue pool, driven by rising passenger vehicle exports from China and Thailand to Middle Eastern and African markets.
China's MIIT enforces dual carbon targets that mandate cleaner logistics fleets, while India's PLI scheme conditions automotive manufacturing incentives on localized supply chain density. Japan's METI coordinates with JIS standards bodies to impose traceability requirements on automotive parts logistics documentation. Stakeholders must monitor how ASEAN harmonization of cross-border road transport permits affects hub-and-spoke network economics against direct port-to-plant delivery models.
Market Dynamics
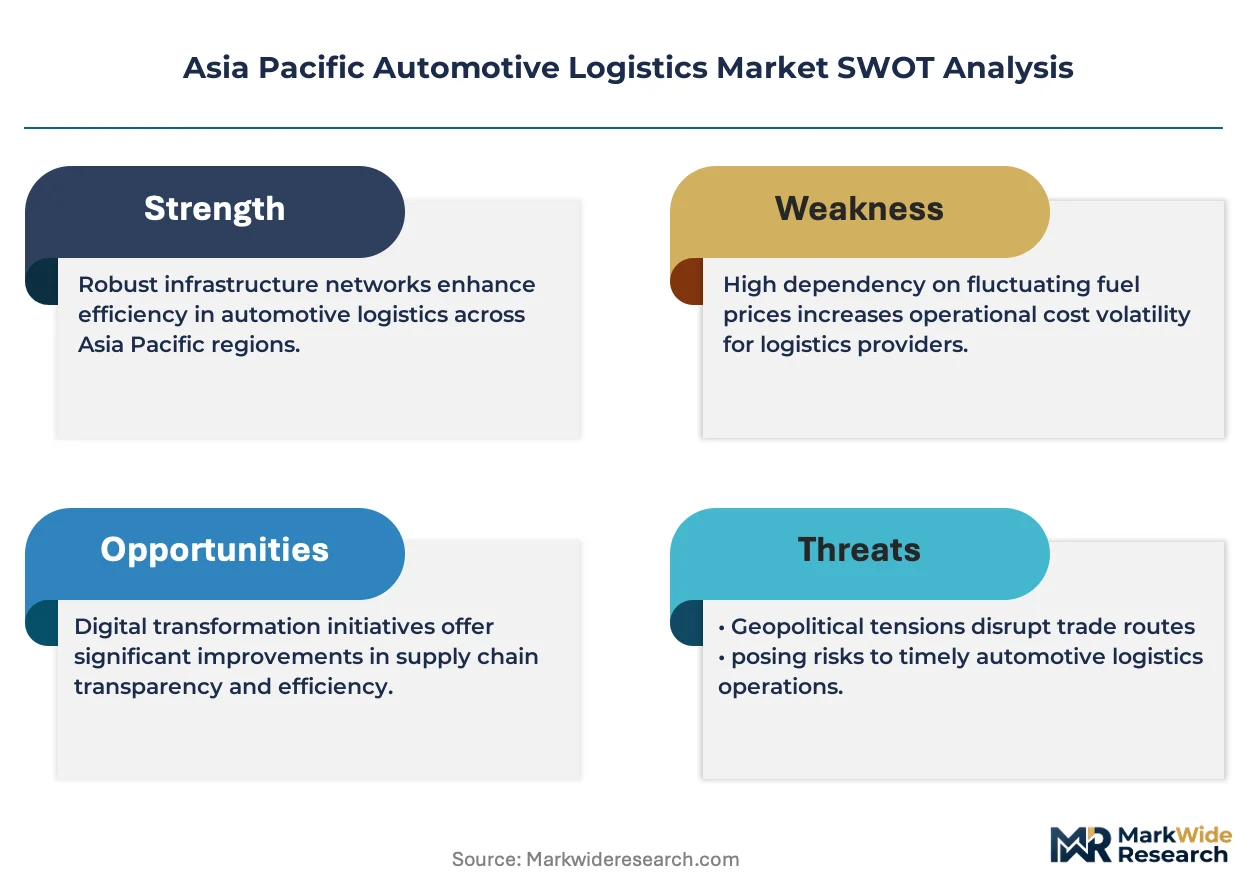
Electric vehicle battery logistics is compressing warehouse specifications and multimodal handoff protocols across Asia Pacific corridors, forcing 3PLs to retrofit facilities for hazardous materials compliance and thermal stability.
Growth Catalysts
- China's MIIT dual carbon mandates:Fleet electrification requirements for commercial transport are accelerating demand for EV charging infrastructure at logistics hubs throughout the Yangtze River Delta.
- Thailand's Eastern Economic Corridor:Concentrated OEM assembly investments are creating integrated supplier parks that reduce inbound component lead times to under four hours.
- Lithium-ion cell traceability systems:Blockchain-enabled chain-of-custody documentation is becoming mandatory for cross-border battery shipments under Japan's METI coordination with JIS standards bodies.
Market Restraints
- Port congestion at Shanghai and Ningbo:Container vessel queuing creates 7-14 day delays for automotive component imports, disrupting just-in-sequence delivery commitments to assembly plants.
- Semiconductor logistics bottlenecks:Specialized cold-chain and anti-static handling requirements for chip consignments limit carrier flexibility and inflate unit transport costs.
- ASEAN permit fragmentation:Non-harmonized cross-border road transport licensing forces multi-day customs holds at Thailand-Malaysia and Vietnam-Cambodia frontier crossings.
Strategic Opportunities
- Vietnam's northern industrial zones:Underdeveloped automotive supplier density creates first-mover advantage for integrated logistics park development around Haiphong port corridors.
- Battery recycling reverse logistics:End-of-life EV cell collection networks remain nascent, opening dedicated return-loop infrastructure partnerships with OEMs.
- India's PLI scheme localization thresholds:Component sourcing mandates are compelling tier-1 suppliers to establish captive warehousing within 50 kilometers of Chennai and Pune assembly clusters.
Industry Challenges
- Hazmat certification scarcity:Qualified lithium-ion battery handling specialists remain concentrated in China and Japan, creating wage inflation and training bottlenecks for Southeast Asian facility expansions.
- Legacy WMS integration:Warehouse management systems deployed for conventional automotive parts lack lot-traceability granularity required for EV battery cell tracking under emerging safety protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive Logistics Market |
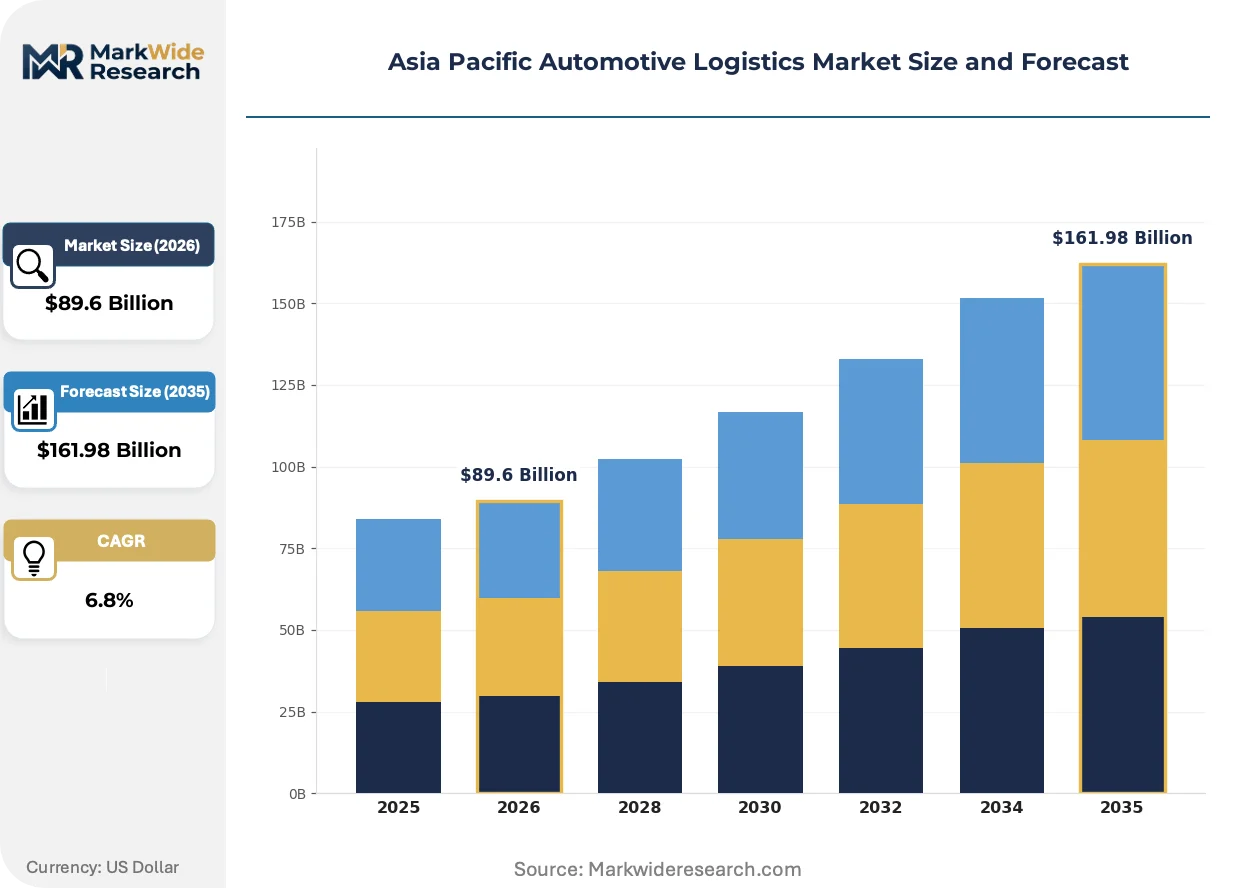
| Market Size in 2026 | $89.6 Billion |
| Market Size in 2035 | $161.98 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Packaging End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Logistics Companies Delivery Mode: Road, Rail, Sea, Air Product Type: Finished Vehicles, Components, Spare Parts, Raw Materials |
| Companies Covered | DB Schenker, DHL, Kuehne + Nagel, CEVA Logistics, DSV, GEODIS, Nippon Express, Yusen Logistics, Hitachi Transport System, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive Logistics Market Emerging Trajectories
Autonomous yard management and predictive port scheduling are compressing dwell times at automotive logistics nodes. Real-time visibility platforms now coordinate multimodal handoffs with precision previously unattainable through manual dispatch.
Digital twin simulation of port-to-plant corridors is rendering obsolete static routing schedules that failed to account for vessel delays, customs variability, and road congestion. Japanese OEMs are deploying these systems across their Thailand and Indonesia supplier networks. The technology enables dynamic rerouting decisions that protect assembly line continuity without safety stock accumulation.
China's MIIT enforcement of dual carbon targets is mandating electric truck penetration in commercial fleets serving automotive manufacturing zones. Logistics providers must phase out diesel tractors or forfeit operating licenses in designated low-emission zones. Battery-swapping infrastructure at major ports is emerging as the dominant compliance pathway given charging time constraints.
Consolidation of procurement authority among Chinese EV manufacturers is displacing fragmented supplier-managed inventory arrangements. BYD and NIO now dictate inbound logistics terms through centralized 4PL contracts covering tier-2 and tier-3 component flows. This concentration shifts working capital burdens upstream while demanding granular shipment visibility from smaller suppliers.
Asia Pacific Automotive Logistics Market Segmentation
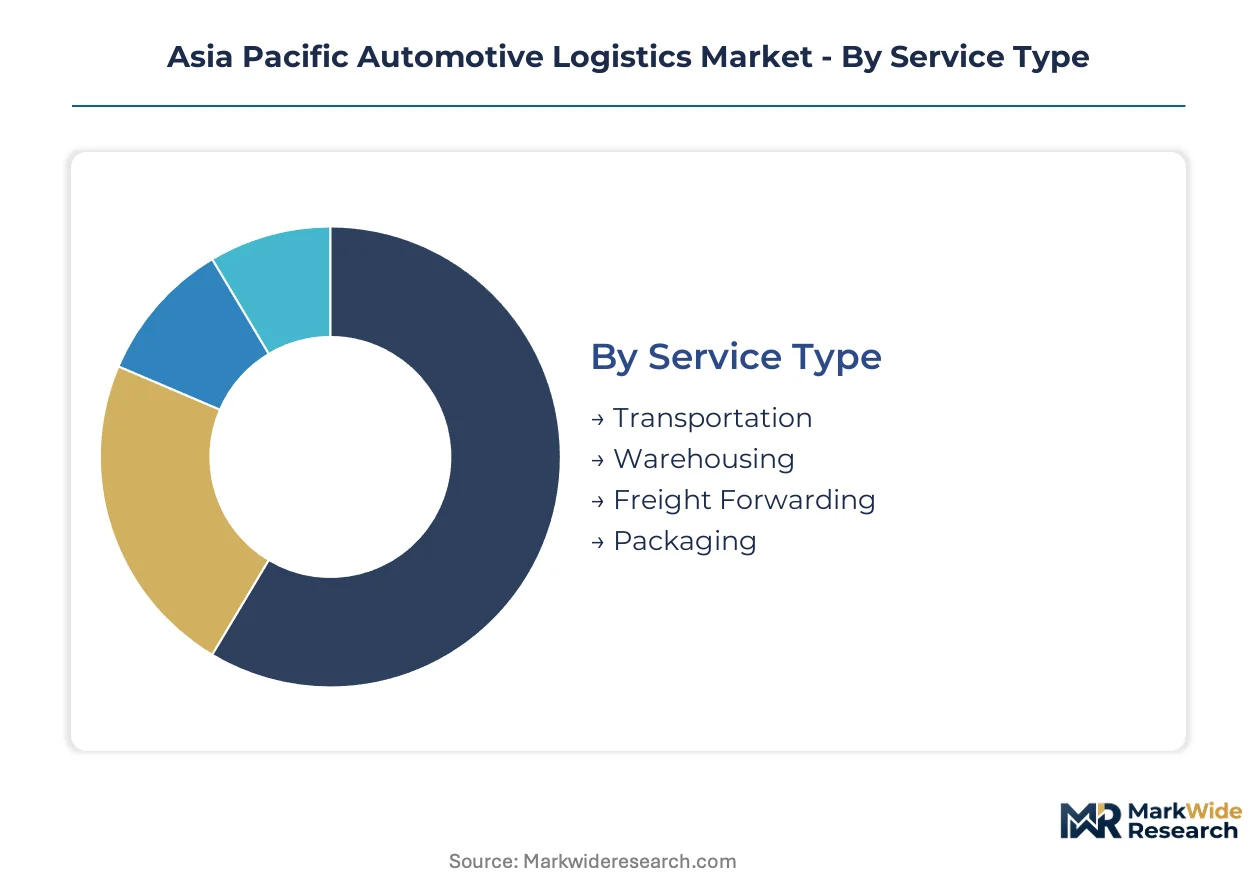
Asia Pacific automotive logistics operates through four distinct segmentation dimensions that govern capital allocation and operational design. Service type determines margin structure and asset intensity. End user classification shapes contract terms and inventory liability. Delivery mode and product type together dictate network topology and compliance requirements across the region's manufacturing corridors.
Service Type:
Cost tier separates asset-heavy operations from coordination-intensive services, with capital requirements scaling dramatically across the spectrum.
- Transportation:Fleet-based road haulage and specialized vehicle carriers dominate revenue pools, with China-based operators commanding density advantages across the Yangtze River Delta automotive cluster. Japanese and Korean OEMs impose 15-30 minute JIT tolerance windows that compress route optimization requirements and elevate technology investment thresholds.
- Warehousing:Temperature-controlled facilities with hazardous materials certifications are becoming mandatory for lithium-ion battery storage, particularly around China's MIIT dual carbon enforcement zones. EV battery inventory protocols are displacing conventional parts storage specifications across existing facilities.
- Freight Forwarding:Ocean-air coordination for cross-border component sourcing from ASEAN to China and India commands premium margins where customs complexity and multimodal handoffs intersect.
- Packaging:Returnable container systems and anti-static semiconductor packaging represent specialized subsegments with concentrated supplier bases.
Transportation commands the established base. The steepest expansion runs through warehousing as EV battery storage requirements proliferate.
End User:
Application type determines inventory ownership, visibility requirements, and working capital allocation across the value chain.
- OEMs:Centralized procurement authority at BYD and NIO is displacing fragmented supplier-managed inventory arrangements, shifting working capital burdens upstream while demanding granular shipment visibility from tier-2 and tier-3 suppliers.
- Tier-1 Suppliers:India's PLI scheme localization thresholds are compelling captive warehousing establishment within 50 kilometers of Chennai and Pune assembly clusters, reshaping network design priorities.
- Aftermarket Providers:Spare parts distribution requires distinct inventory velocity management compared to production logistics, with reverse logistics integration becoming a competitive differentiator.
- Logistics Companies:Third-party and fourth-party providers are consolidating procurement authority through centralized contracts covering multi-tier component flows.
OEMs anchor the revenue foundation. The fastest share gains are concentrating among tier-1 suppliers responding to localization mandates.
Delivery Mode:
Volume and distance economics shape modal selection, with corridor-specific infrastructure determining feasible alternatives.
- Road:Dominates intraregional distribution within manufacturing clusters, though diesel fleet phaseout requirements under China's MIIT dual carbon targets are accelerating electric truck adoption and battery-swapping infrastructure deployment.
- Rail:Nippon Express sustains competitive positioning through rail-road intermodal solutions tied to OEM production schedules across Japan's domestic corridors.
- Sea:Finished vehicle exports from China and Thailand to Middle Eastern and African markets retain the largest revenue pool, though port congestion at Shanghai and Ningbo creates 7-14 day delays disrupting delivery commitments.
- Air:Compresses lead times for just-in-time component deliveries to Japanese and Korean assembly plants, with DHL leveraging Asia-Pacific air freight networks for premium service tiers.
Road retains the volume base. The most rapid infrastructure investment is flowing into sea corridors as Chinese and Thai export capacity expands.
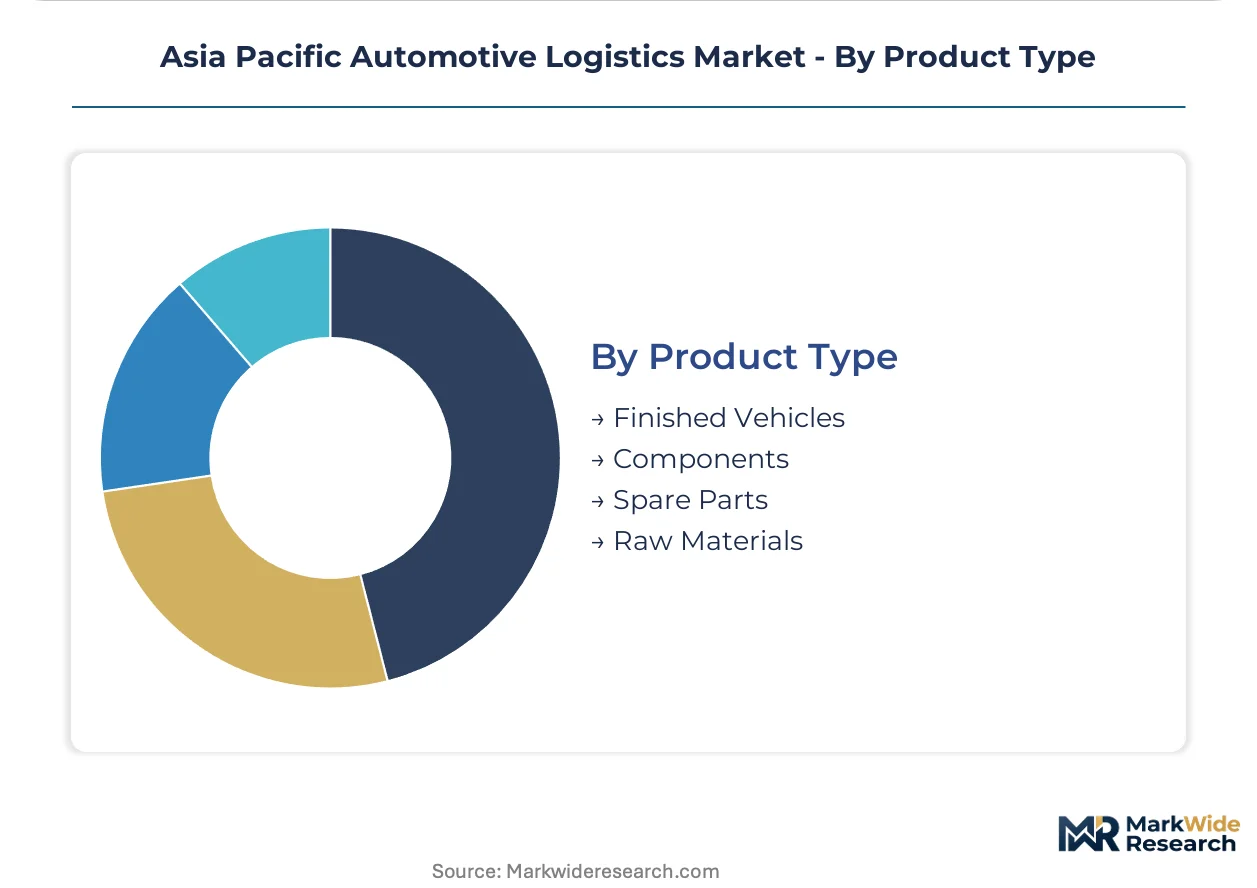
Product Type:
Maturity and handling requirements differentiate segments, with emerging product categories demanding specialized capabilities.
- Finished Vehicles:Roll-on/roll-off vessel capacity and dedicated vehicle processing centers at major Chinese and Southeast Asian ports anchor Yusen Logistics's competitive positioning.
- Components:Just-in-sequence delivery requirements for assembly line feeds demand real-time visibility platforms coordinating multimodal handoffs with precision previously unattainable through manual dispatch.
- Spare Parts:Aftermarket distribution networks require distinct inventory positioning strategies compared to production logistics, with regional distribution center placement optimizing for service level rather than manufacturing proximity.
- Raw Materials:Steel, aluminum, and polymer feedstock movements operate on different contracting and hedging frameworks than finished automotive products.
Finished vehicles represent the incumbent revenue center. Components are climbing the fastest as EV battery logistics complexity intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports finished vehicles through Thai and Indonesian transshipment hubs to Middle Eastern and African markets, creating multimodal corridor dependencies across Southeast Asian port infrastructure.
China
BYD and NIO are consolidating procurement authority over tier-2 and tier-3 component flows through centralized 4PL contracts. MIIT dual carbon mandates are accelerating electric truck penetration and battery-swapping infrastructure deployment at Yangtze River Delta logistics hubs. Shanghai and Ningbo port congestion creates 7-14 day vessel queuing delays disrupting just-in-sequence delivery commitments to assembly plants.
Japan
Nippon Express sustains domestic automotive logistics dominance through rail-road intermodal solutions synchronized to OEM production schedules. METI coordination with JIS standards bodies imposes blockchain-enabled traceability requirements on automotive parts logistics documentation. Toyota and Honda supplier networks in the Chubu region demand 15-30 minute JIT tolerance windows compressing route optimization requirements.
India
PLI scheme localization thresholds are compelling tier-1 suppliers to establish captive warehousing within 50 kilometers of Chennai and Pune assembly clusters. DGFT customs modernization programs are reducing clearance times for automotive component imports at Jawaharlal Nehru Port. Tamil Nadu's automotive corridor is attracting dedicated EV battery storage facilities with hazardous materials certifications.
Thailand
Eastern Economic Corridor OEM assembly investments are creating integrated supplier parks reducing inbound component lead times to under four hours. Non-harmonized cross-border road transport licensing forces multi-day customs holds at Thailand-Malaysia frontier crossings. Laem Chabang port vehicle processing centers are expanding capacity for Chinese and Japanese export volumes to Middle Eastern markets.
South Korea
Hyundai and Kia are compressing air freight lead times for just-in-time component deliveries through Incheon International Airport corridors. MFDS battery safety regulations are mandating temperature-controlled storage protocols for lithium-ion cell inventories at Gwangyang port facilities. Busan-Ulsan automotive cluster logistics providers are retrofitting warehouses for hazardous materials compliance under emerging EV supply chain requirements.
Asia Pacific Automotive Logistics Market Vendor Landscape
On the supply side, the industry is consolidating around integrated 4PL platforms that consolidate procurement authority over multi-tier component flows. European-origin freight forwarders command premium margins in ocean-air coordination corridors, while Japanese operators dominate domestic intermodal networks through rail-road synchronization. Three archetypes define competitive positioning: global network coordinators, regional multimodal specialists, and domestic intermodal operators. M&A activity targets hazardous materials certification capabilities, while strategic partnerships focus on battery recycling reverse logistics infrastructure.
Among global network coordinators, DHL leverages Asia-Pacific air freight infrastructure to compress lead times for JIT component deliveries. Yusen Logistics anchors competitiveness through dedicated vehicle processing centers at major Chinese and Southeast Asian ports. Nippon Express exemplifies the domestic intermodal archetype through rail-road solutions tied to Japanese OEM production schedules.
| Leading Market Players |
|---|
| DB Schenker |
| DHL |
| Kuehne + Nagel |
| CEVA Logistics |
| DSV |
| GEODIS |
| Nippon Express |
| Yusen Logistics |
| Hitachi Transport System |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port-to-plant corridors compress cost dynamics through supplier density concentration, enabling OEMs to extract tiered service premiums while diesel-to-electric fleet transitions reshape operating cost structures across integrated logistics networks.
Pricing Analysis
Conventional diesel-based road haulage, nascent electric truck fleets, and emerging battery-swapping service tiers stratify pricing across three performance levels. Premium rates attach to JIT-compliant deliveries with sub-30-minute tolerance windows and hazardous materials certification for lithium-ion handling, while standard pricing covers conventional component flows without temperature control requirements. Cost compression in baseline road haulage is intensifying because China's MIIT dual carbon mandates are forcing accelerated fleet turnover before depreciation cycles complete. Tier-1 suppliers with captive warehousing obligations under India's PLI scheme exhibit highest price sensitivity due to fixed cost absorption, whereas OEMs consolidating 4PL contracts demonstrate lowest sensitivity through volume concentration.
Supply Chain Analysis
Integrated logistics park operators in China's Yangtze River Delta, Thailand's Eastern Economic Corridor, and Japan's Chubu region hold dominant contract-fulfillment capacity for automotive manufacturing. Lithium-ion cells, semiconductor consignments, and precision-machined powertrain components constitute critical input dependencies with specialized handling protocols. Single-source vulnerability concentrates in qualified battery handling specialists concentrated in China and Japan, creating training bottlenecks for Southeast Asian facility expansions. Distribution runs through hub-and-spoke networks anchored at Shanghai, Ningbo, and Laem Chabang ports, with final-mile road haulage completing assembly line feeds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of hazardous materials-certified warehouse operators and lithium-ion battery handling specialists is constraining capacity expansion across Southeast Asian corridors, compressing margins for underqualified entrants while rewarding early certification investments.
For Market Incumbents: Insulate core positioning through backward integration into battery recycling reverse logistics infrastructure, securing end-of-life cell collection partnerships with BYD and NIO before regulatory mandates harden. Acquire specialized training capabilities for hazmat certification programs to offset wage inflation in Vietnam and Indonesia expansion zones. Prioritize digital twin deployment across Thailand supplier networks to defend against predictive port scheduling disruption. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's northern industrial zones around Haiphong port corridors, where automotive supplier density remains underdeveloped and first-mover logistics park development yields captive tenant relationships. Target captive warehousing mandates under India's PLI scheme localization thresholds, offering 50-kilometer proximity guarantees to Chennai and Pune assembly clusters. Lead with temperature-controlled EV battery storage certification as differentiated service anchor. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming automotive logistics divisions lacking hazardous materials capabilities or digital visibility infrastructure. Long-term viability hinges on exposure to EV battery logistics complexity rather than conventional finished vehicle transport commoditization. Monitor ASEAN cross-border permit harmonization progress as inflection signal for hub-and-spoke versus direct delivery model economics.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Locks lithium-ion cell capacity for EV logistics under China's MIIT compliance zones. |
| Hazmat Certification Investment | Enables warehouse operation in Yangtze River Delta low-emission corridors under tightening enforcement. |
| Digital Twin Deployment | Protects Japanese OEM assembly continuity through dynamic rerouting against port congestion. |
| Reverse Logistics Partnership | Captures end-of-life EV battery collection networks ahead of regulatory recycling mandates. |
| Cross-Border Permit Harmonization | Reduces Thailand-Malaysia customs hold durations through ASEAN regulatory coordination. |
Methodological Framework
Cross-validation between OEM logistics procurement directors and 3PL operations executives anchors the qualitative findings, supplemented by secondary analysis of vehicle production databases, IHS Markit registration data, customs trade flows, and MIIT regulatory filings. Tier 1 supplier procurement managers, aftermarket distribution heads, and port authority planning officers provided primary input on corridor economics and infrastructure constraints. Bottom-up service provider revenue analysis triangulates against top-down automotive production volume allocations across the analysis window.
Calibration against historical CAGRs in automotive logistics and EV penetration trajectories shapes the projection framework. Segmentation dimensions span service type, end user classification, delivery mode, and product category, with additional modeling of propulsion architecture transition rates and regional production cluster evolution. Battery logistics intensity per vehicle and JIT tolerance window compression trends inform demand elasticity assumptions throughout the forecast period.
Sensitivities concentrate around MIIT enforcement timelines for dual carbon fleet mandates, ASEAN cross-border permit harmonization progress, and lithium-ion cell traceability system adoption rates under Japan's METI-JIS coordination. Forecasts reflect documented assumptions on infrastructure investment flows and regulatory implementation cadence. Quarterly review of port congestion indicators, EV battery storage facility permitting velocity, and PLI scheme localization compliance metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia Pacific Sea Freight Forwarding Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
Florida Freight and Logistics Market
Logistics and Shipping
Russia Courier Service Market
Logistics and Shipping
Australia 3PL Market
Logistics and Shipping
GCC Contract Logistics Market
Logistics and Shipping
Fifth-Party Logistics Market
Logistics and Shipping
Multi-Enterprise Logistics Contract and SLA Performance Management Platforms Market
Logistics and Shipping
US Cross-Border Road Freight Transport Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US Express Delivery Market
Logistics and Shipping
Air Cargo Market
Logistics and Shipping
Autonomous Last Mile Delivery Market
Logistics and Shipping
GCC Air Freight Transport Market
Logistics and Shipping
Air Cargo Container Market
Logistics and Shipping
Global 5PL Solutions Market