
 Latin America Air Freight Market | 2026-2036
Latin America Air Freight Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Air Freight Market Insights
Pilot training bottlenecks across Latin America is unwinding capacity expansion plans for several carriers. LATAM Cargo leverages its integrated belly-hold and freighter network to dominate southbound flower and perishables corridors from Colombia and Ecuador. FedEx sustains cross-border express volumes through its Miami hub-and-spoke architecture serving Central American manufacturing clients. DHL anchors pharmaceutical cold-chain operations with temperature-controlled facilities in São Paulo and Mexico City.
Latin America air freight encompasses the commercial transport of goods via aircraft across the region, utilizing narrow-body, wide-body, and dedicated freighter aircraft with payload capacities ranging from 15 to 120 tons depending on route density and cargo category. The primary purpose is to bridge time-critical supply chains for temperature-sensitive agricultural exports, automotive components, and high-value electronics where ocean transit proves insufficient. Express services command premium yields on intra-regional lanes due to e-commerce fulfillment pressures, while charter operations capture outsized margins during peak harvest seasons for Chilean salmon and Colombian flowers. Standard services occupy the volume core on north-south trade lanes, though margin compression persists from belly-hold capacity overhang on passenger wide-body routes.
Brazil's ANAC enforces strict slot coordination and noise abatement protocols that constrain night-time freighter movements at Congonhas and Santos Dumont, pushing cargo flows to Viracopos and Guarulhos. Mexico's AFAC implements ICAO-aligned security screening mandates that elevate handling costs for cross-border e-commerce parcels entering the United States. IATA's CEIV Pharma certification requirements shape investment priorities for carriers serving the region's growing vaccine and biologics distribution needs. Stakeholders must weigh fleet renewal timelines against sustainable aviation fuel infrastructure gaps before committing to long-term capacity contracts.
Market Dynamics
ANAC's modernization of cargo handling standards at Brazilian airports is forcing carriers to reconfigure ground operations and fleet deployment across the region's busiest corridor. This regulatory pressure compounds with pilot training bottlenecks to constrain capacity expansion timelines.
Growth Catalysts
- Perishables export corridors:Colombian and Ecuadorian flower producers rely on temperature-controlled air freight to reach North American markets within 48 hours, sustaining dedicated freighter demand on northbound lanes.
- AFAC security mandates:Mexico's alignment with ICAO screening protocols for cross-border e-commerce parcels creates compliant handling infrastructure that attracts express carriers serving US-bound manufacturing clients.
- CEIV Pharma certification:IATA's cold-chain standards for vaccine and biologics distribution drive investment in temperature-controlled facilities at São Paulo and Mexico City hubs.
Market Restraints
- SAF infrastructure gaps:Sustainable aviation fuel production and distribution networks remain underdeveloped across Brazil, Mexico, and Chile, limiting fleet renewal options for carriers committed to emissions targets.
- Slot coordination constraints:ANAC's night-time movement restrictions at Congonhas and Santos Dumont push freighter operations to Viracopos and Guarulhos, adding ground transport costs and extending transit times.
- Belly-hold capacity overhang:Passenger wide-body restoration on trans-Pacific and trans-Atlantic routes floods north-south lanes with cheap cargo space, compressing yields for dedicated freighter operators.
Strategic Opportunities
- Central American manufacturing:Nearshoring of electronics and automotive component production to Costa Rica and Guatemala creates demand for time-critical inbound air freight from Asian supplier bases.
- Chilean salmon charter peaks:Seasonal harvest windows for premium seafood exports support outsized margins on ad-hoc freighter deployments during Q1 and Q4.
- Express channel expansion:E-commerce fulfillment pressures are opening dedicated last-mile air networks between São Paulo, Buenos Aires, and Santiago that bypass traditional cargo terminals.
Industry Challenges
- Certified pilot scarcity:Training pipeline limitations for type-rated crews on wide-body freighter aircraft delay fleet expansion plans for multiple carriers.
- Legacy system integration:Digital cargo platforms for real-time tracking and customs pre-clearance require costly retrofitting of existing ground handling IT infrastructure at secondary airports.
- Biometric screening delays:Implementation of crew and handler identity verification systems at Mexican and Brazilian hubs extends security checkpoint processing times during peak periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Air Freight Market |
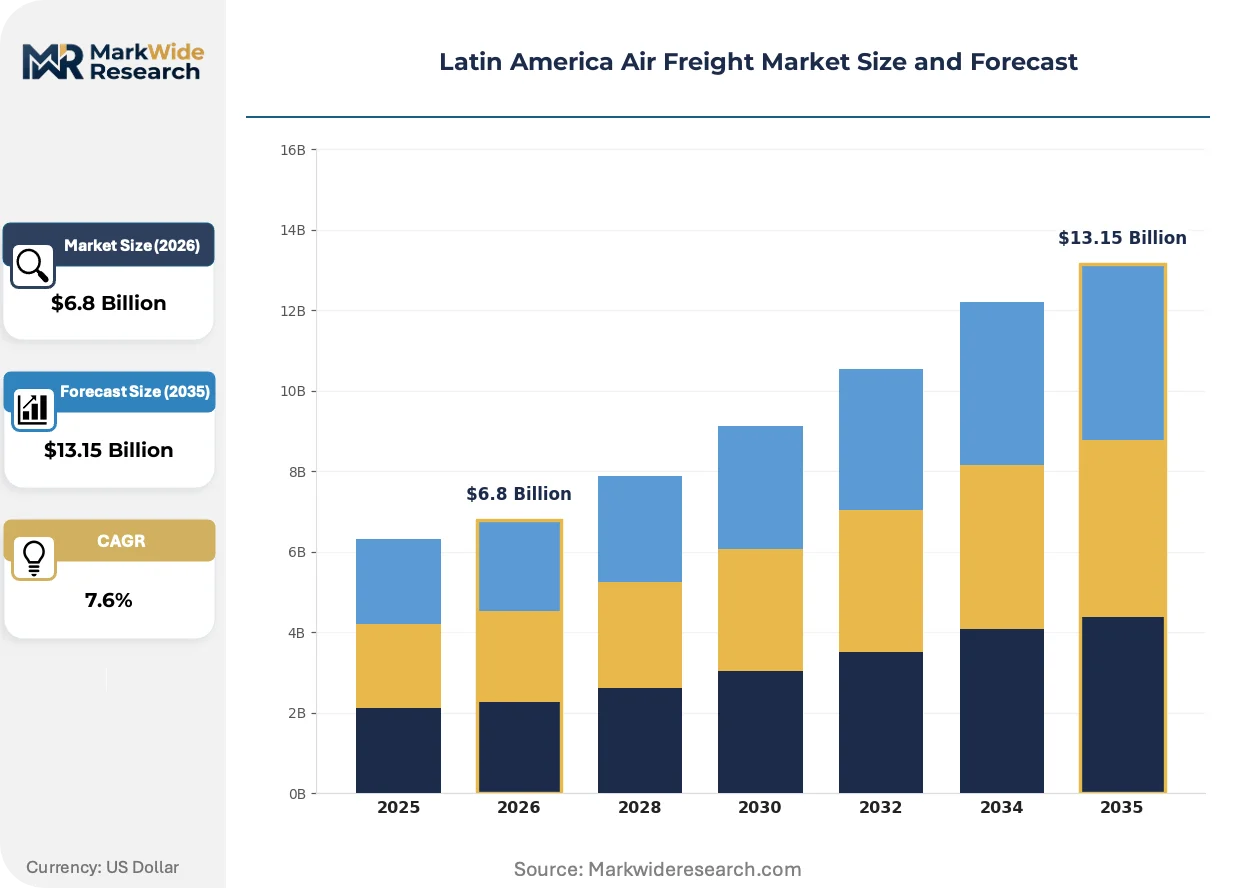
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.15 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Express, Standard, Charter, Cross-Border End User: E-commerce, Manufacturing, Retail, Automotive Delivery Mode: Door-to-Door, Airport-to-Airport, Warehouse-to-Warehouse, Direct Fuel Type: Aviation Gasoline, Jet A, Jet A-1, Biofuels |
| Companies Covered | LATAM Cargo, Aeromexico, FedEx, Cargolux, Emirates SkyCargo, UPS, Avianca Cargo, Copa Airlines, DHL, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Air Freight Market Trends and Innovations
Digitalization of cargo documentation and real-time tracking systems is reshaping operational transparency across Latin American air freight networks. These technologies intersect with sustainability mandates and evolving buyer procurement patterns.
Blockchain-enabled electronic air waybills are fragmenting traditional paper-based documentation workflows between shippers, forwarders, and customs authorities. Pharmaceutical exporters and high-value electronics manufacturers in Mexico and Brazil are adopting these platforms fastest. The technology is fragmenting established freight forwarder intermediation roles by enabling direct shipper-carrier data exchange.
ANAC's noise abatement protocols and emissions disclosure requirements for slot allocation are tightening operational constraints at Brazilian airports. Carriers must now submit fleet noise certification and carbon reporting to secure preferred departure windows. Perishables exporters operating from Viracopos face the steepest compliance costs as older freighter aircraft lose slot priority.
Shippers are consolidating freight procurement around integrated logistics providers offering end-to-end visibility rather than transactional spot-market bookings. Automotive and aerospace manufacturers in Mexico's Bajío region are driving this consolidation. Chilean salmon exporters remain the exception, maintaining direct charter relationships during peak harvest windows.
Latin America Air Freight Market Segmentation
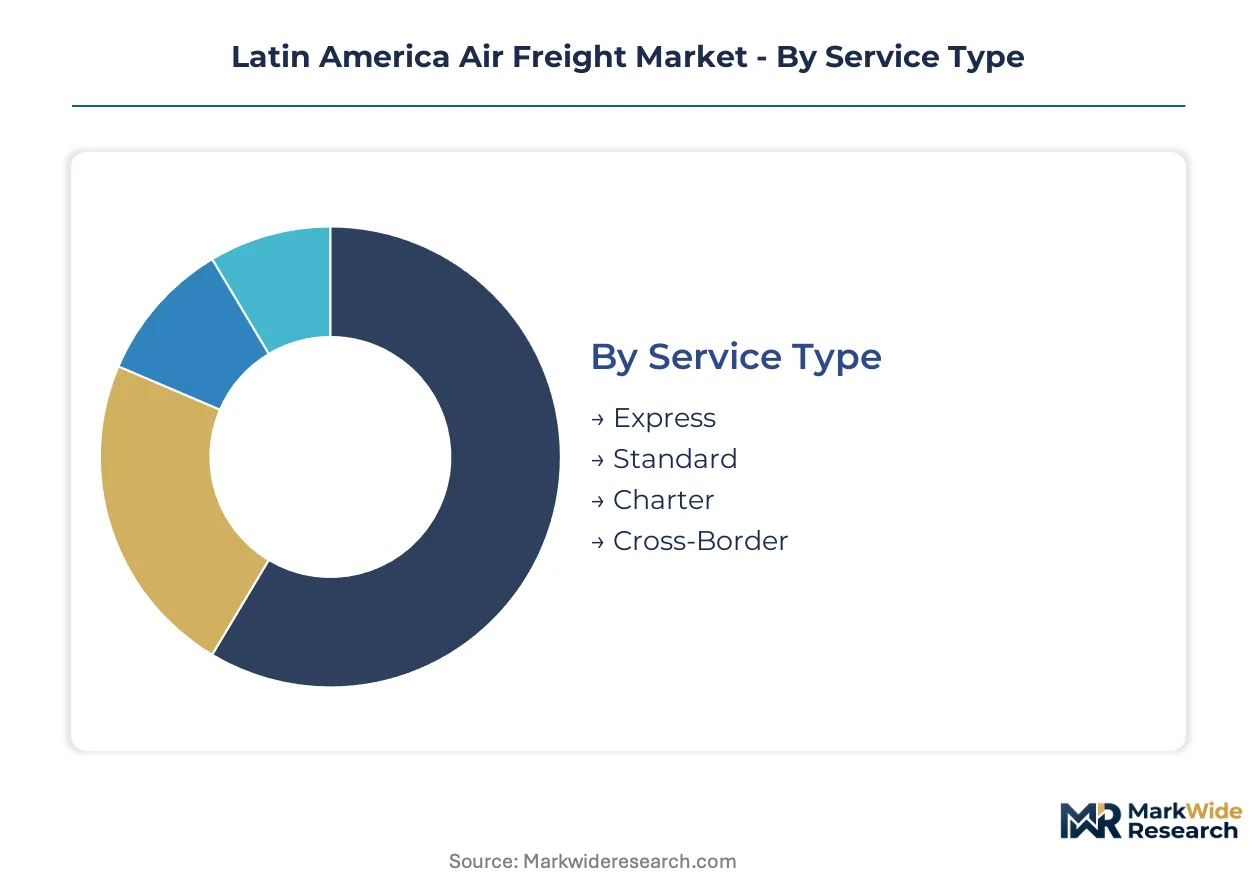
Segmentation in Latin America air freight reveals how service configurations align with corridor economics and regulatory environments across Brazilian, Mexican, and Andean markets. Distinct operational models emerge for perishables exports versus e-commerce fulfillment, each demanding specialized infrastructure and compliance frameworks.
Service Type:
Domestic networks within Brazil and Mexico run predominantly on express and standard configurations, while export-led corridors from Colombia and Ecuador rely heavily on charter capacity for flower and seafood seasons.
- Express:Time-definite delivery guarantees with dedicated last-mile networks and customs pre-clearance. E-commerce platforms in São Paulo and Mexico City drive consolidation around integrated providers offering end-to-end visibility rather than transactional bookings.
- Standard:Scheduled belly-hold and freighter capacity on fixed routes with longer transit windows. Yield compression persists on north-south lanes as passenger wide-body restoration floods markets with cheap cargo space.
- Charter:Ad-hoc freighter deployments for seasonal harvest peaks and project cargo. Colombian flower exporters and Chilean salmon producers sustain outsized margins during Q1 and Q4 harvest windows.
- Cross-Border:Specialized customs handling for e-commerce parcels entering the United States from Mexican manufacturing zones. AFAC's ICAO-aligned security screening mandates elevate compliance costs but attract express carrier investment.
Standard services command the established base. The steepest expansion runs through Express as e-commerce fulfillment pressures intensify.
End User:
Cost tier stratification separates premium temperature-controlled shipments from commodity freight, with pharmaceutical and automotive manufacturers absorbing higher rates for reliability guarantees.
- E-commerce:Parcel volumes requiring rapid customs clearance and last-mile integration. Platforms are opening dedicated air networks between São Paulo, Buenos Aires, and Santiago that bypass traditional cargo terminals.
- Manufacturing:Time-critical inbound components for nearshored electronics and automotive production in Costa Rica and Guatemala. Asian supplier bases feed these corridors through Miami hub-and-spoke architectures.
- Retail:Seasonal inventory replenishment with flexible booking patterns. Demand concentrates around fashion and consumer electronics with compressed selling windows.
- Automotive:Just-in-sequence parts shipments with zero-defect handling requirements. Mexico's Bajío region anchors this segment with precision-scheduled inbound supply chains.
Manufacturing absorbs the premium tier. E-commerce is gaining share fastest through dedicated network investments.
Delivery Mode:
Volume concentration favors airport-to-airport for established trade lanes, while door-to-door expands through integrated logistics provider consolidation.
- Door-to-Door:Complete custody control from shipper facility to consignee address. Pharmaceutical cold-chain operations in São Paulo and Mexico City require this mode for CEIV Pharma compliance.
- Airport-to-Airport:Traditional terminal-to-terminal handoff with forwarder intermediation. Still dominates standard freight on trans-Andean and north-south corridors.
- Warehouse-to-Warehouse:Bonded facility transfers for consolidated shipments. Emerging for cross-border e-commerce through Mexican border zones.
- Direct:Non-stop freighter operations bypassing intermediate hubs. ANAC's slot restrictions at Congonhas and Santos Dumont push these movements to Viracopos and Guarulhos.
Airport-to-Airport retains the volume core. Door-to-Door is climbing the fastest as shippers demand integrated visibility.
Fuel Type:
Supply concentration for conventional jet fuel centers on Brazilian and Mexican refining infrastructure, while biofuel availability remains geographically scattered.
- Aviation Gasoline:Piston-engine aircraft for remote airstrip access in Amazonian and Andean regions. Limited volumes restrict commercial significance.
- Jet A:Kerosene-based fuel for domestic turboprop and jet operations. Brazilian refineries supply this grade for intra-regional networks.
- Jet A-1:Lower freeze-point variant required for high-altitude and long-haul operations. Standard for international departures from Guarulhos and Mexico City.
- Biofuels:Sustainable aviation fuel blends from agricultural feedstocks. Production and distribution networks remain underdeveloped across Brazil, Mexico, and Chile, constraining fleet renewal timelines for emissions-targeted carriers.
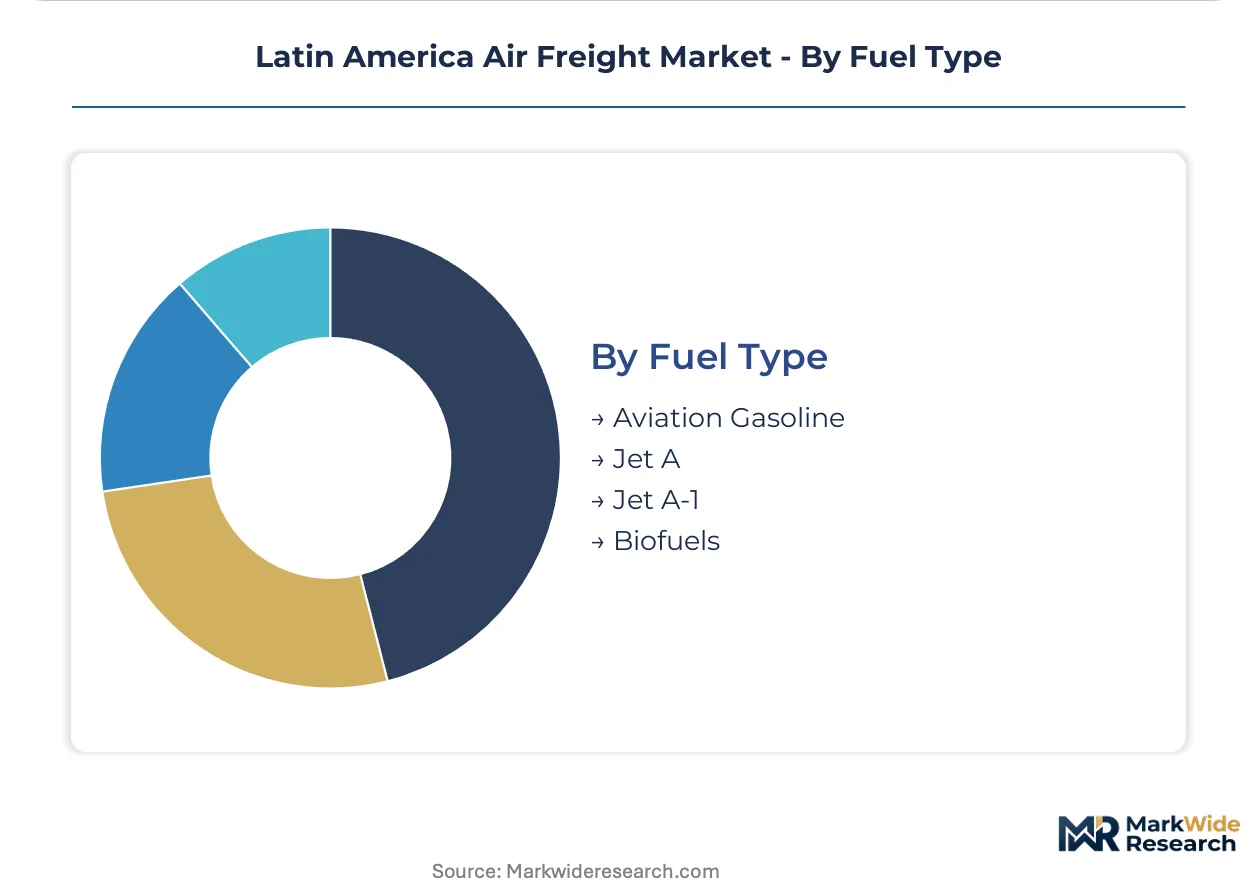
Jet A-1 dominates international departures. Biofuels face the steepest supply-side constraints despite regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANAC's slot coordination and noise abatement protocols at Brazilian airports anchor regulatory pressure across the region's busiest corridor, reshaping where freighter operations can deploy.
Brazil
Flower and perishables exporters from Colombia and Ecuador rely on São Paulo and Viracopos as transshipment hubs for northbound corridors. ANAC's modernization of cargo handling standards forces carriers to reconfigure ground operations and fleet deployment. Guarulhos absorbs displaced freighter movements from Congonhas and Santos Dumont, adding ground transport costs for time-sensitive agricultural shipments.
Mexico
Cross-border e-commerce parcels entering the United States from Mexican manufacturing zones drive express carrier investment. AFAC implements ICAO-aligned security screening mandates that elevate handling costs but create compliant infrastructure. Mexico City anchors pharmaceutical cold-chain operations with temperature-controlled facilities serving vaccine and biologics distribution needs.
Chile
Seasonal harvest windows for premium salmon exports support outsized margins on ad-hoc freighter deployments during Q1 and Q4. The country's national aviation regulator enforces emissions disclosure requirements for slot allocation at Santiago's Arturo Merino Benítez International Airport. Seafood exporters maintain direct charter relationships during peak periods, bypassing consolidated freight procurement patterns.
Colombia
Bogotá's El Dorado International Airport serves as the primary export gateway for Colombian flower producers reaching North American markets within 48 hours. Temperature-controlled air freight sustains dedicated freighter demand on northbound lanes. Perishables corridors concentrate operational investment around integrated belly-hold and freighter networks.
Argentina
Buenos Aires anchors southbound manufacturing component flows and pharmaceutical distribution across the Southern Cone. E-commerce fulfillment pressures are opening dedicated last-mile air networks between São Paulo, Buenos Aires, and Santiago that bypass traditional cargo terminals. Regulatory alignment with IATA's CEIV Pharma certification shapes investment priorities for carriers serving regional vaccine distribution.
Latin America Air Freight Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the Latin America air freight market. The competitive structure fragments between integrated express networks, dedicated freighter operators, and passenger airline cargo divisions leveraging belly-hold capacity. Two strategic archetypes dominate: carriers with hub-and-spoke architectures serving cross-border manufacturing clients, and specialists in temperature-controlled perishables corridors. Competitive moves concentrate on strategic partnerships for last-mile integration and fleet renewal timelines aligned with sustainable aviation fuel infrastructure development.
Among integrated logistics providers, FedEx and DHL exemplify the hub-and-spoke archetype with Miami-serving Central American manufacturing corridors and pharmaceutical cold-chain operations in São Paulo and Mexico City. LATAM Cargo occupies a position within the dedicated freighter tier, leveraging integrated belly-hold and freighter networks for southbound flower and perishables corridors from Colombia and Ecuador.
| Leading Market Players |
|---|
| LATAM Cargo |
| Aeromexico |
| FedEx |
| Cargolux |
| Emirates SkyCargo |
| UPS |
| Avianca Cargo |
| Copa Airlines |
| DHL |
| Others |
Pricing and Supply Chain Analysis
SAF substitution for conventional Jet A-1 is simultaneously redrawing refinery sourcing geographies and compressing fuel cost differentials across Latin American cargo terminals. Carriers now face dual pressure to secure compliant supply while absorbing infrastructure premiums that reshape lane economics.
Pricing Analysis
Price spreads between São Paulo and Miami corridors diverge by certification tier, with CEIV Pharma-compliant shipments commanding substantial premiums over standard perishables. Three-tier pricing structure across express, standard, and charter levels separates time-definite guarantees from belly-hold commodity space. Cost compression in standard services intensifies as passenger wide-body restoration floods northbound lanes with excess capacity. E-commerce platforms exhibit lowest price sensitivity due to fulfillment SLA penalties, while seasonal salmon exporters negotiate hardest on spot charter rates.
Supply Chain Analysis
Brazil and Mexico anchor jet fuel refining capacity for intra-regional networks, while Chile and Colombia remain dependent on imported Jet A-1 for international departures. Supply chains draw from agricultural feedstock networks for biofuel blending, kerosene refining infrastructure, and specialized cool-chain ground handling equipment. Single-source vulnerability concentrates in Miami hub-and-spoke architectures serving Central American manufacturing corridors. Distribution runs through integrated logistics providers consolidating last-mile custody rather than fragmented forwarder intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANAC's cargo handling modernization and CEIV Pharma certification mandates are creating a high-growth disruption where compliant infrastructure becomes the primary competitive moat. Carriers that front-load certification investment capture permanent yield premiums.
For Market Incumbents: Compound fleet renewal timelines with SAF offtake agreements to lock in emissions-compliant slot priority at Brazilian hubs. Integrate temperature-controlled ground handling capabilities at Viracopos and Guarulhos before ANAC noise restrictions displace additional freighter movements. Vertical integration into pharmaceutical cold-chain facilities at São Paulo and Mexico City defends margin position against express carrier encroachment. For New Entrants and Emerging Players: Differentiate on ad-hoc charter specialization for Chilean salmon and Colombian flower peak seasons where incumbent networks lack flexibility. Target Central American manufacturing corridors from Costa Rica and Guatemala with dedicated freighter capacity bypassing Miami hub congestion. White-space exists in cross-border e-commerce customs pre-clearance services for Mexican manufacturing zones. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated logistics providers with CEIV Pharma certification and established SAF supply relationships. Long-term viability hinges on captive access to temperature-controlled infrastructure rather than transactional spot-market positioning. Watch for ANAC slot reallocation decisions as the signal indicating which carrier networks gain operational leverage.| Strategic Initiative | Industry Significance |
|---|---|
| CEIV Pharma Certification Investment | Unlocks premium yield tiers for vaccine and biologics distribution at São Paulo and Mexico City hubs. |
| SAF Supply Agreement | Secures emissions-compliant slot priority under ANAC's carbon disclosure requirements for freighter operations. |
| Last-Mile Network Integration | Bypasses traditional cargo terminal congestion through dedicated air networks between São Paulo, Buenos Aires, and Santiago. |
| Charter Fleet Specialization | Captures outsized margins during Q1 and Q4 salmon harvest peaks when scheduled capacity saturates. |
| Central American Hub Development | Positions for nearshored electronics and automotive component flows from Costa Rica and Guatemala manufacturing zones. |
Research Methodology
Initial hypotheses were tested against primary input from cargo operations directors, airline network planners, pharmaceutical logistics managers, and ground handling executives and refined through secondary validation. Sources included IATA cargo traffic databases, ANAC regulatory filings, AFAC security mandate documentation, and customs trade flow records. Bottom-up lane-specific volume estimates triangulated with top-down regional GDP-correlation models.
Variance decomposition across service type, end user category, delivery mode, and fuel certification tier shaped the analytical framework over the projection horizon. CAGRs were derived from trend extrapolation of corridor-specific yield data and capacity deployment schedules. Forecast inputs incorporated ANAC slot allocation timelines, CEIV Pharma facility buildout pipelines, and SAF infrastructure development milestones.
Forecasts assume regulatory continuity in Brazilian ANAC and Mexican AFAC regimes; material policy shifts would require re-modeling. Specific risks include pilot training pipeline disruptions, biometric screening implementation delays, and SAF supply shortfalls. Recalibration cycles align with material shifts in slot coordination rules and cold-chain certification adoption rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Asia-Pacific Courier Market
Logistics and Shipping
North America Logistics Automation Market
Logistics and Shipping
United States Automotive Logistics Market
Logistics and Shipping
Flat Rack Containers Market
Logistics and Shipping
Egypt 3PL Market
Logistics and Shipping
GCC Freight and Logistics Market
Logistics and Shipping
Europe Sea Freight Forwarding Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Automotive Logistics Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Global Drone Logistics and Transportation Market
Logistics and Shipping
UAE Contract Logistics Market
Logistics and Shipping
Jordan Freight and Logistics Market
Logistics and Shipping
Sweden Courier, Express, and Parcel Market
Logistics and Shipping
APAC Contract Logistics Market
Logistics and Shipping
Air Cargo Capacity and Allotment Marketplace Platforms Market