
 Japan Digital Radiology Market | 2026-2036
Japan Digital Radiology Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Digital Radiology Market Insights
Japan's domestic imaging equipment manufacturing base is restructuring around higher-value detector fabrication and integrated software platforms. Fujifilm Holdings Corporation leverages decades of film-to-digital transition experience to sustain installed base loyalty across prefectural hospital networks. Canon Medical Systems Corporation anchors premium CT-MR hybrid workflows that compete directly with imported modalities. Siemens Healthineers differentiates through AI-embedded reconstruction algorithms that reduce scan times for aging patient populations.
Digital radiology encompasses X-ray-based imaging systems that capture anatomical data through solid-state flat panel detectors or photostimulable phosphor plates, converting ionizing radiation into digital signals with spatial resolution typically exceeding 2.5 line pairs per millimeter. These systems serve primarily to replace analog film-screen combinations, enabling immediate image distribution, dose optimization, and integration with hospital information networks. DR Systems command the largest revenue share among product categories, reflecting Japan's preference for direct-capture efficiency over cassette-based computed radiography in high-volume settings. Flat Panel Detectors represent the fastest-expanding technology segment, while Cloud-Based Systems are gaining traction among diagnostic centers seeking centralized archiving without capital-intensive PACS infrastructure.
Japan's PMDA governs medical device approval timelines and software-as-medical-device classifications that shape vendor market entry strategies. METI promotes domestic manufacturing competitiveness through standards alignment with IEC 60601-1-3 radiation safety protocols. The country's national health insurance fee schedule revisions directly influence hospital capital expenditure cycles for diagnostic equipment replacement. Stakeholders must monitor how impending amendments to the Act on Securing Quality, Efficacy and Safety of Products Including Pharmaceuticals and Medical Devices affect AI diagnostic software registration pathways.
Market Dynamics
Japan's radiology infrastructure replacement cycle is accelerating as METI's reimbursement reforms compress hospital capital expenditure timelines from seven-year cycles to four-year refresh mandates.
Growth Catalysts
- PMDA Software-as-Medical-Device Pathway:Streamlined AI diagnostic algorithm approvals reduce vendor time-to-market for automated image interpretation tools.
- Prefectural Hospital Networks:Consolidated procurement across regional health alliances creates volume concentration for flat panel detector upgrades.
- Flat Panel Detector Technology:Direct-capture efficiency gains over cassette-based systems drive replacement demand in high-throughput metropolitan emergency departments.
Market Restraints
- Xenon Detector Supply Concentration:Three specialized Japanese foundries control amorphous selenium deposition capacity, creating single-source vulnerability for premium detector substrates.
- JIS X-ray Shielding Standards:Incremental lead-equivalence requirements add material cost burden without proportional reimbursement adjustment.
- Computed Tomography Substitution:Low-dose CT protocols in lung cancer screening programs erode chest radiography volume in tertiary oncology centers.
Strategic Opportunities
- Telemedicine-Enabled Teleradiology:Rural Hokkaido and Okinawa prefectures lack on-site radiologist coverage, creating demand for cloud-archived image distribution to urban interpretation hubs.
- METI Carbon Neutrality Incentives:Equipment replacement subsidies for energy-efficient digital systems accelerate analog-to-digital conversion in municipally operated clinics.
- AI-Workflow Convergence:Integration of automated positioning assistance with dose modulation software reduces technologist training burden for aging hospital workforces.
Industry Challenges
- Legacy PACS Integration Complexity:Proprietary DICOM implementations from 1990s-era hospital information systems resist seamless connectivity with modern detector hardware.
- Radiologic Technologist Labor Pool Contraction:Japan Medical Association licensing bottlenecks restrict new entrant supply as existing practitioners age into retirement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Digital Radiology Market |
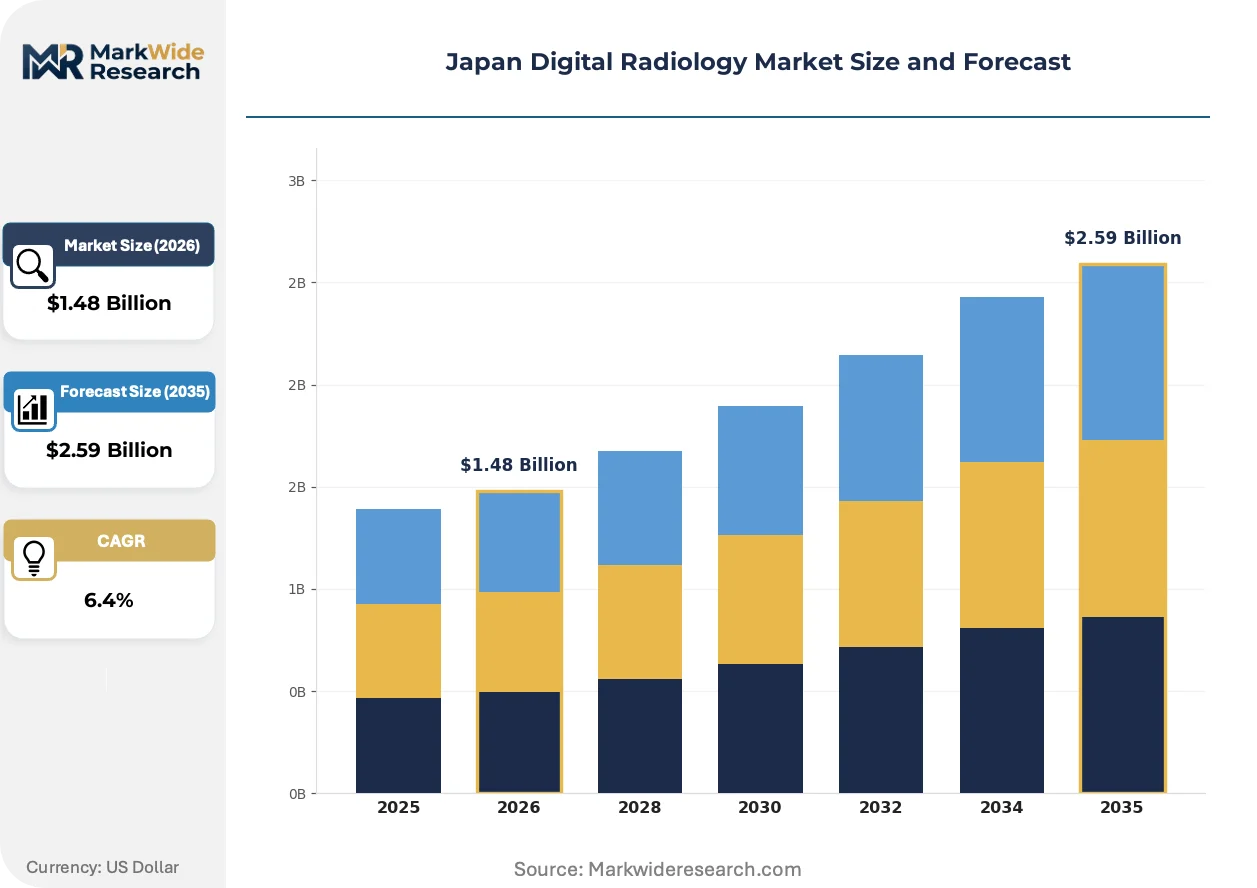
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CR Systems, DR Systems, Imaging Software, Accessories Application: Cardiology, Orthopedics, Oncology, Neurology End User: Hospitals, Diagnostic Centers, Research Institutes, Clinics Technology: Flat Panel Detectors, Computed Radiography, Portable Devices, Cloud-Based Systems |
| Companies Covered | Shimadzu Corporation, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Siemens Healthineers, Koninklijke Philips N.V., GE Healthcare, Konica Minolta, Carestream Health, Hitachi Medical Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Digital Radiology Market Trends and Innovations
Detector fabrication and image reconstruction software are converging into unified platform offerings that bundle hardware procurement with recurring algorithm licensing fees.
Photon-counting CT detector arrays are absorbing research investment from conventional energy-integrating flat panels. Tertiary academic medical centers in Tokyo and Osaka are piloting these systems for spectral imaging protocols. The technology is absorbing capital that previously flowed to iterative reconstruction software licenses, compressing the standalone software market.
PMDA's 2023 guidance on machine learning-enabled medical devices clarified validation requirements for deep learning reconstruction algorithms. Domestic manufacturers now face accelerated clinical evidence submission timelines for AI-embedded modalities. Prefectural hospitals with limited research infrastructure are outsourcing validation studies to contracted academic consortia, altering vendor-hospital partnership structures.
Consolidated purchasing through regional medical associations is displacing individual hospital procurement autonomy. Chubu and Kinki region health alliances now negotiate detector replacements on three-year fleet contracts rather than transactional equipment purchases. This concentration is most visible among mid-tier municipal hospitals seeking volume discounts without dedicated supply chain staff.
Japan Digital Radiology Market Segmentation
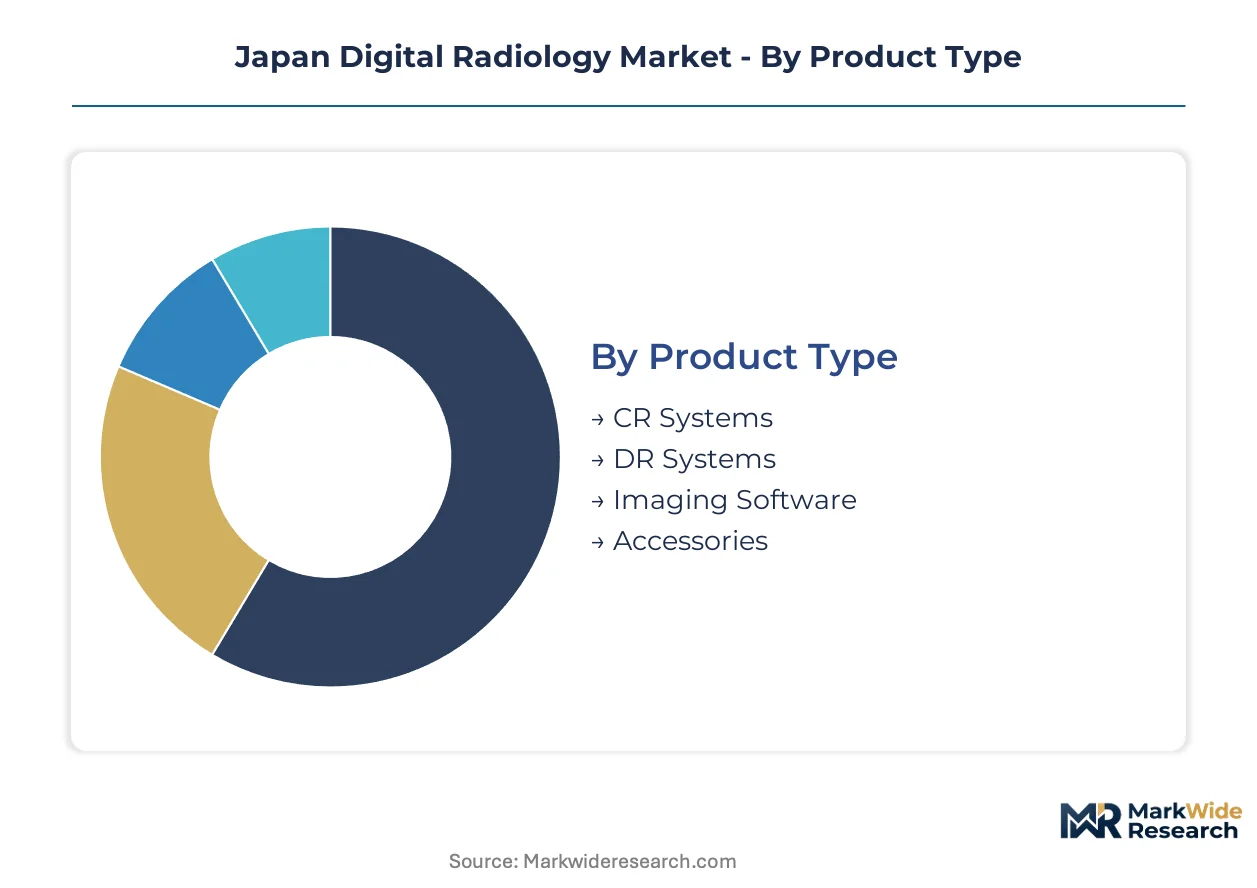
Japan's digital radiology procurement patterns fragment across hardware maturity cycles, software licensing models, and facility infrastructure tiers. Understanding these segment boundaries clarifies how METI reimbursement reforms differentially impact capital allocation across prefectural hospital networks and municipal clinic systems.
Product Type:
Supply concentration in detector fabrication and software platforms creates divergent margin profiles across hardware versus recurring revenue segments.
- DR Systems:Direct-capture digital radiography systems employ amorphous silicon or selenium flat panel detectors to convert X-ray photons into electrical signals without intermediate cassette processing. Tokyo and Osaka tertiary hospitals are replacing aging CR infrastructure with DR suites to meet METI's compressed four-year refresh mandates.
- CR Systems:Computed radiography utilizes photostimulable phosphor plates that require mechanical scanning to extract latent images, retaining installed base in cost-constrained municipal clinics. Prefectural health alliances in rural Hokkaido defer full DR conversion due to capital budget limitations.
- Imaging Software:PACS workstations and AI-embedded reconstruction algorithms command recurring licensing fees from consolidated regional hospital networks.
- Accessories:Grid assemblies, protective shielding, and positioning aids follow equipment replacement cycles with lower margin profiles.
DR Systems absorb the bulk of installed capacity; Imaging Software is expanding most quickly.
Application:
Clinical workflow demands and reimbursement intensity shape specialty-specific procurement priorities across Japan's hospital tiers.
- Orthopedics:Weight-bearing extremity imaging and spinal alignment protocols drive demand for high-resolution flat panel configurations in metropolitan trauma centers. Kinki region hospitals prioritize automated stitching software for long-leg and full-spine acquisitions.
- Oncology:Chest radiography volume faces erosion from low-dose CT lung screening programs, though bone metastasis surveillance retains DR utilization in tertiary oncology centers.
- Cardiology:Portable DR systems support bedside cardiac imaging in intensive care units with space-constrained fluoroscopy suites.
- Neurology:Skull base and sinus imaging requirements concentrate in academic medical centers with hybrid CT-MR workflows.
Orthopedics commands the largest installed base; Oncology is experiencing the steepest volume reallocation pressures.
End User:
Facility scale and reimbursement access determine technology tier adoption across Japan's fragmented provider landscape.
- Hospitals:Large tertiary institutions in Tokyo, Osaka, and Nagoya anchor premium detector procurement through consolidated prefectural purchasing alliances. METI's carbon neutrality subsidies accelerate analog-to-digital conversion in municipally operated facilities.
- Diagnostic Centers:Independent imaging facilities in Chubu and Kanto regions favor cloud-archived DR systems to avoid capital-intensive PACS infrastructure.
- Clinics:Solo practitioner and small group practices in Okinawa and rural prefectures retain CR systems due to constrained capital budgets.
- Research Institutes:Academic medical centers pilot photon-counting detector arrays for spectral imaging protocol development.
Hospitals retain dominant procurement volume; Diagnostic Centers are climbing the fastest as outpatient imaging decentralizes.
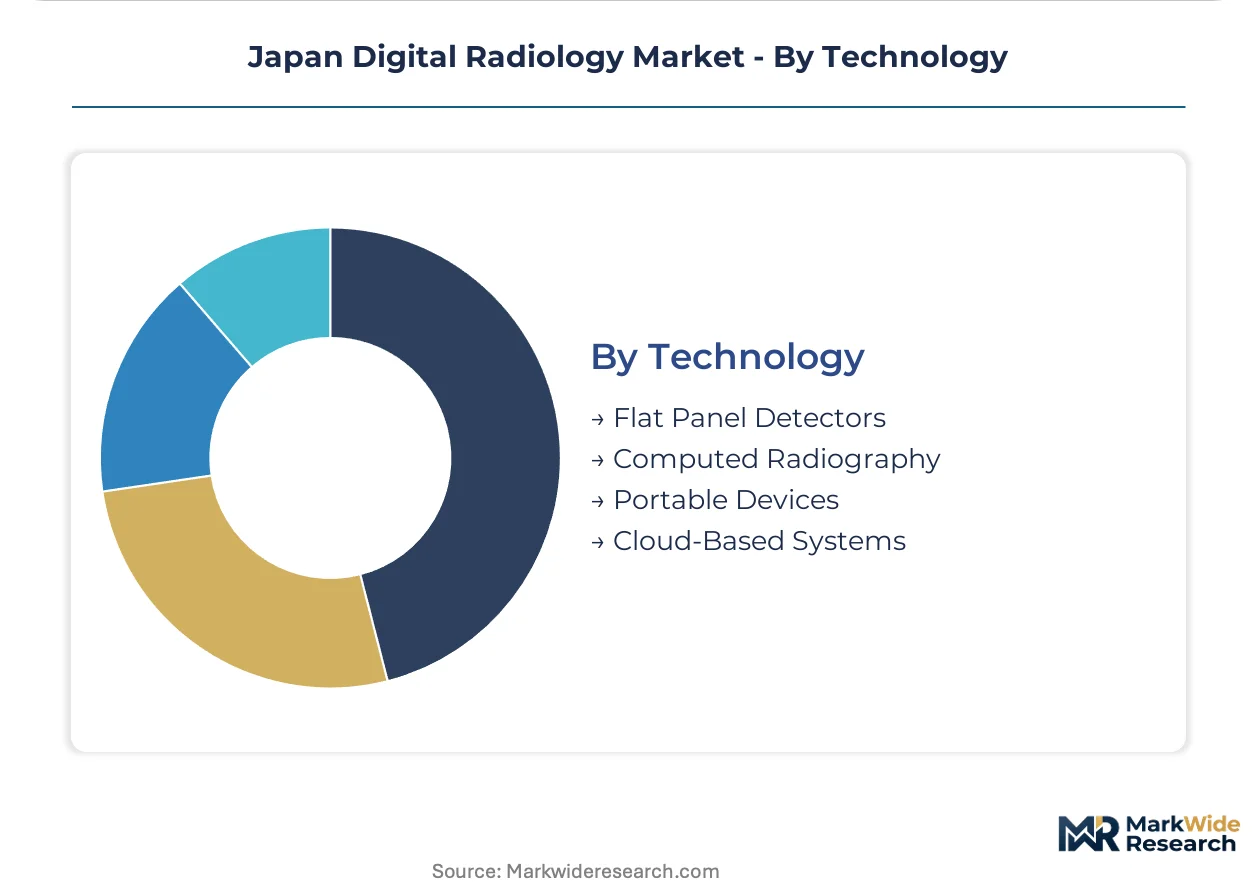
Technology:
Detector physics and data architecture differentiation separate capital-intensive hardware from scalable platform offerings.
- Flat Panel Detectors:Direct-capture amorphous selenium and silicon arrays achieve spatial resolution exceeding 2.5 line pairs per millimeter with immediate image availability. Three specialized Japanese foundries control amorphous selenium deposition capacity, creating supply concentration for premium substrates.
- Cloud-Based Systems:Centralized archiving and teleradiology distribution enable rural Hokkaido and Okinawa facilities to access urban radiologist interpretation without on-site specialist staffing.
- Computed Radiography:Cassette-based phosphor plate systems persist in budget-constrained installations with lower throughput requirements.
- Portable Devices:Battery-powered wireless DR detectors support emergency department and bedside imaging workflows in aging hospital infrastructure.
Flat Panel Detectors represent the dominant installed technology; Cloud-Based Systems are gaining share fastest among new installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amorphous selenium deposition capacity concentrates in three specialized Japanese foundries that supply detector substrates to domestic equipment manufacturers. This feedstock localization shapes procurement patterns across Japan's prefectural hospital networks.
Kanto/Tokyo
Metropolitan tertiary hospitals drive premium flat panel detector procurement through consolidated purchasing alliances. METI's four-year equipment refresh mandates accelerate replacement of aging CR infrastructure. Tokyo academic medical centers pilot photon-counting detector arrays for spectral imaging protocol development.
Kansai/Osaka
Osaka anchors hybrid CT-MR workflow adoption among large hospital systems seeking integrated diagnostic platforms. PMDA's streamlined Software-as-Medical-Device pathway reduces time-to-market for AI-embedded reconstruction algorithms. Kinki region health alliances negotiate three-year fleet contracts for detector replacements.
Chubu/Nagoya
Regional medical associations in Chubu consolidate procurement across municipal hospital networks. METI carbon neutrality subsidies accelerate analog-to-digital conversion in municipally operated facilities. Nagoya-based manufacturing clusters supply positioning aids and grid assemblies to domestic equipment vendors.
Hokkaido
Rural prefectural hospitals lack on-site radiologist coverage, creating demand for cloud-archived teleradiology distribution. Prefectural health alliances defer full DR conversion due to capital budget limitations. Sapporo medical centers serve as urban interpretation hubs for remote facility image analysis.
Okinawa
Island clinic systems retain cassette-based CR systems constrained by limited capital budgets and lower throughput requirements. Cloud-based archiving enables access to mainland radiologist interpretation without specialist staffing. Okinawa prefectural networks prioritize portable wireless DR detectors for emergency department workflows.
Japan Digital Radiology Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-embedded software licensing and cloud-archived distribution models. The vendor base clusters around three strategic archetypes: domestic detector fabricators with integrated software platforms, multinational modality manufacturers with premium reconstruction algorithms, and regional specialists in cassette-based legacy systems. Competitive moves concentrate on consolidated procurement negotiations with prefectural hospital alliances and technology licensing partnerships for automated positioning assistance.
Among Japan-based equipment manufacturers, Shimadzu Corporation, Canon Medical Systems Corporation, and Fujifilm Holdings Corporation exemplify the domestic integrated-platform archetype. These entities anchor detector fabrication and software development within consolidated supply chains serving prefectural hospital networks. Siemens Healthineers and Koninklijke Philips N.V. represent multinational participants competing through AI-embedded reconstruction offerings. The competitive terrain rewards vendors capable of bundling hardware procurement with recurring algorithm licensing fees across METI-mandated refresh cycles.
| Leading Market Players |
|---|
| Shimadzu Corporation |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| GE Healthcare |
| Konica Minolta |
| Carestream Health |
| Hitachi Medical Corporation |
| Others |
Pricing and Supply Chain Analysis
Amorphous selenium deposition technology is displacing legacy amorphous silicon fabrication across Japan's detector substrate production, simultaneously compressing unit economics for premium flat panels and concentrating supply among three specialized domestic foundries. This dual transformation reshapes how prefectural hospital networks negotiate procurement terms and how vendors structure hardware-software bundles.
Pricing Analysis
Warranty and service-bundling arrangements separate premium detector procurement from unbundled transactional sales. Three-tier pricing structure across premium, standard, and economy levels reflects detector resolution specifications and AI-embedded software licensing tiers. Price differentiation stems from JIS X-ray shielding certification grade and volume scale under consolidated prefectural fleet contracts. Cost compression in economy-tier CR systems is intensifying because municipal clinics defer full DR conversion amid capital budget constraints. Small group practices in Okinawa and rural prefectures exhibit highest price sensitivity; Tokyo tertiary hospitals prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Dual-sourcing requirements for amorphous selenium substrates mandate multi-supplier qualification across Japan's three specialized foundries, though actual deposition capacity remains geographically tethered to domestic manufacturing clusters. The supply chain draws from Japan for detector substrates, South Korea for semiconductor components, and Germany for precision mechanical assemblies. Raw material dependencies include high-purity selenium, indium tin oxide coatings, and carbon fiber structural elements. Single-source vulnerability in amorphous selenium deposition creates procurement risk for premium DR system manufacturers. Distribution runs through consolidated prefectural health alliance contracts rather than individual hospital procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's digital radiology market reads as a supply-constrained story where amorphous selenium deposition bottleneck props pricing for premium detector tiers and limits vendor expansion velocity.
For Market Incumbents: Hedge against photon-counting CT substitution by accelerating software licensing revenue streams through AI-embedded reconstruction algorithms. Secure captive supply of amorphous selenium substrates through equity partnerships with specialized Japanese foundries. METI's compressed four-year refresh mandates create volume concentration risk that demands diversified prefectural alliance coverage. For New Entrants and Emerging Players: Cloud-native teleradiology platforms offer a technology-first wedge into rural Hokkaido and Okinawa prefectures lacking on-site radiologist coverage. Municipal clinic systems in budget-constrained regions represent the most penetrable end-user segment. Pursue software-as-medical-device registration through PMDA's streamlined AI diagnostic pathway to bypass capital-intensive hardware manufacturing barriers. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by domestic integrated-platform manufacturers seeking AI-embedded software capabilities. Long-term viability hinges on recurring licensing revenue durability rather than transactional hardware margins. Monitor PMDA amendments to the Act on Securing Quality, Efficacy and Safety of Products Including Pharmaceuticals and Medical Devices as the signal to watch for AI diagnostic software registration pathway shifts.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Software-as-Medical-Device Registration | Streamlined AI algorithm approvals reduce vendor time-to-market for automated image interpretation tools. |
| Prefectural Health Alliance Partnership | Consolidated procurement across Chubu and Kinki regions creates volume concentration for detector fleet contracts. |
| Amorphous Selenium Foundry Integration | Captive substrate supply secures premium detector manufacturing capacity against single-source vulnerability. |
| Cloud-Based Teleradiology Deployment | Centralized archiving enables rural Hokkaido facilities to access urban radiologist interpretation without specialist staffing. |
| METI Carbon Neutrality Equipment Subsidy | Energy-efficient digital system incentives accelerate analog-to-digital conversion in municipally operated clinics. |
Research Methodology
Multi-period observation of prefectural hospital procurement cycles, PMDA registration timelines, and METI reimbursement reform implementation anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and radiology department heads. Secondary validation drew from PMDA medical device approval databases, METI industrial statistics, hospital procurement disclosure filings, and JIS standards documentation. Bottom-up facility-level demand modeling and top-down national health expenditure triangulation ensured cross-verification.
Segment-weighting across product type, application specialty, end-user facility tier, and technology platform informed the analytical framework. Modeled dimensions included hardware maturity cycles, software licensing models, and prefectural infrastructure tiers. CAGRs were derived through iterative reconciliation of replacement cycle velocity, reimbursement intensity, and technology substitution rates. Forecast inputs incorporated METI carbon neutrality subsidy allocation trajectories and PMDA AI-embedded device validation timeline compression.
Several conditions sit outside the modeled scope, including potential amendments to national health insurance fee schedules, unforeseen supply disruptions in amorphous selenium deposition capacity, and accelerated photon-counting CT adoption in lung cancer screening programs. Deviation in PMDA regulatory enforcement posture toward machine learning-enabled medical devices would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
AI Capsule Endoscopy Reading Platform Market
Medical Imaging
Mexico Computed Tomography Market
Medical Imaging
Magnetoencephalography (MEG) Market
Medical Imaging
Radio-Fluoroscopy Systems Market
Medical Imaging
Germany Digital Radiology Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Global Computed Tomography (CT) Market
Medical Imaging
Global Picture Archiving Communications System Market
Medical Imaging
Molecular Breast Imaging Market
Medical Imaging
Industrial Computed Radiography Market
Medical Imaging
Molecular Imaging Market
Medical Imaging
MRI Ferromagnetic Detection Systems Market
Medical Imaging
Whole-Body Imaging Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Automated Contouring Radiotherapy Software Market
Medical Imaging
India Digital Radiology Market