
 US Contrast Media Market | 2026-2036
US Contrast Media Market Size, Share, and Industry Trends Forecast 2026-2036
US Contrast Media Market Intelligence
Modular packaging of contrast agents with pre-filled syringes and integrated delivery systems is hardening as the dominant procurement format for hospital radiology departments. Bracco Diagnostic leverages its vertically integrated manufacturing network to sustain supply reliability across the Northeast and Midwest. Bayer AG competes through specialized iodinated portfolios optimized for cardiac catheterization labs. GE Healthcare anchors its position with comprehensive service contracts that bundle contrast supply with imaging equipment maintenance.
Contrast media comprise pharmacologically active chemical compounds—typically iodinated benzoic acid derivatives, gadolinium chelates, or insoluble barium sulfate suspensions—engineered to attenuate electromagnetic radiation differentially from surrounding tissues during diagnostic imaging procedures. Their primary commercial purpose is to enhance visualization of vascular structures, organ perfusion, and pathological lesions across CT, MRI, and fluoroscopic modalities. Iodinated agents dominate current revenue pools due to entrenched CT protocol volumes, while gadolinium-based formulations command premium positioning in neurological and oncological MRI applications. Microbubble contrast for echocardiography represents the fastest-expanding segment, driven by expanding stress-echo protocols in outpatient cardiology settings.
FDA oversight through its Center for Drug Evaluation and Research governs new molecular entity approvals and post-market surveillance of gadolinium retention risks, while USP Chapter 797 standards enforce sterile compounding requirements that shape hospital pharmacy purchasing decisions. The Nuclear Regulatory Commission and state-level radiological health branches impose additional handling protocols that filter market access for non-compliant suppliers. Stakeholders must monitor pending FDA guidance on macrocyclic versus linear gadolinium agent prioritization, as this determination will redirect formulary investments and reshape competitive rankings among manufacturers without warning.
Market Dynamics
FDA safety reviews of gadolinium retention are forcing manufacturers to accelerate macrocyclic agent development while hospital formularies freeze linear agent purchases. This regulatory pressure concentrates procurement power among academic medical centers that dictate protocol standardization across affiliated networks.
Growth Catalysts
- Oncology imaging expansion:Tumor characterization protocols at Massachusetts General and Memorial Sloan Kettering drive gadolinium-based agent volumes for MRI staging sequences.
- IRA hospital infrastructure provisions:Federal funding for rural imaging equipment installation creates first-time contrast demand in underserved counties across Appalachia and the Great Plains.
- Microbubble echocardiography:Stress-echo protocols in outpatient cardiology settings are displacing nuclear perfusion studies for coronary artery disease screening.
Market Restraints
- Active pharmaceutical ingredient concentration:Iodinated contrast precursor synthesis concentrates in coastal Chinese chemical manufacturing zones, exposing US supply chains to shipping volatility.
- Gadolinium retention liability exposure:FDA post-market surveillance requirements extend product development timelines and inflate clinical trial costs for new molecular entities.
- Barium sulfate substitution:CT enterography protocols with neutral oral contrast are displacing traditional barium studies for small bowel evaluation.
Strategic Opportunities
- Pre-filled syringe standardization:Integrated delivery systems reduce pharmacy compounding labor and align with USP Chapter 797 sterile handling mandates.
- Texas Medical Center corridor:Houston's unconsolidated hospital network presents white-space opportunity for service-contract bundling with imaging equipment maintenance.
- AI-enhanced dosing algorithms:Machine learning integration with contrast injection systems enables personalized volume optimization based on patient biometric profiles.
Industry Challenges
- Radiopharmacist certification bottlenecks:USP 797 compliance training programs face capacity constraints, delaying hospital pharmacy readiness for new sterile product categories.
- Legacy PACS integration friction:Contrast tracking software requires custom middleware development to interface with decade-old radiology information systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Contrast Media Market |
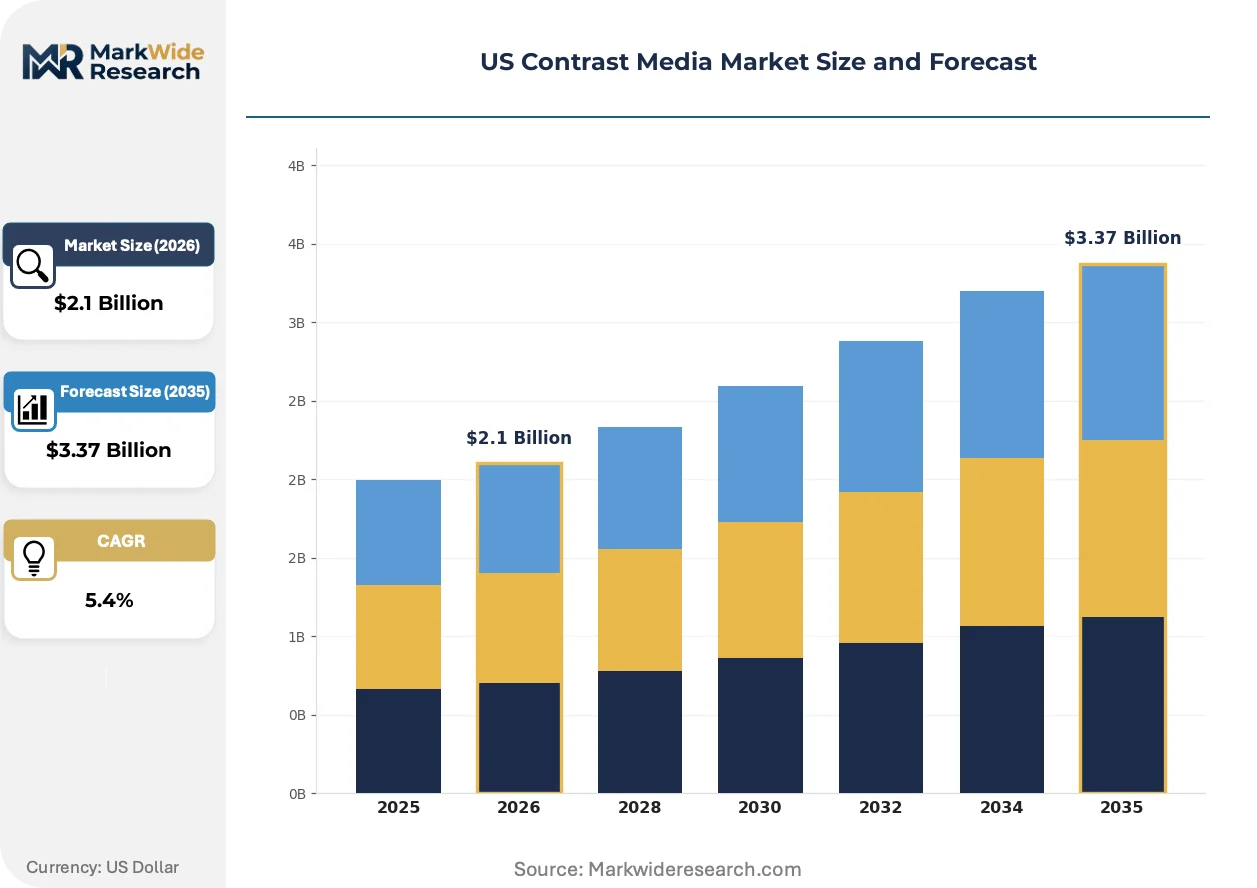
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.37 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
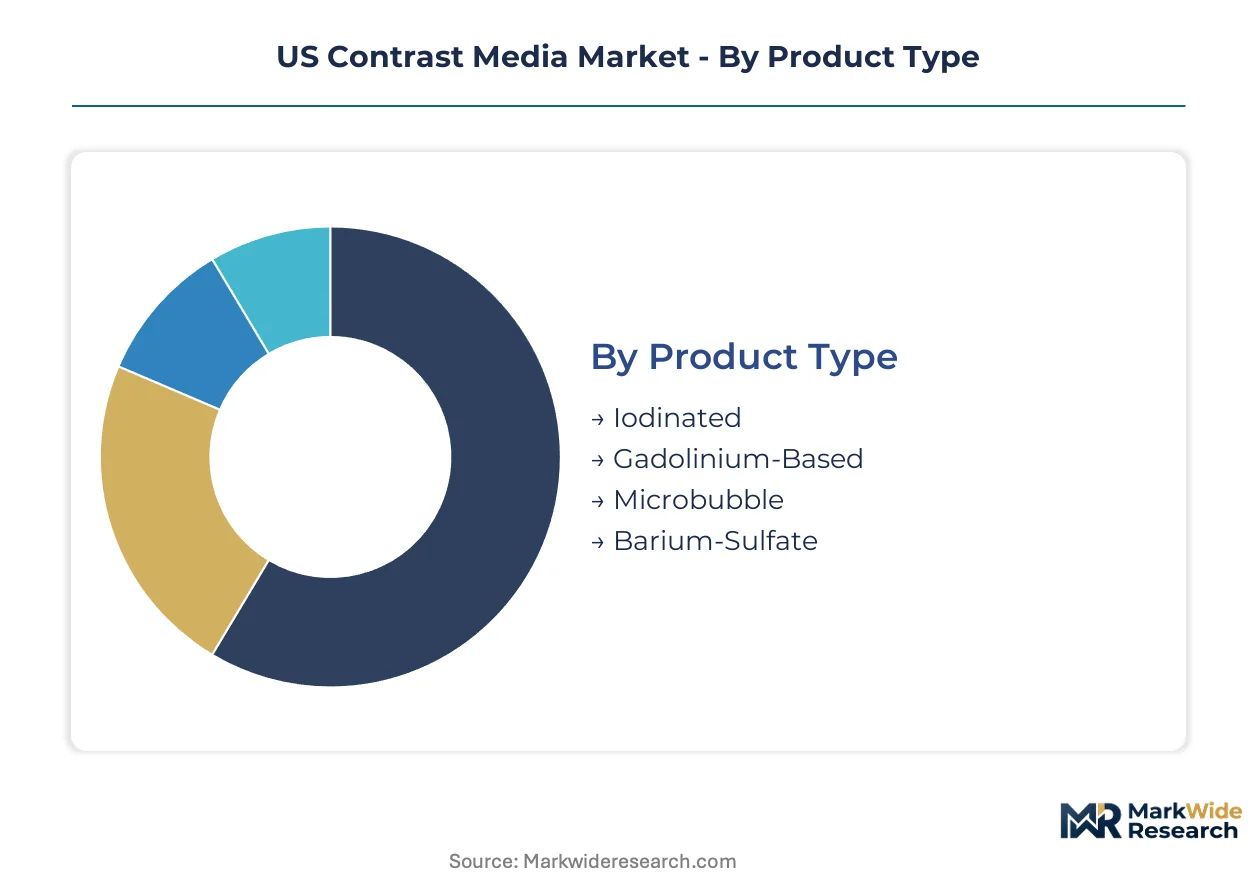
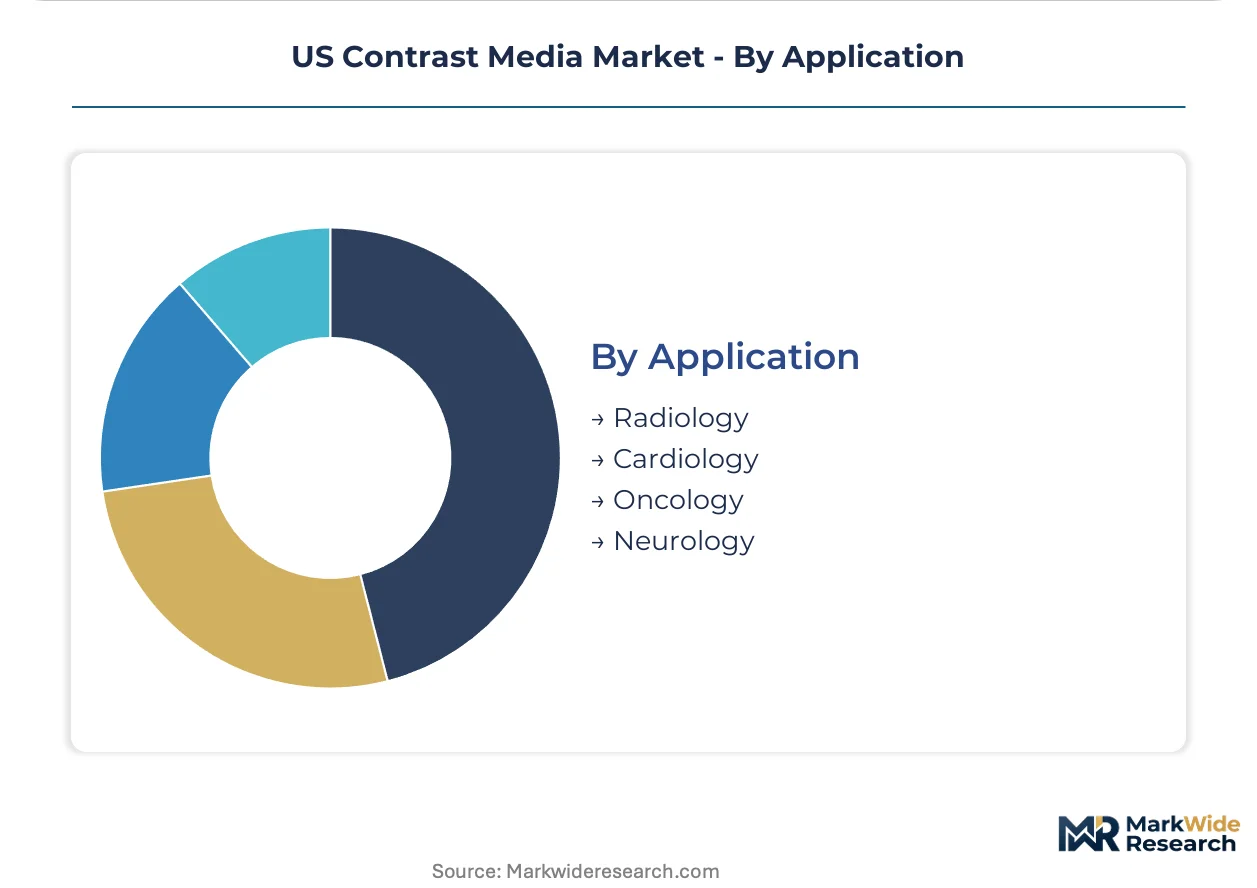
| Segmentation | Product Type: Iodinated, Gadolinium-Based, Microbubble, Barium-Sulfate End User: Hospitals, Imaging Centers, Outpatient Facilities, Research Institutions Delivery Mode: Injectable, Oral, Intravenous, Intra-arterial Application: Radiology, Cardiology, Oncology, Neurology |
| Companies Covered | Bracco Diagnostic, Inc., Trivitron Healthcare, Bayer AG, IMAX Diagnostic Imaging, CMC Contrast AB, GE Healthcare, Lantheus Medical Imaging, Inc., Nano Therapeutics Pvt. Ltd., Guerbet, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Contrast Media Market Strategic Shifts & Innovations
Product development is pivoting toward safety-optimized molecular structures while distribution models compress inventory touchpoints. Hospital procurement committees now weight supply reliability metrics alongside unit pricing in vendor scorecards.
Macrocyclic gadolinium chelates with enhanced kinetic stability are electrifying the neurological MRI segment. Academic medical centers in Boston and New York have completed formulary conversions ahead of anticipated FDA prioritization guidance. This molecular transition is compressing residual market share for linear agent manufacturers.
FDA Center for Drug Evaluation and Research draft guidance on gadolinium agent risk categorization is reshaping manufacturer R&D allocation. Companies with macrocyclic portfolios are accelerating clinical data packages while linear agent producers diversify into iodinated portfolios. The regulatory uncertainty most acutely affects multi-site radiology groups standardizing protocols across state lines.
Consignment inventory arrangements with direct-to-department delivery are displacing traditional central pharmacy purchasing for high-volume CT suites. Radiology department managers at Cleveland Clinic and Mayo Clinic Rochester now negotiate guaranteed stock levels rather than price-per-vial contracts. This behavioral shift concentrates most visibly in the Midwest corridor where integrated delivery networks dominate market structure.
US Contrast Media Market Segmentation
Contrast media procurement patterns diverge sharply across product chemistry, delivery infrastructure, and clinical setting. Understanding these fault lines reveals where formulary power concentrates and which technology transitions will reshape vendor relationships.
Product Type:
Supply concentration in iodinated precursor manufacturing and gadolinium chelate synthesis determines which manufacturers control hospital contract negotiations.
- Iodinated:Benzoic acid derivatives with tri-iodinated aromatic rings attenuate X-ray beams for CT angiography and urography. Massachusetts General and Cleveland Clinic drive volume concentration through high-throughput emergency department protocols. Cost pressures from Medicare reimbursement cuts favor high-osmolar legacy formulations in price-sensitive community hospitals.
- Gadolinium-Based:Paramagnetic chelates—macrocyclic and linear—shorten T1 relaxation times for enhanced MRI tissue contrast. Memorial Sloan Kettering and MD Anderson anchor demand for tumor characterization sequences. FDA safety reviews of retention in neural tissues accelerate macrocyclic formulary conversions.
- Microbubble:Perfluorocarbon-filled lipid shells create acoustic impedance mismatches for echocardiography perfusion imaging. Outpatient cardiology suites in Texas and Florida displace nuclear stress tests.
- Barium-Sulfate:Insoluble suspensions coat mucosal surfaces for fluoroscopic GI tract evaluation. CT enterography protocols erode traditional small bowel follow-through demand.
Today's leader: Iodinated agents. Tomorrow's challenger: Microbubble formulations.
End User:
Procurement authority fragments across centralized pharmacy committees and decentralized radiology department managers.
- Hospitals:Integrated delivery networks negotiate enterprise-wide contracts bundling contrast supply with imaging equipment service agreements. Mayo Clinic Rochester and Johns Hopkins anchor multi-site standardization.
- Imaging Centers:Independent diagnostic facilities prioritize price-per-study metrics over supply reliability guarantees. Volume concentration in suburban Dallas and Phoenix corridors.
- Outpatient Facilities:Freestanding cardiology clinics drive microbubble demand through same-day stress-echo protocols.
- Research Institutions:NIH-funded clinical trials at academic medical centers command specialized molecular entities outside commercial formularies.
Hospital networks consolidate purchasing power. Imaging centers seek price transparency.
Delivery Mode:
USP Chapter 797 sterile compounding mandates filter which delivery formats penetrate hospital pharmacy workflows.
- Injectable:Pre-filled syringes with integrated needle-safety systems dominate CT suite throughput. Bracco's Visipack and Bayer's Medrad Stellant reduce pharmacy labor.
- Intravenous:Power injector compatibility determines contrast agent selection for cardiac catheterization labs. GE Healthcare's OptiVantage anchors protocol standardization.
- Oral:Neutral and positive oral contrast suspensions for CT enterography require flavor masking for patient compliance.
- Intra-arterial:Selective angiography protocols in interventional radiology demand customized concentration formulations.
Pre-filled injectable systems gain share fastest. Compounded intra-arterial formulations face regulatory headwinds.
Application:
Clinical specialization depth determines pricing power and formulary stickiness across therapeutic areas.
- Radiology:Cross-sectional imaging departments consume the highest contrast volumes per procedure. University of Pennsylvania and Stanford Health standardize dual-energy CT protocols with spectral iodine mapping.
- Cardiology:Coronary CT angiography and invasive catheterization labs demand iso-osmolar iodinated agents with low viscosity profiles. NewYork-Presbyterian drives protocol innovation.
- Oncology:Tumor staging sequences require gadolinium-enhanced MRI for metastasis detection. Dana-Farber and City of Hope anchor precision imaging demand.
- Neurology:Blood-brain barrier permeability assessment in multiple sclerosis protocols favors macrocyclic gadolinium chelates with minimal retention profiles.
Radiology commands volume leadership. Oncology applications generate premium pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US contrast media industry traces its commercial origins to the mid-20th century development of iodinated benzoic acid derivatives at Eastman Kodak's research laboratories in Rochester, New York, establishing the Northeast corridor as the historical center of diagnostic imaging chemistry innovation.
Northeast Corridor
Massachusetts General Hospital and Memorial Sloan Kettering anchor gadolinium-based agent demand for oncological MRI staging protocols. FDA Center for Drug Evaluation and Research safety reviews of gadolinium retention accelerate macrocyclic formulary conversions across Boston and New York academic medical centers. The Greater Boston cluster drives protocol standardization that radiates through affiliated hospital networks statewide.
Midwest
Mayo Clinic Rochester and Cleveland Clinic command enterprise-wide contract negotiations bundling contrast supply with imaging equipment service agreements. USP Chapter 797 sterile compounding mandates filter pharmacy purchasing decisions throughout Illinois, Ohio, and Michigan integrated delivery networks. The Cleveland-Akron corridor concentrates pre-filled syringe procurement for high-throughput emergency department CT suites.
South
MD Anderson Cancer Center and Texas Medical Center's unconsolidated hospital network present white-space opportunity for service-contract bundling with contrast supply. IRA hospital infrastructure provisions channel federal funding toward rural imaging equipment installation across Appalachia and the Great Plains. Houston's outpatient cardiology clinics drive microbubble echocardiography volumes for stress-echo protocols displacing nuclear perfusion studies.
Southwest
Arizona and Nevada imaging centers prioritize price-per-study metrics over supply reliability guarantees in suburban Phoenix and Las Vegas corridors. State radiological health branches impose handling protocols that filter market access for non-compliant suppliers. The Phoenix-Tucson corridor concentrates independent diagnostic facility volume for iodinated CT angiography.
Pacific Coast
Stanford Health and University of California medical centers standardize dual-energy CT protocols with spectral iodine mapping for cross-sectional imaging departments. California's Office of Statewide Health Planning and Development oversees imaging equipment capital allocation that shapes contrast demand patterns. The San Francisco Bay Area anchors precision imaging demand for research institutions commanding specialized molecular entities outside commercial formularies.
US Contrast Media Market Key Industry Players
Premium-margin players sit above commodity-margin players across formulary stickiness and supply reliability guarantees. The market structure concentrates procurement power among three to four manufacturers with vertically integrated manufacturing networks, while smaller specialists occupy niche molecular categories. Strategic archetypes include integrated diagnostic conglomerates with imaging equipment bundling capabilities, pure-play contrast manufacturers with precursor synthesis control, and regional distributors with pharmacy compounding expertise. Dominant competitive moves encompass pre-filled syringe standardization for USP 797 compliance and AI-enhanced dosing algorithm integration with power injector systems.
Within the integrated diagnostic tier, GE Healthcare exemplifies the equipment-contrast bundling archetype through comprehensive service contracts. Bracco Diagnostic, Inc. occupies a position representing supply reliability specialization across Northeast and Midwest corridors. Bayer AG sits within the cardiac catheterization-focused tier through iodinated portfolio optimization. Guerbet and Lantheus Medical Imaging, Inc. represent the mid-scale specialist archetype with concentrated presence in specific clinical applications.
| Leading Market Players |
|---|
| Bracco Diagnostic, Inc. |
| Trivitron Healthcare |
| Bayer AG |
| IMAX Diagnostic Imaging |
| CMC Contrast AB |
| GE Healthcare |
| Lantheus Medical Imaging, Inc. |
| Nano Therapeutics Pvt. Ltd. |
| Guerbet |
| Others |
Cost & Logistics Intelligence
Radiopharmacist certification bottlenecks in the Northeast corridor widen labor-cost differentials between academic medical centers and community hospitals, compressing pricing-tier spreads for sterile compounding services while elevating premiums for USP 797-compliant pre-filled delivery systems.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates macrocyclic gadolinium formulations from iodinated CT agents and legacy barium suspensions. Price differentiation hinges on FDA safety tier designation and guaranteed supply reliability metrics in vendor scorecards. Pricing pressure stems from Medicare reimbursement compression on diagnostic imaging procedures. Community hospital networks exhibit highest price sensitivity, while integrated delivery networks prioritize supply guarantees over unit cost.
Supply Chain Analysis
Direct-to-department consignment arrangements with guaranteed stock levels now handle high-volume CT suite demand across Midwest integrated delivery networks. Active pharmaceutical ingredient synthesis concentrates in coastal Chinese chemical manufacturing zones for iodinated precursors, while gadolinium chelate production anchors in European and North American facilities. Raw material dependencies span tri-iodinated benzoic acid derivatives, rare earth oxide feedstocks, and perfluorocarbon gases. Single-source vulnerability in Chinese precursor manufacturing exposes US formularies to shipping volatility. Distribution runs through vertically integrated manufacturer networks with captive pharmacy compounding capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US contrast media rests on macrocyclic formulary conversions accelerating ahead of FDA guidance, compressing clinical trial cost burdens for retention-optimized molecular entities while premium-tier pricing hardens at academic medical centers.
For Market Incumbents: Anticipate FDA macrocyclic prioritization guidance by accelerating clinical data packages for kinetic-stable chelates while freezing linear agent R&D allocation. Deepen backward integration into rare earth oxide refining to secure gadolinium feedstock against export restriction risks. Defend formulary position through pre-filled syringe standardization that locks in USP 797 compliance workflows.
For New Entrants and Emerging Players: IRA hospital infrastructure provisions in Appalachia and the Great Plains open a window for service-contract bundling with rural imaging equipment installation. Target unconsolidated hospital networks in the Texas Medical Center corridor where equipment-contrast bundling penetration remains incomplete. Pursue microbubble echocardiography white space through outpatient cardiology clinic direct sales.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play contrast manufacturers lacking imaging equipment bundling capabilities. Long-term viability centers on molecular structure patent estates and FDA safety tier positioning. Target acquisition archetype: mid-scale specialists with macrocyclic portfolios and established GPO contracts. Watch FDA draft guidance publication timing as inflection indicator for formulary investment redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Macrocyclic Gadolinium Portfolio Conversion | Aligns molecular offerings with anticipated FDA retention-risk prioritization guidance. |
| Pre-Filled Syringe Manufacturing Scale-Up | Reduces hospital pharmacy labor costs while ensuring USP Chapter 797 sterile handling compliance. |
| Integrated Service Contract Bundling | Locks in multi-year contrast supply through imaging equipment maintenance agreements at Mayo Clinic-scale IDNs. |
| AI-Enhanced Dosing Algorithm Development | Enables personalized volume optimization based on patient biometric profiles at NewYork-Presbyterian. |
| Rare Earth Oxide Supply Agreement | Secures gadolinium feedstock against export volatility through captive mining partnerships. |
Research Approach
Coverage spans the Northeast corridor, Midwest integrated delivery networks, South unconsolidated hospital systems, and Pacific Coast academic medical centers, with primary inputs from each. The analysis combines structured interviews with radiology department managers, hospital pharmacy directors, GPO contracts specialists, and contrast manufacturer commercial leads with secondary validation from FDA Center for Drug Evaluation and Research filings, USP Chapter 797 compliance databases, CMS Medicare reimbursement schedules, and hospital procurement contract repositories. Bottom-up volume modeling triangulates against top-down market sizing across product chemistry segments.
Rate-of-change decomposition separates volume growth from pricing dynamics across the projection horizon. The analytical framework models segmentation dimensions spanning product type, delivery mode, clinical application, and end-user facility scale. CAGRs derive from procedure volume projections tied to imaging equipment installation patterns and protocol standardization trends. Industry-specific forecast inputs include IRA infrastructure funding disbursement timelines and FDA safety review publication schedules.
Revisions become necessary when FDA macrocyclic prioritization guidance materializes ahead of or behind modeled assumptions, or when Chinese export restrictions disrupt iodinated precursor supply chains. Forecasts reflect documented assumptions regarding formulary conversion velocity and reimbursement stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Australia Digital X-Ray Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
China Digital X-Ray Market
Medical Imaging
Japan Computed Tomography Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
North America Digital Pathology Market
Medical Imaging
China Nuclear Imaging Market
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
Digital Pathology Market
Medical Imaging
Middle East and Africa Mammography Market
Medical Imaging
US Diagnostic Imaging Services Market
Medical Imaging
Global Veterinary Radiography System Market
Medical Imaging
Global Pediatric Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Breast Imaging Equipment Market