
 Poland Data Center Construction Market | 2026-2036
Poland Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Poland Data Center Construction Market Insights
The gap between premium hyperscale facilities and commodity enterprise builds is consolidating around power density and certification standards. AECOM leverages its engineering scale to dominate complex mission-critical campuses across Central Europe. Skanska anchors its position through sustainable construction protocols that align with tightening EU energy codes. Turner & Townsend differentiates via cost consultancy and program management for multi-phase expansions.
Data center construction encompasses the specialized engineering, mechanical and electrical installation, and structural build-out of facilities designed to house computing infrastructure with precise environmental controls, typically maintaining temperatures between 18°C and 27°C and achieving tiered redundancy ratings from Uptime Institute. Built-to-suit facilities command the deepest margin pools as cloud providers seek customized power and cooling architectures rather than generic white space. Colocation centers sustain volume leadership by serving enterprises that outsource infrastructure without bearing full capital burdens. Modular data centers are capturing share in edge deployments where speed-to-market overrides long-term optimization.
Polish construction law, the EU Energy Performance of Buildings Directive, and national fire safety regulations administered by the Generalna Dyrekcja Ochrony Środowiska shape everything from site selection to mechanical system specifications. Compliance with CE marking for electrical components and adherence to F-Gas Regulation for cooling equipment create technical barriers that favor contractors with proven certification track records. Stakeholders must weigh location decisions against evolving grid interconnection queues and renewable energy sourcing requirements before committing capital to ground-up development.
Market Dynamics
Hyperscale cloud providers are consolidating demand around purpose-built campuses with power densities exceeding 50 MW per site, compressing project timelines and squeezing mid-tier contractors from high-value mechanical and electrical work.
Growth Catalysts
- EU Green Deal carbon thresholds:The directive mandates net-zero operational emissions for new public buildings by 2030, pushing developers toward liquid cooling and on-site renewable generation to secure planning approvals.
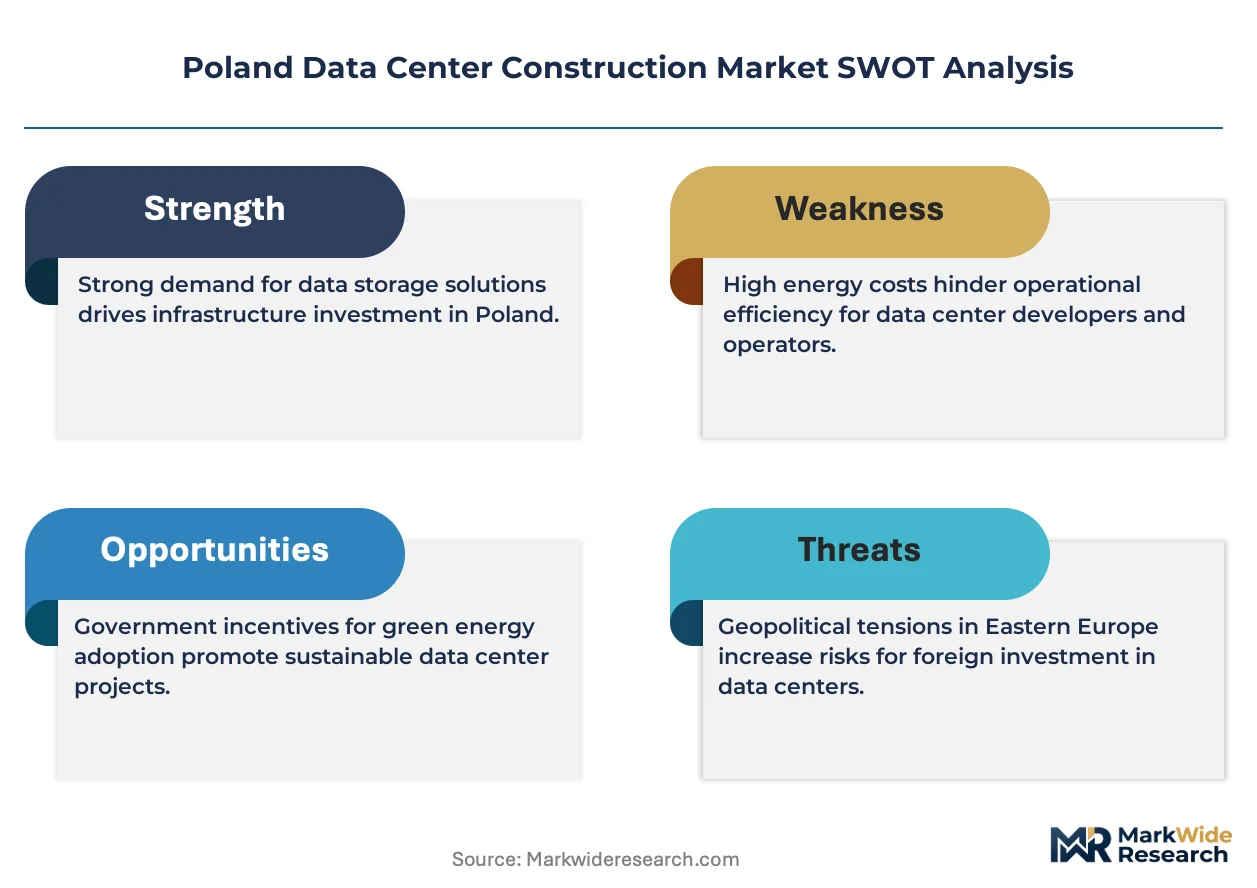
- Cloud provider expansion:Amazon Web Services, Google Cloud, and Microsoft Azure are commissioning multiple facilities across Greater Warsaw, creating sustained demand for mission-critical construction expertise.
- Fiber-optic corridor concentration:Dense fiber routes along the Silesian metropolitan corridor and Warsaw metro area reduce latency to Frankfurt and Stockholm, anchoring site selection for latency-sensitive workloads.
Market Restraints
- Grid interconnection queues:Poland's transmission system operator faces 18-24 month backlogs for new substations, delaying energization schedules and inflating carrying costs for developers.
- Copper and electrical steel volatility:Transformer and busbar materials account for 12-15% of electrical package costs, with price swings eroding fixed-price contract margins.
- F-Gas Regulation compliance:The EU phasedown of hydrofluorocarbon refrigerants forces retrofits of existing cooling designs and limits supplier pools for low-GWP alternatives.
Strategic Opportunities
- Edge node deployment in secondary cities:Kraków, Wrocław, and Poznań lack hyperscale presence but offer lower land costs and growing enterprise demand for sub-10ms latency.
- Waste heat recovery integration:District heating networks in Warsaw and Katowice present offtake agreements that improve project economics and align with EU Energy Performance of Buildings Directive targets.
- Modular prefabrication convergence:Factory-built power modules and cooling skids compress on-site construction windows, enabling faster revenue recognition for speculative builds.
Industry Challenges
- Certified mission-critical electricians:Poland produces fewer than 400 technicians annually with Uptime Institute Tier certification experience, creating bidding wars for qualified crews.
- Multi-phase expansion coordination:Live facility upgrades demand hot-work protocols and redundant system cutovers that extend program durations and insurance premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Poland Data Center Construction Market |
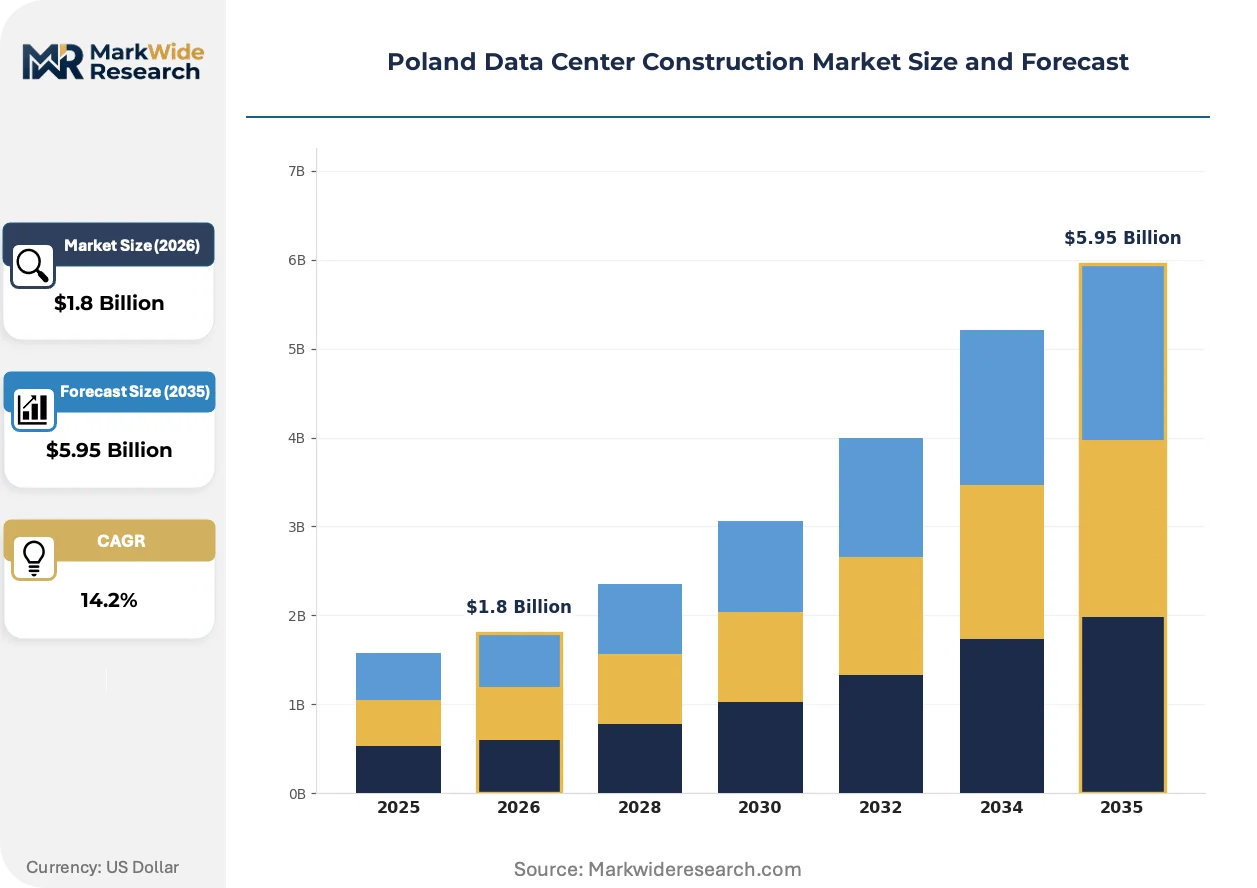
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Data Centers, Containerized Data Centers, Built-to-Suit Facilities, Colocation Centers Technology: Cooling Solutions, Power Management, UPS Systems, Network Infrastructure End User: Telecommunications, IT Services, Cloud Providers, Enterprises Deployment: On-Premise, Colocation, Hybrid, Edge |
| Companies Covered | AECOM, Jacobs, Turner & Townsend, Skanska, PORR AG, FAST Group, Atlas Ward, EdgeConneX, Vantage Data Centers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Poland Data Center Construction Market Trends and Innovations
Liquid cooling and prefabricated infrastructure are compressing traditional design-build cycles while regulatory pressure on embodied carbon forces material specification changes across the supply base.
Immersion cooling systems using dielectric fluids are modularizing deployment patterns for AI training clusters above 100 kW per rack. Cloud providers in Warsaw are piloting two-phase immersion for GPU-intensive workloads, enabling 40% footprint reduction versus air-cooled alternatives while sidestepping chiller plant lead times.
The EU F-Gas Regulation is tightening refrigerant phase-down schedules through 2030, forcing mechanical contractors to specify propane-based chillers and CO2 transcritical systems. Polish developers are absorbing 15-20% first-cost premiums for compliant equipment, with procurement teams prioritizing vendors with proven CE marking and environmental product declarations.
Enterprise buyers are consolidating vendor relationships around design-build-operate contracts that bundle construction with long-term facility management. Financial services and gaming verticals in Warsaw are displacing traditional general contracting with single-source accountability models, transferring operational risk to contractors with in-house commissioning expertise.
Poland Data Center Construction Market Segmentation
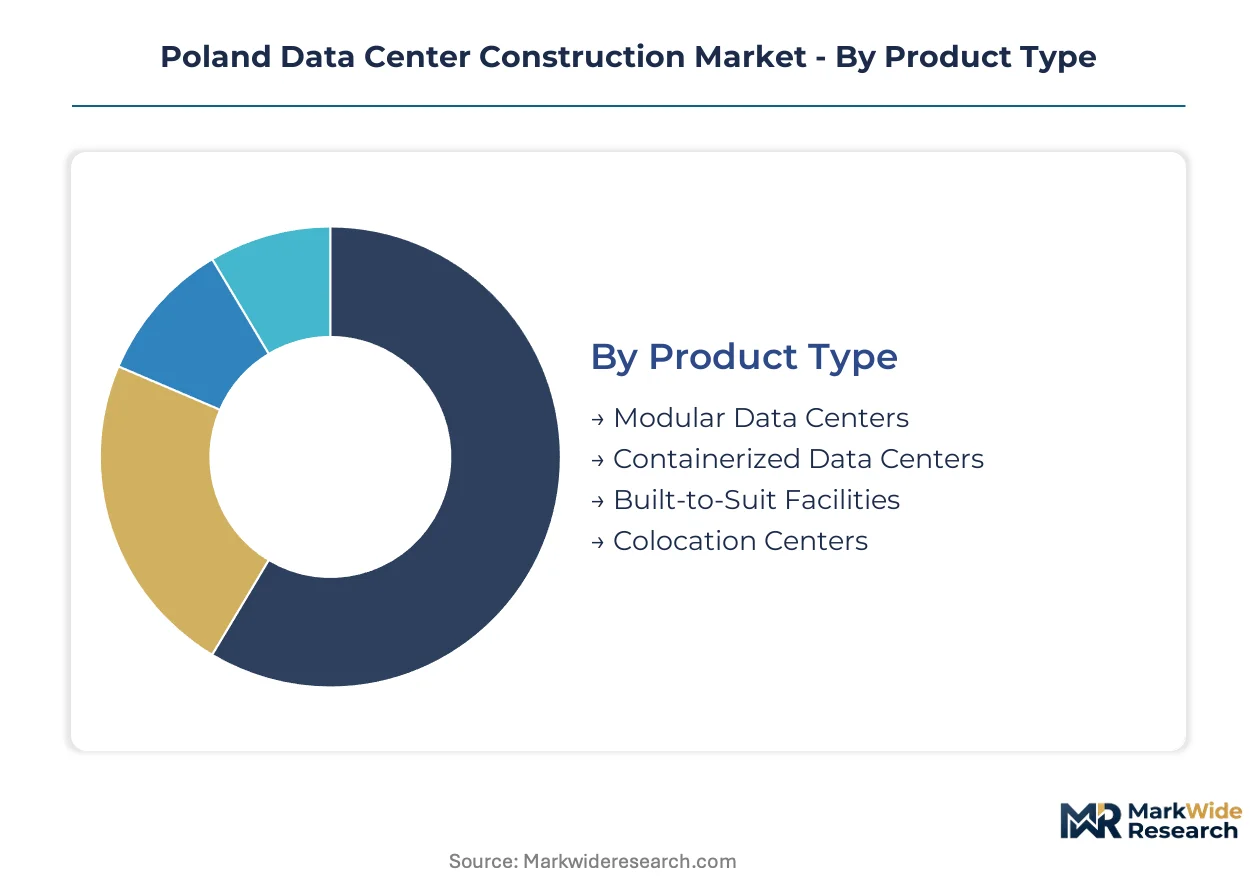
Segmentation in Poland's data center construction market reveals how facility architecture, technical infrastructure, buyer profiles, and deployment models create distinct margin pools and capability requirements for contractors. Each dimension shapes project complexity, certification standards, and revenue recognition timelines differently across the build cycle.
Product Type:
Standalone facilities dominate capital deployment, while embedded modular systems serve latency-sensitive edge workloads requiring rapid site activation.
- Built-to-Suit Facilities:Purpose-engineered campuses with customized power densities exceeding 50 MW per site. AWS, Google Cloud, and Microsoft Azure commission these across Greater Warsaw to match proprietary cooling architectures and redundancy protocols. EU Green Deal carbon thresholds push liquid cooling integration to secure planning approvals.
- Colocation Centers:Multi-tenant facilities where developers retain infrastructure ownership and lease white space to enterprises. Demand concentrates in Warsaw and the Silesian corridor where fiber connectivity to Frankfurt reduces latency for financial services and gaming workloads. Poland's national fire safety regulations administered by the Generalna Dyrekcja Ochrony Środowiska shape mechanical system specifications.
- Modular Data Centers:Factory-built power and cooling skids compress on-site construction windows for speculative builds.
- Containerized Data Centers:Self-contained units deployed in secondary cities where speed-to-market overrides long-term optimization.
Built-to-Suit Facilities lead volumes today; Modular Data Centers are gaining share fastest.
Technology:
Cost tier stratification separates premium liquid-cooled systems from commodity air-handling infrastructure, with compliance premiums widening spreads under F-Gas Regulation.
- Cooling Solutions:Chiller plants, CRAH units, and emerging immersion systems maintain 18°C to 27°C operating bands. Two-phase immersion pilots for GPU-intensive workloads in Warsaw enable 40% footprint reduction versus air-cooled alternatives. Propane-based chillers and CO2 transcritical systems absorb 15-20% first-cost premiums under EU F-Gas Regulation phasedown schedules.
- Power Management:Medium-voltage switchgear, busbar distribution, and transformer installations account for 12-15% of electrical package costs. Copper and electrical steel volatility erodes fixed-price contract margins for contractors without material hedging programs.
- UPS Systems:Battery and flywheel configurations providing Tier III and Tier IV redundancy ratings per Uptime Institute standards.
- Network Infrastructure:Fiber termination, cross-connects, and structured cabling systems.
Cooling Solutions lead volumes today; Power Management is expanding most quickly.
End User:
Customer type determines procurement complexity, with cloud providers consolidating around design-build-operate contracts and enterprises favoring traditional general contracting.
- Cloud Providers:Hyperscale operators commissioning multiple facilities across Poland with consolidated vendor relationships. These buyers demand single-source accountability models that transfer operational risk to contractors with in-house commissioning expertise.
- Enterprises:Financial services and gaming verticals in Warsaw displacing traditional contracting with bundled construction and facility management agreements.
- IT Services:Managed infrastructure providers with hybrid deployment requirements.
- Telecommunications:Mobile network operators building edge presence for 5G core infrastructure.
Cloud Providers lead volumes today; Enterprises are climbing the fastest.
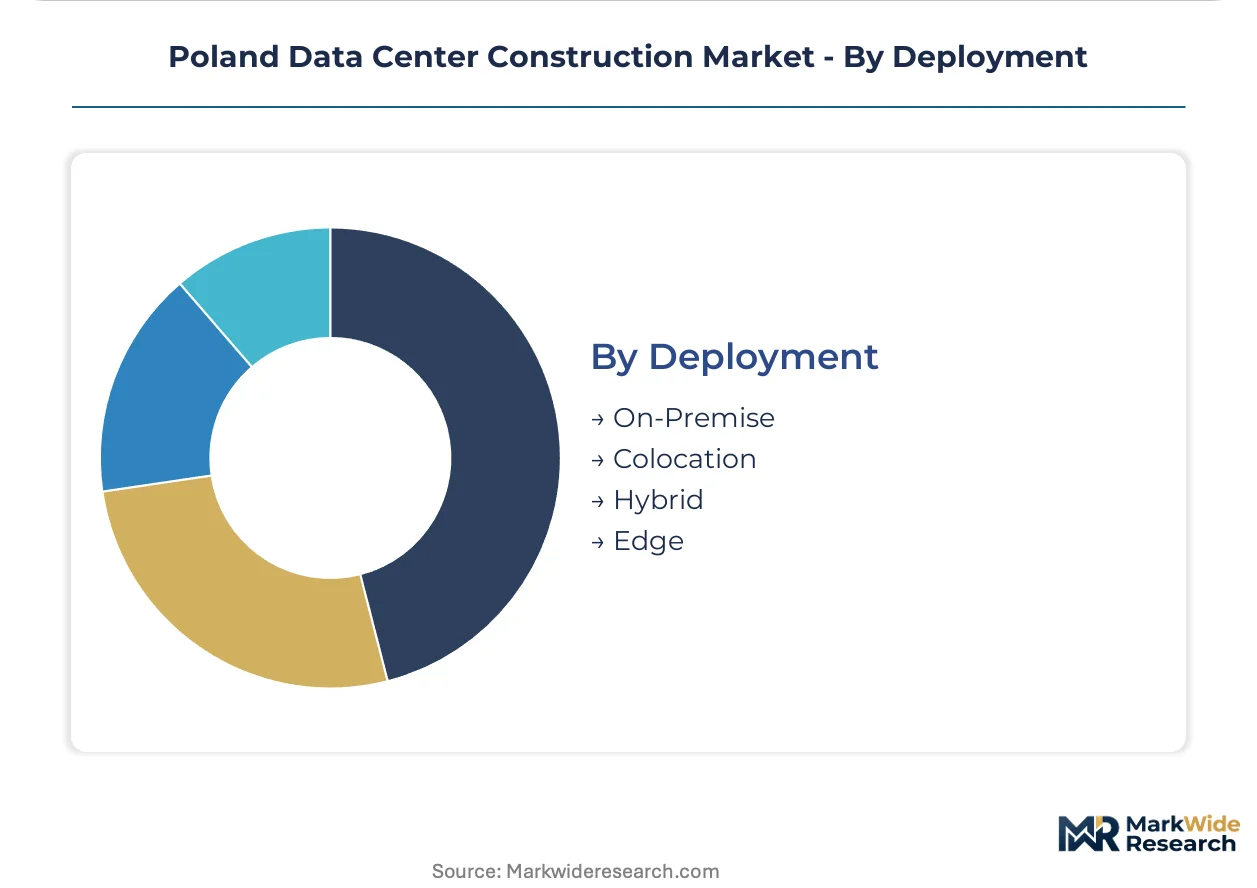
Deployment:
Geography drives site selection logic, with metropolitan concentration competing against secondary city expansion for latency positioning.
- Colocation:Third-party facilities in Warsaw and Silesia where dense fiber routes reduce latency to Stockholm and Frankfurt. Grid interconnection queues of 18-24 months delay energization schedules and inflate carrying costs.
- Edge:Distributed nodes in Kraków, Wrocław, and Poznań offering sub-10ms latency with lower land costs than Warsaw. Waste heat recovery integration with district heating networks in Katowice improves project economics.
- On-Premise:Enterprise-owned facilities with captive infrastructure management.
- Hybrid:Mixed environments combining owned and outsourced capacity.
Colocation leads volumes today; Edge is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified mission-critical electricians in Poland number fewer than 400 annually, creating acute bidding wars for qualified crews across Central European construction markets.
Greater Warsaw
Hyperscale cloud providers commission purpose-built campuses exceeding 50 MW per site across this metropolitan zone. EU Green Deal carbon thresholds mandate liquid cooling integration to secure planning approvals from municipal authorities. Dense fiber routes reduce latency to Frankfurt and Stockholm, anchoring site selection for financial services and gaming workloads.
Silesian Metropolitan Corridor
Grid capacity and fiber connectivity converge in Katowice and surrounding industrial zones, attracting data center developers seeking lower land costs than Warsaw. Waste heat recovery integration with district heating networks improves project economics under EU Energy Performance of Buildings Directive targets. PGE and Tauron manage interconnection queues stretching 18-24 months for new substations.
Kraków
Enterprise demand for sub-10ms latency drives edge node deployment in this secondary city with expanding fiber infrastructure. National fire safety regulations administered by the Generalna Dyrekcja Ochrony Środowiska shape mechanical system specifications for new builds. Jagiellonian University and tech sector growth create local talent pipelines for facility operations.
Wrocław
Lower land costs and proximity to German border markets attract modular data center deployments requiring rapid site activation. CE marking compliance for electrical components and F-Gas Regulation adherence for cooling equipment create technical barriers favoring experienced contractors. LG Chem and other industrial anchors drive sustained connectivity investment.
Poznań
Telecommunications operators build edge presence for 5G core infrastructure across this logistics hub connecting Berlin and Warsaw. Renewable energy sourcing requirements under national energy efficiency mandates influence developer capital commitments. Poznań-Ławica Airport proximity supports rapid equipment import for speculative builds.
Poland Data Center Construction Market Competitive Landscape
Top-tier vendors anchor complex mission-critical engineering, while mid-tier contractors compete for standardized electrical and mechanical packages. The market consolidates around three capability clusters: engineering-scale generalists with Central European reach, sustainable construction specialists aligned with EU energy codes, and cost consultancies focused on program management for multi-phase expansions. Dominant competitive moves include strategic partnerships with hyperscale cloud providers and portfolio diversification into waste heat recovery integration.
Within the engineering-scale tier, AECOM and Jacobs occupy positions representing transnational capability depth for hyperscale campus delivery. Turner & Townsend exemplifies the cost consultancy archetype through program management specialization. Skanska anchors sustainable construction protocols that align with tightening EU Green Deal mandates. These three entities represent distinct competitive vectors rather than interchangeable service providers.
| Leading Market Players |
|---|
| AECOM |
| Jacobs |
| Turner & Townsend |
| Skanska |
| PORR AG |
| FAST Group |
| Atlas Ward |
| EdgeConneX |
| Vantage Data Centers |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud providers commissioning 50 MW-plus campuses in Greater Warsaw anchor pricing power toward bundled design-build-operate contracts with single-source accountability. This buyer concentration compresses margins for unbundled mechanical and electrical packages while inflating premiums for certified mission-critical execution.
Pricing Analysis
Bundled design-build-operate contracts dominate hyperscale procurement, while unbundled electrical and mechanical packages serve mid-tier enterprise builds. Price differentiation rests on Uptime Institute Tier certification level and liquid cooling integration under EU Green Deal mandates. Cost compression in commodity electrical packages is intensifying because copper and electrical steel volatility erodes fixed-price contract margins. Mid-tier contractors show highest price sensitivity; hyperscale operators with consolidated vendor relationships demonstrate lowest sensitivity due to operational risk transfer.
Supply Chain Analysis
Workforce availability constraints in Poland, Germany, and the Czech Republic limit certified mission-critical electrician pools to fewer than 400 annual graduates. Electrical steel and copper for transformers, dielectric fluids for immersion cooling, and low-GWP refrigerants for F-Gas Regulation compliance constitute critical input dependencies. Single-source vulnerability runs through specialized chiller manufacturers with proven CE marking track records. Distribution runs through engineering-scale generalists with Central European reach and sustainable construction specialists aligned with tightening EU energy codes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Poland's data center construction market functions as a stable compounder. Cloud provider expansion across Greater Warsaw and the Silesian corridor generates sustained demand for mission-critical construction expertise.
For Market Incumbents: Deploy liquid cooling integration capabilities to defend margin position against commodity electrical contractors. Skanska's sustainable construction protocols and AECOM's engineering scale represent defensible moats as EU Green Deal carbon thresholds tighten. Incumbents should consolidate relationships with hyperscale cloud providers before multi-phase expansion programs lock in preferred vendor status. For New Entrants and Emerging Players: Capture edge node deployment opportunities in Kraków, Wrocław, and Poznań where sub-10ms latency demand outpaces hyperscale presence. Modular prefabrication for speculative builds offers the most penetrable entry point. New entrants should lead with factory-built power modules and cooling skids that compress on-site construction windows relative to traditional design-build cycles. For Investors and Strategic Acquirers: Engineering-scale generalists with Central European hyperscale delivery track records are the most active acquirer targets in this space. Long-term viability centers on contractors bundling construction with commissioning expertise and waste heat recovery integration capabilities. Investors should monitor grid interconnection queue clearance rates as the primary inflection indicator for development velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Integration | EU Green Deal compliance secures planning approvals from municipal authorities in Warsaw. |
| Waste Heat Recovery Partnership | District heating offtake agreements with PGE and Tauron improve project economics in Katowice. |
| Modular Prefabrication Scale-Up | Factory-built skids compress construction windows for speculative edge deployments in secondary cities. |
| Certified Workforce Development | Uptime Institute Tier certification programs address acute technician scarcity across Central Europe. |
| Design-Build-Operate Bundling | Single-source accountability transfers operational risk from cloud providers to contractors with commissioning expertise. |
Research Methodology
Multiple input streams — primary interviews with data center developers, EPC contractors, and hyperscale cloud procurement officers; secondary validation against EU regulatory filings, Polish construction permits, and hyperscaler capex disclosures; plus customs data on electrical steel and copper imports — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured mission-critical construction program timelines, certification requirements, and vendor selection criteria. Secondary sources included Generalna Dyrekcja Ochrony Środowiska environmental permits, Uptime Institute Tier certification databases, and F-Gas Regulation compliance registries.
Data-stream reconciliation across facility type, cooling technology, end-user vertical, and deployment geography enabled segmented demand modeling across the projection horizon. The analytical framework incorporated power density specifications, grid interconnection queue durations, and renewable energy sourcing requirements as industry-specific forecast inputs. CAGRs were derived from installed capacity buildout trajectories and capital expenditure patterns reported by major cloud providers.
Underlying measurement precision varies by segment; hyperscale built-to-suit facilities carry tighter precision than speculative modular deployments. Forecasts reflect assumptions regarding cloud provider expansion continuity, EU Green Deal implementation timelines, and grid infrastructure investment pacing. Material deviation in grid interconnection clearance rates or F-Gas Regulation enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
KVM Market
Data Center Infrastructure
Jakarta Data Center Market
Data Center Infrastructure
South Korea Data Center Rack Market
Data Center Infrastructure
Belgium Data Center Market
Data Center Infrastructure
Data Center UPS Market
Data Center Infrastructure
China Data Center Rack Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Russia Data Center Construction Market
Data Center Infrastructure
Thailand Data Center Rack Market
Data Center Infrastructure
DCIM Market
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
Data Quality Management Market
Data Center Infrastructure
India Data Center Server Market
Data Center Infrastructure
Japan Data Center Physical Security Market
Data Center Infrastructure
Malaysia Data Center Construction Market
Data Center Infrastructure
Netherlands Data Center Rack Market