
 Global Content Delivery Network (CDN) Software Market | 2026-2036
Global Content Delivery Network (CDN) Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Content Delivery Network (CDN) Software Market Foresight
Edge caching revenue is reshaping margin distribution across the CDN value chain. Akamai leverages its proprietary edge server footprint to sustain premium positioning in latency-sensitive segments. Cloudflare anchors its expansion through integrated cloud security and zero-trust networking capabilities. Amazon CloudFront dominates within the AWS ecosystem, extending reach through native integration with compute and storage services.
Content Delivery Network (CDN) software distributes digital content through geographically dispersed proxy servers, reducing latency by caching static and dynamic assets at points of presence typically located within 50 milliseconds of end users; its primary purpose is to ensure reliable, high-performance content delivery for web applications, streaming media, and software distribution. The media and entertainment application segment leads in absolute traffic volume, though cloud security within the solution offering dimension captures disproportionate margin as enterprises harden distributed infrastructure. Hybrid cloud deployment models are gaining structural importance as organizations balance sovereignty requirements with scalability needs across regulated and unregulated workloads.
The EU AI Act and GDPR impose content provenance and data residency obligations that shape CDN architecture decisions across European deployments. The FCC in the United States and MIIT in China enforce network neutrality and cross-border data flow restrictions that determine peering arrangements and edge node placement. Stakeholders must monitor how divergent national frameworks for content governance and data sovereignty reshape the economics of global edge infrastructure deployment.
Market Dynamics
Edge computing architectures are forcing CDN providers to rebuild infrastructure for sub-50-millisecond latency requirements, compressing traditional hub-and-spoke distribution economics while opening new revenue pools in real-time processing.
Growth Catalysts
- EU AI Act compliance mandates:Content provenance requirements across European deployments are accelerating investment in verifiable edge infrastructure and audit-ready caching systems.
- Live streaming bandwidth surge:Sports betting platforms and interactive entertainment services in India are driving capacity expansion at metropolitan points of presence.
- Zero-trust security integration:Enterprise buyers now bundle CDN procurement with SASE requirements, pulling security-conscious vendors into preferred supplier positions.
Market Restraints
- Energy cost volatility:Edge server power consumption in Germany faces pressure from the EU Green Deal carbon border adjustments and renewable transition timelines.
- Peering concentration risk:Tier-1 network interconnection in the United States depends on a narrowing set of backbone providers, creating single-point-of-failure exposure.
- IPv4 address exhaustion:Legacy protocol limitations complicate node expansion in emerging markets where carrier-grade NAT introduces routing instability.
Strategic Opportunities
- India tier-2 city buildout:Underpenetrated markets including Jaipur, Lucknow, and Indore lack sufficient edge density for 4K streaming and cloud gaming latency thresholds.
- Healthcare data localization:HIPAA-adjacent state laws in the United States are creating demand for sovereign caching zones that separate regulated from unregulated workloads.
- WebAssembly edge runtime convergence:Portable compute modules are collapsing the distinction between CDN and serverless platforms, enabling new application architectures.
Industry Challenges
- Edge DevOps talent scarcity:Distributed systems engineering expertise remains concentrated in Seattle, San Francisco, and Bangalore, constraining deployment velocity elsewhere.
- Multi-cloud orchestration complexity:Enterprises operating across AWS, Azure, and Google Cloud require abstraction layers that introduce latency penalties and vendor coordination overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Content Delivery Network (CDN) Software Market |
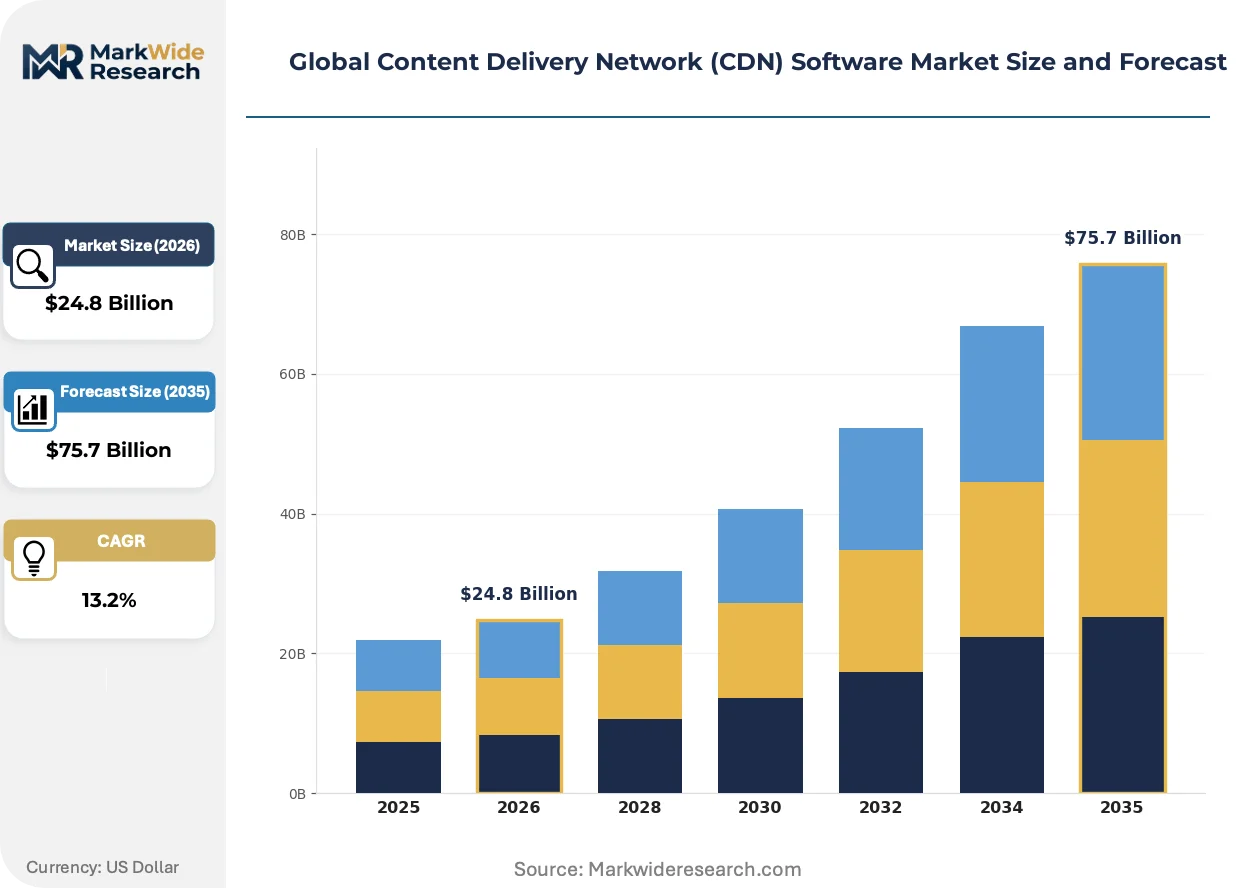
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $75.7 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Edge Caching, Load Balancing, Video Streaming, Web Acceleration, Cloud Security, Analytics Platform Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud, On-Premises, Distributed Network Application: Media & Entertainment, E-Commerce, Gaming, E-Learning, Enterprise Content Distribution, Digital Advertising End User Industry: Telecommunications Providers, Financial Services, Government Agencies, Educational Institutions, Software Developers, Cloud Service Providers |
| Companies Covered | Fastly, KeyCDN, Cloudflare, Microsoft Azure CDN, StackPath, Akamai, CDN77, Google Cloud CDN, Amazon CloudFront, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Content Delivery Network (CDN) Software Market Shifts & Advancements
Real-time personalization and immersive media formats are compressing acceptable latency thresholds from hundreds of milliseconds to sub-20-millisecond targets, rewriting infrastructure investment priorities across the value chain.
Serverless edge computing is hybridizing content delivery with application logic execution. Media companies in South Korea now deploy personalized ad insertion and dynamic bitrate adjustment at the network edge rather than origin servers. This convergence collapses the traditional separation between CDN and compute infrastructure, enabling interactive live experiences that were previously architecturally impossible.
The EU AI Act's transparency requirements are reshaping data handling protocols for machine-learning-generated content. Platforms distributing synthetic media must now maintain verifiable audit trails from creation through distribution. France's CNIL and Germany's data protection authorities are actively enforcing these provisions, forcing infrastructure providers to implement cryptographic content provenance systems that add processing overhead but create compliance differentiation.
Enterprise procurement patterns are fragmenting as buyers unbundle security, performance, and analytics components that were previously purchased as integrated suites. Financial services firms in Singapore now separately evaluate web application firewalls, bot management, and edge caching providers, compressing contract values for full-stack vendors while opening niches for specialized challengers. This disaggregation is most visible in regulated industries where compliance teams demand component-level auditability.
Global Content Delivery Network (CDN) Software Market Segmentation
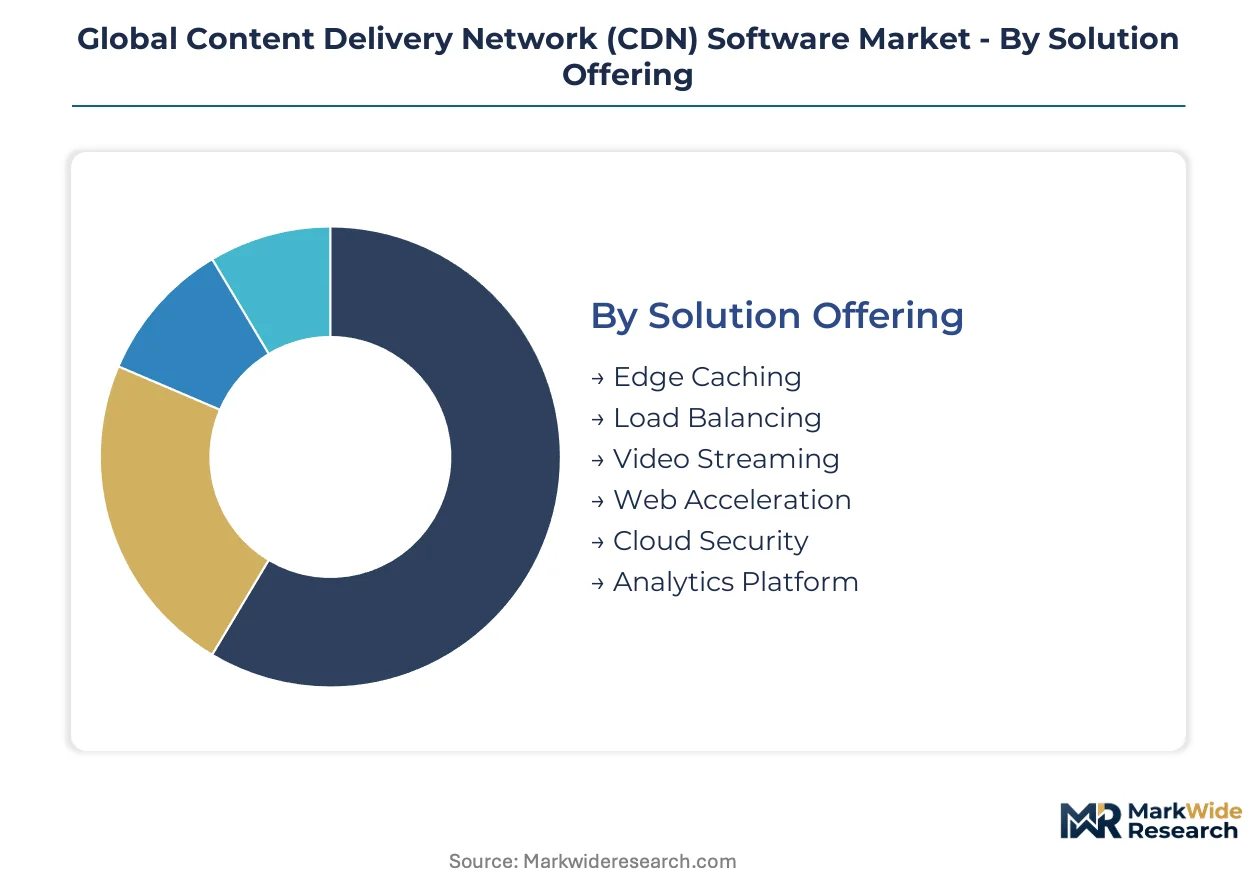
CDN software segmentation reveals how infrastructure investment priorities diverge across latency requirements, compliance obligations, and traffic patterns. Buyers configure solutions around specific performance thresholds rather than purchasing uniform platforms.
Solution Offering:
Mature caching and acceleration technologies anchor procurement budgets while emerging security-integrated and analytics-driven modules capture disproportionate expansion.
- Edge Caching:Distributed proxy servers store static assets within 50 milliseconds of end users, reducing origin server load and transit costs. Demand concentrates among streaming platforms in India and Germany as 4K video traffic saturates metropolitan networks.
- Cloud Security:Web application firewalls, DDoS mitigation, and bot management deploy at edge nodes to intercept threats before reaching origin infrastructure. Financial services firms in Singapore and the United States bundle these capabilities with performance procurement under zero-trust mandates.
- Load Balancing:Traffic distribution algorithms optimize server utilization across distributed architectures.
- Video Streaming:Adaptive bitrate delivery and live event caching optimize bandwidth for broadcast-scale audiences.
- Web Acceleration:Protocol optimization and compression reduce page load times for dynamic applications.
- Analytics Platform:Real-time telemetry and audience measurement tools inform content distribution decisions.
Edge Caching retains volume leadership; Cloud Security holds the steepest expansion curve.
Deployment Model:
Cost tier segmentation separates commodity public cloud deployments from premium sovereign and distributed configurations carrying compliance premiums.
- Public Cloud:Shared infrastructure delivers elastic capacity without capital expenditure, appealing to startups and seasonal traffic patterns. E-commerce platforms in the United States and South Korea dominate consumption as flash sales and live commerce events drive unpredictable demand spikes.
- Hybrid Cloud:Split architectures separate regulated workloads in private environments from scalable public-facing traffic. Healthcare systems across Germany and France deploy this model to satisfy GDPR and EU AI Act data residency requirements while maintaining performance.
- Private Cloud:Dedicated infrastructure serves single-tenant compliance and latency requirements.
- Multi-Cloud:Abstraction layers coordinate across AWS, Azure, and Google Cloud to avoid vendor lock-in.
- On-Premises:Self-managed edge nodes serve classified government and defense applications.
- Distributed Network:Federated architectures place compute and storage at cellular towers and ISP points of presence.
Public Cloud captures the largest deployment base; Hybrid Cloud is climbing the fastest as sovereignty requirements harden.
Application:
Application segmentation tracks how bandwidth intensity and interactivity requirements reshape infrastructure specifications across verticals.
- Media & Entertainment:Video-on-demand libraries, live sports broadcasts, and music streaming consume the absolute majority of global CDN traffic. Platforms in India and Brazil drive capacity expansion as subscription growth outpaces infrastructure buildout in tier-2 cities.
- Gaming:Cloud gaming services and multiplayer synchronization demand sub-20-millisecond latency that traditional architectures cannot satisfy. South Korean and Japanese operators deploy specialized edge nodes to support real-time competitive titles and emerging metaverse applications.
- E-Commerce:Product imagery, checkout acceleration, and personalized recommendations optimize conversion rates.
- E-Learning:Video lectures and interactive assessments require reliable delivery across variable connectivity environments.
- Enterprise Content Distribution:Software updates, internal video communications, and SaaS application delivery serve distributed workforces.
- Digital Advertising:Real-time bidding systems and dynamic creative optimization execute at edge scale.
Media & Entertainment retains volume leadership; Gaming holds the steepest expansion curve.
End User Industry:
Customer type segmentation distinguishes between infrastructure owners building proprietary networks and enterprise buyers purchasing CDN as a managed service.
- Telecommunications Providers:Mobile and fixed-line operators deploy CDN to reduce transit costs and differentiate consumer broadband offerings. Carriers in Germany and India invest heavily as 5G fixed wireless and fiber expansion create capacity competition.
- Cloud Service Providers:Hyperscalers integrate CDN with compute and storage portfolios to capture workload gravity. Amazon, Microsoft, and Google leverage native integration to pull enterprise customers into unified cloud ecosystems across the United States and Western Europe.
- Financial Services:Banks and trading platforms prioritize security and low-latency market data distribution.
- Government Agencies:Sovereign requirements drive classified and public service content delivery investments.
- Educational Institutions:Universities and K-12 systems scale video learning and research data distribution.
- Software Developers:Application vendors embed CDN APIs for global SaaS performance.
Telecommunications Providers retain volume leadership; Cloud Service Providers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across geographies. Buyers in India and Brazil demand volume-scaled commodity pricing, while German and US enterprises absorb premium rates for sovereign compliance and sub-50-millisecond latency guarantees.
United States
Live sports betting platforms and interactive streaming services drive edge capacity expansion in metropolitan markets. FCC network neutrality enforcement shapes peering arrangements between backbone providers and CDN operators. Northern Virginia's data center corridor hosts the densest concentration of hyperscale edge nodes, with Amazon CloudFront and Microsoft Azure CDN maintaining primary presence.
Germany
Industrial IoT and automotive software distribution require localized caching for predictive maintenance systems and over-the-air updates. EU AI Act content provenance mandates and GDPR data residency rules force hybrid deployment architectures. Frankfurt's internet exchange anchors central European traffic exchange, while Munich and Berlin host specialized nodes for regulated healthcare and financial workloads.
India
Mobile-first video consumption and cloud gaming penetration in tier-2 cities outstrip existing edge density. TRAI's net neutrality framework and data localization guidance influence infrastructure investment patterns. Hyderabad and Bangalore clusters concentrate engineering talent and hyperscaler partnerships, though Jaipur, Lucknow, and Indore remain underserved for 4K streaming latency thresholds.
South Korea
Esports broadcasting and metaverse platform requirements push latency demands below 20 milliseconds. Korea Communications Commission regulations govern content distribution licensing and cross-border data flows. Seoul's metropolitan network hosts specialized gaming-optimized edge infrastructure, with Busan-Ulsan corridor expanding for maritime logistics and port automation applications.
Brazil
Subscription video growth and live commerce events strain metropolitan CDN capacity in São Paulo and Rio de Janeiro. ANATEL's infrastructure sharing mandates and local content quotas shape provider market entry strategies. São Paulo state concentrates 60 percent of national data center investment, though Belo Horizonte and Porto Alegre emerge as secondary hubs for regional redundancy.
Global Content Delivery Network (CDN) Software Market Competitive Landscape
Capability concentration sits with specialized edge computing vendors; scale advantage sits with hyperscale cloud platforms integrated with broader infrastructure portfolios. The market structure splits between premium latency-optimized specialists and volume-driven ecosystem players. Three archetypes dominate: security-integrated platforms, developer-centric edge compute providers, and cloud-native distribution services bundled with storage and compute. Competitive moves center on zero-trust security bundling and sovereign compliance certification for regulated industries.
Among security-integrated specialists, Cloudflare exemplifies the converged edge-security archetype through its zero-trust networking positioning. Akamai occupies the established latency-optimized tier with proprietary server footprint advantages. Amazon CloudFront anchors the hyperscale ecosystem play through native AWS integration. These three represent distinct strategic vectors rather than direct substitution competitors.
| Leading Market Players |
|---|
| Fastly |
| KeyCDN |
| Cloudflare |
| Microsoft Azure CDN |
| StackPath |
| Akamai |
| CDN77 |
| Google Cloud CDN |
| Amazon CloudFront |
| Others |
Supply & Pricing Matrix
Server-grade solid-state drive manufacturing concentrates in South Korea and Taiwan, anchoring cost structures for edge node deployment and concentrating margin capture with hyperscale cloud providers who negotiate direct component supply agreements.
Pricing Analysis
Extended service contracts and managed security bundles drive lifetime value more than raw bandwidth pricing. Three-tier pricing structure across premium, standard, and economy levels separates sovereign-compliant deployments from commodity public cloud offerings. Cost compression in the economy tier is intensifying because Indian and Brazilian buyers demand volume-scaled rates for video streaming. Financial services firms in Singapore and Germany show lowest price sensitivity, absorbing premiums for zero-trust integration and sub-50-millisecond latency guarantees.
Supply Chain Analysis
Upstream feedstock for edge infrastructure draws from semiconductor fabrication in Taiwan, South Korea, and the United States, with memory modules and network processors forming critical input categories. Power distribution equipment and precision cooling systems constitute secondary dependencies. Single-source vulnerability concentrates in advanced node chip fabrication. Distribution runs through hyperscaler direct procurement channels and carrier-managed service partnerships, bypassing traditional IT distribution tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge DevOps engineering talent scarcity constrains deployment velocity outside Seattle, Bangalore, and Frankfurt clusters, creating acquisition premiums for teams with distributed systems expertise.
For Market Incumbents: Build proprietary server footprint moats through accelerated point-of-presence expansion in tier-2 Indian cities and German automotive corridors. Defensive consolidation should prioritize zero-trust certification investments to counter Cloudflare's security-integrated positioning. Capacity addition in Hyderabad and Munich anchors latency guarantees against hyperscaler ecosystem plays. For New Entrants and Emerging Players: Pursue healthcare data localization as the most penetrable white-space target, where HIPAA-adjacent state laws in the United States create demand for sovereign caching zones. WebAssembly edge runtime convergence offers a technical wedge for collapsing CDN-serverless distinctions. Channel partnerships with electronic health record vendors accelerate enterprise access without direct sales infrastructure. For Investors and Strategic Acquirers: Capital is best deployed toward developer-centric edge compute providers with WebAssembly runtime capabilities and established multi-cloud orchestration layers. Long-term viability favors platforms that bridge security, performance, and analytics components as enterprise procurement disaggregates. The signal to watch is hyperscaler capex allocation toward custom silicon for edge inference workloads.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Trust Security Certification | EU AI Act and GDPR enforcement in Germany and France mandate audit-ready edge infrastructure. |
| Edge Node Expansion | Jaipur, Lucknow, and Indore in India lack sufficient density for 4K streaming latency thresholds. |
| WebAssembly Runtime Integration | South Korean media companies deploy personalized ad insertion at network edge rather than origin servers. |
| Healthcare Sovereign Caching Zones | HIPAA-adjacent state laws in the United States separate regulated from unregulated workloads. |
| Multi-Cloud Orchestration Platform | Enterprises operating across AWS, Azure, and Google Cloud require abstraction layers reducing vendor coordination overhead. |
Research Methodology
The analysis maps edge caching, cloud security, load balancing, and video streaming solution offerings, each validated through infrastructure architects at telecommunications providers, cloud procurement officers at financial services firms, platform engineers at streaming media companies, and regulatory compliance leads at healthcare systems. Primary interview findings triangulate against hyperscaler capex disclosures, TRAI and FCC regulatory filings, EU AI Act implementation guidance, and SEC 10-K infrastructure investment disclosures. Bottom-up point-of-presence deployment counts reconcile with top-down bandwidth demand estimates.
Assumptions held fixed include sustained 5G fixed wireless expansion timelines in Germany and India, EU AI Act content provenance enforcement patterns, and prevailing net neutrality frameworks under FCC and TRAI jurisdiction. The modeling period spans solution offering, deployment model, application, and end user industry dimensions, with regional adoption patterns and latency requirement tiers as secondary segmentation axes. CAGRs derive from installed base growth curves and traffic intensity projections, with edge computing architecture shift and live streaming bandwidth surge as primary demand drivers.
Sensitivities concentrate around energy cost volatility in Germany affecting edge server economics, IPv4 address exhaustion complicating emerging market expansion, and divergent national data sovereignty frameworks reshaping peering arrangements. Cross-checking against hyperscaler quarterly infrastructure investment disclosures and carrier capital expenditure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center and Networking
Middle East Data Center Server Market
Data Center and Networking
Network Optimization Services Market
Data Center and Networking
Data Center Networks Market
Data Center and Networking
Virtual Networking Market
Data Center and Networking
Mobile Data Offload Market
Data Center and Networking
Cluster Computing Market
Data Center and Networking
Dedicated Internet Access Market
Data Center and Networking
Taiwan Data Center Networking Market
Data Center and Networking
Mobile Data Traffic Market
Data Center and Networking
Data Center Servers Market
Data Center and Networking
Japan Data Center Networking Market
Data Center and Networking
Network As a Service (Naas) Market
Data Center and Networking
Italy Data Center Networking Market
Data Center and Networking
Data Deduplication Tools Market
Data Center and Networking
Global Network Configuration and Change Management Market
Data Center and Networking
India Data Center Networking Market