
 India Container Glass Market | 2026-2036
India Container Glass Market Size, Share, and Industry Trends Forecast 2026-2036
India Container Glass Market Foresight
Modular packaging configurations is restructuring buyer choice across India's container glass sector as brands unbundle bulk pharmaceutical shipments into smaller, serialization-ready vial sets. Haldyn Glass Limited leverages its Gujarat manufacturing base to anchor supply for domestic pharma exporters. Piramal Glass Limited differentiates through specialized molded glass capabilities for cosmetic and pharmaceutical applications. AGI Glaspac competes on scale across the food and beverage bottle segment with distributed furnace operations.
Container glass comprises silica-soda-lime formulations melted at temperatures exceeding 1500°C and formed through blow-and-blow or press-and-blow processes to create impermeable, chemically inert vessels for liquid and solid storage. The material's oxygen and moisture barrier properties make it indispensable for shelf-stable pharmaceuticals and reactive chemical contents. Bottles occupy the largest volume share within product type classifications, while vials command premium positioning through stringent pharmacopeial compliance requirements. The 50-500 ml capacity band captures the widest end-user crossover, spanning spirits, sauces, and prescription liquid formulations where standardization reduces mold changeover costs.
BIS mandatory certification for food-contact glassware and FSSAI packaging material safety regulations directly determine market access for domestic producers and importers alike. CDSCO's evolving pharmaceutical packaging guidelines for primary containers further tighten dimensional and chemical durability specifications for vial and bottle suppliers. Stakeholders must monitor how state-level plastic ban extensions in Maharashtra, Tamil Nadu, and Karnataka redirect beverage and condiment packaging decisions toward glass alternatives.
Market Dynamics
Serialization mandates for pharmaceutical packaging are forcing container glass producers to reconfigure mold designs and quality systems around track-and-trace compatibility. This structural pressure cascades from CDSCO's evolving primary container guidelines through every tier of the supply chain.
Growth Catalysts
- FSSAI packaging material safety regulations:Mandatory compliance for food-contact glassware redirects condiment and beverage brands toward certified domestic suppliers, expanding addressable demand for amber and flint glass bottles.
- Maharashtra-Tamil Nadu plastic ban extensions:State-level prohibitions on single-use plastics in India's densest consumption corridors accelerate substitution toward glass alternatives for sauces, spirits, and personal care products.
- Borosilicate vial demand from injectable formulations:Biologic drug pipelines require chemically inert primary containers with thermal shock resistance, pulling specialized capacity expansion from domestic manufacturers.
Market Restraints
- Natural gas price volatility:Furnace operations consume methane-derived energy for sustained 1500°C melting, exposing margin structures to input cost swings without pass-through mechanisms in long-term pharma contracts.
- Imported cullet supply concentration:Quality recycled glass feedstock depends on fragmented collection networks across Gujarat and Maharashtra, constraining output scale for circular production claims.
- Aluminum and polymer substitution:Lightweight aseptic cartons and multilayer plastic bottles capture share in mass-market beverages where barrier requirements permit non-glass solutions.
Strategic Opportunities
- Karnataka and Telangana pharma clusters:Underpenetrated southern states with expanding formulation facilities present greenfield demand for localized vial and bottle supply, reducing logistics costs for exporters.
- PLI scheme for specialty glass:Production-linked incentives for technical glass manufacturing subsidize capital investment in borosilicate capacity, lowering breakeven thresholds for domestic players.
- Direct-to-pharma distribution platforms:Digital procurement channels bypass traditional distributor markups, enabling smaller mold houses to access formulation facilities without intermediaries.
Industry Challenges
- Pharmacopeial certification timelines:USP and EP compliance testing for vial dimensional stability extends qualification cycles, delaying revenue recognition on new mold investments.
- Furnace rebuild capex intensity:Refractory lining replacement every 10-12 years requires production halts and capital deployment exceeding smaller player balance sheet capacity.
- Serialization integration complexity:Embedding unique identifiers at forming stage demands retrofits to legacy IS machines, disrupting output rates during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Container Glass Market |
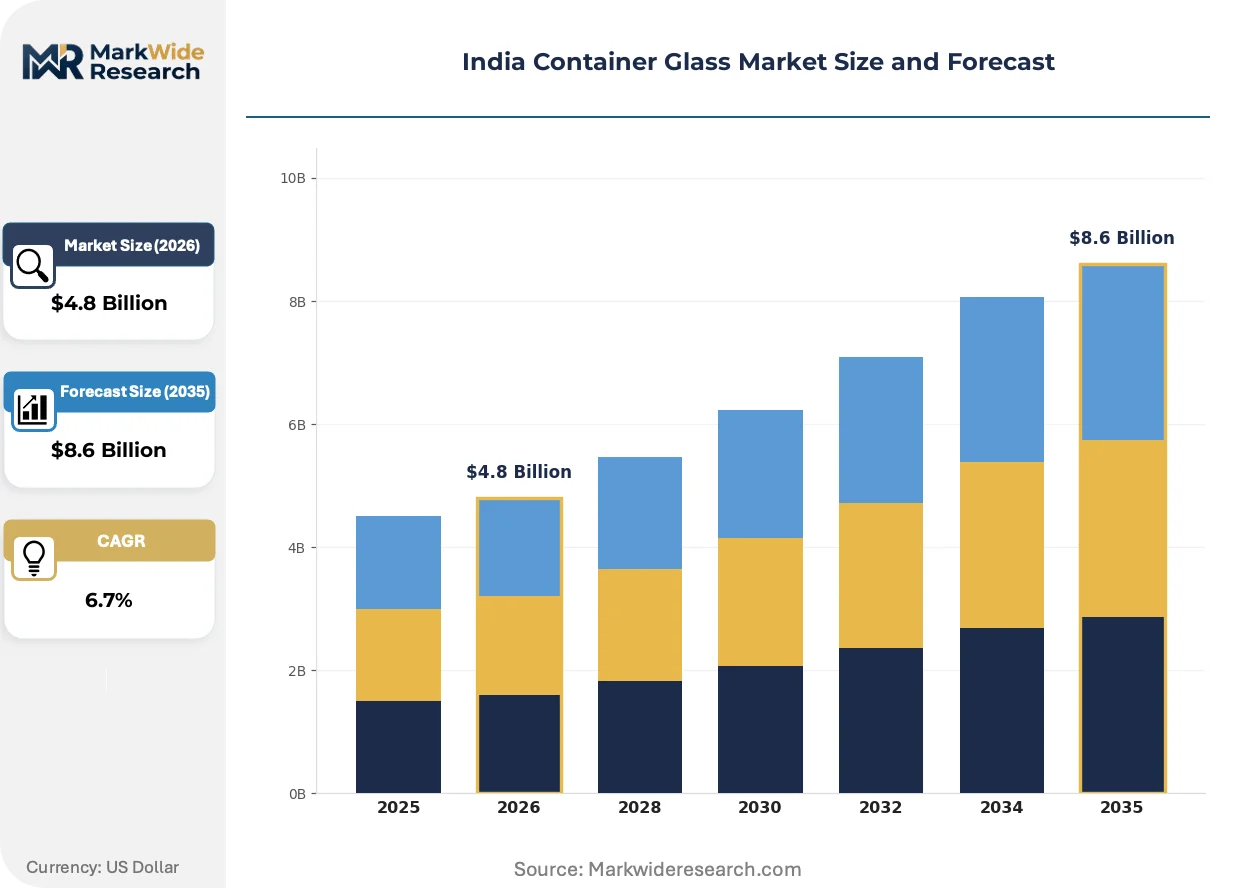
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Vials, Canisters End User: Food & Beverage, Pharmaceuticals, Cosmetics, Chemicals Capacity: 0-50 ml, 50-500 ml, 500 ml-1 L, Above 1 L Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Gerresheimer AG, Haldyn Glass Limited, AGI Glaspac, Eagle Glass Deco (P.) Ltd, Hindusthan National Glass & Industries Limited, Piramal Glass Limited, Schott Kaisha Pvt Ltd, Sunrise Glass Industries Private Limited, Borosil Glass Works Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Container Glass Market Shifts & Advancements
Active restructuring of buyer-supplier relationships around smaller lot sizes and faster mold changeovers is compressing traditional economies of scale in Indian container glass. Three interconnected developments are reshaping competitive positioning.
Lightweighting technology is modularizing product architecture across the 50-500 ml capacity band. Thinner wall designs maintain structural integrity through optimized silica-soda-lime formulations, reducing material input per unit. Generic pharma exporters in Gujarat and Maharashtra are adopting these configurations to offset freight costs in international shipments, while the technology is modularizing supplier relationships toward multi-source, shorter-contract arrangements that favor flexible furnace operations over volume commitments.
CDSCO's draft guidelines on primary container dimensional tolerances are tightening pharmacopeial alignment requirements for vial neck finish specifications. This regulatory compression forces mold shops to upgrade CNC engraving capabilities and statistical process control systems. Injectable formulation facilities in Baddi and Hyderabad are responding by consolidating supplier panels toward certified domestic producers with documented compliance trails, away from opportunistic imports.
Brand procurement of container glass is fragmenting toward specification-driven spot purchasing from long-term single-source contracts. Food and beverage multinationals in India now run parallel supplier qualification tracks for standard versus premium flint grades, enabling dynamic allocation based on real-time quality audits. This behavioral shift is most visible in Maharashtra's spirits and condiment corridors, where seasonal demand spikes favor distributed sourcing over captive supply arrangements.
India Container Glass Market Segmentation
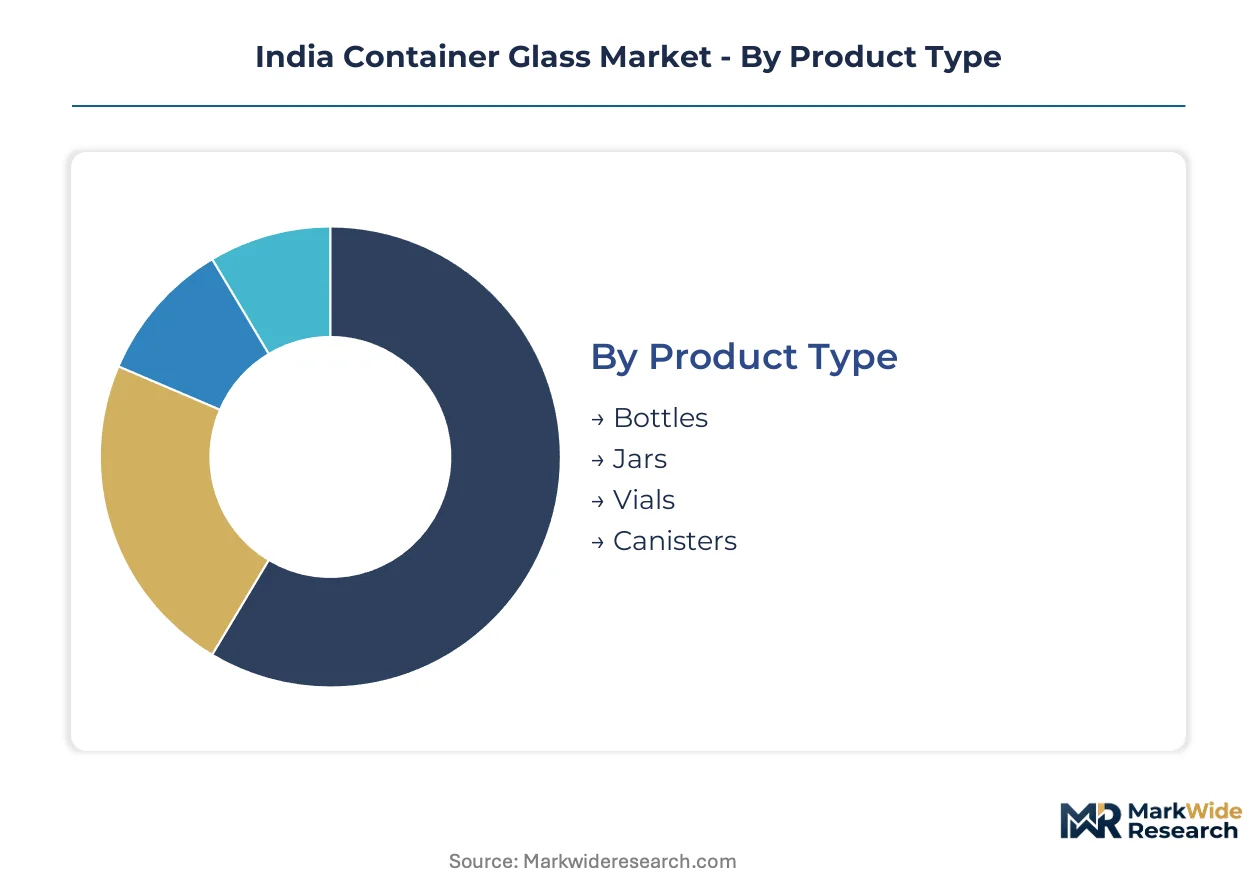
Container glass segmentation in India reflects divergent furnace economics and compliance burdens across end-use applications. Product type and capacity configurations determine mold investment cycles, while distribution channel selection shapes working capital intensity for suppliers.
Product Type:
Supply concentration clusters around formats with pharmacopeial certification requirements, where furnace qualification timelines create defensive moats for incumbent producers.
- Bottles:Silica-soda-lime formulations dominate this segment through blow-and-blow forming of 50-500 ml spirits, sauces, and beverage containers. Maharashtra and Gujarat absorb the majority of output through dense food processing corridors, though lightweighting pressures are compressing material input per unit.
- Vials:Borosilicate compositions with thermal shock resistance serve injectable pharmaceutical formulations requiring USP and EP dimensional compliance. Baddi and Hyderabad formulation facilities are consolidating supplier panels toward certified domestic producers with documented compliance trails.
- Jars:Wide-mouth configurations preserve condiments and spreads through press-and-blow processes with lower neck finish tolerance requirements than vials. FSSAI certification mandates redirect procurement toward BIS-certified domestic suppliers.
- Canisters:Large-format cylindrical containers store bulk chemicals and institutional food service quantities above 1 L capacity. Chemical processing clusters in Gujarat concentrate demand for amber and flint variants with chemical durability specifications.
Today's leader: Bottles. Tomorrow's challenger: Vials.
End User:
Application-driven margin stratification separates premium pharmacopeial grades from commodity food-contact specifications.
- Pharmaceuticals:Primary container regulations from CDSCO enforce dimensional stability and chemical durability testing for vial and bottle suppliers. Serialization mandates are forcing mold design reconfigurations around track-and-trace compatibility.
- Food & Beverage:FSSAI packaging material safety regulations redirect condiment and beverage brands toward certified domestic suppliers. Maharashtra-Tamil Nadu plastic ban extensions accelerate substitution toward glass alternatives for sauces and spirits.
- Cosmetics:Molded glass capabilities for premium fragrance and skincare applications require specialized decorative finishing equipment. Piramal Glass Limited anchors supply through dedicated cosmetic glass furnace capacity.
- Chemicals:Reactive contents demand chemically inert vessels with oxygen and moisture barrier properties. Gujarat chemical processing clusters source amber variants for light-sensitive formulations.
Pharmaceuticals command premium positioning. Food & Beverage delivers volume scale.
Capacity:
Furnace output allocation follows mold changeover economics, with mid-range formats capturing the widest end-user crossover.
- 50-500 ml:The dominant capacity band spans spirits, sauces, and prescription liquid formulations where standardization reduces mold changeover costs. Generic pharma exporters adopt lightweighted configurations to offset international freight costs.
- 0-50 ml:Small vial formats serve injectable biologics requiring precise dosing and serialization-ready packaging. CDSCO draft guidelines on dimensional tolerances are tightening pharmacopeial alignment requirements.
- 500 ml-1 L:Intermediate formats bridge retail beverage and institutional condiment applications. Seasonal demand spikes in Maharashtra's spirits corridors favor distributed sourcing over captive supply.
- Above 1 L:Large-format canisters serve bulk chemical storage and food service quantities with lower per-unit value density. Chemical processing facilities in Gujarat concentrate procurement for amber variants.
50-500 ml anchors current furnace utilization. 0-50 ml vials are climbing the fastest on biologics pipeline expansion.
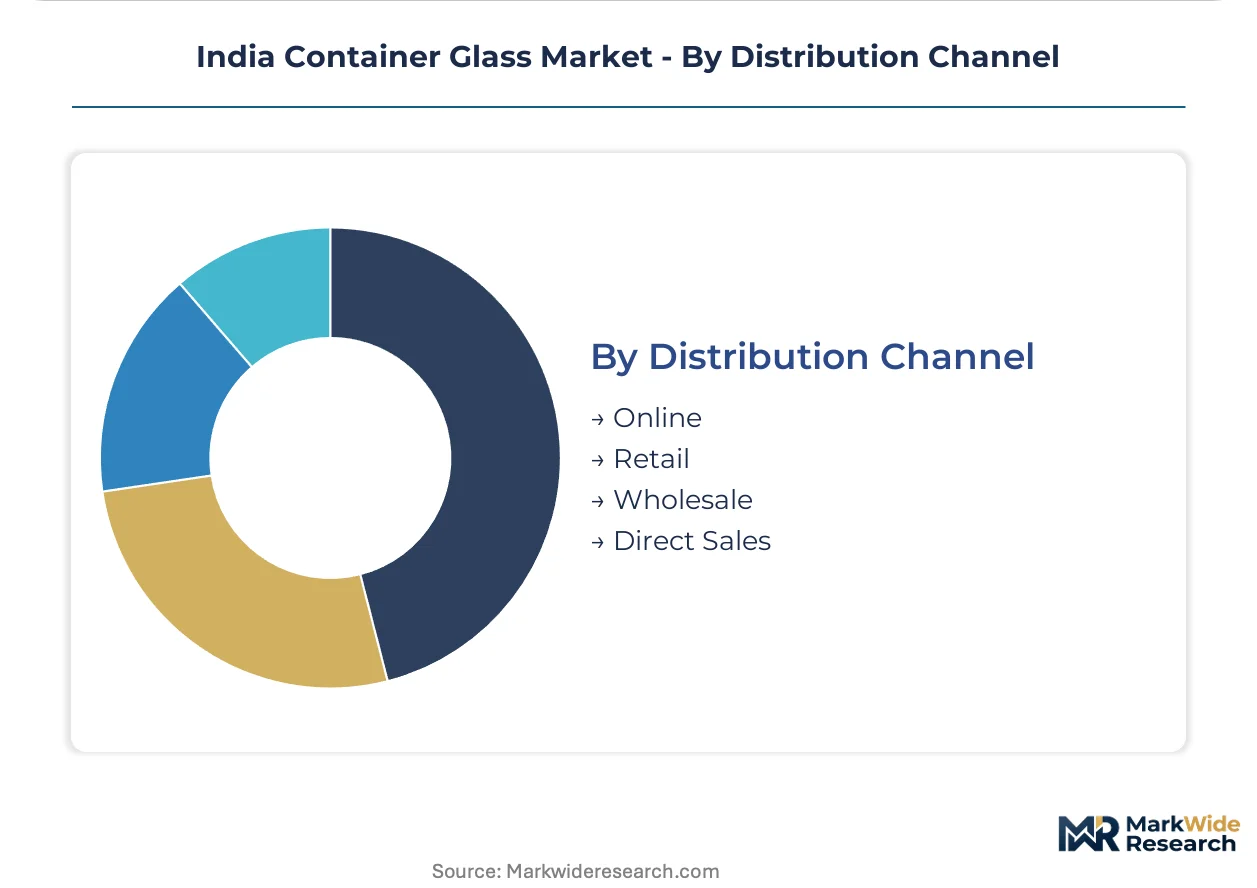
Distribution Channel:
Channel selection determines inventory holding patterns and payment cycle exposure for mold houses.
- Direct Sales:Long-term contracts with formulation facilities and food multinationals provide volume visibility but extend payment cycles. CDSCO compliance documentation requirements favor established supplier relationships.
- Wholesale:Distributor networks aggregate fragmented demand from regional condiment and beverage producers across Maharashtra and Gujarat. Working capital intensity rises with inventory pooling requirements.
- Retail:Specification-driven spot purchasing enables dynamic allocation based on real-time quality audits. Food and beverage multinationals now run parallel supplier qualification tracks for standard versus premium flint grades.
- Online:Digital procurement channels bypass traditional distributor markups, enabling smaller mold houses to access formulation facilities without intermediaries. Direct-to-pharma platforms are gaining traction in Karnataka and Telangana clusters.
Direct Sales locks in volume commitments. Online channels are expanding most quickly through procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's container glass industry traces its modern scale to post-independence industrialization, when Gujarat and Maharashtra established the first large-format furnace operations to serve domestic pharmaceutical and food processing demand.
Maharashtra
Mumbai-Pune corridor hosts the densest concentration of food processing multinationals and spirits distillers, driving demand for 50-500 ml flint and amber bottles. FSSAI packaging material safety regulations redirect procurement toward BIS-certified domestic suppliers. Nashik and Aurangabad industrial zones anchor supply chain logistics for western India distribution.
Gujarat
Ankleshwar-Vadodara chemical processing clusters generate sustained demand for amber canisters and chemically durable glassware. State-level plastic prohibition enforcement accelerates beverage and condiment packaging substitution toward glass alternatives. Mundra port proximity enables cost-competitive export shipments for generic pharma bottle consignments.
Karnataka
Bengaluru-Biocon pharmaceutical corridor exhibits underpenetrated demand for borosilicate vial supply, with formulation facilities expanding injectable biologics capacity. CDSCO serialization mandates force mold design reconfigurations for track-and-trace compatibility. Mysuru and Hassan districts concentrate emerging food processing investments requiring FSSAI-compliant jar and bottle sourcing.
Telangana
Hyderabad's vaccine and biologics manufacturing base pulls specialized container glass demand for USP and EP-compliant primary packaging. PLI scheme incentives for specialty glass manufacturing subsidize capital investment in localized borosilicate furnace capacity. Genome Valley life sciences cluster reduces logistics costs through proximity sourcing from emerging domestic suppliers.
Tamil Nadu
Chennai-Sriperumbudur automotive and chemical industrial zones sustain demand for large-format canisters and institutional packaging. State plastic ban extensions in consumer corridors redirect personal care and condiment brands toward glass alternatives. Coimbatore food processing belt requires seasonal surge capacity for sauce and pickle jar shipments.
India Container Glass Market Competitive Landscape
The competitive structure tilts toward integrated furnace operators with pharmacopeial certification capabilities. Domestic producers command position through BIS compliance infrastructure and proximity to Maharashtra-Gujarat demand clusters. Two archetypes dominate: scale-driven multi-furnace operators serving food and beverage volume contracts, and specialized borosilicate producers targeting injectable pharmaceutical specifications. Capacity expansion and mold technology upgrades constitute the primary competitive vectors, with serialization-ready forming equipment representing the critical differentiation threshold.
Among integrated domestic producers, Haldyn Glass Limited and AGI Glaspac occupy positions as scale anchors across food-contact and standard pharmaceutical bottle segments. Piramal Glass Limited exemplifies the specialized tier through dedicated cosmetic and pharmaceutical molded glass capabilities. These three represent the competitive core around which smaller mold houses and import-dependent distributors arrange their market access strategies.
| Leading Market Players |
|---|
| Gerresheimer AG |
| Haldyn Glass Limited |
| AGI Glaspac |
| Eagle Glass Deco (P.) Ltd |
| Hindusthan National Glass & Industries Limited |
| Piramal Glass Limited |
| Schott Kaisha Pvt Ltd |
| Sunrise Glass Industries Private Limited |
| Borosil Glass Works Limited |
| Others |
Supply & Pricing Matrix
Natural gas price benchmarks at Hazira and Dahej anchor furnace economics across western India, cascading through silica-soda-lime batch costs into three-tier pricing structures that separate pharmacopeial-certified vials from commodity food-contact bottles. This input cost concentration amplifies margin volatility for operators without long-term offtake agreements, pushing procurement departments toward spot purchasing for non-certified grades while locking strategic volumes under index-linked contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by certification burden and thermal shock resistance specifications. Price differentiation hinges on BIS compliance status and CDSCO pharmacopeial alignment, with borosilicate vials commanding substantial premiums over flint bottles. Cost compression in the standard tier is intensifying because lightweighting technology reduces material input per unit. Generic pharma exporters exhibit highest price sensitivity, while injectable biologics manufacturers prioritize dimensional stability over unit economics.
Supply Chain Analysis
Skilled furnace operator availability constrains capacity expansion in Gujarat and Maharashtra, where traditional glassmaking apprenticeships compete with chemical and pharmaceutical manufacturing wages. Geographic supply concentration clusters in India, with secondary dependencies on imported cullet from Europe and soda ash from Kenya and Turkey. Single-source vulnerability runs through the Mundra-Nhava Sheva logistics corridor, where port congestion disrupts export consignments. Distribution runs through direct sales contracts with formulation facilities, supplemented by wholesale networks aggregating regional condiment producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's container glass market compounds steadily as pharmaceutical serialization mandates and state-level plastic prohibitions structurally displace alternative packaging materials. The regulatory tailwind creates durable demand visibility for certified domestic producers.
For Market Incumbents: Acquire borosilicate furnace capacity in Karnataka and Telangana to anchor supply for southern pharma clusters expanding injectable biologics output. CDSCO's evolving dimensional tolerance guidelines threaten opportunistic import suppliers; incumbent domestic producers should deepen backward integration into CNC mold engraving and statistical process control systems to compress pharmacopeial certification timelines and consolidate supplier panels at Baddi and Hyderabad formulation facilities. For New Entrants and Emerging Players: Direct-to-pharma digital procurement platforms offer the most penetrable route for smaller mold houses to bypass traditional distributor markups and access Genome Valley life sciences clusters. Karnataka's underpenetrated vial supply market presents white-space opportunity, particularly for serialization-ready forming equipment serving biologics pipelines. New entrants should anchor initial capacity through co-manufacturing arrangements with established furnace operators before independent greenfield investment. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized borosilicate producers holding documented USP and EP compliance trails, as CDSCO guidelines tighten pharmacopeial alignment requirements that commodity bottle manufacturers cannot quickly replicate. The five-to-ten year viability window favors acquisition targets with existing serialization-ready IS machine footprints and proximity to southern pharma corridors. Monitor PLI scheme disbursement velocity for specialty glass manufacturing as the critical inflection signal; delayed subsidy realization would compress capital deployment timelines for capacity expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soda Ash Supply | Captive sourcing from Gujarat chemical clusters insulates margin structures from imported input volatility. |
| Serialization-Ready Forming Equipment Upgrade | CDSCO track-and-trace mandates require mold retrofits that disqualify legacy IS machine operators. |
| Greenfield Borosilicate Capacity in Telangana | PLI scheme subsidies lower breakeven thresholds for Genome Valley proximity sourcing. |
| Direct-to-Pharma Digital Platform Launch | Procurement digitization bypasses distributor markups for smaller mold houses in underpenetrated southern states. |
| Lightweighting Technology Deployment | Optimized silica-soda-lime formulations reduce freight costs for generic pharma exporters in Gujarat. |
Research Methodology
Direct dialogue with furnace operations managers, pharmaceutical packaging procurement leads, CDSCO regulatory affairs specialists, and FSSAI compliance officers grounded qualitative findings in operational reality. Secondary validation drew from BIS certification databases, CDSCO draft guideline publications, customs import records for cullet and soda ash, and state-level plastic prohibition enforcement notifications. Bottom-up capacity estimates from individual furnace operators triangulated against top-down demand projections from pharmaceutical formulation facility expansion announcements.
Segment-level value and volume estimates across the analysis window reflect disaggregated modeling of product type, end-use application, capacity band, and distribution channel configurations. CAGRs were derived from regression analysis of historical furnace output data against pharmaceutical production indices and food processing investment flows. Forecast inputs incorporated PLI scheme implementation timelines, natural gas price trajectory assumptions, and state-level plastic ban extension schedules.
The model assumes a particular technology adoption path; alternative pathways for lightweighting and serialization integration would alter the outlook if furnace rebuild cycles accelerate beyond standard ten-to-twelve year intervals. Forecasts reflect assumptions regarding regulatory enforcement consistency and subsidy disbursement velocity. Material deviation in CDSCO guideline finalization or PLI scheme eligibility criteria warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Glass Jugs Market
Glass Packaging
Hungary Container Glass Market
Glass Packaging
Retail Glass Packaging Market
Glass Packaging
Kenya Container Glass Market
Glass Packaging
Global Container Glass Market
Glass Packaging
Africa Glass Bottles and Containers Market
Glass Packaging
Australia Container Glass Market
Glass Packaging
North America Pharmaceutical Glass Packaging Market
Glass Packaging
APAC Glass Bottles/Containers Market
Glass Packaging
Vietnam Container Glass Market
Glass Packaging
Tunisia Container Glass Market
Glass Packaging
Mason Jars Market
Glass Packaging
Denmark Container Glass Market
Glass Packaging
Amber Glass Packaging Market
Glass Packaging
Ukraine Container Glass Market
Glass Packaging
Glass Veil Market