
 Glass Jugs Market | 2026-2036
Glass Jugs Market Size, Share, and Industry Trends Forecast 2026-2036
Glass Jugs Market Foresight
Premium borosilicate-grade specifications is unwinding across commercial procurement channels as temperature-resistance thresholds become mandatory for hospitality contracts. Owens-Illinois leverages captive furnace networks across multiple continents to sustain cost-advantaged output. Ardagh Group anchors European food-service supply through dedicated borosilicate lines in Germany and France. Verallia competes on decoration-to-volume ratios for branded beverage programs.
Glass jugs are rigid vessels formed from silica-based melts, typically soda-lime or borosilicate compositions, with wall thickness calibrated for thermal shock resistance and mechanical durability; they serve liquid storage, measurement, and service functions across domestic, scientific, and commercial settings. Borosilicate material grade commands the strongest margin pool due to laboratory and specialty-café certification requirements, while standard soda-lime jugs dominate unit volume in retail home-use channels. Application-wise, food service and hospitality segments absorb the fastest growth as on-premise beverage presentation standards tighten globally.
FDA food-contact regulations in the United States govern leachable limits and thermal-cycling test protocols for commercial-grade glassware, while the EU's REACH framework and F-Gas Regulation indirectly shape manufacturing energy profiles and coating chemistries for insulated jug variants. China's SAMR enforces GB standards on glassware migration limits that affect export-oriented producers. Stakeholders must monitor evolving extended-producer-responsibility frameworks and energy-cost differentials between natural-gas and electric melting technologies as regulatory timelines compress.
Market Dynamics
The EU's Packaging and Packaging Waste Regulation is compressing supply chains toward reusable formats, forcing furnace operators to reconfigure output mixes and hospitality buyers to rewrite procurement specifications around certified borosilicate grades.
Growth Catalysts
- REACH-compliant coating chemistries:ECHA-mandated restrictions on fluorinated compounds are accelerating migration to silicone-based thermal barrier formulations for insulated jug variants.
- Specialty coffeehouse chains:Temperature-resistance certification requirements in the United States are pulling borosilicate-grade procurement into multi-year supply agreements with dedicated furnace operators.
- Germany's hospitality sector:On-premise beverage presentation standards tightening across Berlin and Munich restaurants are mandating wall-thick borosilicate service vessels for thermal shock durability.
Market Restraints
- Natural-gas cost volatility:Furnace energy profiles in Central Europe remain exposed to pipeline supply disruptions, compressing margin pools for soda-lime volume producers.
- Single-use plastic substitution threat:Lightweight PET carafes with barrier coatings are capturing price-sensitive catering contracts in institutional food service segments.
- FDA thermal-cycling test protocols:Extended certification timelines for commercial-grade glassware are stretching working capital cycles for export-oriented Chinese manufacturers.
Strategic Opportunities
- India's organized café expansion:Metro-tier cities including Bangalore and Hyderabad are importing borosilicate certification standards from European hospitality training programs.
- Direct-to-hospitality distribution:Bypassing traditional wholesale channels through dedicated e-procurement platforms is opening margin recovery for mid-cap furnace operators.
- EU Green Deal industrial decarbonization incentives:Electric melting technology adoption subsidies are creating first-mover positioning for furnace retrofits ahead of 2030 compliance deadlines.
Industry Challenges
- Borosilicate furnace technician scarcity:Specialized temperature-control expertise for thermal shock calibration is concentrating among aging workforces in Germany and France.
- Extended-producer-responsibility framework integration:Reverse logistics systems for reusable jug pooling require capital-intensive tracking infrastructure that mid-scale operators lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glass Jugs Market |
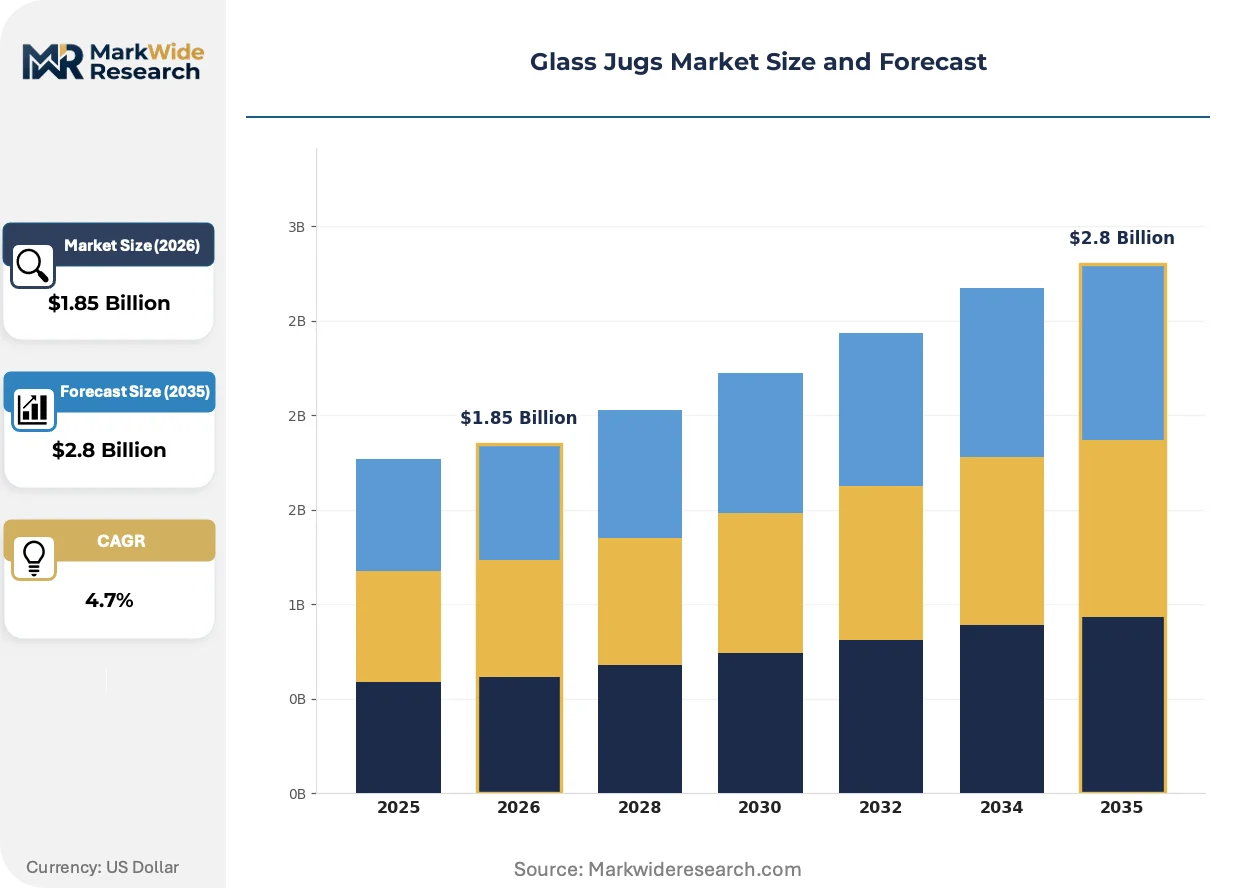
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Jugs, Measuring Jugs, Decorative Jugs, Insulated Jugs, Beverage Jugs Material Grade: Tempered Glass, Borosilicate Glass, Annealed Glass, Soda-lime Glass, Lead Glass Application: Home Use, Laboratory Use, Food Service, Hospitality, Event Catering End User: Retail Consumers, Scientific Institutions, Food & Beverage Businesses, Event Managers |
| Companies Covered | Owens-Illinois, Ardagh Group, Verallia, Heinz-Glas, Stölzle Glass Group, Vetropack, Vidrala, Bormioli Rocco, Saverglass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glass Jugs Market Shifts & Advancements
Active reshaping of the glass jugs market centers on material-grade bifurcation, regulatory-driven format standardization, and procurement specification tightening across hospitality verticals.
Electrified furnace melting technology is supplanting natural-gas-fired production across European furnace networks. Ardagh Group and Verallia are piloting all-electric lines in France and Germany to meet EU Green Deal decarbonization milestones. This transition is compressing the cost advantage historically held by gas-dependent operators in Eastern Europe and forcing consolidation among sub-scale furnace owners unable to fund electrode infrastructure retrofits.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating legacy non-stick interior coatings from insulated jug variants. Manufacturers are reformulating with plasma-applied silica barriers or bare borosilicate interiors to maintain thermal performance. The laboratory and specialty-café segments in Germany and the Netherlands are responding fastest, rewriting supplier qualification protocols to exclude fluorinated chemistries entirely.
Specification-driven procurement is displacing price-first purchasing in United States specialty coffeehouse chains. Buyers now mandate thermal shock certification thresholds and wall-thickness tolerances in request-for-proposal documents, compressing the supplier pool to furnace operators with dedicated borosilicate lines. This pattern is most visible in Pacific Northwest roasting clusters, where direct trade relationships with glassware specialists are replacing distributor-mediated supply.
Glass Jugs Market Segmentation
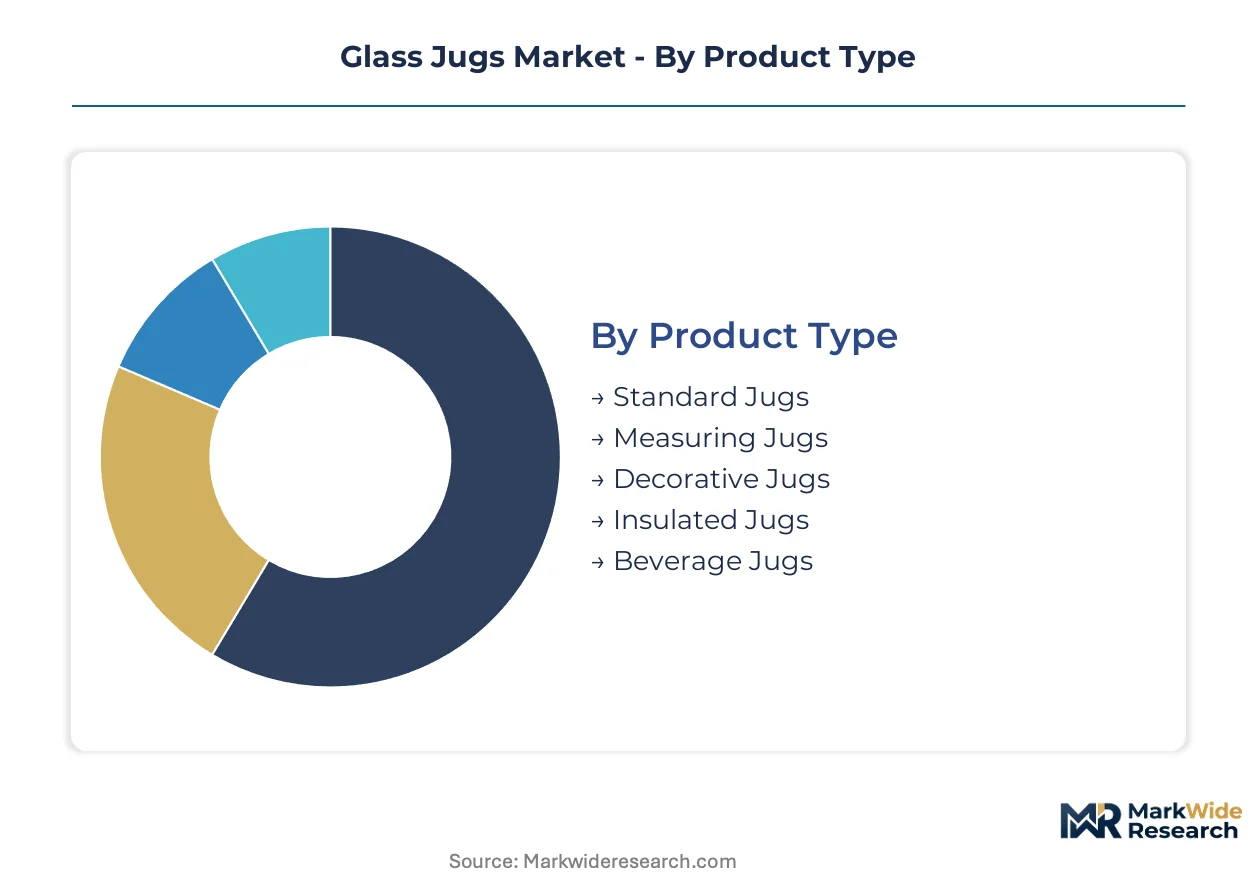
Glass jug procurement divides across performance tiers, thermal specifications, and channel requirements. Material-grade certification and end-use durability standards increasingly determine supplier qualification and contract terms.
Product Type:
Substitution pressure from coated PET carafes and stainless-steel vessels hits utilitarian formats hardest while premium presentation formats retain glass loyalty.
- Standard Jugs:Basic soda-lime construction with uniform wall thickness serves bulk liquid storage in institutional pantries and residential kitchens. Price-sensitive food service buyers in the United States shift toward barrier-coated plastic alternatives for high-turnover catering contracts, compressing volume for undifferentiated glass suppliers.
- Measuring Jugs:Calibrated volumetric markings etched or printed on borosilicate or tempered substrates meet laboratory tolerance requirements and professional kitchen portion-control needs. Scientific institutions in Germany and specialty coffeehouse chains in the Pacific Northwest specify graduated borosilicate grades for thermal cycling durability.
- Decorative Jugs:Applied ceramic inks, embossed patterns, and colored glass tints target gift retail and premium table service. Hospitality venues in France prioritize decoration-to-volume ratios for branded beverage programs.
- Insulated Jugs:Double-wall construction with vacuum or air-gap thermal barriers requires REACH-compliant coating chemistries replacing legacy fluorinated formulations. European furnace operators pilot plasma-applied silica interiors to maintain performance under ECHA restrictions.
- Beverage Jugs:Wide-mouth profiles with pour-spout engineering serve on-premise service of infused waters, craft lemonades, and batch cocktails. Berlin and Munich restaurants mandate wall-thick borosilicate construction for thermal shock resistance.
Standard jugs retain volume leadership; insulated jugs hold the steepest expansion curve.
Material Grade:
Cost tier stratification separates commodity furnace output from certified specialty grades requiring dedicated production lines and technician expertise.
- Tempered Glass:Rapid thermal quenching creates compressive surface layers that resist mechanical impact and moderate thermal shock. Home-use retail channels in the United States favor tempered construction for dishwasher durability and drop resistance.
- Borosilicate Glass:Low thermal expansion coefficient from elevated silica and boron oxide content enables direct flame contact and freezer-to-oven cycling. Laboratory certification requirements and specialty-café procurement specifications in Germany and the Netherlands concentrate demand for this grade.
- Annealed Glass:Controlled cooling relieves internal stresses for decorative and cold-service applications without thermal cycling demands. Event catering rentals specify annealed construction for cost-efficient large-format vessels.
- Soda-lime Glass:Standard silicate-soda-lime formulation dominates unit volume through retail home-use channels and price-sensitive institutional procurement. Central European furnace operators face margin compression from natural-gas cost volatility.
- Lead Glass:Heavy metal oxide inclusion produces optical clarity and density for luxury tableware and ceremonial applications. Regulatory migration limits under FDA and REACH frameworks constrain food-contact applications.
Soda-lime glass retains volume leadership; borosilicate glass holds the steepest expansion curve.
Application:
Customer type maturity varies from saturated residential replacement cycles to rapidly professionalizing commercial service standards.
- Home Use:Replacement-driven demand through mass retail and e-commerce channels favors tempered and soda-lime construction for dishwasher compatibility and cost accessibility.
- Laboratory Use:ASTM and DIN thermal shock certification requirements mandate borosilicate grades with calibrated volumetric accuracy for analytical protocols.
- Food Service:Quick-service and fast-casual chains balance presentation standards against breakage replacement costs; some operators test coated PET alternatives for back-of-house efficiency.
- Hospitality:On-premise beverage presentation standards tighten across Berlin, Munich, and Paris restaurants, mandating wall-thick borosilicate service vessels and direct furnace relationships.
- Event Catering:Rental-pool logistics and breakage insurance drive preference for annealed and tempered grades with standardized replacement sourcing.
Home use retains volume leadership; hospitality holds the steepest expansion curve.
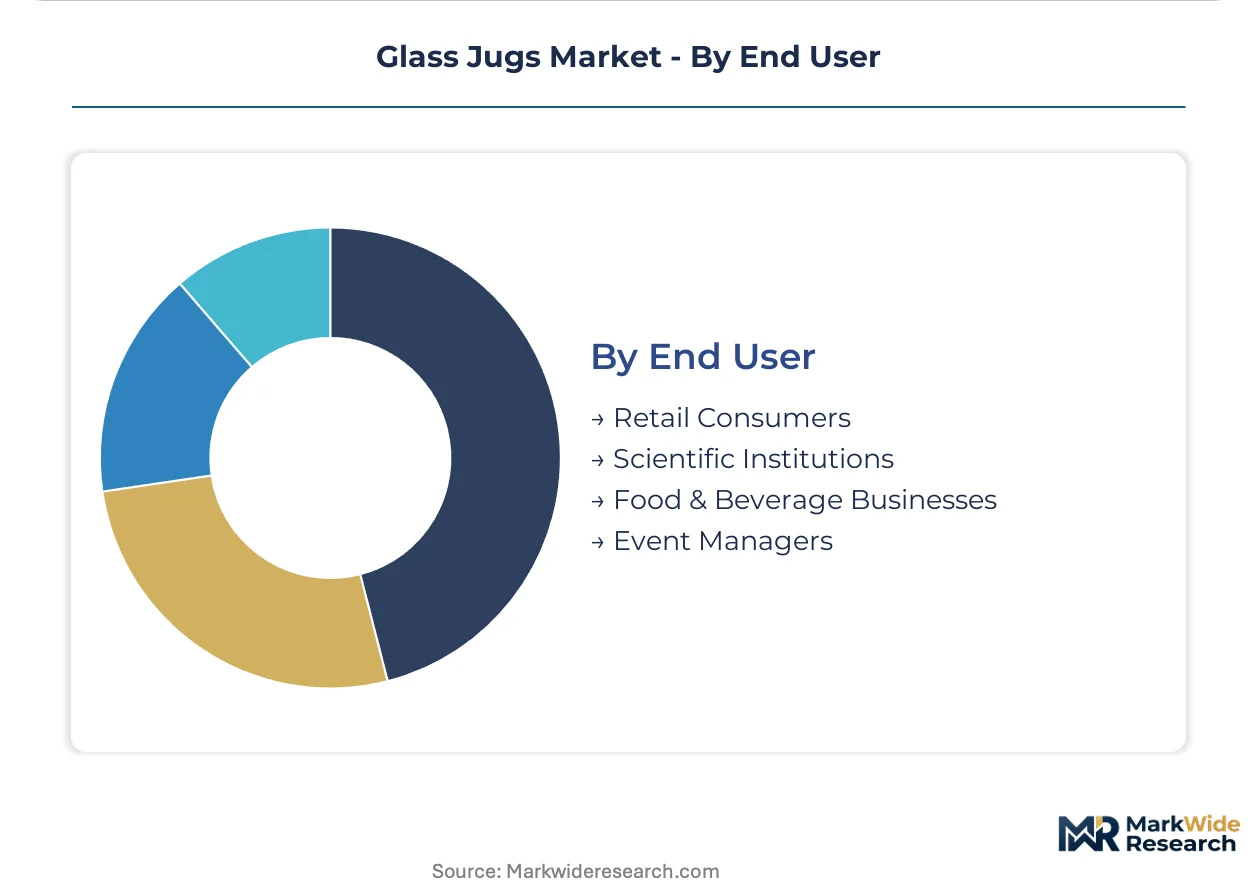
End User:
Supply concentration clusters around furnace operators with captive borosilicate capacity and decoration capabilities.
- Retail Consumers:Mass-market channels and e-commerce platforms source standardized soda-lime and tempered formats through distributor-mediated supply.
- Scientific Institutions:Procurement departments enforce ASTM E438 and DIN 12400 certification protocols, limiting qualified suppliers to furnace operators with dedicated laboratory-grade lines.
- Food & Beverage Businesses:Specialty coffeehouse chains in the United States rewrite RFP documents to mandate thermal shock thresholds and wall-thickness tolerances, compressing the supplier pool.
- Event Managers:Rental logistics and reverse-pooling requirements favor standardized formats from suppliers with regional warehousing infrastructure.
Retail consumers retain volume leadership; food and beverage businesses hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Furnace networks cluster in Germany, France, and the United States where borosilicate certification requirements concentrate procurement volumes. Natural-gas cost differentials and electric melting subsidies are reshaping output allocation across these production hubs.
Germany
Berlin and Munich restaurants enforce wall-thick borosilicate service standards for thermal shock durability. The EU's Packaging and Packaging Waste Regulation accelerates reusable format mandates across hospitality procurement. Ardagh Group operates dedicated borosilicate lines in Baden-Württemberg to supply certified vessels for laboratory and café segments.
United States
Specialty coffeehouse chains in the Pacific Northwest rewrite supplier qualification protocols around thermal cycling thresholds. FDA food-contact regulations govern leachable limits and extended certification timelines for commercial-grade glassware. Owens-Illinois leverages captive furnace networks across multiple states to sustain cost-advantaged borosilicate output for hospitality contracts.
France
Parisian hospitality venues prioritize decoration-to-volume ratios for branded beverage programs. The EU Green Deal industrial decarbonization incentives subsidize electric melting technology adoption ahead of 2030 compliance deadlines. Verallia pilots all-electric furnace lines in northeastern production facilities to meet emerging carbon benchmarks.
China
Export-oriented producers face stretched working capital cycles from FDA thermal-cycling test protocol requirements. SAMR enforces GB standards on glassware migration limits affecting outbound shipments. Yangtze River Delta manufacturing clusters supply undifferentiated soda-lime volume to price-sensitive retail channels.
India
Metro-tier cities including Bangalore and Hyderabad import borosilicate certification standards from European hospitality training programs. BIS standards on food-contact materials create compliance thresholds for domestic producers. Organized café expansion in Maharashtra and Karnataka drives premium-grade procurement from import channels.
Glass Jugs Market Competitive Landscape
Concentration sits with integrated furnace operators possessing dedicated borosilicate capacity and captive technician expertise. The supplier pool compresses around three archetypes: multi-continental volume producers with electrode infrastructure, European specialists with decoration-to-certification capabilities, and regional soda-lime volume players exposed to energy cost volatility. Dominant competitive moves include electric melting retrofits for decarbonization positioning and direct-to-hospitality distribution bypassing wholesale intermediaries.
Among integrated multi-continental operators, Owens-Illinois and Ardagh Group exemplify scale-driven furnace network leverage. Verallia occupies a position within the European specialist tier where decoration capabilities intersect with borosilicate certification lines. These three anchors represent divergent strategic postures: geographic diversification against energy risk, regional clustering for hospitality proximity, and premium-format specialization for branded program capture.
| Leading Market Players |
|---|
| Owens-Illinois |
| Ardagh Group |
| Verallia |
| Heinz-Glas |
| Stölzle Glass Group |
| Vetropack |
| Vidrala |
| Bormioli Rocco |
| Saverglass |
| Others |
Supply & Pricing Matrix
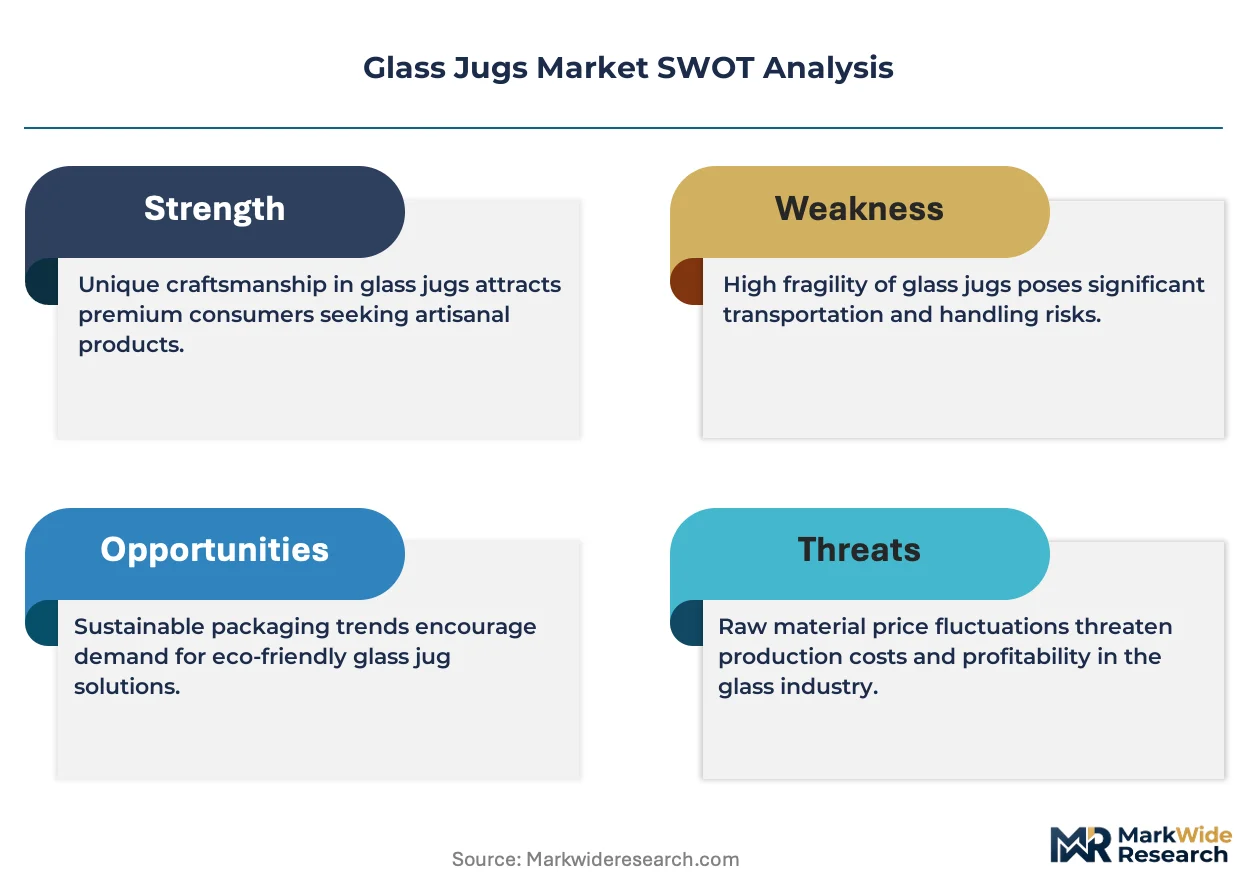
FDA thermal-cycling test protocols gate both supplier qualification and price differentiation simultaneously, compressing the supplier pool to furnace operators with dedicated borosilicate lines while creating three distinct pricing tiers based on certification burden and thermal performance thresholds.
Pricing Analysis
FDA food-contact regulations dictate the pricing tier structure across commercial-grade procurement channels. Three-tier pricing separates borosilicate-certified specialty grades from tempered mid-tier formats and undifferentiated soda-lime economy vessels. Price differentiation rests on thermal shock certification thresholds and wall-thickness tolerances demanded by United States specialty coffeehouse chains. Cost compression in standard soda-lime tiers is intensifying because natural-gas volatility in Central Europe erodes margin pools for gas-dependent furnace operators. Institutional food service buyers exhibit the highest price sensitivity, while hospitality procurement teams in Germany and the Pacific Northwest prioritize performance certification over unit cost.
Supply Chain Analysis
Strategic stockpiling of silica sand and boron oxide concentrates dominates raw material procurement for furnace operators facing energy cost volatility. Manufacturing gravity centers on Germany, France, and the United States where borosilicate certification requirements concentrate procurement volumes and captive technician expertise. Supply chains draw from high-purity silica deposits in Germany and the United States, boron oxide feedstock from Turkey and the United States, and natural-gas or electric melting infrastructure. Single-source vulnerability sits with aging borosilicate furnace technician workforces concentrated in Germany and France. Distribution runs through dedicated e-procurement platforms bypassing traditional wholesale intermediaries for hospitality direct accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where thermal calibration certification and breakage replacement programs expand faster than vessel hardware sales, creating recurring revenue layers for furnace operators with captive technician networks.
For Market Incumbents: Shield borosilicate-grade margin pools by accelerating electric melting retrofits ahead of EU Green Deal subsidy expiration windows. Vertical integration into silica sand preprocessing secures feedstock quality for thermal shock calibration consistency. Capacity consolidation in Baden-Württemberg and Pacific Northwest roasting clusters captures hospitality procurement specification tightening before mid-scale competitors fund electrode infrastructure. For New Entrants and Emerging Players: FDA fast-track certification pathways for borosilicate thermal-cycling protocols open white-space penetration in United States specialty coffeehouse supply chains. India's organized café expansion in Bangalore and Hyderabad offers the most penetrable geography as European certification standards import through hospitality training programs. Direct-to-hospitality e-procurement platforms provide the optimal go-to-market angle for bypassing entrenched distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electric melting furnace retrofits as EU Green Deal subsidies compress payback periods for first-mover operators. Five-to-ten year viability favors integrated furnace networks with dedicated borosilicate lines and captive decoration capabilities. Acquisition targets should display electrode infrastructure commitments and hospitality direct-channel penetration. The signal to watch is electric melting adoption rates among mid-scale European operators unable to self-fund retrofits.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Melting Retrofit | EU Green Deal subsidies in France and Germany compress payback periods for decarbonized furnace output. |
| Borosilicate Certification Investment | FDA thermal-cycling protocols in the United States gate hospitality procurement contract eligibility. |
| Direct-to-Hospitality Distribution | E-procurement platforms bypass wholesale intermediaries to recover margin in Berlin and Munich restaurant supply. |
| Silica Sand Backward Integration | Turkish and German high-purity deposits anchor thermal shock calibration consistency for laboratory-grade lines. |
| REACH-Compliant Coating Reformulation | ECHA fluorinated compound restrictions force plasma-applied silica barrier adoption for insulated jug variants. |
Research Methodology
A spread of perspectives from furnace operations managers, hospitality procurement directors, laboratory certification officers, and glassware distribution channel heads converged on the working assumptions underlying volume and value estimates. Primary fieldwork combined structured interviews with secondary validation against SEC filings from integrated furnace operators, EU ETS carbon market disclosures, and FDA food-contact guidance documents. Customs data from Germany, France, and the United States provided trade flow triangulation against bottom-up production estimates and top-down demand aggregation.
Segmentation dimensions modeled include material grade tier, end-use application, thermal performance specification, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-calibrated demand projections and capacity expansion announcements. Forecast inputs incorporated natural-gas price scenarios for Central European furnace networks and electric melting adoption curves tied to EU Green Deal subsidy timelines.
The analysis sits within stated boundaries; outcomes outside sustained EU decarbonization policy support or abrupt natural-gas supply disruption would require recalibration. Forecasts reflect documented assumptions about certification timeline stability and hospitality procurement specification trajectories. Revision becomes warranted when borosilicate furnace technician attrition rates cross thresholds that constrain certified output expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Glass Packaging
Angola Container Glass Market
Glass Packaging
Beveled Edge Jars Market
Glass Packaging
Croatia Container Glass Market
Glass Packaging
Glass Logistics Market
Glass Packaging
Czech Republic Container Glass Market
Glass Packaging
Container Glass in the UAE Market
Glass Packaging
Uruguay Container Glass Market
Glass Packaging
France Container Glass Market
Glass Packaging
Congo Container Glass Market
Glass Packaging
Glass Decanters Market
Glass Packaging
Mexico Container Glass Market
Glass Packaging
Turkey Container Glass Market
Glass Packaging
Panama Container Glass Market
Glass Packaging
Bangladesh Container Glass Market
Glass Packaging
India Glass Packaging Market
Glass Packaging
Vietnam Container Glass Market