
 India Construction Chemicals Market | 2026-2036
India Construction Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
India Construction Chemicals Market Outlook
Contractor-led procurement is rotating toward developer-direct purchasing in India's construction chemicals channel. Sika India Pvt. Ltd. anchors its position through waterproofing specialization in metro and tunnel projects. BASF India leverages R&D intensity to dominate high-performance admixture formulations for ready-mix concrete. Pidilite Industries Ltd. controls retail and distributor networks that reach tier-2 and tier-3 contractor bases.
Construction chemicals encompass admixtures, protective coatings, sealants, and waterproofing compounds formulated to modify cementitious properties, enhance durability, and protect structural integrity across building lifecycles. These products typically incorporate polymers, surfactants, and specialty additives blended at dosage rates between 0.5% and 5% by weight of cement content. Admixtures command the largest volume share as mass concrete pours multiply across infrastructure corridors. Waterproofing compounds represent the fastest-expanding margin pool, driven by basement and tunnel specifications that now mandate dual-layer membrane systems. The residential application segment sustains baseline demand, though infrastructure projects generate premium pricing and longer contract tenures.
BIS mandates certification for concrete admixtures under IS 9103 and waterproofing products under IS 15058, forcing reformulation investments among domestic blenders. CDSCO and state pollution control boards enforce solvent-content limits that push formulation migration from solvent-based to water-based and powder-based systems. CEA building energy codes indirectly amplify demand for protective coatings that improve thermal performance in commercial envelopes. Stakeholders must monitor BIS revision cycles and state-level green building directives that will determine which formulation types retain market access.
Market Dynamics
BIS certification mandates for concrete admixtures and waterproofing grades are compressing formulation timelines while infrastructure procurement volumes concentrate in Maharashtra, Gujarat, and Karnataka corridor.
Growth Catalysts
- Highway and metro rail network expansion:Central government capital allocation to national infrastructure corridors generates multi-year concrete pour schedules. Mass transit tunnel specifications now mandate dual-layer waterproofing systems.
- IS 9103 and IS 15058 compliance cycles:Mandatory BIS certification for admixtures and waterproofing products forces product standardization. Reformulation investments by domestic blenders lift overall category quality thresholds.
- Ready-mix concrete proliferation:Urban batching plant density in Mumbai, Ahmedabad, and Bengaluru accelerates high-performance admixture uptake. Developer-direct purchasing bypasses traditional distributor markups.
Market Restraints
- Petrochemical feedstock volatility:Polymer emulsions and specialty surfactants constitute 35-45% of formulation costs. Crude-linked input swings compress blender margins unpredictably.
- Import dependency for performance additives:Superplasticizer base chemicals and redispersible polymer powders concentrate with German and Southeast Asian suppliers. Rupee depreciation amplifies landed cost exposure.
- Solvent-content regulatory migration:CDSCO and state pollution control boards enforce volatile organic compound limits. Water-based system conversion requires capital-intensive dispersion equipment.
Strategic Opportunities
- Tier-2 and tier-3 contractor network penetration:Pidilite's distributor reach demonstrates latent demand in Indore, Coimbatore, and Lucknow construction markets. Localized blending facilities reduce logistics cost to interior sites.
- Green building directive alignment:CEA energy codes and state-level sustainable construction mandates create specification pull for thermal-performance coatings. LEED-India and GRIHA certification pathways favor low-VOC formulations.
- Polymer-modified cementitious system convergence:Hybrid admixture-waterproofing combinations simplify single-source procurement. Metro rail developers consolidate specification sheets around integrated product suites.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in cement-polymer compatibility and rheology modification concentrates with Mumbai and Delhi-NCR technical centers. Tier-2 production facilities struggle to retain qualified staff.
- BIS certification timeline compression:Revised IS standards require accelerated retesting cycles. Laboratory queue bottlenecks delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Construction Chemicals Market |
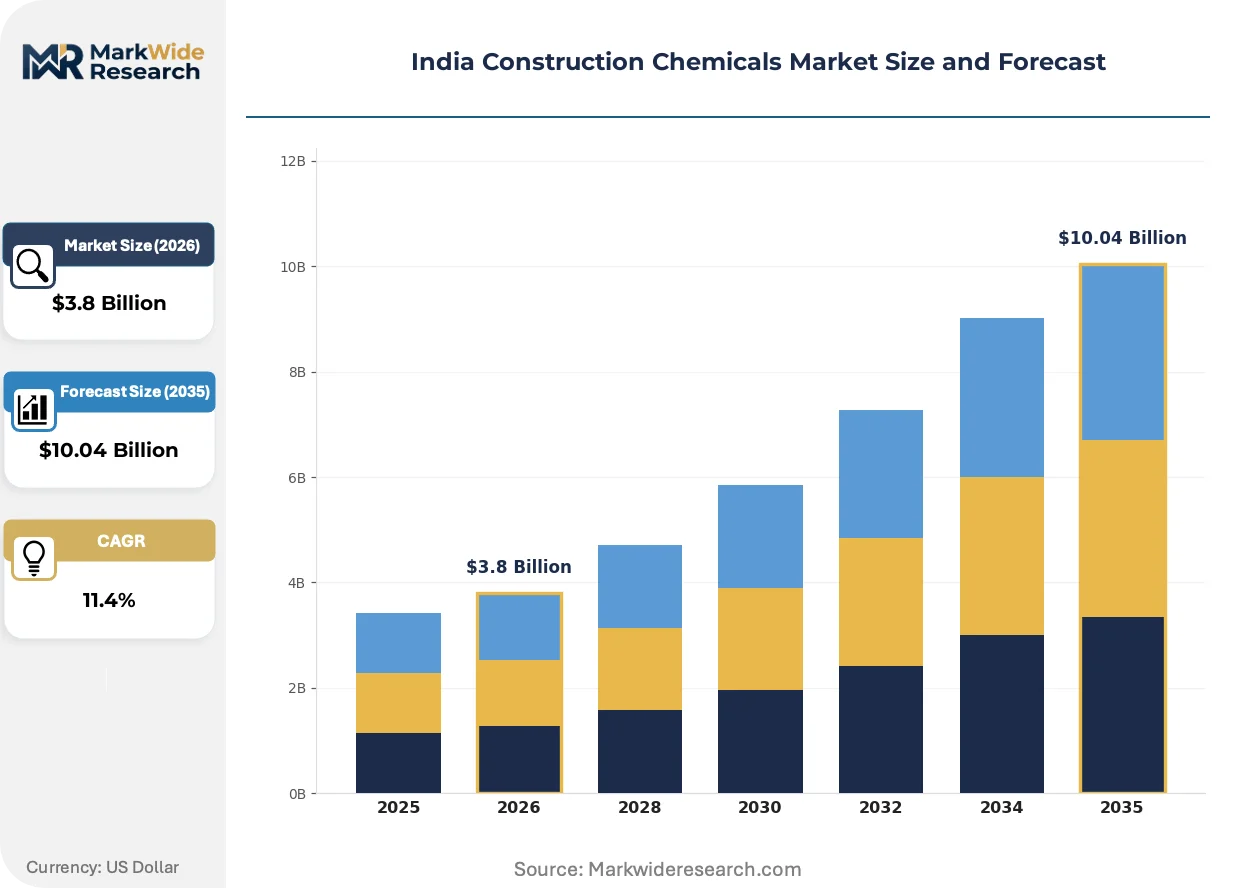
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Admixtures, Protective Coatings, Sealants, Waterproofing Compounds Application: Residential, Commercial, Industrial, Infrastructure End User: Contractors, Builders, Architects, Developers Formulation Type: Water-Based, Solvent-Based, Powder-Based, Dispersion |
| Companies Covered | BASF India, MAPEI Construction Products India Pvt. Ltd., Sika India Pvt. Ltd., Chembond Chemicals Limited, Asian Paints, Pidilite Industries Ltd., Fosroc India, Ardex Endura India Pvt. Ltd., Saint-Gobain, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Construction Chemicals Market Strategic Shifts
Formulation chemistry and procurement architecture are undergoing parallel transformation. Polymer science advances are rewriting performance benchmarks while channel structures compress toward direct developer relationships.
Polycarboxylate ether-based superplasticizers are decomposing traditional naphthalene and melamine admixture demand in high-strength concrete applications. Ready-mix producers in Mumbai and Bengaluru specify PCE systems for slump retention beyond 90 minutes. The technology is decomposing commodity admixture pricing power and forcing naphthalene blenders into downstream waterproofing diversification.
BIS revision cycles for IS 9103 and IS 15058 are tightening permissible chloride content and setting time variation windows. Domestic blenders must revalidate entire product portfolios against accelerated testing protocols. Maharashtra and Gujarat manufacturing clusters face the steepest compliance cost given their concentration of legacy naphthalene production lines.
Developer-direct specification authority is displacing contractor-led procurement in metro rail and highway packages. Sika and BASF technical teams embed directly with Delhi Metro Rail Corporation and National Highways Authority project offices. Tamil Nadu and Karnataka infrastructure tenders now require manufacturer-certified application supervision, bypassing traditional distributor technical support roles.
India Construction Chemicals Market Segmentation
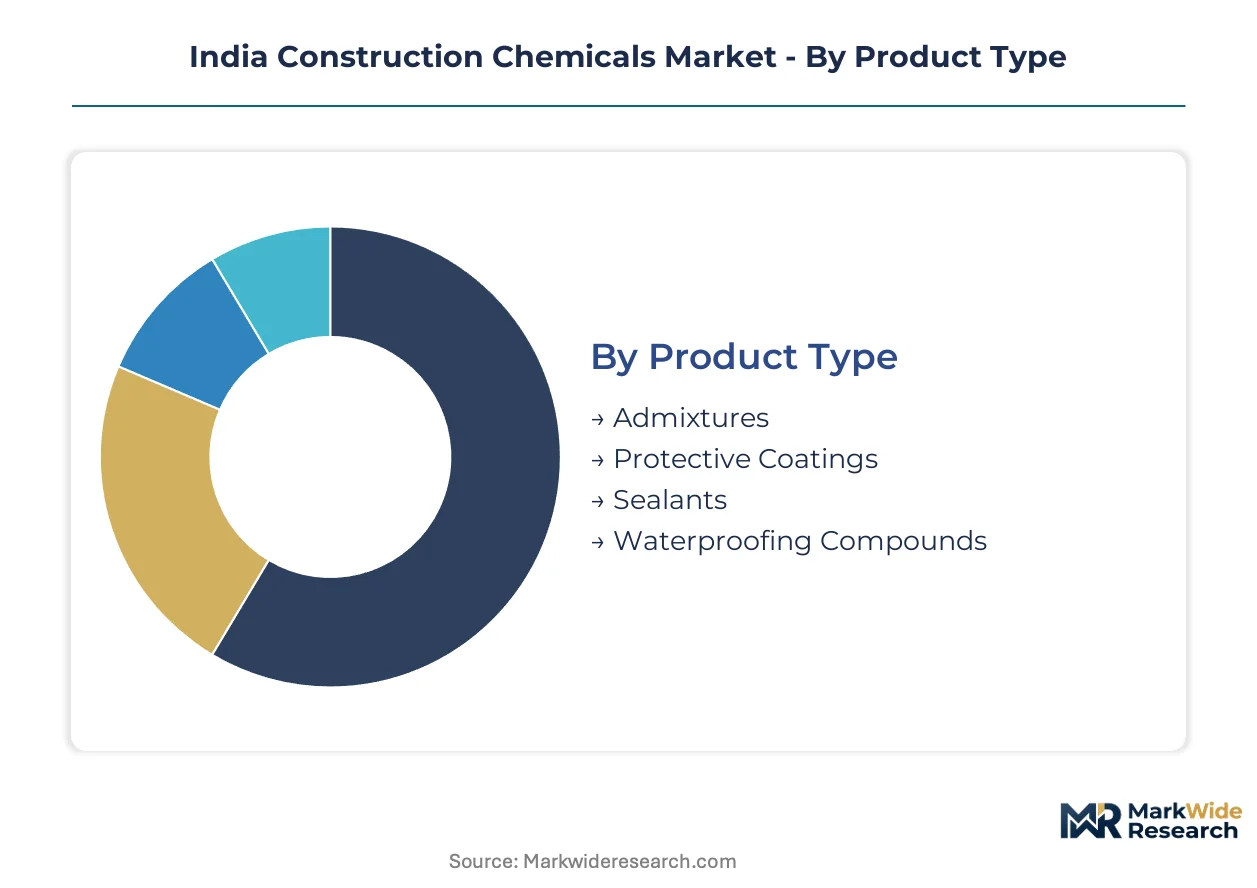
Product differentiation across formulation chemistries and procurement channels determines margin capture in India's construction chemicals landscape. Segment boundaries increasingly blur as metro rail developers demand integrated admixture-waterproofing systems rather than discrete product categories.
Product Type:
Domestic manufacturing clusters in Maharashtra and Gujarat concentrate admixture blending capacity, while waterproofing compounds draw heavier import dependency for redispersible polymer powders.
- Admixtures:Polycarboxylate ether and naphthalene-based formulations modify cement hydration kinetics and rheology at 0.5-2% dosage rates. Mumbai, Ahmedabad, and Bengaluru batching plants specify PCE systems for slump retention beyond 90 minutes, decomposing commodity naphthalene pricing power.
- Waterproofing Compounds:Cementitious crystalline systems and bituminous membranes protect basements, tunnels, and podium structures. Delhi Metro Rail Corporation and National Highways Authority now mandate dual-layer membrane specifications, generating premium contract tenures.
- Protective Coatings:Epoxy and polyurethane films shield concrete from carbonation and chloride ingress in coastal infrastructure.
- Sealants:Polyurethane and silicone compounds accommodate structural movement in expansion joints and facade glazing systems.
Admixtures command the established base. The steepest expansion runs through waterproofing compounds.
Application:
Cost tier stratification separates specification-grade infrastructure demand from price-sensitive residential procurement.
- Infrastructure:Highway and metro rail packages generate multi-year concrete pour schedules with manufacturer-certified application requirements. National Highways Authority tenders specify BIS-certified admixtures under IS 9103 and dual-layer waterproofing under IS 15058, consolidating procurement around technical service capabilities.
- Residential:Individual housing and apartment construction sustains baseline volume through distributor networks reaching tier-2 and tier-3 cities. Pidilite's retail penetration demonstrates latent demand in Indore, Coimbatore, and Lucknow markets.
- Commercial:Office and retail envelopes drive protective coating specifications aligned with CEA energy codes for thermal performance.
- Industrial:Manufacturing floors and chemical containment structures demand acid-resistant epoxy and polyurethane screed systems.
Infrastructure anchors premium pricing. Residential sustains volume scale.
End User:
Procurement authority is rotating from contractor-led purchasing toward developer-direct specification in large infrastructure packages.
- Developers:Delhi Metro Rail Corporation and state highway authorities now embed manufacturer technical teams directly in project offices, bypassing traditional distributor markups. Tamil Nadu and Karnataka tenders require certified application supervision.
- Contractors:Tier-1 construction firms in Maharashtra, Gujarat, and Karnataka concentrate procurement volumes but face margin compression from petrochemical feedstock volatility.
- Builders:Small and mid-scale residential construction relies on distributor networks for admixture and waterproofing procurement.
- Architects:Specification influence concentrates in commercial and high-end residential projects pursuing LEED-India and GRIHA certification pathways.
Developers are consolidating specification authority. Contractors retain execution-scale procurement.
Formulation Type:
Regulatory migration from solvent-based systems is reshaping manufacturing capital allocation across domestic blending facilities.
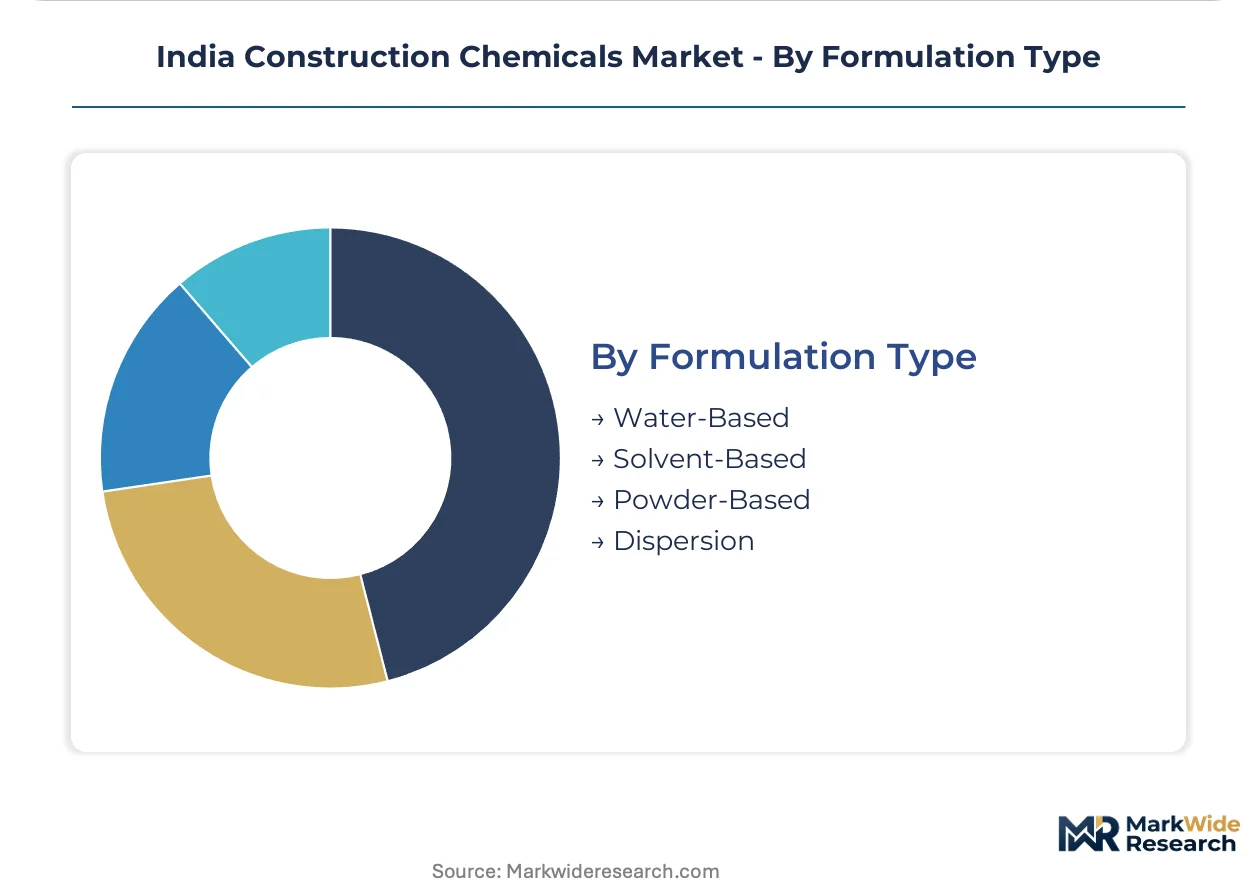
- Water-Based:Polymer emulsions and acrylic dispersions dominate new capacity investment as CDSCO and state pollution control boards enforce volatile organic compound limits. Conversion requires capital-intensive dispersion equipment.
- Powder-Based:Redispersible polymer powders and dry-mix additives eliminate solvent content entirely, aligning with green building directives. Import dependency for base chemicals concentrates with German and Southeast Asian suppliers.
- Solvent-Based:Epoxy and polyurethane systems face contracting market access outside specialized industrial applications.
- Dispersion:Colloidal silica and specialty nanoparticle suspensions serve high-performance concrete specifications.
Water-based systems capture regulatory tailwinds. Powder-based formulations are climbing the fastest on sustainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic blending capacity clusters in western and southern manufacturing corridors, with BIS compliance costs compressing margins for legacy producers concentrated in Maharashtra and Gujarat.
Maharashtra
Mumbai's ready-mix concrete density drives polycarboxylate ether superplasticizer specifications for slump retention beyond 90 minutes. BIS mandates under IS 9103 force reformulation investments among naphthalene-based legacy producers. Thane and Pune industrial belts host the highest concentration of certified admixture blending facilities serving national highway packages.
Gujarat
Ahmedabad's batching plant expansion accelerates high-performance admixture uptake from developer-direct procurement channels. CDSCO solvent-content limits push water-based system conversion requiring capital-intensive dispersion equipment. Vadodara and Surat manufacturing clusters face steepest compliance costs given legacy naphthalene production line concentration.
Karnataka
Bengaluru's metro rail tunnel specifications mandate dual-layer waterproofing systems under IS 15058 certification requirements. State pollution control boards enforce volatile organic compound limits that favor powder-based formulation migration. Mysuru and Hubli-Dharwad corridors demonstrate latent distributor network demand for tier-2 contractor penetration.
Tamil Nadu
Chennai's infrastructure tenders now require manufacturer-certified application supervision bypassing traditional distributor technical roles. CEA building energy codes amplify protective coating specifications for commercial envelope thermal performance. Coimbatore and Madurai construction markets show untapped residential waterproofing demand through retail channel expansion.
Delhi-NCR
Delhi Metro Rail Corporation embeds technical teams directly with admixture suppliers for multi-year concrete pour schedules. BIS revision cycles compress product launch timelines amid laboratory queue bottlenecks. Gurgaon and Noida commercial development drives specification-grade procurement for LEED-India and GRIHA certification pathways.
India Construction Chemicals Market Competitive Environment
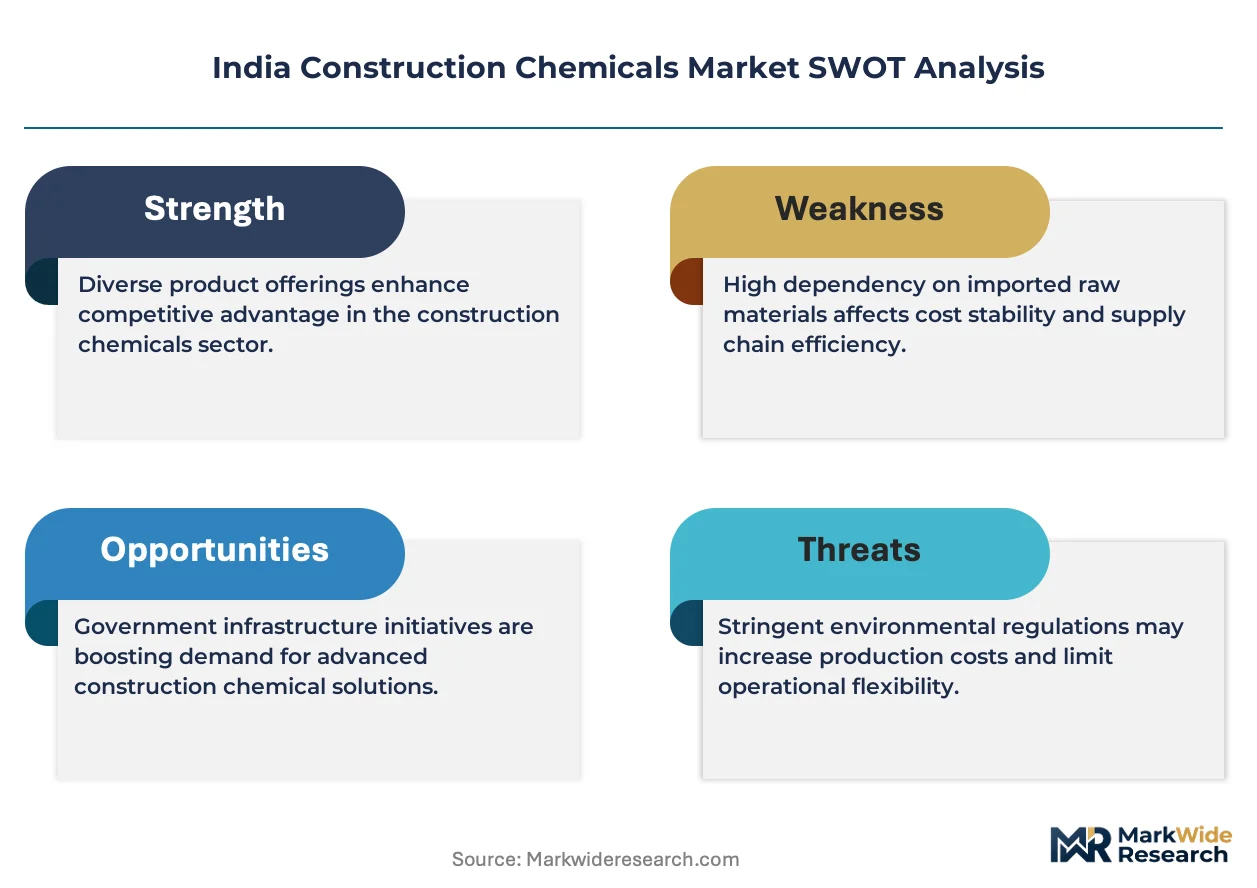
Concentration sits with multinational specialists and domestic distributor networks. Three distinct tiers structure competitive positioning: global formulation leaders with embedded infrastructure project teams, national retail networks penetrating tier-2 and tier-3 cities, and regional blenders serving price-sensitive residential contractors. Strategic moves center on BIS certification acceleration and water-based capacity conversion to retain market access under tightening environmental regulations.
Within the multinational specialist tier, BASF India and Sika India Pvt. Ltd. exemplify technical service-intensive positioning for metro rail and highway packages. Pidilite Industries Ltd. anchors the domestic network archetype with distributor reach into secondary construction markets. These three occupy positions that reflect divergent channel strategies: direct developer embedding versus retail penetration versus infrastructure project consolidation.
| Leading Market Players |
|---|
| BASF India |
| MAPEI Construction Products India Pvt. Ltd. |
| Sika India Pvt. Ltd. |
| Chembond Chemicals Limited |
| Asian Paints |
| Pidilite Industries Ltd. |
| Fosroc India |
| Ardex Endura India Pvt. Ltd. |
| Saint-Gobain |
| Others |
Value Chain & Pricing Dynamics
BIS certification cycles under IS 9103 and IS 15058 simultaneously gate supplier qualification and stratify price tiers across admixture and waterproofing categories. Manufacturers absorbing accelerated laboratory testing costs pass differential markups to infrastructure developers versus residential contractors.
Pricing Analysis
IS 9103 and IS 15058 compliance dictates the pricing tier structure across certified admixtures and waterproofing grades. Three-tier pricing separates BIS-certified infrastructure-grade formulations from standard residential products and uncertified economy blends. Price differentiation hinges on certification level and volume scale, with metro rail packages commanding premium positioning for certified application supervision. Cost compression in commodity naphthalene admixtures is intensifying because polycarboxylate ether systems capture specification authority in Mumbai and Bengaluru batching plants. Residential contractors in tier-2 cities exhibit highest price sensitivity, while Delhi Metro Rail Corporation and National Highways Authority tenders show lowest sensitivity due to mandated technical service bundling.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes amplify landed cost volatility for redispersible polymer powders and superplasticizer base chemicals. Manufacturing concentration clusters in Germany, Southeast Asia, and domestic Maharashtra-Gujarat corridors for performance additives and blending capacity. Raw material dependencies center on petrochemical feedstocks for polymer emulsions, specialty surfactants, and cementitious base materials. Single-source vulnerability concentrates with German suppliers for polycarboxylate ether base chemicals. Distribution runs through developer-direct technical teams for infrastructure packages and Pidilite's retail network for residential penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemistry expertise concentrates with Mumbai and Delhi-NCR technical centers, creating acute bottlenecks for tier-2 production facilities attempting BIS-compliant product development. This capability scarcity rewards early certification investments and localized technical team deployment.
For Market Incumbents: Consolidate specification authority by embedding technical teams directly with Delhi Metro Rail Corporation and National Highways Authority project offices. Accelerate water-based capacity conversion ahead of CDSCO solvent-content enforcement timelines. Defensive positioning requires backward integration into polymer emulsion production to offset petrochemical feedstock volatility compressing blender margins. For New Entrants and Emerging Players: BIS certification fast-track partnerships with Maharashtra and Gujarat testing laboratories unlock tier-2 contractor procurement in Indore, Coimbatore, and Lucknow construction markets. White-space concentration sits with powder-based waterproofing formulations for state pollution control board compliance. Green building directive alignment through low-VOC product suites offers specification entry into CEA energy code-driven commercial envelope projects. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical parents seeking portfolio rationalization outside core geographies. Long-term viability hinges on water-based formulation capabilities and embedded infrastructure project relationships rather than commodity blending assets. Acquisition focus should center on domestic blenders with certified product portfolios and underutilized dispersion equipment. The inflection signal to monitor is BIS revision cycle acceleration compressing laboratory queue timelines and delaying competitor product launches.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Emulsions | Captive supply of surfactant inputs insulates margins from crude-linked petrochemical volatility. |
| BIS Certification Acceleration | Fast-tracked IS 9103 and IS 15058 approvals unlock Delhi Metro Rail Corporation specification authority. |
| Water-Based Capacity Conversion | CDSCO solvent-content compliance preserves market access under tightening state pollution control board enforcement. |
| Tier-2 Technical Team Deployment | Localized application supervision penetrates Indore and Coimbatore distributor networks beyond Mumbai-Bengaluru corridors. |
| Green Building Formulation Alignment | Low-VOC coatings capture CEA energy code specifications for LEED-India and GRIHA certification pathways. |
Study Parameters
A spread of perspectives from plant managers at domestic blending facilities, procurement leads at ready-mix concrete producers, distribution channel partners serving tier-2 contractors, and technical R&D directors at multinational suppliers converged on the working assumptions. Secondary validation drew from BIS certification records, CDSCO regulatory filings, customs trade data for polymer powder imports, and state pollution control board enforcement notices. Bottom-up volume estimates from individual batching plant specifications triangulated against top-down infrastructure capex allocation patterns.
Segmentation dimensions modeled span product type, application sector, end-user procurement authority, and formulation chemistry across the projection horizon. CAGRs derived from infrastructure project pipeline analysis and residential construction permit trajectories. Industry-specific forecast inputs incorporated BIS revision cycle timelines and petrochemical feedstock price elasticity assumptions for polymer emulsion cost structures.
Decision-makers should treat outputs as directional under sustained highway and metro rail capital allocation, BIS enforcement continuity, and rupee exchange rate stability; material deviation would warrant model refresh. Specific risk factors include accelerated BIS standard revisions, import duty fluctuations on Southeast Asian polymer powders, and state-level green building mandate adoption variance. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Europe Human Fibrin Glue Market
Adhesives & Sealants
Wood Glue Market
Adhesives & Sealants
US Pressure Sensitive Adhesives Market
Adhesives & Sealants
South America Construction Adhesives Market
Adhesives & Sealants
High Temperature Sealants Market
Adhesives & Sealants
Wood to Metal Glue Market
Adhesives & Sealants
North America Construction Adhesives Market
Adhesives & Sealants
Aqueous Acrylic Binders Market
Adhesives & Sealants
Europe Cyanoacrylate Adhesives Market
Adhesives & Sealants
Global Hybrid Adhesives and Sealants Market
Adhesives & Sealants
Water-Borne Adhesives Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Global Spray Adhesive Market
Adhesives & Sealants
Global Isononyl Acrylate Market
Adhesives & Sealants
Asia-Pacific Pressure Sensitive Adhesives (PSA) Market
Adhesives & Sealants
Latex Binders Market