
 Global Isononyl Acrylate Market | 2026-2036
Global Isononyl Acrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Isononyl Acrylate Market Foresight
High-purity specification-grade isononyl acrylate is collapsing the gap between commodity monomers and performance copolymers across adhesive formulation. BASF SE leverages its Ludwigshafen monomer complex to sustain integrated supply chains for European coating houses. Osaka Organic Chemical Industry Ltd. anchors Asia-Pacific specialty demand through precision esterification technology. Mitsubishi Chemical Group Corporation differentiates via proprietary catalyst systems that lower residual alcohol content below 50 ppm.
Isononyl acrylate is a branched C9 alkyl ester of acrylic acid, synthesized through acid-catalyzed esterification of isononyl alcohol with acrylic acid, yielding a monomer with a glass transition temperature near -60°C and exceptional low-temperature flexibility in polymer films. Its primary industrial purpose centers on pressure-sensitive adhesives, UV-curable coatings, and sealant formulations requiring tack retention across thermal cycles. The monomer segment leads volume throughput due to direct integration into acrylic copolymer backbones for tape and label applications, while reactive diluents represent the fastest-expanding category as UV-curable coating lines replace solvent-based systems in furniture and automotive finishing. Coatings applications command the deepest margin pools where VOC compliance premiums attach to low-odor, high-solids formulations.
EMA and ECHA enforce REACH Annex XVII restrictions on residual acrylic acid content in cosmetic-grade monomer streams, while EPA Toxic Substances Control Act reporting requirements shape U.S. import volumes for polymer precursor chemicals. China's MEE implements GB standards on volatile organic compound emissions from coating operations, directly filtering permissible monomer specifications for domestic adhesive manufacturers. Stakeholders must monitor regulatory divergence between EU hazard classification updates and Asia-Pacific national chemical inventory listings to preempt formulation redesign costs.
Market Dynamics
UV-curable coating lines are displacing solvent-based furniture and automotive finishing systems, forcing monomer suppliers to reconfigure purity specifications and reactive diluent portfolios around instantaneous cure chemistry rather than conventional thermal drying.
Growth Catalysts
- Pressure-sensitive adhesive expansion:Tape and label manufacturers in China are absorbing specification-grade monomer volumes as domestic coating capacity scales to serve e-commerce logistics packaging demand.
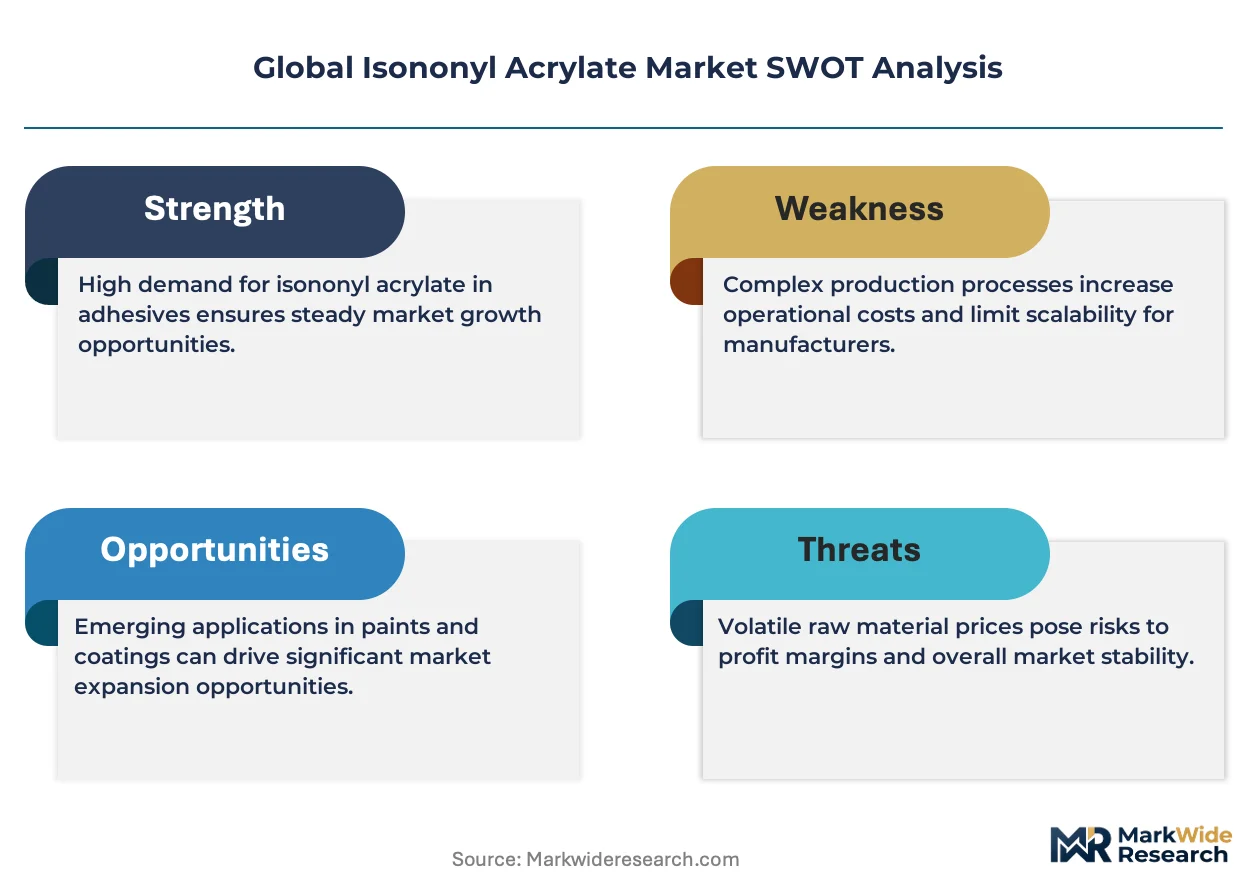
- REACH Annex XVII compliance:Tightened residual acrylic acid thresholds in cosmetic-grade monomer streams are filtering substandard suppliers and consolidating procurement toward integrated European producers.
- Dual carbon goals:China's MEE is accelerating VOC emission standards for coating operations, mandating high-solids formulations that rely on low-odor isononyl acrylate reactive diluents.
Market Restraints
- Propylene feedstock volatility:Acrylic acid price swings transmit directly to isononyl acrylate cost structures, compressing margin predictability for formulation houses lacking backward integration into cracker operations.
- Ludwigshafen supply concentration:European coating manufacturers face single-source dependency risks from integrated monomer complexes, with limited alternative qualified suppliers for REACH-compliant high-purity grades.
- Silicone pressure-sensitive adhesive substitution:Medical and electronics applications are migrating toward silicone chemistry where extreme thermal cycling tolerance outweighs acrylic cost advantages.
Strategic Opportunities
- India coating infrastructure buildout:Domestic adhesive manufacturers under BIS standards compliance timelines represent uncaptured specification-grade monomer demand as automotive assembly localizes.
- UV-LED convergence with acrylate chemistry:Furniture finishing lines combining 395nm LED cure systems with low-viscosity reactive diluents are opening formulation white space distinct from conventional mercury arc installations.
- EU Green Deal procurement mandates:Public sector coating contracts attaching carbon footprint disclosure requirements are favoring regional monomer suppliers with documented supply chain emissions data.
Industry Challenges
- Esterification catalyst expertise scarcity:Precision control over residual alcohol content below 50 ppm requires specialized chemical engineering talent concentrated at Japanese and German specialty chemical operations.
- GB standard recertification timelines:China's MEE emission standard updates force 12-18 month reformulation validation cycles, locking adhesive manufacturers into pre-qualified monomer supplier relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Isononyl Acrylate Market |
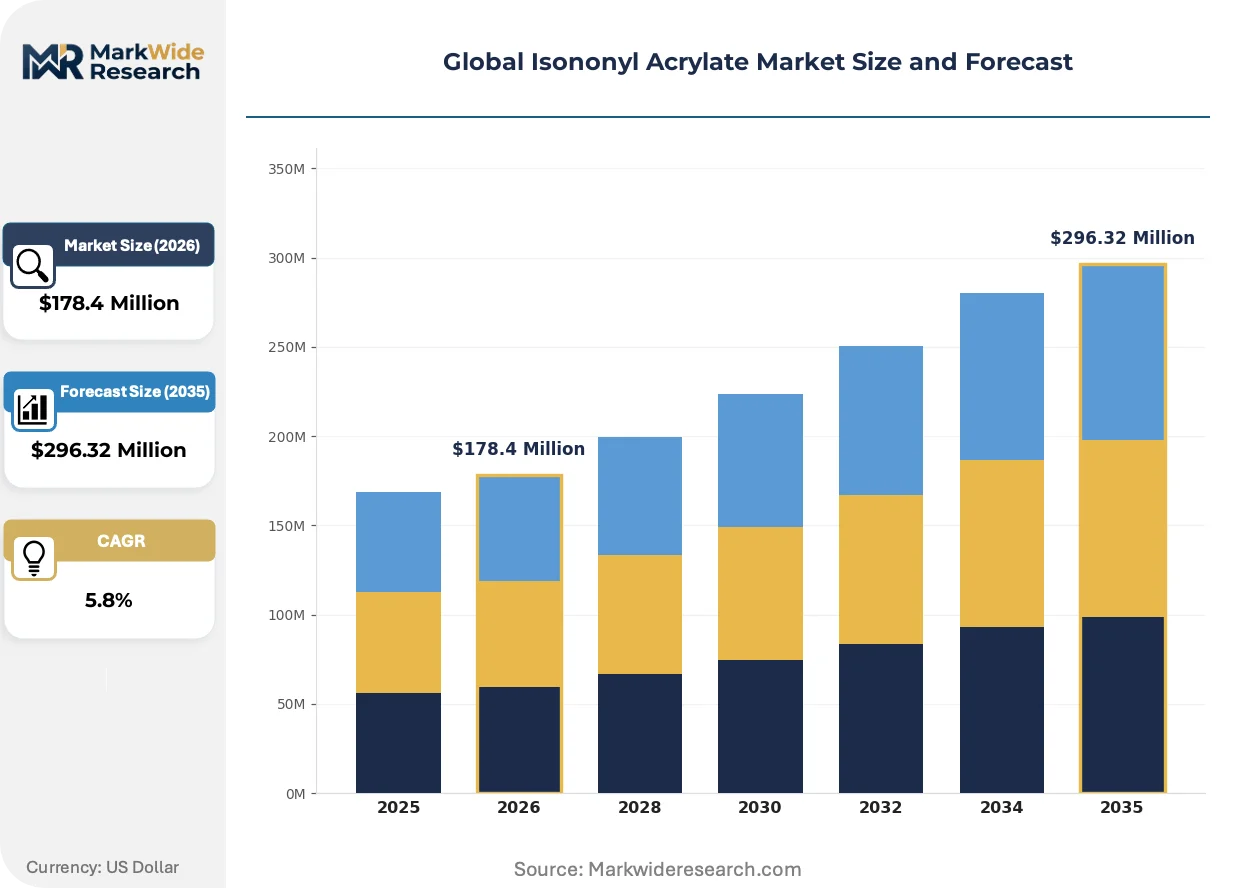
| Market Size in 2026 | $178.4 Million |
| Market Size in 2035 | $296.32 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Isononyl Acrylate Monomer, Isononyl Acrylate Copolymer, Polymer Blends, Reactive Diluents Application: Coatings, Adhesives, Sealants, Elastomers, Printing Inks End Use Industry: Construction, Packaging, Electronics Manufacturing, Cosmetics, Textile Processing Packaging Type: Drums, Intermediate Bulk Containers, Pails, Bulk Tankers |
| Companies Covered | BASF SE, Osaka Organic Chemical Industry Ltd., Mitsubishi Chemical Group Corporation, Dow Inc., Arkema S.A., Nippon Shokubai Co. Ltd., Evonik Industries AG, Sumitomo Chemical Co. Ltd., LG Chem Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Isononyl Acrylate Market Shifts & Advancements
Reactive diluent technology is bifurcating the coating supply base between commodity monomer traders and performance-integrated formulation partners, with cure speed and odor profiles replacing unit cost as primary procurement filters.
Low-viscosity bifunctional acrylate blends are fragmenting the furniture finishing segment. Italian and German automotive tier-one suppliers are adopting these formulations for interior trim UV lines, collapsing the traditional separation between monomer commodity supply and formulated coating performance guarantees.
REACH Annex XVII residual monomer restrictions are tightening cosmetic-grade specifications. ECHA enforcement actions against non-compliant imports are redirecting European adhesive procurement toward domestic producers with validated purity documentation, compressing trader margins on unverified Asian material.
Specification-driven procurement is consolidating buyer power among multinational tape and label manufacturers. Direct monomer supply agreements with integrated petrochemical complexes are displacing distributor intermediaries in China and Germany, with formulation houses absorbing inventory risk previously held by chemical traders.
Global Isononyl Acrylate Market Segmentation
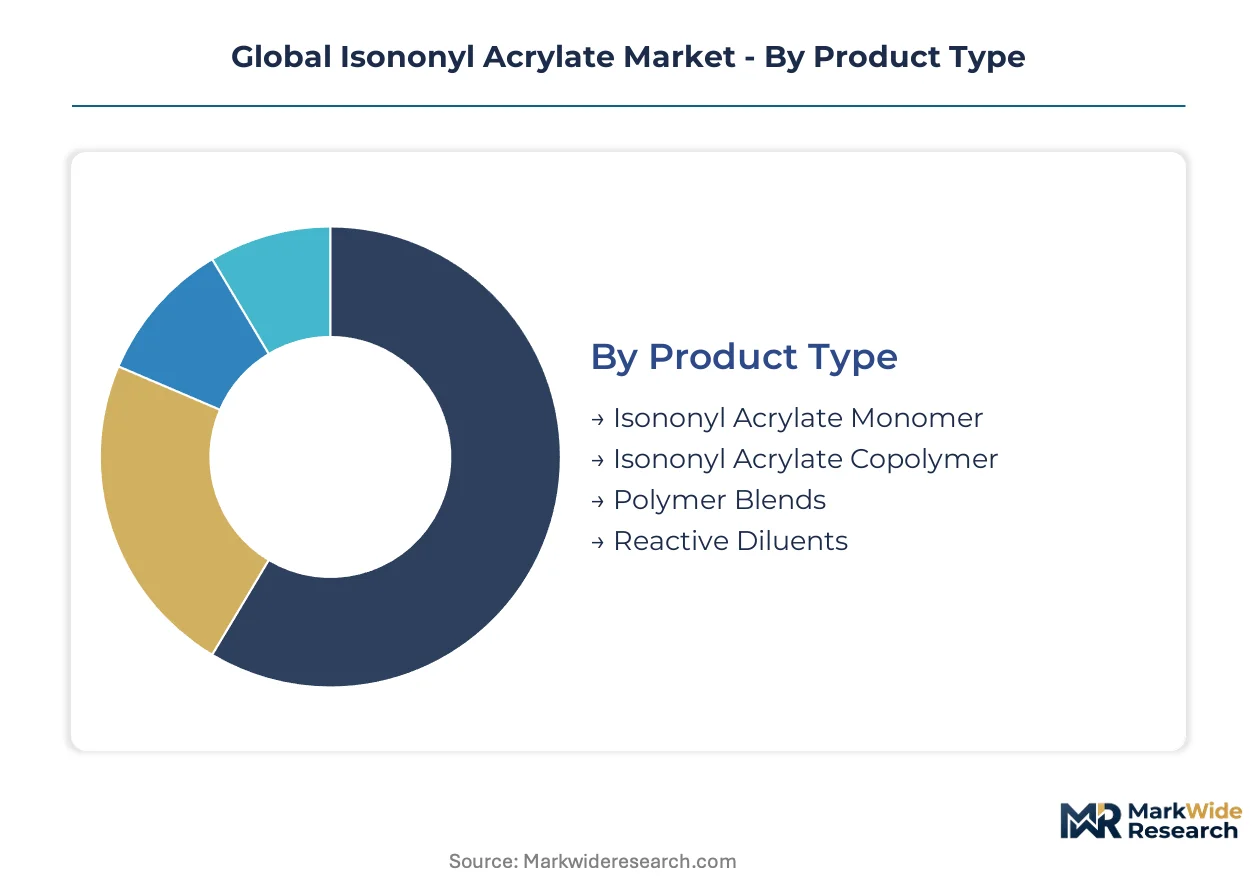
Segmentation in isononyl acrylate markets exposes how purity grades and packaging formats channel through distinct procurement pathways. Formulation houses, integrated coating manufacturers, and distributor networks each favor specific segment combinations based on volume scale and technical service requirements.
Product Type:
Channel economics split sharply between specification-grade monomers flowing direct to large coating houses and commodity grades moving through distributor networks.
- Isononyl Acrylate Monomer:High-purity monomer with glass transition temperature near -60°C serves as the backbone for pressure-sensitive adhesive copolymers. Tape and label manufacturers in China absorb specification-grade volumes as domestic coating capacity scales to serve e-commerce logistics packaging demand.
- Reactive Diluents:Low-viscosity acrylate esters formulated for instantaneous cure chemistry in UV-curable coating lines. Furniture finishing operations in Italy and Germany are adopting these formulations for interior trim UV lines, displacing conventional thermal drying systems.
- Isononyl Acrylate Copolymer:Pre-polymerized resins offering formulation consistency for mid-tier adhesive houses lacking in-house esterification capability.
- Polymer Blends:Compounded formulations targeting specific tack and peel performance requirements in sealant applications.
Isononyl Acrylate Monomer dominates installed base. Reactive Diluents is where expansion concentrates.
Application:
Margin structure varies by cure chemistry and VOC compliance burden, with UV-curable segments commanding premium positioning over conventional thermal systems.
- Coatings:High-solids formulations requiring low-odor, low-residual monomer specifications for VOC compliance. China's MEE emission standards are mandating these formulations across domestic furniture and automotive finishing operations.
- Adhesives:Pressure-sensitive tape and label formulations represent the deepest volume pool. ECHA enforcement of REACH Annex XVII residual acrylic acid thresholds is filtering procurement toward European producers with validated purity documentation.
- Sealants:Flexible joint compounds leveraging low-temperature flexibility across thermal cycling.
- Elastomers:Rubber modification applications requiring tack retention in dynamic stress environments.
- Printing Inks:UV-curable ink systems for packaging graphics with instantaneous cure requirements.
Adhesives commands volume leadership. Coatings is climbing the fastest as VOC regulations tighten.
End Use Industry:
Customer concentration patterns separate bulk chemical procurement by multinational manufacturers from specification-grade purchasing by specialty formulators.
- Electronics Manufacturing:High-purity grades for adhesive films in display and semiconductor packaging. REACH compliance in Europe and GB standards in China are tightening monomer purity thresholds for electronics-grade material.
- Packaging:Pressure-sensitive labels and tapes for e-commerce logistics. Domestic coating capacity expansion in China is concentrating demand for specification-grade monomer volumes.
- Construction:Sealant and adhesive applications in building envelope systems.
- Cosmetics:Nail care and personal care formulations subject to EMA and ECHA residual acrylic acid restrictions.
- Textile Processing:Fabric finishing and coating applications requiring low-temperature flexibility.
Packaging holds the largest installed demand base. Electronics Manufacturing is gaining share fastest on purity premium capture.
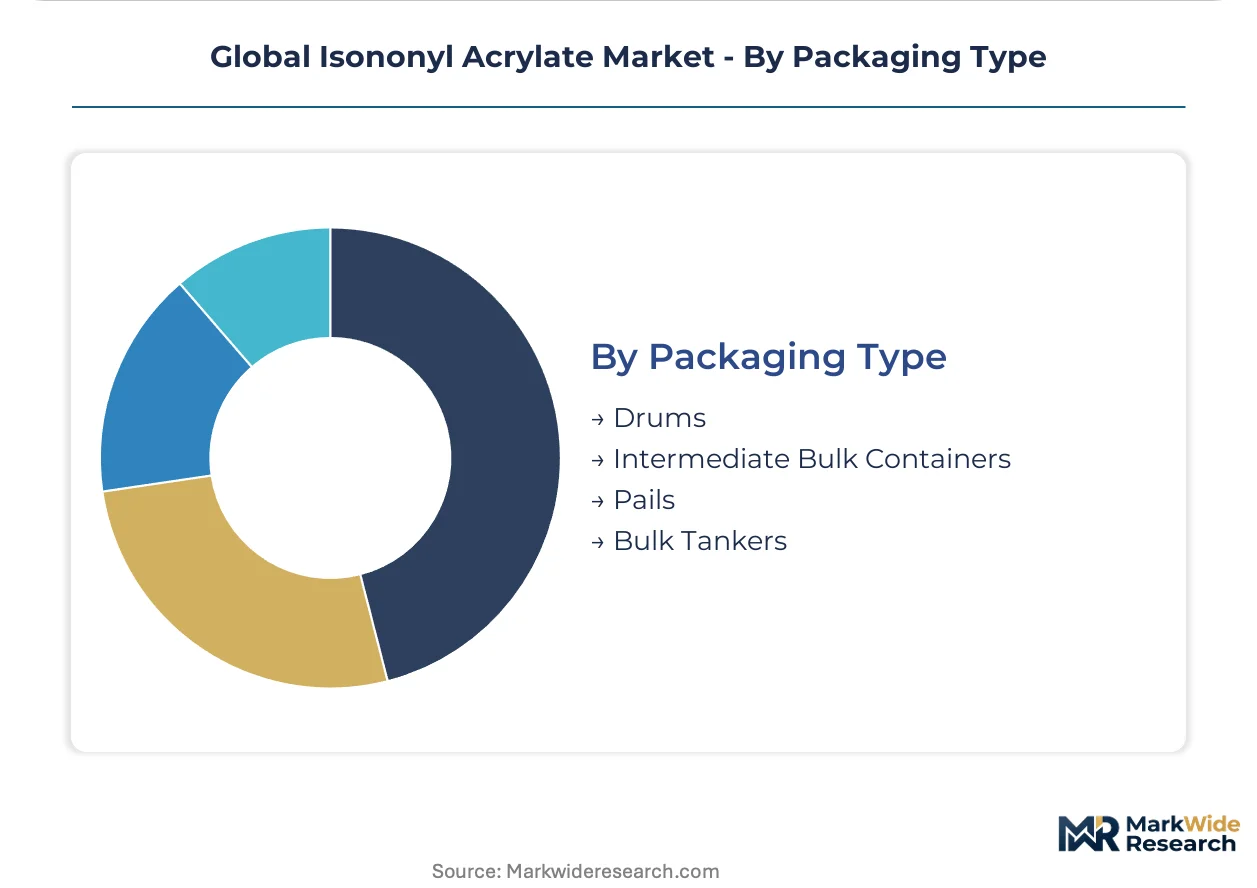
Packaging Type:
Logistics economics and inventory risk allocation determine format selection, with integrated manufacturers favoring bulk delivery and formulation houses preferring smaller units.
- Bulk Tankers:Dedicated tanker deliveries for integrated petrochemical complexes and large coating houses with captive storage. Ludwigshafen monomer complex supply chains sustain these flows for European coating manufacturers.
- Intermediate Bulk Containers:Flexible intermediate volume solution for mid-tier formulation houses managing multi-product inventories.
- Drums:Standard 200-liter units for specialty adhesive manufacturers with batch-scale operations.
- Pails:Small-format packaging for laboratory-scale formulation development and cosmetic-grade applications.
Bulk Tankers dominates throughput volume. Intermediate Bulk Containers is where procurement flexibility concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany absorb premium pricing for REACH-compliant grades with minimal elasticity, while Chinese purchasers concentrate procurement power through direct monomer supply agreements that compress trader margins. India's emerging coating infrastructure shows intermediate price sensitivity as BIS compliance timelines force specification-grade sourcing decisions.
China
E-commerce logistics packaging expansion drives specification-grade monomer absorption by domestic tape and label manufacturers. MEE implements GB standards on VOC emissions from coating operations, filtering permissible monomer specifications for adhesive producers. The Yangtze River Delta coating cluster scales capacity to serve furniture and automotive finishing demand.
Germany
European coating houses sustain integrated supply chains from the Ludwigshafen monomer complex for REACH-compliant high-purity grades. ECHA enforces Annex XVII residual acrylic acid thresholds, redirecting procurement toward domestic producers with validated purity documentation. The Rhine-Neckar industrial region anchors specialty adhesive formulation for automotive tier-one suppliers.
United States
UV-curable coating lines displace solvent-based furniture and automotive finishing systems, forcing monomer suppliers to reconfigure reactive diluent portfolios. EPA Toxic Substances Control Act reporting requirements shape import volumes for polymer precursor chemicals. The Gulf Coast petrochemical corridor supplies acrylic acid feedstock to domestic esterification operations.
Japan
Precision esterification technology anchors Asia-Pacific specialty demand for electronics-grade material with residual alcohol content below 50 ppm. METI oversees chemical inventory listings that filter formulation inputs for display and semiconductor packaging adhesives. The Osaka-Kobe industrial zone concentrates catalyst expertise for high-purity monomer production.
India
Automotive assembly localization under BIS standards compliance timelines generates uncaptured specification-grade monomer demand. CDSCO and central environmental regulators implement emission standards that mandate high-solids coating formulations. The Maharashtra-Gujarat industrial corridor builds domestic adhesive manufacturing capacity for construction and packaging applications.
Global Isononyl Acrylate Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated petrochemical complexes commanding purity documentation advantages while regional esterification specialists capture formulation flexibility premiums. The vendor base separates into three strategic tiers: backward-integrated monomer complexes, precision catalyst specialists, and commodity traders facing margin compression from direct supply agreements. Dominant competitive moves include capacity expansion in high-purity grades and strategic partnerships between monomer suppliers and UV-curable coating formulators.
Among German-integrated chemical conglomerates, BASF SE exemplifies the monomer complex archetype with Ludwigshafen supply chain control. Osaka Organic Chemical Industry Ltd. and Mitsubishi Chemical Group Corporation represent Japanese precision esterification specialists occupying positions in catalyst-driven purity differentiation. These three anchors illustrate how geographic clustering around regulatory compliance and technical capability shapes competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Osaka Organic Chemical Industry Ltd. |
| Mitsubishi Chemical Group Corporation |
| Dow Inc. |
| Arkema S.A. |
| Nippon Shokubai Co. Ltd. |
| Evonik Industries AG |
| Sumitomo Chemical Co. Ltd. |
| LG Chem Ltd. |
| Others |
Supply & Pricing Matrix
REACH Annex XVII residual acrylic acid thresholds gate both supplier qualification and price differentiation simultaneously, forcing European coating houses toward documented high-purity grades while Asian traders face margin compression on unverified material. This regulatory filter concentrates procurement power among integrated monomer complexes that command premium positioning through validated purity documentation.
Pricing Analysis
After-sales technical service and formulation support drives lifetime value in specification-grade isononyl acrylate procurement. Three-tier pricing structure across premium, standard, and economy levels separates REACH-compliant monomers with sub-50 ppm residual alcohol from commodity grades lacking purity certification. Cost compression in standard-tier reactive diluents is intensifying because acrylic acid feedstock volatility transmits directly from propylene cracker economics. Mid-tier formulation houses in India and Southeast Asia show highest price sensitivity, while German automotive tier-one suppliers absorb premium pricing with minimal elasticity.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints elevate inbound logistics costs for specification-grade monomer shipments. Supply concentrates in Germany, China, and Japan, with the Ludwigshafen complex, Yangtze River Delta coating cluster, and Osaka-Kobe industrial zone anchoring regional production. Feedstock dependencies on propylene-derived acrylic acid and isononyl alcohol from oxo-alcohol streams tether margin predictability to cracker operations. Single-source vulnerability from BASF's Ludwigshafen concentration creates procurement risk for European REACH-compliant grades. Distribution runs through direct supply agreements with integrated petrochemical complexes, displacing distributor intermediaries in volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. REACH compliance documentation and GB standard recertification timelines create switching costs that lock formulation houses into pre-qualified supplier relationships.
For Market Incumbents: Fortify supply chain control through captive esterification capacity in high-purity grades and strategic partnerships with UV-curable coating formulators. Silicone pressure-sensitive adhesive substitution in medical and electronics applications threatens acrylic volume retention. Backward integration into acrylic acid feedstock secures margin predictability against propylene volatility.
For New Entrants and Emerging Players: Differentiate on catalyst-driven purity differentiation below 50 ppm residual alcohol content to serve electronics-grade specifications in Japan and China. India's emerging coating infrastructure under BIS compliance timelines represents the most penetrable geography. Target direct supply agreements with domestic adhesive manufacturers scaling capacity for automotive assembly localization.
For Investors and Strategic Acquirers: China's MEE GB standard recertification timelines reshape the acquisition landscape by locking adhesive manufacturers into 12-18 month validation cycles. Long-term viability centers on precision esterification technology specialists with demonstrated catalyst expertise. Monitor ECHA enforcement actions against non-compliant imports as the signal indicating procurement consolidation toward documented purity suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in High-Purity Grades | BASF and Osaka Organic Chemical anchor supply security for REACH-compliant European coating houses. |
| Backward Integration into Acrylic Acid Feedstock | Integrated petrochemical complexes compress cost volatility transmission from propylene cracker economics. |
| Long-term Supply Agreement with UV Formulators | Furniture finishing lines in Italy and Germany lock in reactive diluent volumes for LED cure systems. |
| Joint Venture for India Coating Infrastructure | Maharashtra-Gujarat industrial corridor localization captures BIS compliance-driven specification-grade demand. |
| Green Manufacturing Transition | EU Green Deal procurement mandates favor regional suppliers with documented supply chain emissions data. |
Research Methodology
Cross-validation between primary interviews with plant managers at European coating houses and secondary customs trade data anchors the qualitative findings. Technical R&D directors at Japanese precision esterification specialists, procurement leads at Chinese tape and label manufacturers, distribution channel partners in India, and regulatory affairs specialists at ECHA contributed primary perspective. Bottom-up triangulation against Cefic chemical industry reports, SEC filings from listed petrochemical conglomerates, and MEE GB standard documentation validated volume estimates.
Sensitivity analysis across propylene feedstock price scenarios and regulatory compliance cost assumptions shapes the analytical framework. Segmentation dimensions include purity grade tier, end-use industry, packaging format, and regional production hub. CAGRs derive from modeled volume absorption in pressure-sensitive adhesives and UV-curable coatings across the projection horizon. Electronics-grade purity thresholds and VOC emission standard stringency serve as industry-specific forecast inputs.
Material uncertainties — propylene feedstock volatility, REACH Annex XVII threshold revisions, and silicone substitution acceleration in medical applications — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and coating capacity buildout timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
Acrylic Flooring Adhesives Market
Adhesives & Sealants
North America Automotive Adhesives and Sealants Market
Adhesives & Sealants
Acrylates Copolymer Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
Electric Vehicle Adhesives and Sealants Market
Adhesives & Sealants
Mexico Adhesives Market
Adhesives & Sealants
Global Epoxy Adhesive Market
Adhesives & Sealants
Global EVA Adhesives Market
Adhesives & Sealants
South Korea Adhesives Market
Adhesives & Sealants
Wearable Adhesives Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Spray Glue Market
Adhesives & Sealants
South America Cyanoacrylate Adhesives Market
Adhesives & Sealants
Dibutyl Maleate (DBM) Market
Adhesives & Sealants
Malaysia Sealants Market
Adhesives & Sealants
Wood Repair Epoxy Market