
 Europe Ventilation Equipment Market | 2026-2036
Europe Ventilation Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ventilation Equipment Market Insights
Market Context
Poland is narrowing the capacity gap in ventilation component manufacturing as several suppliers expand motor and fan assembly lines near Wrocław. Systemair AB leverages its Baltic production footprint to sustain delivery advantages across Central European construction channels. Volution Group plc anchors its position through dedicated R&D facilities in the United Kingdom that focus on acoustic performance and energy recovery. Daikin Industries Ltd. competes by integrating ventilation with its established climate systems presence across European commercial building portfolios.
Technical Definition and Segment Structure
Europe ventilation equipment encompasses mechanical systems designed to extract, supply, filter, and condition air within enclosed spaces, typically operating at pressure differentials between 50 and 2,500 Pascals and achieving heat recovery efficiencies exceeding 80 percent in premium configurations. These systems serve to maintain indoor air quality, control humidity, and minimize thermal energy loss in residential, commercial, and industrial environments. Air handling units dominate value capture due to their central role in integrated HVAC architectures and higher engineering content, while demand-controlled ventilation is expanding fastest as building automation penetration deepens. Ducting systems remain a mature margin pool where material cost management and installation labor efficiency determine supplier profitability.
Regulatory Framework and Outlook
The EU Green Deal, Ecodesign Directive, and F-Gas Regulation collectively mandate progressive efficiency improvements and refrigerant phase-downs that reshape product development priorities for equipment manufacturers. CE marking and the Energy Performance of Buildings Directive enforce compliance thresholds that filter out lower-tier imports and reward certified domestic suppliers. Stakeholders must monitor how the proposed revision to the Energy Performance of Buildings Directive affects ventilation rate requirements in existing building stock, as this will determine retrofit opportunity scale and product specification intensity across member states.
Market Dynamics
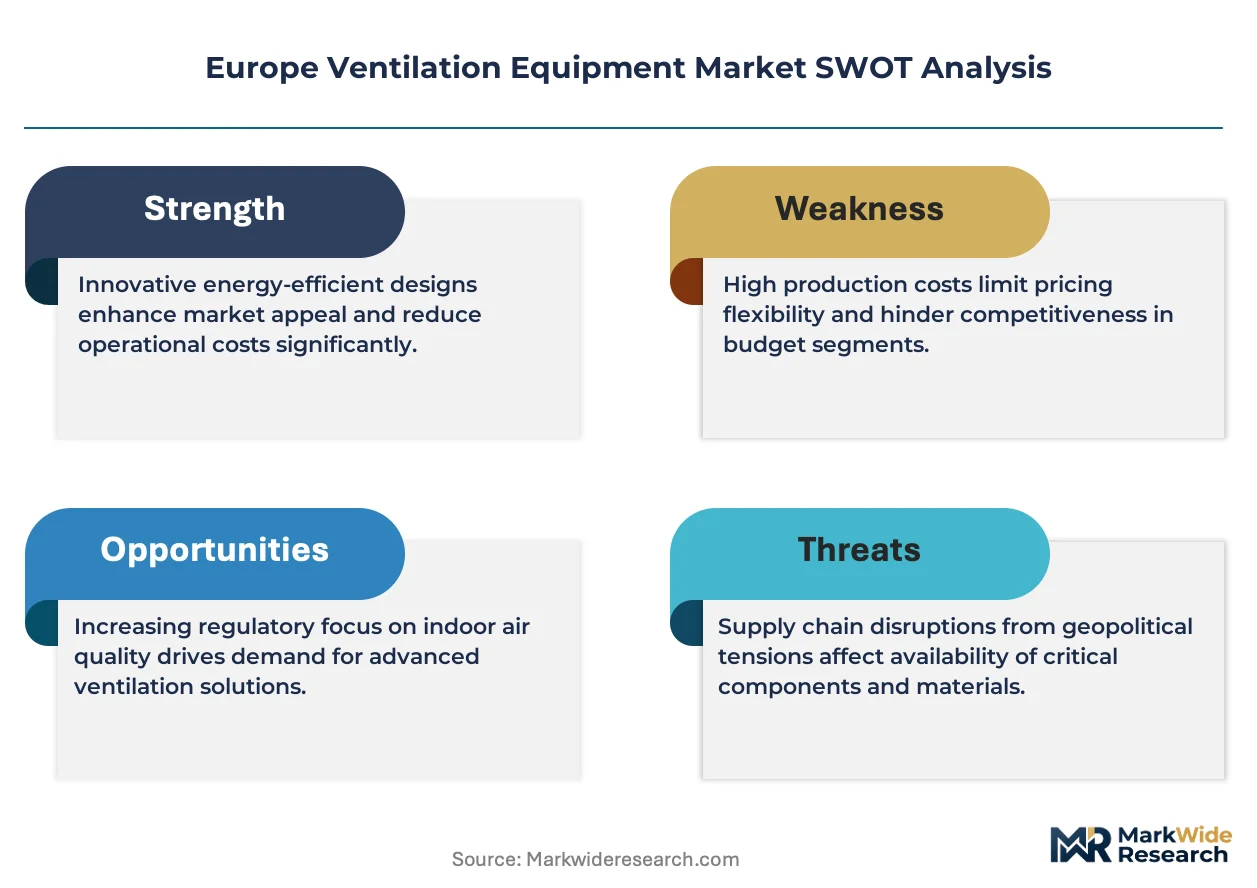
The EU Green Deal's tightening Ecodesign thresholds are compressing product lifecycles across European ventilation equipment, forcing manufacturers to accelerate heat recovery efficiency gains while managing component cost inflation from rare-earth magnet supply constraints.
Growth Catalysts
- Healthcare Construction Surge:Hospital and clinic builds in Germany and France are specifying centralized air handling units with 85%+ heat recovery efficiency as standard infrastructure.
- F-Gas Regulation Phase-Down:Refrigerant restrictions under the EU F-Gas Regulation are redirecting commercial HVAC specification toward natural refrigerant-compatible ventilation architectures.
- Building Automation Penetration:Demand-controlled ventilation systems are capturing specification share as BMS integration becomes mandatory in Nordic commercial building codes.
Market Restraints
- Rare-Earth Magnet Dependency:Permanent magnet motor supply concentrates among Chinese processors, exposing European fan manufacturers to neodymium price volatility and export restriction risk.
- Installation Labor Bottlenecks:Certified ventilation installer capacity in France and Benelux trails equipment delivery capacity by 18-24 months, elongating project completion timelines.
- CE Marking Complexity:Evolving harmonized standards under the Construction Products Regulation create compliance lag for innovative heat exchanger geometries.
Strategic Opportunities
- Polish Manufacturing Scale-Up:Component assembly expansion near Wrocław offers tariff-advantaged supply positioning for Central European renovation markets.
- Residential Retrofit Wave:The proposed Energy Performance of Buildings Directive revision will mandate mechanical ventilation in existing single-family stock across Germany and Austria.
- Acoustic Performance Premium:R&D investment in low-noise fan blade geometries addresses specification intensity in Netherlands and Denmark urban residential towers.
Industry Challenges
- Thermal Bridge Engineering Talent:Heat exchanger design expertise for counter-flow configurations remains concentrated among aging specialist engineers in Germany and Switzerland.
- Legacy Ductwork Compatibility:Pressure-optimized EC motor retrofits require dimensional adaptation to 1980s-era galvanized steel distribution systems common in French commercial stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ventilation Equipment Market |
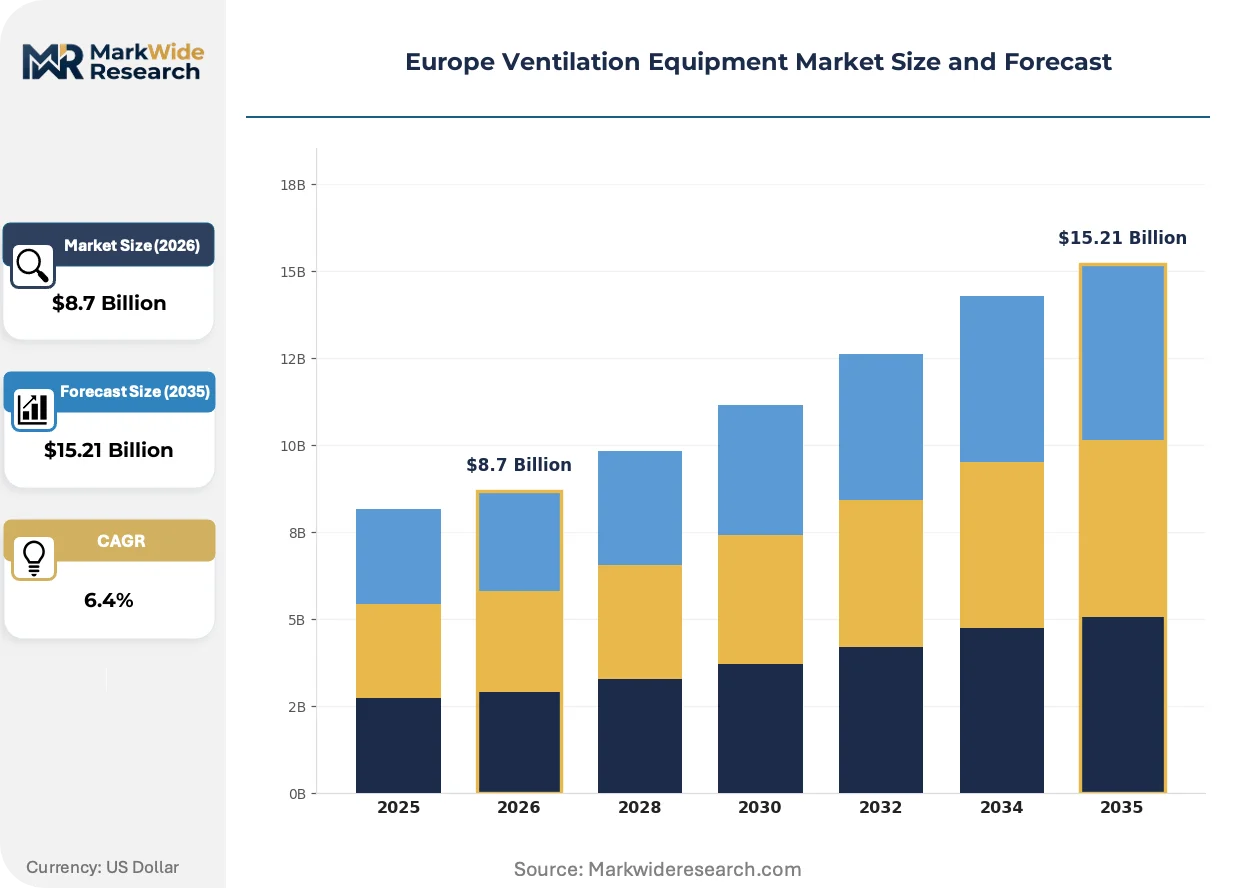
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exhaust Fans, Air Handling Units, Ducting Systems, VAV Systems Application: Residential, Commercial, Industrial, Automotive Technology: Natural Ventilation, Mechanical Ventilation, Hybrid Ventilation, Demand-Controlled Ventilation End User: Contractors, Builders, Facility Managers, Engineers |
| Companies Covered | Systemair AB, Volution Group plc, Aldes Aéraulique S.A., Daikin Industries Ltd., Swegon AB, ebm-papst, Zehnder Group, FLAKT Group, Helios Ventilatoren, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ventilation Equipment Market Trends and Innovations
Digital twin architectures are compressing equipment commissioning cycles while refrigerant-free heat pump integration and acoustic specification intensity are redefining competitive differentiation across European project channels.
Computational fluid dynamics software is virtualizing the traditional physical prototyping phase for air handling unit design. German and Swedish manufacturers are deploying these tools to validate heat exchanger geometries before metal fabrication. This compression of development cycles is virtualizing the competitive advantage previously held by incumbents with extensive physical test facilities.
The EU Ecodesign Directive's 2025 efficiency tier upgrades are mandating variable-speed drives as baseline equipment across residential and commercial categories. Manufacturers serving the Nordic markets are pre-certifying products to stricter national building codes ahead of harmonized EU implementation. Air-to-air heat recovery segments face the steepest compliance cost escalation as specific fan power limits tighten.
Facility managers in Netherlands and Denmark are unbundling maintenance contracts from initial equipment procurement, favoring specialist service providers over manufacturer-captive offerings. Independent ventilation service firms are capturing recurring revenue streams through IoT-enabled filter change and performance optimization subscriptions. This disintermediation is most visible in commercial office retrofits where operating expenditure visibility outweighs capital cost minimization priorities.
Europe Ventilation Equipment Market Segmentation
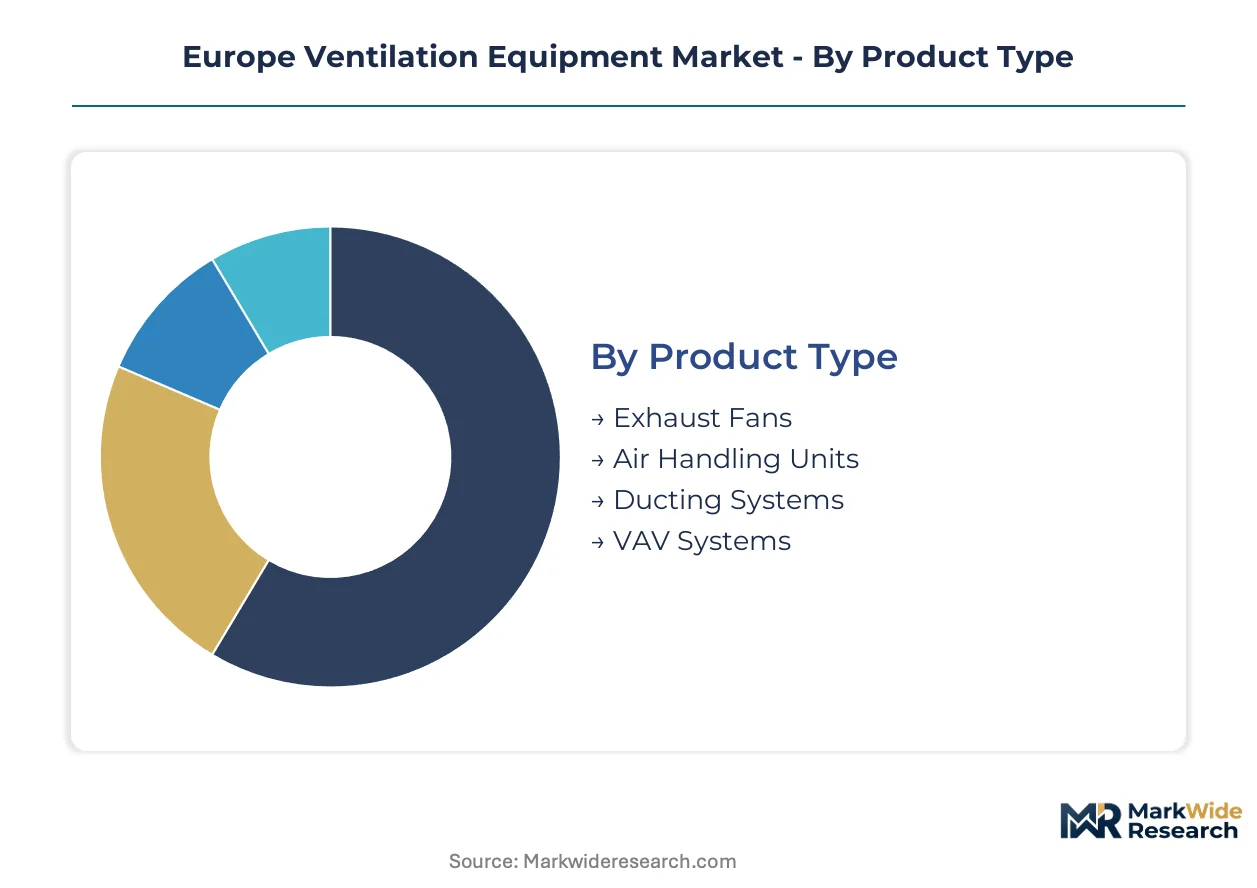
Segmentation in European ventilation equipment reveals how regulatory pressure and building stock characteristics fragment demand across technical specifications and procurement channels. Understanding these divisions exposes where efficiency mandates concentrate investment and where installer capacity constraints throttle adoption.
Product Type:
Cost tiers separate commodity components from engineered systems with heat recovery integration.
- Air Handling Units:Centralized systems integrating filtration, heating, cooling, and heat recovery functions at pressure ratings up to 2,500 Pascals. German hospital construction and Nordic commercial retrofits specify these units with 85%+ thermal efficiency, though rare-earth motor supply constraints inflate lead times for premium configurations.
- Exhaust Fans:Point-source extraction devices ranging from residential bathroom units to industrial fume hoods, typically operating at 50-400 Pascals. Demand concentrates in French residential renovation where the Energy Performance of Buildings Directive mandates mechanical extraction in existing single-family stock.
- Ducting Systems:Galvanized steel, aluminum, and polymer distribution networks with standardized diameters. Polish manufacturing clusters near Wrocław exploit tariff advantages to supply Central European contractor networks.
- VAV Systems:Variable air volume terminals modulating supply based on zone occupancy and temperature load. BMS integration requirements in Netherlands commercial codes accelerate specification of pressure-independent terminal units.
The dominant share belongs to Air Handling Units, while VAV Systems is closing the gap fastest.
Application:
Building automation penetration and renovation intensity vary sharply across use cases.
- Commercial:Office, retail, and hospitality installations requiring centralized air management with demand-controlled ventilation. Nordic building codes mandate BMS integration, compressing payback periods for sensor-driven airflow modulation.
- Residential:Single-family and multi-unit mechanical ventilation with heat recovery. German and Austrian regulatory proposals will mandate retrofit installation in existing stock, expanding addressable market scope beyond new construction.
- Industrial:Process ventilation, fume extraction, and contamination control for manufacturing environments. CE marking complexity under the Construction Products Regulation delays certification for specialized heat exchanger geometries.
- Automotive:Paint booth ventilation and battery manufacturing cleanroom systems. F-Gas Regulation phase-down redirects specification toward natural refrigerant-compatible architectures in assembly plant HVAC.
Commercial applications command the largest installed base, while Residential retrofits are expanding most quickly.
Technology:
Regulatory efficiency thresholds filter legacy approaches from compliant system architectures.
- Mechanical Ventilation:Fan-driven supply and extraction with optional heat recovery, operating continuously or on timer control. EU Ecodesign Directive mandates variable-speed drives as baseline equipment, eliminating single-speed motor specifications.
- Demand-Controlled Ventilation:Sensor-activated airflow modulation responding to CO2, humidity, or occupancy signals. Netherlands and Denmark facility managers prioritize operating expenditure visibility through IoT-enabled performance optimization subscriptions.
- Natural Ventilation:Buoyancy and wind-driven airflow through operable openings and stack effect. Urban residential towers in Denmark face acoustic specification intensity that limits reliance on window-based strategies.
- Hybrid Ventilation:Combined mechanical and natural modes switching by season or indoor condition. Legacy ductwork compatibility challenges in French commercial stock constrain pressure-optimized EC motor retrofits.
Mechanical Ventilation retains the dominant installed position, though Demand-Controlled Ventilation is gaining share fastest.
End User:
Procurement authority and technical specification capability determine product selection criteria.
- Facility Managers:Operating-phase decision-makers unbundling maintenance from initial procurement in Netherlands and Denmark commercial retrofits. Independent service firms capture recurring revenue through filter change and performance optimization subscriptions.
- Contractors:Installation-phase purchasers balancing equipment cost against labor efficiency. Certified installer capacity in France and Benelux trails equipment delivery by 18-24 months, elongating project timelines.
- Engineers:Design-phase specifiers leveraging computational fluid dynamics to validate heat exchanger geometries before fabrication. German and Swedish manufacturers deploy these tools to compress development cycles.
- Builders:New construction procurement focused on capital cost minimization and code compliance documentation. Polish manufacturing scale-up offers tariff-advantaged supply positioning for Central European builder networks.
Facility Managers control the largest replacement and retrofit spend, while Engineers are reshaping specification fastest through digital design tools.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component assembly clusters near Wrocław and Baltic production footprints concentrate supply-side capacity for Central European distribution. German hospital construction and Nordic commercial retrofits anchor demand intensity. The EU Green Deal and Ecodesign Directive reshape efficiency thresholds across member states.
Germany
Hospital and clinic construction in Berlin and Munich specifies centralized air handling units with 85%+ heat recovery efficiency as standard infrastructure. The Energy Performance of Buildings Directive mandates progressive efficiency improvements that filter out lower-tier equipment. Manufacturing expertise for counter-flow heat exchanger geometries concentrates among specialist engineers in Baden-Württemberg and Bavaria.
France
Residential renovation mandates mechanical extraction in existing single-family stock under EPBD implementation, driving exhaust fan demand. CE marking complexity under the Construction Products Regulation creates compliance lag for innovative heat exchanger designs. Certified installer capacity in Île-de-France and Auvergne-Rhône-Alpes trails equipment delivery by 18-24 months.
Netherlands
Facility managers unbundle maintenance contracts from initial procurement, favoring independent service providers with IoT-enabled performance subscriptions. BMS integration requirements in commercial building codes accelerate specification of pressure-independent VAV terminals. Urban residential towers in Amsterdam and Rotterdam face acoustic specification intensity that limits natural ventilation reliance.
Poland
Manufacturing expansion near Wrocław exploits tariff-advantaged positioning for Central European contractor networks. Motor and fan assembly lines scale to serve renovation markets in Germany and Austria. Polish production clusters supply ducting systems and component assemblies to builder networks across the Visegrád region.
Sweden
Computational fluid dynamics deployment compresses development cycles for air handling unit validation before metal fabrication. Pre-certification to stricter national building codes ahead of harmonized EU implementation secures specification advantages. Manufacturers leverage digital twin architectures to virtualize commissioning cycles for Nordic commercial retrofits.
Europe Ventilation Equipment Market Competitive Landscape
Pan-European HVAC conglomerates and specialized ventilation engineering houses split the market between integrated climate system portfolios and dedicated air management expertise. Consolidation pressure intensifies as Ecodesign efficiency tiers compress product lifecycles and raise R&D capital requirements. Two strategic archetypes dominate: diversified climate technology groups leveraging cross-product bundling, and focused ventilation specialists commanding premium positioning through acoustic performance and heat recovery engineering. Competitive moves concentrate on manufacturing scale-up in tariff-advantaged locations and backward integration into motor and heat exchanger component supply.
Within the specialized ventilation tier, Systemair AB and Volution Group plc exemplify contrasting geographic anchoring strategies. Systemair leverages its Baltic production footprint to sustain delivery advantages across Central European construction channels. Volution Group anchors its position through dedicated R&D facilities in the United Kingdom that focus on acoustic performance and energy recovery. Daikin Industries occupies a position as the diversified climate technology archetype, competing by integrating ventilation with its established climate systems presence across European commercial building portfolios.
| Leading Market Players |
|---|
| Systemair AB |
| Volution Group plc |
| Aldes Aéraulique S.A. |
| Daikin Industries Ltd. |
| Swegon AB |
| ebm-papst |
| Zehnder Group |
| FLAKT Group |
| Helios Ventilatoren |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in certified installer networks across France and Benelux drives supplier pricing power for bundled equipment-service packages while compressing margins on standalone hardware transactions. Equipment manufacturers respond by shifting revenue mix toward recurring maintenance subscriptions that capture value from elongated project timelines.
Pricing Analysis
The EU Ecodesign Directive dictates the pricing tier structure across European ventilation equipment, separating premium heat recovery configurations from standard-efficiency units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and heat recovery efficiency thresholds. Cost compression in economy tiers is intensifying because rare-earth magnet supply constraints inflate motor costs. Residential contractors in France exhibit highest price sensitivity, while Nordic facility managers prioritize operating expenditure visibility over capital cost minimization.
Supply Chain Analysis
Polish contract manufacturers and Baltic assembly operations hold the dominant share of component fabrication capacity for Central European distribution. Supply concentrates in Poland, Germany, and Sweden for heat exchanger engineering and final unit assembly. Raw material dependencies center on neodymium magnets from Chinese processors, galvanized steel sheet from European mills, and polymer ducting compounds. Single-source vulnerability in permanent magnet supply exposes manufacturers to export restriction risk. Distribution runs through specialized HVAC wholesalers and direct contractor channels serving national renovation markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Independent ventilation service firms are capturing recurring revenue streams through IoT-enabled filter change and performance optimization subscriptions, expanding faster than hardware shipments in Netherlands and Denmark commercial retrofits.
For Market Incumbents: Build switching-cost moats through captive IoT service platforms that lock facility managers into multi-year performance contracts. Deepen backward integration into heat exchanger core manufacturing to offset rare-earth magnet cost volatility. Acquire certified installer networks in France and Benelux to resolve capacity bottlenecks that elongate project completion timelines. For New Entrants and Emerging Players: Austrian and German residential retrofit markets offer underpenetrated white-space as EPBD revisions mandate mechanical ventilation in existing single-family stock. Polish manufacturing clusters provide tariff-advantaged supply positioning for Central European contractor networks. Partner with computational fluid dynamics software providers to compress product development cycles without capital-intensive physical test facilities. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across heat recovery ventilation segments as Ecodesign efficiency tiers compress product lifecycles and raise R&D requirements. Acquisition targets should command premium positioning through acoustic performance engineering or Nordic market pre-certification advantages. Monitor rare-earth magnet price volatility and Chinese export policy shifts as early indicators of margin compression risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Manufacturing | Captures value from counter-flow thermal engineering expertise concentrated in Baden-Württemberg and Bavaria. |
| IoT Service Platform Development | Enables recurring revenue capture from facility managers unbundling maintenance from initial procurement in Netherlands. |
| Polish Manufacturing Scale-Up | Exploits tariff-advantaged positioning to serve Central European renovation markets from Wrocław assembly clusters. |
| Pre-Certification to Nordic Building Codes | Secures specification advantages ahead of harmonized EU Ecodesign implementation across Sweden and Denmark. |
| Certified Installer Network Acquisition | Resolves 18-24 month capacity gaps in France and Benelux that elongate project completion timelines. |
Research Methodology
The analysis maps air handling units, exhaust fans, ducting systems, and demand-controlled ventilation architectures, each validated through equipment manufacturers, certified installation contractors, facility management directors, and building automation integrators. Primary fieldwork combined structured interviews with secondary validation against EU Ecodesign Directive filings, national building code registries, CE marking databases, and customs trade records. Bottom-up equipment shipment data triangulates against top-down construction spending estimates.
Assumptions held fixed include regulatory implementation timelines and rare-earth magnet supply availability, while variables tested included renovation intensity across member states and BMS penetration rates. Segmentation dimensions modeled encompass product type, application, technology, and end-user procurement authority across the projection horizon. CAGRs derive from regression analysis of historical efficiency mandate adoption curves and heat recovery technology cost reduction trajectories. Forecast inputs incorporate hospital construction pipelines in Germany and EPBD revision implementation schedules.
Practitioners should monitor rare-earth export restrictions, installer certification rates, and EPBD revision finalization for early signals of forecast deviation. Quarterly review of neodymium price indices, national building permit data, and CE marking approval timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Asia-Pacific Heating Equipment Market
HVAC Equipment
France Commercial HVAC Market
HVAC Equipment
HVAC Fan and Evaporator Coil Market
HVAC Equipment
Europe Hydronic Radiators Market
HVAC Equipment
China HVAC Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
Warming Cabinet Market
HVAC Equipment
Variable Air Volume Box Market
HVAC Equipment
Europe Heat Pump Market
HVAC Equipment
Global Fan Coil Unit Market
HVAC Equipment
Air-Conditioning Natural Convection Refrigerator Market
HVAC Equipment
Global Industrial Air Chiller Market
HVAC Equipment
Global VRF System Market
HVAC Equipment
Positive Displacement Blowers Market
HVAC Equipment
United Kingdom Commercial HVAC Market
HVAC Equipment
Shell and Tube Heat Exchangers Market