
 Acetyl Tributyl Citrate Market | 2026-2036
Acetyl Tributyl Citrate Market Size, Share, and Industry Trends Forecast 2026-2036
Acetyl Tributyl Citrate Market Outlook
Pharmaceutical and medical device buyers are gaining share as food packaging demand is bifurcating between premium citrate grades and commodity substitutes. Jungbunzlauer leverages its fermentation-based platform to supply high-purity ATBC for European medical applications. Vertellus anchors North American supply through backward integration into citric acid feedstocks. Jiangsu Lemon competes on volume, specializing in liquid-grade shipments for Asian coating producers.
Acetyl tributyl citrate functions as a citric acid ester plasticizer produced via esterification of citric acid with n-butanol followed by acetylation, yielding a colorless liquid with low volatility and excellent compatibility with PVC and cellulosic resins. Its primary purpose centers on replacing phthalate plasticizers in applications requiring direct food contact or physiological safety clearance. The plasticizers segment dominates volume as manufacturers convert legacy phthalate lines, while medical devices represents the fastest-growing application channel where biocompatibility certification commands margin premiums. Liquid form leads distribution due to ease of incorporation into existing compounding equipment, though granular variants are gaining traction in automated dry-blend operations.
REACH restrictions on ortho-phthalates and FDA Title 21 food-contact substance notifications shape formulation mandates across European and North American supply chains, directly determining market access for imported ATBC grades. China's GB standards and SAMR oversight enforce parallel compliance thresholds for domestic pharmaceutical and toy applications, creating dual-certification requirements for exporters. Stakeholders must monitor regulatory divergence between EU ECHA updates and emerging economy standards to anticipate reformulation timelines and qualification costs.
Market Dynamics
REACH ortho-phthalate restrictions and FDA Title 21 food-contact mandates are forcing immediate formulation switches across European and North American PVC compounding operations, redirecting procurement budgets toward citrate ester alternatives.
Growth Catalysts
- REACH Annex XVII phthalate limitations:European manufacturers must eliminate DEHP and DBP from food-contact articles by 2025, accelerating ATBC qualification programs across legacy extrusion lines.
- Medical device biocompatibility certification:ISO 10993-compliant grades command margin premiums as catheter and IV bag producers seek phthalate-free alternatives for neonatal and long-term implant applications.
- China's specialty chemical production scaling:Domestic fermentation-based citric acid capacity expansion is compressing regional feedstock costs and enabling localized ATBC synthesis for Asian coating markets.
Market Restraints
- n-Butanol feedstock volatility:Petrochemical-derived alcohol prices fluctuate with crude oil movements, squeezing esterification margins for non-integrated producers.
- Supply concentration in fermentation citric acid:Three producers control 70% of pharmaceutical-grade feedstock, creating bottleneck risk for high-purity ATBC batches.
- Performance gap in high-temperature wire insulation:ATBC's lower thermal stability versus trimellitates limits penetration into automotive under-hood cable applications.
Strategic Opportunities
- India's toy and childcare product export sector:BIS certification requirements for phthalate-free plastics are creating first-mover advantage for ATBC-qualified compounders serving European retail chains.
- Bioplastic compatibility formulations:PLA and PHA blending with citrate plasticizers addresses brittleness limitations in compostable food serviceware.
- EU Green Deal sustainable chemistry incentives:Fermentation-derived ATBC qualifies for preferential procurement scoring in public-sector medical device tenders.
Industry Challenges
- Multi-jurisdiction food-contact notification backlog:FDA FCN queue delays and EFSA re-evaluation timelines extend product launch cycles by 18-24 months.
- Legacy phthalate compounding equipment contamination:Cross-grade switching requires dedicated storage and processing lines to prevent regulatory non-compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetyl Tributyl Citrate Market |
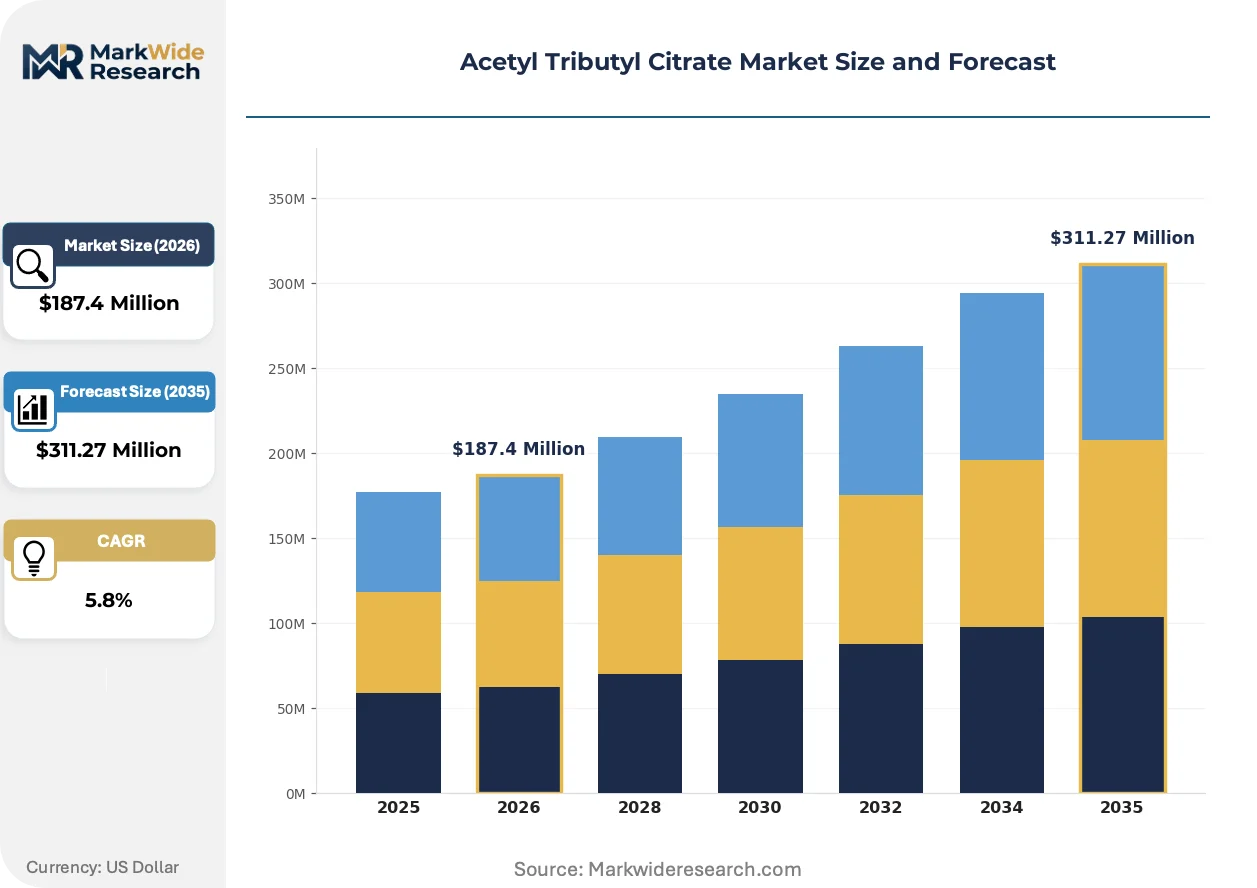
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Coatings, Adhesives, Sealants Application: Food Packaging, Medical Devices, Pharmaceuticals, Toys End User: Manufacturers, Retailers, Distributors, Medical Facilities Form: Liquid, Powder, Granular, Emulsion |
| Companies Covered | Jiangsu Lemon, Jiangsu Licheng Chemical, Jungbunzlauer, Taizhou Mingguang Chemical, Wuxi Kailai Biotechnology, Vertellus, Shandong Kexing Chemical, Yangzhou Feiyang Chemical, KLJ Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetyl Tributyl Citrate Market Strategic Shifts
Enzymatic esterification processes are displacing traditional acid-catalyzed routes, promising lower energy intensity and reduced byproduct formation for pharmaceutical-grade ATBC production.
Continuous-flow reactor technology is decomposing batch manufacturing economics. European specialty chemical producers are retrofitting pilot plants with microreactor arrays to shorten residence times and improve color specifications. This shift is compressing capital requirements for entry-level pharmaceutical-grade capacity.
REACH SVHC candidate list expansion to include additional ortho-phthalate metabolites is tightening compliance windows. Compounders serving children's products and food contact must complete supply chain audits and reformulation validations ahead of 2026 sunset dates. Nordic markets are responding fastest, with Swedish and Danish converters already mandating citrate-only certificates.
Specification-driven tendering is replacing spot purchasing in medical device supply chains. German and Swiss catheter manufacturers now require ISO 13485-traceable ATBC with dedicated batch documentation, displacing commodity traders from qualified supplier lists. This behavioral shift concentrates procurement authority among vertically integrated fermentation specialists with captive citric acid supply.
Acetyl Tributyl Citrate Market Segmentation
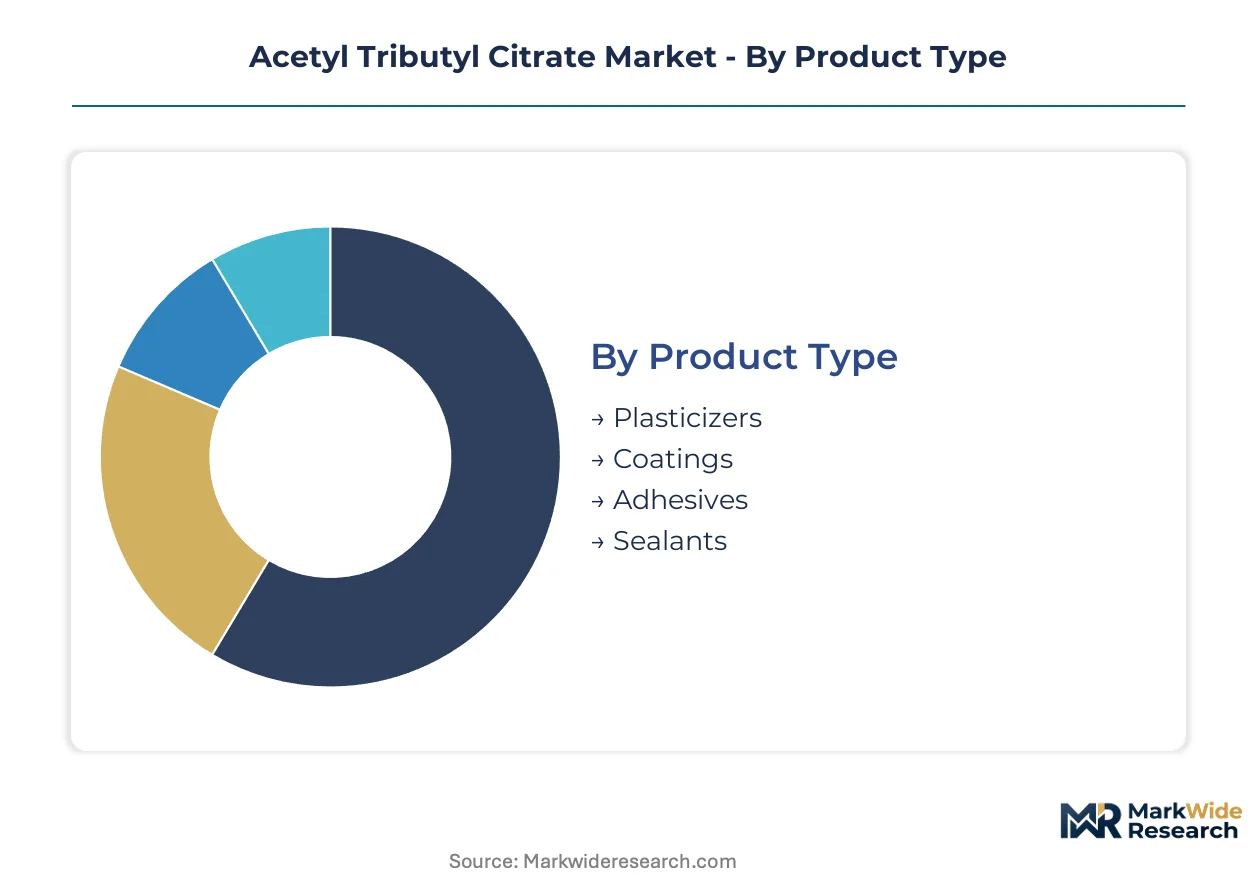
ATBC market segmentation reveals how regulatory compliance tiers fragment procurement across end-use channels. Specification requirements diverge sharply between food-contact mandates and medical-grade certifications, forcing suppliers to maintain parallel production lines.
Product Type:
REACH Annex XVII and FDA Title 21 create divergent purity specifications across product categories, with pharmaceutical applications demanding fermentation-traceable feedstocks.
- Plasticizers:Citric acid ester formulations replace ortho-phthalates in PVC compounding for food-contact films and medical tubing. European converters must eliminate DEHP from legacy extrusion lines ahead of compliance deadlines. German and Swiss catheter manufacturers now require ISO 13485-traceable grades with dedicated batch documentation.
- Coatings:Low-volatility ATBC serves as a film-forming plasticizer in cellulose-based lacquers for pharmaceutical tablet coatings. Chinese coating producers source liquid-grade shipments from domestic fermentation-based suppliers to serve regional generic drug manufacturers. India's pharmaceutical export sector drives specification tightening for coating-grade material.
- Adhesives:Pressure-sensitive adhesive formulations leverage ATBC's compatibility with natural rubber and acrylic polymers for food-label applications.
- Sealants:Construction and packaging sealants utilize citrate plasticizers where direct food contact or toy safety compliance is required.
Plasticizers handles the majority of throughput; Coatings is gaining share fastest on pharmaceutical export demand.
Application:
Customer procurement behavior splits between spot purchasing for commodity food packaging and specification-driven tendering for medical channels.
- Food Packaging:Flexible film and rigid container manufacturers convert phthalate lines to citrate esters under tightening EU and US food-contact mandates. Nordic markets already mandate citrate-only certificates for children's food contact articles. Swedish and Danish converters lead qualification programs ahead of broader European adoption.
- Medical Devices:Catheter, IV bag, and blood bag producers seek ISO 10993-compliant grades for neonatal and long-term implant applications. Jungbunzlauer supplies high-purity ATBC from its fermentation platform for European medical device manufacturers. Biocompatibility certification commands substantial margin premiums over food-contact grades.
- Pharmaceuticals:Tablet coating and capsule shell applications require pharmaceutical-grade ATBC with full supply chain traceability.
- Toys:India's BIS certification requirements for phthalate-free plastics create first-mover advantage for ATBC-qualified compounders serving European retail chains.
Food Packaging manages current volume leadership; Medical Devices shows the steepest expansion trajectory on biocompatibility premiums.
End User:
Supply chain configuration determines pricing power, with integrated manufacturers capturing margin through captive citric acid production.
- Manufacturers:PVC compounders, coating formulators, and adhesive producers purchase ATBC in bulk for captive consumption. Vertellus anchors North American supply through backward integration into citric acid feedstocks. Non-integrated producers face margin pressure from n-butanol price volatility.
- Retailers:Private-label food packaging and toy brands specify citrate-only plasticizers to meet consumer safety expectations and preempt regulatory action.
- Distributors:Chemical distributors serve smaller compounders lacking direct supplier relationships, though medical-grade qualification requirements are displacing commodity traders from approved vendor lists.
- Medical Facilities:Hospital procurement departments increasingly specify phthalate-free devices, transmitting demand pressure upstream to device manufacturers.
Manufacturers dominate procurement volume; Medical Facilities is expanding most quickly as institutional purchasing policies tighten.
Form:
Processing economics favor liquid incorporation into existing compounding equipment, though automation trends reshape dry-blend preferences.
- Liquid:Colorless liquid ATBC integrates directly into PVC plastisol and coating formulations without additional processing. Ease of incorporation preserves legacy equipment utilization across European and Asian extrusion lines. Liquid form leads distribution due to established handling infrastructure.
- Powder:Spray-dried ATBC serves specialized adhesive and sealant applications requiring solid-phase blending.
- Granular:Automated dry-blend operations in high-volume food packaging favor granular variants for precise metering and reduced dust exposure. Granular grades are gaining traction as compounders retrofit for continuous processing.
- Emulsion:Water-based emulsion forms address aqueous coating systems and environmentally formulated adhesives.
Liquid form commands the largest share of shipments; Granular is climbing the fastest on automation investment in food packaging lines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese fermentation-based ATBC producers supply pharmaceutical-grade volumes to European medical device manufacturers under REACH-compliant certification programs. German compounders source high-purity citrate esters for catheter and IV bag applications ahead of DEHP elimination deadlines.
China
Domestic citric acid capacity expansion in Shandong and Jiangsu provinces compresses regional feedstock costs for ATBC synthesis. SAMR oversight enforces GB standards compliance for pharmaceutical and toy applications, creating dual-certification requirements for exporters. Yangzhou and Taizhou chemical clusters specialize in liquid-grade shipments for Asian coating markets.
Germany
Catheter manufacturers in Baden-Württemberg and North Rhine-Westphalia mandate ISO 13485-traceable ATBC with dedicated batch documentation. ECHA REACH Annex XVII phthalate limitations force immediate formulation switches across PVC compounding operations. Bavarian specialty chemical producers retrofit pilot plants with microreactor arrays for pharmaceutical-grade capacity.
United States
Medical device producers in Minnesota and Massachusetts seek ISO 10993-compliant grades for neonatal and long-term implant applications. FDA Title 21 food-contact substance notifications shape formulation mandates across North American supply chains. Vertellus anchors regional supply through backward integration into citric acid feedstocks.
India
Pharmaceutical coating formulators in Maharashtra and Gujarat drive specification tightening for export-grade material. BIS certification requirements for phthalate-free plastics create first-mover advantage for ATBC-qualified compounders serving European retail chains. Tamil Nadu toy manufacturers convert legacy phthalate lines ahead of childcare product export deadlines.
Switzerland
Swissmedic oversight of medical device materials elevates traceability requirements for citrate plasticizers in catheter and blood bag applications. Swiss and German catheter manufacturers now require dedicated batch documentation, displacing commodity traders from qualified supplier lists. Basel-region pharmaceutical clusters source fermentation-traceable ATBC for tablet coating applications.
Acetyl Tributyl Citrate Market Competitive Environment
Player mix skews toward fermentation-based specialists with captive citric acid supply and regional volume producers serving coating and packaging segments. The market structures around three tiers: vertically integrated pharmaceutical-grade suppliers, mid-scale Asian compounders, and commodity traders facing displacement from medical certification programs. Dominant competitive moves include backward integration into citric acid feedstocks and continuous-flow reactor technology licensing for color specification improvement.
Within the fermentation-specialist tier, Jungbunzlauer exemplifies the European pharmaceutical-grade archetype through its biobased platform, while Vertellus occupies the North American integrated position. Jiangsu Lemon and Taizhou Mingguang Chemical represent the Asian volume-driven segment, specializing in liquid-grade shipments for regional coating markets. KLJ Group sits within the diversified chemical portfolio archetype, spanning multiple plasticizer chemistries across industrial applications.
| Leading Market Players |
|---|
| Jiangsu Lemon |
| Jiangsu Licheng Chemical |
| Jungbunzlauer |
| Taizhou Mingguang Chemical |
| Wuxi Kailai Biotechnology |
| Vertellus |
| Shandong Kexing Chemical |
| Yangzhou Feiyang Chemical |
| KLJ Group |
| Others |
Value Chain & Pricing Dynamics
REACH Annex XVII phthalate limitations gate both supply qualification and price differentiation simultaneously, as European compounders must source ISO 13485-traceable ATBC with dedicated batch documentation to access medical device channels while food-contact grades compete on volume economics.
Pricing Analysis
Batch-reactor pricing gaps separate legacy acid-catalyzed production from enzymatic and continuous-flow pharmaceutical-grade tiers. Three-tier pricing structure across pharmaceutical-grade, food-contact, and industrial-coating levels reflects certification burden and traceability investment. Cost compression in industrial grades intensifies because Jiangsu Lemon and Taizhou Mingguang Chemical compete on liquid-grade volume for Asian coating markets. Medical device manufacturers show least price sensitivity due to biocompatibility certification requirements, while food packaging converters face acute pressure from commodity citrate substitutes.
Supply Chain Analysis
Inventory cycles stretch 8-12 weeks for pharmaceutical-grade ATBC due to fermentation citric acid batch release protocols and dual-certification documentation. Supply concentrates in China, Germany, and the United States, with Shandong and Jiangsu provinces anchoring Asian fermentation capacity. Feedstock dependencies rest on petrochemical-derived n-butanol, pharmaceutical-grade citric acid, and acetic anhydride acetylation agents. Single-source vulnerability runs through three producers controlling 70% of pharmaceutical-grade citric acid feedstock. Distribution runs through vertically integrated manufacturers serving qualified medical device compounders, with commodity traders displaced from approved vendor lists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ATBC incumbents face substitution defense against trimellitate plasticizers in high-temperature wire insulation and emerging bio-based polyester alternatives in compostable food serviceware.
For Market Incumbents: Secure captive citric acid supply through backward integration or long-term fermentation partnerships to defend margin position against n-butanol volatility. Lock in ISO 13485 certification investments ahead of ECHA SVHC candidate list expansion, as medical-grade traceability requirements displace commodity traders from qualified supplier lists. For New Entrants and Emerging Players: Anchor in India's BIS-certified toy and childcare export sector, where phthalate-free mandates create first-mover advantage for ATBC-qualified compounders serving European retail chains. Target automated dry-blend food packaging lines with granular-grade offerings, as compounders retrofit for continuous processing and precise metering. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous-flow reactor pharmaceutical-grade capacity, as microreactor arrays compress capital requirements for entry-level production. Prioritize acquisition targets with fermentation-traceable citric acid platforms and existing REACH/FDA dual-certification infrastructure. Watch enzymatic esterification process yields as the signal for next-generation cost structure inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Citric Acid Feedstocks | Vertellus and Jungbunzlauer anchor regional supply security through captive fermentation capacity. |
| Continuous-Flow Reactor Technology Licensing | European specialty chemical producers retrofit pilot plants with microreactor arrays for color specification improvement. |
| ISO 13485 Medical-Grade Certification Investment | German and Swiss catheter manufacturers mandate dedicated batch documentation, displacing commodity traders. |
| Long-term Supply Agreement with Coating Formulators | Chinese producers secure liquid-grade offtake from regional generic drug manufacturers in Yangzhou and Taizhou clusters. |
| Joint Venture for Indian Toy Sector Qualification | Tamil Nadu manufacturers convert legacy phthalate lines ahead of BIS certification deadlines for European retail chains. |
Study Parameters
A spread of perspectives from PVC compounding plant managers, pharmaceutical coating formulators, medical device procurement leads, and chemical distribution channel partners converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with fermentation platform R&D directors and downstream technical specification officers. Secondary validation drew from ECHA REACH Annex XVII updates, FDA Title 21 food-contact substance notifications, SEC 10-K disclosures from listed specialty chemical producers, and customs trade data tracking citric acid ester shipments. Bottom-up volume builds triangulated against top-down market sizing from regulatory mandate timelines and substitution elasticity estimates.
Segmentation dimensions modeled include product grade tier, end-use application channel, form factor, and regional production hub across the projection horizon. CAGRs were derived from elasticity-adjusted substitution curves and capacity expansion announcements. Forecast inputs incorporated REACH compliance deadline phasing, FDA FCN queue progression rates, and fermentation citric acid capacity buildout in Shandong and Jiangsu provinces.
Decision-makers should treat outputs as directional under assumptions of sustained phthalate regulatory tightening and stable n-butanol feedstock availability; material deviation in crude oil volatility or ECHA SVHC list expansion timing would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Lithium Nitrate Market
Bulk Chemicals
Bromine Market
Bulk Chemicals
Global Cyclopentane Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Global Sodium Phosphate Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
Europe Methyl Acrylate Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
Caprylic Acid Market
Bulk Chemicals
Hydrochloric Acid Electrolysis Market
Bulk Chemicals
Barium Chloride Market
Bulk Chemicals
Potassium Chloride Market