
 Pineapple Juice Market | 2026-2036
Pineapple Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Pineapple Juice Market Intelligence
Single-serve pouch bundling is repositioning household purchasing patterns toward trial-sized variety packs. PepsiCo leverages its bottling network to sustain shelf presence across multiple packaging configurations. The Coca-Cola Company anchors its portfolio through controlled distribution in food service channels. Fresh Del Monte Produce differentiates by competing on integrated plantation-to-retail traceability.
Pineapple juice is the aqueous extract of Ananas comosus fruit, typically containing 10-13% soluble solids measured as Brix, processed through crushing, enzymatic treatment, and either pasteurization or concentration to 60-72 Brix for industrial use. Fresh juice commands premium positioning in health-focused retail while concentrated juice occupies bulk ingredient supply to beverage manufacturers. Carton packaging leads household consumption for ambient stability, though pouches represent the fastest-growing configuration in online retail channels driven by e-commerce logistics efficiency.
The FDA enforces juice hazard analysis and critical control points regulations that shape pasteurization standards for US market access, while the EU Green Deal's sustainable packaging directives are forcing material transitions across European export-bound production. India's FSSAI maintains additive and labeling requirements that govern imported concentrate formulations. Stakeholders must monitor how diverging national packaging waste regulations alter capital allocation between glass, carton, and flexible film lines.
Market Dynamics
Cold-pressed extraction technology is compressing processing margins and forcing legacy thermal pasteurization lines into accelerated obsolescence across Southeast Asian production clusters.
Growth Catalysts
- EU Green Deal Packaging Directives:Material transition mandates are creating first-mover advantages for carton and flexible film producers who certify compostable barrier layers ahead of enforcement deadlines.
- Functional Beverage Formulation:Enzymatically clarified pineapple juice with retained bromelain activity is penetrating sports nutrition and digestive health product pipelines.
- Thailand Export Hub Concentration:Integrated plantation-to-port infrastructure in Rayong and Chonburi provinces is reducing concentrate export logistics costs relative to Indonesian and Philippine alternatives.
Market Restraints
- Input Cost Volatility:Fertilizer price swings tied to natural gas benchmarks directly compress plantation operating margins in Costa Rica and the Philippines.
- Supply Concentration Risk:Over half of global not-from-concentrate capacity sits within 200 kilometers of Bangkok, exposing buyers to single-point climate and labor disruption.
- Substitution Threat:Mango and passionfruit concentrates are displacing pineapple in multi-fruit nectar formulations where cost-per-Brix drives procurement decisions.
Strategic Opportunities
- Vietnam Processing Investment:Underdeveloped enzymatic clarification capacity creates entry points for cold-pressed specialists seeking tariff advantages under EU-Vietnam trade frameworks.
- E-Commerce Pouch Channels:Single-serve flexible packaging is capturing online grocery logistics efficiencies that cartons cannot match for ambient last-mile delivery.
- US FDA Juice HACCP Compliance Services:Third-party audit and certification infrastructure for Southeast Asian exporters remains fragmented, opening advisory and testing revenue streams.
Industry Challenges
- Enzyme Stabilization Expertise Gap:Cold-pressed operations require biochemical process engineers with limited availability in traditional thermal processing labor markets.
- Concentrate-to-NFC Line Conversion:Retooling existing evaporator infrastructure for not-from-concentrate output demands capital commitments that mid-scale cooperatives struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pineapple Juice Market |
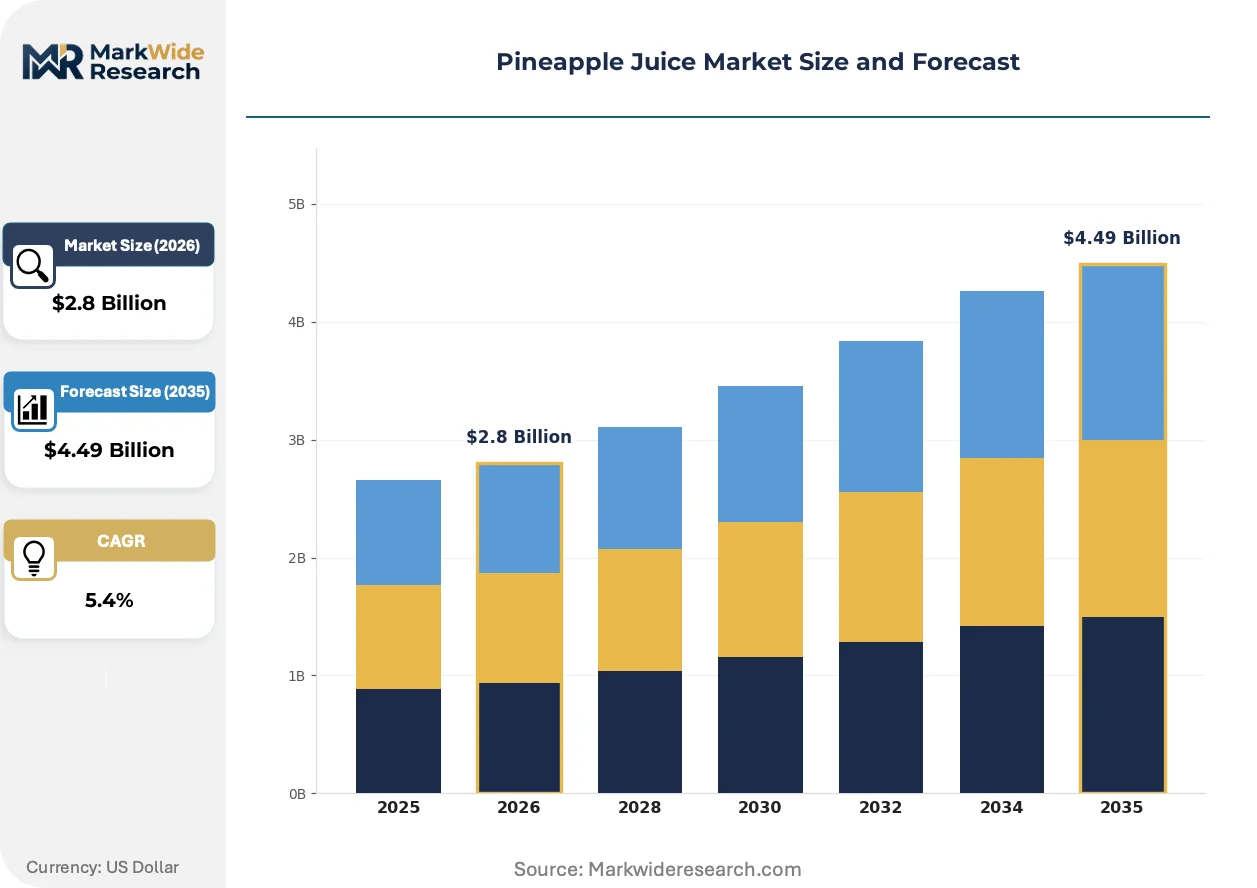
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Concentrated Juice, Fresh Juice, Frozen Juice, Powdered Juice Packaging Type: Bottles, Cartons, Cans, Pouches End User: Household, Food Service, Beverage Industry, Health Sector Distribution Channel: Online Retail, Supermarkets, Speciality Stores, Direct Sales |
| Companies Covered | Keurig Dr Pepper, Kraft Heinz Company, PepsiCo, Pineapple India, Langer Juice Company, The Coca-Cola Company, Ocean Spray, Grace Foods UK Limited, Fresh Del Monte Produce, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pineapple Juice Market Strategic Shifts & Innovations
Processing technology and packaging material science are converging to redefine shelf-stable juice economics, with sustainability compliance emerging as the primary axis of competitive differentiation.
High-pressure processing is overtaking thermal pasteurization in premium not-from-concentrate segments. European and North American private-label retailers are specifying HPP-treated pineapple juice for refrigerated distribution networks. This shift is compressing the viable shelf-life gap between ambient concentrate and chilled fresh alternatives, forcing thermal processors to reposition toward ingredient supply or exit retail-facing channels entirely.
REACH-compliant barrier coatings are mandating material transitions across EU-bound export production. Recyclable mono-material flexible pouches with plasma-deposited silicon oxide layers are replacing aluminum-laminate structures. Thai and Indonesian converters are accelerating certification timelines to maintain access to German and Dutch retail procurement frameworks before 2027 enforcement windows.
Direct-to-manufacturer concentrate procurement is consolidating purchasing power among multinational beverage formulators. Traditional trader intermediaries in Rotterdam and Singapore are losing volume to plantation-direct contracts with integrated quality laboratories. This disintermediation is most visible in Coca-Cola and PepsiCo supply chains, where blockchain-tracked Brix certificates are replacing documentary letters of credit as settlement instruments.
Pineapple Juice Market Segmentation
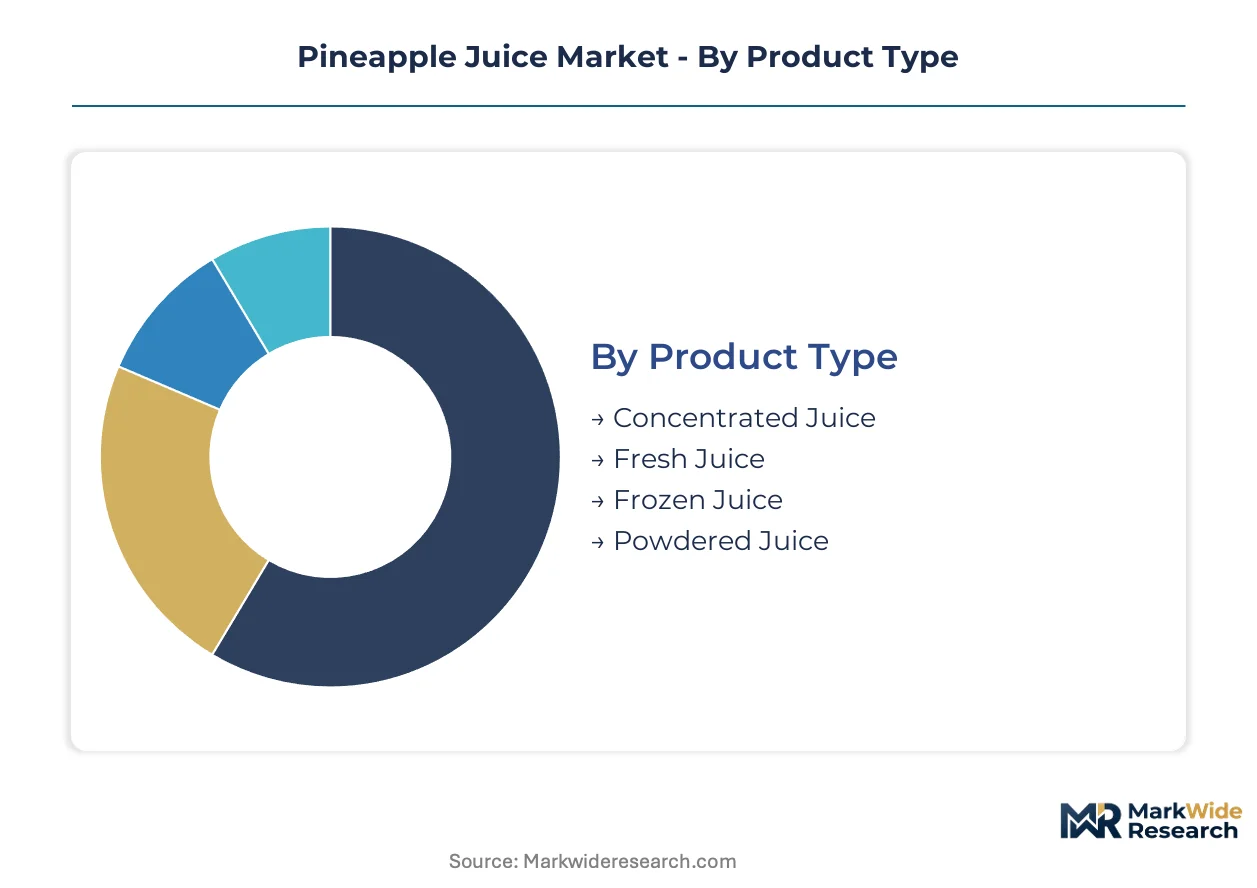
Pineapple juice segmentation reflects divergent capital requirements across processing technologies and packaging formats. Investment intensity varies sharply between thermal concentration infrastructure and cold-pressed not-from-concentrate lines.
Product Type:
Capital intensity peaks in enzymatic clarification and high-pressure processing equipment for premium not-from-concentrate output.
- Concentrated Juice:Evaporator infrastructure dominates processing economics, with 60-72 Brix output serving industrial beverage formulators. Thai and Indonesian processors in Rayong and Chonburi provinces concentrate capacity here due to established port logistics for bulk export.
- Fresh Juice:High-pressure processing lines demand the steepest upfront investment per liter of capacity. North American and European retailers specify HPP-treated product for refrigerated distribution, compressing shelf-life gaps with ambient alternatives.
- Frozen Juice:Blast freezing and cold-chain infrastructure lock working capital in inventory cycles. Demand concentrates in food service channels requiring extended storage flexibility.
- Powdered Juice:Spray-drying towers and encapsulation technology serve niche sports nutrition applications. Lower moisture content reduces freight costs for distant markets.
Concentrated juice absorbs the bulk of installed capacity; fresh juice is expanding most quickly.
Packaging Type:
Cost tier stratification separates premium barrier technologies from commodity formats in procurement frameworks.
- Cartons:Aseptic filling lines and multi-layer board lamination anchor household consumption for ambient stability. EU Green Deal packaging directives are accelerating transitions toward certified recyclable structures.
- Pouches:Mono-material flexible film with plasma-deposited silicon oxide layers captures e-commerce logistics efficiencies. Online grocery channels favor single-serve configurations for last-mile delivery optimization.
- Bottles:PET and glass formats serve refrigerated retail placement with established consumer familiarity. Higher unit weights disadvantage long-distance export.
- Cans:Aluminum beverage can lines require scale thresholds that favor multinational bottling networks. Food service fountain systems drive concentrated demand.
Cartons retain the largest installed base; pouches are climbing the fastest.
End User:
Application-driven specification intensity separates pharmaceutical-grade bromelain retention from commodity ingredient supply.
- Beverage Industry:Enzymatically clarified concentrate with controlled bromelain activity supplies multi-fruit nectar and functional drink pipelines. Procurement concentrates among Coca-Cola and PepsiCo formulators with direct plantation contracts.
- Health Sector:Pharmaceutical-grade extraction demands laboratory-certified bromelain potency for digestive enzyme supplements. FDA Juice HACCP compliance shapes supplier qualification.
- Household:Retail-facing not-from-concentrate and reconstituted products serve daily consumption patterns. Packaging convenience drives trial-sized variety pack adoption.
- Food Service:Bulk concentrate and frozen formats supply fountain systems and institutional kitchens. Cost-per-Brix procurement dominates multi-fruit blend decisions.
The beverage industry commands the largest volume commitment; the health sector shows the steepest expansion trajectory.
Distribution Channel:
Customer type fragmentation separates direct manufacturer procurement from layered retail intermediation.
- Supermarkets:Ambient carton placement and refrigerated fresh juice facings require slotting fee negotiations with consolidated retail buyers. Thai exporters prioritize German and Dutch retail procurement frameworks.
- Online Retail:Flexible pouch configurations optimize parcel logistics and reduce damage rates in ambient last-mile delivery. E-commerce grocery platforms favor single-serve bundling for trial conversion.
- Speciality Stores:Organic and cold-pressed positioning commands premium shelf placement with traceability certification requirements. Fresh Del Monte's integrated plantation-to-retail model targets this channel.
- Direct Sales:Plantation-direct concentrate contracts displace traditional Rotterdam and Singapore trader intermediaries. Blockchain-tracked Brix certificates replace documentary letters of credit in Coca-Cola and PepsiCo supply chains.
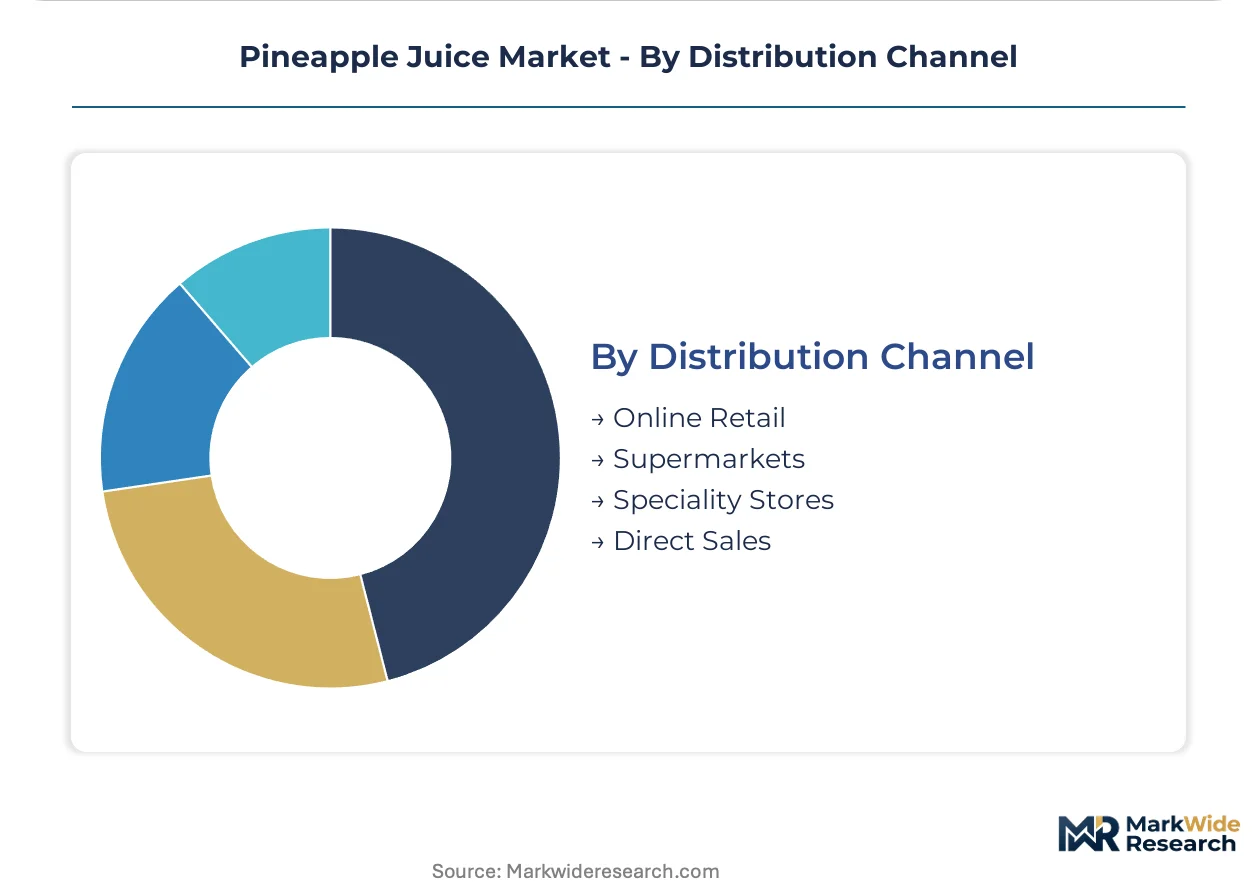
Supermarkets retain the deepest volume footprint; online retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand processes the majority of global export-grade concentrate while the United States and Germany absorb the highest per-capita consumption of premium not-from-concentrate formats. This production-consumption divide shapes logistics infrastructure, regulatory compliance requirements, and packaging specification intensity across originating and destination markets.
Thailand
Rayong and Chonburi provinces host integrated plantation-to-port infrastructure that reduces concentrate export logistics costs. The Thai FDA enforces additive and labeling standards that govern both domestic retail and re-export formulations. Cold-pressed extraction lines are displacing legacy thermal pasteurization capacity in eastern seaboard processing clusters.
United States
Refrigerated distribution networks for high-pressure processed juice command premium shelf placement in consolidated retail channels. FDA Juice HACCP regulations mandate pasteurization standards that shape supplier qualification for Southeast Asian exporters. Florida's diminishing processing footprint redirects import dependence toward Thai and Costa Rican concentrate supply.
Germany
EU Green Deal packaging directives accelerate transitions toward certified recyclable carton and flexible film structures. EFSA and REACH compliance frameworks govern barrier coating specifications for ambient retail placement. Hamburg and Rotterdam serve as consolidation points for plantation-direct concentrate contracts displacing traditional trader intermediaries.
India
FSSAI maintains additive and labeling requirements that govern imported concentrate formulations for reconstituted retail products. Domestic pineapple cultivation in Karnataka and Tamil Nadu supplies raw material to emerging enzymatic clarification capacity. Cold-chain infrastructure gaps constrain not-from-concentrate penetration outside major metropolitan distribution networks.
Indonesia
Plantation expansion in Sumatra and Sulawesi challenges Thai concentrate export dominance through proximity to Chinese and Japanese import demand. The national food and drug regulator enforces halal certification requirements that shape processing line segregation protocols. Surabaya port infrastructure investments aim to replicate Thailand's integrated plantation-to-export logistics model.
Pineapple Juice Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Consolidated beverage formulators leverage bottling networks and direct plantation contracts to compress procurement costs, while mid-scale processors struggle to finance concentrate-to-NFC line conversions. Three archetypes dominate: integrated plantation-to-retail operators, multinational bottling network deployers, and regional cold-pressed specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with blockchain-tracked Brix certificates displacing documentary letters of credit as settlement instruments.
Among North American beverage conglomerates, PepsiCo and The Coca-Cola Company exemplify scale-driven network deployment through controlled distribution across multiple packaging configurations. Fresh Del Monte Produce occupies a position within the integrated plantation-to-retail tier, competing on traceability certification rather than bottling infrastructure scale.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| Kraft Heinz Company |
| PepsiCo |
| Pineapple India |
| Langer Juice Company |
| The Coca-Cola Company |
| Ocean Spray |
| Grace Foods UK Limited |
| Fresh Del Monte Produce |
| Others |
Cost & Logistics Intelligence
EU Green Deal packaging directives gate qualified supply for European export-bound production, restricting premium-tier pricing access to converters who certify compostable barrier layers ahead of enforcement deadlines. Thai and Indonesian processors who lag material transitions face exclusion from German and Dutch retail procurement frameworks, compressing their pricing power in the bloc's highest-value channels.
Pricing Analysis
Margin tightening in ambient concentrate reflects fertilizer price volatility tied to natural gas benchmarks that directly compress plantation operating margins in Costa Rica and the Philippines. Three-tier pricing structure across premium not-from-concentrate, standard reconstituted, and economy multi-fruit blend levels stratifies procurement frameworks, with certification grade and volume scale as primary differentiation drivers. Cost-down pressure on standard-tier product accelerates because mango and passionfruit concentrates displace pineapple in cost-per-Brix-driven formulations. Beverage manufacturers with direct plantation contracts exhibit lowest price sensitivity; mid-scale cooperatives financing concentrate-to-NFC conversions face highest.
Supply Chain Analysis
Return flows of used carton and flexible film packaging for recycling and re-pulping are gaining regulatory weight under extended producer responsibility schemes. Geographic supply concentrates in Thailand, Indonesia, and Costa Rica, with Rayong and Chonburi provinces hosting integrated plantation-to-port infrastructure. Raw material dependencies rest on Ananas comosus fruit supply, enzymatic clarification inputs, and barrier coating chemicals for compliant packaging. Single-point climate and labor disruption within 200 kilometers of Bangkok poses structural supply chain risk. Distribution runs through plantation-direct contracts with multinational beverage formulators, displacing traditional Rotterdam and Singapore trader intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic clarification capacity scarcity props pricing for qualified not-from-concentrate supply, creating a supply-constrained market structure where cold-pressed extraction expertise commands persistent premiums.
For Market Incumbents: Deploy backward integration into captive plantation supply to secure raw material access against Indonesian expansion in Sumatra and Sulawesi. Consolidate enzymatic clarification and high-pressure processing capacity in Rayong and Chonburi provinces to defend margin position against Vietnamese entrants leveraging EU-Vietnam tariff advantages. Channel control through direct manufacturer contracts with blockchain-tracked Brix certificates replaces documentary letters of credit as the dominant settlement instrument. For New Entrants and Emerging Players: Specialty retailers seeking organic and cold-pressed positioning with traceability certification requirements represent the most penetrable buyer archetype. Cold-chain infrastructure gaps in India outside major metropolitan distribution networks create white-space for ambient pouch configurations optimized for e-commerce grocery logistics. A go-to-market angle anchored in plasma-deposited silicon oxide barrier certification captures EU Green Deal compliance premiums ahead of 2027 enforcement windows. For Investors and Strategic Acquirers: Plantation-direct contract volume displacing traditional trader intermediaries is the leading indicator that disintermediation is accelerating across concentrate procurement. Long-term viability over a multi-year window favors integrated plantation-to-retail operators with laboratory-certified bromelain potency and FDA Juice HACCP compliance infrastructure. Acquisition targets should exhibit enzymatic clarification capacity and REACH-compliant barrier coating certification. Practitioners should monitor EU-Vietnam trade framework utilization rates and Thai FDA enforcement patterns for early signals of competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Pressed Capacity Expansion | High-pressure processing lines in Rayong and Chonburi capture premium not-from-concentrate demand from North American retailers. |
| Backward Integration into Plantation Supply | Captive Ananas comosus cultivation in Sumatra reduces exposure to fertilizer price volatility tied to natural gas benchmarks. |
| Sustainability Certification Program | REACH-compliant barrier coating and compostable film certification maintains access to German and Dutch procurement frameworks. |
| Direct-to-Manufacturer Contracting | Blockchain-tracked Brix certificates with Coca-Cola and PepsiCo displace Rotterdam and Singapore trader intermediaries. |
| E-Commerce Pouch Channel Development | Mono-material flexible packaging with plasma-deposited silicon oxide layers optimizes last-mile delivery for online grocery platforms. |
Research Approach
Document review covered customs and trade data, FDA Juice HACCP enforcement records, EU Green Deal packaging directive implementation timelines, and FSSAI additive regulations, complemented by interviews with enzymatic clarification process engineers, plantation operations managers at Thai and Indonesian processing clusters, procurement leads at multinational beverage formulators, and barrier coating certification specialists. Bottom-up capacity modeling across Rayong, Chonburi, Sumatra, and Sulawesi production clusters triangulated against top-down demand estimates from North American and European retail channels.
Historical volume trajectories cross-referenced against panel input from category buyers and supply planners informed analytical framework construction across the analysis window. Segmentation dimensions modeled include product type (concentrated, fresh, frozen, powdered), packaging format (carton, pouch, bottle, can), end-use application (beverage industry, health sector, household, food service), and distribution channel (supermarket, online retail, specialty store, direct sales). CAGRs derived from trend extrapolation with enzyme stabilization expertise gap and concentrate-to-NFC conversion financing constraints as industry-specific forecast inputs.
Revisions become necessary when EU packaging enforcement deadlines accelerate, Thai labor or climate disruption materializes, or substitution thresholds for mango and passionfruit concentrates shift procurement patterns. Forecasts reflect assumptions documented across stakeholder interviews and secondary validation sources. Practitioners should monitor EU-Vietnam trade framework utilization, fertilizer price benchmarks, and cold-pressed line commissioning announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Popping Bobas Market
Beverages
Hot Chocolate Market
Beverages
Premium Bottled Water Market
Beverages
Still Drinks Market
Beverages
Europe Yerba Mate Market
Beverages
Caffeine Mint Market
Beverages
Water Flavor Market
Beverages
Japan Kombucha Market
Beverages
Italy Bottled Water Market
Beverages
South America Dairy Based Beverages Market
Beverages
Italy Probiotic Drinks Market
Beverages
Bangladesh Energy Drinks Market
Beverages
Sarsaparilla Market
Beverages
Fruit Juices and Nectars Market
Beverages
Europe Smoothies Market
Beverages
Botanical Infused Beverages Market