
 Sparkling Water Machine Market | 2026-2036
Sparkling Water Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Sparkling Water Machine Market Insights
China is rewriting production economics for sparkling water machines through expanded manufacturing capacity in Guangdong and Zhejiang provinces. SodaStream leverages its captive CO2 cylinder exchange network to sustain recurring revenue across sixty-plus markets. Aarke anchors premium positioning through stainless-steel construction and design-forward aesthetics that command price premiums in Nordic and North American households. Philips competes on appliance ecosystem integration, embedding its carbonators within broader kitchen automation platforms.
A sparkling water machine is a pressurized beverage appliance that injects food-grade carbon dioxide into potable water via a refillable cylinder system, typically operating at 30-60 psi to achieve effervescence levels comparable to commercial bottled products. The device serves both residential and foodservice sectors seeking to displace pre-packaged carbonated beverages with on-demand, flavor-customizable alternatives. Countertop models dominate household volume due to minimal installation requirements and compact footprints suited to urban kitchens. Commercial-grade under-sink installations capture the strongest margin pools by locking foodservice operators into long-term CO2 supply contracts and maintenance agreements. Portable units represent the fastest-growing structural category as camping and outdoor recreation segments expand addressable occasion-based demand.
EU F-Gas Regulation and REACH compliance frameworks constrain cylinder refrigerant specifications and material composition thresholds for machines sold across member states. FDA oversight in the United States governs food-contact surfaces and CO2 purity standards, while China's SAMR enforces GB standards for electrical safety and pressure vessel integrity in domestic manufacturing. Stakeholders must monitor evolving extended producer responsibility mandates that could impose cylinder recovery obligations and reshape aftermarket economics.
Market Dynamics
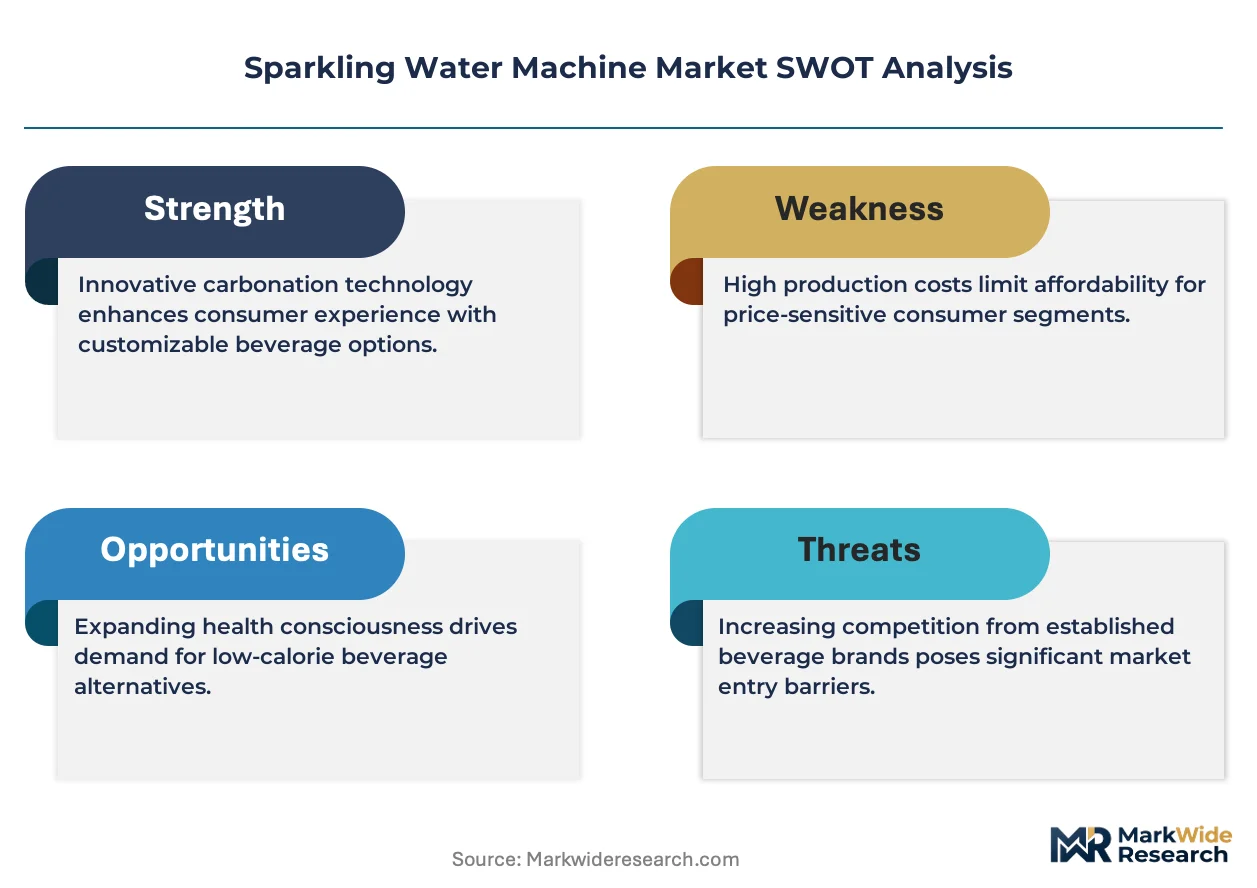
EU F-Gas Regulation compliance costs are compressing margin structures for manufacturers serving member states, forcing cylinder refrigerant redesigns and material substitutions that favor capitalized incumbents over emerging entrants.
Growth Catalysts
- REACH material thresholds:Stricter EU chemical composition rules for food-contact surfaces are accelerating stainless-steel adoption in premium machine construction, locking in higher replacement cycles.
- Outdoor recreation verticals:Camping and portable occasion-based consumption are expanding addressable demand beyond traditional kitchen countertop placement.
- Guangdong manufacturing clusters:Expanded production capacity in southern China is compressing unit economics for entry-level machines and reshaping export pricing floors.
Market Restraints
- Food-grade CO2 supply concentration:Cylinder refill infrastructure remains captive to regional gas distributors, creating geographic access gaps in secondary cities.
- Pressure vessel certification timelines:SAMR GB standards in China and EU pressure equipment directives impose extended validation periods that delay product launches.
- Pre-packaged beverage substitution:Discount private-label sparkling water in German and French retail channels retains price advantage for low-occasion households.
Strategic Opportunities
- Underpenetrated Nordic households:Sweden and Norway exhibit below-average carbonator penetration relative to sustainability consciousness, presenting white-space expansion.
- Smart kitchen convergence:Integration with voice-activated home automation platforms and app-controlled carbonation levels is opening premium positioning.
- Extended producer responsibility mandates:Pending EU cylinder recovery obligations would structurally advantage brands with captive exchange networks.
Industry Challenges
- Cross-border refrigerant compliance:Divergent F-Gas implementation across EU member states fragments product variant requirements and inventory management.
- Aftermarket service unbundling:Third-party CO2 refill providers are eroding manufacturer recurring revenue attachment rates in mature markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sparkling Water Machine Market |
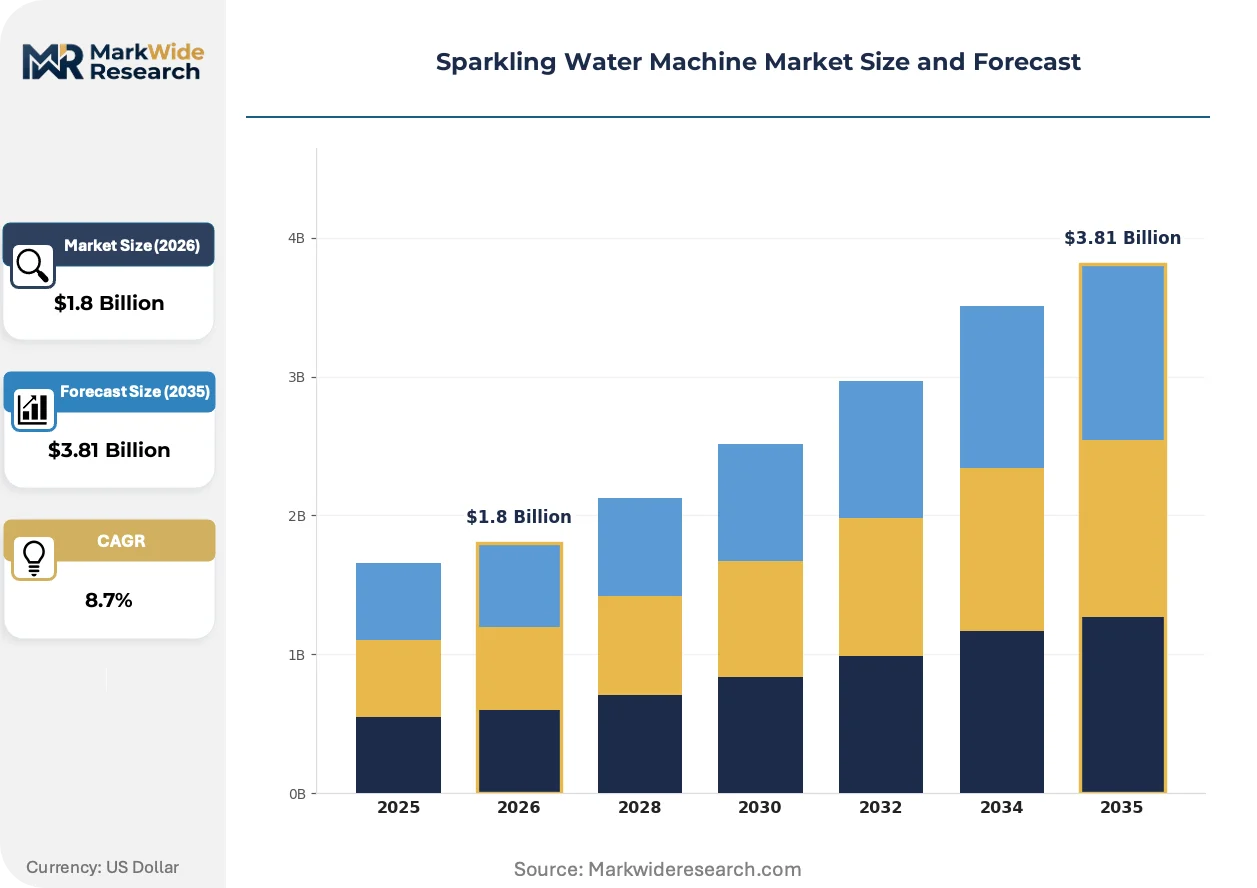
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Portable, Under-Sink, Commercial End User: Households, Restaurants, Cafés, Offices Capacity: 1L, 2L, 3L, 4L Distribution Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Drinkmate, Smeg, SodaStream, Carbonator Pro, ensō, Aarke, Philips, Thirsty, Ninja Kitchen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sparkling Water Machine Market Trends and Innovations
Electromechanical carbonation systems are displacing traditional valve-based architectures, while regulatory pressure on refrigerants and shifting household beverage rituals are compressing product lifecycles and reshaping channel economics.
Precision electronic pressure control is rendering obsolete manual lever-operated carbonation mechanisms. Urban households in Germany and the Netherlands are adopting sensor-calibrated machines at accelerated replacement cycles. This shift is compressing the viable product lifecycle for mechanical valve platforms and elevating R&D spend on firmware development.
EU F-Gas Regulation phase-down schedules are forcing refrigerant transitions in cylinder cooling systems for commercial under-sink installations. Manufacturers serving foodservice operators face retrofit obligations or product line discontinuations. German and Italian commercial channels are responding with extended lease structures that bundle compliance upgrades into service contracts.
Direct-to-consumer cylinder subscription models are capturing household relationships that retail distribution previously controlled. Nordic and North American buyers are shifting from big-box purchase patterns to automated refill scheduling. This channel rotation is most pronounced in urban Canadian and US coastal markets where delivery density supports unit economics.
Sparkling Water Machine Market Segmentation
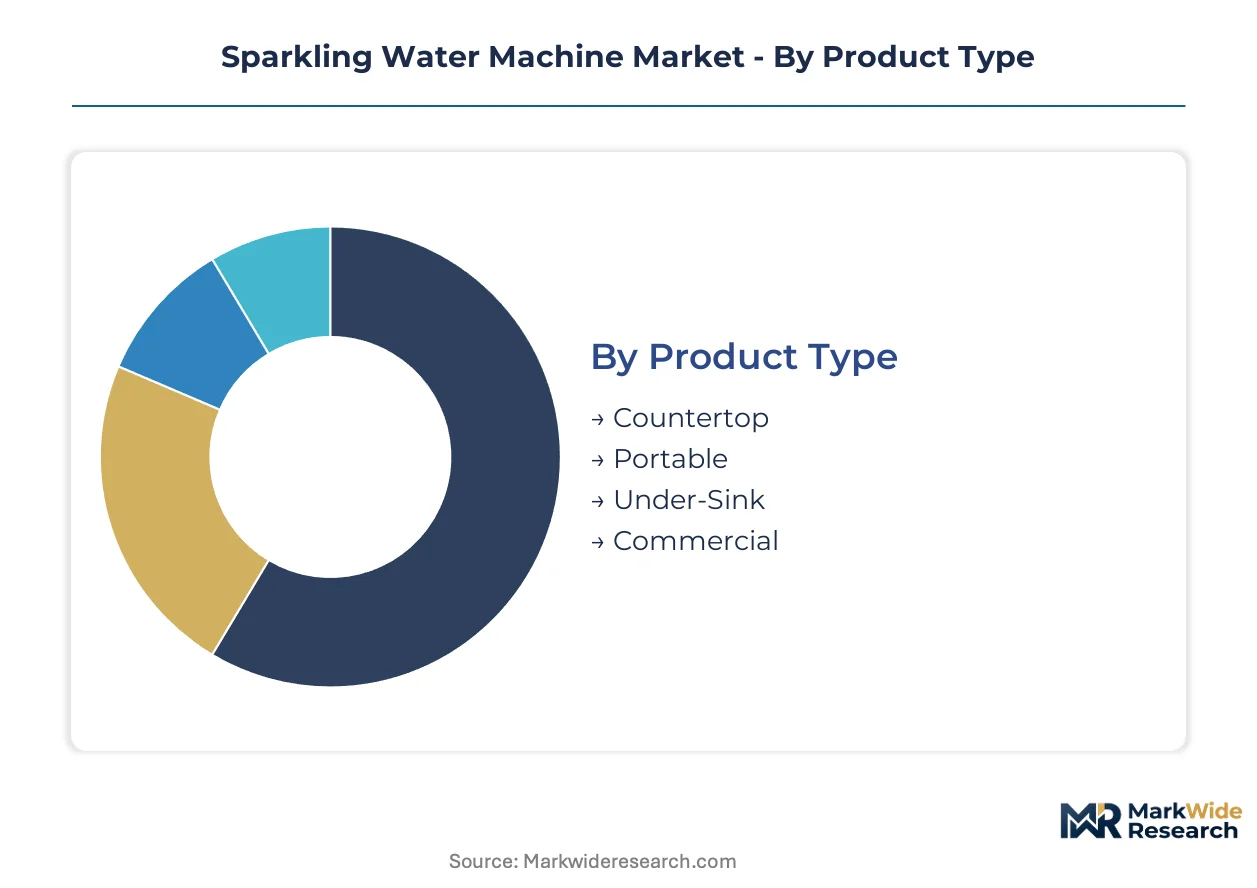
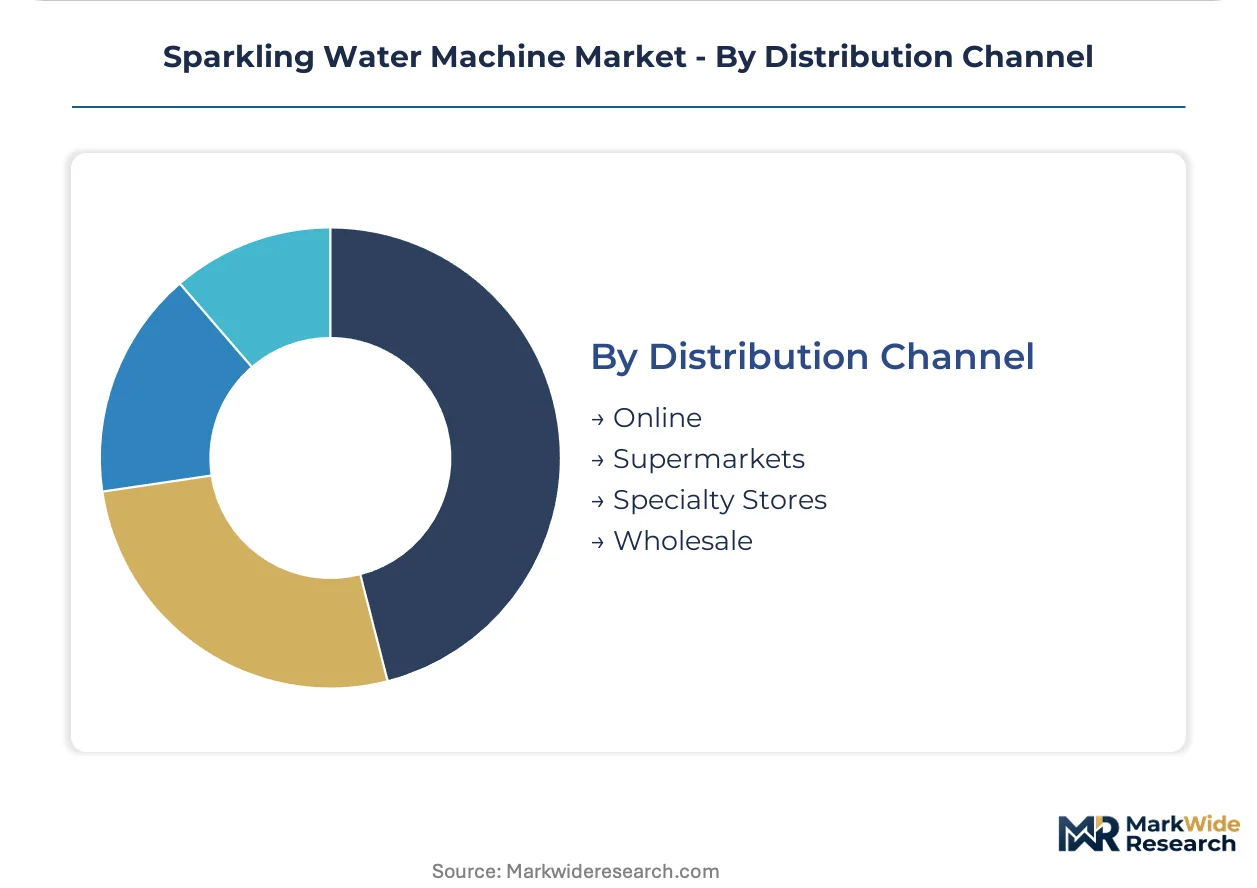
Segmentation in the sparkling water machine market determines recurring revenue attachment rates and cylinder exchange economics. Product type and distribution channel choices lock manufacturers into distinct margin structures and service intensity models.
Product Type:
After-sales-service intensity varies sharply across product architectures, with commercial installations demanding scheduled maintenance contracts and portable units requiring minimal technical support.
- Countertop:Compact pressurized vessels designed for residential kitchen placement, typically integrating 30-60 psi carbonation systems with snap-lock bottle interfaces. German and Dutch urban households drive replacement demand as electromechanical controls displace manual valve mechanisms. By volume, Countertop leads. By growth pace, Portable is ahead.
- Portable:Battery or manual-pressurized units engineered for camping, outdoor recreation, and travel use cases with reduced pressure thresholds. Expanding addressable occasion-based demand in Nordic outdoor recreation markets compresses traditional household placement boundaries.
- Under-Sink:Fixed commercial-grade installations with dedicated CO2 line connections and cooling integration for foodservice operators. Extended lease structures in German and Italian commercial channels bundle compliance upgrades into service contracts.
- Commercial:High-throughput systems serving restaurants, cafés, and institutional foodservice with continuous carbonation capacity and multi-tap dispensing configurations.
Margin concentration pools in Under-Sink and Commercial categories through long-term supply contracts, while Countertop and Portable segments compete on acquisition cost and brand recognition.
End User:
Customer type dictates purchasing authority complexity, with household buyers prioritizing design aesthetics and foodservice procurement emphasizing total cost of ownership and compliance documentation.
- Households:Individual consumers purchasing through retail or direct-to-consumer channels for residential beverage preparation. Sustainability consciousness in German markets accelerates displacement of single-use plastic bottles.
- Restaurants:Full-service dining establishments requiring high-volume carbonation with flavor customization and rapid service integration.
- Cafés:Coffee-focused beverage retailers expanding menu breadth through sparkling water-based refreshment options.
- Offices:Corporate and co-working facilities provisioning employee amenities with centralized or distributed carbonation points.
Procurement centralization distinguishes Restaurants and Offices, where facilities managers negotiate enterprise agreements, from Households and Cafés with fragmented individual purchasing authority.
Capacity:
Volume specifications align with consumption occasion frequency and household composition, directly influencing cylinder exchange cadence and recurring revenue predictability for manufacturers.
- 1L:Single-serve vessels optimized for individual users and limited counter space in compact urban kitchens.
- 2L:Mid-size bottles balancing portability with multi-serve capacity for small households and personal office use.
- 3L:Family-oriented capacity tier capturing multi-person household demand in suburban German and North American markets.
- 4L:Maximum residential capacity reducing cylinder exchange frequency for high-consumption households and small commercial settings.
Capacity selection inversely correlates with exchange frequency, with 4L users generating lower service touchpoints but higher per-transaction cylinder revenue.
Distribution Channel:
Channel structure determines customer relationship ownership, with direct subscription models capturing recurring revenue previously controlled by retail intermediaries.
- Online:Direct-to-consumer platforms and marketplace retailers enabling automated cylinder subscription scheduling and replacement logistics.
- Supermarkets:Mass-market retail chains offering impulse purchase placement and bundled cylinder exchange services at point of sale.
- Specialty Stores:Kitchen appliance and home goods retailers providing demonstration environments and premium brand curation.
- Wholesale:Business-to-business distributors serving foodservice and office procurement with volume pricing and consolidated fulfillment.
Channel migration toward Online subscription models concentrates in urban Canadian and US coastal markets where delivery density supports unit economics, while Supermarkets retain volume leadership in European mass-market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH compliance thresholds are reshaping material specifications for machines sold across Germany, the largest European market for home carbonation systems. Regulatory stringency varies by member state implementation of EU F-Gas phase-down schedules.
Germany
Urban households in Berlin and Munich are accelerating replacement cycles as electromechanical controls displace manual valve mechanisms. The national implementation of EU F-Gas Regulation imposes stricter refrigerant phase-down timelines than minimum Brussels mandates. Manufacturing and R&D activity clusters in North Rhine-Westphalia, where appliance engineering firms are redesigning cylinder cooling systems for commercial under-sink installations.
United States
FDA food-contact surface standards and CO2 purity requirements govern household machine safety, while coastal metropolitan markets drive subscription-based cylinder refill adoption. The EPA maintains secondary oversight of refrigerant emissions in commercial foodservice equipment. Distribution infrastructure concentrates in California and New York metro areas, where direct-to-consumer delivery density supports automated refill scheduling economics.
China
SAMR GB standards for pressure vessel integrity and electrical safety extend product validation timelines for domestic manufacturers and export-bound producers alike. The MIIT promotes dual carbon goals through efficiency mandates on small appliance manufacturing. Production capacity expansion in Guangdong and Zhejiang provinces is compressing unit economics for entry-level machines and resetting export pricing floors.
Sweden
Sustainability consciousness exceeds carbonator penetration rates, creating white-space expansion opportunity in Stockholm and Gothenburg metropolitan households. The Swedish Chemicals Agency enforces REACH compliance with stricter national interpretations than EU baseline requirements. Nordic outdoor recreation demand is absorbing portable unit production from specialized fabricators in southern manufacturing zones.
Netherlands
Sensor-calibrated machines are penetrating Amsterdam and Rotterdam urban kitchens at replacement cycles shorter than mechanical valve platforms. The national regulator aligns with ECHA guidance on food-contact material thresholds, accelerating stainless-steel adoption. Distribution runs through Rotterdam port logistics for re-export to other EU member states.
Sparkling Water Machine Market Competitive Landscape
Capability concentration sits with design-forward premium specialists; scale advantage sits with mass-market platform owners. The market structures around three tiers: stainless-steel premium positioning, ecosystem-integrated appliance platforms, and volume-driven entry-level manufacturing. Two dominant competitive moves are shaping rivalry: captive CO2 cylinder exchange network expansion, and electromechanical carbonation system R&D escalation.
Within the premium-tier vector, Aarke exemplifies design-forward positioning through material differentiation. SodaStream anchors the scale-driven end with established exchange infrastructure across sixty-plus markets. Philips occupies a position within ecosystem-integrated appliance platforms, embedding carbonation within broader kitchen automation architectures. These three represent the strategic archetypes dividing competitive investment priorities.
| Leading Market Players |
|---|
| Drinkmate |
| Smeg |
| SodaStream |
| Carbonator Pro |
| ensō |
| Aarke |
| Philips |
| Thirsty |
| Ninja Kitchen |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in Guangdong manufacturing clusters is pressuring component suppliers to extend payment terms and absorb inventory risk, compressing margins for entry-level machine assemblers while creating pricing leverage for brands with captive cylinder exchange networks.
Pricing Analysis
Price spreads between German and Chinese retail channels exceed those within either market alone, reflecting divergent after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels separates Aarke's stainless-steel positioning from Philips ecosystem bundles and white-label Guangdong production. Cost compression in entry-tier machines is intensifying because Zhejiang capacity additions outpace demand absorption. Household buyers in Nordic markets exhibit lowest price sensitivity due to sustainability premiums, while German mass-market shoppers gravitate toward private-label substitutes.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for cylinder valve suppliers serving under-sink commercial installations, straining working capital for smaller fabricators. Manufacturing concentrates in China, Italy, and Germany, with precision electromechanical components sourcing from Taiwan and South Korea. Food-grade CO2 cylinder production rests on aluminum extrusion and specialized sealing polymer inputs. Single-source vulnerability runs through regional gas distributor networks for cylinder refill logistics. Distribution runs through Rotterdam port consolidation for EU re-export and direct-to-consumer subscription platforms in North American coastal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where cylinder subscription revenue expands faster than hardware replacement cycles, rewarding manufacturers who capture recurring household relationships before retail intermediaries.
For Market Incumbents: Insulate recurring revenue streams by tightening cylinder exchange exclusivity clauses in retail partnerships, countering third-party refill providers eroding attachment rates. Deepen backward integration into CO2 cylinder production to secure supply continuity against regional gas distributor consolidation.
For New Entrants and Emerging Players: Build out portable unit distribution through Nordic outdoor recreation specialty retailers, where sustainability consciousness exceeds carbonator penetration and occasion-based demand remains underdeveloped. Anchor go-to-market strategy around camping and travel use cases that sidestep incumbent kitchen countertop dominance.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across electromechanical carbonation system development, favoring acquisition targets with proven firmware capabilities and sensor calibration IP. Prioritize brands with established direct-to-consumer subscription infrastructure over hardware-only manufacturers. Monitor EU extended producer responsibility mandate progression as signal for cylinder recovery obligation economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Cylinder Exchange Network Expansion | Captures recurring revenue streams that retail distribution previously controlled in German and North American households. |
| Electromechanical System R&D Escalation | Compresses product lifecycles for manual valve platforms and elevates firmware development spend requirements. |
| Stainless-Steel Premium Positioning | Locks in higher replacement cycles through REACH-compliant material differentiation in EU member states. |
| Direct-to-Consumer Subscription Launch | Concentrates customer relationship ownership in urban Canadian and US coastal markets with delivery density. |
| Commercial Under-Sink Lease Restructuring | Bundles F-Gas compliance upgrades into service contracts for German and Italian foodservice operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, appliance retail audit records, and regulatory filing databases. Conversations with product managers at carbonation equipment manufacturers, procurement leads at CO2 gas distributors, kitchen appliance category buyers, and aftermarket service heads informed demand-side assumptions. Top-down market sizing triangulated against bottom-up unit shipment analysis across product type and capacity tiers.
Forecast inputs span electromechanical replacement cycle compression, EU F-Gas phase-down implementation variance, and outdoor recreation participation trends. Segmentation modeling covers product architecture, end-user procurement authority, capacity specification, and channel structure across the analysis window. CAGRs derive from regression against historical penetration rates and elasticity-adjusted price trajectory assumptions.
Sensitivities concentrate around cylinder refill infrastructure expansion pace and REACH material threshold enforcement stringency. Forecasts embed documented assumptions regarding household sustainability premium persistence and commercial lease contract renewal rates. Macroeconomic contraction, regulatory timeline acceleration, or electromechanical system reliability breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Bottled Water Processing Market
Beverages
South America Energy Drink Market
Beverages
Europe Animal-Based Food and Beverage Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Juice Concentrates Market
Beverages
Canned Beverages Market
Beverages
Ready to Drink Shakes Market
Beverages
Sports Drink Market
Beverages
Saudi Arabia Bottled Water Market
Beverages
Fruit Water Market
Beverages
Spring Water Market
Beverages
Morocco Bottled Water Market
Beverages
CBD-Infused Beverages Market
Beverages
Aloe Vera Juice Market
Beverages
Coconut Water Market
Beverages
Sarsaparilla Market