
 Road Snow Melt Market | 2026-2036
Road Snow Melt Market Size, Share, and Industry Trends Forecast 2026-2036
Road Snow Melt Market Insights
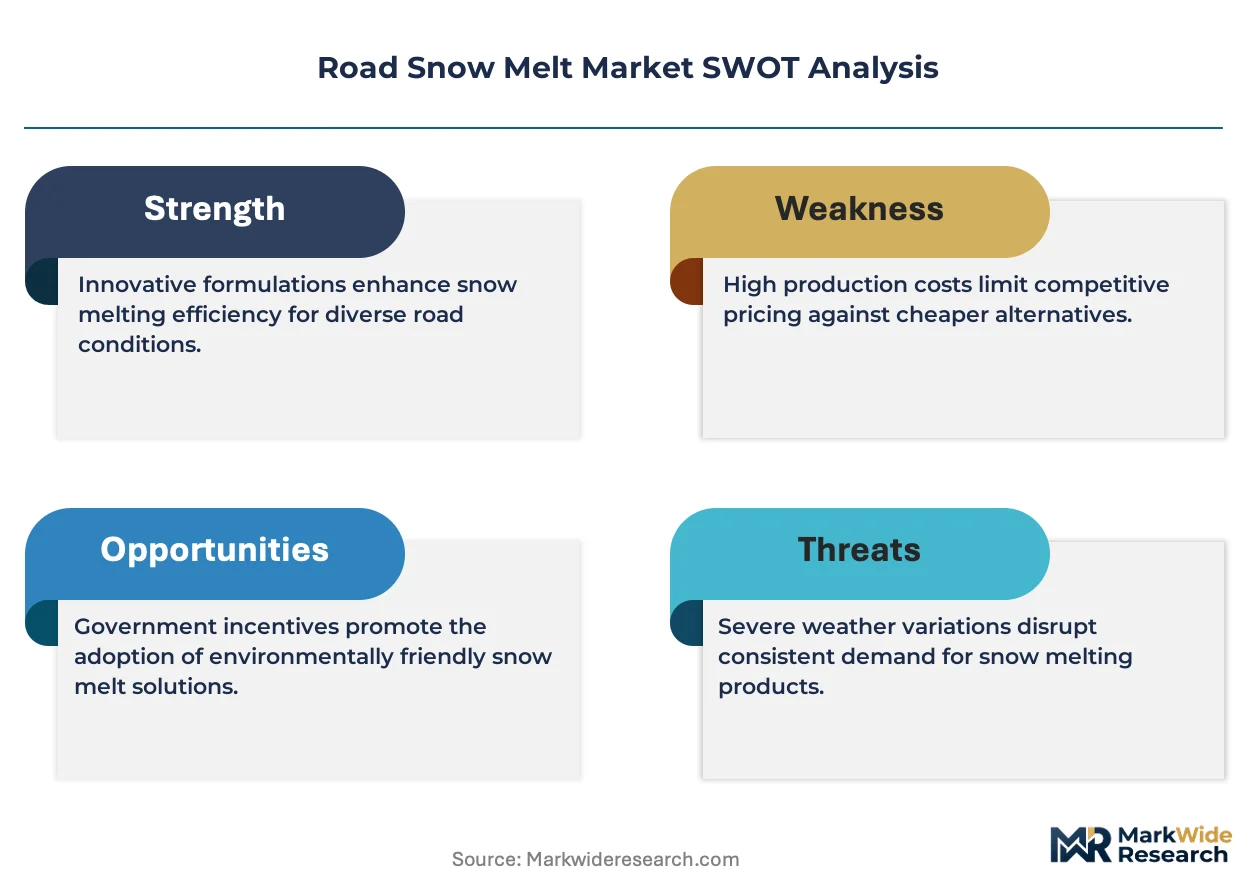
Canada is reshaping competitive dynamics through expanded hydronic system deployments across provincial highway networks. Thermon Group Holdings leverages its vertical integration in heating cable manufacturing to sustain pricing power in electric snow melt segments. Danfoss A/S anchors its position through advanced hydronic controls engineered for sub-zero operational reliability. Watts Water Technologies competes aggressively in the municipal procurement channel with specialized pumping and mixing solutions.
Road snow melt encompasses engineered surface heating systems that maintain pavement temperatures above freezing through embedded electric resistance elements, circulated glycol-water mixtures, or radiant energy transfer, typically operating at 30-50 watts per square foot for electric systems and 100-150 BTU per hour per square foot for hydronic configurations. These installations eliminate manual snow removal, reduce chemical de-icer consumption, and extend infrastructure service life in climates exceeding 30 annual freeze-thaw cycles. Electric Heating Cables dominate current installed value due to lower upfront capital requirements and simpler retrofit feasibility, while Hydronic Systems capture premium margin pools in large-format applications such as airport aprons and bridge decks where centralized boiler plants achieve operational economies. Bridge Decks represent the fastest-growing application segment as structural engineers prioritize chloride-free preservation strategies that protect reinforcing steel from corrosion-induced spalling.
The US Department of Transportation enforces Buy America domestic content standards for federally assisted surface transportation projects, compelling contractors to source qualifying heating cable assemblies from certified domestic producers. Canada's National Research Council publishes performance criteria for heated pavement systems under its highway infrastructure guidelines, while provincial building codes in Ontario and Quebec mandate specific energy efficiency thresholds for snow melt installations. Stakeholders must monitor evolving federal infrastructure appropriations and provincial climate adaptation budgets to anticipate procurement cycles and qualification requirements.
Market Dynamics
Bridge deck preservation mandates are forcing chloride-free heating system retrofits across North American transportation networks. Provincial agencies in Canada and state DOTs in the US are prioritizing embedded hydronic and electric systems to eliminate structural corrosion from road salt exposure.
Growth Catalysts
- Infrastructure Investment and Jobs Act (US):Federal surface transportation appropriations mandate Buy America compliance for heating cable assemblies, directing procurement toward domestic manufacturing facilities.
- Freeze-thaw cycle intensity:Climatic zones exceeding 30 annual freeze-thaw events generate sustained replacement demand for damaged pavement infrastructure across Ontario, Quebec, and northern US states.
- Airport apron expansion:North American aviation authorities are specifying centralized boiler plants for hydronic snow melt across de-icing pads and taxiway intersections to achieve operational economies.
Market Restraints
- Copper and polymer input volatility:Electric resistance cable production faces margin compression from commodity price swings in conductive metals and high-temperature insulation compounds.
- Specialized contractor scarcity:Qualified installation firms capable of embedding heating elements in structural concrete concentrate in limited metropolitan markets, creating regional bottlenecks.
- Natural gas dependency:Hydronic system operational economics remain tethered to fossil fuel pricing, exposing municipal operators to energy cost fluctuations in boiler-dependent configurations.
Strategic Opportunities
- Geothermal integration:Ground-source heat pump convergence with hydronic snow melt loops offers zero-emission operational pathways for sustainability-focused transportation agencies.
- Smart grid synchronization:Demand-response electric cable systems capable of load-shifting during peak grid events unlock utility incentive programs and reduced rate tariffs.
- Provincial climate adaptation budgets:Quebec's infrastructure resilience allocations specifically target heated bridge deck retrofits as priority projects within multi-year capital plans.
Industry Challenges
- Thermal engineering specialization:System designers must balance wattage density, snow load calculations, and structural load requirements across varying pavement substrates and traffic classifications.
- Buy America certification timelines:Component manufacturers face extended qualification periods to document domestic content percentages for federally funded project eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Road Snow Melt Market |
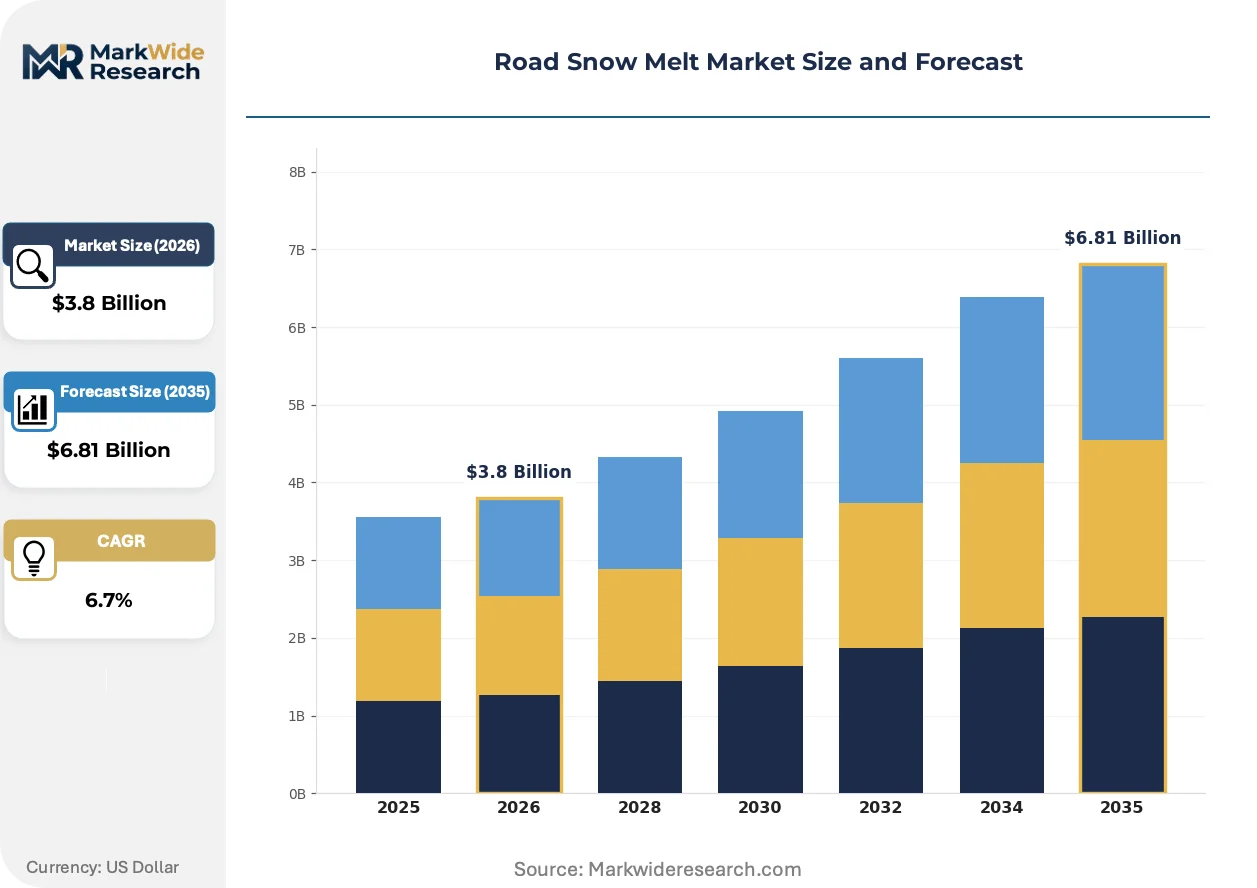
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Heating Cables, Hydronic Systems, Infrared Panels, Hot Water Pipes, Steam Pipes, Thermal Mats Technology: Inductive Heating, Resistive Heating, Hydronic Heating, Infrared Heating, Thermal Conductive Coatings, Radiant Heat Systems Application: Highways, Urban Roads, Airports, Pedestrian Walkways, Bridge Decks, Parking Lots End User: Municipal Authorities, Transportation Departments, Facility Managers, Airport Operators, Construction Firms, Property Managers |
| Companies Covered | Thermon Group Holdings, Inc., Warmup Plc, Raychem (nVent), Emerson Electric Co., Watts Water Technologies, Inc., Danfoss A/S, Uponor, Rehau Group, Chromalox, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Road Snow Melt Market Trends and Innovations
Digital control architectures are displacing electromechanical thermostats across snow melt installations. Sensor networks, predictive algorithms, and remote monitoring platforms are compressing operational response times while reducing energy waste through condition-based activation.
Self-regulating polymer composite heating elements are virtualizing traditional fixed-resistance cable designs. These materials adjust conductive output based on ambient temperature, eliminating overheating risk and reducing energy consumption. Municipal operators in Minnesota and Wisconsin are specifying these systems for sidewalk and plaza installations. The technology is virtualizing project engineering workflows by simplifying load calculations and reducing specification complexity for consulting engineers.
The US Department of Transportation's Buy America provisions are tightening domestic content thresholds for federally assisted surface transportation projects. Heating cable assemblies must now demonstrate qualifying domestic manufacturing to secure project eligibility. Contractors in Michigan, New York, and Pennsylvania are restructuring supplier relationships to maintain compliance access.
Integrated design-build procurement is consolidating responsibility for snow melt system performance under single-contractor accountability. Transportation agencies are abandoning fragmented bid packages that separated civil, mechanical, and electrical scopes. Ontario's Ministry of Transportation and Colorado DOT have adopted this model for recent bridge deck projects, compressing project timelines and reducing interface disputes between trades.
Road Snow Melt Market Segmentation
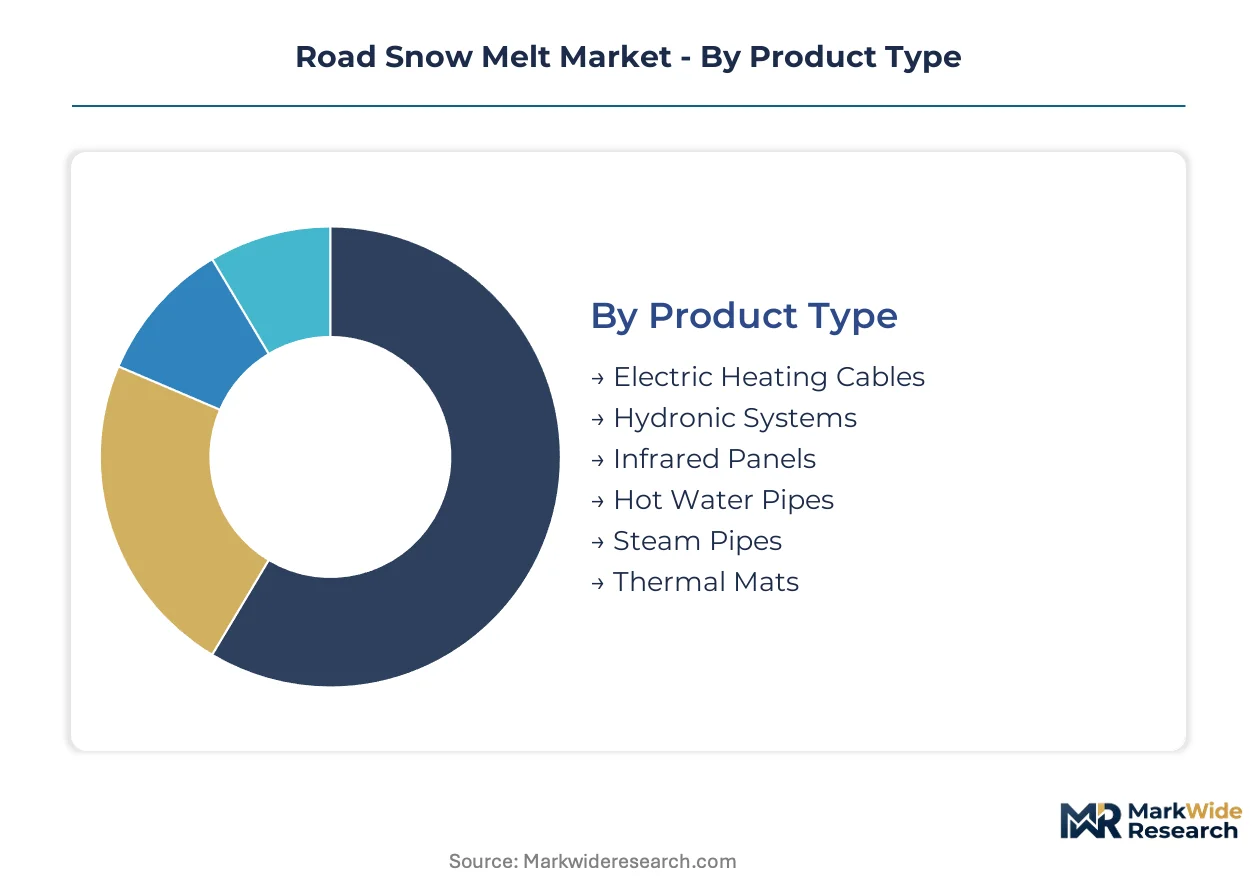
Segmentation in road snow melt reveals distinct procurement cycles and technical requirements across heating technologies and installation contexts. Electric cable retrofits turn over faster than embedded hydronic infrastructure. Application scale dictates whether centralized boiler plants or distributed resistance systems deliver optimal lifecycle economics.
Product Type:
Cycle times vary dramatically — thermal mats and surface-mounted cables retrofit in weeks, while hydronic loops embedded in structural concrete persist for decades.
- Electric Heating Cables:Resistance wire elements sheathed in fluoropolymer or XLPE insulation operate at 30-50 watts per square foot. Demand concentrates in US municipal sidewalk retrofits where Buy America compliance simplifies procurement. Federal infrastructure appropriations accelerate replacement cycles for aging installations.
- Hydronic Systems:Closed-loop glycol-water circuits fed by centralized boiler plants deliver 100-150 BTU per hour per square foot. Ontario and Quebec provincial agencies specify these for bridge deck preservation where chloride-free operation protects reinforcing steel. Capital intensity limits deployments to large-format applications with operational economies.
- Infrared Panels:Radiant ceramic or quartz elements mounted overhead target spot heating for loading docks and transit platforms.
- Hot Water Pipes:District heating network extensions leverage existing thermal infrastructure for snow melt in Nordic municipal networks.
- Steam Pipes:High-pressure condensate systems serve industrial facility perimeters with accessible steam distribution.
- Thermal Mats:Pre-fabricated mesh assemblies reduce field installation labor for commercial parking and walkway projects.
Electric Heating Cables dominate installed base. Hydronic Systems are where expansion concentrates.
Technology:
Cost tiers separate mature resistive and hydronic methods from emerging inductive and coating technologies still seeking scale validation.
- Resistive Heating:Fixed-output mineral-insulated or self-regulating cables constitute the bulk of operational infrastructure. Minnesota and Wisconsin municipal specifications favor polymer composite self-regulating variants for energy efficiency.
- Hydronic Heating:Circulated fluid systems with glycol antifreeze mixtures anchor large-apron airport installations. Denver International and Toronto Pearson centralized plants demonstrate operational reliability at scale.
- Inductive Heating:Electromagnetic field generation through embedded conductive loops remains experimental for roadway deployment.
- Infrared Heating:Electromagnetic radiation transfer suits overhead clearance-constrained environments like parking garage ramps.
- Thermal Conductive Coatings:Nanomaterial-enhanced surface applications promise retrofit without structural modification.
- Radiant Heat Systems:Broad category encompassing both infrared and hydronic radiant distribution architectures.
Resistive Heating commands current procurement volume. Hydronic Heating captures premium project scale.
Application:
Volume scales from pedestrian walkways through highway networks, with bridge decks and airport aprons representing concentrated capital deployment.
- Bridge Decks:Structural concrete heating eliminates chloride-induced reinforcing steel corrosion. Colorado DOT and Ontario Ministry of Transportation mandate embedded systems for new construction and retrofit. Preservation budgets prioritize these installations for lifecycle cost reduction.
- Airports:De-icing pads and taxiway intersections demand continuous operational readiness. Centralized hydronic plants serve multiple zones from single boiler installations. FAA surface transportation guidelines influence specification standards.
- Highways:Longitudinal roadway heating remains rare due to capital cost per lane-mile.
- Urban Roads:Downtown core intersections and transit corridors justify investment in high-visibility locations.
- Pedestrian Walkways:Commercial district and transit station access paths drive municipal sidewalk program specifications.
- Parking Lots:Retail and medical facility operators prioritize liability reduction and accessibility compliance.
Bridge Decks dominate technical innovation. Airports are where expansion concentrates.
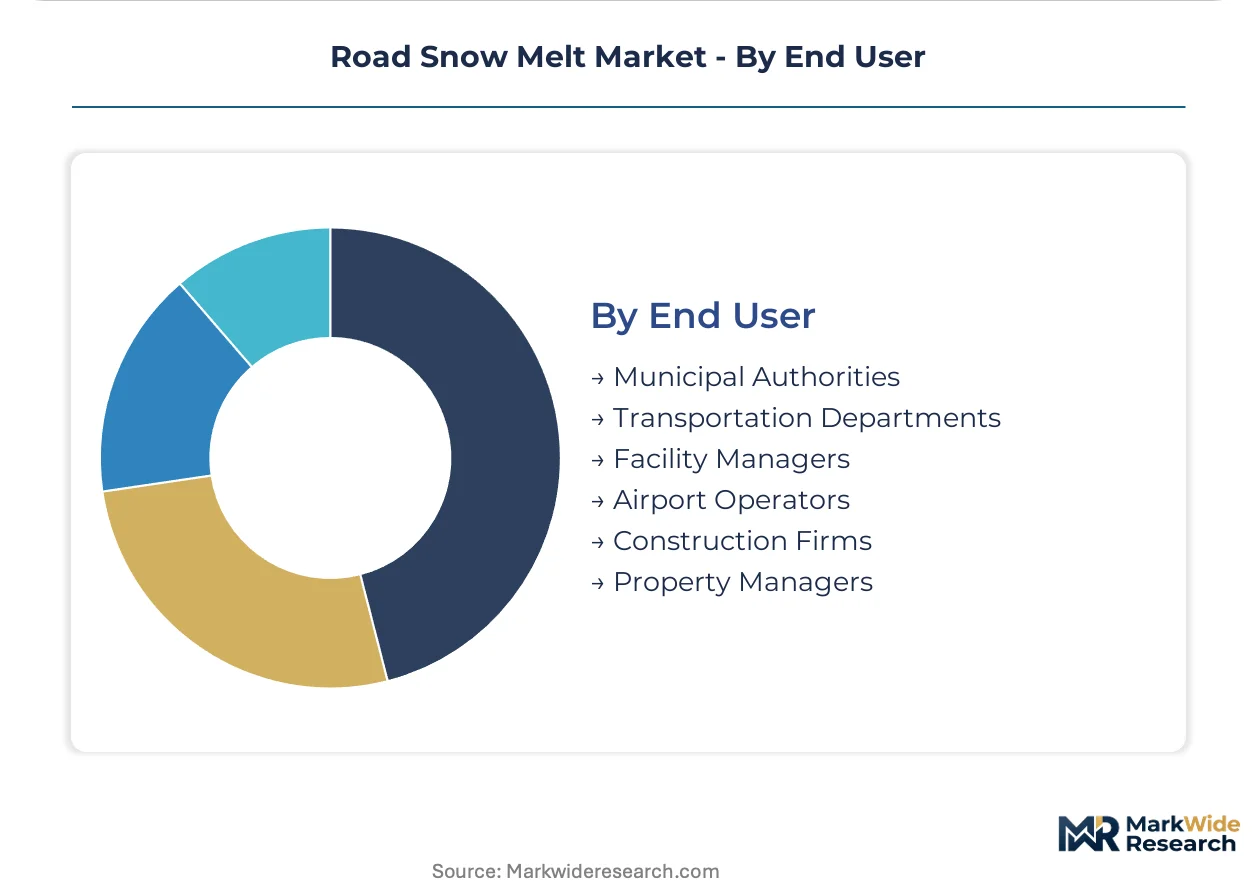
End User:
Customer type determines procurement channel structure — municipal bid processes differ sharply from private facility management or federal aviation authority contracting.
- Transportation Departments:State DOTs and provincial agencies control bridge deck and highway specifications. USDOT Buy America provisions constrain supplier qualification. Multi-year capital programming drives predictable procurement cycles.
- Airport Operators:Authority-managed aviation infrastructure specifies centralized systems for operational reliability. Design-build procurement consolidation reduces interface risk between civil, mechanical, and electrical trades.
- Municipal Authorities:City and county governments manage sidewalk and plaza installations through public works departments.
- Facility Managers:Commercial and institutional property operators prioritize maintenance cost reduction and slip-liability mitigation.
- Construction Firms:General contractors and concrete specialists execute embedded installations as subcontracted scope.
- Property Managers:Retail and residential complex operators specify surface-mounted systems for existing pavement retrofit.
Transportation Departments dominate specification authority. Airport Operators are where design complexity concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Trans-Canada Highway's heated bridge deck retrofits anchor Canada's position as the primary demand center. Federal infrastructure appropriations in the United States direct procurement toward domestic cable assembly manufacturers. Provincial climate adaptation budgets across Ontario and Quebec prioritize chloride-free preservation systems for structural concrete.
United States
FAA surface transportation guidelines influence snow melt specifications at Denver International and Chicago O'Hare. The US Department of Transportation enforces Buy America domestic content standards for federally assisted projects. Michigan DOT and New York State DOT concentrate procurement cycles in the Great Lakes and Northeast corridors where freeze-thaw damage accelerates pavement replacement.
Canada
Ontario's Ministry of Transportation mandates embedded hydronic systems for new bridge construction across the 400-series highways. The National Research Council publishes performance criteria for heated pavement systems under highway infrastructure guidelines. Quebec's infrastructure resilience allocations target heated bridge deck retrofits as priority projects within multi-year capital plans.
Germany
Airport operators at Frankfurt and Munich specify centralized boiler plants for apron de-icing operations. The country's national building energy regulator enforces efficiency thresholds for snow melt installations in commercial developments. Industrial fabricators in Baden-Württemberg supply hydronic control systems for Nordic export markets.
Japan
Tokyo's metropolitan transit authority deploys electric cable systems at elevated station platforms for passenger safety. METI efficiency standards shape procurement specifications for municipal sidewalk programs. Hokkaido's regional airports install localized heating infrastructure to maintain operational continuity during heavy snowfall events.
China
Beijing Capital International Airport expands hydronic infrastructure across new terminal aprons. GB standards for building heating systems incorporate snow melt performance benchmarks for northern province applications. Yangtze River Delta municipalities pilot infrared panel installations at transit hub pedestrian corridors.
Road Snow Melt Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in cable and control manufacturing. Market structure consolidates around heating cable assembly producers with domestic certification access and hydronic system providers with large-project execution capability. Two strategic archetypes dominate: vertically integrated manufacturers with in-house polymer compounding and regional system integrators with design-build contracting expertise. Competitive moves concentrate on qualification for federal procurement programs and consolidation of installation contractor networks.
Among North American heating cable specialists, Thermon Group Holdings and Chromalox occupy positions anchored by domestic manufacturing footprints. Danish hydronic control engineering is represented by Danfoss A/S. These three exemplify the split between electric resistance platform providers and fluid-based system architects competing for transportation authority specifications.
| Leading Market Players |
|---|
| Thermon Group Holdings, Inc. |
| Warmup Plc |
| Raychem (nVent) |
| Emerson Electric Co. |
| Watts Water Technologies, Inc. |
| Danfoss A/S |
| Uponor |
| Rehau Group |
| Chromalox, Inc. |
| Others |
Pricing and Supply Chain Analysis
The Great Lakes freight corridor's volatile fuel surcharge dynamics compress margins for copper-alloy wire shipments from Michigan mills to Ontario contractors, amplifying price differentiation between Buy America-certified domestic cable assemblies and imported hydronic components while pushing municipal procurement officers toward volume-consolidated purchasing agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs procurement, with UL-certified self-regulating cables commanding premiums over mineral-insulated alternatives and unbranded thermal mats occupying the entry tier. Price differentiation rests on certification grade and after-sales engineering support, with DOT-mandated domestic content thresholds adding compliance premiums to federal project bids. Cost compression in the standard tier is intensifying because copper futures volatility and polymer feedstock swings squeeze cable manufacturers. Municipal transportation departments exhibit highest price sensitivity due to fixed capital appropriations, while airport authorities with operational continuity mandates show lowest sensitivity.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard for qualified installation contractors bidding provincial bridge deck projects, with supply-chain finance facilities increasingly offered by cable distributors to preserve liquidity. Manufacturing concentrates in the United States, Canada, and Germany, with conductive polymer compounding anchored in Ohio and Michigan, hydronic boiler production centered in Baden-Württemberg, and control system assembly distributed across Ontario. Raw material dependencies draw from Chilean copper cathode, Gulf Coast petrochemical complexes for fluoropolymer insulation, and Nordic glycol suppliers. Single-source vulnerability around qualified concrete-embedding contractors in Minneapolis, Toronto, and Denver creates regional bottlenecks. Distribution runs through electrical wholesale distributors serving municipal procurement channels and direct-to-contractor relationships for large-format airport projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated transportation departments as Ontario's Ministry of Transportation and Colorado DOT merge electrical, mechanical, and civil scopes under single design-build accountability, fragmenting supplier influence across fragmented contractor networks.
For Market Incumbents: Pre-empt margin erosion from self-regulating polymer composite entrants by securing exclusive supply agreements with the twelve largest municipal concrete-embedding contractors across the Great Lakes corridor. Accelerate backward integration into conductive polymer compounding to offset copper price volatility exposure and defend pricing power in electric cable segments against hydronic system encroachment on bridge deck specifications. For New Entrants and Emerging Players: Build out geothermal-hydronic hybrid system capabilities to capture Quebec's infrastructure resilience allocations targeting zero-emission heated bridge deck retrofits. The pedestrian walkway segment in Minnesota and Wisconsin municipal markets offers lowest certification barriers and fastest specification turnover. Partner with regional electrical distributors already holding municipal procurement relationships to bypass direct DOT qualification timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant heating cable divisions lacking Buy America certification infrastructure. Long-term viability favors specialists with captive polymer compounding and embedded installation contractor networks rather than pure-play component manufacturers. Watch for Ontario and Quebec provincial climate adaptation budget acceleration as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Buy America Certification Investment | USDOT compliance unlocks federal infrastructure appropriations across Michigan, New York, and Pennsylvania DOTs. |
| Geothermal-Hydronic Integration | Ground-source heat pump convergence captures Quebec's zero-emission infrastructure resilience allocations. |
| Self-Regulating Polymer R&D | Temperature-responsive conductive materials reduce energy consumption and simplify consulting engineer specifications. |
| Design-Build Contractor Consolidation | Single-accountability procurement models compress project timelines and reduce interface disputes for Ontario MOT. |
| Smart Grid Synchronization | Demand-response cable systems unlock utility incentive programs and reduced rate tariffs for municipal operators. |
Research Methodology
Operator-level perspectives from DOT specification engineers, airport authority facilities directors, municipal public works procurement officers, and qualified concrete-embedding contractors anchored the qualitative base. Secondary validation drew from USDOT Buy America compliance filings, FAA surface transportation guidelines, Canada's National Research Council highway infrastructure publications, and provincial capital budget disclosures across Ontario and Quebec. Bottom-up installation cost modeling triangulated against top-down infrastructure appropriation tracking.
Scenario-bracketing framed the analytical framework across the analysis window, with volume and value outputs stress-tested against freeze-thaw cycle intensity variations, federal infrastructure appropriation timing, and copper commodity price bands. Segmentation dimensions spanned heating technology type, application scale from pedestrian walkways to airport aprons, end-user procurement channel structure, and regional regulatory cluster. CAGRs derived from installed base replacement cycles, new construction penetration rates, and technology substitution elasticities between electric and hydronic systems.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by European hydronic specialists or accelerated self-regulating cable adoption by municipal specifiers would shift outcomes. Macroeconomic deviation in copper and polymer input markets, regulatory tightening of domestic content thresholds, or breakthrough inductive heating field trials would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Harmonic Gearboxes Market
Automotive Parts
Vehicle Transfer Case Market
Automotive Parts
Thailand Passenger Vehicles Lubricants Market
Automotive Parts
Battery Jump Starters Market
Automotive Parts
Automotive Lifts Market
Automotive Parts
Automotive Transmission Valve Spool Market
Automotive Parts
Australia Automotive Airfilters Market
Automotive Parts
Camshaft Lifters Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Automotive OEM Brake Friction Material Market
Automotive Parts
Global Fuel and Oil Filters Market
Automotive Parts
Automotive Fuel Delivery System Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
Global Intelligent All-Wheel Drive System Market