
 China Biofertilizer Market | 2026-2036
China Biofertilizer Market Size, Share, and Industry Trends Forecast 2026-2036
China Biofertilizer Market Outlook
Soil amendment service revenue is reconfiguring margin pools away from standalone product sales toward integrated crop nutrition programs. Genliduo Bio-Tech Corporation Ltd. leverages its Shandong manufacturing base to dominate nitrogen-fixing inoculant supply for the North China Plain wheat corridor. Kiwa Bio-Tech Products Group Corporation anchors its position through R&D partnerships with provincial agricultural extension stations. CBF China Biofertilizers AG competes on mycorrhizal formulations tailored to orchard replant disease in Shaanxi apple districts.
Biofertilizers are living microbial preparations containing bacteria, fungi, or algae that colonize plant rhizospheres to enhance nutrient availability through biological nitrogen fixation, phosphate solubilization, or phytohormone production, typically formulated with carrier materials such as peat, vermiculite, or liquid broth cultures at minimum viable cell counts exceeding 10^8 CFU per gram. Nitrogen-fixing biofertilizers occupy the largest revenue share due to established Rhizobium and Azotobacter applications on legume and cereal crops across China's major grain belts. Phosphate-solubilizing variants represent the fastest-expanding product category as growers confront declining soil phosphorus use efficiency and rising diammonium phosphate costs. Mycorrhizal products command premium positioning in horticulture and greenhouse segments where root-zone biology directly determines yield quality metrics.
China's Ministry of Agriculture and Rural Affairs enforces GB 20287-2006 microbial fertilizer standards that mandate strain identification, contamination limits, and shelf-life testing for market access. The National Development and Reform Commission channels subsidies through county-level agricultural bureaus to accelerate biofertilizer adoption under carbon-neutrality targets for the cropping sector. NMPA-equivalent oversight of novel genetically modified microbial strains adds regulatory complexity for developers pursuing enhanced nitrogenase activity. Stakeholders must monitor strain patent filings and provincial subsidy quota allocations to anticipate competitive shifts in China's fragmented county-level distribution networks.
Market Dynamics
China's zero-growth chemical fertilizer action plan is compressing demand for synthetic inputs while redirecting procurement budgets toward microbial alternatives, creating a forced substitution dynamic that restructures agricultural input supply chains from county-level distribution upward.
Growth Catalysts
- GB 20287-2006 Standards:The Ministry of Agriculture and Rural Affairs enforces mandatory strain identification and contamination limits that legitimize biofertilizer quality tiers, accelerating farmer trust in certified products.
- Greenhouse Vegetable Belt:Shandong province's intensive protected agriculture generates concentrated demand for mycorrhizal and phosphate-solubilizing formulations that command premium positioning.
- Dual Carbon Goals:Beijing's national carbon-neutrality targets for agriculture channel county-level subsidies toward nitrogen-fixing inoculants that reduce synthetic nitrogen's embodied emissions.
Market Restraints
- Shelf-Life Constraints:Living microbial preparations require cold chain integrity and rapid turnover, limiting inventory holding periods at county distribution nodes.
- Carrier Material Volatility:Peat and vermiculite sourcing faces environmental extraction limits and price instability that compress formulation margins.
- Synthetic Fertilizer Price Anchoring:Diammonium phosphate and urea remain subsidized in grain belts, creating reference price resistance among cost-sensitive cooperative buyers.
Strategic Opportunities
- Heilongjiang Corn-Soy Rotations:Expanding microbial inoculant penetration in Northeast China grain systems offers volume scaling potential as farmers confront soil organic matter decline.
- Orchard Replant Disease:Shaanxi apple districts present specialized demand for mycorrhizal formulations addressing replant syndrome in aging tree stock.
- Agricultural Extension Integration:Provincial extension station partnerships enable technical credibility transfer and farmer demonstration plot networks that reduce adoption friction.
Industry Challenges
- Strain Patent Complexity:Novel genetically modified microbial developments face NMPA-equivalent oversight timelines that extend commercialization cycles.
- County Network Fragmentation:Distribution across thousands of county-level agricultural bureaus demands localized relationship management without national channel consolidation.
- Technical Support Scaling:Living product efficacy depends on application timing and soil conditions, requiring extension labor that strains supplier field service capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Biofertilizer Market |
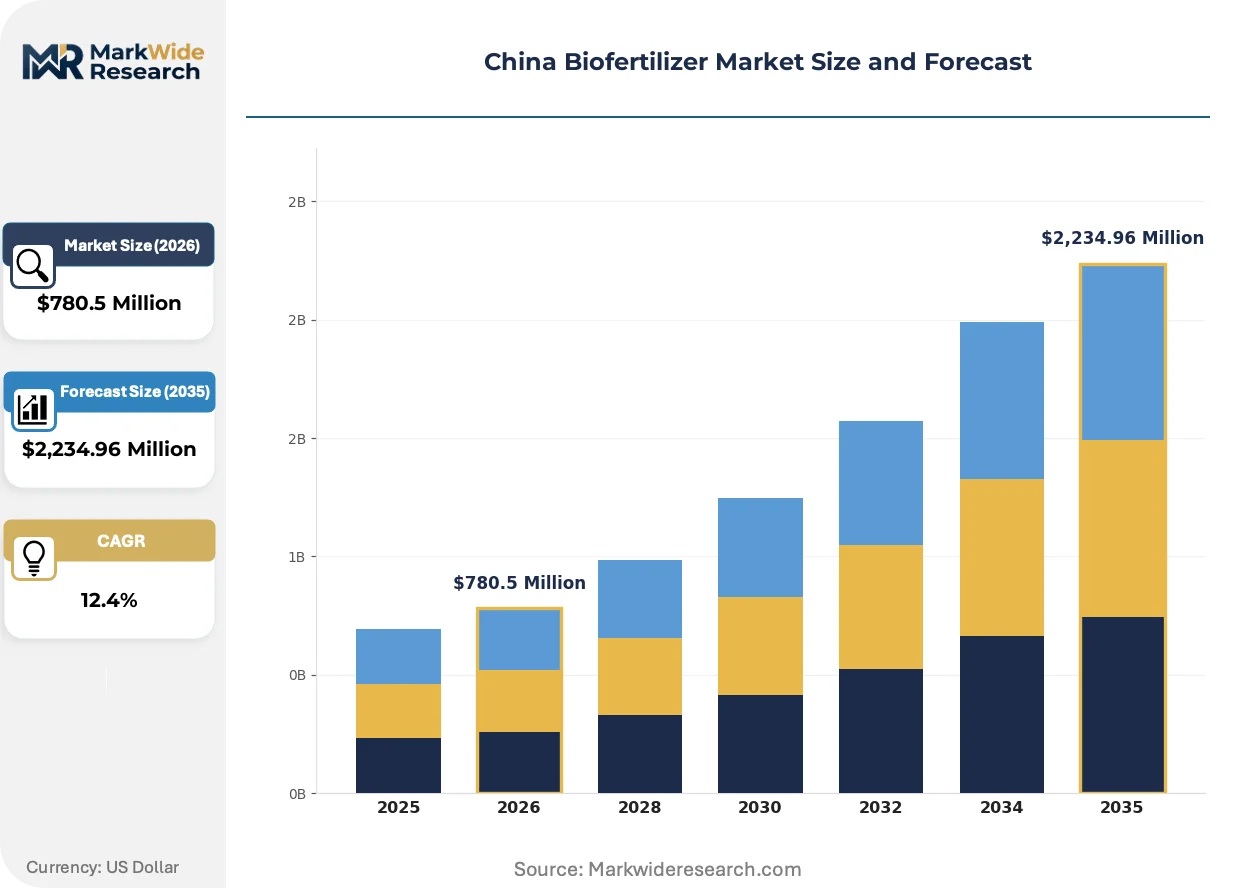
| Market Size in 2026 | $780.5 Million |
| Market Size in 2035 | $2,234.96 Million |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nitrogen-Fixing, Phosphate-Solubilizing, Potassium-Solubilizing, Mycorrhizae Application: Agricultural Land, Horticulture, Organic Farming, Greenhouse End User: Farmers, Agricultural Cooperatives, Garden Centers, Research Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Agricultural Suppliers |
| Companies Covered | Genliduo Bio-Tech Corporation Ltd., Shanxi Haozhida Biotechnology Co., Ltd., Kiwa Bio-Tech Products Group Corporation, Binzhou Jingyang Biology Fertilizer Industry Co., Ltd., Shandong Sukahan Bio-Technology Co., Ltd., Xingtai Sinobest Biotech Co., Ltd., UPL Limited, Lallemand Inc., CBF China Biofertilizers AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Biofertilizer Market Strategic Shifts
Microbial formulation science and digital agriculture tools are converging to transform how Chinese farmers manage rhizosphere biology, shifting from commodity input purchasing toward precision-guided crop nutrition programs.
Liquid broth culture formulations with enhanced cell viability stabilization are virtualizing traditional peat-based carrier systems. Large-scale vegetable cooperatives in Shandong are adopting these shelf-stable alternatives to reduce storage infrastructure requirements. The technology is virtualizing capital allocation patterns away from cold storage investment toward precision application equipment.
China's Ministry of Agriculture and Rural Affairs is tightening enforcement of contamination limits and minimum viable cell count thresholds under updated GB 20287 interpretations. This regulatory compression is disqualifying substandard domestic suppliers and elevating technical documentation requirements for market access. Provincial agricultural bureaus are responding with preferential subsidy quotas for manufacturers demonstrating full strain traceability.
Cooperative buyers in intensive production zones are consolidating procurement decisions through volume contract negotiations that displace individual farmer purchasing. This buyer concentration is compressing supplier margins while demanding integrated technical service packages. The pattern is most pronounced in Shandong's greenhouse belt where cooperative purchasing power exceeds individual farm scale by orders of magnitude.
China Biofertilizer Market Segmentation
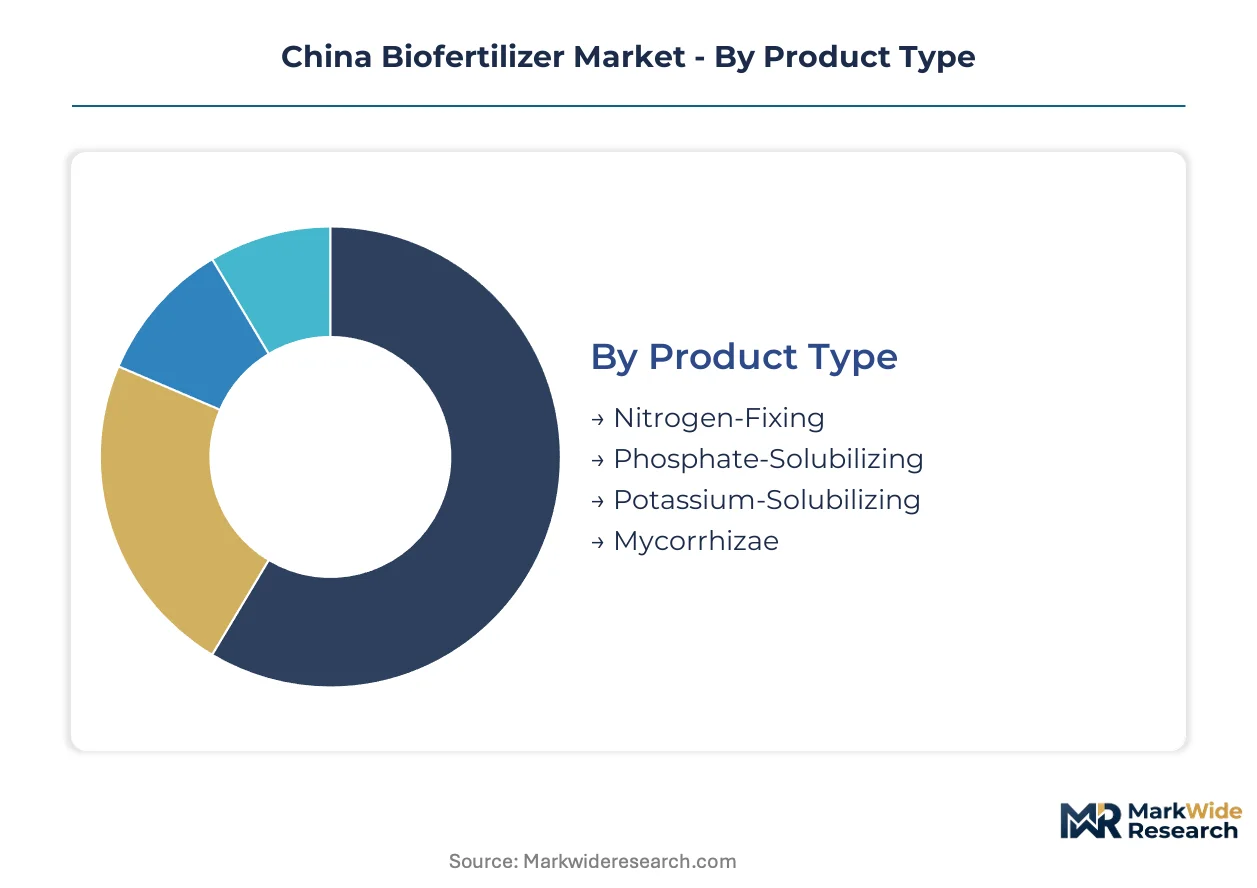
Segmentation in China's biofertilizer market reveals how microbial formulations align with distinct agronomic systems, procurement behaviors, and technical service requirements across the country's fragmented county-level distribution networks.
Product Type:
Microbial functional categories span from nitrogen fixation to symbiotic root colonization, each commanding different price positioning and technical support intensity across China's major cropping belts.
- Nitrogen-Fixing:Rhizobium and Azotobacter preparations colonize legume and cereal root zones to convert atmospheric nitrogen into plant-available ammonium. Heilongjiang corn-soy rotations drive concentrated procurement through provincial extension networks under dual carbon subsidy programs.
- Phosphate-Solubilizing:Bacillus and Pseudomonas strains secrete organic acids that mineralize bound soil phosphorus, addressing declining use efficiency in intensively cultivated North China Plain wheat systems. Shandong greenhouse operators pay premiums for liquid broth formulations that integrate with drip fertigation.
- Potassium-Solubilizing:Silicate-dissolving bacteria release K from feldspar minerals in sandy loam soils prevalent across the Yangtze River Delta vegetable belt.
- Mycorrhizae:Arbuscular and ectomycorrhizal fungi establish extended hyphal networks that expand root absorption surface area, commanding premium positioning in Shaanxi apple orchard replant protocols.
The dominant share belongs to nitrogen-fixing formulations, while phosphate-solubilizing products are gaining share fastest as diammonium phosphate costs climb.
Application:
Application context determines formulation specifications, with protected agriculture demanding shelf-stable liquid cultures and open-field grain systems tolerating peat-based carriers.
- Agricultural Land:Open-field cereal and oilseed production across the North China Plain and Northeast grain belts. County agricultural bureaus channel zero-growth chemical fertilizer substitution subsidies toward microbial inoculants in wheat and maize systems.
- Horticulture:Deciduous fruit orchards and perennial cropping systems where mycorrhizal establishment affects multi-year yield trajectories. Shaanxi apple districts generate specialized demand for replant disease suppression formulations.
- Organic Farming:Certified organic operations under China's national organic standard that prohibit synthetic inputs entirely.
- Greenhouse:Intensive protected vegetable production in Shandong's Weifang and Qingdao clusters where cooperative buyers negotiate volume contracts for precision-applied microbial nutrition.
Agricultural land absorbs the largest volume, though greenhouse applications capture the steepest margin expansion as technical service bundling increases.
End User:
Buyer scale and technical sophistication segment procurement patterns, from individual farmer trial purchases to cooperative volume commitments with embedded extension support.
- Farmers:Individual smallholders operating sub-hectare plots across China's 280,000 villages. Price sensitivity anchors reference points to subsidized synthetic fertilizer benchmarks, slowing adoption without county-level demonstration plot validation.
- Agricultural Cooperatives:Consolidated purchasing entities in Shandong and Heilongjiang that aggregate demand from hundreds of member farms. Cooperative procurement officers negotiate technical service packages alongside product supply, compressing standalone margins.
- Garden Centers:Urban and peri-urban retail outlets serving hobbyist and landscape segments.
- Research Institutions:Provincial agricultural academies and extension stations conducting strain efficacy trials under Ministry of Agriculture and Rural Affairs protocols.
Agricultural cooperatives command the fastest-growing procurement volume, while individual farmers remain the largest addressable base pending trust-building investments.
Distribution Channel:
Channel structure reflects the last-mile challenge of living product logistics, with cold chain requirements favoring localized distributor networks over centralized e-commerce.
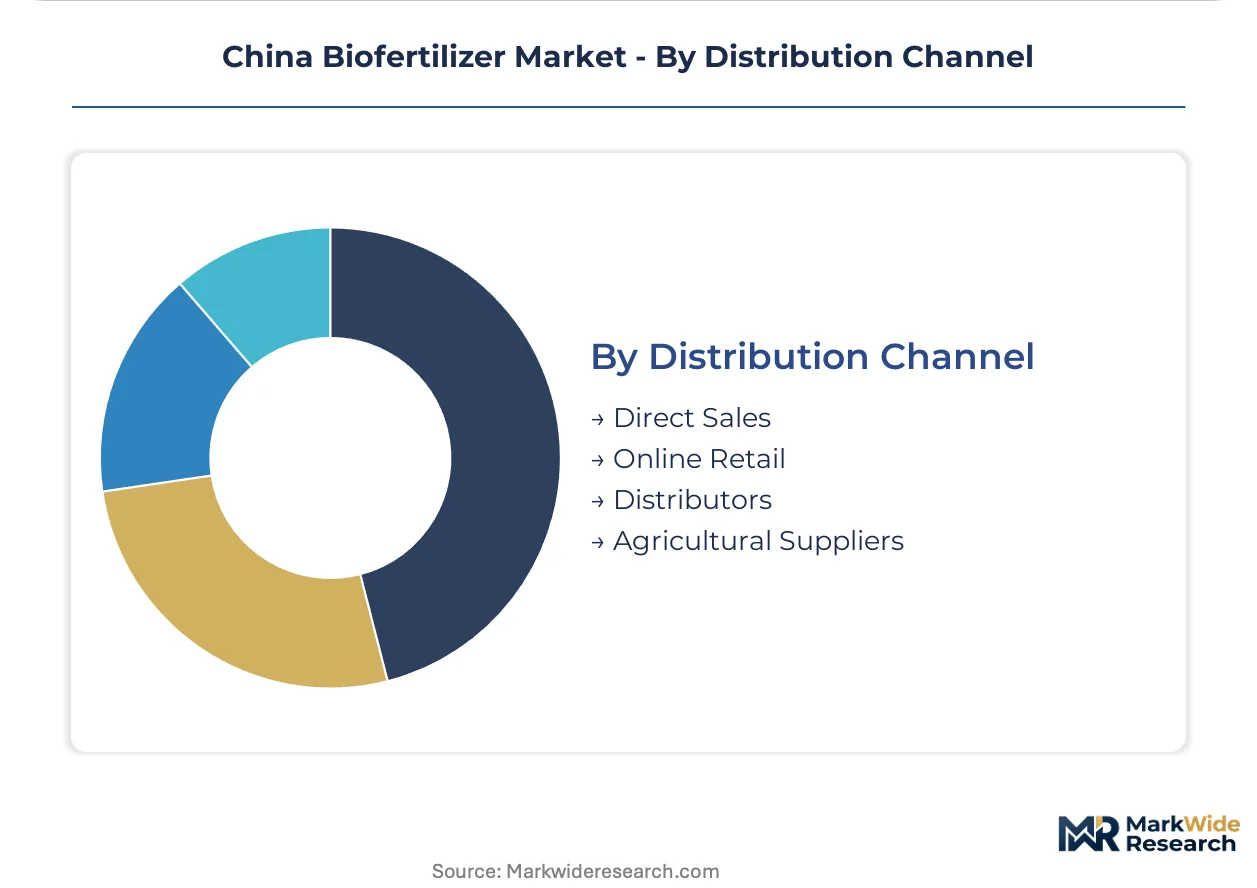
- Direct Sales:Manufacturer field teams contract directly with large cooperatives and state farms. Genliduo Bio-Tech deploys technical agronomists to Shandong greenhouse clusters for application timing guidance.
- Online Retail:E-commerce platforms serving remote counties with limited agricultural supply store penetration. Shelf-life constraints limit category viability to stabilized liquid formulations with extended viability windows.
- Distributors:County-level agricultural supply companies that maintain cold storage and credit relationships with township retailers. Thousands of independent distributors fragment national channel consolidation.
- Agricultural Suppliers:Township-level input stores that combine synthetic fertilizer, seed, and microbial product offerings. Technical advice quality varies sharply by store owner training.
Distributors retain the dominant channel share, while direct sales to cooperatives are climbing fastest as procurement centralization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across China's biofertilizer demand centers. Grain belt cooperatives in Heilongjiang benchmark microbial inoculants against subsidized urea, while Shandong greenhouse operators accept 40-60% premiums for mycorrhizal formulations that integrate with precision fertigation systems.
Shandong Province
Intensive protected vegetable production in Weifang and Qingdao clusters drives concentrated demand for shelf-stable liquid broth cultures. Provincial agricultural bureaus channel GB 20287-2006 compliance subsidies toward manufacturers demonstrating full strain traceability. Cooperative buyers in the greenhouse belt negotiate volume contracts that bundle technical service with product supply, compressing standalone margins while accelerating adoption.
Heilongjiang Province
Corn-soybean rotation systems across the Northeast grain belt generate scaled procurement of nitrogen-fixing Rhizobium and Azotobacter preparations. Dual carbon targets redirect county-level subsidies toward microbial alternatives that reduce synthetic nitrogen's embodied emissions. Demonstration plot networks operated by provincial extension stations validate efficacy for cost-sensitive cooperative members.
Shaanxi Province
Apple orchard replant disease in the Guanzhong Plain creates specialized demand for mycorrhizal formulations addressing soil fatigue in aging tree stock. Orchard consolidation among commercial operators enables premium pricing for multi-year root-zone establishment protocols. Technical service requirements exceed grain system norms due to perennial crop biology complexity.
North China Plain Wheat Corridor
Declining soil phosphorus use efficiency across Henan and Hebei intensive wheat systems accelerates phosphate-solubilizing Bacillus adoption. Zero-growth chemical fertilizer mandates force substitution of diammonium phosphate with microbial alternatives. County agricultural supply companies maintain cold storage infrastructure for peat-based carrier formulations distributed through township retail networks.
China Biofertilizer Market Competitive Environment
Capability concentration sits with specialized microbial strain developers; scale advantage sits with integrated crop nutrition platforms that bundle biofertilizers with synthetic inputs. The market structures around three tiers: national champions with provincial extension partnerships, regional manufacturers serving single crop belts, and foreign technology licensors targeting horticulture premiums. Competitive moves center on agricultural extension integration and liquid formulation capacity expansion.
Within the national champion tier, Genliduo Bio-Tech Corporation Ltd. and Kiwa Bio-Tech Products Group Corporation occupy positions defined by manufacturing base geography and R&D partnership density. CBF China Biofertilizers AG exemplifies the specialized technology licensor archetype. Shanxi Haozhida Biotechnology Co., Ltd. and Shandong Sukahan Bio-Technology Co., Ltd. represent regional fabricators anchored to provincial agricultural bureaus. These entities collectively illustrate how market position derives from proximity to subsidy allocation channels and extension station credibility transfer.
| Leading Market Players |
|---|
| Genliduo Bio-Tech Corporation Ltd. |
| Shanxi Haozhida Biotechnology Co., Ltd. |
| Kiwa Bio-Tech Products Group Corporation |
| Binzhou Jingyang Biology Fertilizer Industry Co., Ltd. |
| Shandong Sukahan Bio-Technology Co., Ltd. |
| Xingtai Sinobest Biotech Co., Ltd. |
| UPL Limited |
| Lallemand Inc. |
| CBF China Biofertilizers AG |
| Others |
Value Chain & Pricing Dynamics
Carrier material volatility in peat and vermiculite extraction determines both the spread between liquid broth and peat-based formulation tiers and the geographic clustering of manufacturing capacity around Shandong and Heilongjiang processing hubs.
Pricing Analysis
After-sales technical service revenue from application timing guidance and soil condition diagnostics drives lifetime value per cooperative account. Three-tier pricing structure across premium mycorrhizal formulations, standard nitrogen-fixing inoculants, and economy peat-based carriers reflects GB 20287-2006 certification grade and strain traceability documentation depth. Cost compression in the economy tier is intensifying because county agricultural bureaus are consolidating procurement toward liquid formulations with reduced cold storage overhead. Individual smallholder farmers in grain belts exhibit the highest price sensitivity, benchmarking microbial products against subsidized urea, while Shandong greenhouse cooperatives accept substantial premiums for precision-integrated nutrition programs.
Supply Chain Analysis
Upstream feedstock sourcing for carrier materials draws from domestic peat extraction in Heilongjiang and vermiculite mining operations in Xinjiang, with liquid culture media components anchored in Shandong chemical processing clusters. Raw material dependencies center on pharmaceutical-grade nutrient broths, sterilized peat substrates, and stabilizing polymer additives. Single-source vulnerability concentrates in cold chain logistics providers serving county-level distribution nodes, where inventory holding periods for living products create spoilage risk. Distribution runs through thousands of independent county agricultural supply companies that maintain credit relationships with township retailers and coordinate last-mile delivery to cooperative buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Strain patent prosecution capacity and extension station relationship density constitute the critical capability gap separating national champions from regional fabricators in this subsidy-gated procurement environment.
For Market Incumbents: Build regulatory moats through accelerated GB 20287-2006 strain documentation investments that preempt provincial subsidy quota reallocation toward certified competitors. Deepen backward integration into liquid broth culture manufacturing in Shandong to capture margin compression from carrier material volatility. Anchor field service capacity in Heilongjiang demonstration plot networks before emerging regional manufacturers consolidate cooperative relationships. For New Entrants and Emerging Players: Build out white-space penetration in Shaanxi apple orchard replant protocols, where mycorrhizal technical service requirements exceed incumbent field agronomist capacity. Target potassium-solubilizing formulations for Yangtze River Delta vegetable systems, a segment receiving limited attention from nitrogen-fixing specialists. Pursue agricultural extension station co-development agreements as the primary go-to-market mechanism to bypass fragmented distributor networks. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive strain libraries and provincial subsidy allocation relationships. Long-term viability hinges on carbon-accounting integration that positions nitrogen-fixing inoculants as verifiable emission reduction instruments under national dual carbon frameworks. Monitor county-level procurement centralization rates as the inflection indicator for cooperative buyer concentration tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Formulation Capacity Expansion | Reduces cold chain dependency while capturing Shandong greenhouse cooperative volume contracts. |
| Provincial Extension Station Partnership | Transfers technical credibility through demonstration plot networks that accelerate farmer trust. |
| Strain Patent Filing Acceleration | Preempts NMPA-equivalent oversight timelines for genetically modified nitrogenase enhancements. |
| Backward Integration into Carrier Materials | Insulates margins from peat extraction limits and vermiculite price instability. |
| Carbon Accounting Certification Program | Positions nitrogen-fixing inoculants for dual carbon subsidy quota preference under Ministry of Agriculture protocols. |
Study Parameters
A spread of perspectives from biofertilizer manufacturing executives, provincial agricultural extension directors, cooperative procurement officers, and county supply company managers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with strain development scientists and distribution channel operators alongside secondary validation through Ministry of Agriculture and Rural Affairs subsidy disbursement records, GB 20287-2006 certification databases, and provincial agricultural bureau procurement disclosures. Bottom-up volume estimates from county-level cooperative purchasing data were triangulated against top-down market sizing derived from manufacturer capacity declarations.
Demand-supply balance modeling across the projection horizon integrated microbial functional category segmentation with application context specifications and end-user procurement behavior patterns. CAGRs were derived from trend extrapolation of historical subsidy allocation trajectories and cooperative adoption curve analysis. Industry-specific forecast inputs included diammonium phosphate price elasticity coefficients and cold chain infrastructure expansion rates at county distribution nodes.
Stress conditions across carrier material cost volatility, synthetic fertilizer subsidy reduction schedules, and NMPA-equivalent approval timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding provincial dual carbon target implementation pace and cooperative buyer consolidation velocity. Cross-checking against Ministry of Agriculture and Rural Affairs organic fertilizer substitution mandate enforcement metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
Mycelium Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Spain Biopesticides Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Latin America Biostimulants Market
Bio-Agriculture
Asia-Pacific Bio-Ethanol Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
Cytokinins Market