
 Global Biofortification Market | 2026-2036
Global Biofortification Market Size, Share, and Industry Trends Forecast 2026-2036
Global Biofortification Market Analysis
EU Green Deal sustainability criteria is hardening the cost-of-entry calculus for biofortified seed suppliers seeking European market access. BASF SE leverages its germplasm library to sustain competitive positioning in micronutrient-dense wheat varieties. CIMMYT anchors global research coordination through its CGIAR mandate and field trial networks across South Asia and Sub-Saharan Africa. Syngenta Group differentiates via marker-assisted selection platforms that compress breeding cycles for iron-fortified bean cultivars.
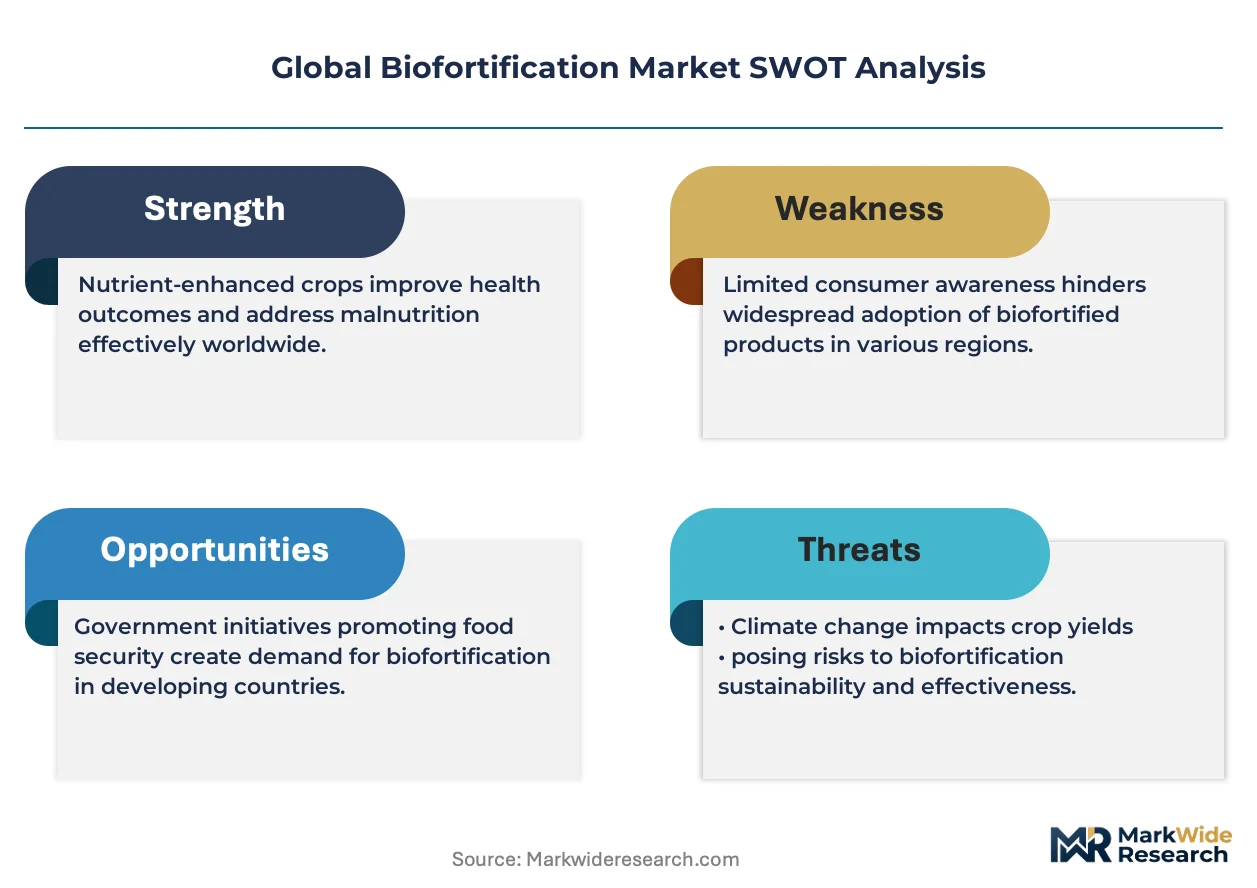
Biofortification denotes the process of increasing the density of vitamins and minerals in a crop through plant breeding, transgenic techniques, or agronomic practices, typically targeting micronutrients such as iron, zinc, and provitamin A that are deficient in regional diets. The primary commercial purpose centers on reducing hidden hunger and diet-related disease burdens while creating differentiated raw material streams for food processors. Traditional breeding occupies the largest deployment share due to lower regulatory barriers and broader consumer acceptance across European and Asian markets. Genetic engineering represents the fastest-expanding technology segment as stacked-trait pipelines advance through field trials in Brazil and the Philippines. Deployment through community programs generates concentrated margin pools where development agencies subsidize seed distribution and farmer training.
WHO biofortification guidelines shape product standards for nutrient retention and bioavailability claims in fortified staple foods. EFSA novel food assessments govern market access for transgenic biofortified varieties entering European processing supply chains. India's FSSAI fortification regulations mandate micronutrient thresholds in distributed wheat and rice, directly stimulating domestic breeding program scale. Stakeholders must monitor how national seed certification bodies reconcile gene-edited crops with existing biosafety frameworks before committing capital to regional production platforms.
Market Dynamics
CRISPR-Cas9 gene editing is compressing breeding timelines from eight years to under three, fundamentally restructuring how seed developers bring micronutrient-dense varieties to commercial scale and forcing traditional breeding programs to accelerate or partner.
Growth Catalysts
- FSSAI fortification mandates:India's mandatory micronutrient thresholds for distributed wheat and rice directly stimulate domestic breeding program expansion and seed procurement volumes.
- HarvestPlus smallholder networks:Development agency partnerships in Sub-Saharan Africa create subsidized distribution channels that de-risk farmer adoption of zinc-enhanced maize varieties.
- Marker-assisted selection platforms:Genomic screening technologies enable parallel trait stacking that cuts phenotypic validation cycles for iron-bean cultivars.
Market Restraints
- EFSA novel food assessments:European transgenic crop approval timelines extending 24-36 months create regulatory friction that blocks near-term market entry for gene-edited varieties.
- Germplasm access concentration:CGIAR gene banks in Mexico and Nigeria control foundational trait libraries, creating licensing bottlenecks for independent seed developers.
- Consumer acceptance variance:European and Japanese markets maintain stigmas against genetically modified staples that limit transgenic biofortification deployment regardless of nutritional merit.
Strategic Opportunities
- Brazil stacked-trait field trials:Regulatory frameworks for gene-edited crops create a permissive testing environment for multivitamin cassava varieties targeting Latin American processors.
- EU Green Deal sustainability criteria:Carbon-accounting requirements for agricultural inputs create preference premiums for biofortified crops that reduce synthetic micronutrient additive use in milling.
- Direct-to-farmer digital channels:Mobile-based seed ordering platforms in Kenya and Ethiopia bypass cooperative intermediaries, capturing margin and farmer data simultaneously.
Industry Challenges
- Bioavailability validation capacity:Human nutrition trial infrastructure remains concentrated at CIMMYT and HarvestPlus hubs, creating queue delays for independent developers seeking nutrient retention certification.
- Gene-editing patent thickets:CRISPR licensing obligations to Broad Institute and Corteva Agriscience create IP cost structures that disadvantage public breeding programs.
- Seed certification reconciliation:National biosafety authorities in the Philippines and Bangladesh lack harmonized protocols for edited-versus-transgenic classification, creating regulatory uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Biofortification Market |
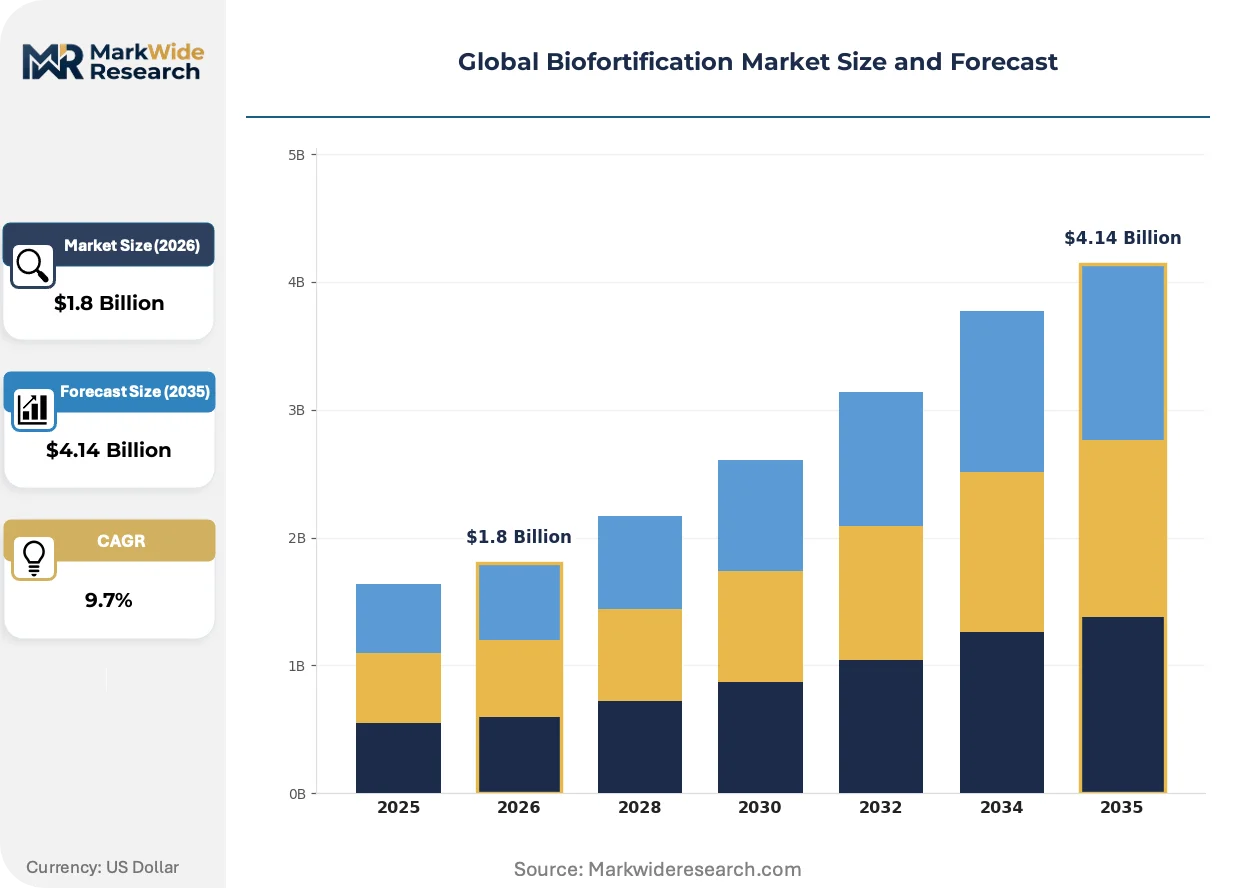
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.14 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wheat, Rice, Maize, Beans End User: Farmers, Food Manufacturers, Research Institutions, NGOs Deployment: Field Trials, Commercial Production, Research Studies, Community Programs Technology: Genetic Engineering, Traditional Breeding, Marker-Assisted Selection, Molecular Marker Technology |
| Companies Covered | BASF SE, International Maize and Wheat Improvement Center (CIMMYT), Bayer AG, DuPont, International Rice Research Institute (IRRI), Syngenta Group, HarvestPlus, Nutrien Ltd., Corteva Agriscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Biofortification Market Emerging Trajectories
Gene editing platforms are collapsing the economics of trait introduction while regulatory frameworks scramble to classify novel varieties, and food manufacturers are rewriting procurement specifications to capture nutritional differentiation.
Base editing technologies are electrifying precision trait insertion by enabling single-nucleotide alterations without double-strand breaks, reducing off-target effects that plagued first-generation CRISPR approaches. Major grain processors in North America and Southeast Asia are accelerating pilot contracts for edited wheat varieties with enhanced zinc content. The technology is electrifying competitive positioning by allowing mid-tier seed developers to bypass germplasm licensing dependencies that previously favored incumbents with decades of breeding records.
EU Green Deal sustainability criteria are hardening the cost-of-entry calculus for biofortified seed suppliers seeking European market access, with carbon footprint disclosures now required for agricultural inputs entering processing supply chains. The regulation forces seed developers to document energy use across breeding, multiplication, and distribution stages. European milling and bakery segments are responding by tightening supplier qualification protocols and demanding third-party verified lifecycle assessments for micronutrient-dense raw materials.
Food manufacturer procurement teams are consolidating supplier relationships around vertically integrated seed-to-ingredient providers capable of certifying micronutrient retention through processing. This pattern displaces spot-market purchasing of commodity staples in favor of multi-year offtake agreements with guaranteed nutritional specifications. The shift is most visible in Indian and Nigerian markets where packaged food brands face government pressure to demonstrate public health impact through fortified product lines.
Global Biofortification Market Segmentation
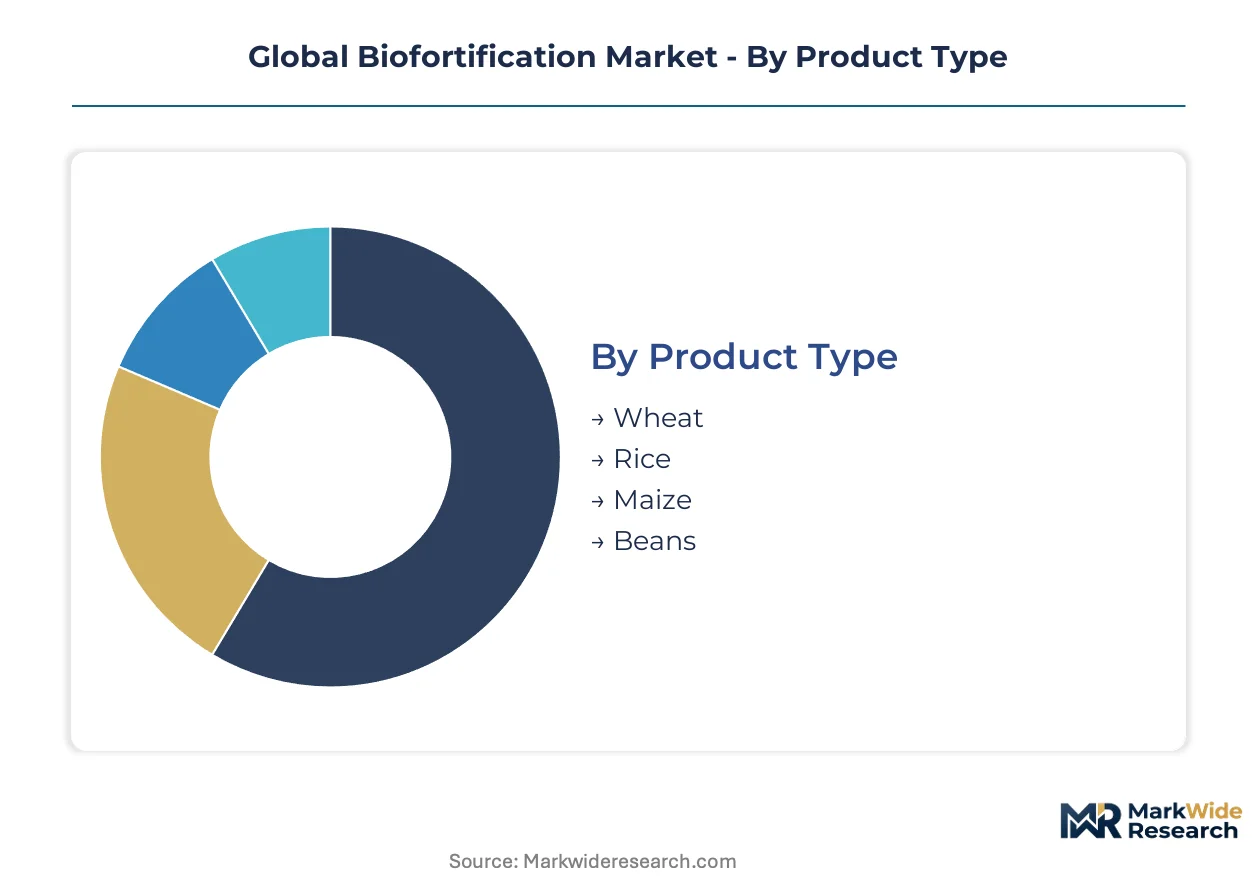
Biofortification market segmentation reveals how nutrient delivery pathways, technical approaches, and stakeholder configurations determine commercial viability. Distinct deployment modes and technology choices create divergent margin structures and regulatory exposure profiles across crop categories.
Product Type:
Technical specifications around micronutrient density and agronomic stability differentiate crop platforms competing for processor procurement contracts.
- Wheat:Zinc-enhanced varieties achieve protein biofortification without yield penalty, attracting Indian milling conglomerates seeking FSSAI-compliant raw material streams. CIMMYT germplasm licensing underpins most commercial cultivars in South Asia.
- Rice:Iron-fortified lines target Southeast Asian diets where polished white rice dominates caloric intake. Golden Rice regulatory approvals in the Philippines demonstrate transgenic pathway viability despite consumer resistance elsewhere.
- Maize:Provitamin A accumulation addresses Sub-Saharan African deficiency patterns through orange-fleshed varieties.
- Beans:Iron and zinc stacking suits Latin American and East African smallholder systems with limited synthetic fertilizer access.
Wheat leads on scale; beans lead on momentum.
End User:
Customer archetypes span from price-sensitive smallholders to specification-driven processors with divergent technical validation requirements.
- Farmers:Subsistence operators in India and Nigeria prioritize yield stability over micronutrient content without subsidy support. Seed procurement decisions hinge on extension service recommendations and demonstration plot visibility.
- Food Manufacturers:Milling and packaged food companies in Europe and North America specify biofortified grain streams to meet EU Green Deal carbon accounting and nutritional labeling commitments.
- Research Institutions:CGIAR centers and national agricultural universities conduct adaptive trials to localize elite germplasm.
- NGOs:HarvestPlus and Gates Foundation grantees distribute subsidized seed through village-based networks.
Food manufacturers command premium pricing; farmers represent volume concentration.
Deployment:
Commercialization stage determines capital intensity and revenue recognition timing across the development pipeline.
- Field Trials:Multi-location testing across agroecological zones generates phenotypic data for variety release submissions. Brazilian regulatory frameworks permit accelerated gene-edited cassava evaluation.
- Commercial Production:Certified seed multiplication and grain offtake contracts deliver recurring revenue to vertically integrated developers.
- Research Studies:Human bioavailability trials at CIMMYT and HarvestPlus hubs validate nutritional efficacy claims.
- Community Programs:Development agency subsidies de-risk farmer adoption in Ethiopia and Bangladesh.
Commercial production anchors revenue; field trials show steepest expansion trajectory.
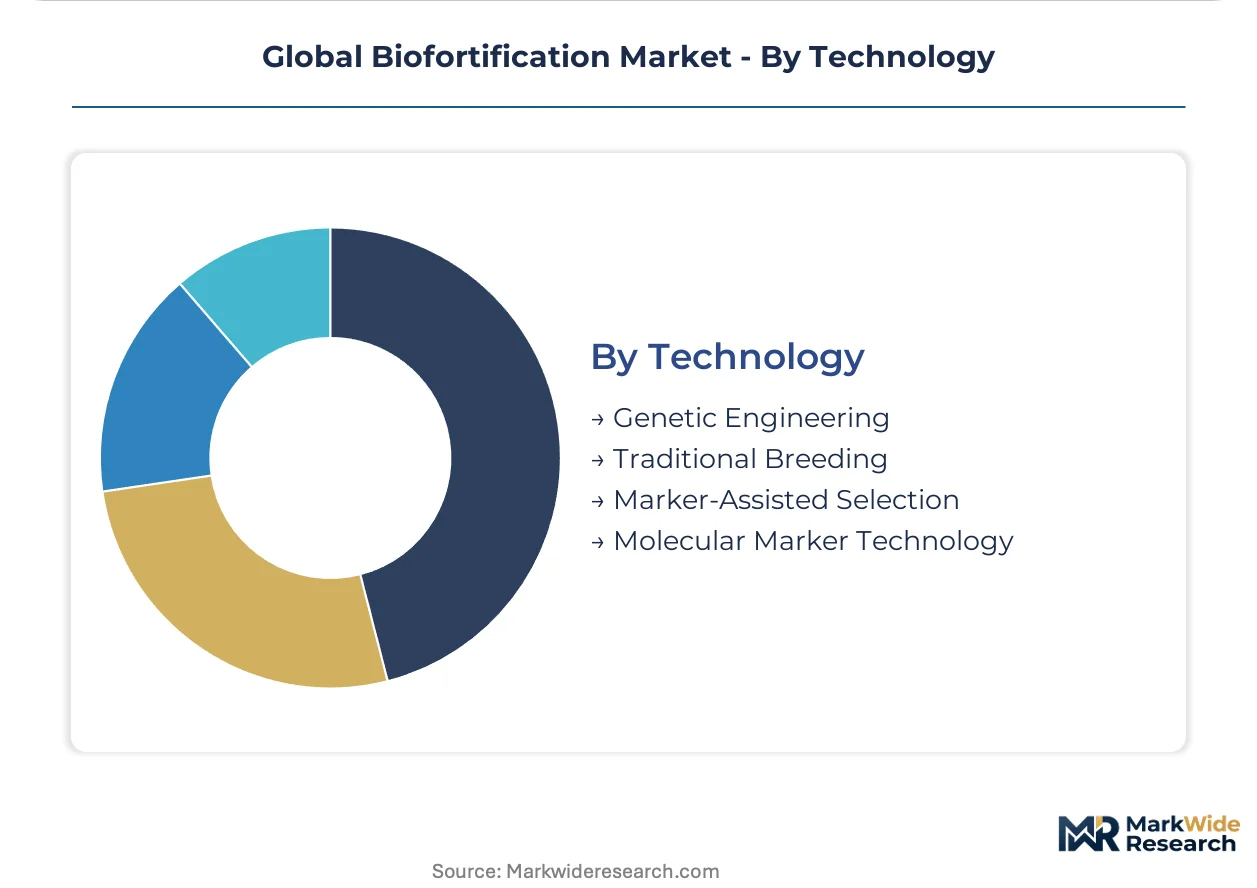
Technology:
Technical approach selection shapes development timelines, regulatory pathways, and intellectual property cost structures.
- Genetic Engineering:Transgenic stacking enables multivitamin trait combinations impossible through conventional breeding. EFSA novel food assessments impose 24-36 month approval delays for European market entry.
- Traditional Breeding:Marker-free selection maintains broad consumer acceptance and streamlined seed certification in Japan and European markets.
- Marker-Assisted Selection:Genomic screening accelerates backcrossing programs for iron-bean cultivars at Syngenta and public breeding stations.
- Molecular Marker Technology:High-density SNP arrays enable precise trait introgression without phenotypic bottlenecks.
Traditional breeding dominates volume; genetic engineering climbs fastest on technical capability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biofortification research and commercial deployment trace their modern lineage to CGIAR breeding programs established in Mexico and the Philippines during the 1960s Green Revolution, with contemporary scaling concentrated in South Asian and Sub-Saharan African smallholder systems.
India
FSSAI fortification mandates for distributed wheat and rice drive procurement volumes from domestic breeding programs. The national food regulator mandates micronutrient thresholds that processors must meet, accelerating seed demand. Punjab and Haryana anchor commercial multiplication of zinc-enhanced wheat varieties for national distribution networks.
Brazil
Stacked-trait cassava trials target Latin American processors seeking multivitamin raw materials. ANVISA maintains permissive frameworks for gene-edited crop evaluation that accelerate field testing timelines. São Paulo state concentrates breeding infrastructure and grain processing capacity for regional supply.
Philippines
Golden Rice regulatory approvals demonstrate transgenic pathway viability for provitamin A delivery in rice-dependent diets. The country's national biosafety authority reconciles edited-versus-transgenic classification protocols. Los Baños hosts IRRI headquarters and field trial networks spanning Southeast Asian agroecological zones.
Germany
EU Green Deal carbon-accounting requirements shape importer qualification protocols for biofortified grain streams. EFSA novel food assessments impose extended approval timelines for transgenic varieties entering European processing chains. Bavaria concentrates milling and bakery R&D facilities adapting procurement specifications to sustainability criteria.
Nigeria
HarvestPlus partnerships create subsidized distribution channels for vitamin A-enhanced maize through smallholder networks. The national agricultural seed council oversees variety release procedures for iron-fortified bean cultivars. Kaduna and Kano states anchor seed multiplication infrastructure for regional deployment.
Global Biofortification Market Vendor Landscape
The competitive structure tilts toward germplasm-backed incumbents with CGIAR licensing relationships and gene-editing platforms compressing development timelines. Market concentration remains moderate, with public research institutions and multinational seed developers occupying distinct functional tiers. Two strategic archetypes dominate: germplasm licensors leveraging decades of breeding records, and technology platforms commercializing CRISPR-edited varieties. Competitive moves center on germplasm access negotiations and marker-assisted selection platform licensing.
Among European-based chemical and seed conglomerates, BASF SE and Bayer AG exemplify the integrated input-provider archetype spanning germplasm through agronomic solutions. Syngenta Group anchors the precision-breeding platform tier with marker-assisted selection capabilities. Public research institutions including CIMMYT and IRRI occupy foundational positions as germplasm custodians and trial coordinators, licensing elite lines to commercial developers while maintaining field networks across South Asia and Sub-Saharan Africa.
| Leading Market Players |
|---|
| BASF SE |
| International Maize and Wheat Improvement Center (CIMMYT) |
| Bayer AG |
| DuPont |
| International Rice Research Institute (IRRI) |
| Syngenta Group |
| HarvestPlus |
| Nutrien Ltd. |
| Corteva Agriscience |
| Others |
Supply Flow & Price Mechanics
EU Green Deal sustainability criteria gates qualified supply and premium-tier pricing access for biofortified seed developers seeking European market entry, forcing documentation of energy use across breeding and distribution stages while carbon-accounting requirements create preference premiums for verified lifecycle assessments.
Pricing Analysis
Contract-based long-term offtake agreements dominate biofortified grain procurement, with pricing stratifying across premium, standard, and economy tiers based on certification grade and volume scale. Price differentiation hinges on FSSAI compliance thresholds and third-party bioavailability validation. Cost compression in standard-tier seed is intensifying because germplasm licensing fees concentrate among CGIAR gene banks. Smallholder farmers in Sub-Saharan Africa exhibit highest price sensitivity, while European milling conglomerates demonstrate lowest sensitivity due to sustainability-linked procurement mandates.
Supply Chain Analysis
Dual-sourcing requirements from European food manufacturers mandate multi-supplier qualification for biofortified wheat and rice streams, reducing single-source dependency. Supply concentrates in India, Brazil, and Nigeria, with germplasm multiplication anchored in Punjab and Haryana states. Raw material dependencies include elite CIMMYT and IRRI germplasm lines, synthetic micronutrient reference standards, and CRISPR reagent kits. Tariff exposure on gene-edited seed imports into the European Union creates structural supply risk. Distribution runs through HarvestPlus village-based networks in Ethiopia and Bangladesh, supplemented by direct-to-farmer mobile platforms in Kenya.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Biofortification Market represents a late-cycle quality story as food manufacturers rewrite procurement specifications to capture nutritional differentiation through micronutrient retention guarantees.
For Market Incumbents: Anchor germplasm licensing relationships with CGIAR centers to defend against CRISPR-enabled challengers bypassing traditional breeding records. Deepen backward integration into certified seed multiplication in India and Nigeria to capture margin from subsidized distribution channels. Invest in marker-assisted selection platform upgrades at Syngenta and Bayer to compress phenotypic validation cycles for iron-bean cultivars. For New Entrants and Emerging Players: Base editing technologies offer a technology-first wedge into the zinc-enhanced wheat segment where mid-tier developers can bypass decades of breeding records. Target Brazil's stacked-trait cassava trials as the most penetrable geography given ANVISA's permissive gene-edited crop evaluation frameworks. Pursue direct-to-farmer digital channel partnerships in Kenya and Ethiopia to capture farmer data and displace cooperative intermediaries. For Investors and Strategic Acquirers: Roll-up economics work for precision-breeding platform specialists because gene-editing patent thickets and bioavailability validation bottlenecks favor consolidated IP portfolios. Acquire developers with CRISPR licensing access and CIMMYT germplasm agreements over the next decade. Watch for EFSA novel food assessment timeline compression as the inflection signal for European market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Multiplication | BASF SE and Bayer AG capture margin from FSSAI-mandated procurement volumes in India. |
| CRISPR Platform Licensing Agreement | Mid-tier developers access Broad Institute patents to compress breeding timelines for zinc-wheat varieties. |
| Long-term Supply Agreement with Processors | Indian milling conglomerates secure certified biofortified grain streams meeting EU Green Deal criteria. |
| Joint Venture with HarvestPlus | Seed developers de-risk farmer adoption through subsidized distribution in Nigerian smallholder networks. |
| Regulatory Approval Pathway Investment | Golden Rice developers navigate Philippines biosafety protocols to demonstrate transgenic viability. |
Methodological Framework
Direct dialogue with seed development executives, regulatory affairs leads at national biosafety authorities, food manufacturer procurement directors, and CGIAR germplasm licensing officers grounded the qualitative foundation. Secondary validation drew from FSSAI fortification regulations, EFSA novel food assessment filings, WHO biofortification guidelines, and HarvestPlus program documentation. Bottom-up variety release timelines and top-down micronutrient deficiency burden estimates were triangulated to anchor demand assumptions.
Bottom-up modeling of certified seed multiplication volumes and grain offtake contracts was cross-checked against top-down food processor procurement specifications across the projection horizon. Segmentation dimensions included crop type, technology platform, deployment stage, and regional regulatory cluster. CAGRs were derived from fitted adoption curves for gene-edited varieties and historical penetration rates of traditional breeding programs. Forecast inputs incorporated FSSAI mandate enforcement intensity and EFSA assessment timeline variability.
The model holds under sustained government micronutrient program funding and permissive gene-edited crop classification; deviation in biosafety protocol harmonization or CGIAR germplasm access restrictions would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Biosolids Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
North America Biopesticides Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Animal Eubiotics Market
Bio-Agriculture
North America Biostimulants Market
Bio-Agriculture
India Biomass Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Africa Biostimulants Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
North America Bio-Ethanol Market
Bio-Agriculture
India Biostimulants Market