
 Middle East and Africa Animal Genetics Market | 2026-2036
Middle East and Africa Animal Genetics Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Animal Genetics Market Insights
Saudi Arabia's large-scale dairy expansion is rewriting regional procurement patterns for elite breeding stock. Zoetis leverages its biotech portfolio to serve government-backed herd improvement schemes across the Gulf. Genus PLC anchors its regional position through bovine semen distribution networks stretching into East Africa. Hendrix Genetics specializes in poultry genetics adapted to heat-stressed environments prevalent across North Africa.
Animal genetics encompasses the selective breeding, genomic evaluation, and reproductive biotechnology used to improve heritable traits in livestock populations, including marker-assisted selection and cryopreserved semen protocols with documented conception rates. The discipline serves commercial agriculture by accelerating genetic gain for milk yield, disease resistance, and feed conversion efficiency. Breeding stock and genetic material together capture the dominant share of product-type revenue, with DNA testing representing the fastest-expanding margin pool as commercial farms replace phenotypic culling with genomic screening. Cattle genetics generates the largest absolute volume across animal-type categories, though poultry genetics is displacing traditional breeding approaches in Morocco and Egypt due to shorter generational intervals and integrated contract farming structures.
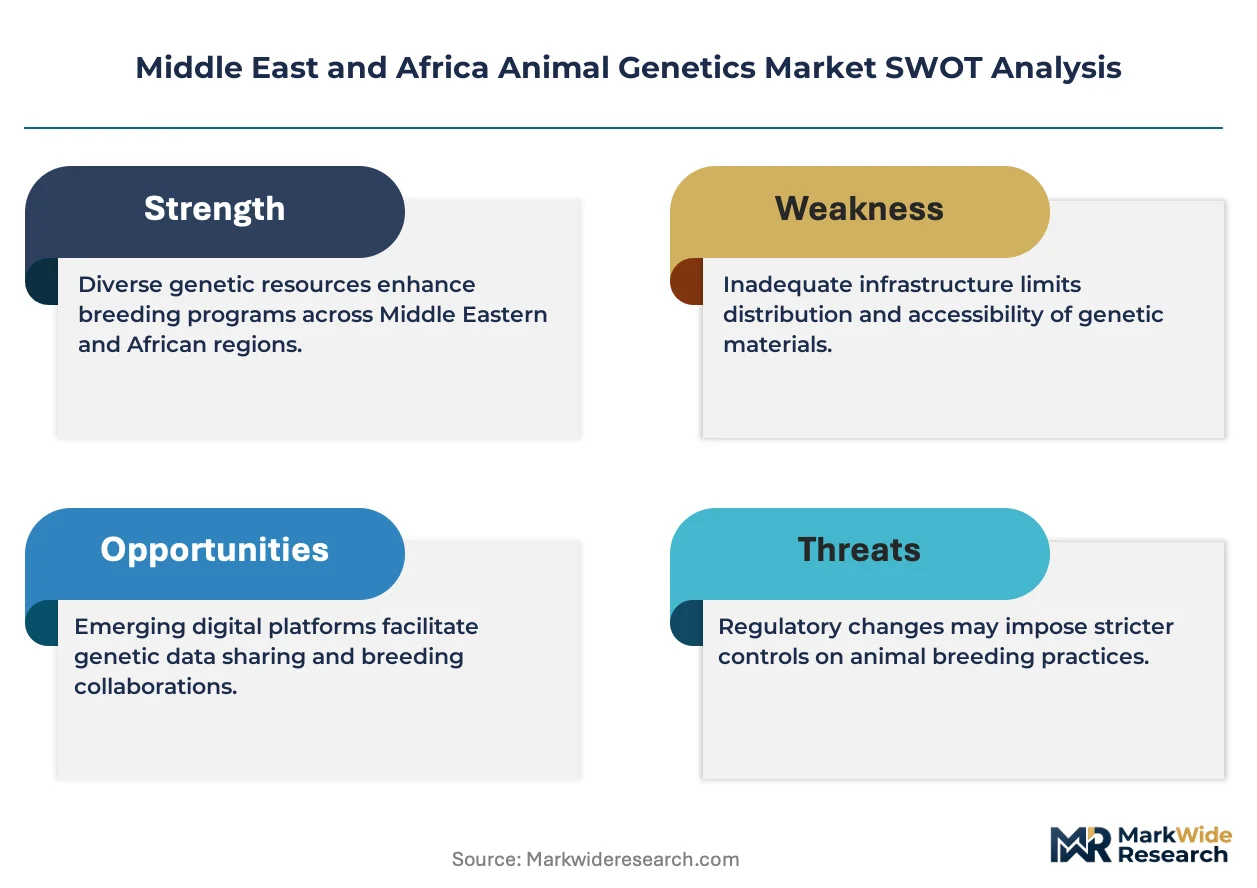
South Africa's Department of Agriculture, Land Reform and Rural Development enforces strict breeding stock health certification that shapes cross-border trade flows with neighboring states. Kenya's Veterinary Services Directorate and Nigeria's national livestock regulator impose parallel import quarantine rules that filter which genetics suppliers gain market access. The OIE/WOAH standards provide a baseline for regional harmonization, though implementation remains uneven. Stakeholders must monitor which national regulators adopt genomic pedigree verification as a mandatory market entry condition.
Market Dynamics
Government-backed herd improvement schemes across Gulf Cooperation Council states are concentrating demand for elite breeding stock into state-procurement channels, compressing supplier access windows and favoring genetics providers with established veterinary service partnerships.
Growth Catalysts
- State Dairy Expansion Mandates:Saudi Arabia's National Transformation Program directs capital toward commercial dairy capacity, creating sustained demand for high-yielding Holstein genetics through centralized import tenders.
- WOAH Harmonization Trajectory:Regional adoption of World Organisation for Animal Health standards for breeding stock health certification is reducing cross-border friction in East African trade corridors.
- Genomic Screening Adoption:Commercial farms in South Africa are replacing phenotypic culling with DNA-based selection protocols, accelerating replacement rates and semen throughput requirements.
Market Restraints
- Liquid Nitrogen Supply Volatility:Cryopreservation logistics depend on concentrated liquid nitrogen production in South Africa and Morocco, exposing semen distribution networks to input cost spikes and cold-chain rupture risk.
- Import Quarantine Friction:Kenya's Veterinary Services Directorate and Nigeria's national livestock regulator impose divergent 30-90 day quarantine rules that fragment supplier compliance costs across neighboring markets.
- Heat Stress Fertility Depression:Ambient temperature elevation above thermal neutral zones in North African production environments degrades conception rates from imported temperate-zone genetics, limiting genetic gain realization.
Strategic Opportunities
- Ethiopian Highlands Underpenetration:Ethiopia's state-led livestock modernization initiative has not yet established formal genetics import channels, creating first-mover positioning for suppliers willing to build veterinary infrastructure partnerships.
- CRISPR Regulatory Tailwind:South Africa's Department of Agriculture, Land Reform and Rural Development has signaled openness to gene-edited disease resistance traits in breeding stock, ahead of neighboring jurisdictions.
- Mobile Cold-Chain Innovation:Solar-powered liquid nitrogen transport units are enabling semen distribution to remote pastoral zones previously excluded from artificial insemination service networks.
Industry Challenges
- Veterinary AI Technician Scarcity:Certified inseminators capable of executing timed artificial insemination protocols remain concentrated in South Africa and Kenya, constraining program scale-up in secondary markets.
- Genomic Pedigree Verification Delays:Turnaround times for SNP-based parentage confirmation from regional laboratories extend breeding decisions by 6-12 weeks, compressing seasonal insemination windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Animal Genetics Market |
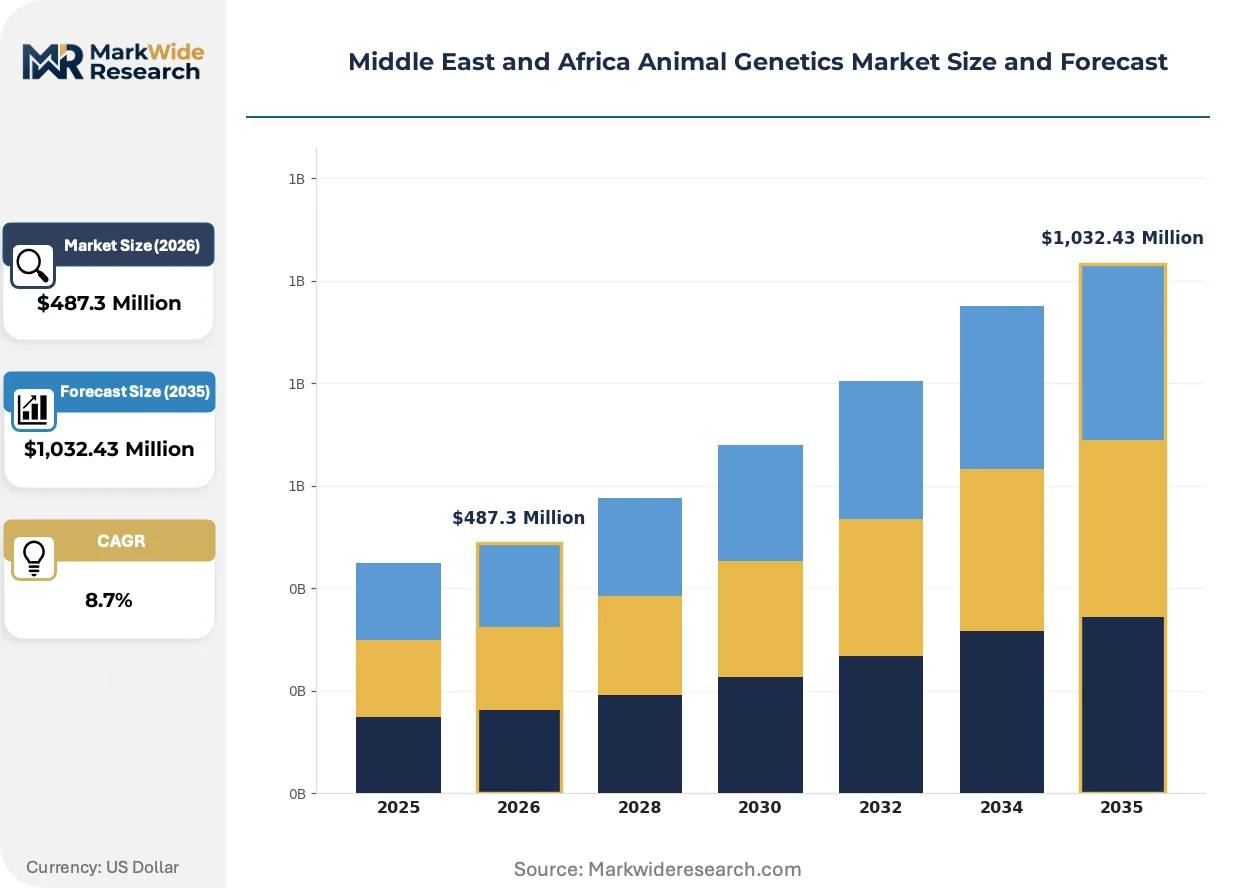
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breeding Stock, Genetic Material, Biotech Solutions, DNA Testing Applications: Agriculture, Research Institutions, Veterinary Clinics, Livestock Management Animal Type: Cattle, Poultry, Sheep, Swine End User: Farmers, Breeders, Government Agencies, Research Organizations |
| Companies Covered | CRV Holding, Zoetis, Genus PLC, URUS Group, Genetics Australia, Hendrix Genetics, Animal Genetics Inc., Topigs Norsvin, Neogen Corporation, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Animal Genetics Market Trends and Innovations
Reproductive biotechnology is converging with digital livestock management platforms, restructuring how commercial operators source, evaluate, and deploy genetic material across dispersed production geographies.
Single-nucleotide polymorphism (SNP) arrays for genomic estimated breeding values are digitizing bull selection decisions in South African and Kenyan commercial dairies. Medium-scale operators with 200-500 head are adopting chip-based screening at replacement heifer selection, compressing the interval between phenotypic observation and culling action from 24 months to weaning. This acceleration is digitizing genetic gain timelines and concentrating semen purchasing power among farms with in-house genomic capability.
Kenya's Veterinary Services Directorate is tightening import health certification requirements for breeding stock, extending documentation requirements to include whole-herd disease freedom statements from origin farms. The policy shift elevates compliance costs for European and North American exporters while creating structural preference for suppliers with established veterinary audit relationships. Dairy cooperatives in the Rift Valley are responding by consolidating procurement through accredited intermediaries capable of navigating multi-jurisdictional paperwork.
Contract farming structures in Moroccan and Egyptian poultry operations are consolidating genetics purchasing decisions into integrator-owned grandparent stock facilities. Independent broiler growers no longer source day-old chicks from distributed hatcheries but receive flock placements under formula pricing tied to feed conversion performance. This concentration is visible most acutely in Egypt's Nile Delta production belt, where three integrators now control over 80 percent of parent stock imports.
Middle East and Africa Animal Genetics Market Segmentation
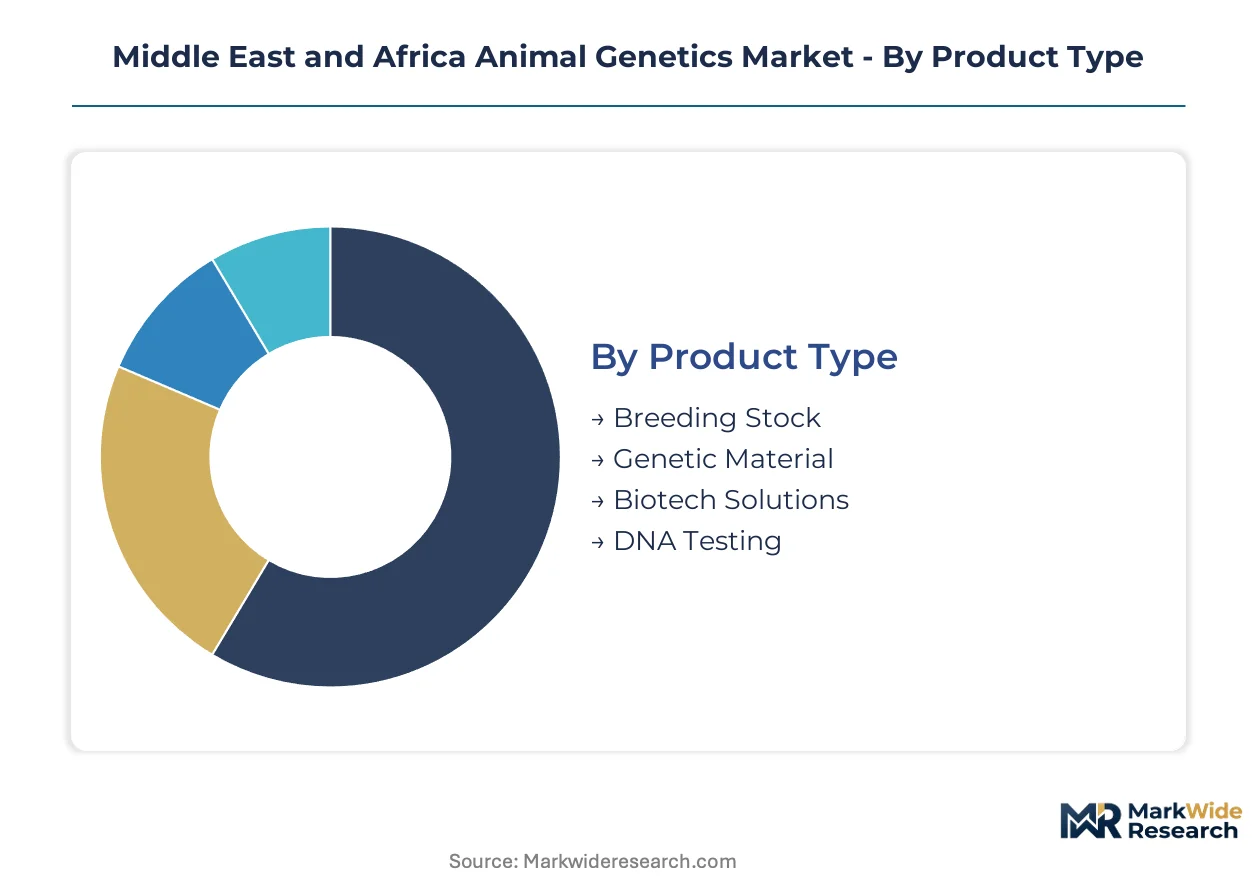
Segmentation in the Middle East and Africa Animal Genetics Market reveals how procurement authority, biological constraints, and regulatory frameworks concentrate value across distinct customer and product categories. Understanding these divisions exposes where supplier margins accumulate and which channels face the steepest compliance burdens.
Product Type:
Cost tier determines procurement channel access and margin structure across genetic inputs, with premium-positioned segments commanding state-backed tenders while commoditized categories compete on cold-chain reliability.
- Breeding Stock:Live animals selected for superior heritable traits including milk yield, disease resistance, and feed conversion efficiency. Saudi Arabia's National Transformation Program channels procurement through centralized import tenders, compressing supplier access to veterinary-certified providers with established Gulf partnerships.
- Genetic Material:Cryopreserved semen and embryos maintained in liquid nitrogen cold chains with documented conception rate protocols. South African commercial dairies scale artificial insemination programs through this segment, driving sustained demand for Holstein and Jersey genetics with verified heat tolerance performance.
- Biotech Solutions:Reproductive technologies including in-vitro fertilization and embryo transfer systems deployed by veterinary service networks.
- DNA Testing:SNP arrays and genomic screening services enabling marker-assisted selection protocols. Commercial farms replace phenotypic culling with chip-based screening, compressing replacement heifer selection timelines from 24 months to weaning.
Breeding stock commands the established base. The steepest expansion runs through DNA Testing.
Applications:
Application scope tracks how genetic technologies migrate from production agriculture into institutional research and clinical service delivery across the region.
- Agriculture:Commercial livestock operations deploying selective breeding and genomic evaluation to accelerate genetic gain for productivity traits. Moroccan and Egyptian poultry integrators concentrate parent stock decisions through contract farming structures that eliminate independent hatchery sourcing.
- Research Institutions:Academic and government facilities conducting heritability studies and breed improvement trials. Kenya's Veterinary Services Directorate collaborates with these entities to validate disease resistance traits under local environmental stressors.
- Veterinary Clinics:Service providers executing artificial insemination protocols and reproductive health monitoring.
- Livestock Management:Digital platforms integrating genomic data with herd performance tracking systems.
Agriculture absorbs the dominant procurement volume. Research Institutions capture the most rapid capability expansion.
Animal Type:
Biological generational intervals and regional climate adaptation pressures reshape which species categories attract investment intensity.
- Cattle:Dairy and beef genetics generating the largest absolute revenue volume across the region. Heat stress fertility depression in North African production environments limits conception rate realization from temperate-zone Holstein imports, creating demand for thermotolerance-selected breeding programs.
- Poultry:Broiler and layer genetics with shorter generational intervals enabling rapid genetic turnover. Hendrix Genetics and similar providers specialize in heat-stressed environment adaptations prevalent across North Africa, displacing traditional breeding approaches in Morocco and Egypt.
- Sheep:Breeding programs targeting wool quality and meat yield in arid-zone pastoral systems.
- Swine:Limited regional presence constrained by religious dietary restrictions and import quarantine complexity.
Cattle maintains the revenue foundation. Poultry gains share fastest through integrated contract farming consolidation.
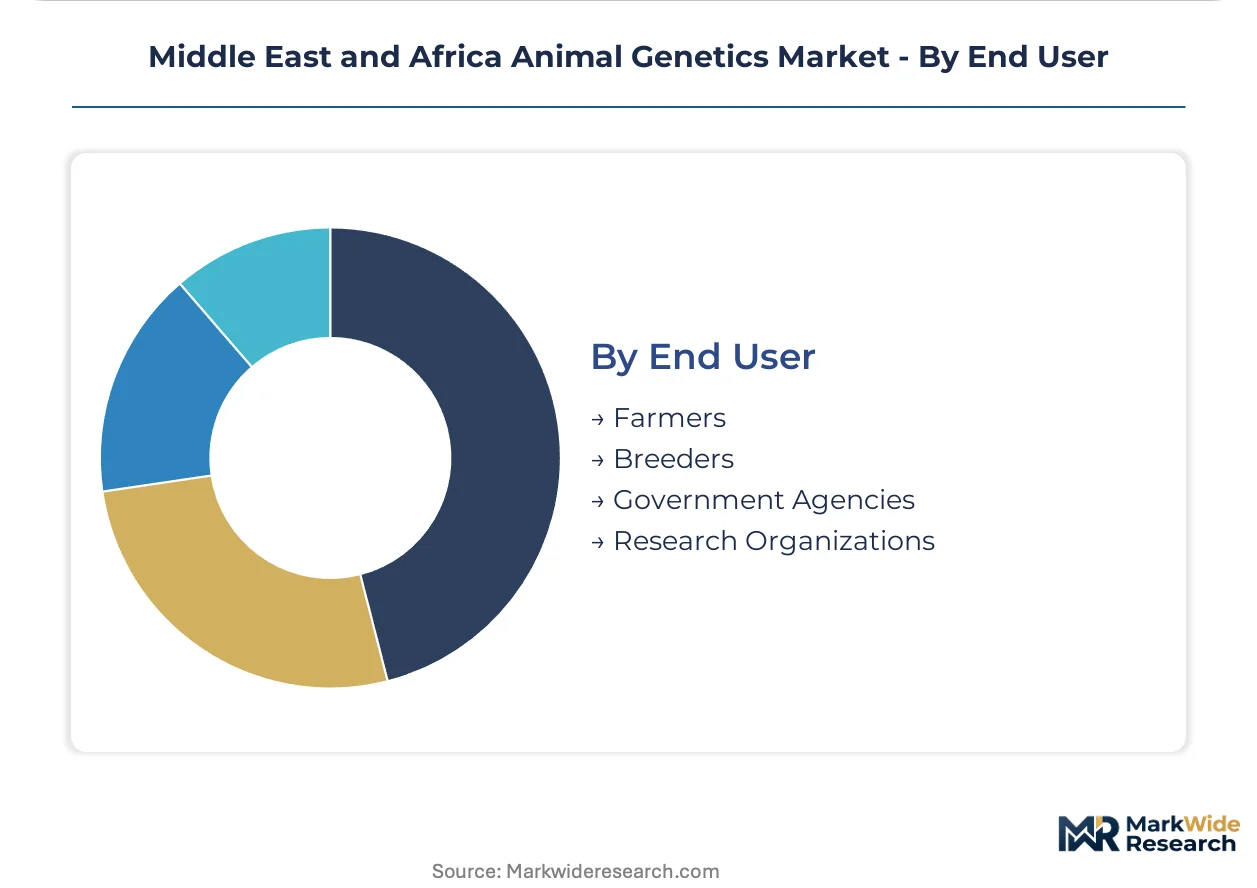
End User:
Customer type segmentation exposes where purchasing authority concentrates and how regulatory compliance burdens distribute across public and private actors.
- Farmers:Commercial operators with 200-500 head in South Africa and Kenya adopting genomic screening at replacement heifer selection. Mobile cold-chain innovations now extend artificial insemination service access to remote pastoral zones previously excluded from formal genetics networks.
- Breeders:Specialized operations maintaining pedigree herds and supplying genetic material downstream. South Africa's Department of Agriculture, Land Reform and Rural Development enforces strict health certification that shapes cross-border trade flows with neighboring states.
- Government Agencies:State procurement channels including Saudi Arabia's dairy expansion mandates and Ethiopia's livestock modernization initiative. These actors concentrate demand for elite breeding stock into tenders favoring suppliers with established veterinary infrastructure partnerships.
- Research Organizations:Entities validating genomic estimated breeding values and trait heritability under regional conditions.
Government Agencies anchor high-value procurement through centralized tenders. Farmers represent the most distributed but fastest-digitizing demand layer.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cryopreserved semen production concentrates in South Africa and Morocco, anchoring liquid nitrogen cold-chain infrastructure that feeds distribution networks across sub-Saharan and North African corridors. National regulators in Kenya, Nigeria, and Saudi Arabia impose divergent import certification rules that fragment supplier compliance architectures.
Saudi Arabia
State dairy expansion under the National Transformation Program generates sustained demand for Holstein breeding stock through centralized government tenders. SFDA enforces veterinary health certification protocols that filter market access to suppliers with established Gulf partnerships. Riyadh-based procurement channels concentrate import volume for elite genetics serving commercial herd improvement schemes.
South Africa
Commercial dairies scale artificial insemination programs with documented conception rate protocols for Jersey and Holstein genetics. The Department of Agriculture, Land Reform and Rural Development mandates strict breeding stock health certification that shapes cross-border trade with neighboring states. Gauteng and Western Cape clusters host the region's dominant liquid nitrogen production and semen distribution infrastructure.
Kenya
Rift Valley dairy cooperatives consolidate procurement through accredited intermediaries capable of navigating multi-jurisdictional paperwork. The Veterinary Services Directorate extends import documentation requirements to whole-herd disease freedom statements from origin farms. Nairobi serves as the regional hub for SNP-based genomic screening services and artificial insemination technician certification programs.
Egypt
Nile Delta poultry integrators control over 80 percent of parent stock imports through contract farming structures that eliminate independent hatchery sourcing. National livestock regulators impose quarantine rules that elevate compliance costs for European and North American exporters. Cairo-Alexandria production belts concentrate demand for heat-tolerant broiler genetics adapted to thermal stress environments.
Ethiopia
State-led livestock modernization initiatives have not yet established formal genetics import channels, leaving pastoral zones dependent on informal breeding stock flows. The country's national veterinary regulator operates without harmonized cross-border health certification frameworks. Addis Ababa and the central highlands represent underpenetrated territory for suppliers willing to build veterinary infrastructure partnerships.
Middle East and Africa Animal Genetics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in genetic material and biotech solutions. The vendor base stratifies across three tiers: multinational breeding stock conglomerates with Gulf state partnerships, regional semen distributors with cold-chain assets, and genomic screening service providers digitizing replacement heifer selection. Competitive positioning depends on veterinary audit relationships with national regulators and liquid nitrogen logistics reach into remote pastoral zones. M&A activity concentrates in artificial insemination service networks, while capacity expansion targets mobile cold-chain units for semen distribution.
Among multinational breeding stock suppliers, CRV Holding and Genus PLC exemplify platform integrators with established bovine semen distribution networks stretching into East Africa. Zoetis anchors the biotech solutions tier through government-backed herd improvement schemes across Gulf Cooperation Council states. Hendrix Genetics occupies a specialist position in poultry genetics adapted to heat-stressed environments prevalent across North African production belts.
| Leading Market Players |
|---|
| CRV Holding |
| Zoetis |
| Genus PLC |
| URUS Group |
| Genetics Australia |
| Hendrix Genetics |
| Animal Genetics Inc. |
| Topigs Norsvin |
| Neogen Corporation |
| Others |
Pricing and Supply Chain Analysis
Liquid nitrogen production clusters in South Africa and Morocco anchor cryopreservation costs and concentrate margin capture among cold-chain operators with captive gas supply contracts. Genetic material pricing tiers separate veterinary-certified breeding stock from commodity semen based on genomic verification depth and heat-tolerance performance documentation.
Pricing Analysis
Kenya's Veterinary Services Directorate and Nigeria's national livestock regulator dictate the pricing tier structure through divergent import certification requirements. Three-tier pricing structure across premium, standard, and economy levels separates WOAH-compliant breeding stock with whole-herd disease freedom statements from basic health-certified alternatives. Cost compression in economy-tier genetic material is intensifying because mobile cold-chain innovations extend distribution reach into price-sensitive pastoral zones. Government procurement channels in Saudi Arabia show least price sensitivity due to National Transformation Program mandates, while medium-scale commercial dairies in South Africa exhibit highest elasticity to semen unit costs.
Supply Chain Analysis
WOAH health certification standards and national quarantine regimes restrict breeding stock flows across East African trade corridors. Geographic supply concentration centers on South Africa, Morocco, and select European exporters with established veterinary audit relationships. Cryopreserved semen distribution draws from liquid nitrogen production hubs in Gauteng and Western Cape, with embryo transfer biotech resting on regional veterinary service networks. Single-source vulnerability runs through concentrated liquid nitrogen manufacturing exposed to energy cost spikes. Distribution runs through state-procurement tenders in Gulf markets and accredited intermediary channels in East Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: national veterinary certification requirements create switching costs that lock in suppliers with established audit relationships and multi-jurisdictional compliance capability.
For Market Incumbents: Entrench position by deepening veterinary infrastructure partnerships in Ethiopia's underpenetrated highlands before formal import channels crystallize. Acquire mobile cold-chain operators to extend liquid nitrogen distribution into remote pastoral zones and preempt emerging entrant beachheads. Prioritize CRISPR trait development investment in South Africa ahead of neighboring regulatory openness to gene-edited disease resistance. For New Entrants and Emerging Players: Establish a beachhead in Ethiopian government agency procurement by building veterinary audit capacity before state-led livestock modernization establishes formal tender structures. Target DNA testing services for medium-scale South African dairies adopting genomic screening at replacement heifer selection. Deploy solar-powered liquid nitrogen transport units as the go-to-market angle to bypass incumbent cold-chain infrastructure gaps. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional semen distributors consolidating artificial insemination service networks. Long-term viability frames around 5-10 year regulatory harmonization trajectories as WOAH standards propagate across East Africa. Watch for Ethiopian regulatory framework formalization as the inflection signal indicating first-mover window closure.| Strategic Initiative | Industry Significance |
|---|---|
| Veterinary Infrastructure Partnership | SFDA and Kenya's Veterinary Services Directorate filter market access to audited suppliers with established Gulf and East African relationships. |
| Mobile Cold-Chain Expansion | Solar-powered liquid nitrogen transport units enable semen distribution to remote pastoral zones previously excluded from artificial insemination networks. |
| Genomic Screening Service Launch | SNP array deployment compresses replacement heifer selection timelines from 24 months to weaning for South African commercial dairies. |
| CRISPR Trait Development Investment | South Africa's Department of Agriculture signals openness to gene-edited disease resistance ahead of neighboring jurisdictions. |
| Accredited Intermediary Consolidation | Rift Valley dairy cooperatives concentrate procurement through intermediaries capable of navigating Kenya's extended documentation requirements. |
Research Methodology
A spread of perspectives from breeding stock suppliers, veterinary service network operators, national livestock regulator officials, and commercial dairy procurement managers converged on the working assumptions. Primary interviews combined with secondary validation from WOAH standards documentation, national veterinary certification registries, and customs trade data for cryopreserved genetic material. Bottom-up segmentation modeling triangulated against top-down macroeconomic drivers across the Middle East and Africa region.
Demand-supply balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include product type tier, animal species, end-user procurement authority, and national regulatory cluster. CAGRs derived from fitted growth curves applied to verified baseline volumes. Industry-specific forecast inputs incorporated artificial insemination adoption rates in South African commercial dairies and state dairy expansion procurement timelines in Saudi Arabia.
Macroeconomic conditions sit as an overlay; deviation in liquid nitrogen production costs, currency volatility affecting import-dependent markets, or regulatory harmonization pace would shift the trajectory. Forecasts reflect documented assumptions about veterinary technician training pipeline expansion and cold-chain infrastructure buildout. Material shifts in Ethiopian regulatory framework formalization or CRISPR policy adoption across additional jurisdictions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
United States Biostimulants Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
United States Biofertilizer Market
Bio-Agriculture
Ulva Lactuca Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Japan Biofertilizer Market
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Asia-Pacific Biopesticides Market
Bio-Agriculture
Asia-Pacific Biological Organic Fertilizers Market
Bio-Agriculture
United States Biocontrol Agents Market