
 Transgenic Animals Market | 2026-2036
Transgenic Animals Market Size, Share, and Industry Trends Forecast 2026-2036
Transgenic Animals Market Outlook
CRISPR-Cas9 multiplexing is reconfiguring how transgenic lines are engineered for therapeutic protein production. Charles River Laboratories leverages its global breeding infrastructure to service contract research demand across multiple continents. Regeneron Pharmaceuticals anchors its VelociGene platform in proprietary mouse model development for antibody discovery pipelines. Cyagen Biosciences specializes in custom knockout and knockin services, competing on turnaround speed and vector design flexibility.
Transgenic animals are organisms whose genome has been deliberately altered through the introduction, deletion, or modification of specific DNA sequences, typically achieved via pronuclear microinjection, embryonic stem cell targeting, or programmable nuclease systems achieving germline transmission rates above 15 percent in optimized protocols. These organisms serve as living bioreactors for recombinant protein production, disease models for preclinical validation, and genetic improvement platforms for agricultural traits. CRISPR-based modification methods now dominate new model generation due to cost efficiency and multiplexing capability, while microinjection retains share in large-animal applications where embryo handling infrastructure is established. Pharmaceutical applications command the deepest margin pools as sponsors fund development under accelerated regulatory pathways, whereas agricultural applications face slower commercialization due to consumer acceptance barriers and extended safety review cycles.
FDA oversight of genetically engineered animals under the animal drug provisions of the Federal Food, Drug, and Cosmetic Act shapes product approval timelines and field trial protocols for US developers. EMA guidelines on genetically modified organisms and REACH chemical safety obligations constrain how European research institutions procure and dispose of transgenic biomaterials. Stakeholders must monitor evolving gene-editing policy distinctions between transgenic and site-directed modification classifications, as regulatory reclassification would unlock or foreclose market access across major jurisdictions.
Market Dynamics
CRISPR multiplexing protocols have compressed germline transmission timelines from months to weeks, fundamentally altering how contract research organizations price model development services and structure milestone-based engagements with pharmaceutical sponsors.
Growth Catalysts
- NIH funding density:The National Institutes of Health maintains concentrated grant streams for translational genomics research, channeling capital toward high-complexity model development pipelines in the United States.
- Biopharmaceutical absorption:Therapeutic protein harvesters now embed transgenic platforms into recombinant antibody manufacturing workflows, treating living bioreactors as upstream production assets rather than experimental tools.
- FDA pathway clarity:The Center for Veterinary Medicine's animal drug provisions provide explicit review frameworks for genetically engineered organisms, reducing regulatory uncertainty for developers pursuing Investigational New Animal Drug submissions.
Market Restraints
- Germline transmission volatility:Microinjection protocols in large-animal applications achieve variable integration efficiency, creating cost unpredictability for agricultural trait developers working with bovine and porcine embryos.
- Consumer acceptance barriers:Agricultural biotechnology faces extended safety review cycles and retail resistance, particularly in European markets where EFSA novel food assessments intersect with member-state labeling disputes.
- Embryo handling infrastructure concentration:Specialized surgical facilities for pronuclear injection remain geographically clustered in Massachusetts, California, and select Swiss cantons, limiting access for distributed research institutions.
Strategic Opportunities
- Site-directed modification reclassification:Evolving gene-editing policy distinctions between transgenic and precision-edited classifications could unlock streamlined approval pathways in jurisdictions adopting product-based rather than process-based regulatory triggers.
- India CDSCO alignment:The Central Drugs Standard Control Organization's emerging biosafety frameworks for genetically modified organisms present first-mover positioning for contract research providers establishing GMP-compliant breeding facilities.
- Base editing convergence:Cytosine and adenine base editors are merging with CRISPR-Cas9 workflows to enable single-nucleotide modifications without double-strand breaks, opening disease-model applications previously inaccessible due to off-target constraints.
Industry Challenges
- Multiplexing skill scarcity:Guide RNA design for simultaneous multi-locus editing requires computational biology expertise that outpaces current veterinary genetics training pipelines, creating recruitment bottlenecks for high-throughput model generation facilities.
- Biocontainment capex intensity:Physical containment infrastructure for transgenic large animals demands specialized HVAC, waste sterilization, and genetic isolation systems that strain capital allocation for mid-scale research service providers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transgenic Animals Market |
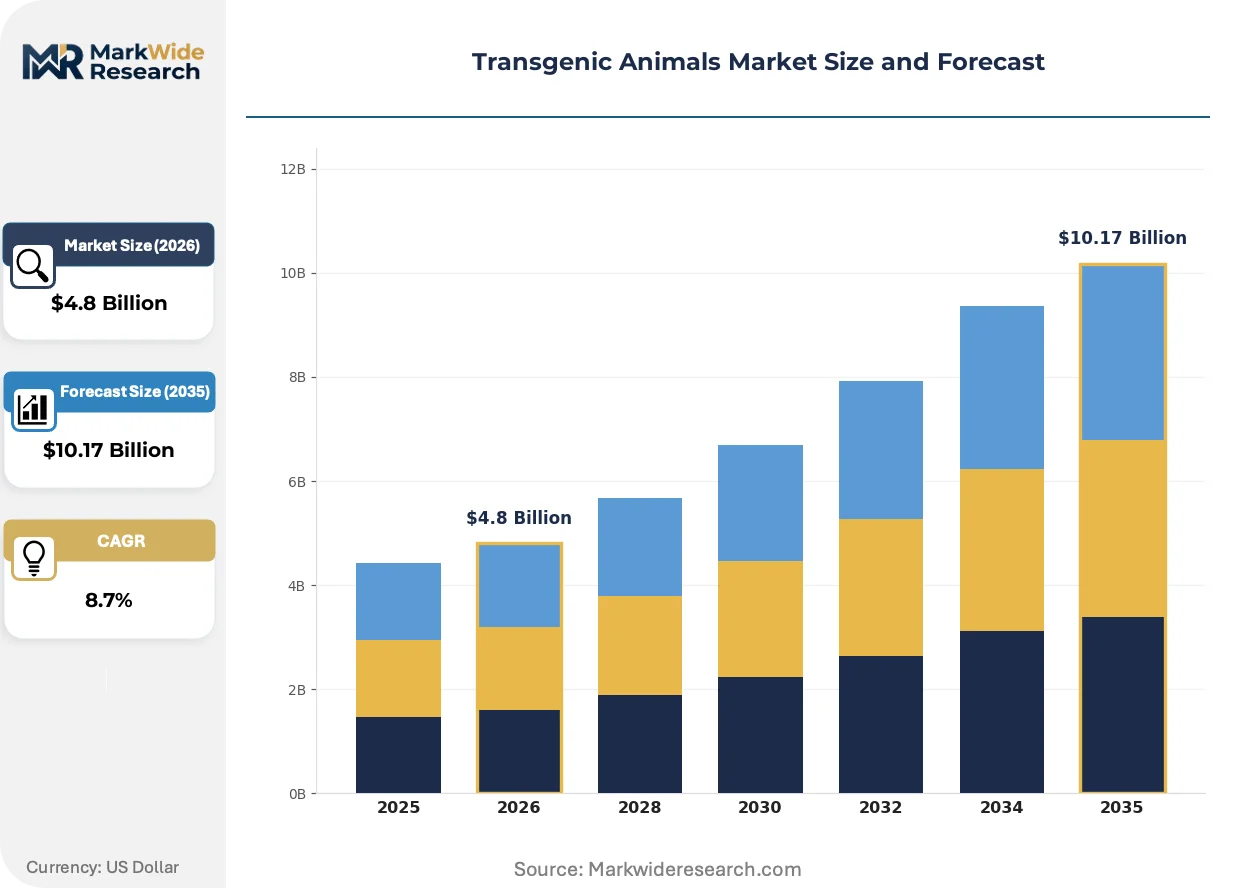
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Agricultural, Pharmaceutical, Research, Biopharmaceutical Genetic Modification Method: CRISPR, Gene Targeting, Transposon-mediated, Microinjection Animal Species: Mice, Goats, Cattle, Pigs End User: Research Institutions, Pharmaceutical Companies, Biotech Firms, Government Agencies |
| Companies Covered | Cyagen Biosciences, Regeneron Pharmaceuticals, Charles River Laboratories, OmniAb, Genus plc, Taconic Biosciences, Biocytogen, Ablexis, genOway, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transgenic Animals Market Strategic Shifts
Programmable nuclease systems are compressing development timelines while regulatory frameworks struggle to distinguish process-based from product-based oversight triggers, creating simultaneous acceleration and friction in model commercialization pathways.
Artificial intelligence platforms for guide RNA design are digitizing the target selection and validation workflow in transgenic model development. Contract research organizations in the United States and Switzerland deploy machine learning tools to predict off-target effects before embryo manipulation, reducing the generation-to-phenotype interval. This compression is digitizing how sponsors structure milestone payments and intellectual property terms in multi-year service agreements.
EMA guidelines on genetically modified organisms are tightening documentation requirements for transgenic biomaterial transfer across European research consortia, particularly affecting cross-border collaboration frameworks under REACH chemical safety obligations. Biobanking facilities in Germany and the Netherlands now dedicate specialized compliance personnel to chain-of-custody protocols for genetically engineered murine lines. Pharmaceutical sponsors operating European preclinical programs are responding by consolidating model sourcing within single-jurisdiction breeding networks to minimize regulatory friction.
Academic medical centers are unbundling after-sales phenotyping services from core model acquisition contracts, treating characterization as a separate procurement category with distinct vendor qualification criteria. This disintermediation is most visible in the United States, where NIH-funded institutions negotiate standardized pricing for baseline pathology while contracting specialized behavioral or imaging studies through competitive secondary sourcing. The shift forces transgenic service providers to demonstrate phenotyping depth beyond genotype confirmation or risk margin compression in commoditized breeding segments.
Transgenic Animals Market Segmentation
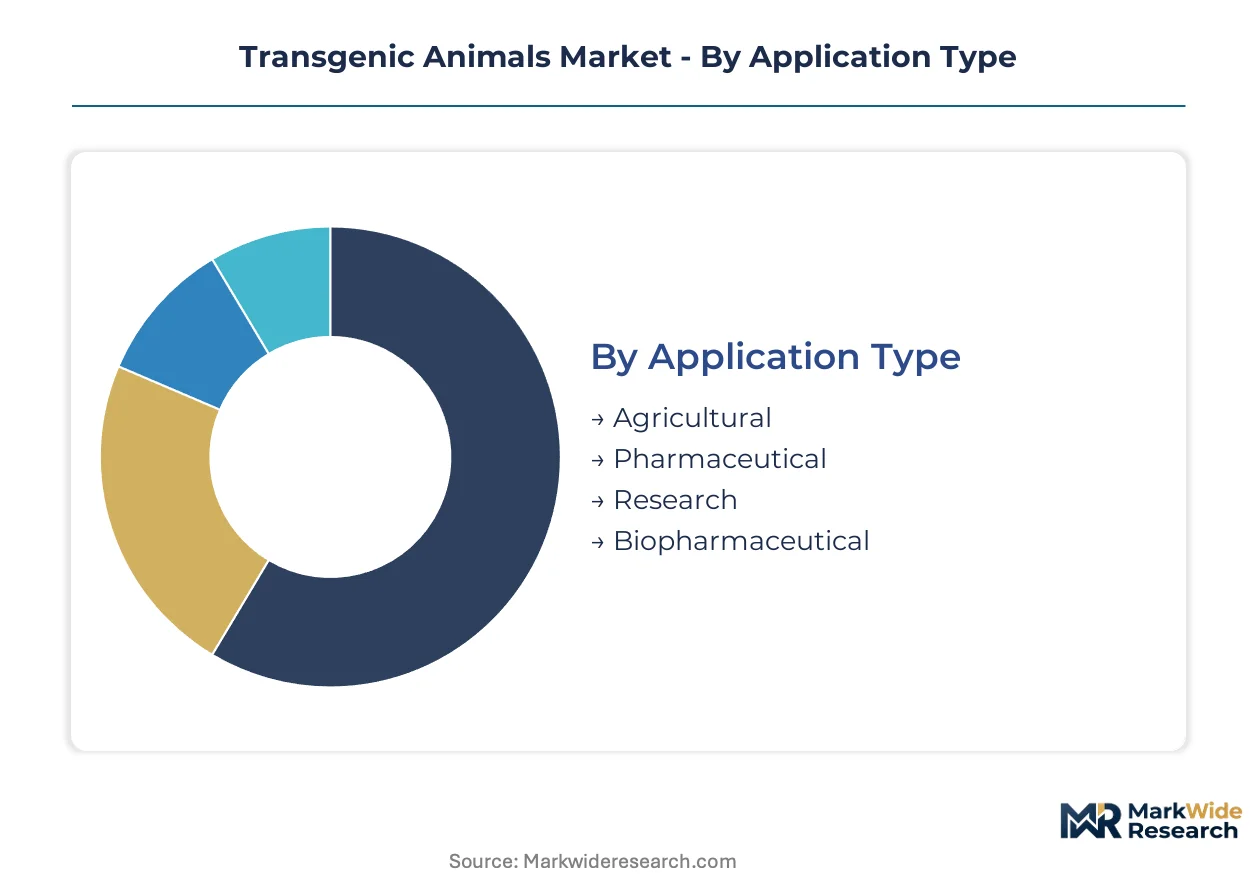
Segmentation in transgenic animals reveals how technical capabilities, species biology, and end-use economics partition value creation across the market. Each dimension carries distinct margin profiles, regulatory exposure, and competitive intensity that shape vendor positioning and investment allocation.
Application Type:
Mature therapeutic pipelines now absorb transgenic platforms as production assets rather than experimental tools, while emerging agricultural applications face commercialization friction from consumer resistance and extended safety reviews.
- Pharmaceutical:Recombinant protein harvesting from transgenic mammary glands or blood yields therapeutic antibodies and enzyme replacement therapies. Sponsors under FDA Center for Veterinary Medicine pathways fund development aggressively, treating living bioreactors as upstream manufacturing infrastructure.
- Biopharmaceutical:Contract manufacturing organizations embed transgenic goats and cattle into antibody discovery workflows, with Regeneron's VelociGene platform demonstrating how proprietary mouse lines accelerate therapeutic candidate generation through humanized immune systems.
- Agricultural:Trait development for disease resistance and feed efficiency in swine and cattle encounters EFSA novel food assessment complexity and member-state labeling disputes across European markets.
- Research:Academic consortia procure knockout and knockin murine lines for disease mechanism validation, with NIH grant density concentrating demand in Massachusetts and California research clusters.
Pharmaceutical applications retain volume leadership; biopharmaceutical platforms hold the steepest expansion curve.
Genetic Modification Method:
Cost tier separation runs from multiplexed CRISPR workflows at the premium end to established microinjection protocols serving large-animal applications where embryo handling infrastructure justifies higher per-unit expense.
- CRISPR:Programmable nuclease systems achieve germline transmission above fifteen percent in optimized protocols, with guide RNA multiplexing enabling simultaneous multi-locus editing. Machine learning platforms now predict off-target effects before embryo manipulation, compressing generation-to-phenotype intervals.
- Microinjection:Pronuclear DNA delivery into fertilized oocytes remains standard for bovine and porcine applications where surgical facilities exist. Variable integration efficiency creates cost unpredictability that agricultural developers factor into capital planning.
- Gene Targeting:Embryonic stem cell homologous recombination underpins conditional knockout strategies in mice, with established vector libraries and positive-negative selection cassettes supporting high-complexity allele design.
- Transposon-mediated:Sleeping Beauty and PiggyBac systems achieve stable integration with larger cargo capacity than viral vectors, finding niche application in transgene expression studies where random insertion patterns are acceptable.
CRISPR dominates new model generation; transposon-mediated approaches occupy specialized niches with constrained expansion prospects.
Animal Species:
Volume concentration favors mice due to breeding economics and genetic tractability, while margin pools deepen in large animals where bioreactor scale and protein yield per animal justify infrastructure intensity.
- Mice:Short gestation cycles and extensive genetic characterization support high-throughput model generation. Cyagen Biosciences and Charles River Laboratories compete on custom knockout turnaround speed, with CRISPR protocols now compressing timelines from months to weeks.
- Goats:ATryn from GTC Biotherapeutics demonstrated commercial viability of transgenic mammary gland protein secretion. Biocontainment infrastructure for caprine herds demands specialized HVAC and genetic isolation systems that strain mid-scale service provider capital allocation.
- Pigs:Organ size compatibility with human physiology positions porcine models for xenotransplantation research, though germline transmission volatility in microinjection protocols creates development cost uncertainty.
- Cattle:Extended generation intervals and embryo handling complexity limit research application, with activity concentrating in agricultural trait development for disease resistance and production efficiency.
Mice retain volume leadership; goats hold the steepest expansion curve among large-animal platforms.
End User:
Customer type determines procurement sophistication, with pharmaceutical sponsors negotiating milestone-based engagements while government agencies impose compliance documentation burdens that favor established vendors with regulatory affairs depth.
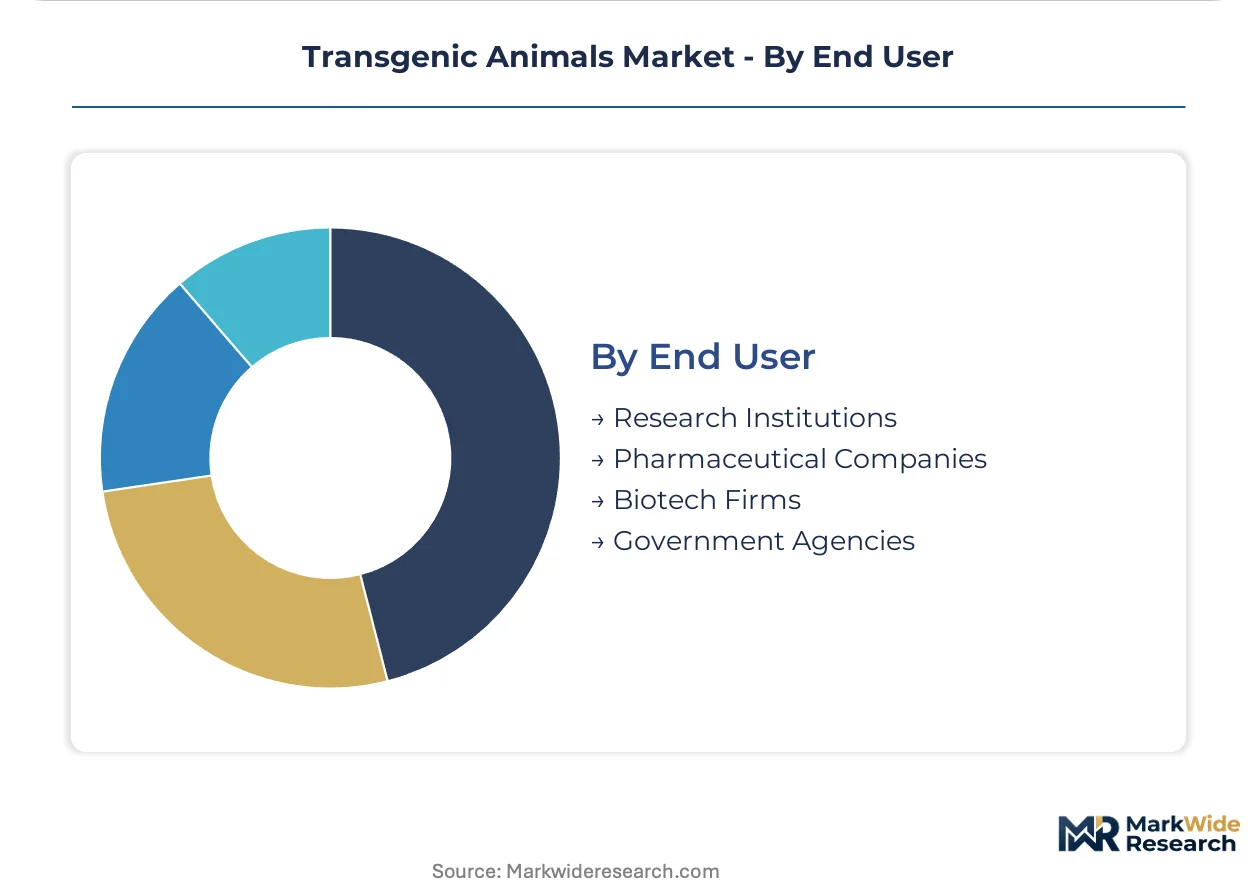
- Pharmaceutical Companies:Sponsors structure multi-year service agreements with intellectual property terms and milestone payment schedules tied to genotype confirmation and phenotypic validation. Consolidated model sourcing within single-jurisdiction breeding networks minimizes EMA cross-border transfer friction.
- Research Institutions:NIH-funded centers unbundle phenotyping from core acquisition, negotiating standardized baseline pathology pricing while competitively sourcing specialized behavioral or imaging studies. This disintermediation pressures service providers to demonstrate depth beyond genotype confirmation.
- Biotech Firms:Venture-backed developers prioritize speed-to-model over breeding scale, favoring contract research organizations with computational biology capabilities for guide RNA design and off-target prediction.
- Government Agencies:Public health and agricultural research programs impose chain-of-custody documentation and biocontainment certification requirements that favor vendors with established quality management systems.
Pharmaceutical companies retain volume leadership; biotech firms are expanding most quickly as venture funding concentrates on platform biologics developers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical sponsors and NIH-funded research institutions concentrate procurement power in the United States, with secondary demand nodes emerging in European biotech clusters and Asia-Pacific contract research expansion zones.
United States
FDA Center for Veterinary Medicine pathways provide explicit review frameworks for genetically engineered organisms, reducing regulatory uncertainty for Investigational New Animal Drug submissions. NIH grant density channels capital toward high-complexity model development pipelines. Massachusetts and California research clusters house specialized surgical facilities for pronuclear injection that service distributed academic consortia.
Germany
EMA guidelines on genetically modified organisms intersect with REACH chemical safety obligations, constraining how research institutions procure and dispose of transgenic biomaterials. Biobanking facilities in Germany dedicate specialized compliance personnel to chain-of-custody protocols for genetically engineered murine lines. Frankfurt and Munich metropolitan zones concentrate pharmaceutical preclinical program consolidation within single-jurisdiction breeding networks.
Switzerland
Swissmedic oversight provides regulatory clarity for genetically modified organism field trials that attracts contract research investment. Cantonal biosafety frameworks permit CRISPR-based germline editing protocols with compressed development timelines. Basel and Zurich regions host embryonic stem cell targeting infrastructure serving European pharmaceutical sponsors.
China
NMPA emerging guidelines for genetically engineered animals create pathway uncertainty that shapes domestic developer capital allocation. National biosafety frameworks for germline editing remain under institutional coordination between MIIT and agricultural regulators. Shanghai and Beijing biotech parks attract venture funding for platform biologics developers prioritizing speed-to-model capabilities.
India
CDSCO emerging biosafety frameworks for genetically modified organisms present first-mover positioning opportunities for contract research providers. Central Drugs Standard Control Organization institutional capacity for gene-editing policy distinction remains under development. Hyderabad and Bangalore research corridors concentrate computational biology expertise for guide RNA design and off-target prediction.
Transgenic Animals Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered service segments. Large contract research organizations leverage global breeding infrastructure to capture multi-year pharmaceutical sponsor agreements. Mid-scale providers differentiate on turnaround speed and vector design flexibility for venture-backed biotech firms. Dominant competitive moves include strategic partnerships for computational biology capability acquisition and geographic expansion into emerging regulatory jurisdictions.
Within the platform technology tier, Regeneron Pharmaceuticals and Charles River Laboratories exemplify divergent strategic positions. Regeneron anchors proprietary mouse model development for antibody discovery pipelines through its VelociGene platform architecture. Charles River Laboratories leverages global breeding infrastructure to service contract research demand across multiple continents with standardized quality management systems. Cyagen Biosciences occupies a specialist position competing on custom knockout turnaround speed and guide RNA multiplexing capabilities.
| Leading Market Players |
|---|
| Cyagen Biosciences |
| Regeneron Pharmaceuticals |
| Charles River Laboratories |
| OmniAb |
| Genus plc |
| Taconic Biosciences |
| Biocytogen |
| Ablexis |
| genOway |
| Others |
Value Chain & Pricing Dynamics
Regulatory chokepoint exposure at the FDA Center for Veterinary Medicine determines both pricing tier spreads and supply chain shape in transgenic animal services, as Investigational New Animal Drug submission complexity creates cost-plus contract indexation that separates premium validation-grade models from commoditized breeding lines.
Pricing Analysis
Cost-plus contracts with NIH grant indexation dominate pharmaceutical sponsor engagements, embedding breeding facility certification tier and phenotyping depth as price differentiation drivers. Pricing pressure stems from CRISPR protocol commoditization compressing custom knockout turnaround premiums. Academic consortia exhibit highest price sensitivity due to unbundled procurement, while biopharmaceutical sponsors prioritize speed-to-model over unit economics.
Supply Chain Analysis
Charles River Laboratories and Taconic Biosciences hold concentrated contract breeding capacity across Massachusetts, California, and Swiss cantons. Germline-qualified embryos and GMP-compliant biocontainment infrastructure anchor input dependencies. Single-source vulnerability runs through pronuclear microinjection surgical facilities clustered in select geographies. Distribution runs through direct pharmaceutical sponsor agreements and NIH-funded institutional procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery driven by CRISPR multiplexing protocol maturation, which resets capacity utilization and pricing power across contract research tiers.
For Market Incumbents: Build regulatory affairs depth as a moat against emerging entrants lacking FDA submission experience. Deepen backward integration into guide RNA design software to capture computational biology margins. Expand biocontainment capacity in India CDSCO-aligned jurisdictions to preempt first-mover positioning by regional challengers.
For New Entrants and Emerging Players: Establish a beachhead in agricultural trait development for disease-resistant swine, where germline transmission volatility has deterred incumbent investment. Target European biotech clusters seeking single-jurisdiction breeding networks to circumvent EMA cross-border transfer friction. Lead with base editing convergence capabilities as differentiated technical positioning.
For Investors and Strategic Acquirers: Computational biology-enabled contract research specialists with established NIH grant relationships represent priority acquisition archetypes. Long-term viability hinges on site-directed modification reclassification unlocking streamlined approval pathways. Monitor CDSCO institutional capacity development as inflection signal for Indian market entry timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway Investment | FDA Center for Veterinary Medicine pre-submission meetings reduce Investigational New Animal Drug review uncertainty for sponsors. |
| Computational Biology Capability Acquisition | Machine learning platforms for guide RNA design compress generation-to-phenotype intervals and capture premium pricing. |
| Geographic Expansion into India | CDSCO emerging biosafety frameworks create first-mover positioning for GMP-compliant breeding facilities in Hyderabad corridors. |
| Backward Integration into Vector Design | In-house production of CRISPR reagents reduces cost unpredictability and protects margins against reagent supplier concentration. |
| Phenotyping Service Unbundling Response | Demonstrating behavioral and imaging study depth beyond genotype confirmation defends against NIH institutional procurement compression. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with transgenic service provider executives, pharmaceutical development leads, and NIH grant administration officers; and secondary validation against FDA Investigational New Animal Drug filings, EMA genetically modified organism assessment reports, and NIH RePORTER grant databases. Bottom-up model generation triangulated with top-down market sizing across application type, species, and end-user segments.
Forecast inputs considered CRISPR protocol adoption curves, germline transmission efficiency improvements, and regulatory reclassification scenarios across the projection horizon. Segmentation dimensions modeled include application type, genetic modification method, animal species, and end-user procurement sophistication. CAGRs derived from multivariate regression incorporating NIH funding density, FDA submission volumes, and contract research organization capacity expansion announcements.
Sensitivities concentrate around gene-editing policy distinctions between transgenic and site-directed modification classifications, CDSCO framework finalization timelines, and EMA REACH chemical safety obligation enforcement intensity. Quarterly review of FDA guidance document releases, NIH funding opportunity announcements, and European Court of Justice genetically modified organism rulings is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
India Biomass Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market
Bio-Agriculture
Animal Eubiotics Market
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
Global Biofortification Market
Bio-Agriculture
India Biocontrol Agents Market