
 Plant-Based Biologics Market | 2026-2036
Plant-Based Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Plant-Based Biologics Market Outlook
Recombinant protein expression in Nicotiana benthamiana is broadening the cost structure for monoclonal antibody production relative to CHO cell platforms. Medicago leverages proprietary virus-like particle technology to anchor vaccine manufacturing in Canada. Kentucky Bioprocessing sustains large-scale transient expression capabilities that dominate contract production for multinational pharmaceutical clients. Eleva differentiates through moss-based expression systems that occupy a specialized tier in the European supply base.
Plant-based biologics comprise recombinant proteins, antibodies, enzymes, and vaccines produced through transgenic or transient expression in whole plants or plant cell cultures, typically yielding glycoproteins with plant-specific glycosylation patterns that require humanization for therapeutic use. Vaccine production through plant cell culture leads in current output volume given established influenza and COVID-19 platform precedents, while antibody segments capture concentrated margin pools due to higher purity requirements and longer development cycles. Gene editing applications within CRISPR-modified tobacco lines represent the fastest-expanding technology dimension as developers seek streamlined glycoengineering pathways.
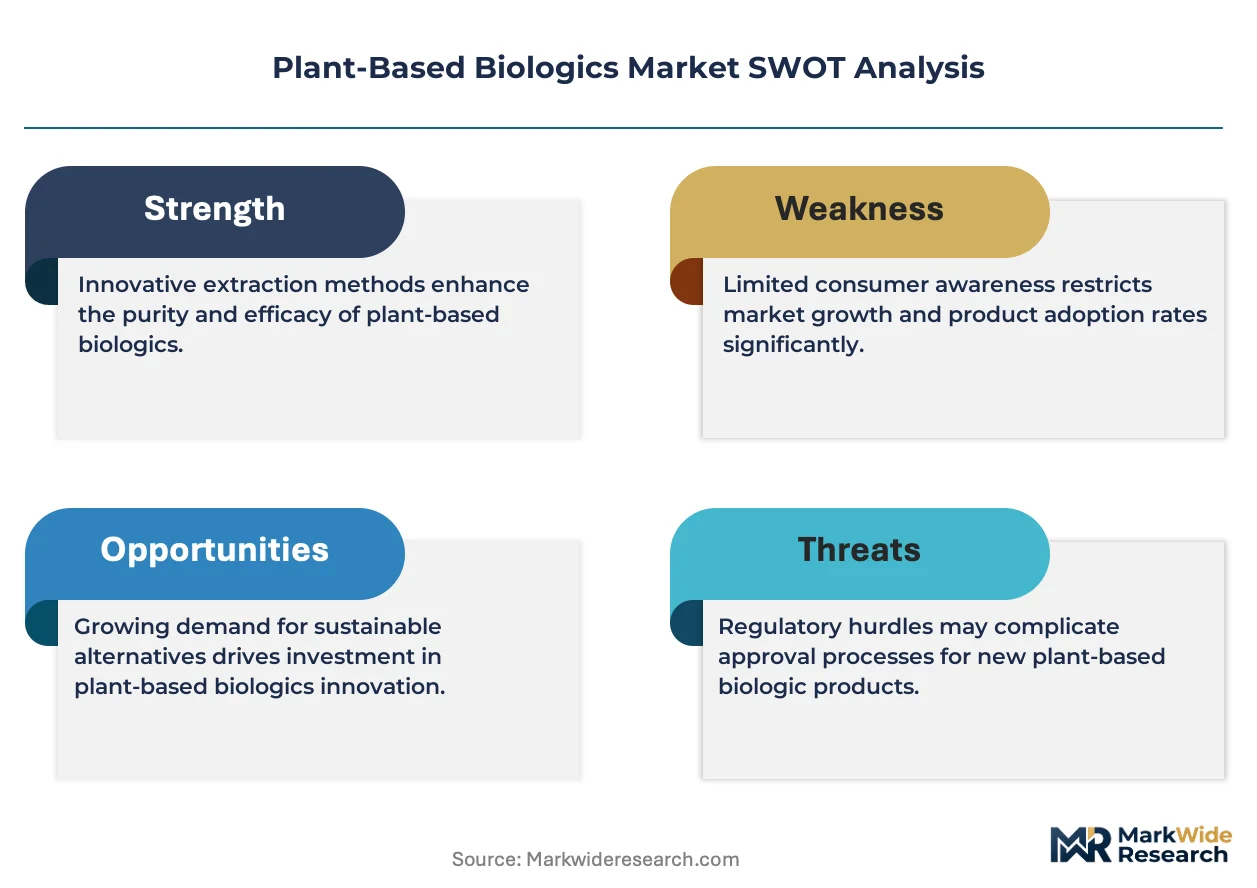
FDA biosimilar guidelines and EMA's Good Manufacturing Practice standards for biologicals jointly shape facility qualification requirements and batch release protocols for plant-derived therapeutics. The EU Green Deal's pharmaceutical sustainability directives are pressuring manufacturers to document carbon intensity advantages of plant systems over mammalian cell culture. South Korea's MFDS has issued accelerated review pathways for plant-made biologics, expanding Asian market access. Stakeholders must monitor how regulatory harmonization across FDA, EMA, and MFDS frameworks influences cross-border technology licensing and facility investment decisions.
Market Dynamics
Pharmaceutical procurement departments are systematically diversifying expression platforms away from mammalian cell dependence, driven by carbon accounting mandates and batch-to-batch variability reduction targets that favor plant-based glycoengineering standardization.
Growth Catalysts
- EMA biosimilar pathway acceleration:The European regulator's streamlined comparability protocols for plant-derived antibodies reduce facility qualification timelines by standardizing glycoprofile acceptance criteria.
- Vaccine platform precedents:Influenza and COVID-19 manufacturing success in Nicotiana benthamiana validates transient expression for pandemic response stockpiling.
- Carbon intensity documentation:EU Green Deal pharmaceutical sustainability directives create procurement preference for plant systems over energy-intensive mammalian bioreactors.
Market Restraints
- Glycoengineering capex concentration:CRISPR-modified tobacco line development requires dedicated R&D infrastructure that concentrates among contract development organizations in Germany and South Korea.
- Humanization bottleneck:Plant-specific glycosylation patterns necessitate downstream processing modifications that extend batch release timelines relative to CHO platforms.
- Regulatory fragmentation:Divergent FDA and MFDS documentation requirements for plant-made biologics create cross-border licensing friction for multinational sponsors.
Strategic Opportunities
- Indian CDMO capacity expansion:CDSCO's emerging plant-based biologics guidance creates first-mover positioning for domestic contract manufacturers serving export markets.
- Moss-based enzyme production:Eleva's Physcomitrella patents demonstrate specialized tier viability for industrial enzymes requiring complex post-translational modifications.
- Gene editing convergence:CRISPR glycoengineering combined with automated transient expression protocols enables rapid antibody variant screening for personalized medicine applications.
Industry Challenges
- Bioprocessing talent scarcity:Plant molecular farming expertise concentrates among academic labs and specialized CDMOs, constraining scale-out for in-house pharmaceutical manufacturing.
- Batch consistency certification:FDA's evolving biosimilar immunogenicity assessment standards create uncertainty in plant-derived therapeutic protein approval timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plant-Based Biologics Market |
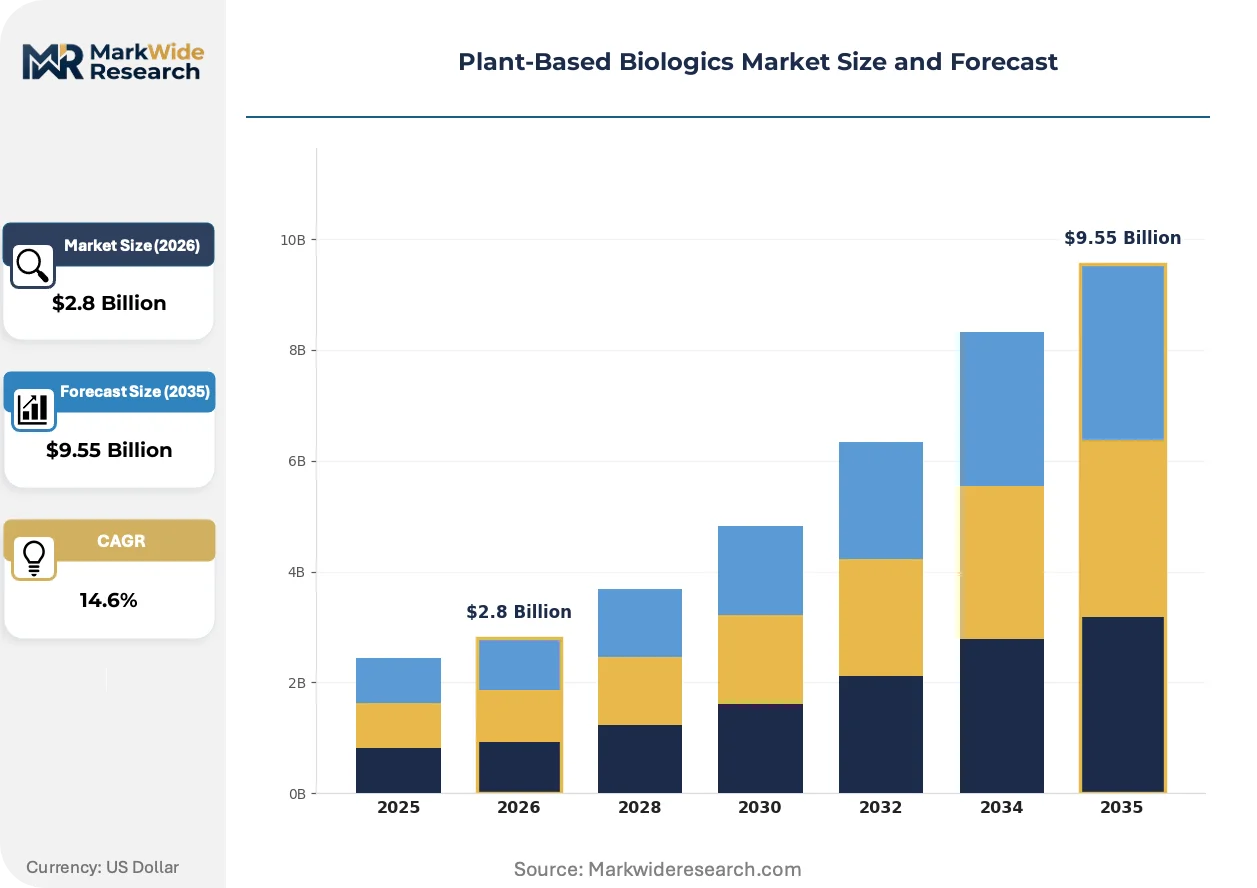
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vaccine, Antibody, Enzyme, Hormone Application: Therapeutics, Diagnostics, Research, Agriculture End User: Pharmaceutical Companies, Biotech Firms, Research Institutions, Agricultural Producers Technology: Plant Cell Culture, Gene Editing, Protein Engineering, Fermentation |
| Companies Covered | Medicago, iBIO, Leaf Expression Systems, PlantForm, Eleva, G+Flas Life Sciences, Kentucky Bioprocessing, Angany, Protalix BioTherapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plant-Based Biologics Market Strategic Shifts
Automation of glycoprofile engineering and regulatory harmonization efforts are compressing development cycles while procurement departments rewrite supplier qualification criteria around platform carbon intensity.
Automated transient expression systems are automating seed-to-harvest workflows for Nicotiana benthamiana, enabling contract manufacturers to reduce batch cycle times from weeks to days. Multinational pharmaceutical sponsors are adopting these platforms for rapid antibody prototyping. The technology is automating capacity allocation decisions that previously required manual greenhouse scheduling and harvest timing optimization.
REACH-aligned sustainability disclosure requirements are forcing European pharmaceutical manufacturers to document Scope 3 emissions across expression platform supply chains. The EU Green Deal's pharmaceutical sector annex specifically targets biologics manufacturing energy intensity. German and French sponsors are responding by mandating plant-based alternatives in contract development organization RFPs where glycoprofile equivalence can be demonstrated.
Buyers are consolidating antibody production contracts with CDMOs offering integrated plant-based platforms rather than maintaining dual-qualified mammalian and plant supplier bases. This channel compression eliminates redundant facility audit costs but increases dependence on Kentucky Bioprocessing and comparable transient expression specialists. The pattern is most visible among US-based biotechnology sponsors seeking pandemic response manufacturing redundancy.
Plant-Based Biologics Market Segmentation
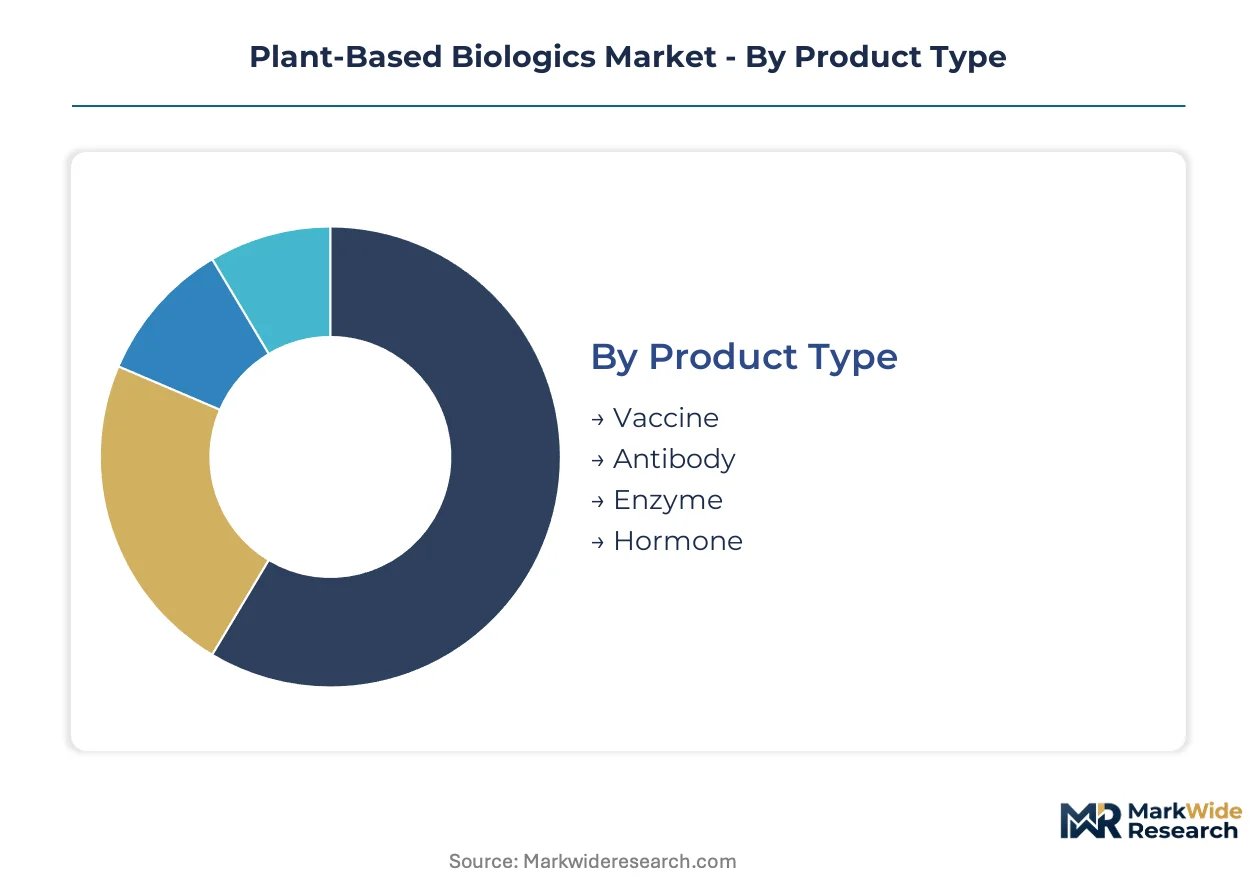
Segmentation in plant-based biologics reveals how procurement criteria diverge across therapeutic categories and technical platforms. Buyers prioritize glycoengineering precision for antibody contracts while accepting standardized profiles for agricultural enzymes. Platform selection directly shapes facility investment timelines and regulatory pathway complexity.
Product Type:
Procurement departments weight batch release timelines against purity requirements when selecting expression platforms for different therapeutic classes.
- Vaccine:Virus-like particle platforms in Nicotiana benthamiana dominate pandemic stockpiling contracts due to rapid scale-up. Demand concentrates in government procurement agencies across the United States, Canada, and South Korea seeking manufacturing redundancy beyond egg-based and mammalian systems.
- Antibody:Monoclonal production requires CRISPR-modified glycoengineered lines to eliminate plant-specific beta-1,2-xylose residues. German and US sponsors prioritize CDMOs with integrated humanization capabilities to compress comparability study timelines for FDA and EMA submissions.
- Enzyme:Industrial applications tolerate plant glycosylation patterns, reducing downstream processing costs for agricultural and food-grade outputs.
- Hormone:Insulin and growth factor production remains nascent, constrained by endocrine potency validation requirements.
Volume sits with Vaccine; growth tilts toward Antibody.
Application:
Margin concentration varies sharply across use cases, with therapeutic applications commanding premium pricing for cGMP compliance while research segments prioritize cost per milligram.
- Therapeutics:Injectable proteins require full validation of immunogenicity profiles and glycan consistency. US and European sponsors dominate contract value, driven by biosimilar development pipelines targeting TNF-alpha and HER2 pathways.
- Diagnostics:Reagent-grade antibodies for immunoassays accept broader glycan heterogeneity. Asian diagnostic manufacturers source heavily from South Korean CDMOs with automated transient expression systems.
- Research:Preclinical antibody variants prioritize speed over humanization, feeding into academic screening programs.
- Agriculture:Veterinary vaccines and feed enzymes operate outside pharmaceutical GMP frameworks, lowering barrier to entry for platform adoption.
Revenue concentrates in Therapeutics; expansion accelerates fastest in Diagnostics.
End User:
Internalization versus outsourcing decisions split the customer base based on pipeline scale and glycoengineering IP ownership.
- Pharmaceutical Companies:Multinational sponsors maintain dual-qualified mammalian and plant supplier bases for pandemic redundancy. Procurement teams in Basel, Boston, and Seoul mandate carbon intensity documentation under EU Green Deal and corporate net-zero commitments.
- Biotech Firms:Venture-backed developers lack capital for dedicated bioreactor infrastructure, concentrating demand on Kentucky Bioprocessing and comparable transient expression specialists with rapid antibody prototyping capabilities.
- Research Institutions:Academic labs access subsidized greenhouse facilities through technology transfer agreements with Medicago and Fraunhofer IME.
- Agricultural Producers:Seed companies integrate plant-made veterinary vaccines into integrated health management programs.
Contract value aggregates with Pharmaceutical Companies; Biotech Firms drive platform adoption velocity.
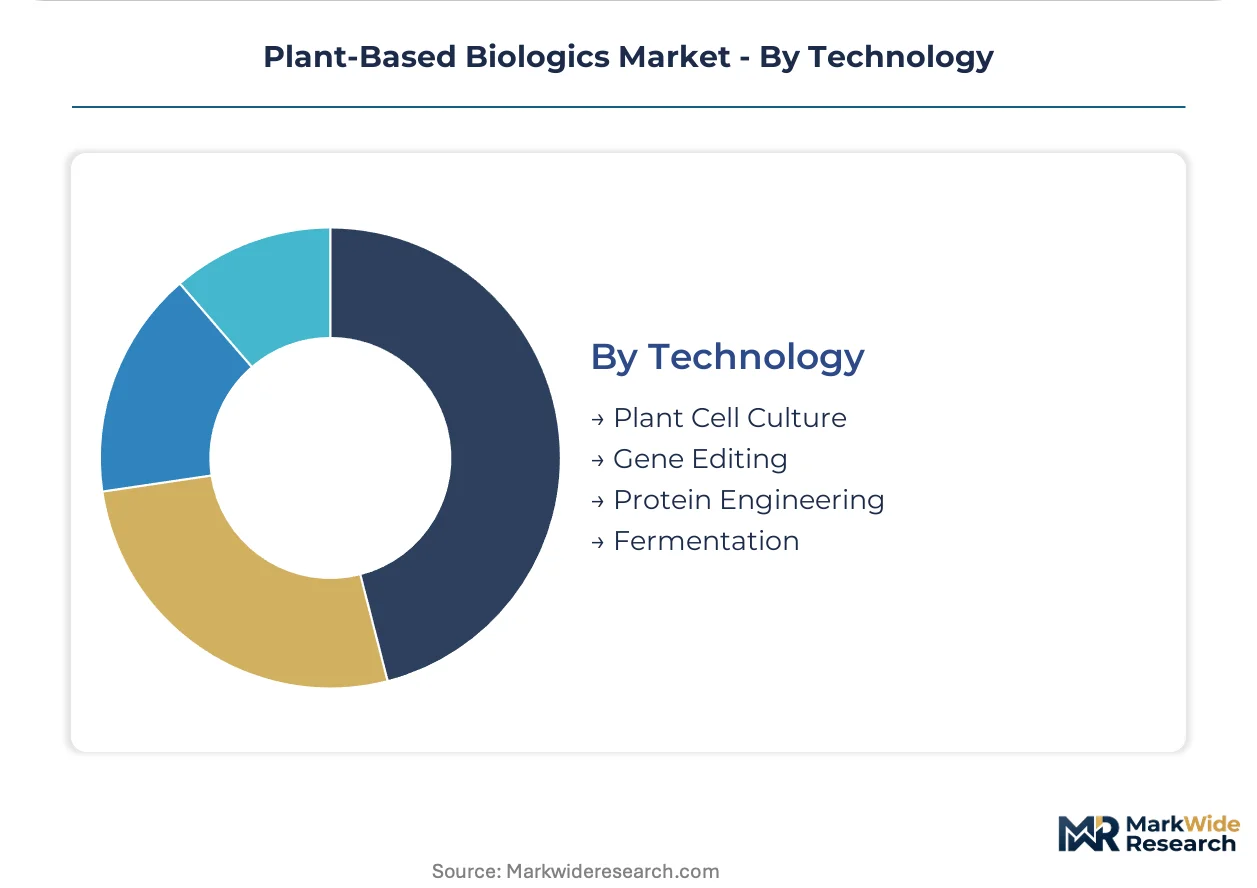
Technology:
Capital intensity and timeline flexibility determine platform selection across development phases.
- Plant Cell Culture:Moss and duckweed systems enable contained production with simplified extraction. Eleva's Physcomitrella patents anchor European capacity for complex post-translational modifications.
- Gene Editing:CRISPR glycoengineering in tobacco lines streamlines humanization pathways, attracting R&D investment from German and South Korean CMOs.
- Protein Engineering:Computational design optimizes codon usage and signal peptides for Nicotiana expression.
- Fermentation:Plant cell fermentation in bioreactors bridges whole-plant and mammalian cell culture methodologies.
Installed capacity favors Plant Cell Culture; R&D investment flows toward Gene Editing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contract development organizations in the United States, Germany, and South Korea capture the majority of plant-based biologics procurement value, reflecting concentrated pharmaceutical sponsor demand for transient expression capacity and glycoengineering expertise.
United States
Kentucky Bioprocessing anchors North American transient expression capacity, serving multinational sponsors seeking pandemic manufacturing redundancy. FDA biosimilar guidelines accelerate facility qualification timelines for plant-derived antibodies. The Kentucky-Ohio corridor concentrates automated greenhouse infrastructure and CRISPR-modified tobacco line development.
Germany
Fraunhofer IME and Eleva anchor European moss-based and whole-plant expression capacity for complex post-translational modifications. EMA streamlined comparability protocols reduce glycoprofile acceptance criteria uncertainty for sponsors. The Aachen-Cologne cluster integrates academic technology transfer with industrial-scale transient expression facilities.
South Korea
G+Flas Life Sciences and domestic CDMOs scale automated Nicotiana benthamiana platforms for diagnostic reagent and antibody prototyping contracts. MFDS accelerated review pathways expand Asian market access for plant-made biologics. The Seoul-Daejeon corridor concentrates gene editing R&D infrastructure and pharmaceutical sponsor co-development programs.
Canada
Medicago's Quebec facilities demonstrate virus-like particle platform viability for government pandemic stockpiling contracts. Health Canada aligns with FDA-EMA trilateral regulatory harmonization initiatives for plant-derived vaccines. The Quebec City region anchors North American influenza and COVID-19 manufacturing precedents.
India
CDSCO's emerging plant-based biologics guidance creates first-mover positioning for domestic contract manufacturers targeting export markets. Regulatory clarity gaps persist for glycoengineered therapeutic proteins versus research-grade outputs. The Hyderabad-Bengaluru corridor attracts technology licensing from German and US platform developers seeking cost-advantaged scale-out.
Plant-Based Biologics Market Competitive Environment
Capacity expansion dominates the current landscape as contract development organizations race to install automated transient expression systems and CRISPR-modified tobacco lines. The vendor base stratifies into three tiers: multinational CDMOs with integrated glycoengineering capabilities, regional specialists in moss or duckweed platforms, and academic spin-offs commercializing proprietary vector systems. Strategic archetypes include platform licensors monetizing IP through technology transfer, scale operators capturing government pandemic stockpiling contracts, and boutique providers occupying specialized enzyme production niches. Competitive intensity centers on facility qualification speed and carbon intensity documentation for EU Green Deal compliance.
Among North American scale operators, Kentucky Bioprocessing exemplifies the contract manufacturing archetype with large-scale transient expression infrastructure serving pharmaceutical sponsors. Medicago occupies a distinct position as a platform developer with government-backed vaccine manufacturing precedents. Eleva represents the European specialist tier, anchoring moss-based expression capacity for complex post-translational modifications. These three entities collectively illustrate how geographic clustering around regulatory hubs and academic technology transfer networks shapes competitive positioning.
| Leading Market Players |
|---|
| Medicago |
| iBIO |
| Leaf Expression Systems |
| PlantForm |
| Eleva |
| G+Flas Life Sciences |
| Kentucky Bioprocessing |
| Angany |
| Protalix BioTherapeutics |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal pharmaceutical sustainability directives function as a gatekeeping mechanism that restricts qualified supply to CDMOs with documented carbon intensity advantages, simultaneously enabling premium-tier pricing for facilities holding EMA-validated glycoengineering credentials.
Pricing Analysis
Volume concentrates in vaccine contracts with standardized virus-like particle platforms, while margins accrue to antibody segments demanding CRISPR-modified glycoengineered lines and downstream humanization processing. Three-tier pricing structure across premium, standard, and economy levels separates cGMP-validated therapeutic production from research-grade outputs and agricultural enzyme tiers. Cost compression in diagnostic reagent contracts is intensifying because South Korean CDMOs with automated transient expression systems are scaling capacity faster than quality-adjusted demand expansion. Biotech firms without captive bioreactor infrastructure exhibit highest price sensitivity, whereas multinational pharmaceutical sponsors prioritize glycoprofile equivalence and batch consistency over unit cost.
Supply Chain Analysis
Regional distribution centers in the Kentucky-Ohio corridor, the Aachen-Cologne cluster, and the Seoul-Daejeon corridor anchor hub-and-spoke patterns for Nicotiana benthamiana biomass and CRISPR-modified tobacco line inputs. Concentrated supply in the United States, Germany, and South Korea draws from proprietary seed stocks, automated greenhouse infrastructure, and gene editing R&D platforms. Single-source vulnerability runs through Kentucky Bioprocessing's dominance in large-scale transient expression capacity serving pandemic stockpiling contracts. Distribution runs through contract development organizations with integrated glycoengineering capabilities rather than discrete raw material suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EMA biosimilar pathway acceleration constructs a cost-of-compliance moat that favors incumbent CDMOs with validated glycoengineering infrastructure over aspirants lacking facility qualification timelines.
For Market Incumbents: To counter regulatory fragmentation across FDA and MFDS documentation requirements, incumbent CDMOs should pursue backward integration into CRISPR-modified tobacco line development and expand automated transient expression capacity in the Kentucky-Ohio corridor to capture pandemic manufacturing redundancy contracts. For New Entrants and Emerging Players: Gene editing convergence with automated transient expression protocols offers a technology-first wedge for entrants targeting the diagnostics reagent segment, where Asian manufacturers source heavily from South Korean CDMOs and glycan heterogeneity tolerance reduces humanization barriers. For Investors and Strategic Acquirers: CDSCO's issuance of formal plant-based biologics guidance is the leading indicator that Indian contract manufacturing capacity will achieve export-market legitimacy, signaling long-term viability for platform licensors with technology transfer agreements in the Hyderabad-Bengaluru corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Transient Expression Scale-Up | Kentucky Bioprocessing's infrastructure investments compress batch cycle times from weeks to days for antibody prototyping contracts. |
| CRISPR Glycoengineering Patent Licensing | Fraunhofer IME's technology transfer agreements enable moss-based complex post-translational modification capabilities in European CDMOs. |
| EMA Facility Qualification Fast-Track | Streamlined comparability protocols reduce glycoprofile acceptance criteria uncertainty for German sponsors submitting biosimilar applications. |
| Carbon Intensity Documentation Compliance | EU Green Deal pharmaceutical sector annex mandates Scope 3 emissions disclosure across biologics manufacturing supply chains. |
| MFDS Accelerated Review Pathway Utilization | South Korea's regulatory framework expands Asian market access for plant-made biologics through reduced approval timelines. |
Study Parameters
Multi-period observation of EMA biosimilar submission volumes, FDA facility inspection outcomes, and CDSCO guidance development anchored the trend analysis, supplemented by interviews with contract development organization executives, regulatory affairs leads at multinational pharmaceutical sponsors, greenhouse operations managers, and gene editing platform specialists. Secondary validation drew from FDA biosimilar guidance documents, EMA Good Manufacturing Practice standards, MFDS accelerated review pathway announcements, ClinicalTrials.gov plant-made biologics entries, and EU Green Deal pharmaceutical sector annex disclosures. Bottom-up capacity assessments across Kentucky Bioprocessing, Fraunhofer IME, and G+Flas Life Sciences facilities triangulated against top-down pharmaceutical procurement survey data.
Segment-weighting across product type, application, end user, and technology dimensions shaped the analytical framework, with therapeutic antibody contracts, diagnostic reagent volumes, and vaccine platform precedents receiving distinct growth trajectory assumptions. CAGRs were derived from facility expansion announcements, technology licensing velocity, and regulatory pathway timeline compression across the projection horizon. Industry-specific forecast inputs included CRISPR glycoengineering R&D investment flows and automated transient expression system deployment rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of regulatory harmonization failure between FDA, EMA, and MFDS frameworks or breakthrough mammalian cell culture efficiency gains that erode plant system carbon advantages. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Europe Biopesticides Market
Bio-Agriculture
Bio-Based Levulinic Acid Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
Bovine High-Mountain Disease Market
Bio-Agriculture
US Bio Pesticides Market
Bio-Agriculture
North America Biological Organic Fertilizer Market
Bio-Agriculture
North America Biocontrol Agents Market
Bio-Agriculture
Biostimulants Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
South America Biofertilizers Market
Bio-Agriculture
Biopesticides Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Plant Based Biosurfactants Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
Middle East and Africa Animal Genetics Market
Bio-Agriculture
Europe Biostimulants Market