
 United States Biocontrol Agents Market | 2026-2036
United States Biocontrol Agents Market Size, Share, and Industry Trends Forecast 2026-2036
United States Biocontrol Agents Market Insights
Market Context
The Federal Insecticide, Fungicide, and Rodenticide Act is pivoting registration economics toward biological active ingredients with reduced data requirements and shorter review cycles. Koppert Biological Systems Inc. leverages its North American production infrastructure to sustain consistent supply chains for beneficial nematode formulations. Bioworks Inc. anchors its competitive position through proprietary Trichoderma manufacturing platforms that command premium placement in specialty crop channels. Arizona Biological Control Inc. specializes in regionally adapted parasitoid rearing programs that dominate integrated pest management contracting across the Southwest.
Technical Definition and Segment Structure
Biocontrol agents comprise living organisms or naturally derived compounds that suppress pest populations through predation, parasitism, competition, or antibiosis, typically formulated with colony-forming unit specifications exceeding 10^8 CFU per gram for microbial products and requiring cold-chain distribution to preserve viability. These agents serve commercial agriculture, horticulture, and forestry sectors as alternatives or complements to synthetic chemistries, with microbial formulations containing Bacillus subtilis, Trichoderma harzianum, and Beauveria bassiana commanding the dominant share of active ingredient volumes. The application dimension shows agriculture absorbing the majority of unit demand while horticulture generates disproportionate margin contribution through greenhouse and nursery protocols. Distribution channel dynamics reveal direct sales sustaining the deepest technical relationships with large-scale farming operations, whereas online retail competes aggressively for garden center and smallholder access.
Regulatory Framework and Outlook
The EPA Office of Pesticide Programs coordinates biopesticide registration with USDA organic certification standards and state-level department of agriculture enforcement, creating a multi-layered compliance architecture that rewards early regulatory engagement. FIFRA Section 25(b) minimum risk exemptions and the Plant Incorporated Protectants framework further differentiate pathway economics for microbial versus biochemical modalities. Stakeholders must monitor emerging state-level pollinator protection statutes and resistance management mandates that will reshape product labeling and buffer zone requirements.
Market Dynamics
The EPA's biopesticide registration streamlining under FIFRA is compressing commercialization timelines from 36 months to 18 months, forcing incumbents to accelerate formulation development while opening entry points for specialized microbial suppliers.
Growth Catalysts
- Precision Agriculture Integration:Variable-rate application systems in Midwest corn-soy operations now accommodate Bacillus-based seed treatments as standard inputs, embedding biocontrol into automated planting protocols.
- California Water Quality Mandates:The State Water Resources Control Board's agricultural runoff restrictions are phasing out synthetic fungicides in specialty crop districts, redirecting vineyard and orchard investment toward Trichoderma programs.
- USDA Organic Certification Thresholds:The National Organic Program's 95% organic ingredient requirement for processed foods is cascading demand backward into input supply chains, prioritizing microbial inoculants over chemical alternatives.
Market Restraints
- Live Culture Cold-Chain Costs:Refrigerated distribution from production facilities in Iowa and California to end-use points in Florida and Washington imposes 15-20% logistics premiums versus ambient synthetic chemistries.
- Strain Patent Concentration:Proprietary Trichoderma and Beauveria isolates remain concentrated among three domestic germplasm repositories, creating licensing bottlenecks for second-tier formulators.
- EPA Resistance Management Labeling:Mandatory rotation requirements with synthetic modes-of-action extend sales cycles and complicate portfolio architecture for single-active-ingredient suppliers.
Strategic Opportunities
- Texas High Plains Cotton Belt:Boll weevil eradication zones transitioning to integrated pest management present open territory for beneficial nematode distribution partnerships with regional cooperatives.
- Controlled Environment Agriculture:Vertical farming operations in New York and Illinois are establishing biocontrol-first protocols without legacy chemical infrastructure, enabling clean-sheet microbial program design.
- Biostimulant-Biopesticide Convergence:Dual-function formulations combining phosphate-solubilizing bacteria with antifungal activity qualify for streamlined EPA registration while commanding premium positioning in specialty channels.
Industry Challenges
- Microbiologist Talent Scarcity:Fermentation scale-up expertise for maintaining 10^8 CFU viability through downstream processing remains concentrated among a handful of agricultural universities and former pharmaceutical operators.
- State-Level Pollinator Buffer Mandates:Emerging requirements in Oregon and Washington for 25-foot untreated zones around flowering crops complicate aerial and ground application logistics for broad-acre row-crop contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Biocontrol Agents Market |
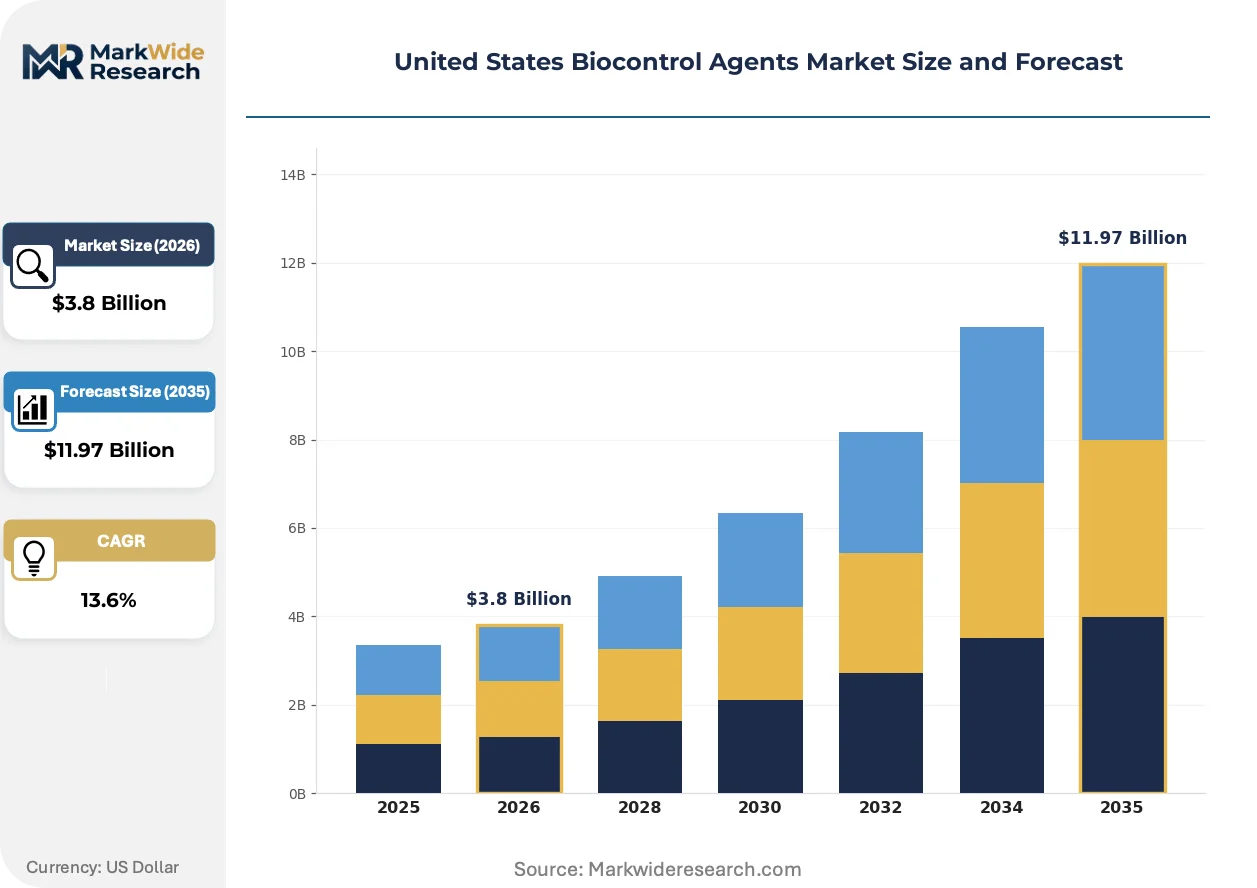
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.97 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Chemical, Botanical, Natural Application: Agriculture, Horticulture, Forestry, Landscape End User: Farmers, Agricultural Cooperatives, Garden Centers, Researchers Distribution Channel: Direct Sales, Online Retail, Wholesale, Others |
| Companies Covered | Arizona Biological Control Inc., Beneficial Insectary Inc., BioBee Sde Eliyahu Ltd., Bioline AgroSciences Ltd., Koppert Biological Systems Inc., Bioworks Inc., Andermatt Group AG, Arbico Organics, Applied Bio-Nomics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Biocontrol Agents Market Trends and Innovations
Formulation chemistry advances are resolving the historical trade-off between microbial shelf stability and field efficacy, enabling biocontrol products to compete directly with synthetic chemistries on application convenience and storage flexibility.
RNA interference technology is unifying pest-specific lethality with environmental compatibility. Greenhouse tomato and pepper operations in Florida are piloting sprayable dsRNA formulations against whitefly and thrips at commercial scale. The technology is unifying previously separate biological and chemical application windows into single-pass protocols.
The EPA's Pesticide Registration Improvement Act reauthorization is embedding biopesticide performance metrics into federal procurement standards. Federal land management agencies must now document biological control attempts before synthetic chemical authorization on Bureau of Land Management and National Forest acreage. Western rangeland restoration projects in Colorado and Montana are restructuring vendor qualification around these new compliance documentation requirements.
Specialty crop growers are consolidating input purchasing through regional horticultural cooperatives that bundle biocontrol with fertility and irrigation services. California's Central Valley nut and stone fruit cooperatives now specify microbial program performance guarantees rather than product volumes, transferring efficacy risk from grower to supplier. This restructuring is most visible in almond operations facing hull rot pressure and seeking integrated solutions across the April-October growing window.
United States Biocontrol Agents Market Segmentation
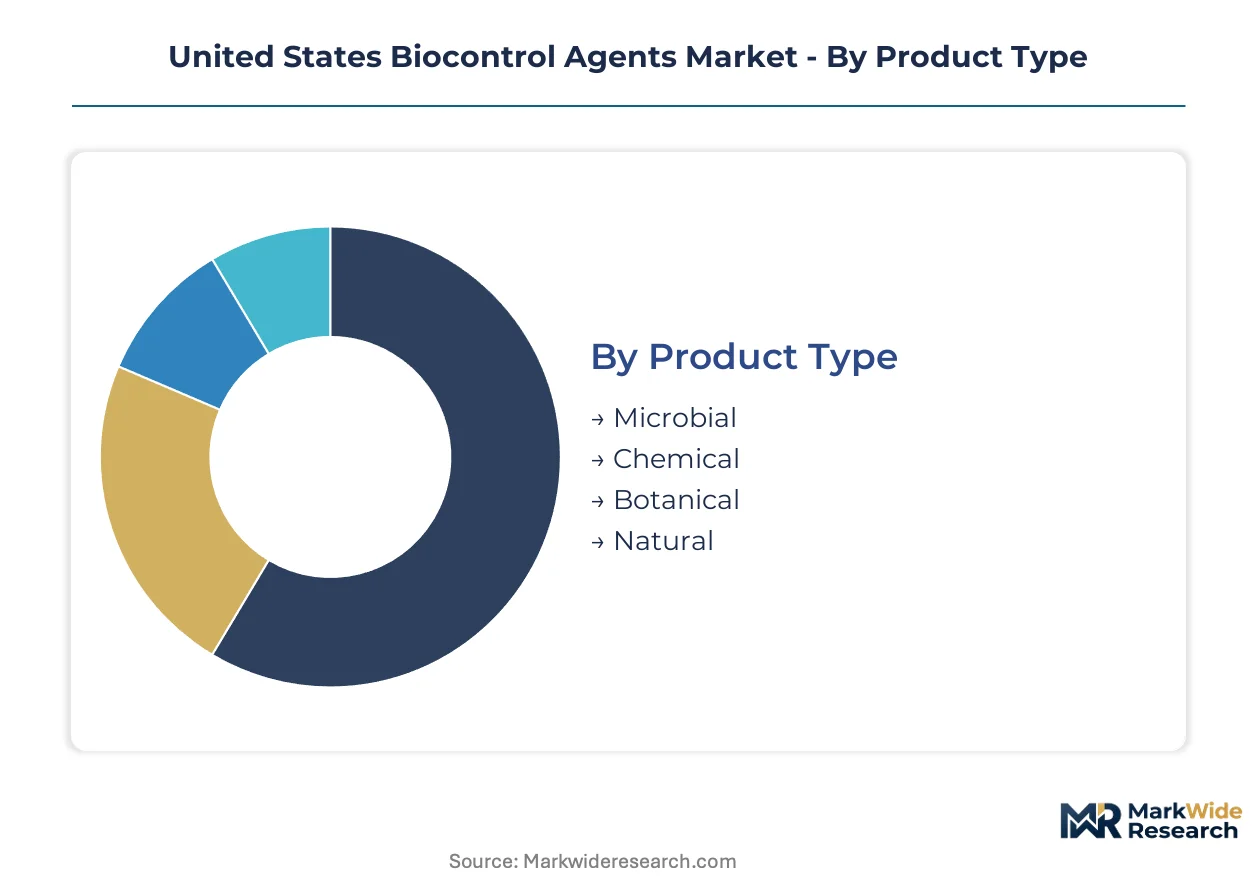
Biocontrol agent purchasing decisions hinge on formulation viability requirements, application scale economics, and regulatory compliance pathways that vary sharply across crop systems and buyer types. Segmentation reveals where margin pools concentrate and which technical specifications command premium positioning.
Product Type:
Buyers prioritize CFU stability specifications and cold-chain feasibility when selecting active ingredient categories, with shelf-life tolerance driving substitution patterns between microbial and non-living alternatives.
- Microbial:Living formulations containing Bacillus subtilis, Trichoderma harzianum, and Beauveria bassiana dominate commercial volumes. Midwest corn-soy operations embed these into precision seed treatment protocols as EPA registration timelines compress. Cold-chain distribution from Iowa production hubs to Florida end-use points imposes logistics premiums that shape procurement consolidation.
- Chemical:Synthetic pheromones and insect growth regulators occupy intermediate positioning between biological and conventional chemistries. California specialty crop districts facing State Water Resources Control Board runoff mandates are redirecting vineyard investment toward these reduced-risk alternatives.
- Botanical:Plant-derived compounds including pyrethrin and azadirachtin extracts serve organic-certified operations with immediate knockdown requirements. Demand concentrates in greenhouse tomato and pepper systems where residue tolerances are strictest.
- Natural:Unprocessed predator and parasitoid organisms including beneficial nematodes and regionally adapted wasp species dominate integrated pest management contracting. Arizona Biological Control's Southwest rearing programs anchor supply for this segment.
Microbial leads on scale; botanical leads on momentum as organic certification thresholds cascade backward through supply chains.
Application:
Application context determines formulation complexity, with open-field row crops tolerating less refined delivery systems than controlled environments where precision application infrastructure exists.
- Agriculture:Broad-acre corn, soybean, and cotton operations absorb the majority of unit volumes through automated planting equipment. Variable-rate application systems in the Midwest now standardize Bacillus-based seed treatments as baseline inputs.
- Horticulture:Greenhouse and nursery protocols generate disproportionate margin contribution through high-frequency application cycles and performance guarantee contracting. California Central Valley nut and stone fruit cooperatives specify microbial program outcomes rather than product volumes.
- Forestry:Western rangeland restoration projects in Colorado and Montana are restructuring vendor qualification around Bureau of Land Management biological control documentation requirements.
- Landscape:Municipal and commercial turf management programs face emerging state-level pollinator buffer mandates in Oregon and Washington that complicate aerial and ground application logistics.
Agriculture dominates volume throughput; horticulture captures margin expansion through outcome-based procurement restructuring.
End User:
End-user scale and technical sophistication determine whether purchasing flows through direct technical relationships or fragmented retail channels.
- Farmers:Large-scale operations with in-house agronomy staff negotiate direct supply agreements with formulation specialists. These buyers demand strain-specific performance data and resistance management protocols.
- Agricultural Cooperatives:Regional purchasing consortia in California and Florida consolidate input buying across fertility, irrigation, and biocontrol categories. Cooperatives now transfer efficacy risk from grower to supplier through performance guarantee structures.
- Garden Centers:Smallholder and residential segments access simplified formulations through retail channels with minimal technical support requirements.
- Researchers:University and federal agricultural experiment stations drive strain development pipelines and field efficacy validation for emerging active ingredients.
Agricultural cooperatives lead on procurement consolidation velocity; researchers anchor innovation pipeline access.
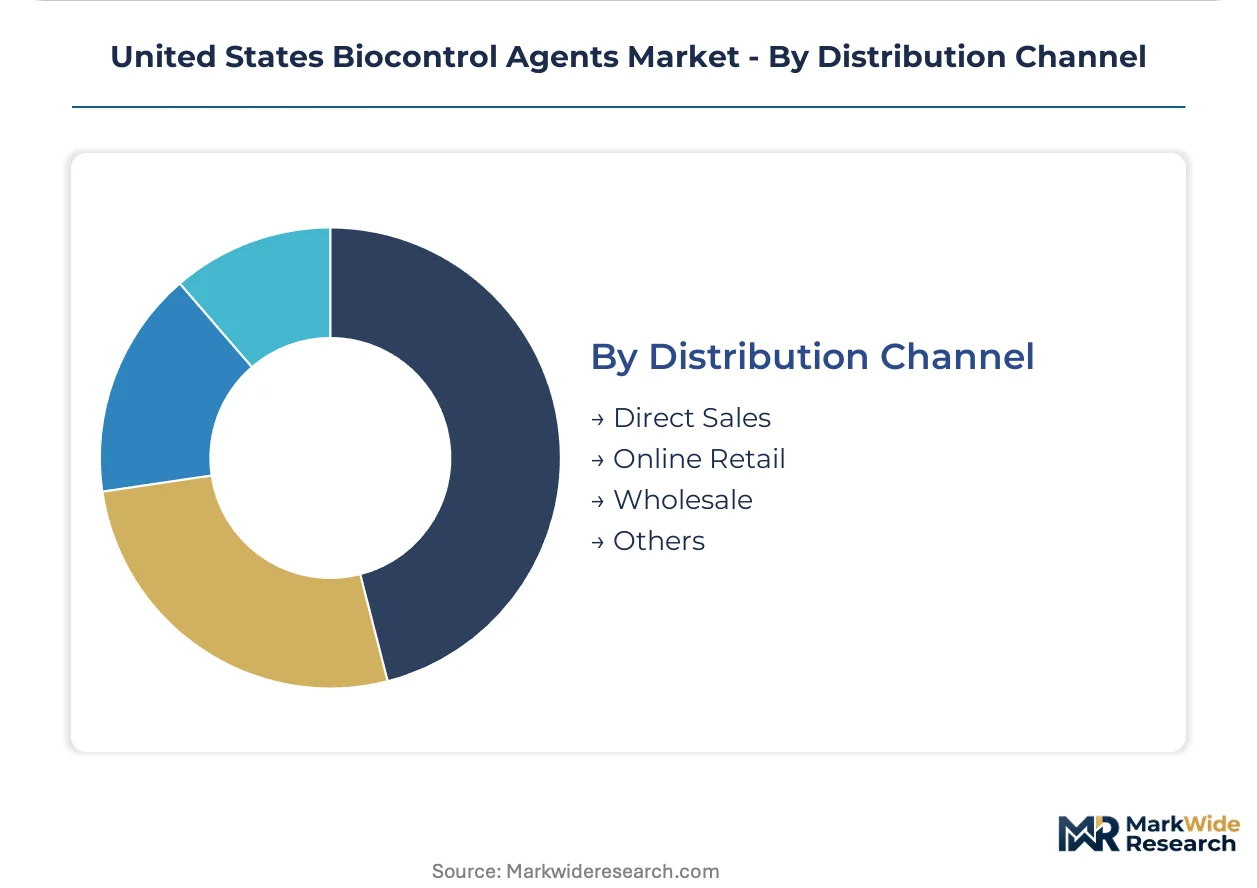
Distribution Channel:
Channel selection reflects buyer scale and the technical intensity of application protocols, with direct relationships sustaining complex program design.
- Direct Sales:Technical specialists from Bioworks and Koppert maintain field-level relationships with large farming operations for integrated program design. These channels sustain the deepest resistance management and rotation planning support.
- Online Retail:E-commerce platforms compete aggressively for garden center and smallholder access with simplified product positioning and competitive logistics.
- Wholesale:Regional distributors aggregate volumes for mid-tier operations lacking direct supplier relationships but requiring technical consultation.
- Others:Cooperative procurement systems and federal land management agency contracting represent specialized pathways with distinct compliance documentation requirements.
Direct sales leads on technical relationship depth; online retail gains share fastest in fragmented smallholder segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States biocontrol industry traces its commercial origins to integrated pest management programs developed in California's Central Valley during the 1970s, with Arizona and Florida subsequently building specialized rearing infrastructure for regionally adapted parasitoid species.
California
Specialty crop districts in the Central Valley and Central Coast are redirecting vineyard and orchard investment toward Trichoderma-based programs as the State Water Resources Control Board phases out synthetic fungicides under agricultural runoff restrictions. Fresno and Kern counties anchor microbial formulation production for national distribution.
Florida
Greenhouse tomato and pepper operations in Immokalee and Palmetto are piloting sprayable RNA interference formulations against whitefly and thrips at commercial scale. The Florida Department of Agriculture and Consumer Services coordinates state-level pollinator protection statutes that reshape product labeling requirements for broad-acre contractors.
Arizona
Beneficial insect rearing facilities in Tucson and Yuma dominate integrated pest management contracting across the Southwest cotton belt. The Arizona Department of Agriculture administers compliance documentation for biological control attempts on Bureau of Land Management acreage prior to synthetic chemical authorization.
Midwest Corn-Soy Belt
Iowa and Illinois production hubs manufacture Bacillus-based seed treatments for automated planting protocols across Nebraska, Indiana, and Ohio. Variable-rate application systems now standardize microbial inoculants as baseline inputs, embedding biocontrol into precision agriculture infrastructure.
Pacific Northwest
Oregon and Washington are implementing 25-foot untreated buffer zones around flowering crops that complicate aerial and ground application logistics. Western rangeland restoration projects in Colorado and Montana are restructuring vendor qualification around federal biological control documentation requirements.
United States Biocontrol Agents Market Competitive Landscape
The competitive structure tilts toward specialized microbial suppliers with proprietary strain libraries and regional rearing capabilities. Three tiers have crystallized: multinational biological systems integrators with North American production infrastructure, mid-tier formulators licensing germplasm from domestic repositories, and regionally focused parasitoid specialists serving integrated pest management contractors. Capacity expansion and strategic partnerships dominate competitive moves as EPA registration timelines compress.
Among North American specialists, Koppert Biological Systems Inc., Bioworks Inc., and Arizona Biological Control Inc. exemplify the three dominant archetypes. Koppert represents the integrated systems model with sustained supply chain capabilities. Bioworks occupies a position anchored to proprietary manufacturing platforms. Arizona Biological Control sits within the regionally adapted specialist tier, concentrating on Southwest parasitoid rearing programs.
| Leading Market Players |
|---|
| Arizona Biological Control Inc. |
| Beneficial Insectary Inc. |
| BioBee Sde Eliyahu Ltd. |
| Bioline AgroSciences Ltd. |
| Koppert Biological Systems Inc. |
| Bioworks Inc. |
| Andermatt Group AG |
| Arbico Organics |
| Applied Bio-Nomics |
| Others |
Pricing and Supply Chain Analysis
Cold-chain logistics costs from Iowa and California production hubs to Florida and Washington end-use points cascade through three distinct pricing tiers, with refrigerated distribution premiums compressing margins for single-active-ingredient suppliers while integrated microbial manufacturers capture value through formulation stability guarantees.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates proprietary Trichoderma manufacturing platforms from licensed-strain formulators and generic microbial alternatives. Premium tiers command position through EPA registration speed and performance guarantee contracting with California agricultural cooperatives, while economy tiers serve smallholder garden center channels with compressed technical support. Price differentiation hinges on strain patent concentration and cold-chain reliability documentation. Pricing pressure stems from accelerating EPA biopesticide registration timelines that compress commercialization windows for second-tier entrants. Large-scale farming operations with direct supplier relationships exhibit lowest price sensitivity; fragmented smallholders through online retail channels drive hardest bargain.
Supply Chain Analysis
Regional distribution centers in Fresno, Iowa, and Tucson anchor hub-and-spoke patterns radiating toward specialty crop districts and Midwest row-crop belts. Production gravity centers on domestic fermentation facilities with germplasm repositories concentrated among three domestic strain libraries. Raw material dependencies include molasses feedstocks for bacterial culture media, sterile packaging films, and refrigerated transport capacity. Single-source vulnerability runs through specialized microbiologist talent pools for fermentation scale-up expertise. Distribution runs through direct technical sales for large operations, wholesale aggregators for mid-tier buyers, and e-commerce platforms for fragmented smallholder access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States biocontrol agents market compounds steadily as EPA registration streamlining permanently lowers barriers for biological active ingredients against synthetic chemistry alternatives.
For Market Incumbents: Acquire proprietary strain libraries and germplasm repositories to lock in licensing revenue from second-tier formulators facing patent concentration bottlenecks. Build backward integration into cold-chain distribution infrastructure to capture logistics premiums currently leaking to third-party refrigerated carriers. Threat of accelerated EPA review cycles demands faster formulation development pipelines; lever in-house fermentation scale-up expertise to compress product launch timelines below eighteen months. For New Entrants and Emerging Players: Launch via controlled environment agriculture partnerships in New York and Illinois vertical farming operations, where clean-sheet microbial program design proceeds without legacy chemical infrastructure to displace. Target Texas High Plains cotton belt integrated pest management zones transitioning from boll weevil eradication programs, where regional cooperative relationships remain uncommitted. White-space opportunity concentrates in biostimulant-biopesticide convergence formulations qualifying for streamlined EPA registration while commanding specialty channel premiums. For Investors and Strategic Acquirers: Consolidation pressure builds where fermentation scale-up expertise concentrates among agricultural universities and former pharmaceutical operators, creating acquisition targets with scarce technical capabilities. Frame long-term viability around biological input substitution trajectories in California specialty crops facing water quality mandates and Midwest row-crop precision agriculture integration. Signal to watch: state-level pollinator protection statutes in Oregon and Washington that reshape application logistics and buffer zone economics for broad-acre contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Acquisition | Proprietary germplasm repositories command licensing revenue from formulators lacking independent R&D pipelines. |
| Cold-Chain Infrastructure Buildout | In-house refrigerated distribution captures fifteen to twenty percent logistics premiums currently paid to third-party carriers. |
| EPA Registration Acceleration | Compressed eighteen-month review timelines reward early regulatory engagement and strain-specific performance documentation. |
| Controlled Environment Partnerships | Vertical farming operations in New York and Illinois enable biocontrol-first protocols without legacy chemical displacement costs. |
| Biostimulant Convergence Development | Dual-function formulations qualify for streamlined EPA pathways while accessing premium specialty crop procurement channels. |
Research Methodology
Direct dialogue with fermentation operations managers, EPA regulatory affairs specialists, agricultural cooperative procurement directors, and precision agriculture technology integrators grounded qualitative findings. Secondary validation drew from EPA Office of Pesticide Programs registration databases, USDA National Organic Program certification records, state department of agriculture enforcement filings, and SEC disclosures from publicly traded biological systems companies. Bottom-up demand modeling across crop-specific application rates triangulated against top-down market sizing from production facility capacity and distribution channel throughput data.
Bottom-up unit economics modeled application intensity by crop system, formulation viability specifications, and cold-chain distribution requirements across the projection horizon. Segmentation dimensions included microbial versus non-living active ingredient categories, agriculture-horticulture-forestry application contexts, and direct-wholesale-online channel structures. CAGRs derived from trend extrapolation of EPA registration velocity, organic certification threshold adoption, and precision agriculture equipment penetration curves. Industry-specific inputs incorporated State Water Resources Control Board runoff mandate implementation schedules and Bureau of Land Management biological control documentation requirements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pollinator protection statute expansion or resistance management labeling intensification. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Bio-Based Levulinic Acid Market
Bio-Agriculture
US Biofungicide Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
Europe Feed Probiotics Market
Bio-Agriculture
Biological Control Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
Biochar Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
Africa Biofertilizer Market
Bio-Agriculture
Biological Seed Treatment Market