
 Brazil Biostimulants Market | 2026-2036
Brazil Biostimulants Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Biostimulants Market Insights
Seaweed-derived extracts is recalibrating product economics as growers substitute synthetic growth regulators with kelp-based alternatives in soybean and corn rotations. BASF SE leverages its distribution network across the Cerrado to anchor premium liquid formulations near major cooperatives. Valagro specializes in micronutrient-chelate combinations that sustain higher price points in horticultural zones around Petrolina. Novozymes competes through enzyme-enhanced microbial platforms that differentiate its portfolio from commodity humic acid suppliers.
Biostimulants comprise organic and biological substances applied to plants or soils to stimulate natural processes that enhance nutrient efficiency, abiotic stress tolerance, and crop quality parameters without direct pesticidal or fertilizing action. These inputs typically contain active compounds such as humic acids, seaweed polysaccharides, or viable microbial cultures at specified colony-forming unit concentrations, functioning primarily to optimize metabolic pathways rather than correct nutritional deficiencies. Microbial-based formulations command attention as the fastest-expanding product category, propelled by MAPA's simplified registration framework for plant-growth-promoting rhizobacteria. Agricultural crops absorb the dominant share of volume, though horticultural applications around São Paulo's protected vegetable clusters concentrate margin pools due to shorter payback cycles and higher per-hectare input budgets.
ANVISA monitors residue thresholds for imported biostimulant precursors, while MAPA's Normative Instruction 75 establishes quality benchmarks for microbial viability claims and contaminant limits. The Central Bank of Brazil's rural credit programs increasingly include biostimulants under financed input bundles, channeling demand through formal distribution networks. Stakeholders must track how pending federal legislation on biological input traceability will reshape distributor compliance costs and direct-to-farm channel economics.
Market Dynamics
MAPA's streamlined registration pathway under Law 14.785 is compressing product development cycles for microbial biostimulants, accelerating commercialization timelines for domestic and imported formulations targeting the Cerrado's intensive cropping systems.
Growth Catalysts
- Regulatory Streamlining:MAPA's simplified framework for plant-growth-promoting rhizobacteria reduces registration barriers, enabling faster market entry for microbial formulations compared to conventional agrochemical pathways.
- Phosphorus Efficiency Imperative:Soybean growers in Mato Grosso deploy biostimulants to enhance phosphorus uptake under no-till systems where soil fixation limits nutrient availability.
- Credit Inclusion:The Central Bank of Brazil's rural credit programs now bundle biostimulants into financed input packages, channeling demand through formal distribution networks.
Market Restraints
- Import Dependency:ANVISA residue monitoring for seaweed extracts and microbial precursors creates supply bottlenecks when international shipments face inspection delays at Brazilian ports.
- Technical Validation Gaps:Field performance variability across Brazil's diverse soil types complicates standardized efficacy claims, requiring region-specific trials that extend commercialization timelines.
- Substitution Pressure:Commodity humic acid suppliers compete on price, compressing margins for premium microbial and seaweed-derived formulations in price-sensitive grain markets.
Strategic Opportunities
- Horticultural Premium Segments:Protected vegetable clusters around São Paulo and Petrolina offer higher per-hectare input budgets and shorter payback cycles compared to extensive grain operations.
- Traceability Mandates:Pending federal legislation on biological input traceability will favor distributors with established compliance infrastructure over informal channel competitors.
- Enzyme-Microbial Convergence:Formulations combining viable microbial cultures with targeted enzyme activity open differentiation pathways beyond commodity biostimulant categories.
Industry Challenges
- Microbial Viability Management:MAPA's Normative Instruction 75 mandates strict colony-forming unit specifications and contaminant limits, requiring cold chain investments that strain smaller domestic blenders.
- Technical Advisory Capacity:The gap between product registration and farmer adoption depends on agronomist training in biostimulant integration with existing crop protection programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Biostimulants Market |
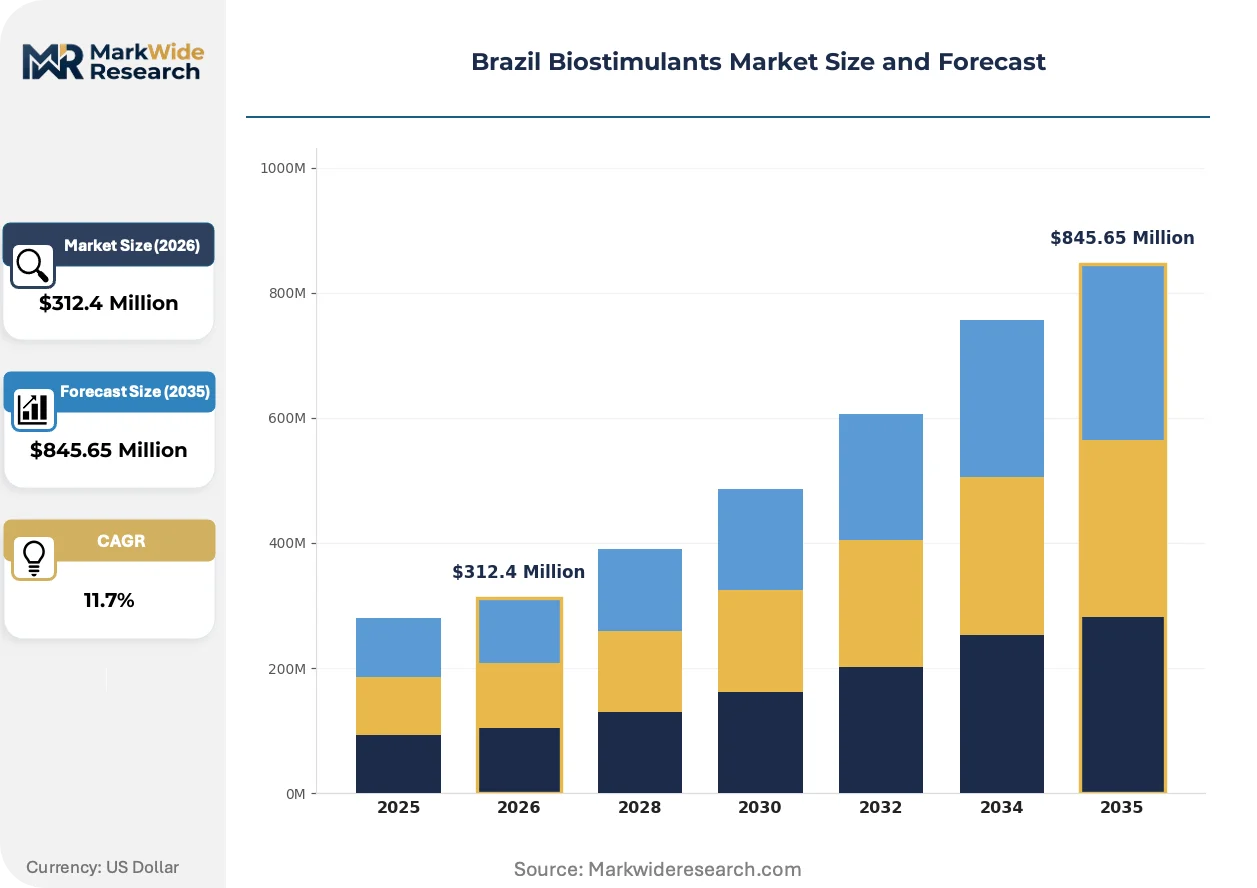
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $845.65 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Humic Acids, Seaweed Extracts, Microbial-Based, Organic Acids Application: Agricultural Crops, Horticultural Crops, Turf & Ornamental, Others Formulation: Liquid, Granular, Powder, Pelleted Distribution Channel: Direct Sales, Retail, Online Sales, Distributors |
| Companies Covered | Vittia Group, Trade Corporation International, Atlántica Agrícola, Humic Growth Solutions, Valagro, BASF SE, Isagro, Novozymes, Koppert, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Biostimulants Market Trends and Innovations
Kelp-based extracts are displacing synthetic growth regulators in soybean-corn rotations, recalibrating input economics across Brazil's main cropping belts. This shift intersects with regulatory modernization and changing procurement patterns to reshape competitive positioning.
Seaweed-derived polysaccharide formulations is rewriting product economics for growers seeking alternatives to synthetic growth regulators. Large cooperatives in Mato Grosso and Goiás are expanding procurement of kelp-based biostimulants for phosphorus uptake enhancement. The technology is compressing price premiums previously commanded by synthetic hormone products while opening formulation differentiation around extraction methods and bioactive compound standardization.
MAPA's Normative Instruction 75 establishes quality benchmarks for microbial viability claims and contaminant thresholds, creating compliance infrastructure requirements that favor capitalized distributors. Domestic blenders must upgrade laboratory capabilities to meet documentation standards for colony-forming unit verification. The regulation most acutely affects microbial formulation entrants, who are consolidating testing partnerships with accredited Brazilian laboratories to accelerate registration timelines.
Cooperative procurement consolidation is displacing traditional distributor relationships in the Cerrado's input supply chains. Large farming operations and multi-property cooperatives negotiate direct supply agreements with biostimulant manufacturers, bypassing regional distributor markups. This pattern concentrates most visibly in Mato Grosso, where scale advantages and credit bundling through the Central Bank's rural finance programs enable volume-based contracting that smaller distributors cannot match.
Brazil Biostimulants Market Segmentation
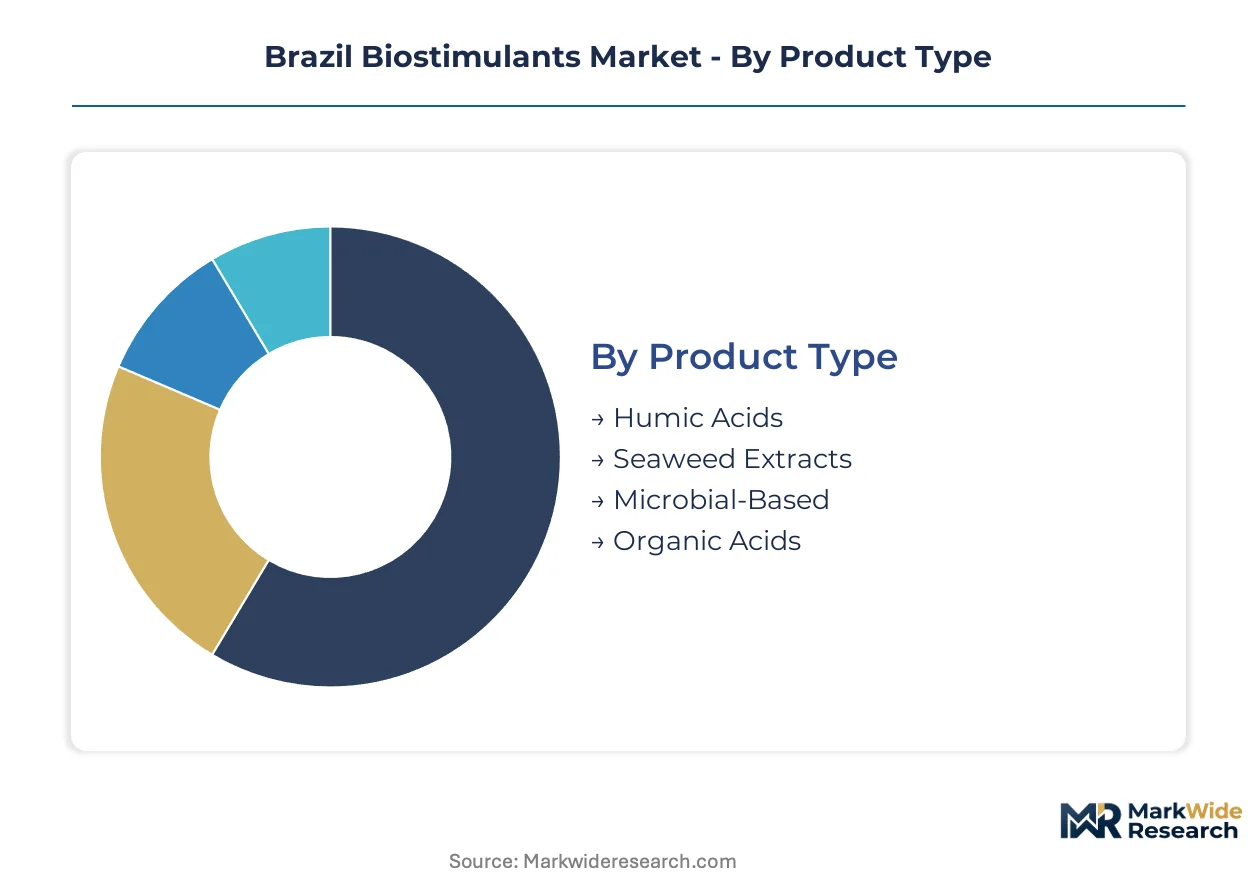
Product differentiation in Brazil's biostimulant sector follows distinct upgrade cycles driven by regulatory modernization and farmer procurement sophistication. Segmentation reveals how formulation chemistry, crop targeting, and channel economics stratify competitive positioning across the Cerrado and southern agricultural belts.
Product Type:
Replacement cycles accelerate where growers shift from commodity inputs to performance-validated biological alternatives, with regulatory tailwinds compressing adoption timelines for premium categories.
- Microbial-Based:Formulations containing plant-growth-promoting rhizobacteria at specified colony-forming unit concentrations. MAPA's streamlined registration pathway under Law 14.785 concentrates demand in Mato Grosso no-till soybean systems where phosphorus uptake enhancement justifies premium positioning.
- Seaweed Extracts:Kelp-derived polysaccharide formulations standardizing bioactive compound profiles. Growers in Goiás and Mato Grosso displace synthetic growth regulators in soybean-corn rotations, with cooperative procurement consolidating volume around extraction-method differentiation.
- Humic Acids:Organic matter derivatives from leonardite or composted biomass serving as baseline soil conditioners in price-sensitive grain markets.
- Organic Acids:Low-molecular-weight compounds including fulvic acid fractions and amino acid blends targeting metabolic pathway optimization in intensive horticultural zones.
Humic acids sits at the top of the volume ranking, with microbial-based climbing the fastest.
Application:
Margin pools stratify sharply by crop economics, with protected cultivation and perennial systems commanding input budgets that extensive grain operations cannot match.
- Horticultural Crops:High-value protected vegetable clusters around São Paulo and Petrolina sustain per-hectare input expenditures three to four times grain-sector levels. Shorter payback cycles and quality premiums for export-grade production validate biostimulant integration with precision irrigation systems.
- Agricultural Crops:Extensive soybean, corn, and cotton operations across the Cerrado absorb the dominant volume share. Phosphorus efficiency imperatives under no-till management drive adoption, though price compression from commodity humic suppliers constrains premium formulation penetration.
- Turf & Ornamental:Golf course maintenance and urban landscaping applications concentrated in São Paulo and Brasília metropolitan corridors.
- Others:Pasture renovation and forestry nursery applications with fragmented demand across Brazil's northern and northeastern frontiers.
Agricultural crops dominates absolute volume, with horticultural crops generating the steepest margin expansion trajectory.
Formulation:
Application equipment compatibility and storage infrastructure dictate formulation selection, with liquid systems leveraging existing spray infrastructure while dry formats target bulk nutrient blending operations.
- Liquid:Ready-to-apply concentrates and suspensions compatible with standard boom sprayers and fertigation systems. BASF and multinational suppliers anchor premium positioning through cooperative direct-supply agreements in Mato Grosso, bypassing distributor markups.
- Granular:Slow-release carriers for soil incorporation at planting, gaining traction where farmers seek to reduce application frequency in extensive operations.
- Powder:Concentrated dry formulations requiring on-farm reconstitution, favored by mid-scale operations with blending equipment.
- Pelleted:Dust-free handling characteristics for bulk blending with conventional fertilizers, penetrating cooperatives with centralized mixing facilities.
Liquid formulations command the largest volume position, with granular formats expanding most quickly as planting-time application protocols standardize.
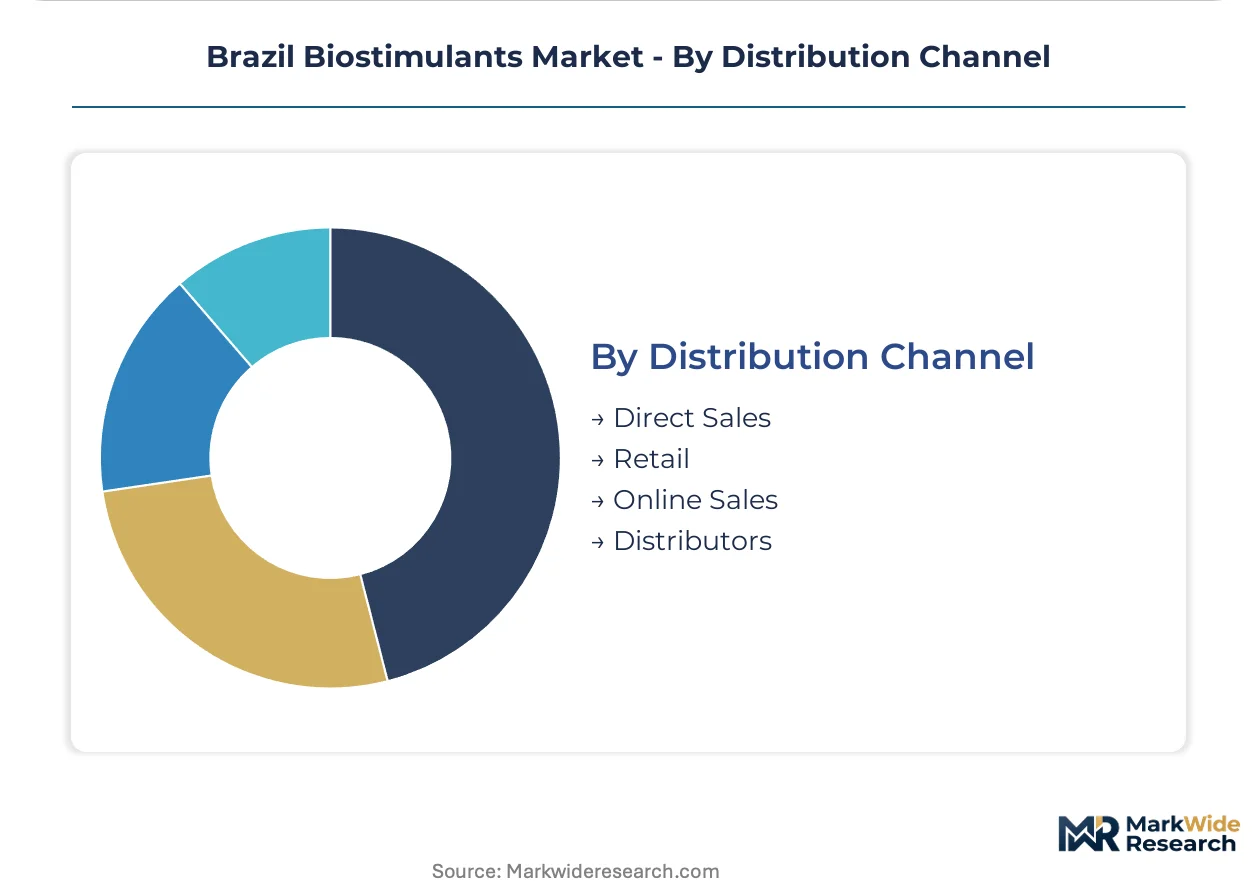
Distribution Channel:
Channel economics shift where credit bundling and traceability mandates favor formal infrastructure over informal trade, consolidating procurement around capitalized distributors and manufacturer-direct relationships.
- Direct Sales:Manufacturer-to-cooperative agreements negotiated by large farming operations and multi-property groups in Mato Grosso. Central Bank rural credit program bundling enables volume-based contracting that regional distributors cannot match.
- Distributors:Regional agrochemical networks with laboratory capabilities for MAPA Normative Instruction 75 compliance. Cold chain investments and accredited testing partnerships create barriers for smaller domestic blenders.
- Retail:Independent agronomic input stores serving fragmented smallholder segments in southern Brazil and transition zones.
- Online Sales:Emerging platform-based procurement for specialty horticultural inputs, constrained by microbial viability requirements and advisory service gaps.
Distributors retain the volume lead, with direct sales gaining share fastest as cooperative consolidation accelerates across the Cerrado.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cerrado agricultural frontier concentrates Brazil's biostimulant demand, with intensive crop production and rising input costs driving adoption across Mato Grosso, Goiás, and São Paulo state clusters.
Mato Grosso
No-till soybean systems and phosphorus fixation challenges propel biostimulant deployment across the state's western grain belt. MAPA's Law 14.785 registration pathway accelerates microbial formulation approvals for domestic blenders. Large cooperatives in Sorriso and Lucas do Rio Verde negotiate direct supply agreements with multinational manufacturers, bypassing traditional distributor channels.
Goiás
Soybean-corn rotation intensity and kelp-based growth regulator substitution create procurement consolidation among central plateau farming operations. Central Bank rural credit bundling channels demand through formal networks with cold chain compliance capabilities. The Rio Verde input cluster anchors formulation distribution for enzyme-microbial convergence products targeting extensive grain systems.
São Paulo
Protected vegetable production around Campinas and the Ribeirão Preto corridor sustains per-hectare input expenditures three to four times grain-sector levels. ANVISA residue monitoring for imported seaweed extracts shapes procurement timelines for specialty horticultural suppliers. Precision irrigation integration in the state's greenhouse clusters validates premium biostimulant positioning for export-grade tomato and pepper operations.
Minas Gerais
Dairy pasture renovation and coffee nursery applications fragment demand across the state's southern and Zona da Mata regions. Normative Instruction 75 microbial viability requirements strain smaller domestic blenders without accredited laboratory partnerships. Belo Horizonte-based distributors upgrade testing infrastructure to maintain compliance certification for regional cooperative networks.
Rio Grande do Sul
Smallholder grain and tobacco systems in the state's northern plateau generate price-sensitive demand for commodity humic acid formulations. Retail agronomic input stores serve fragmented segments where technical advisory gaps slow biostimulant integration with existing crop protection programs. The Passo Fundo cooperative cluster experiments with granular biostimulant blending at centralized mixing facilities.
Brazil Biostimulants Market Competitive Landscape
Direct supply agreement consolidation dominates the current landscape, with large cooperatives displacing traditional distributor relationships across the Cerrado. The vendor base stratifies into three tiers: multinational agrochemical conglomerates with established Brazilian distribution infrastructure, specialized microbial and seaweed extract formulators with MAPA registration expertise, and domestic commodity humic acid suppliers competing on price. Strategic archetypes include premium liquid formulation anchors, micronutrient-chelate specialists, and enzyme-enhanced microbial platform developers. M&A activity and cooperative procurement consolidation represent the dominant competitive moves reshaping channel economics.
Among multinational suppliers, BASF SE anchors premium liquid formulation positioning through cooperative direct-supply agreements in Mato Grosso, while Valagro exemplifies the micronutrient-chelate specialist archetype with sustained price points in horticultural zones. Novozymes occupies a position within the enzyme-microbial convergence tier, differentiating from commodity humic acid competitors through viable culture and targeted enzyme activity combinations. These three companies represent distinct strategic vectors—scale-driven distribution leverage, specialty formulation premiumization, and biological platform differentiation—competing for share across Brazil's divergent crop systems and procurement channels.
| Leading Market Players |
|---|
| Vittia Group |
| Trade Corporation International |
| Atlántica Agrícola |
| Humic Growth Solutions |
| Valagro |
| BASF SE |
| Isagro |
| Novozymes |
| Koppert |
| Others |
Pricing and Supply Chain Analysis
Seaweed extract import costs from Chile and Norway cascade through three distinct pricing tiers before reaching Brazilian soybean cooperatives, with ANVISA inspection delays at Paranaguá and Santos ports amplifying working capital requirements for distributors serving Mato Grosso grain operations.
Pricing Analysis
Input-cost pass-through from kelp-derived polysaccharides and microbial culture substrates shapes the dominant contract-based offtake structure, with pricing stratifying across premium microbial formulations, standard seaweed extracts, and commodity humic acid tiers. Price differentiation hinges on MAPA registration tier under Law 14.785 and cold chain compliance certification. Cost compression in the humic acid tier intensifies because domestic leonardite suppliers expand blending capacity. Grain cooperatives in Goiás exhibit the highest price sensitivity, while protected vegetable growers around Petrolina sustain premium positioning.
Supply Chain Analysis
Freight costs from European and Asian fermentation facilities to Brazilian port terminals represent the dominant logistics burden, with supply concentrating in Denmark, Italy, and China for microbial precursors and seaweed extracts. Raw material dependencies include kelp biomass, rhizobial culture media, and leonardite ore. Single-source vulnerability runs through Chilean kelp harvesters facing climate variability. Distribution runs through cooperative direct agreements and MAPA-accredited distributors with laboratory testing capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's biostimulant sector offers margin expansion as kelp-based formulations displace synthetic growth regulators and cooperative procurement consolidation reduces distributor markups.
For Market Incumbents: Acquire accredited testing laboratory partnerships to secure MAPA Normative Instruction 75 compliance infrastructure ahead of pending traceability mandates. Consolidate direct supply relationships with Sorriso and Lucas do Rio Verde cooperatives before regional distributors upgrade cold chain capabilities. Defend against enzyme-microbial convergence entrants by locking in multi-season offtake contracts with Central Bank credit-bundled buyers. For New Entrants and Emerging Players: Mid-scale horticultural operations in Minas Gerais's Zona da Mata coffee nurseries represent an underserved buyer archetype with limited technical advisory access. Penetrate dairy pasture renovation segments in Rio Grande do Sul's northern plateau where commodity humic acid suppliers dominate. Deploy agronomist-led technical service models to bridge adoption gaps in fragmented smallholder systems. For Investors and Strategic Acquirers: Consolidation pressure builds where domestic blenders lack capital for MAPA-mandated laboratory upgrades and cold chain investments. Frame long-term viability around biological input traceability legislation favoring compliant infrastructure holders. Target domestic microbial formulators with pending Law 14.785 registrations. Monitor cooperative procurement volume shifts as inflection indicators for distributor displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| MAPA Registration Acceleration | Law 14.785 streamlines microbial approval timelines for domestic blenders targeting Cerrado soybean systems. |
| Cooperative Direct Supply Agreements | Bypassing distributor markups concentrates procurement power with Mato Grosso multi-property farming groups. |
| Accredited Laboratory Partnerships | Normative Instruction 75 compliance infrastructure creates barriers for smaller domestic blenders without testing capabilities. |
| Cold Chain Capacity Expansion | Microbial viability requirements strain regional distributors serving Goiás and Minas Gerais cooperative networks. |
| Enzyme-Microbial Convergence R&D | Novozymes-style platforms differentiate beyond commodity humic acid categories in price-sensitive grain markets. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with MAPA regulatory affairs officers, cooperative procurement managers, microbial formulation R&D directors, and agronomic input distributors with secondary validation. Sources included MAPA registration databases, ANVISA import inspection records, Central Bank rural credit disbursement reports, and customs trade data for seaweed extract and microbial precursor shipments. Bottom-up volume estimates from state-level cooperative procurement data triangulated against top-down market sizing from input manufacturer capacity disclosures.
Comparable-period anchoring linked historical adoption curves in Mato Grosso no-till systems to forward projection assumptions across the analysis window. The analytical framework modeled segmentation by product chemistry, crop application intensity, formulation compatibility with existing spray infrastructure, and channel formalization level. CAGRs derived from cooperative procurement volume trajectories and credit program bundling expansion rates. Forecast inputs incorporated phosphorus fixation severity indices for Cerrado soils and pending biological input traceability legislation progression.
Underlying measurement precision varies by segment; horticultural crop applications carry tighter precision than fragmented pasture renovation demand. Forecasts reflect assumptions about MAPA registration processing timelines and cooperative consolidation velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
North America Biostimulants Market
Bio-Agriculture
United States Biostimulants Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
Canada Biofertilizers Market
Bio-Agriculture
Brazil Biofertilizers Market
Bio-Agriculture
Spain Biopesticides Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Brazil Agricultural Biologicals Market
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
Latin America Biostimulants Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
India Biomass Market