
 Argentina Biopesticides Market | 2026-2036
Argentina Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Argentina Biopesticides Market Outlook
Domestic fermentation capacity in Argentina is decoupling from import dependence for microbial active ingredients. Bioceres Crop Solutions leverages its Rosario-based biotech infrastructure to anchor production of indigenous Beauveria bassiana strains. Bayer Crop Science sustains competitive pressure through extensive field trial networks across Córdoba and Santa Fe provinces. Valent Biosciences differentiates by controlling cold-chain distribution for live biological formulations.
Biopesticides comprise living organisms, naturally occurring substances, and metabolites engineered for pest, disease, and weed management in agricultural systems, typically formulated with colony-forming units exceeding viable thresholds per milliliter for liquid concentrates. These products serve as targeted alternatives to synthetic agrochemicals in integrated pest management programs. Bacterial biopesticides lead volume given established Bacillus thuringiensis applications in soybean and corn, while fungal segments capture expanding share in specialty fruit operations. Wettable powder formulations dominate smallholder channels due to storage stability, whereas liquid concentrates command premium positioning among large-scale mechanized farms.
SENASA governs product registration and residue monitoring under Argentina's national agrochemical framework, while the Secretariat of Agriculture enforces Good Agricultural Practice protocols that increasingly favor biological inputs. The country's national agricultural technology regulator tightened import equivalency standards for foreign-manufactured biologicals, reshaping competitive access. Provincial extension services in Entre Ríos and La Pampa now mandate biocontrol training modules. Stakeholders must track evolving SENASA registration timelines and provincial subsidy programs to secure positioning before supply bottlenecks intensify.
Market Dynamics
SENASA's tightening of residue limits on synthetic chemicals is forcing Argentine soybean and corn producers to rebuild crop protection protocols around biological active ingredients, creating structural demand pull for locally fermented biocontrol agents.
Growth Catalysts
- SENASA regulatory pressure:The national agricultural technology regulator's stricter residue monitoring protocols eliminate synthetic chemical options for export-oriented growers, redirecting procurement toward bacterial and fungal biopesticides.
- Pampas soybean expansion:Large-scale mechanized farms in Buenos Aires, Córdoba, and Santa Fe provinces are embedding biological programs into integrated pest management systems at unprecedented scale.
- Fermentation infrastructure:Domestic biotech capacity in Rosario and surrounding industrial clusters is decoupling supply chains from imported microbial concentrates, shortening lead times and hardening price competitiveness.
Market Restraints
- Cold-chain fragility:Live biological formulations require uninterrupted refrigerated distribution from production through application, a capability gap that limits penetration beyond the Buenos Aires-Córdoba-Santa Fe triangle.
- Import equivalency barriers:SENASA's tightened foreign-manufactured biological registration standards erect non-tariff obstacles that delay market entry for offshore suppliers by 18-36 months.
- Performance inconsistency:Microbial biocontrol efficacy fluctuates with temperature, humidity, and soil microbiome conditions, creating adoption resistance among risk-averse smallholders in La Pampa and Entre Ríos.
Strategic Opportunities
- Specialty fruit penetration:Mendoza and Río Negro viticulture and stone fruit operations represent underexploited demand for fungal biopesticides targeting vine mealybug and brown rot.
- Provincial extension mandates:Biocontrol training modules now required by Entre Ríos and La Pampa agricultural services create captive audiences for technical product positioning.
- Seed treatment convergence:Biological inoculants paired with biopesticide coatings on soybean and corn seed offer bundled entry into farmer decision-making at planting.
Industry Challenges
- Formulation stability expertise:Shortage of fermentation scientists and formulation chemists capable of extending shelf life for tropicalized Beauveria bassiana and Metarhizium anisopliae strains constrains product pipeline velocity.
- SENASA registration timelines:Unpredictable review cycles for novel microbial active ingredients tie up R&D capital for years without revenue certainty, favoring incumbents with established dossiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Argentina Biopesticides Market |
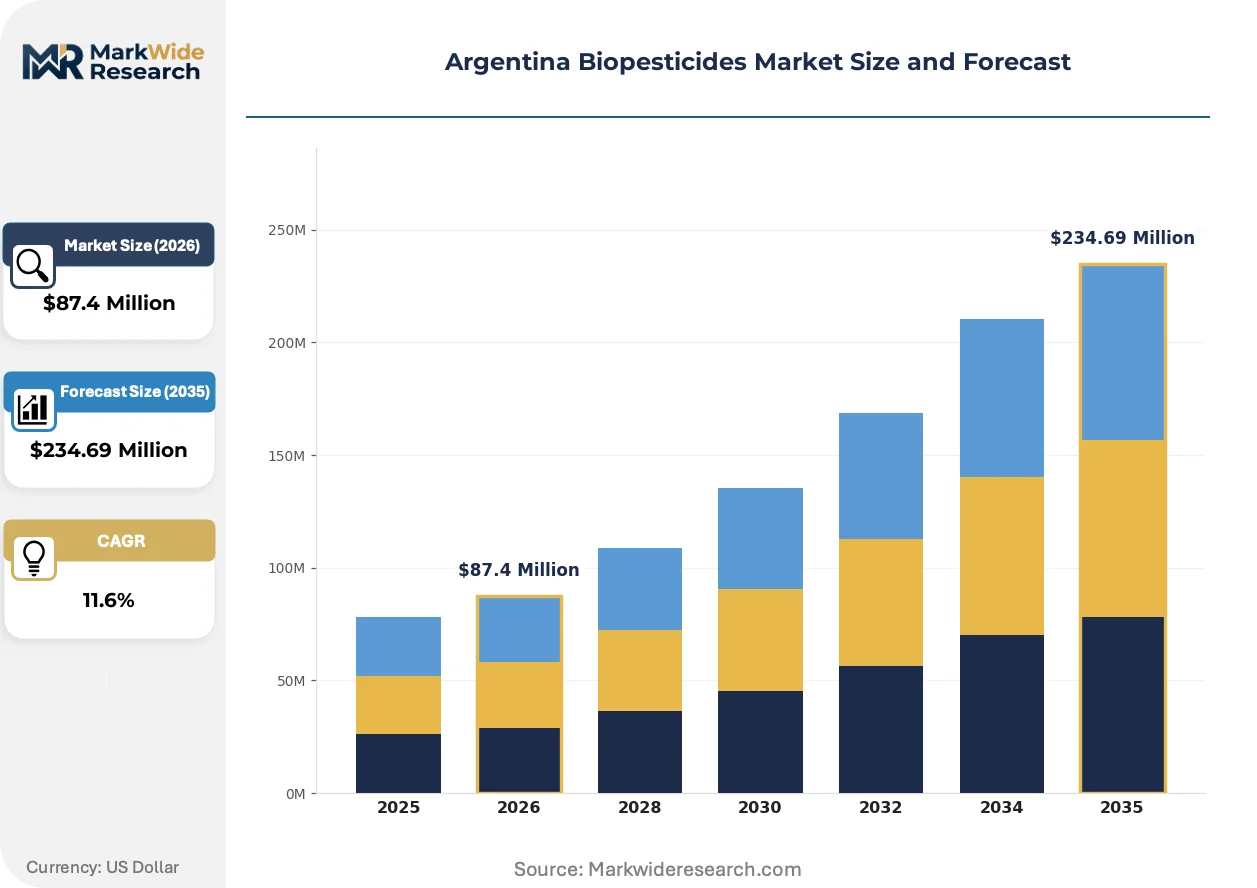
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $234.69 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacterial, Fungal, Botanical, Viral Formulation: Granular, Liquid Concentrate, Wettable Powder, Emulsifiable Concentrate Crops: Cereals, Fruits, Vegetables, Oilseeds Distribution Channel: Online Sales, Direct Sales, Retail, Agro-Distributors |
| Companies Covered | BASF, Bayer Crop Science, Corteva Agriscience, American Vanguard Corporation, Koppert Biological Systems, FMC Corporation, Valent Biosciences, Marrone Bio Innovations, Bioceres Crop Solutions Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Argentina Biopesticides Market Strategic Shifts
Biological crop protection in Argentina is pivoting from commodity substitution toward precision-integrated systems where formulation science and digital application tools determine competitive outcomes.
Precision fermentation technology is automating the production of high-titer microbial concentrates with standardized colony-forming unit counts. Large-scale cooperatives in Santa Fe province are adopting liquid inoculum systems that integrate directly with planter-mounted application equipment. This automation is compressing the cost gap between biological and synthetic chemistries while hardening supply security.
SENASA's 2023 import equivalency protocol revision now demands full toxicological and ecotoxicological dossiers for foreign-manufactured biologicals, mirroring standards previously reserved for synthetic agrochemicals. Argentine biotechnology firms with established domestic fermentation assets gain asymmetric registration speed. Offshore suppliers face extended timeline risk, reshaping partnership strategies toward local manufacturing joint ventures.
Farmer procurement of biopesticides is consolidating through agronomic service providers who bundle biological recommendations with soil testing and variable-rate application. This channel shift displaces traditional agrochemical distributor relationships in the Pampas core. Specialty crop growers in Mendoza retain direct manufacturer relationships, creating a bifurcated channel structure.
Argentina Biopesticides Market Segmentation
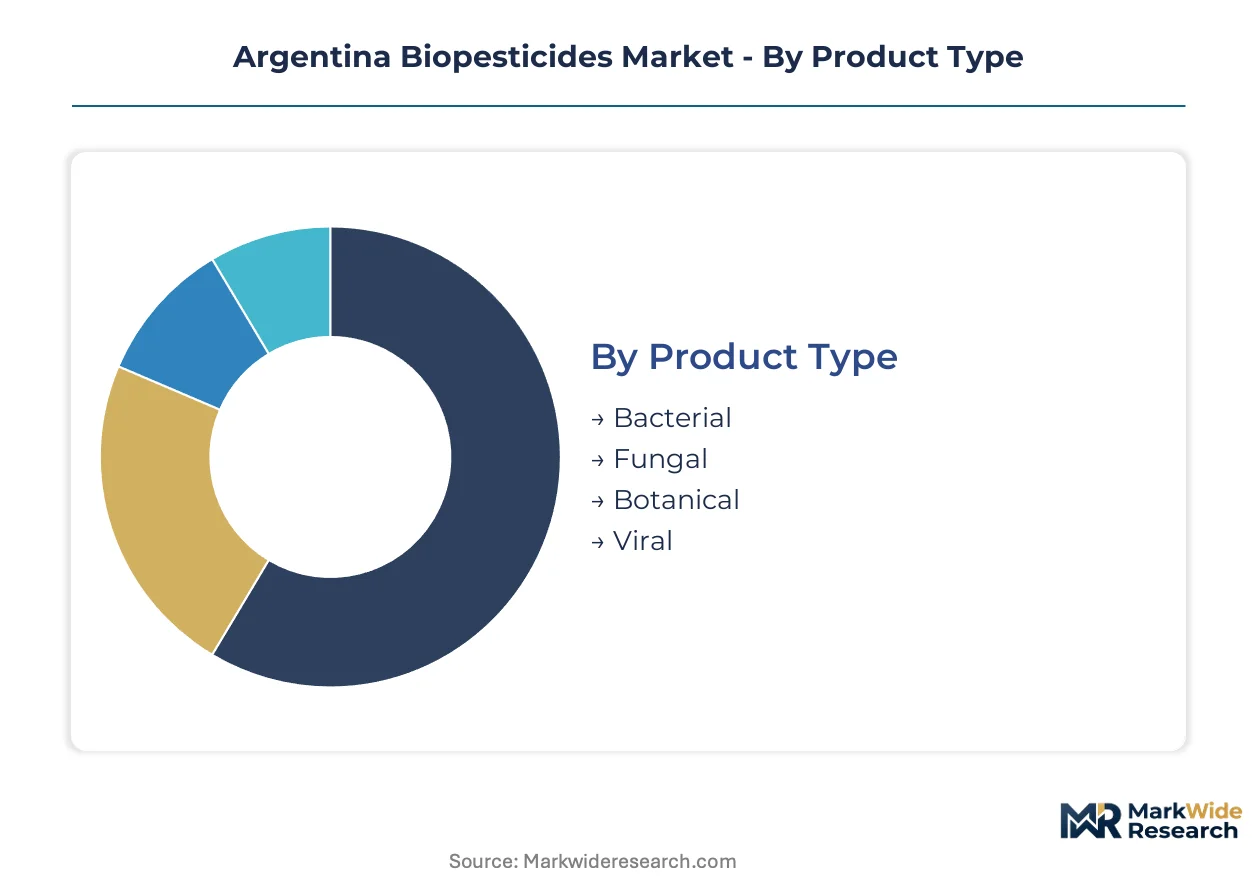
Argentina's biopesticides market fragments across technical specifications, application methods, and crop-specific protocols that determine procurement patterns and margin structures. Understanding these segment boundaries reveals where capital deployment concentrates and which product configurations command pricing power.
Product Type:
Capital intensity varies sharply across microbial production platforms, with fermentation infrastructure requirements separating scalable bacterial platforms from specialized viral propagation systems.
- Bacterial:Bacillus thuringiensis strains dominate Argentine production volumes through established fermentation protocols at Rosario biotech clusters. Demand concentrates in Buenos Aires province soybean operations where SENASA residue protocols have eliminated synthetic alternatives for export certification.
- Fungal:Beauveria bassiana and Metarhizium anisopliae formulations require extended incubation cycles and precise sporulation conditions that strain domestic capacity. Mendoza viticulture and Río Negro stone fruit growers drive uptake for vine mealybug and brown rot management despite cold-chain constraints.
- Botanical:Plant-derived extracts from neem and pyrethrum face raw material sourcing limitations across the Pampas region.
- Viral:Nucleopolyhedrovirus products for Lepidoptera control remain import-dependent with restricted local manufacturing infrastructure.
Most installed capacity flows through bacterial fermentation platforms. Expansion is steepest in fungal formulations as specialty crop penetration accelerates.
Formulation:
Application equipment compatibility and storage logistics create distinct cost tiers that segment farmer access across mechanized versus smallholder operations.
- Liquid Concentrate:High-titer microbial suspensions with standardized colony-forming unit counts integrate directly with planter-mounted inoculum systems adopted by Santa Fe cooperatives. Large-scale Pampas farms absorb premium positioning for refrigerated supply security.
- Wettable Powder:Spray-dried formulations with extended ambient-temperature stability dominate smallholder procurement in La Pampa and Entre Ríos where cold-chain infrastructure remains fragmented.
- Granular:Soil-incorporated delivery systems for root-zone biocontrol carry higher per-hectare material costs limiting penetration.
- Emulsifiable Concentrate:Oil-based carriers for foliar fungal applications require specialized tank-mix compatibility testing that delays adoption.
Volume concentrates in wettable powder for storage resilience. Technical migration favors liquid concentrate as precision application equipment spreads.
Crops:
Farm scale and export orientation determine biocontrol intensity, with commodity oilseeds anchoring volume and specialty crops driving margin expansion.
- Oilseeds:Soybean hectares across Buenos Aires, Córdoba, and Santa Fe provinces embed bacterial biopesticides into standard integrated pest management protocols at unprecedented scale. SENASA's tightened residue monitoring redirects procurement from synthetic chemistry toward locally fermented alternatives.
- Fruits:Mendoza viticulture and Río Negro pome and stone fruit operations generate concentrated demand for fungal biocontrol agents targeting region-specific pest complexes with limited synthetic alternatives.
- Vegetables:Smaller plot sizes and diverse pest pressure in peri-urban Buenos Aires and Córdoba create fragmented demand patterns.
- Cereals:Wheat and corn biopesticide adoption lags oilseeds due to lower export certification pressure and established synthetic chemistry routines.
Revenue gravity centers on oilseed applications. Fastest share gains emerge in fruit segments as fungal formulation stability improves.
Distribution Channel:
Channel structure bifurcates between bundled agronomic services for commodity producers and direct manufacturer relationships for specialty crop growers.
- Agro-Distributors:Traditional wholesale networks across the Pampas triangle retain volume leadership through credit extension and logistics reach into Córdoba and Santa Fe farming cooperatives. Technical recommendation bundling with soil testing displaces standalone product transactions.
- Direct Sales:Manufacturer relationships dominate Mendoza and Río Negro specialty crop segments where technical consultation requirements exceed distributor capability.
- Retail:Provincial agro-input stores serve smallholders in Entre Ríos and La Pampa with limited product range and minimal technical support.
- Online Sales:Digital procurement channels remain marginal due to live biological shipment constraints and farmer preference for verified cold-chain handling.
Transaction volume concentrates through agro-distributor networks. Fastest structural shift occurs in direct sales as specialty crop technical demands intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where biopesticide production concentrates, as compliance-cost gaps between jurisdictions drive fermentation infrastructure toward markets with streamlined biological registration pathways.
Buenos Aires Province
Soybean export certification requirements and SENASA residue protocols anchor bacterial biopesticide demand in the Pampas core. Provincial extension services mandate biocontrol training modules that accelerate farmer adoption. The Azul and Pergamino agricultural clusters host the densest concentration of liquid inoculum application equipment.
Córdoba Province
Large-scale mechanized farms embed biological programs into integrated pest management systems at unprecedented scale. SENASA's tightened import equivalency standards favor locally fermented alternatives over foreign-manufactured competitors. The Río Cuarto industrial corridor anchors domestic Beauveria bassiana production capacity.
Santa Fe Province
Cooperative farming structures drive consolidated procurement through bundled agronomic service providers. Cold-chain infrastructure penetration exceeds neighboring provinces, enabling live biological formulation distribution. The Rosario biotech cluster anchors precision fermentation technology for high-titer microbial concentrates.
Mendoza Province
Viticulture and stone fruit operations generate concentrated demand for fungal biocontrol agents targeting vine mealybug and brown rot. Direct manufacturer relationships dominate procurement given technical consultation requirements. The Maipú and Luján de Cuyo valleys represent underexploited penetration potential for Metarhizium anisopliae formulations.
Entre Ríos Province
Smallholder fragmentation and cold-chain gaps constrain adoption despite provincial extension mandates for biocontrol training. Wettable powder formulations dominate due to ambient-temperature storage stability. The Paraná and Concordia agricultural zones show emerging uptake for bacterial seed treatments on corn hectares.
Argentina Biopesticides Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue specialty crop differentiation through formulation stability expertise. The market exhibits moderate concentration around fermentation-capable incumbents with SENASA-registered dossiers. Strategic archetypes include domestic biotech specialists, multinational agrochemical diversifiers, and cold-chain logistics integrators. Capacity expansion and local manufacturing joint ventures represent the dominant competitive moves as import equivalency barriers harden.
Among multinational diversifiers, Bayer Crop Science and BASF occupy positions anchored by extensive field trial networks and synthetic-to-biological portfolio transitions. Bioceres Crop Solutions exemplifies the domestic specialist archetype, leveraging Rosario-based infrastructure to compress registration timelines and supply security. Valent Biosciences sits within the logistics-integrated tier, with cold-chain distribution capabilities creating positioning differentiation for live biological formulations.
| Leading Market Players |
|---|
| BASF |
| Bayer Crop Science |
| Corteva Agriscience |
| American Vanguard Corporation |
| Koppert Biological Systems |
| FMC Corporation |
| Valent Biosciences |
| Marrone Bio Innovations |
| Bioceres Crop Solutions Corp. |
| Others |
Value Chain & Pricing Dynamics
SENASA's tightened residue limits on synthetic chemicals gate both qualified supply and premium-tier pricing access, as export-oriented soybean producers in Buenos Aires province must source SENASA-registered bacterial biopesticides to maintain EU and Chinese market entry. This regulatory filter concentrates pricing power among domestic fermentation operators with established dossiers while marginalizing unregistered imports.
Pricing Analysis
Distributor margins absorb the steepest compression as agro-distributor networks across the Pampas triangle bundle biological recommendations with soil testing and variable-rate application services. Three-tier pricing structure across premium, standard, and economy levels stratifies by cold-chain reliability and CFU concentration guarantees, with liquid concentrates commanding substantial premia over wettable powders. Price erosion runs through smallholder channels in Entre Ríos and La Pampa where ambient-stable formulations face procurement consolidation. Large-scale mechanized farms in Santa Fe exhibit lowest price sensitivity given integrated pest management compliance requirements.
Supply Chain Analysis
SENASA's 2023 import equivalency protocol revision reshapes sourcing toward domestic fermentation capacity, as foreign-manufactured biologicals now require full toxicological dossiers mirroring synthetic agrochemical standards. Raw material inputs center on molasses substrates, proprietary spore carrier matrices, and refrigerated transport assets. Single-source vulnerability concentrates in live biological formulation distribution where uninterrupted cold-chain infrastructure remains fragmented beyond the Buenos Aires-Córdoba-Santa Fe triangle. Distribution runs through cooperative procurement structures in Santa Fe and direct manufacturer relationships in Mendoza viticulture clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Argentina's biopesticides market functions as a stable compounder, with SENASA regulatory pressure on synthetic residue limits generating structural demand pull that insulates biological producers from commodity cyclicality.
For Market Incumbents: Cement market position by expanding Rosario-based precision fermentation capacity to capture SENASA registration speed advantages over import-dependent competitors. Deepen backward integration into indigenous Beauveria bassiana strain development to harden supply security against cold-chain fragility in fungal segments. Prioritize formulation stability R&D to extend shelf life for tropicalized Metarhizium anisopliae products targeting Mendoza viticulture.
For New Entrants and Emerging Players: Enter via specialty fruit penetration in Río Negro and Mendoza where technical consultation requirements exceed incumbent distributor capabilities and direct manufacturer relationships dominate procurement. Target wettable powder formulations for smallholder channels in Entre Ríos and La Pampa where cold-chain gaps constrain live biological competition. Pursue provincial extension service partnerships to embed products within mandated biocontrol training modules.
For Investors and Strategic Acquirers: Roll-up economics work for domestic fermentation specialists with SENASA-registered dossiers because import equivalency barriers extend offshore competitor timelines by 18-36 months, creating captive revenue visibility. Focus acquisition screening on Rosario industrial corridor assets with precision fermentation technology and established bacterial platform expertise. Watch SENASA registration queue velocity as the inflection signal indicating competitive access tightening or loosening.
| Strategic Initiative | Industry Significance |
|---|---|
| Local Manufacturing Joint Venture | Compresses SENASA registration timelines by establishing domestic fermentation presence in Rosario biotech clusters. |
| Formulation Stability Investment | Extends shelf life for Beauveria bassiana strains, enabling penetration beyond cold-chain-dependent Pampas core. |
| Provincial Extension Partnership | Captures captive farmer audiences through mandated biocontrol training modules in Entre Ríos and La Pampa. |
| Seed Treatment Convergence | Bundles biological inoculants with biopesticide coatings at planting decision point for soybean and corn hectares. |
| Cold-Chain Infrastructure Buildout | Enables live biological distribution to Mendoza and Río Negro specialty crop segments beyond Pampas triangle. |
Study Parameters
Coverage spans Buenos Aires, Córdoba, Santa Fe, Mendoza, and Entre Ríos provinces, with primary inputs from each region's agricultural extension services, cooperative procurement managers, and SENASA registration officials. The analytical approach combines structured interviews with fermentation scientists, formulation chemists, and agronomic service providers with secondary validation through SENASA regulatory filings, provincial agricultural statistics, and customs trade data for microbial concentrate imports. Bottom-up farmer adoption modeling and top-down market sizing triangulate volume estimates across bacterial, fungal, and viral product categories.
Rate-of-change decomposition isolates volume drivers from price mix effects across the projection horizon. Segmentation dimensions include microbial production platform, formulation type, crop application, and distribution channel structure. CAGRs derive from province-level hectare expansion rates for biological program adoption, weighted by SENASA registration velocity assumptions and cold-chain infrastructure penetration curves. Industry-specific inputs incorporate soybean export certification requirements and precision fermentation technology diffusion patterns.
Inputs from SENASA officials and provincial extension directors were available through the study window; gaps in smallholder adoption data from La Pampa and Entre Ríos introduce uncertainty bands around penetration rate assumptions. Forecasts reflect documented regulatory trajectories and infrastructure investment pipelines, with revision risk concentrated in SENASA registration timeline unpredictability and cold-chain buildout delays. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
Brazil Biocontrol Agents Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Africa Biostimulants Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
Biochar Machine Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
Horticulture Bioplastic Market
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Bacterial Biopesticides Market