
 Europe Biocontrol Agents Market | 2026-2036
Europe Biocontrol Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biocontrol Agents Market Insights
A capital-intensity divergence between fermentation-based manufacturers and field-service distributors is rotating competitive advantage toward firms with captive bioproduction capacity. Koppert B.V. leverages its Dutch breeding infrastructure to sustain year-round beneficial insect supply chains. Biobest Group NV anchors its position through bumblebee pollination and biocontrol integration across Mediterranean greenhouse clusters. E-NEMA GmbH specializes in nematode cultivation systems that dominate Central European soil-borne pest segments.
Biocontrol agents comprise living organisms and naturally derived compounds that suppress agricultural pests through predation, parasitism, competition, or antibiosis, typically requiring formulation densities of 10^6–10^9 colony-forming units per gram for viable field efficacy. Microbial products command the largest revenue share due to Bacillus thuringiensis and Trichoderma-based portfolios with established efficacy dossiers under EU Regulation 1107/2009. Plant Extracts represent the fastest-expanding category as pyrethrin and azadirachtin formulations gain emergency use approvals for resistance management in high-value horticultural crops.
EMA and EFSA govern active substance approval timelines under EU Regulation 1107/2009, while the EU Green Deal pesticide reduction targets are reshaping product registration incentives and farmer subsidy structures. REACH compliance for biochemical metabolites adds toxicological testing burdens that favor larger dossier sponsors with dedicated regulatory affairs teams. Stakeholders must monitor the EU's pending revision of sustainable use of pesticides directive, as this will determine whether biocontrol substitutes qualify for accelerated national authorization pathways.
Market Dynamics
The EU Green Deal's pesticide reduction mandates are compressing farmer decision timelines, forcing rapid substitution of synthetic chemistries with biological alternatives across specialty crop systems. This regulatory pressure is reshaping capital allocation toward fermentation infrastructure and field-service networks.
Growth Catalysts
- Farm to Fork Strategy:The EU's binding pesticide reduction targets are redirecting national subsidy structures toward biocontrol adoption in French viticulture and Spanish greenhouse horticulture.
- Resistance management protocols:Vineyard operators in Bordeaux and Champagne are integrating Bacillus thuringiensis and Trichoderma-based products into integrated pest management rotations.
- Greenhouse cluster densification:Mediterranean vegetable producers in Almería and Sicily are scaling microbial inoculant programs for soil-borne pest suppression.
Market Restraints
- REACH compliance burdens:Toxicological testing requirements for biochemical metabolites favor larger dossier sponsors with dedicated regulatory affairs teams, excluding smaller innovators.
- Formulation stability constraints:Microbial products requiring 10^6–10^9 colony-forming units per gram face viability degradation in non-refrigerated distribution channels.
- Synthetic pesticide price competition:Generic agrochemicals continue to undercut biological alternatives on per-hectare cost metrics in broad-acre cereal production.
Strategic Opportunities
- Central European nematode segments:Soil-borne pest pressure in German and Polish vegetable production creates demand for specialized entomopathogenic nematode cultivation systems.
- Plant extract emergency approvals:Pyrethrin and azadirachtin formulations are gaining accelerated authorization pathways for resistance management in high-value horticultural crops.
- Bumblebee pollination integration:Mediterranean greenhouse operators are bundling biocontrol with pollination services, creating stickier supplier relationships.
Industry Challenges
- Regulatory timeline unpredictability:EMA and EFSA active substance approval timelines under EU Regulation 1107/2009 create multi-year revenue recognition gaps for novel microbial strains.
- Technical formulation expertise scarcity:Fermentation-based manufacturing requires specialized bioprocess engineering talent that concentrates in Dutch and German research clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biocontrol Agents Market |
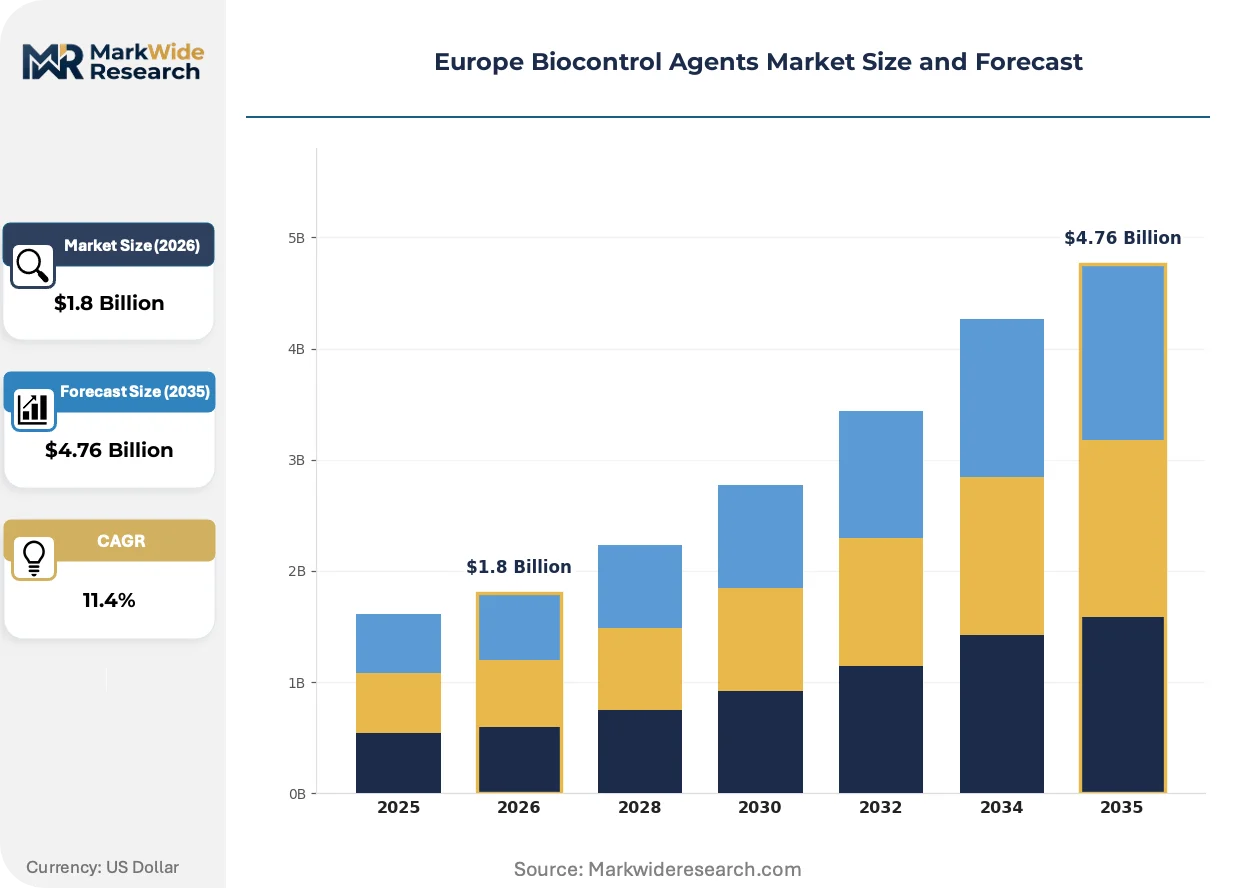
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Biochemical, Plant Extracts, Insect Growth Regulators Application: Agricultural Crops, Horticultural Plants, Turf, Ornamental Plants End User: Farmers, Agronomists, Distributors, Agricultural Cooperatives Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | E-NEMA GmbH, Andermatt Group AG, Koppert B.V., OpenNatur, Dragonfli, Biobest Group NV, Bioplanet France, VIRIDAXIS SA, Bioline AgroSciences Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biocontrol Agents Market Trends and Innovations
Biocontrol markets are experiencing technology convergence between precision agriculture platforms and biological product delivery systems. This integration is compressing application windows and raising efficacy expectations.
RNA interference-based biopesticides are supplanting conventional microbial sprays in targeted lepidopteran pest management. Dutch greenhouse operators are piloting these sequence-specific solutions for tomato leafminer control. The technology is supplanting broad-spectrum chemistries by reducing non-target organism impacts and shortening pre-harvest intervals.
REACH compliance revisions for biochemical metabolites are extending toxicological data requirements for novel active substances. ECHA's expanded dossier demands are filtering market entrants toward established players with captive testing infrastructure. Microbial product categories face the heaviest documentation burdens, accelerating consolidation around firms with dedicated regulatory affairs capabilities.
Buyer concentration among large vineyard cooperatives and greenhouse consortiums is shifting procurement toward multi-year supply agreements with embedded technical advisory services. French winegrower associations in Languedoc-Roussillon are negotiating consolidated biocontrol contracts that bundle product supply with integrated pest management protocol design. This behavior concentrates demand volume with vertically integrated suppliers possessing both manufacturing and field-service capabilities.
Europe Biocontrol Agents Market Segmentation
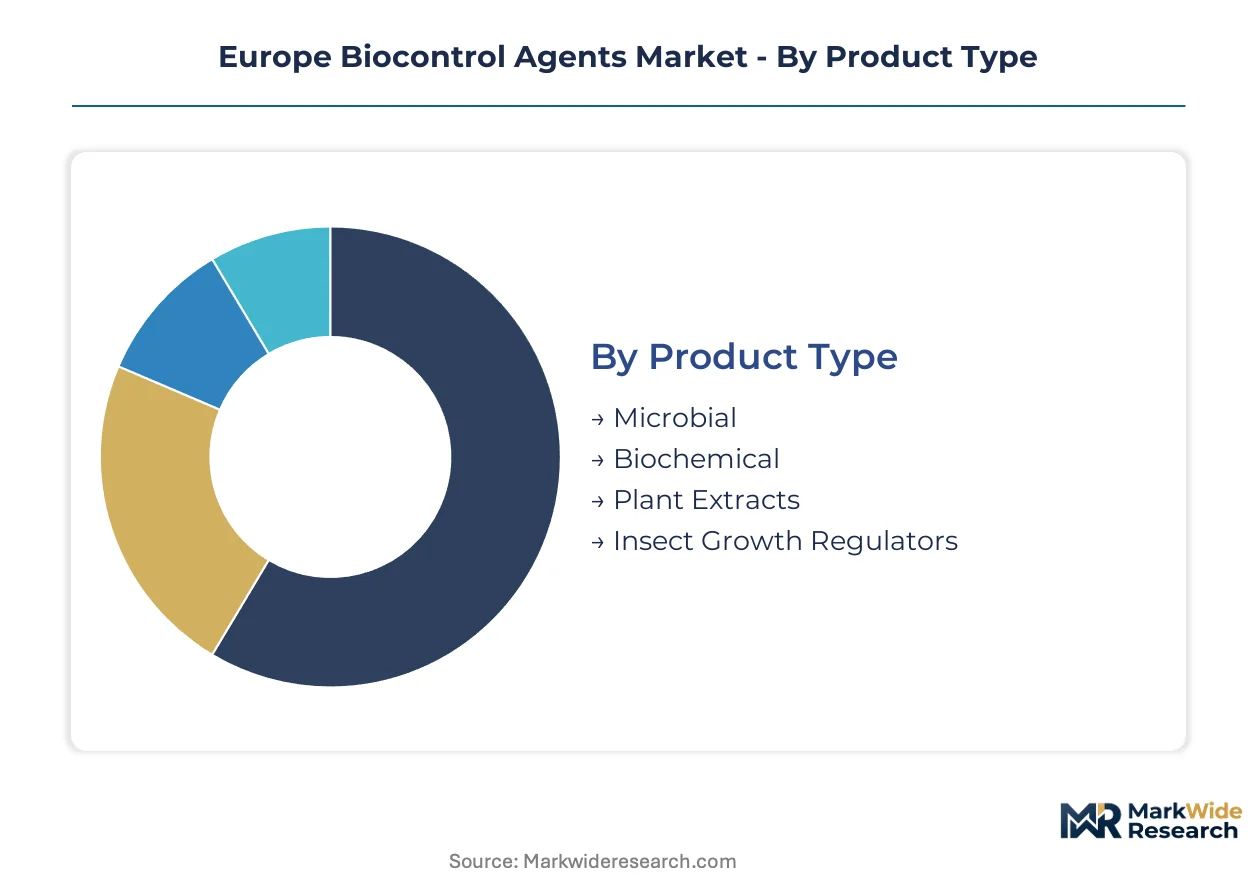
EU Regulation 1107/2009 creates distinct approval pathways for each product category, fragmenting competitive positioning across microbial dossiers, biochemical metabolites, and plant-derived substances. Segmentation clarity enables stakeholders to align R&D investment with regulatory timeline risk and end-use concentration patterns.
Product Type:
EMA and EFSA distinguish microbial strains from biochemical metabolites and plant extracts through divergent toxicological data requirements, concentrating dossier sponsorship among firms with dedicated regulatory infrastructure.
- Microbial:Living organisms including Bacillus thuringiensis and Trichoderma formulations require 10^6–10^9 colony-forming units per gram for viable field efficacy. Vineyard operators in Bordeaux and Champagne are integrating these into integrated pest management rotations as resistance management protocols tighten.
- Biochemical:Naturally occurring compounds like pheromones and plant growth regulators face REACH compliance burdens that extend toxicological testing timelines. ECHA's expanded dossier demands filter market entrants toward established players with captive testing infrastructure.
- Plant Extracts:Pyrethrin and azadirachtin formulations are climbing the fastest as emergency use approvals accelerate for high-value horticultural crops in Mediterranean greenhouse clusters.
- Insect Growth Regulators:Chitin synthesis inhibitors and juvenile hormone analogs target specific developmental stages of pest populations.
Established volume favors Microbial; emerging adoption favors Plant Extracts.
Application:
Cost tier differentiation separates high-input specialty systems from broad-acre commodity production, with per-hectare biocontrol economics determining feasible crop categories.
- Agricultural Crops:Cereal and oilseed production faces synthetic pesticide price competition that undercuts biological alternatives on per-hectare metrics. German and Polish vegetable operations present exceptions where soil-borne pest pressure justifies premium biological inputs.
- Horticultural Plants:Greenhouse vegetables in Almería and Sicily are scaling microbial inoculant programs, with Mediterranean cluster densification compressing application windows and raising efficacy expectations.
- Turf:Golf course and sports field maintenance in France and Germany drives demand for nematode-based solutions against scarab larvae and cutworms.
- Ornamental Plants:Dutch floriculture operations bundle biocontrol with precision agriculture platforms for thrips and whitefly management in chrysanthemum and rose production.
Margin concentration sits with Horticultural Plants; volume potential resides in Agricultural Crops.
End User:
Customer type determines procurement complexity, with consolidated cooperatives negotiating multi-year supply agreements while fragmented farmer bases require embedded technical advisory services.
- Farmers:Individual operators in French viticulture and Spanish greenhouse horticulture are redirecting toward biological alternatives as national subsidy structures realign under Farm to Fork mandates.
- Agronomists:Technical consultants design integrated pest management protocols that bundle product recommendations with scouting services, creating stickier supplier relationships in Languedoc-Roussillon winegrower associations.
- Distributors:Wholesale intermediaries face formulation stability constraints as microbial products degrade in non-refrigerated channels, favoring suppliers with cold-chain logistics.
- Agricultural Cooperatives:Large vineyard operators and greenhouse consortiums are shifting procurement toward vertically integrated suppliers possessing both manufacturing and field-service capabilities.
Technical influence concentrates with Agronomists; purchasing volume aggregates through Agricultural Cooperatives.
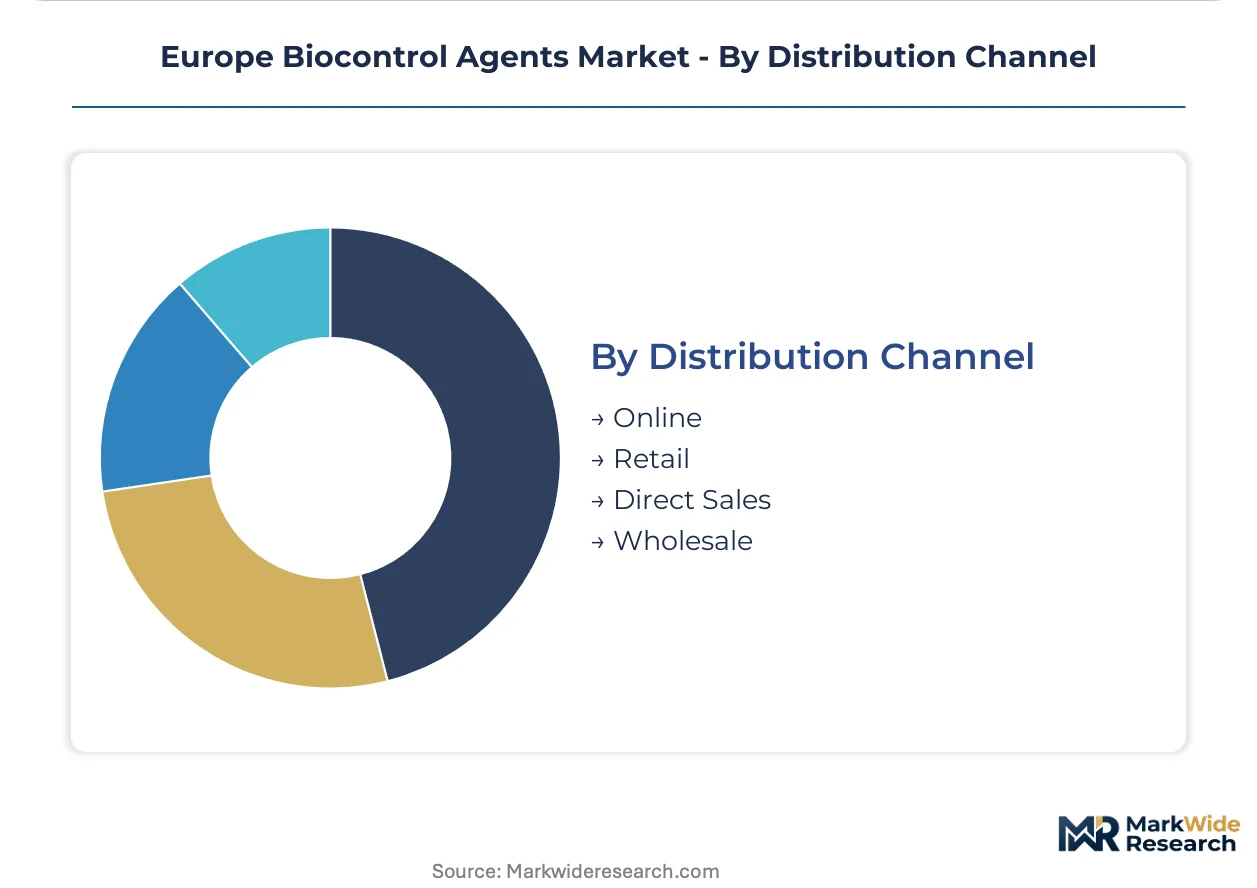
Distribution Channel:
Supply chain configuration determines product viability for temperature-sensitive biological formulations, with direct manufacturer relationships outperforming arm's-length retail for microbial categories.
- Direct Sales:Fermentation-based manufacturers leverage captive bioproduction capacity to sustain year-round supply chains through technical advisory relationships with large vineyard cooperatives.
- Wholesale:Central European distributors aggregate nematode demand from German and Polish vegetable producers, though refrigerated logistics requirements limit viable intermediaries.
- Retail:Brick-and-mortar agricultural supply stores serve fragmented farmer bases with established microbial brands carrying EU 1107/2009 approval dossiers.
- Online:Digital procurement channels are expanding for plant extract formulations with extended shelf stability, particularly for resistance management in high-value horticultural crops.
Service integration favors Direct Sales; reach expansion favors Wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spanish greenhouse operators demonstrate the highest price elasticity for biocontrol inputs, while French vineyard cooperatives absorb premium pricing for integrated pest management bundles. German vegetable producers occupy a middle tier where soil-borne pest pressure justifies biological premiums. Dutch floriculture clusters represent the least price-sensitive demand segment due to bundled pollination service contracts.
France
Vineyard operators in Bordeaux and Champagne drive demand for Bacillus thuringiensis and Trichoderma-based products as resistance management protocols tighten. The EU Green Deal pesticide reduction targets redirect national subsidy structures toward biological alternatives in Languedoc-Roussillon winegrower associations. Large cooperatives in Provence-Alpes-Côte d'Azur negotiate consolidated multi-year supply agreements with embedded technical advisory services.
Spain
Greenhouse vegetable producers in Almería scale microbial inoculant programs for soil-borne pest suppression under Farm to Fork Strategy mandates. Mediterranean cluster densification compresses application windows and raises efficacy expectations for biological formulations. Andalusian operators bundle biocontrol with precision agriculture platforms across expanding protected cultivation acreage.
Germany
Vegetable operations in Lower Saxony and Bavaria create demand for specialized entomopathogenic nematode cultivation systems against soil-borne pest pressure. REACH compliance for biochemical metabolites extends toxicological data requirements, filtering market entrants toward established players. Central European distribution networks aggregate nematode demand through refrigerated logistics channels serving Polish border regions.
Netherlands
Floriculture clusters in Randstad and Brabant bundle biocontrol with bumblebee pollination services, creating stickier supplier relationships. Dutch breeding infrastructure sustains year-round beneficial insect supply chains for greenhouse thrips and whitefly management. Eindhoven Region research clusters concentrate specialized bioprocess engineering talent for fermentation-based manufacturing.
Italy
Sicilian greenhouse operators expand microbial inoculant adoption for vegetable production under EU sustainable use of pesticides directive revisions. Lombardy and Emilia-Romagna specialty crop systems integrate biological alternatives into integrated pest management rotations. Northern Italian distributors face formulation stability constraints as microbial products degrade in non-refrigerated channels.
Europe Biocontrol Agents Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with fermentation-based manufacturers commanding premium positioning while field-service distributors compete on coverage density. The market structure concentrates around firms with captive bioproduction capacity, excluding smaller innovators lacking dedicated regulatory affairs teams. Three archetypes dominate: Dutch-German breeding specialists, Mediterranean pollination-integrated service providers, and Central European nematode cultivators. Competitive moves center on backward integration into fermentation infrastructure and multi-year supply agreement negotiations with consolidated cooperatives.
Among Dutch breeding specialists, Koppert B.V. and Biobest Group NV exemplify the pollination-integrated service archetype, anchoring positions through technical advisory relationships with Mediterranean greenhouse clusters. E-NEMA GmbH occupies a position within the Central European nematode specialization tier. These three entities represent the dominant competitive positioning patterns visible across the player set, with geographic origin and corporate structure signaling strategic focus areas without requiring specific operational claims.
| Leading Market Players |
|---|
| E-NEMA GmbH |
| Andermatt Group AG |
| Koppert B.V. |
| OpenNatur |
| Dragonfli |
| Biobest Group NV |
| Bioplanet France |
| VIRIDAXIS SA |
| Bioline AgroSciences Ltd |
| Others |
Pricing and Supply Chain Analysis
Fermentation facility utilization rates above 80% in Dutch and German production clusters compress marginal costs for microbial formulations while erecting price floors that exclude smaller competitors lacking captive bioproduction capacity. Scale concentration in these regions concentrates pricing power with integrated manufacturers serving large vineyard cooperatives and greenhouse consortiums.
Pricing Analysis
Technical advisory contracts bundled with multi-year product supply agreements drive lifetime value for biocontrol manufacturers serving French winegrower associations. Pricing stratifies across premium, standard, and economy tiers based on EU 1107/2009 dossier completeness and cold-chain logistics integration. Cost compression in standard-tier microbial products intensifies as generic Bacillus thuringiensis formulations proliferate. Spanish greenhouse operators demonstrate highest price sensitivity, while Dutch floriculture clusters absorbing bundled pollination services show least elasticity.
Supply Chain Analysis
Refrigerated logistics chokepoints across Mediterranean distribution corridors constrain viable pathways for temperature-sensitive nematode and microbial products. Manufacturing concentrates in the Netherlands, Germany, and Belgium, with these countries housing specialized fermentation infrastructure and beneficial insect breeding facilities. Raw material dependencies span agricultural substrates for microbial cultivation, sterile packaging materials, and entomopathogenic nematode host organisms. Single-source vulnerability concentrates in Dutch bumblebee breeding stock. Distribution runs through direct manufacturer relationships with large cooperatives, supplemented by wholesale aggregation for fragmented vegetable producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
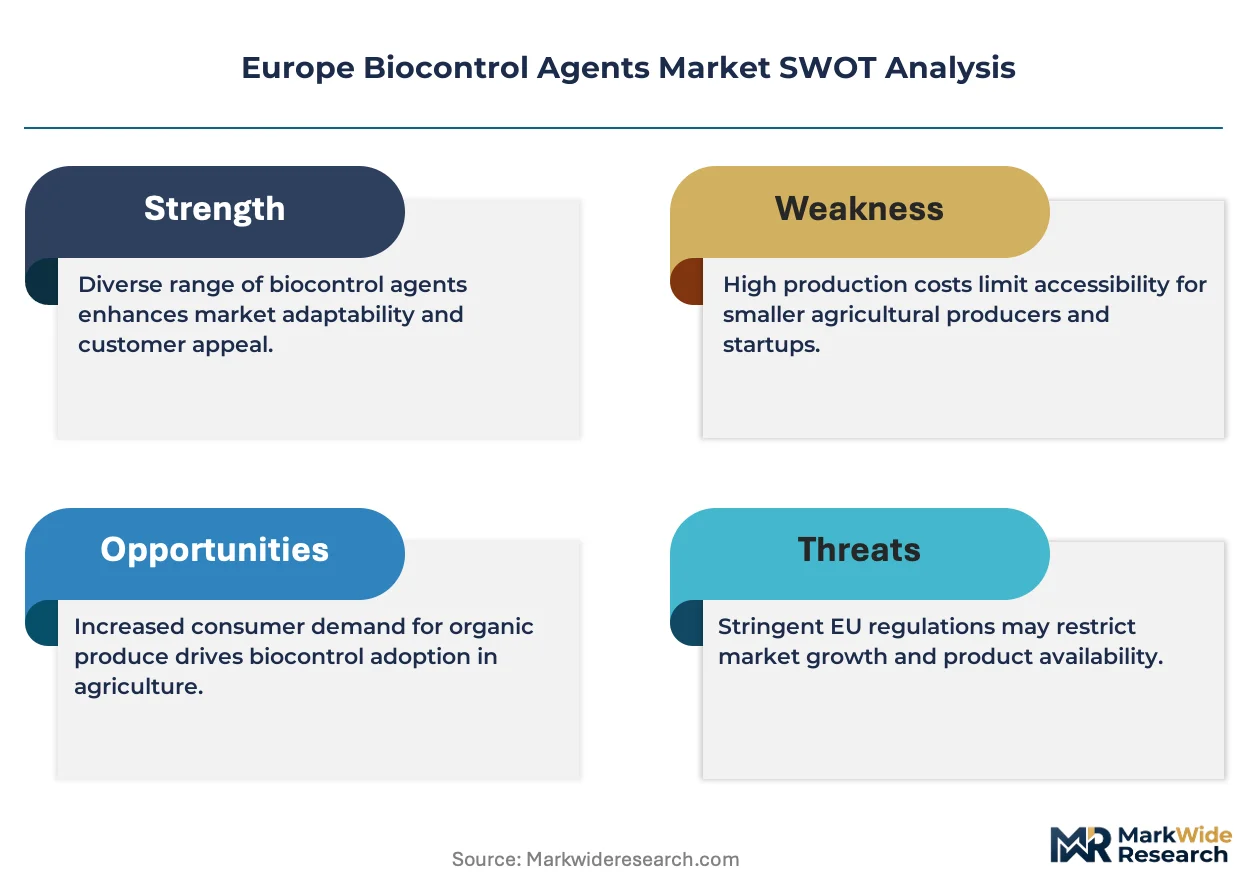
EU Green Deal pesticide reduction mandates fragment demand across specialty crop systems, creating white-space opportunities for differentiated biocontrol positioning beyond commodity microbial formulations.
For Market Incumbents: Fortify captive bioproduction capacity through fermentation infrastructure expansion in the Netherlands and Germany to defend against emerging RNA interference biopesticide substitutes. Prioritize EU 1107/2009 dossier investment for novel Trichoderma strains to extend regulatory moats. Deepen backward integration into beneficial insect breeding programs to secure year-round supply continuity. For New Entrants and Emerging Players: Emergency use authorization fast-tracks for pyrethrin and azadirachtin plant extracts in Mediterranean greenhouse clusters offer lowest barrier to revenue traction. Target Sicilian and Almería vegetable producers with resistance management formulations bypassing multi-year microbial approval timelines. Deploy agronomist-embedded technical advisory services as primary go-to-market channel to build sticky supplier relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated specialists with captive regulatory affairs capabilities over pure-play distributors. Long-term viability hinges on fermentation-based manufacturing scale and EU dossier sponsorship concentration. Acquisition screening should prioritize Dutch-German breeding infrastructure owners. Monitor EFSA active substance approval velocity as inflection signal for revenue recognition predictability.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Expansion | EU 1107/2009 approval concentration determines market access for novel microbial strains in French viticulture. |
| Cold-Chain Logistics Investment | Refrigerated distribution capabilities unlock nematode segments in German and Polish vegetable production. |
| Technical Advisory Integration | Embedded IPM protocol design creates multi-year contract stickiness with Languedoc-Roussillon cooperatives. |
| RNA Interference Pipeline Development | Sequence-specific biopesticides target lepidopteran pests in Dutch tomato leafminer control trials. |
| Beneficial Insect Breeding Scale-Up | Year-round bumblebee supply chains anchor bundled pollination-biocontrol offerings across Mediterranean greenhouses. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with vineyard managers, greenhouse technical directors, agricultural cooperative procurement leads, and regulatory affairs specialists at fermentation-based manufacturers. Secondary validation drew from EFSA active substance approval databases, EU Green Deal implementation progress reports, customs trade data for biocontrol product categories, and SEC filings of publicly listed agribiological firms. Bottom-up volume estimates from individual country crop protection expenditures were triangulated against top-down market sizing from regulatory dossier counts.
Across the analysis window, the forecasting framework modeled product type segmentation by regulatory pathway complexity, application segmentation by crop value intensity, and end-user segmentation by procurement consolidation level. CAGRs were derived from trajectory fitting to historical adoption curves for biological substitutes in comparable regulatory environments. Industry-specific inputs incorporated Farm to Fork Strategy implementation timelines and REACH compliance cost escalation patterns for biochemical metabolites.
Underlying assumptions cover EU pesticide reduction target adherence, EFSA approval velocity stability, and refrigerated logistics network expansion, with deviation risk concentrated in regulatory timeline unpredictability and synthetic pesticide price volatility. Practitioners should keep alternative scenarios live as EU sustainable use of pesticides directive revisions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
China Agricultural Biologicals Market
Bio-Agriculture
Seed Biostimulants Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Latin America Biostimulants Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Asia-Pacific Biological Organic Fertilizers Market
Bio-Agriculture
Microphytes Market
Bio-Agriculture
Lignocellulosic Biomass Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
Asia-Pacific Bio-Ethanol Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
Red Algae Market
Bio-Agriculture
Hydroponics Market
Bio-Agriculture
Biochar Machine Market