
 South America Passenger Cars Market | 2026-2036
South America Passenger Cars Market Size, Share, and Industry Trends Forecast 2026-2036
South America Passenger Cars Market Analytics
A multi-source component strategy is decoupling from the single-source legacy that long defined South American auto assembly. Stellantis leverages its Betim complex to sustain flexible-fuel and hybrid output across multiple brands. Toyota Motor Corporation anchors hybrid penetration through localized powertrain production in São Bernardo do Campo. Volkswagen AG competes on manufacturing scale at its Anchieta and Taubaté plants.
Passenger cars are four-wheeled motor vehicles designed primarily for personal transport, typically seating two to seven occupants and powered by internal combustion, electric, or hybrid propulsion systems with unladen weights below 3,500 kilograms. Their primary commercial purpose is to deliver individual mobility, fleet utilization, and rental services across urban and interurban road networks. SUV configurations now command the largest volume share within vehicle type segmentation, driven by ride-height preference and perceived safety across Brazilian and Argentine buyers. Hybrid fuel type variants represent the fastest-expanding category as Proconve standards tighten and local biofuel blending infrastructure supports flexible-fuel hybrid architectures. Individual customers dominate end user segmentation, though fleet operators generate superior margin pools through volume contracts and predictable replacement cycles.
Brazil's national environmental council (CONAMA) and Argentina's transport ministry enforce emission and safety frameworks that dictate powertrain availability and homologation timelines across the Mercosur trade zone. ANVISA in Brazil and the national automotive regulatory bodies in Argentina shape cabin air quality standards and material substance restrictions that filter into supplier specifications. Stakeholders must monitor how Mercosur-EU trade negotiations and local content rule modifications alter competitive positioning for OEMs versus importers.
Market Dynamics
Proconve emission standards in Brazil are compressing powertrain development cycles and forcing OEMs to accelerate hybrid and flexible-fuel architectures ahead of original timelines.
Growth Catalysts
- Proconve L7 and L8 mandates:Brazil's CONAMA-enforced emission tiers are compelling powertrain diversification and expanding hybrid vehicle availability across the São Paulo industrial corridor.
- Biofuel blending infrastructure:Brazil's established ethanol distribution network supports flexible-fuel hybrid architectures that reduce consumer fuel cost volatility and improve fleet operator total cost of ownership calculations.
- Fleet electrification procurement:Corporate and rental fleet operators in Argentina's Córdoba manufacturing cluster are expanding electrified vehicle contracts to meet sustainability targets and predict maintenance spend.
Market Restraints
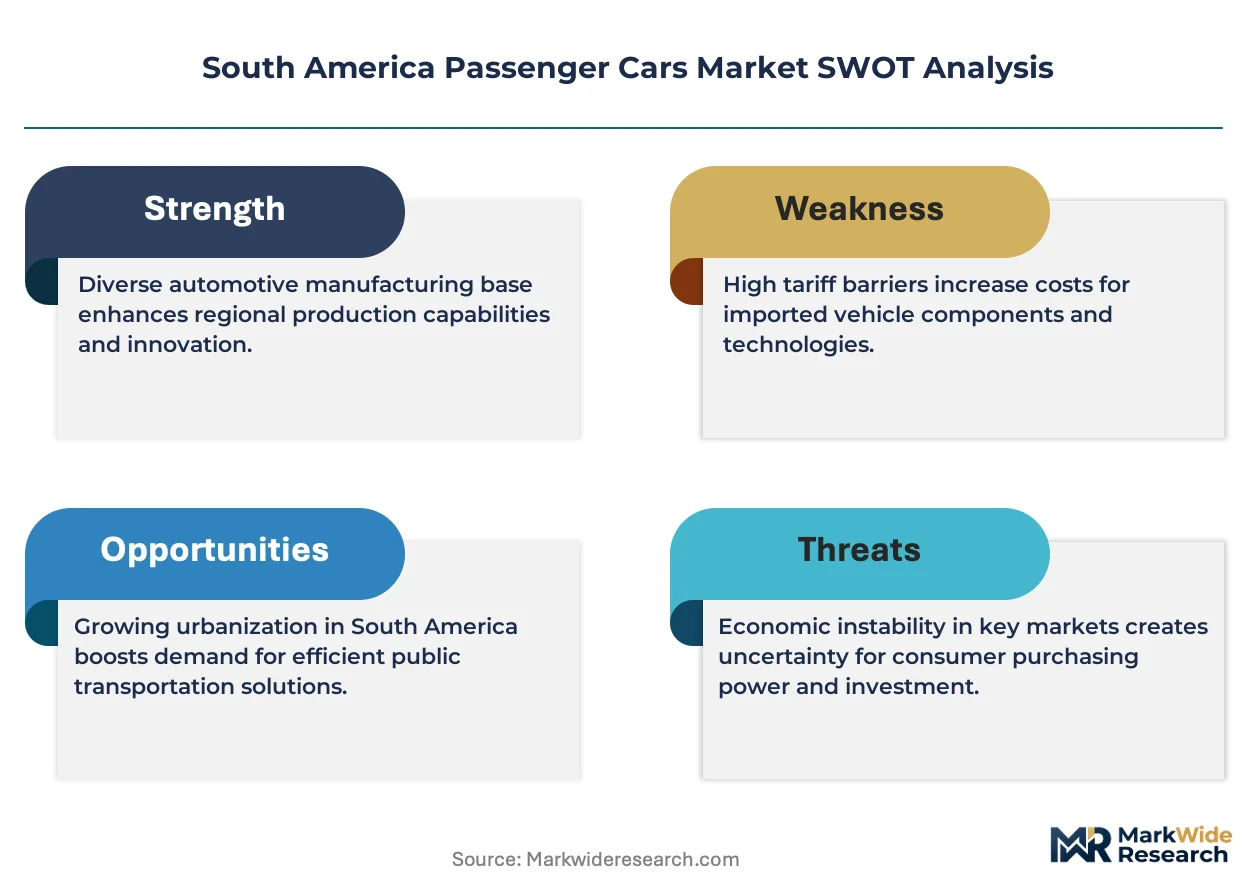
- Lithium-ion cell supply concentration:Battery pack assembly depends on imported cells from concentrated Asian suppliers, exposing Brazilian and Argentine OEMs to currency fluctuation and logistics disruption risks.
- Local content requirement friction:Argentina's domestic component mandates create homologation delays for imported hybrid powertrains and restrict model availability relative to consumer demand timing.
- Charging infrastructure gaps:Urban concentration of fast-charging stations in São Paulo and Buenos Aires leaves interurban corridors underserved, constraining pure-electric vehicle penetration outside metropolitan radii.
Strategic Opportunities
- Colombian market underpenetration:Hybrid and flexible-fuel vehicle availability remains limited in Colombian urban centers, creating first-mover positioning for OEMs with established Mercosur production bases.
- Subscription mobility services:Technology-enabled vehicle subscription platforms are emerging as alternatives to traditional ownership and long-term leasing in Brazilian metropolitan markets.
- Battery second-life applications:Retired electric vehicle packs present stationary energy storage opportunities for industrial facilities in Argentina's renewable energy zones.
Industry Challenges
- Powertrain engineering talent scarcity:Brazilian and Argentine technical universities produce insufficient hybrid-electric and battery management system specialists to match OEM hiring velocity.
- Homologation timeline compression:Accelerated Proconve phase-in schedules strain ANVISA and national automotive regulatory body certification capacities, delaying market launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Passenger Cars Market |
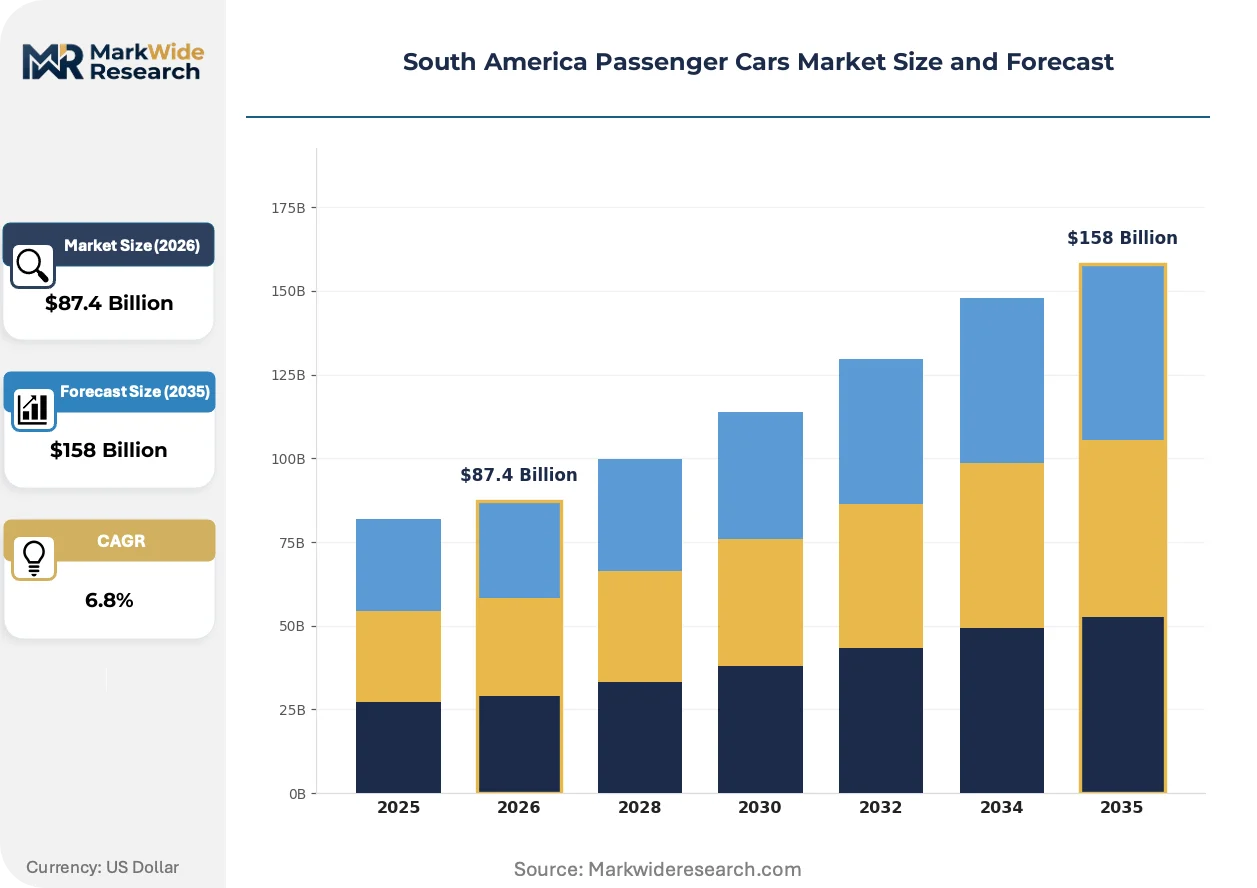
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Sedan, Hatchback, SUV, Coupe Fuel Type: Petrol, Diesel, Electric, Hybrid End User: Individual Customers, Fleet Operators, Rental Services, Dealerships Manufacturing Stage: OEM, Aftermarket, New Production, Assembly |
| Companies Covered | Stellantis, Volkswagen AG, General Motors Company, Toyota Motor Corporation, Ford Motor Company, Renault S.A., Honda Motor Co., Ltd., Hyundai Motor Company, Nissan Motor Co., Ltd., Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Passenger Cars Market Evolving Landscape
Powertrain electrification is restructuring competitive advantage around localized hybrid system production and biofuel-compatible architectures rather than scale economies in pure combustion engineering.
Flexible-fuel hybrid systems are overtaking conventional gasoline-only powertrains in Brazilian consumer preference. These architectures combine electric motor assist with ethanol-capable combustion engines to optimize fuel cost across Brazil's variable ethanol-gasoline price ratios. São Paulo-based OEMs are capturing margin compression from pure-electric competitors by leveraging existing biofuel infrastructure rather than requiring parallel charging network investments.
Argentina's transport ministry is tightening local content enforcement for Mercosur trade zone vehicle eligibility. This regulatory pressure is redirecting supplier sourcing from Asian component imports to Argentine and Brazilian tier-one manufacturing investments. Hybrid powertrain assemblers are responding by qualifying domestic battery pack and electric motor suppliers ahead of 2025 certification deadlines.
Fleet operators are consolidating procurement decisions into centralized sustainability and total cost of ownership frameworks. Rental and corporate fleet managers in Brazil are displacing decentralized regional purchasing with national contracts tied to carbon reporting requirements and predictable replacement cycles. This concentration is visible in São Paulo and Rio de Janeiro metropolitan fleet tenders prioritizing hybrid vehicle minimum share clauses.
South America Passenger Cars Market Segmentation
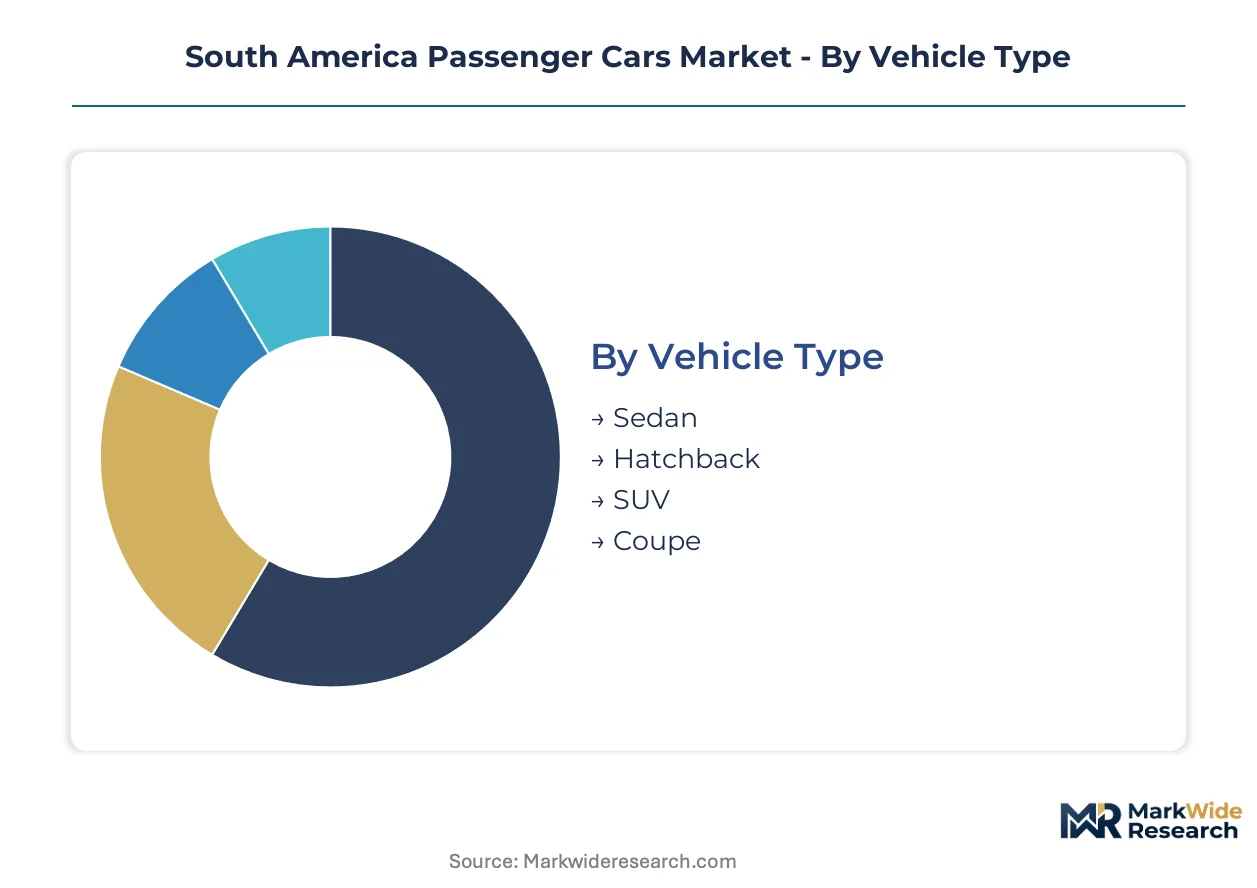
Segmentation in the South America passenger cars market reveals how Proconve emission tiers and local content rules differentially impact vehicle configurations across Brazilian and Argentine production corridors. Understanding these divides enables OEMs to align powertrain portfolios with regulatory enforcement intensity and consumer preference clusters.
Vehicle Type:
SUV configurations operate as standalone platform decisions with dedicated chassis engineering, while sedans and hatchbacks increasingly embed within flexible-architecture programs to amortize hybrid powertrain investments.
- SUV:Elevated ride-height platforms dominate Brazilian consumer preference through perceived safety advantages and flood-resistance utility in São Paulo's variable drainage infrastructure. São Paulo metropolitan dealerships report sustained inventory velocity for compact and mid-size SUV segments as fleet operators prioritize residual value retention.
- Hatchback:Compact two-box designs concentrate in Argentina's Córdoba manufacturing cluster where Stellantis and Volkswagen anchor flexible-fuel production for urban density-optimized mobility. Local content requirements favor hatchback scale economics over sedan derivatives for Mercosur trade zone distribution.
- Sedan:Three-box configurations retain corporate fleet procurement share in Brazilian executive transport segments.
- Coupe:Two-door variants occupy niche positioning within premium import channels.
Volume placements concentrate in SUV configurations; the faster expansion belongs to hatchback segments as urban congestion intensifies across Argentine and Brazilian metropolitan cores.
Fuel Type:
Cost tier stratification separates established liquid fuel infrastructure from emerging electrification investments, with hybrid architectures capturing intermediate positioning through biofuel compatibility.
- Hybrid:Dual-powertrain systems combining electric motor assist with ethanol-capable combustion engines optimize fuel cost volatility across Brazil's variable ethanol-gasoline price ratios. São Paulo-based OEMs leverage existing biofuel distribution infrastructure rather than requiring parallel charging network investments, compressing total cost of ownership for fleet operators.
- Electric:Battery-electric platforms face charging infrastructure gaps outside São Paulo and Buenos Aires metropolitan radii, constraining penetration to urban subscription services and corporate sustainability mandates.
- Petrol:Gasoline-only powertrains retain volume in price-sensitive entry segments.
- Diesel:Compression-ignition engines concentrate in commercial-adjacent passenger applications.
Manufacturing investments flow toward hybrid architectures; pure-electric segments climb fastest where municipal charging procurement accelerates.
End User:
Customer type determines contract structure complexity, with individual transactions requiring retail financing infrastructure while fleet and rental procurement centralizes through sustainability-linked national tenders.
- Fleet Operators:Corporate and rental fleet managers displace decentralized regional purchasing with centralized contracts tied to carbon reporting requirements and predictable replacement cycles. São Paulo and Rio de Janeiro metropolitan tenders now embed hybrid vehicle minimum share clauses.
- Individual Customers:Retail purchasers drive configuration diversity through financing-accessible entry segments and premium aspiration segments, with São Paulo industrial corridor dealerships capturing margin through extended warranty and service bundling.
- Rental Services:Short-term mobility providers concentrate procurement in residual-value-optimized segments.
- Dealerships:Franchise networks intermediate inventory risk and local homologation compliance.
Transaction volume concentrates in individual customer channels; fleet operator segments gain share fastest as sustainability reporting mandates proliferate.
Manufacturing Stage:
Supply concentration distinguishes captive OEM assembly from aftermarket parts distribution, with local content enforcement redirecting sourcing from import dependency to Argentine and Brazilian tier-one investments.
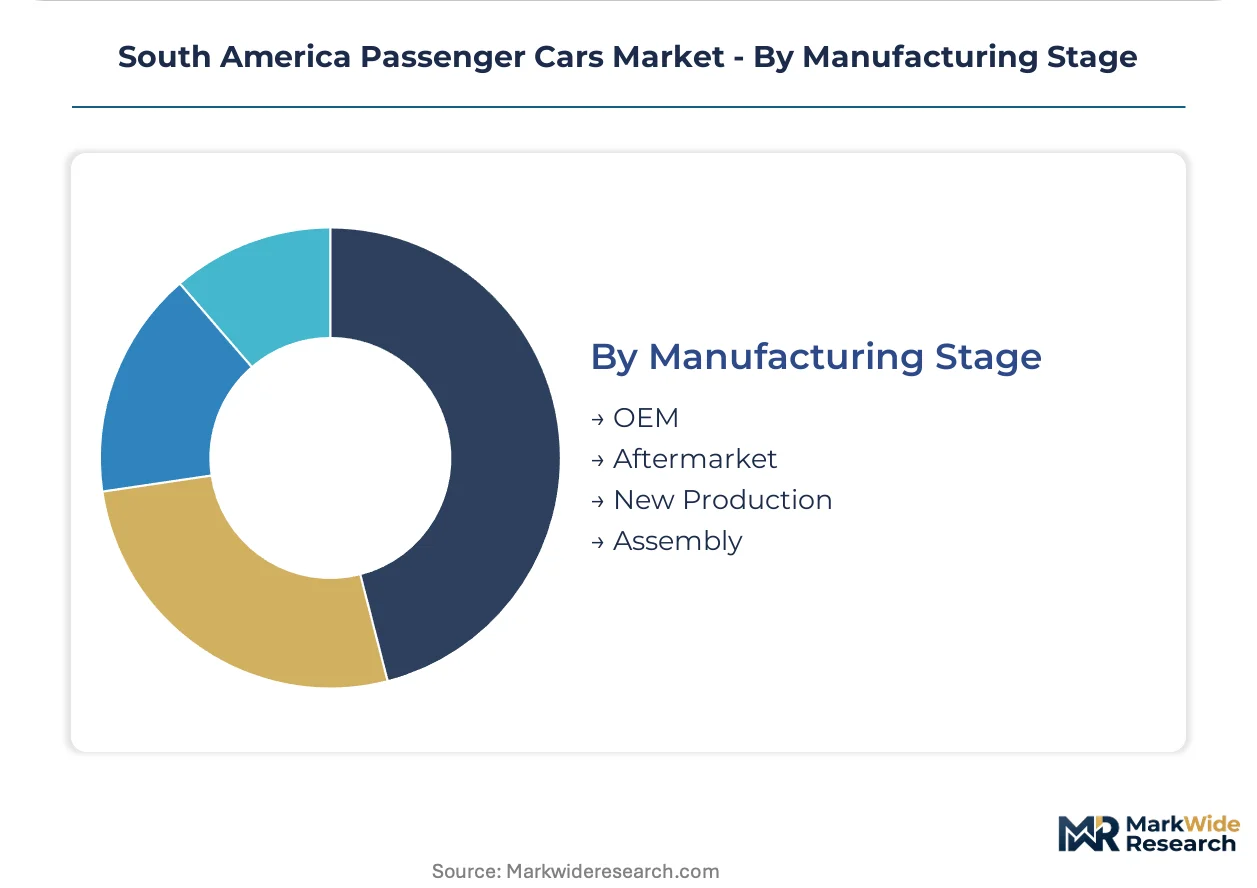
- OEM:Original equipment manufacturers anchor production at Stellantis Betim, Toyota São Bernardo do Campo, and Volkswagen Anchieta complexes, with hybrid powertrain assemblers qualifying domestic battery pack and electric motor suppliers ahead of certification deadlines. Argentina's transport ministry tightening of local content enforcement redirects supplier sourcing from Asian component imports.
- Assembly:Knock-down kit operations concentrate in Mercosur trade zone adjacency zones to optimize tariff positioning.
- Aftermarket:Parts distribution networks serve aging fleet maintenance demand.
- New Production:Greenfield capacity additions remain constrained by powertrain engineering talent scarcity.
Installed capacity concentrates in OEM-integrated manufacturing; assembly operations expand fastest as regional trade rule modifications alter competitive positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's ethanol feedstock belt anchors South American passenger car manufacturing, with sugarcane-derived biofuel infrastructure shaping powertrain investment patterns across the Mercosur trade zone.
Brazil
Proconve L7 and L8 emission mandates from CONAMA accelerate hybrid powertrain diversification. São Paulo's industrial corridor hosts Stellantis Betim and Toyota São Bernardo do Campo complexes where flexible-fuel hybrid assembly expands. Fleet operators in the metropolitan region embed minimum hybrid share clauses into centralized procurement tenders.
Argentina
Local content requirements from the transport ministry redirect supplier sourcing toward domestic tier-one manufacturing. Córdoba's manufacturing cluster concentrates hatchback production for Mercosur distribution. Stellantis and Volkswagen anchor flexible-fuel output to optimize trade zone tariff positioning.
Colombia
Urban congestion intensifies demand for compact vehicle configurations in Bogotá and Medellín metropolitan areas. National biofuel blending mandates support flexible-fuel hybrid penetration. Import dependency persists for electrified powertrains as local assembly remains underdeveloped.
Chile
Corporate sustainability reporting requirements drive fleet electrification procurement in Santiago's corporate transport segment. Lithium extraction from the Atacama Desert creates battery supply chain proximity advantages. Charging infrastructure concentrates in metropolitan radii with interurban corridor gaps.
Uruguay
Renewable energy grid composition supports electric vehicle operating cost advantages for Montevideo-based fleet operators. Small market scale limits OEM direct investment. Import channels from Argentine and Brazilian production bases dominate vehicle availability.
South America Passenger Cars Market Competitive Landscape
Capacity expansion dominates the current landscape as OEMs localize hybrid powertrain assembly ahead of Proconve certification deadlines. The market structure consolidates around established Mercosur production bases with high barriers to greenfield entry. Three archetypes define competitive positioning: diversified global OEMs with multi-brand portfolios, Japanese specialists in hybrid system integration, and Korean challengers scaling regional distribution. M&A activity and strategic supplier partnerships represent the dominant competitive moves as firms secure domestic battery pack and electric motor qualification.
Within the diversified global OEM tier, Stellantis N.V. and Volkswagen AG exemplify scale-driven positioning through captive Brazilian manufacturing complexes. Toyota Motor Corporation occupies the hybrid specialist archetype with localized powertrain production in São Bernardo do Campo. These three anchors demonstrate how Mercosur trade zone access and local content compliance separate viable competitors from import-dependent challengers.
| Leading Market Players |
|---|
| Stellantis |
| Volkswagen AG |
| General Motors Company |
| Toyota Motor Corporation |
| Ford Motor Company |
| Renault S.A. |
| Honda Motor Co., Ltd. |
| Hyundai Motor Company |
| Nissan Motor Co., Ltd. |
| Others |
Value Network & Pricing Analysis
Brazilian ethanol price benchmarks cascade through hybrid powertrain cost structures, compressing margins for gasoline-only architectures while elevating flexible-fuel hybrid competitiveness across São Paulo's fleet procurement corridors. This commodity-linked pricing architecture splits the market into biofuel-compatible premium tiers and legacy-combustion economy segments.
Pricing Analysis
Extended warranty and service bundling separate premium from unbundled economy offerings, with São Paulo dealerships capturing margin through maintenance-included financing packages. Three-tier pricing structure across premium, standard, and economy levels reflects Proconve certification grade and local content compliance. Cost compression in entry segments intensifies as Argentine import-dependent challengers undercut Mercosur-qualified OEMs. Fleet operators exhibit lowest price sensitivity due to total cost of ownership frameworks, while individual retail purchasers drive aggressive discounting in volume hatchback segments.
Supply Chain Analysis
Battery pack refurbishment and electric motor remanufacturing flows are emerging from São Bernardo do Campo technical centers as hybrid penetration accelerates. Lithium-ion cell supply concentrates in China, South Korea, and Japan, with Brazilian assembly operations drawing from imported cylindrical and prismatic formats. Rare earth magnet dependencies for traction motors create single-source vulnerability through concentrated Asian processor networks. Distribution runs through captive OEM logistics networks serving Mercosur trade zone assembly plants, with aftermarket channels fragmenting across regional parts distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Proconve L7 and L8 emission mandates construct a cost-of-compliance moat that rewards incumbent OEMs with localized hybrid powertrain qualification while excluding import-dependent challengers from fleet tender participation.
For Market Incumbents: Deepen backward integration into domestic battery pack assembly at Betim and São Bernardo do Campo complexes to defend against Korean challengers scaling regional distribution. Secure ANVISA homologation capacity ahead of compressed certification timelines to maintain model launch velocity against regulatory bottlenecks. For New Entrants and Emerging Players: Begin with Colombian urban subscription services where hybrid availability gaps and biofuel infrastructure create first-mover positioning outside established Mercosur production bases. Target Bogotá metropolitan fleet tenders with flexible-fuel hybrid offerings before incumbent OEMs redirect capacity northward. For Investors and Strategic Acquirers: Distressed-cycle entries favor Argentine tier-one suppliers with electric motor qualification progress in Córdoba's manufacturing cluster as local content enforcement redirects sourcing from Asian imports. Long-term viability hinges on Proconve certification pipeline depth; monitor CONAMA accelerated phase-in announcements for demand inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Powertrain Localization | Stellantis Betim and Toyota São Bernardo do Campo complexes anchor Mercosur-compliant production ahead of Proconve deadlines. |
| Battery Supply Agreement | Domestic pack assembly partnerships with Asian cell suppliers reduce currency exposure for Brazilian OEMs. |
| Flexible-Fuel Platform Standardization | Ethanol-capable architectures leverage Brazil's established biofuel distribution infrastructure against charging network gaps. |
| Software-Defined Vehicle Investment | Fleet telematics integration supports corporate sustainability reporting requirements in São Paulo metropolitan tenders. |
| Charging Infrastructure Partnership | Fast-charging corridor development between São Paulo and Buenos Aires addresses interurban penetration constraints. |
Research Methodology
Independent corroboration across OEM platform engineering directors, Tier 1 supplier procurement leads, and ANVISA regulatory affairs specialists underwrites the qualitative findings. Secondary validation draws from CONAMA emission standard filings, Mercosur trade zone customs records, and vehicle production databases. Bottom-up segment sizing triangulates against top-down macroeconomic absorption models.
Rate-of-change decomposition separates volume growth into fleet replacement cycle acceleration, powertrain mix shift, and regional production capacity expansion across the analysis window. Segmentation modeling spans vehicle class, propulsion architecture, and OEM tier. CAGRs derive from fitted trend extrapolation adjusted for regulatory phase-in schedules and biofuel price elasticity assumptions.
Underlying measurement precision varies by segment; hybrid powertrain forecasts carry tighter precision than pure-electric projections given infrastructure uncertainty. Forecasts reflect documented assumptions on Proconve enforcement timing and Mercosur-EU trade negotiation outcomes. Practitioners should monitor CONAMA accelerated certification announcements and Argentine local content rule modifications for early demand signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Passenger Vehicles
Luxury Car Market
Passenger Vehicles
Microcars Market
Passenger Vehicles
Minivans Market
Passenger Vehicles
Compact Cars Market
Passenger Vehicles
Passenger Vehicle Market
Passenger Vehicles
Asia Pacific Luxury Cars Market
Passenger Vehicles
Small Suvs Market
Passenger Vehicles
Train Market
Passenger Vehicles
North America Automotive Market
Passenger Vehicles
Global SUV Market
Passenger Vehicles
Inland Water Passenger Transport Market
Passenger Vehicles
China Luxury Car Market
Passenger Vehicles
Latin America Passenger Car Market
Passenger Vehicles
India Luxury Car Market
Passenger Vehicles
Family Car Market
Passenger Vehicles
India Automotive Market