
 US Healthcare Assets Management Market | 2026-2036
US Healthcare Assets Management Market Size, Share, and Industry Trends Forecast 2026-2036
US Healthcare Assets Management Market Analysis
Joint Commission accreditation standards for medical equipment management is redrawing competitive boundaries for platform vendors. GE Healthcare leverages its installed base of imaging modalities to bundle asset tracking with service contracts. Zebra Technologies anchors its position through ruggedized mobile computers that dominate hospital barcode scanning workflows. CenTrak differentiates via proprietary infrared and RFID fusion technology that delivers room-level location accuracy in complex clinical environments.
Healthcare assets management encompasses the systematic tracking, maintenance scheduling, and utilization optimization of medical equipment, IT hardware, and facility infrastructure through automated data capture and analytics platforms. Core systems integrate RFID tags, barcode identifiers, and IoT sensors to maintain real-time visibility of asset location, condition, and compliance status across distributed care delivery networks. RFID Solutions command the premium tier within technology segments due to their ability to track high-value mobile equipment without line-of-sight constraints, while Cloud-based Platforms represent the fastest-expanding deployment model as health systems seek to unify multi-site operations. Among end users, Hospitals absorb the dominant share of capital allocation for these systems, though Nursing Facilities present concentrated growth opportunity as post-acute operators modernize legacy inventory practices under value-based reimbursement pressure.
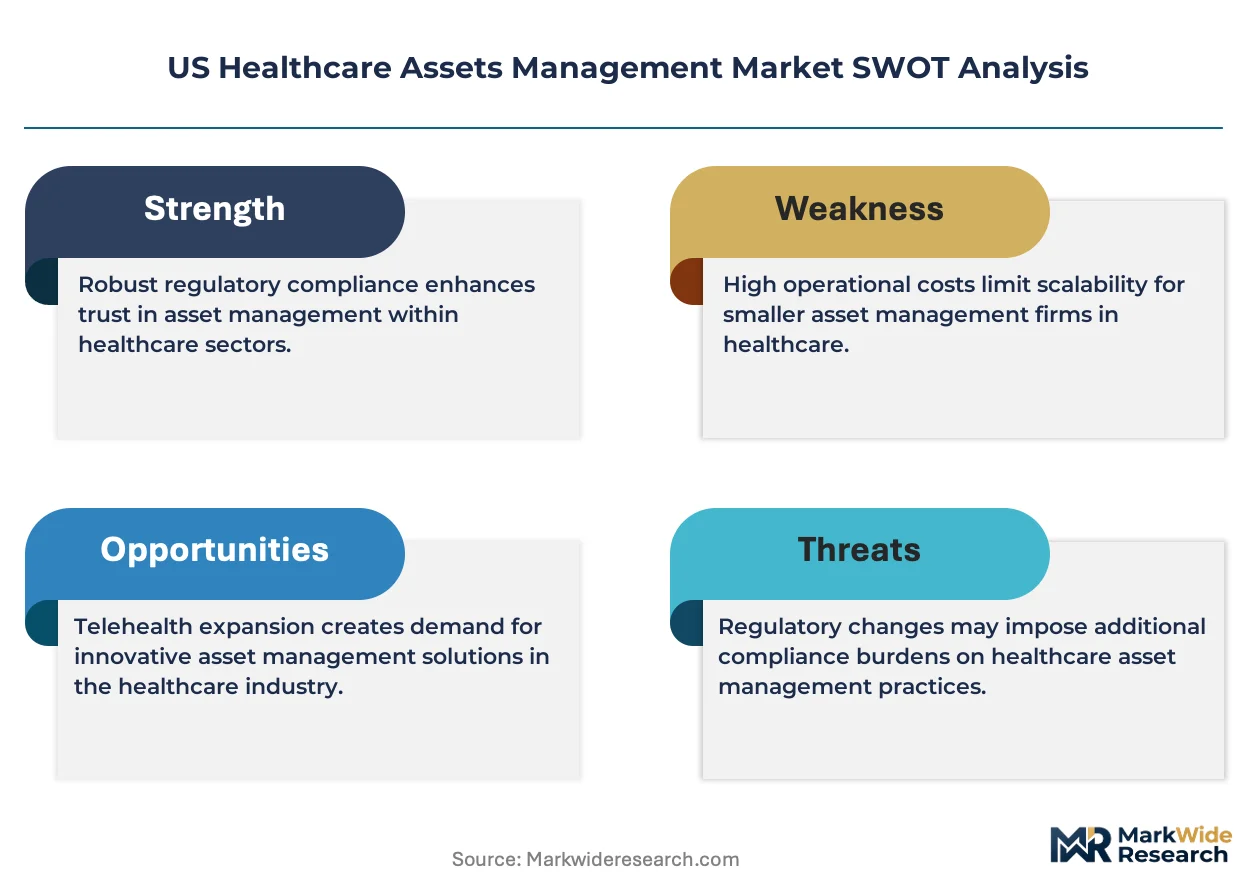
FDA unique device identification rules and Joint Commission equipment management standards collectively mandate traceable maintenance records and location-aware recall capabilities, directly elevating demand for integrated software platforms. OSHA workplace safety requirements and state-level healthcare facility licensure rules in California, Texas, and New York further compel systematic preventive maintenance documentation. Stakeholders must weigh the capital efficiency of cloud-native architectures against the cybersecurity compliance burden of HIPAA-covered data flows as they evaluate platform investments.
Market Dynamics
Hospital system consolidation across Florida, Texas, and California is compressing procurement timelines and forcing enterprise-wide standardization of asset tracking platforms. Health networks now mandate unified visibility across dozens of acquired facilities, eliminating the patchwork of departmental solutions that previously dominated.
Growth Catalysts
- FDA Unique Device Identification:The UDI Final Rule mandates traceable maintenance records and location-aware recall capabilities for all implantable devices, compelling hospitals to deploy integrated RFID and barcode systems.
- Joint Commission Equipment Management Standards:Accreditation requirements for preventive maintenance documentation drive systematic adoption of automated scheduling platforms across acute care facilities.
- Southeast Health System Consolidation:Florida and Texas hospital networks are rolling out multi-site asset deployments to unify inventory visibility across newly integrated delivery systems.
Market Restraints
- HIPAA Cloud Compliance Burden:Covered entities face substantial legal and technical costs when migrating protected health information to cloud-native architectures, slowing platform transitions.
- RFID Tag Cost Volatility:Specialized passive tags for metal-rich clinical environments carry premium pricing that scales poorly across thousands of lower-value equipment items.
- Legacy System Integration Friction:Proprietary data formats in existing CMMS and ERP installations create middleware dependencies that extend deployment timelines.
Strategic Opportunities
- Post-Acute Modernization:Nursing facilities under value-based reimbursement pressure present concentrated demand as operators replace paper-based inventory with automated tracking.
- IoT Sensor Convergence:Integration of condition-monitoring sensors with location platforms enables predictive maintenance workflows for high-utilization mobile equipment.
- OSHA Workplace Safety Alignment:Systematic preventive maintenance documentation satisfies both equipment management and employee safety audit requirements, expanding platform justification.
Industry Challenges
- Clinical Engineering Talent Scarcity:Shortages of technicians trained in both biomedical equipment and networked sensor systems delay implementation and optimization.
- Multi-Modal Data Standardization:Infrared, ultra-wideband, and RFID location feeds require normalization layers that complicate real-time dashboard accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Healthcare Assets Management Market |
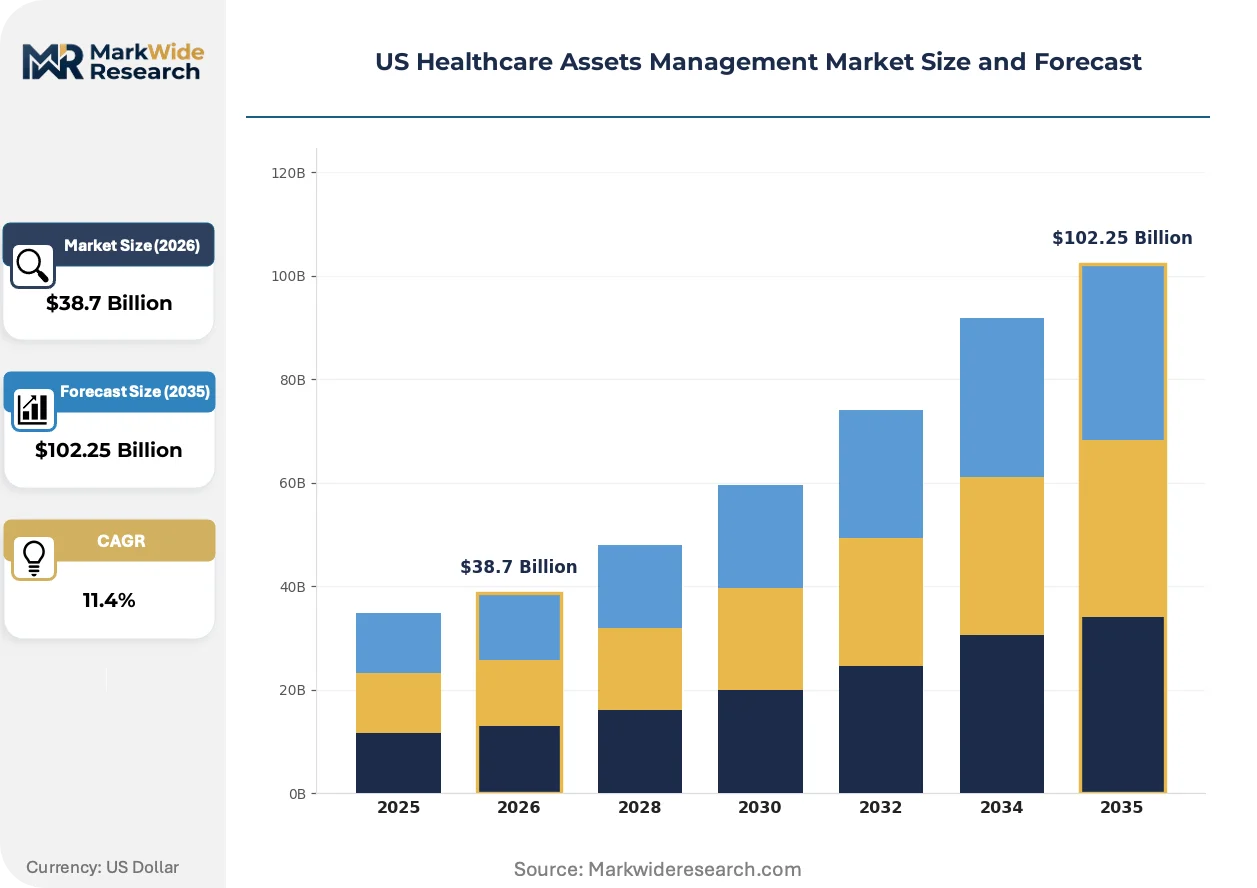
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $102.25 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Asset Tracking Systems, Inventory Management Software, Equipment Management Solutions, Maintenance Management Tools End User: Hospitals, Clinics, Laboratories, Nursing Facilities Technology: RFID Solutions, Barcode Scanning, Cloud-based Platforms, IoT-enabled Systems Application: Resource Optimization, Compliance Management, Cost Control, Workflow Automation |
| Companies Covered | GE Healthcare, Zebra Technologies, CenTrak, AiRISTA Flow, STANLEY Healthcare, Versus Technology, Novanta, IBM, Siemens Healthineers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Healthcare Assets Management Market Emerging Trajectories
Real-time location technology is converging with predictive analytics to transform asset management from passive inventory tracking into dynamic capacity optimization. Vendors are racing to embed machine learning directly at the edge of clinical networks.
Bluetooth Low Energy beacon hardware is miniaturizing to sub-credit-card dimensions while maintaining sub-meter accuracy in dense RF environments. Emergency departments and operating rooms are deploying these tags on portable ultrasound units and infusion pumps within eighteen-month refresh cycles. The form factor reduction is miniaturizing deployment barriers for previously untrackable small equipment categories.
OSHA workplace safety requirements now intersect with Joint Commission equipment standards, creating overlapping audit trails that favor unified platform architectures. California, Texas, and New York state licensure rules compel documented preventive maintenance that automated systems streamline. Ambulatory surgery centers face the steepest compliance cost increases and are prioritizing cloud-based solutions with built-in regulatory reporting modules.
Health system procurement teams are consolidating vendor relationships and demanding subscription-based pricing with guaranteed uptime SLAs. Traditional capital expenditure models for on-premise software are yielding to multi-year operational contracts that bundle hardware, software, and support. The Southeast region shows the most aggressive shift, with Florida-based IDNs negotiating enterprise licenses spanning fifty-plus facilities.
US Healthcare Assets Management Market Segmentation
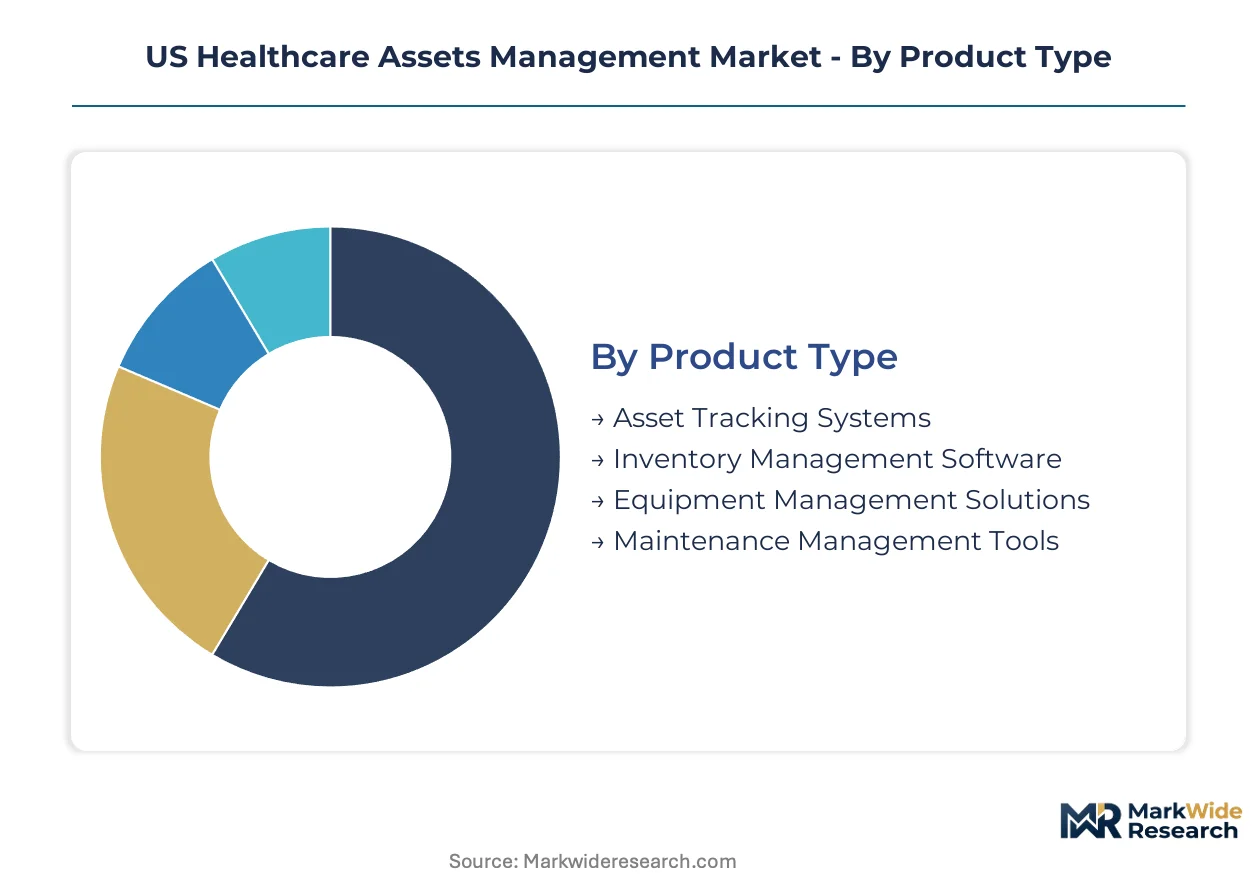
Segmentation in healthcare assets management reflects how capital flows diverge across technology maturity curves and regulatory pressure points. Procurement teams structure vendor evaluations around deployment complexity, compliance burden, and integration depth with existing clinical workflows.
Product Type:
Margin pools concentrate in integrated platforms that bundle hardware, software, and ongoing support under multi-year contracts, while standalone tools face commoditization pressure from cloud-native alternatives.
- Asset Tracking Systems:These platforms deploy RFID tags, infrared sensors, and ultra-wideband anchors to maintain real-time visibility of mobile medical equipment across distributed care networks. Demand concentrates in Southeast hospital systems—particularly Florida and Texas IDNs—where multi-site standardization mandates following consolidation are forcing enterprise-wide rollouts. The Joint Commission's equipment management standards elevate these systems from operational convenience to accreditation necessity.
- Inventory Management Software:Cloud-native architectures dominate new deployments, offering centralized dashboards that unify procurement, utilization analytics, and par-level optimization across acquired facilities. California and New York state licensure rules compel documented inventory controls that automated platforms streamline, while HIPAA compliance burdens slow migration timelines for covered entities.
- Equipment Management Solutions:Preventive maintenance scheduling, calibration tracking, and recall management modules satisfy overlapping FDA UDI and OSHA audit requirements. These solutions anchor vendor relationships through high switching costs embedded in CMMS integration.
- Maintenance Management Tools:Specialized modules for clinical engineering workflows address technician scarcity through automated work order routing and skill-matched dispatch algorithms. Smaller critical access hospitals in rural Texas and Florida represent concentrated demand for simplified, lower-touch implementations.
The dominant share belongs to Asset Tracking Systems, while Inventory Management Software is gaining share fastest as cloud migration accelerates.
End User:
Customer concentration patterns map directly to reimbursement model complexity and regulatory inspection frequency, with acute care facilities absorbing disproportionate platform investment.
- Hospitals:Acute care facilities command the largest capital allocations, driven by FDA UDI mandates for implantable device traceability and Joint Commission accreditation cycles. Health system consolidation across Florida, Texas, and California is compressing procurement into enterprise-wide standardization mandates that eliminate departmental point solutions.
- Nursing Facilities:Post-acute operators under value-based reimbursement pressure are modernizing legacy paper-based inventory practices, creating concentrated growth opportunity. CMS quality metrics and state survey readiness requirements in Texas and Florida accelerate automation adoption.
- Clinics:Ambulatory settings prioritize lightweight, cloud-based deployments with rapid implementation timelines. Cost pressures from Medicare reimbursement compression favor subscription pricing over capital expenditure models.
- Laboratories:Specimen tracking integration, reagent inventory controls, and equipment calibration documentation drive specialized demand. CLIA compliance requirements and CAP accreditation standards elevate platform sophistication requirements.
Hospitals retain the dominant position in absolute spending, though Nursing Facilities are expanding most quickly as post-acute modernization accelerates.
Technology:
Technology selection hinges on accuracy requirements, metal-rich environmental constraints, and the trade-off between tag cost and infrastructure investment.
- RFID Solutions:Passive and active radio-frequency identification systems deliver non-line-of-sight tracking for high-value mobile equipment in dense clinical environments. Premium pricing for specialized tags suited to metal-rich settings limits scalability across lower-value asset categories, constraining deployment breadth.
- Cloud-based Platforms:Multi-tenant architectures enable health systems to unify visibility across dozens of acquired facilities without on-premise infrastructure proliferation. HIPAA-covered data flows impose substantial legal and technical compliance costs that slow migration for risk-averse organizations.
- Barcode Scanning:Ruggedized mobile computers dominate high-volume, low-accuracy workflows where room-level precision is unnecessary. Zebra Technologies' installed base anchors this segment through hospital workflow integration.
- IoT-enabled Systems:Condition-monitoring sensor convergence with location platforms enables predictive maintenance for high-utilization mobile equipment. Edge computing architectures address latency requirements for real-time alerts in critical care settings.
RFID Solutions command the premium tier in pricing and performance, yet Cloud-based Platforms are climbing the fastest as enterprise standardization mandates proliferate.
Application:
Functional use cases align with C-suite priority shifts between operational efficiency, regulatory risk mitigation, and financial performance optimization.
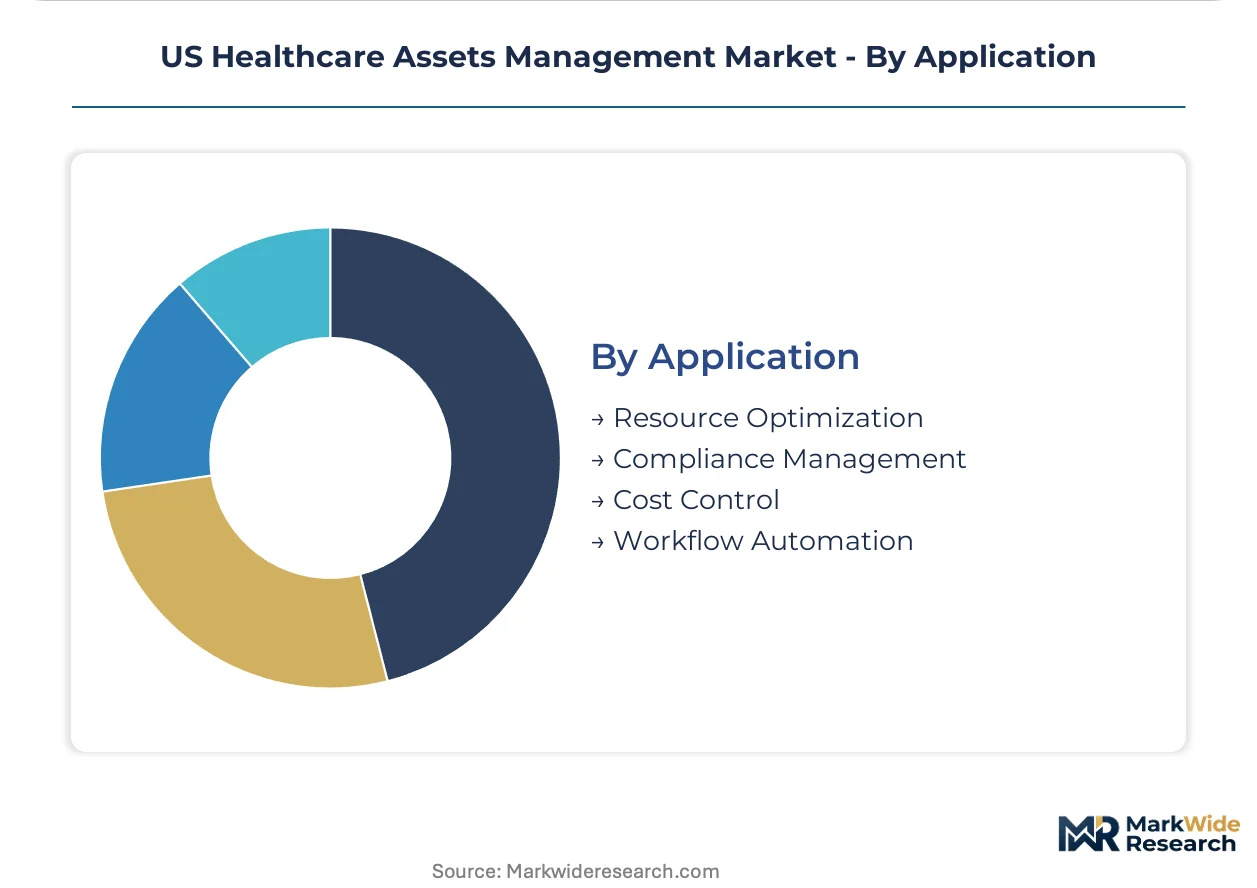
- Compliance Management:Automated documentation trails satisfy FDA UDI recall capabilities, Joint Commission preventive maintenance records, and OSHA workplace safety requirements through unified audit architectures. California, Texas, and New York state licensure rules compound documentation burdens.
- Resource Optimization:Real-time visibility reduces equipment hoarding, improves patient throughput, and lowers capital expenditure on redundant device purchases. Emergency departments and operating rooms in high-volume Florida systems deploy these capabilities most aggressively.
- Cost Control:Utilization analytics, maintenance cost tracking, and lease-versus-buy optimization modules target CFO priorities under margin compression. Value-based reimbursement transitions elevate financial accountability for asset lifecycle costs.
- Workflow Automation:Automated par-level replenishment, work order dispatch, and recall execution reduce clinical engineering administrative burden. Integration with ERP and supply chain systems determines deployment complexity.
Compliance Management captures the largest addressable spend given regulatory mandate density, while Resource Optimization is advancing most rapidly as throughput pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 95 corridor and the Texas Medical Center's 1,345-acre campus anchor the Southeast's concentration of health system consolidation activity, where enterprise-wide asset deployments are compressing procurement timelines across multi-facility networks.
Southeast (Florida/Georgia)
Florida-based IDNs are rolling out fifty-plus facility enterprise licenses following aggressive consolidation in the Tampa and Miami metro areas. Joint Commission accreditation cycles and state licensure rules compel documented preventive maintenance across newly integrated delivery systems. The Texas Medical Center in Houston drives demand for room-level location accuracy as Methodist and Memorial Hermann systems standardize platforms post-merger.
Southwest (Texas/Arizona)
Texas health networks absorb the dominant share of RFID infrastructure investment as Dallas-Fort Worth and San Antonio systems unify visibility across acquired rural facilities. OSHA workplace safety requirements intersect with state hospital licensure rules to mandate systematic equipment documentation. Austin's Dell Medical School and surrounding specialty surgical centers prioritize cloud-native deployments with rapid implementation timelines.
West Coast (California)
California's state healthcare facility licensure rules impose documentation burdens that automated platforms streamline across Kaiser Permanente's integrated network. HIPAA compliance costs slow cloud migration for risk-averse organizations in the Los Angeles and San Francisco Bay Area clusters. Sacramento's Sutter Health and Palo Alto's Stanford Medicine anchor demand for predictive maintenance integration with existing CMMS installations.
Northeast (New York Metro/New England)
New York state licensure rules and New York-Presbyterian's multi-site expansion drive enterprise standardization mandates across the Hudson Valley and Long Island. Greater Boston's Mass General Brigham and Beth Israel Lahey Health systems compete on operational efficiency metrics that real-time location visibility enables. Hartford's insurance-dominated healthcare economy favors subscription pricing models over capital expenditure procurement.
Midwest (Illinois/Michigan/Ohio)
Chicago's Advocate Aurora Health and Cleveland Clinic anchor demand for utilization analytics that reduce redundant equipment purchases across sprawling Midwest networks. Michigan's Henry Ford Health system consolidation creates procurement urgency for unified inventory visibility. Ohio's Cleveland Clinic and Cincinnati Children's Hospital Medical Center prioritize integration with existing ERP and supply chain systems.
US Healthcare Assets Management Market Vendor Landscape
Listed leaders compete with private specialists across technology integration depth, with publicly traded equipment manufacturers leveraging installed base relationships against venture-backed location technology pure-plays. The market structure tilts toward consolidation as health system procurement teams demand multi-year operational contracts bundling hardware, software, and support. Three archetypes dominate: imaging modality incumbents extending into tracking services, ruggedized hardware specialists anchoring barcode workflows, and proprietary location technology developers delivering sub-meter accuracy. Competitive moves center on enterprise license negotiations spanning fifty-plus facilities and edge computing architectures that embed machine learning directly at clinical network endpoints.
Within the imaging incumbent tier, GE Healthcare and Siemens Healthineers occupy positions that bundle asset tracking with service contract renewals on modality fleets. Among location technology specialists, CenTrak exemplifies the proprietary sensor fusion approach through infrared and RFID convergence, while Zebra Technologies anchors the ruggedized mobile computing segment that dominates high-volume hospital barcode scanning workflows. IBM represents the enterprise IT services archetype seeking to bridge legacy CMMS integration friction through middleware platforms.
| Leading Market Players |
|---|
| GE Healthcare |
| Zebra Technologies |
| CenTrak |
| AiRISTA Flow |
| STANLEY Healthcare |
| Versus Technology |
| Novanta |
| IBM |
| Siemens Healthineers |
| Others |
Supply Flow & Price Mechanics
FDA Unique Device Identification compliance gates both supplier qualification and price tiering simultaneously, as vendors must demonstrate validated traceability architectures before health system procurement committees award enterprise contracts. Joint Commission accreditation requirements further stratify pricing by mandating documented preventive maintenance capabilities that only integrated platform providers can satisfy.
Pricing Analysis
Volume-discount tiering structures dominate enterprise procurement negotiations, with Florida and Texas IDNs extracting steep concessions for fifty-plus facility deployments. Pricing stratifies across premium, standard, and economy tiers based on location accuracy specifications and CMMS integration depth. Cost compression in the economy tier is intensifying because cloud-native alternatives commodify basic inventory visibility. Ambulatory surgery centers exhibit highest price sensitivity due to Medicare reimbursement compression, while integrated delivery networks prioritize guaranteed uptime SLAs over unit cost.
Supply Chain Analysis
Inbound logistics costs from East Asian semiconductor fabrication centers have stabilized following pandemic-era container shortages, though specialized RFID tag substrates remain vulnerable to Pacific trade lane congestion. Hardware assembly concentrates in Mexico, Taiwan, and Malaysia, with firmware development anchored in US and Israeli engineering clusters. Supply chains draw from rare earth magnet suppliers in China and specialized antenna substrate producers in Japan, creating single-source vulnerability for room-precision location hardware. Distribution runs through group purchasing organizations and direct health system contracts, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has shifted decisively toward consolidated health systems, as Florida and Texas IDNs compress vendor margins through enterprise-wide standardization mandates that eliminate departmental point solutions.
For Market Incumbents: Consolidate service contract relationships with imaging modality fleets to lock out standalone location technology vendors. Deepen backward integration into proprietary sensor fusion hardware to defend margin position against commoditizing Bluetooth Low Energy alternatives. Threat substitution from cloud-native inventory platforms demands accelerated edge computing investment to maintain performance differentiation.
For New Entrants and Emerging Players: Differentiate on predictive maintenance analytics convergence with existing CMMS installations rather than competing head-to-head on location accuracy. Target nursing facility post-acute modernization as the most penetrable segment, where paper-based inventory practices create low-friction displacement opportunity. Lead with rapid cloud deployment timelines and subscription pricing to bypass capital committee approval bottlenecks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native software layers as multi-tenant architectures achieve scale efficiencies. Long-term viability favors platform vendors with sticky CMMS integration and recurring revenue concentration over hardware-dependent tag suppliers. Acquisition target archetype: clinical engineering workflow software specialists with HIPAA-compliant cloud infrastructure. Signal to watch: health system CIO consolidation of vendor relationships into single-platform mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Enterprise License Negotiation | Fifty-plus facility deployments in Florida IDNs extract volume pricing and unified architecture commitments. |
| Edge Computing Architecture | Machine learning embedding at clinical network endpoints reduces latency for real-time location alerts. |
| CMMS Integration Partnership | Preventive maintenance module connectivity anchors vendor relationships through high switching costs. |
| Post-Acute Market Expansion | Nursing facility automation addresses CMS quality metrics and state survey readiness requirements. |
| RFID-IoT Sensor Convergence | Condition monitoring integration enables predictive maintenance for high-utilization mobile equipment. |
Methodological Framework
A standing panel of hospital CIOs, biomedical engineering directors, GPO contracts managers, and health system procurement executives provided ongoing calibration across the study period. Primary interview data combined with secondary validation from FDA UDI guidance documents, CMS Medicare cost reports, hospital procurement databases, and Joint Commission accreditation standards. Bottom-up facility-level deployment estimates triangulated against top-down health system capital expenditure disclosures.
Consistency checks validated volume and value outputs against external benchmarks including health system IT spending surveys and medical device tracking adoption metrics. The analytical framework modeled segmentation dimensions across technology type, deployment architecture, end-user facility category, and application function throughout the forecast period. CAGRs derived from facility expansion pipelines, regulatory mandate implementation timelines, and technology refresh cycle analysis. Forecast inputs incorporated health system consolidation velocity and cloud migration adoption curves specific to HIPAA-covered entities.
Forecasts assume regulatory continuity in FDA UDI enforcement and Joint Commission equipment management standards; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Asset Management
China Mutual Funds Market
Asset Management
Asset and Wealth Management Market
Asset Management
Pension Fund Management Software Market
Asset Management
Canada Asset Management Market
Asset Management
Healthcare Asset Management Market
Asset Management
UK Asset Management Market
Asset Management
Mutual Fund Assets Market
Asset Management
Hardware Asset Management Market
Asset Management
Assets Under Management Market
Asset Management
Canada Pension Fund Market
Asset Management
Japan Asset Management Market
Asset Management
Fund Management Fee Market
Asset Management
Global Investment Management Software Market
Asset Management
Europe Asset Management Market
Asset Management
Global AI in Asset Management Market
Asset Management
India AMC Industry Market