
 Hams Market | 2026-2036
Hams Market Size, Share, and Industry Trends Forecast 2026-2036
Hams Market Analysis
USDA Process Verified certification is reorganizing competitive access in the hams sector, forcing smaller processors to upgrade traceability systems or exit branded retail channels. Smithfield Foods leverages vertical integration from farm to case-ready packaging, sustaining cost advantages across fresh and cured product lines. Hormel Foods Corporation specializes in premium deli and foodservice formulations, occupying strong positions in sliced and portion-controlled offerings. JBS Foods competes through global protein platform scale, navigating multiple regulatory environments with centralized quality protocols.
Hams comprise pork hind leg cuts processed through curing, smoking, or fresh chilling to achieve specific moisture content, salt levels, and flavor profiles for commercial and consumer consumption. The product serves retail deli counters, institutional foodservice, and prepared meal manufacturing as a versatile center-plate protein. Cured ham leads volume throughput due to extended shelf stability and established consumer preference, while vacuum sealed packaging commands margin premiums through convenience positioning and waste reduction. Premium grade segments concentrate value capture in specialty retail and direct-to-consumer channels where provenance labeling commands price separation.
USDA grading standards, FDA Hazard Analysis Critical Control Point rules, and EU REACH chemical safety frameworks govern curing agent approvals, residue limits, and import eligibility across major trade corridors. These bodies shape formulation choices, label claim permissibility, and cross-border market access for processed pork products. Stakeholders must monitor evolving nitrite reduction mandates and alternative curing technology validations to preserve formulation flexibility and geographic market presence.
Market Dynamics
USDA Process Verified certification requirements are forcing processor consolidation as smaller operators face capital barriers to traceability system upgrades, reshaping competitive access across retail and foodservice channels.
Growth Catalysts
- Quick-service menu expansion:Foodservice operators are adding ham-centric breakfast and lunch items, driving portion-controlled product demand across drive-thru and fast-casual formats.
- HACCP compliance infrastructure:Hazard Analysis Critical Control Point protocols are standardizing processing quality, enabling branded retail penetration for mid-tier processors meeting certification thresholds.
- Vacuum-sealed packaging adoption:Extended shelf-life formats are capturing convenience-oriented retail segments, reducing household food waste and supporting premium positioning.
Market Restraints
- Feed grain input volatility:Corn and soybean price swings compress processor margins, particularly for fresh ham categories with thinner value-add capture.
- Midwest processing concentration:Iowa and North Carolina facility clustering creates regional supply vulnerability to weather disruptions and labor availability shocks.
- Plant-based protein substitution:Pea and mycoprotein deli alternatives are capturing flexitarian trial in coastal urban markets, pressuring volume growth in traditional cured segments.
Strategic Opportunities
- Direct-to-consumer channel development:Specialty ham producers are building subscription and e-commerce fulfillment capabilities, bypassing traditional retail slotting fee structures.
- Clean-label curing convergence:Celery powder and natural nitrite alternatives are opening premium positioning opportunities as FDA labeling scrutiny intensifies on traditional curing agents.
- Prepared meal manufacturing partnerships:Ham processors are co-developing center-plate components with frozen and refrigerated meal assemblers, capturing value beyond commodity wholesale.
Industry Challenges
- USDA certification timeline compression:Process Verified program audit backlogs are delaying new product launches, requiring processors to build buffer inventory during approval windows.
- Legacy ERP integration friction:Traceability system mandates are clashing with decades-old plant-floor data architectures, forcing expensive middleware development or full system replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hams Market |
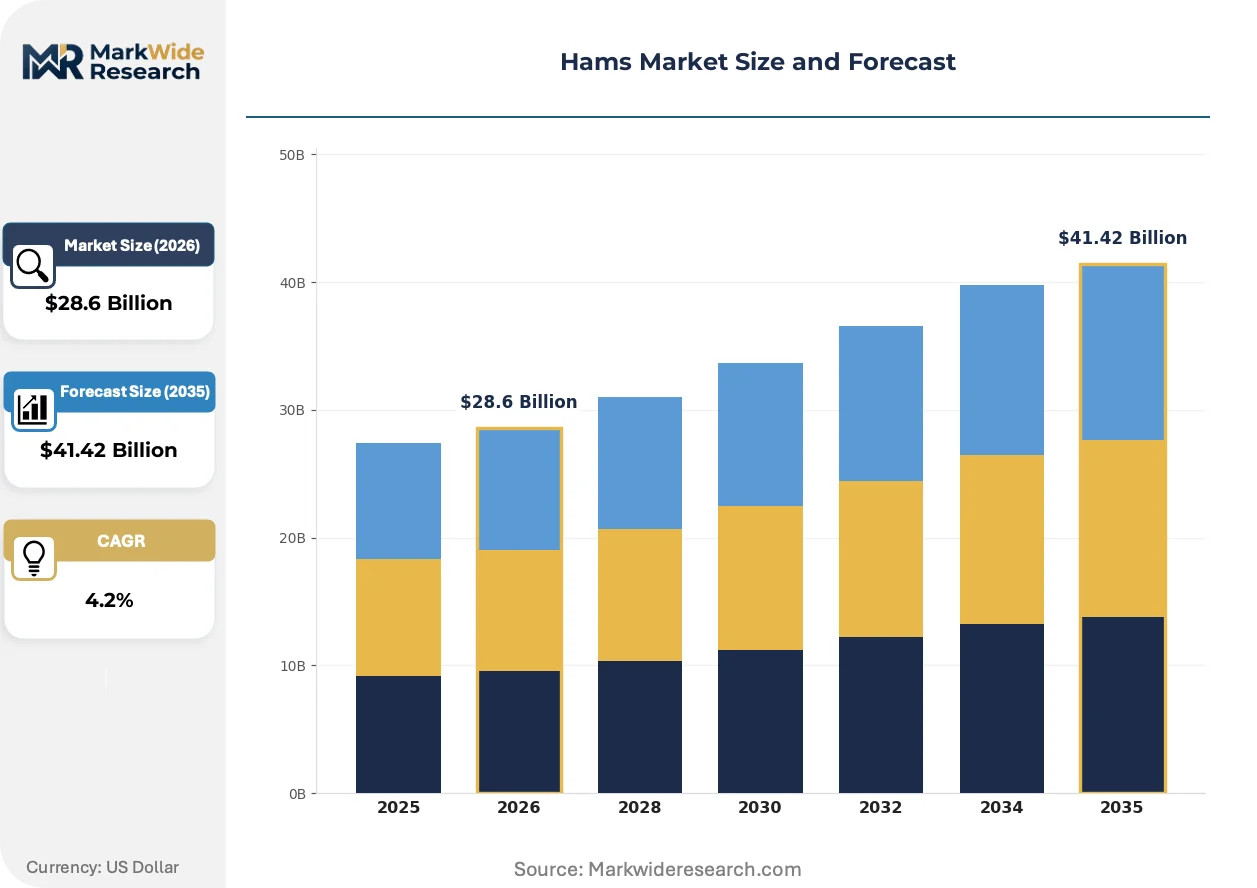
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $41.42 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Ham, Cured Ham, Smoked Ham, Honey Ham End User: Restaurants, Retailers, Caterers, Households Packaging Type: Vacuum Sealed, Pre-Packaged, Bulk, Canned Grade: Premium, USDA Choice, USDA Select, Others |
| Companies Covered | Clemens Food Group, Cargill Protein, Smithfield Foods, WH Group Limited, JBS Foods, Hormel Foods Corporation, Indiana Packers Corporation, Seaboard, Tyson Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hams Market Emerging Trajectories
Processing technology and curing chemistry are converging to reshape product formulation, packaging formats, and channel economics across fresh and cured ham categories.
High-pressure processing technology is extending refrigerated shelf life without thermal degradation, preserving texture and flavor profiles that traditional pasteurization compromises. Deli counter operators and prepared meal manufacturers are adopting HPP-treated hams to reduce shrink and expand distribution radius. This preservation method is displacing conventional thermal processing in premium retail segments where sensory quality commands price separation.
EU REACH chemical safety frameworks are tightening residual nitrosamine limits, forcing reformulation across export-oriented processors. The European Food Safety Authority's evolving stance on curing agent safety is accelerating validation work for plant-derived nitrite alternatives. North American facilities targeting EU market access are investing in dual-formulation capabilities to maintain geographic optionality.
Foodservice procurement consolidation is compressing supplier rosters as national restaurant chains centralize protein purchasing through contracted distribution networks. Independent regional distributors are losing share to broadline operators with national scale and dedicated protein logistics. This buyer concentration is most visible in the United States, where quick-service and casual dining chains now direct majority volume through single-source agreements with integrated processors.
Hams Market Segmentation
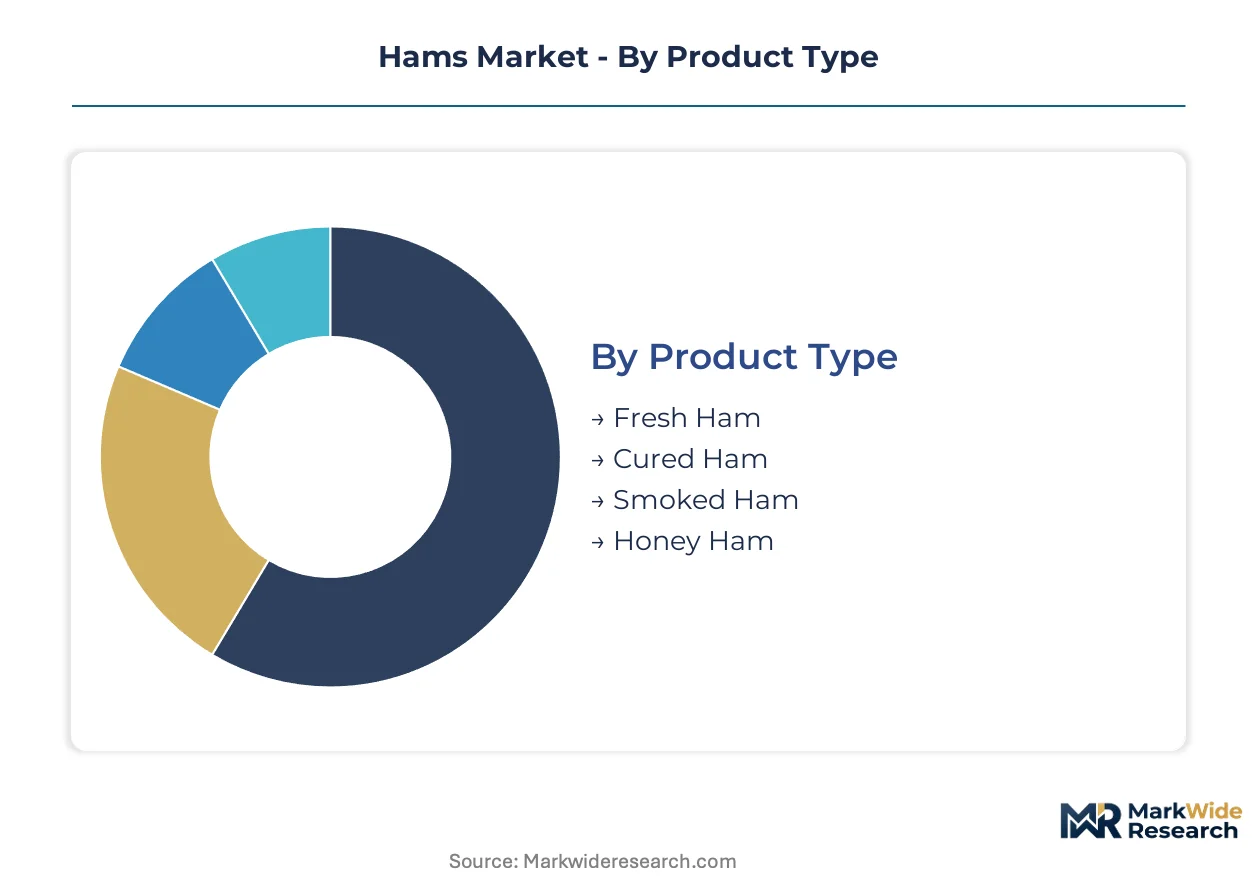
Segmentation in the hams sector reveals how curing methods, distribution channels, and quality grades create distinct profit pools with varying exposure to plant-based substitutes and regulatory scrutiny. Understanding these divides helps processors allocate capital between volume efficiency and premium positioning.
Product Type:
Plant-based deli alternatives exert the strongest substitution pressure on segments with the thinnest processing differentiation and lowest consumer loyalty, reshaping where processors must defend through sensory quality or provenance storytelling.
- Cured Ham:Pork hind legs undergo brine injection or dry salt curing with controlled nitrite application to achieve stable moisture content and extended shelf life. Retail deli counters and institutional foodservice concentrate demand here, though nitrite reduction mandates from FDA and EFSA are forcing costly reformulation investments.
- Fresh Ham:Uncured pork leg cuts sold refrigerated with minimal processing beyond trimming and chilling. Quick-service breakfast programs and prepared meal manufacturers drive volume, but feed grain cost volatility compresses margins for this commodity-exposed category.
- Smoked Ham:Cured cuts exposed to hardwood smoke for flavor development and surface preservation. Regional smokehouse traditions in the Carolinas and Virginia sustain specialty demand through direct-to-consumer channels.
- Honey Ham:Glazed cured product with honey or honey-based coatings targeting holiday and gift segments. Seasonal demand concentration requires processors to build inventory ahead of fourth-quarter retail resets.
Cured ham anchors the volume base while honey ham gains share at the steepest rate through premium gifting and direct-to-consumer expansion.
End User:
Procurement consolidation patterns split the customer base between price-takers facing broadline distributor leverage and value-creators building captive demand through menu differentiation or private label development.
- Restaurants:Quick-service chains and casual dining operators specify portion-controlled formats with consistent slice geometry and yield predictability. National procurement centralization is compressing supplier rosters to integrated processors with HACCP-certified facilities across multiple states.
- Retailers:Supermarket deli counters and meat case operators balance branded premium placement against private label value tiers. Clean-label curing convergence is reshaping assortment priorities as celery powder alternatives capture shelf space.
- Caterers:Event and institutional foodservice operators demand spiral-sliced and pre-portioned formats for buffet service efficiency. Volume seasonality around holidays creates capacity planning challenges for processors.
- Households:Direct-to-consumer and subscription channel growth is bypassing traditional retail slotting structures for specialty and heritage breed products.
Restaurants deliver the steadiest volume commitment while households expand most quickly through e-commerce subscription models.
Packaging Type:
Packaging technology investments separate processors capable of extended distribution radius and reduced shrink from those trapped in localized fresh delivery models with higher logistics costs.
- Vacuum Sealed:Modified atmosphere packaging removes oxygen to inhibit microbial growth and preserve color stability without freezing. Premium retail and prepared meal manufacturing concentrate demand here, with high-pressure processing integration extending refrigerated shelf life further.
- Pre-Packaged:Retail-ready formats with branded labeling for grab-and-go deli case placement. Slotting fee structures at major retailers favor processors with national distribution scale.
- Bulk:Foodservice-focused formats for deli counter slicing or kitchen further processing. Cost-per-pound efficiency appeals to institutional buyers with in-house preparation capabilities.
- Canned:Shelf-stable retort packaging for emergency preparedness and military ration applications. Long production runs and commodity pricing characterize this mature segment.
Bulk formats retain the largest volume footprint while vacuum sealed climbs the fastest on convenience positioning and waste reduction premiums.
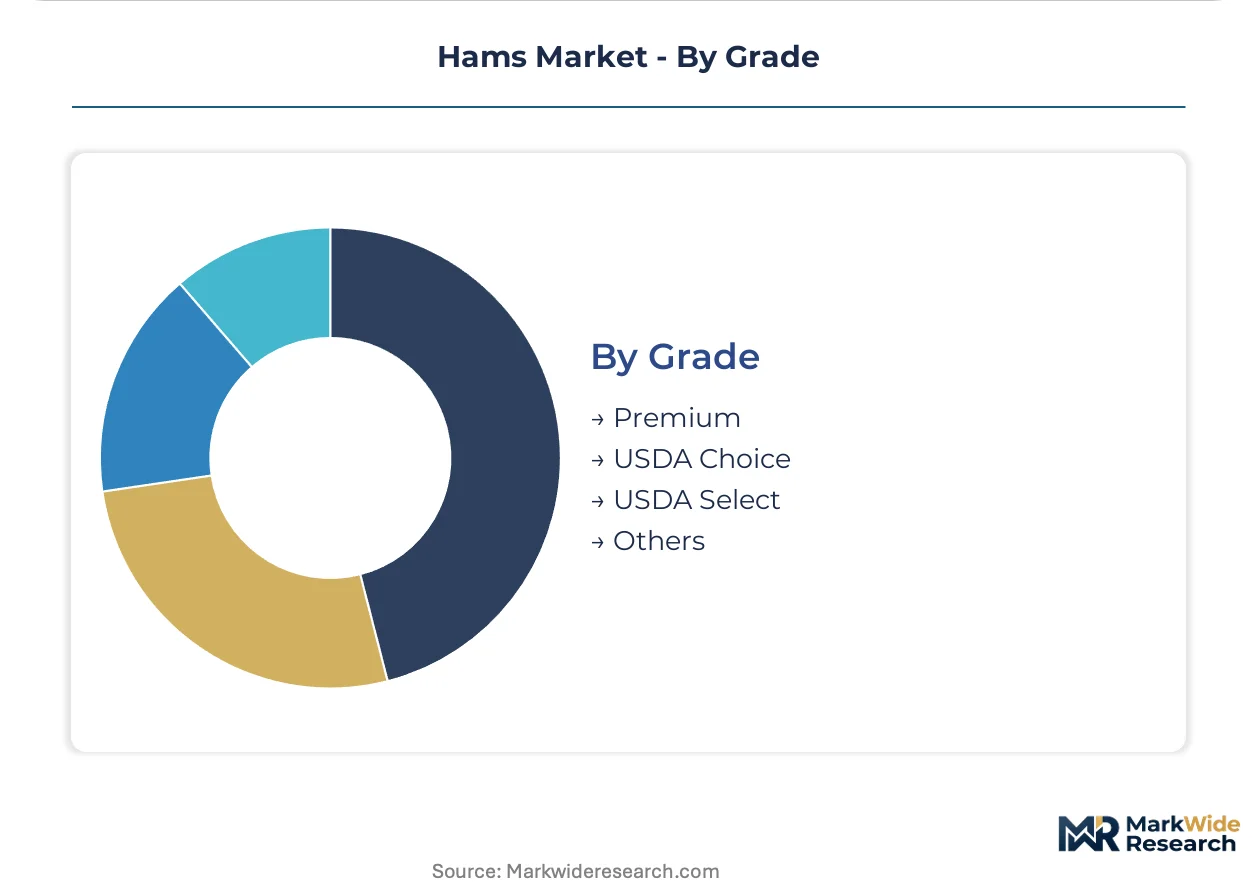
Grade:
USDA certification infrastructure creates tiered access to branded retail channels, with audit backlogs and traceability system requirements filtering which processors can compete above commodity levels.
- USDA Choice:Mid-tier grade with specified lean-to-fat ratios and processing consistency standards. Mainstream retail and foodservice procurement specifications concentrate demand here, making this the volume threshold for branded market participation.
- Premium:Heritage breed, pasture-raised, or extended aging designations commanding price separation in specialty retail and direct channels. Provenance labeling and breed-specific claims drive consumer willingness to pay.
- USDA Select:Leaner grade specification targeting health-positioned retail segments and institutional accounts with nutritional compliance requirements.
- Others:Ungraded or processor-specific quality designations for export markets with divergent grading protocols or commodity trading applications.
USDA Choice carries the volume foundation while premium grade expands most quickly through specialty retail penetration and subscription channel development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Virginia's cold chain infrastructure underwrites the United States' dominance in cured pork exports, connecting Midwest processing clusters to Atlantic shipping lanes.
United States
Quick-service breakfast menu expansion and deli counter penetration drive domestic consumption. USDA Process Verified certification mandates filter processor access to branded retail channels. Iowa and North Carolina host the densest facility clustering, where Smithfield Foods maintains integrated operations from farm to case-ready packaging.
Germany
Artisanal curing traditions and premium retail segments sustain heritage ham demand. EU REACH chemical safety frameworks govern residual nitrosamine limits and curing agent approvals. Bavaria's smokehouse cooperatives and North Rhine-Westphalia's industrial processors operate under divergent regulatory thresholds for export eligibility.
China
Urban middle-class protein diversification and prepared meal manufacturing expansion reshape consumption patterns. SAMR food safety protocols and GB standards for processed meat imports create compliance complexity. Yangtze River Delta cold chain logistics hubs concentrate distribution capacity for premium imported hams.
Brazil
Domestic foodservice growth and Mercosur trade access position processors for regional export expansion. ANVISA residue monitoring and plant registration requirements shape facility investment decisions. São Paulo state's protein processing corridor anchors JBS Foods' global platform scale.
Spain
Protected Designation of Origin frameworks for jamón ibérico command price premiums in specialty channels. EFSA evolving stances on curing agent safety accelerate validation of natural nitrite alternatives. Extremadura and Andalusia dehesa ecosystems sustain heritage breed production for export markets.
Hams Market Vendor Landscape
Listed leaders compete with private specialists across certification access and channel reach, producing a tiered structure where USDA Process Verified status separates branded retail participants from commodity traders. Consolidation pressures concentrate volume among integrated processors with captive supply chains, while regional smokehouses defend niche positions through provenance claims. Three archetypes dominate: vertically integrated protein platforms, premium deli specialists, and heritage breed direct-to-consumer operators. M&A activity targets HACCP-certified facilities in underrepresented states, and capacity expansion concentrates in Iowa and North Carolina to exploit feed grain proximity.
Within the integrated platform tier, Smithfield Foods exemplifies scale-driven consolidation, while Hormel Foods Corporation occupies a position in premium deli formulation. JBS Foods anchors the global protein platform archetype with multi-jurisdictional facility networks. These three represent distinct competitive vectors: captive supply integration, branded retail specialization, and geographic diversification under centralized quality protocols.
| Leading Market Players |
|---|
| Clemens Food Group |
| Cargill Protein |
| Smithfield Foods |
| WH Group Limited |
| JBS Foods |
| Hormel Foods Corporation |
| Indiana Packers Corporation |
| Seaboard |
| Tyson Foods |
| Others |
Supply Flow & Price Mechanics
Celery powder curing substitution is redrawing cost curves across processing tiers while compressing geographic sourcing advantages for traditional nitrite-dependent facilities.
Pricing Analysis
Certification level creates the primary spread between commodity and branded retail tiers. Three-tier pricing structure across premium USDA Process Verified, mid-tier HACCP-compliant, and economy ungraded levels stratifies the market. Pricing pressure stems from feed grain cost volatility squeezing fresh ham margins. Quick-service chains exhibit highest price sensitivity through centralized procurement leverage, while direct-to-consumer households accept premium positioning for heritage breed provenance.
Supply Chain Analysis
Strategic stockpile preferences dominate holiday inventory cycles, with processors building honey ham reserves ahead of fourth-quarter retail resets. Supply concentrates in Iowa and North Carolina processing corridors, drawing from Midwest corn-soybean feed inputs and Southeast livestock finishing operations. Single-source vulnerability to weather disruptions and labor availability shocks threatens regional clusters. Distribution runs through broadline foodservice operators and retail deli counter networks with national scale requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feed grain cost cyclicality positions the market for margin recovery as input costs normalize from recent volatility peaks.
For Market Incumbents: Fortify traceability infrastructure ahead of USDA Process Verified audit backlogs to preserve branded retail channel access. Deepen backward integration into heritage breed supply through contracted farmer partnerships, defending against plant-based substitution in coastal urban markets. For New Entrants and Emerging Players: Differentiate on clean-label curing convergence using celery powder formulations to capture premium retail shelf space. Target direct-to-consumer subscription channels for specialty smoked and honey ham segments, bypassing slotting fee barriers through e-commerce fulfillment capabilities. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors HACCP-certified mid-tier processors with underutilized capacity. Long-term viability hinges on geographic diversification beyond Iowa-North Carolina clustering. Watch EU REACH nitrosamine limit enforcement as signal for reformulation investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Adoption | Extends refrigerated shelf life for premium deli segments without thermal degradation. |
| Dual-Formulation Facility Investment | Enables EU market access through REACH-compliant nitrite alternative capabilities. |
| Direct-to-Consumer Channel Buildout | Bypasses retail slotting structures for heritage breed and specialty smokehouse products. |
| USDA Process Verified Certification | Unlocks branded retail placement and national foodservice contract eligibility. |
| Prepared Meal Manufacturing Partnership | Captures value beyond commodity wholesale through co-developed center-plate components. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of USDA facility inspection records, FDA HACCP compliance databases, and EU EFSA safety assessments. Interviews with plant operations managers, retail deli category buyers, foodservice procurement directors, and agricultural commodity traders inform demand and cost assumptions. Trade flow analysis from customs data, SEC processor filings, and industry association production surveys provide volume anchors. Bottom-up facility capacity modeling triangulates against top-down consumption estimates across retail, foodservice, and export channels.
Segmentation dimensions modeled include curing method, distribution channel, packaging technology, and USDA grade tier across the projection horizon. CAGRs derive from elasticity-adjusted demand projections and capacity expansion schedules. Forecast inputs incorporate feed grain price trajectory assumptions, regulatory approval timelines for alternative curing technologies, and quick-service menu development pipelines.
Material uncertainties — abrupt feed input cost spikes, EU nitrosamine limit enforcement acceleration, or plant-based substitution adoption rate shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions about processor certification compliance rates and cold chain infrastructure expansion. Revision becomes warranted when USDA Process Verified audit backlogs exceed twelve-month processing windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Global Lab-Based Meat Market
Meat Products
Poultry Processing Meat Market
Meat Products
Emulsified Meat Market
Meat Products
Mechanically Separated Meat Market
Meat Products
Meat Flavors Market
Meat Products
Global Poultry Meat Market
Meat Products
Europe Poultry Meat Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Beef Bouillon Market
Meat Products
Asia-Pacific Low Fat Sausage Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Meat Paste Market
Meat Products
Global Beef Market
Meat Products
Low-Fat Ham Market
Meat Products
Mexico Meat Products Market
Meat Products
Ham Slicers Market