
 Pork Meat Market | 2026-2036
Pork Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Pork Meat Market Outlook
Global G.A.P. certification for swine production is redrawing supplier eligibility across export corridors, forcing feed-to-fork traceability upgrades that smaller packers cannot finance. Smithfield Foods leverages its vertically integrated grain-to-pork operations across the US Midwest to sustain cost advantages in primal cuts. Tyson Foods Inc. competes through R&D intensity in value-added bacon and sausage formulations. WH Group anchors its position through channel control in Chinese retail and foodservice, where it operates the largest national distribution network for chilled pork.
Pork meat comprises the skeletal muscle, adipose tissue, and associated proteins derived from domesticated Sus scrofa domesticus, typically processed to moisture contents between 65-75 percent for fresh retail and lower thresholds for cured products such as ham and bacon. Its primary commercial purpose centers on providing high-biological-value protein for direct consumption and as an input for further-processed foods across retail and institutional channels. Fresh whole hog and primal cuts dominate volume flows through wholesale and retail channels, while vacuum-packed bacon and sausages capture expanding margin pools in convenience-oriented household segments. Foodservice distribution sustains premium pricing for specification-grade product, whereas online channels represent the fastest-growing outlet for branded processed pork in urban markets.
USDA grading standards and FSIS inspection protocols govern slaughter and processing compliance for US-exported product, while EFSA residue monitoring and EU F-Gas Regulation cold-chain requirements shape European import acceptance criteria. China's SAMR enforcement of GB 2707 fresh meat hygiene standards and growing traceability mandates restrict market access for uncertified foreign suppliers. Stakeholders must monitor divergence between national antibiotic restriction regimes and cold-chain infrastructure gaps when allocating capital across sourcing regions and processing formats.
Market Dynamics
Chilled pork distribution is consolidating around cold-chain infrastructure investments, as exporters face escalating traceability mandates that favor vertically integrated packers with captive logistics networks over fragmented regional suppliers.
Growth Catalysts
- EU F-Gas Regulation compliance:European cold-chain equipment upgrades are enabling longer shelf-life exports of vacuum-packed primals into Asian retail channels.
- Foodservice specification-grade demand:Premium pork belly and loin contracts from hotel chains and QSR networks are pulling volume through certified processing facilities.
- China's GB livestock traceability rollout:Mandatory farm-to-slaughter digital records are accelerating consolidation among export-qualified packers who can finance RFID and blockchain integration.
Market Restraints
- Feed grain price volatility:Corn and soybean meal input costs swing with Black Sea supply disruptions and US drought cycles, compressing packer margins unpredictably.
- Antibiotic residue divergence:Mismatch between EU EFSA zero-tolerance enforcement and legacy veterinary practices in non-certified sourcing regions blocks corridor access.
- Plant-based protein substitution:Cultured and fermented alternatives are capturing flexitarian trial in urban European and North American foodservice accounts.
Strategic Opportunities
- Vietnam chilled retail underpenetration:Modern trade expansion in Ho Chi Minh City and Hanoi creates first-mover positioning for cold-chain-equipped exporters.
- Carbon-labeled pork premiums:EU Green Deal-aligned farm certification schemes reward methane-reduction investments with shelf-space access.
- Direct-to-foodservice platforms:B2B e-procurement portals bypass traditional wholesale layers, capturing margin and data in urban Chinese institutional kitchens.
Industry Challenges
- Veterinary pharmacovigilance talent scarcity:Qualified residue testing technicians and compliance officers are concentrated in legacy EU and US packer workforces.
- Slaughter facility capex intensity:Automated stunning, robotic carcass splitting, and wastewater treatment upgrades demand capital commitments that regional cooperatives cannot syndicate.
- Global G.A.P. audit timeline compression:Certification backlogs and recurring surveillance costs delay market entry for mid-tier producers seeking export eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pork Meat Market |
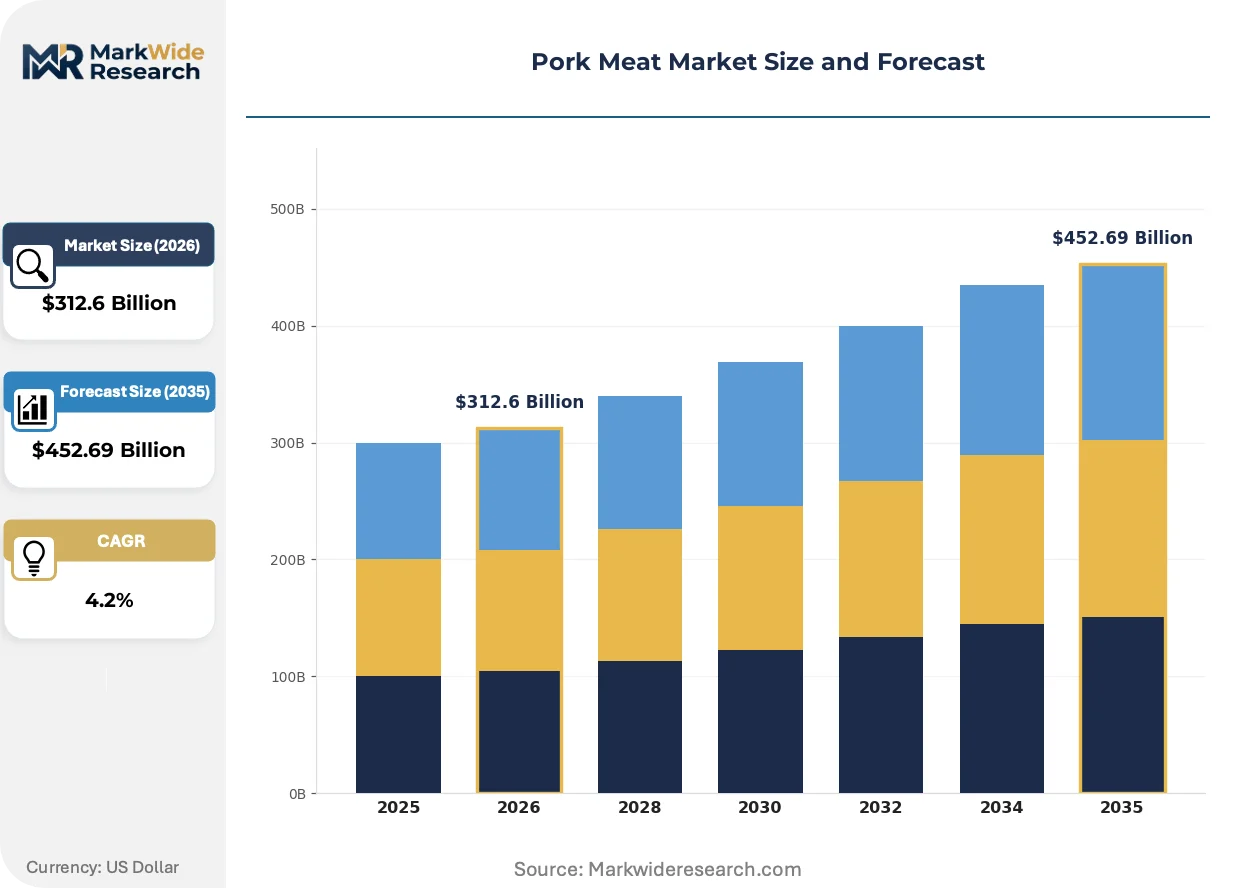
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $452.69 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Hog, Ham, Bacon, Sausages Distribution Channel: Retail, Foodservice, Online, Wholesale End User: Households, Restaurants, Food Processors, Catering Services Packaging Type: Vacuum Packs, Cans, Trays, Chubs |
| Companies Covered | Smithfield Foods, WH Group, Tyson Foods Inc., JBS USA Holdings, Inc., Danish Crown, Tönnies, Westfleisch, Hormel Foods Corporation, China Yurun Food Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pork Meat Market Strategic Shifts
Processing technology and regulatory stringency are diverging competitive outcomes across the value chain, rewarding capital-intensive operators while marginalizing traditional packers. These shifts are compressing the viable supplier base and reconfiguring procurement relationships.
Advanced magnetic resonance imaging (MRI) grading systems are displacing manual USDA marbling assessment in high-throughput plants. Premium branded programs and export-certified facilities are adopting this technology fastest. The capability gap is bifurcating the market into specification-grade suppliers and commodity packers unable to justify the hardware investment.
China's SAMR enforcement of GB 2707 fresh meat hygiene standards is tightening cold-chain documentation requirements for all imported product. Foreign suppliers must now maintain unbroken temperature logs from slaughter through retail delivery. European and Brazilian exporters with pre-existing digital traceability infrastructure are capturing expanded quota allocations.
Urban Chinese households are rotating protein purchases toward pre-portioned convenience formats sold through quick-commerce platforms. Traditional wet market whole-carcass transactions are losing share to 30-minute delivery of branded chilled cuts. This channel migration concentrates volume with packers who can maintain case-ready inventory positions in city-center distribution hubs.
Pork Meat Market Segmentation
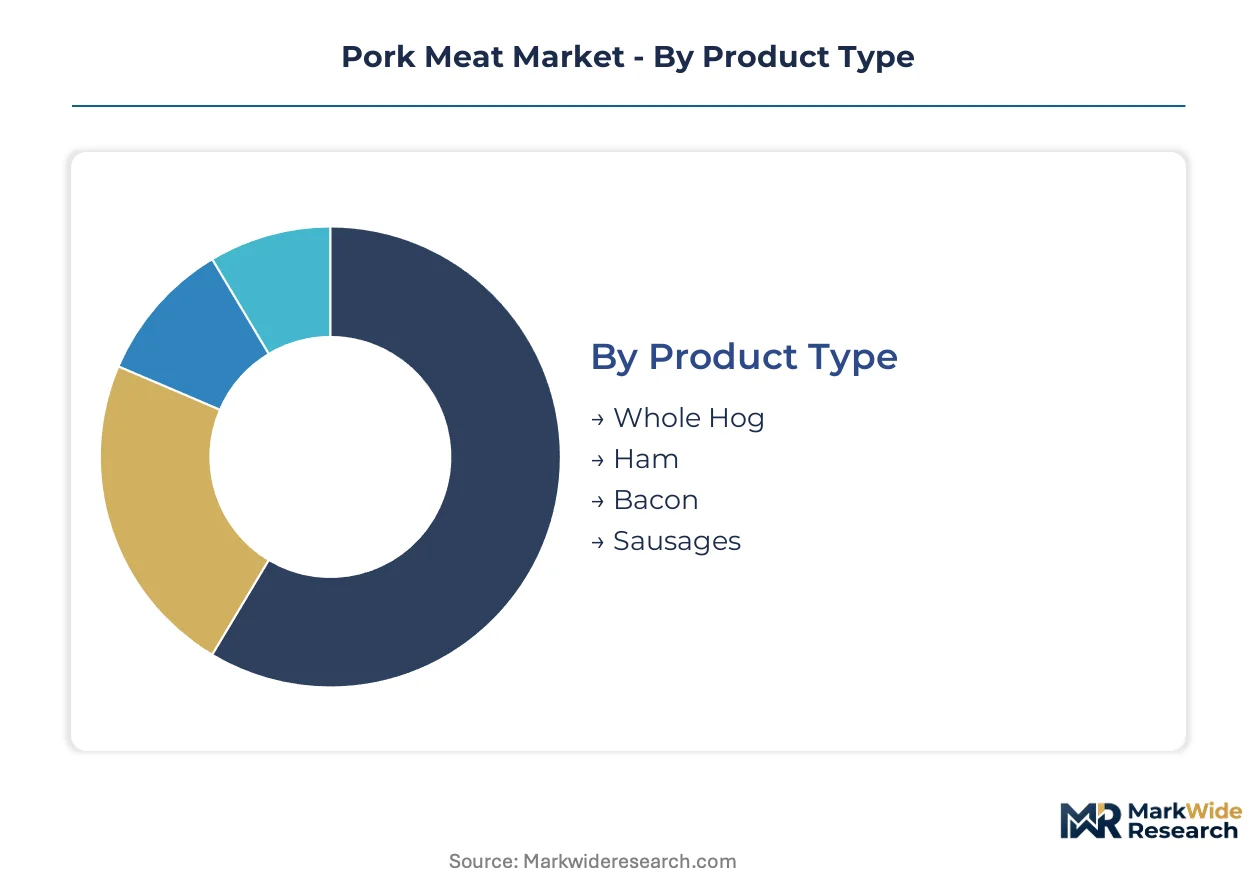
Margin pools in pork meat concentrate where cold-chain reliability intersects with specification-grade demand. Segmentation reveals how packers allocate capital across formats and channels to capture premium pricing versus commodity throughput.
Product Type:
Fresh primal cuts command the widest margin spreads, while processed formats extract value through convenience premiums and extended shelf-life engineering.
- Whole Hog:Carcass sales to institutional butchers and further processors retain moisture specifications between 72-75 percent. Demand clusters in East Asian wet markets and US barbecue supply chains where primal breakdown flexibility matters more than case-ready convenience.
- Ham:Cured and cooked hams require controlled brine injection and thermal processing to achieve target water activity below 0.95. European deli counters and US holiday retail seasons concentrate demand for bone-in and boneless formats with protected designation certifications.
- Bacon:Belly slicing and smokehouse operations yield consistent slice counts for foodservice griddle operations and retail breakfast segments.
- Sausages:Ground and emulsified products span fresh, smoked, and dried categories with casing and seasoning variations.
The dominant share belongs to whole hog and primal cuts, while bacon is closing the gap fastest through breakfast QSR contract expansion.
Distribution Channel:
Channel selection determines working capital intensity and traceability compliance burden, with direct relationships commanding price premiums over arm's-length wholesale.
- Retail:Supermarket and hypermarket distribution demands case-ready packaging, barcode traceability, and promotional slotting fees. Urban Chinese consumers through HEMA and RT-Mart are rotating toward chilled counters with RFID-enabled provenance displays.
- Foodservice:Specification-grade contracts from hotel chains and QSR networks require HACCP-certified facilities and consistent primal dimensions. This channel sustains premium pricing for loin and belly cuts with exact fat trim specifications.
- Online:Quick-commerce platforms in Shanghai and Beijing deliver pre-portioned chilled pork within 30 minutes, bypassing traditional wholesale layers.
- Wholesale:Central market aggregation serves traditional butchers and small processors with volume pricing and minimal packaging overhead.
Foodservice holds the margin leadership position, though online channels are expanding most quickly through platform subsidies and urban convenience demand.
End User:
User type shapes order frequency, specification tolerance, and payment terms, with institutional buyers driving standardization while households reward brand differentiation.
- Households:Urban consumers in tier-1 Chinese cities and European capitals are shifting from wet market whole-carcass purchase toward branded chilled cuts with recipe-ready portioning.
- Restaurants:Independent operators and chain kitchens require consistent primal dimensions and delivery windows, with Chinese hotpot chains specifying exact belly thickness for tableside presentation.
- Food Processors:Further-processing facilities demand frozen or chilled raw material with defined lean-to-fat ratios for sausage, canned, and ready-meal manufacturing.
- Catering Services:Institutional feeding operations prioritize cost control through bulk primal purchases and extended payment terms.
Food processors absorb the highest volume tonnage, while restaurants are gaining share fastest through experience-dining expansion.
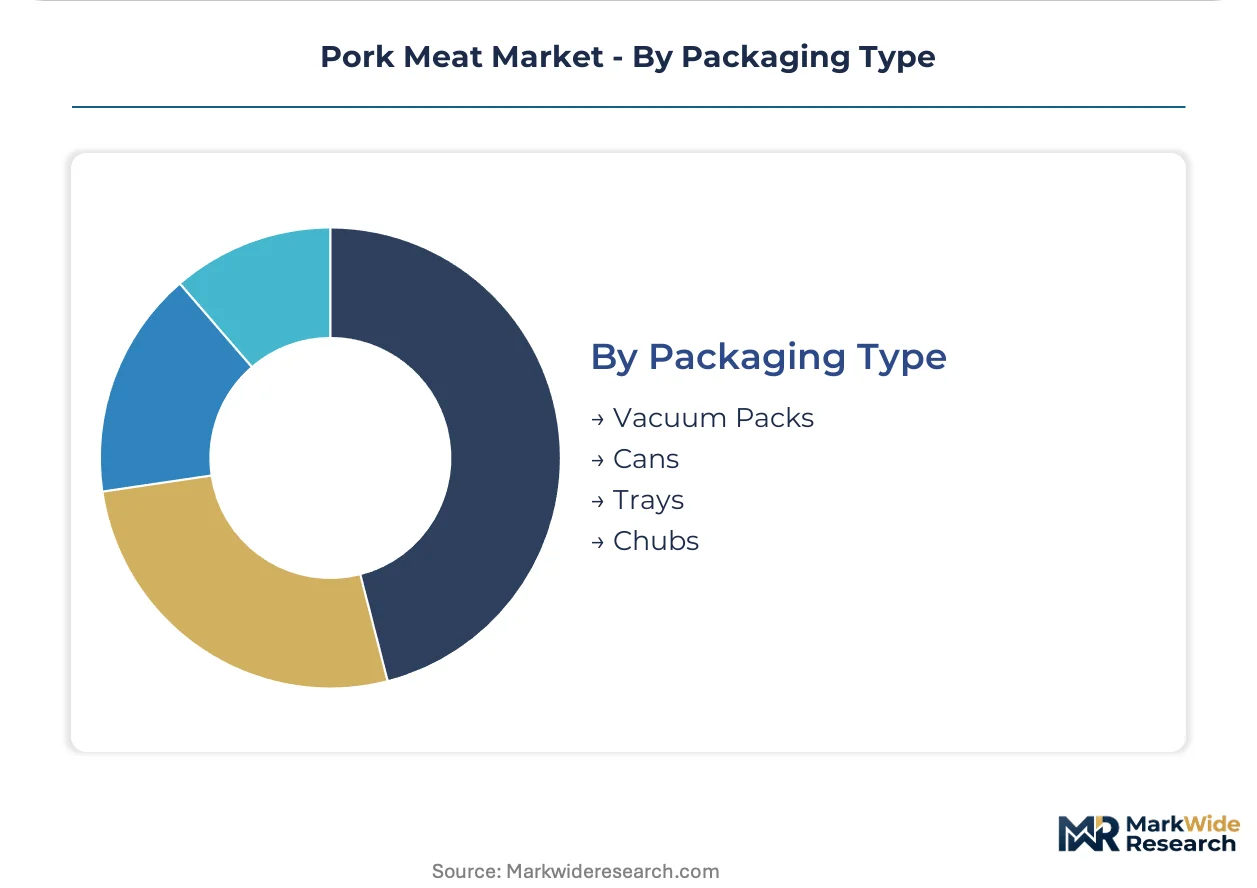
Packaging Type:
Packaging technology determines shelf-life extension, logistics efficiency, and retail presentation quality, with gas-flushed and vacuum formats displacing traditional overwrap.
- Vacuum Packs:Barrier film evacuation extends chilled shelf life to 21-28 days, enabling centralized processing and longer distribution radii. European retail chains and Japanese convenience stores specify vacuum primals for reduced shrinkage.
- Cans:Retort processing achieves ambient stability for ham and luncheon meat in tropical markets with limited cold-chain infrastructure.
- Trays:Modified atmosphere packaging with gas flush preserves color and extends retail case life for fresh cuts in North American and European supermarkets.
- Chubs:Collagen or cellulose casings contain ground pork for institutional foodservice and retail sausage segments.
Vacuum packs dominate value contribution, while trays are climbing the fastest through MAP technology adoption in premium retail segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese foodservice chains and Japanese retail buyers concentrate procurement power in East Asia, while Brazilian packers and US Midwest integrators supply chilled primals through divergent cold-chain standards. European supermarket consolidation and Vietnam's modern trade expansion create parallel demand corridors with distinct compliance requirements.
China
Hotpot chains and quick-commerce platforms in Shanghai and Beijing drive specification-grade belly and loin contracts. SAMR enforcement of GB 2707 hygiene standards and mandatory farm-to-slaughter digital traceability blocks uncertified foreign suppliers. The Yangtze River Delta processing corridor concentrates RFID-enabled packers serving HEMA and RT-Mart chilled counters.
United States
QSR breakfast contracts and barbecue supply chains sustain volume demand for primal cuts with exact fat trim specifications. USDA grading standards and FSIS inspection protocols govern export-eligible slaughter and processing compliance. Iowa-Illinois hog production clusters feed vertically integrated packers with captive grain sourcing and automated processing infrastructure.
Germany
EFSA residue monitoring and EU F-Gas Regulation cold-chain requirements shape domestic retail and export acceptance criteria for vacuum-packed primals. Protected designation ham certifications anchor premium positioning in European deli counters. The North Rhine-Westphalia meat processing belt hosts automated facilities serving REWE and EDEKA centralized distribution.
Brazil
Export quota allocations to China and Southeast Asia drive investment in digital traceability infrastructure compliant with destination market mandates. The country's federal agricultural inspection service enforces equivalent standards for foreign market access. Santa Catarina and Rio Grande do Sul packing clusters specialize in boneless frozen primals for Asian foodservice reprocessing.
Vietnam
Modern trade expansion in Ho Chi Minh City and Hanoi creates first-mover positioning for cold-chain-equipped exporters serving urban household convenience demand. The Ministry of Agriculture and Rural Development implements livestock traceability pilots aligned with regional export standards. Metro retail chains in southern provinces are rotating procurement from wet markets toward case-ready chilled pork with barcode provenance.
Pork Meat Market Competitive Environment
Player mix skews toward vertically integrated grain-to-pork operators and multinational protein conglomerates with captive distribution networks. The structure concentrates volume among packers with in-house feed milling, slaughter automation, and refrigerated logistics assets. Strategic archetypes include Midwest-anchored integrators controlling upstream grain supply, Chinese channel dominants with national retail distribution, and European cooperative federations pooling farmer-owned processing capacity. Dominant competitive moves encompass cold-chain infrastructure expansion and traceability certification acquisition.
Among US-based protein conglomerates, Smithfield Foods and Tyson Foods Inc. exemplify scale-driven archetypes with integrated Midwest operations. WH Group anchors the China-centric channel control archetype through national retail and foodservice distribution density. Danish Crown represents the European cooperative federation model with farmer-owned processing and protected designation premium positioning.
| Leading Market Players |
|---|
| Smithfield Foods |
| WH Group |
| Tyson Foods Inc. |
| JBS USA Holdings, Inc. |
| Danish Crown |
| Tönnies |
| Westfleisch |
| Hormel Foods Corporation |
| China Yurun Food Group |
| Others |
Value Chain & Pricing Dynamics
Midwest grain-to-pork capacity utilization above 85 percent compresses unit costs for integrated packers while forcing regional cooperatives toward distressed spot sales. This scale asymmetry establishes price floors that commodity suppliers cannot breach without margin collapse, concentrating procurement power with operators commanding captive feed milling and automated slaughter infrastructure.
Pricing Analysis
Cost-plus contracts indexed to Chicago Board of Trade corn and soybean meal futures dominate procurement agreements between packers and foodservice operators. Pricing stratifies across Global G.A.P.-certified premium, standard commercial grade, and economy frozen tiers, with certification premiums widening as China's SAMR tightens residue enforcement. Pricing pressure stems from Black Sea grain supply disruptions compressing packer margins. Quick-commerce platforms exhibit highest price sensitivity due to subsidy-dependent customer acquisition, while hotel chains tolerate specification premiums for consistent primal dimensions.
Supply Chain Analysis
The United States, Brazil, and Germany anchor global pork supply through divergent production architectures. US Midwest integrators draw from captive corn and soybean meal sourcing, Brazilian Santa Catarina clusters rest on export-oriented boneless primal processing, and German North Rhine-Westphalia facilities hinge on protected designation ham certifications. Supply chain risk centers on single-source vulnerability in veterinary pharmacovigilance talent concentrated among legacy EU and US packers. Distribution runs through vertically integrated cold-chain networks for chilled product and maritime container aggregation for frozen exports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's mandatory farm-to-slaughter digital traceability rollout constitutes a regulatory inflection that will eliminate uncertified foreign suppliers within the analysis window, compressing viable supply base and amplifying returns for compliant operators.
For Market Incumbents: Shield market position through accelerated RFID and blockchain traceability investment ahead of GB standard enforcement deadlines. Acquire distressed mid-tier packers lacking certification capital to consolidate export quota allocations. Prioritize Vietnam chilled retail pre-positioning before modern trade expansion saturates Ho Chi Minh City and Hanoi distribution nodes.
For New Entrants and Emerging Players: Global G.A.P. certification fast-track programs offer expedited market entry for capitalized operators targeting underpenetrated segments. Vietnam's modern trade transition presents the most penetrable geography, with Metro retail chains rotating procurement from wet markets toward case-ready product. Pursue direct-to-foodservice B2B platform partnerships in urban Chinese institutional kitchens to bypass wholesale margin capture.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated operators with in-house feed milling and automated processing infrastructure. Long-term viability rests on carbon-labeled premium positioning aligned with EU Green Deal farm certification schemes. Monitor veterinary pharmacovigilance talent scarcity as inflection indicator for compliance cost escalation and consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Traceability Infrastructure Investment | RFID and blockchain integration secures SAMR-compliant export eligibility for China-bound product. |
| Cold-Chain Network Expansion | Refrigerated logistics buildout captures Vietnam modern trade growth ahead of competitor positioning. |
| Carbon Certification Program | Methane-reduction farm audits unlock EU Green Deal-aligned shelf-space premiums in European retail. |
| Direct-to-Foodservice Platform Launch | B2B e-procurement portals bypass wholesale layers in urban Chinese institutional kitchens. |
| Automated Processing Upgrade | MRI grading and robotic carcass splitting sustain specification-grade margin premiums against commodity packers. |
Study Parameters
A spread of perspectives from packer operations executives, cold-chain logistics directors, foodservice procurement managers, and regulatory compliance officers converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against USDA FSIS inspection protocols, EFSA residue monitoring guidelines, China's SAMR GB standard filings, and trade flow databases. Bottom-up volume modeling triangulated against top-down value estimates derived from channel pricing intelligence.
Segmentation dimensions modeled span product type, distribution channel, end user, packaging technology, and regional regulatory cluster across the analysis window. CAGRs were derived from trend extrapolation of historical volume flows adjusted for regulatory inflection points and infrastructure investment cycles. Forecast inputs incorporated cold-chain penetration rates, traceability compliance cost curves, and feed grain price volatility assumptions.
Underlying assumptions cover sustained enforcement of China's GB livestock traceability mandates and EU F-Gas Regulation cold-chain equipment standards, with deviation risk concentrated in veterinary pharmacovigilance talent availability and Black Sea grain supply continuity. Recalibration cycles align with material shifts in SAMR enforcement intensity and major market cold-chain infrastructure commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Organic Meat Market
Meat Products
Meat Market
Meat Products
Meat Ingredients Market
Meat Products
Meat Packaging Market
Meat Products
Saudi Arabia Goat Meat and Cheese Market
Meat Products
North America Canned Meat Market
Meat Products
Europe Poultry Meat Market
Meat Products
Global Duck Meats Market
Meat Products
Organic Halal Meat Market
Meat Products
North America Bacon Market
Meat Products
North America Poultry Meat Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Antibiotic Free Meat Market
Meat Products
United States Red Meat Market
Meat Products
Canned Chicken Market
Meat Products
Nitrate-Free Bacon Market