
 Middle-East and Africa Animal-Based Meat and Dairy Products Market | 2026-2036
Middle-East and Africa Animal-Based Meat and Dairy Products Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa Animal-Based Meat and Dairy Products Market Foresight
Skilled halal slaughter technicians and cold-chain logistics specialists is reorganizing production capacity across the Middle-East and Africa. Almarai Company leverages its integrated dairy and poultry operations across Saudi Arabia and Egypt to sustain supply continuity. Danone S.A. anchors its regional growth through localized yogurt and fresh dairy manufacturing in Morocco and Nigeria. Al Islami Foods competes on certified halal meat exports to Gulf Cooperation Council markets, while SADAFCO controls distribution reach through its Saudi-based refrigerated logistics network.
Animal-based meat and dairy products encompass fresh, chilled, frozen, and processed tissues and secretions from cattle, poultry, ovine, and caprine species, preserved through temperature-controlled handling to maintain protein integrity and microbiological safety for human nutrition. The category serves commercial food manufacturing, foodservice operations, and retail household consumption as primary protein and fat sources. Poultry leads volume across the region due to lower feed conversion ratios and shorter production cycles suited to arid climates. Dairy commands premium margin pools where UHT processing and aseptic packaging extend shelf life for supermarket channels. Organic and free-range production methods remain niche but attract urban retailer differentiation in the UAE and South Africa.
SFDA in Saudi Arabia, ESMA in the UAE, and national food safety authorities across North Africa enforce halal certification, import licensing, and cold-chain compliance that shape product standards and market access for regional and international suppliers. The EU Green Deal's due diligence requirements on embedded deforestation are pressuring beef import documentation from sub-Saharan suppliers into North African transit hubs. Stakeholders must monitor evolving national food security strategies and halal traceability mandates as determinants of competitive positioning in procurement and distribution investments.
Market Dynamics
Halal traceability mandates from Saudi SFDA and UAE ESMA are forcing cold-chain infrastructure investments that reshape procurement geography and supplier qualification timelines across Middle-East and Africa meat and dairy networks.
Growth Catalysts
- State food security programs:Saudi Arabia's National Food Security Strategy and UAE's Operation 300bn are channeling sovereign capital into domestic dairy herds and poultry capacity, reducing import dependency for protein staples.
- Retail modernization:Supermarket penetration in Cairo, Lagos, and Riyadh is accelerating demand for UHT milk and chilled packaged meats that tolerate extended shelf-life requirements.
- EU Green Deal due diligence:Documentation requirements for deforestation-free beef are tightening traceability standards at North African transit hubs, favoring suppliers with certified supply chain visibility.
Market Restraints
- Feed input volatility:Maize and soybean meal prices fluctuate with Black Sea grain corridor disruptions, compressing margins for intensive poultry and dairy operations dependent on imported concentrate feeds.
- Slaughter capacity concentration:Certified halal facilities cluster in Saudi Arabia's Riyadh and Jeddah corridors, creating bottlenecks for regional exporters seeking Gulf Cooperation Council market access.
- Plant-based protein substitution:Pea and soy protein isolates from European suppliers are penetrating UAE and South African food manufacturing, displacing processed meat in ready-meal formulations.
Strategic Opportunities
- East African dairy deficit:Ethiopia and Kenya's growing urban populations outrun domestic milk powder production, opening import channels for Egyptian and Sudanese processors with cross-border logistics capability.
- Blockchain halal verification:Distributed ledger systems for slaughter-to-shelf traceability are converging with mobile payment platforms, enabling premium positioning for certified products in Saudi and UAE retail.
- E-commerce cold-chain expansion:Nigeria's Jumia and Saudi Noon are building refrigerated last-mile networks that bypass traditional wholesale markets for direct-to-consumer fresh meat and dairy delivery.
Industry Challenges
- Halal slaughter technician scarcity:Qualified personnel for hand-slaughter certification remain concentrated in Pakistan and Bangladesh, requiring recruitment pipelines that extend certification timelines for new facilities.
- Refrigerated fleet capex intensity:Temperature-controlled trucks and warehousing for dairy distribution demand capital deployment that exceeds balance sheet capacity for mid-scale regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa Animal-Based Meat and Dairy Products Market |
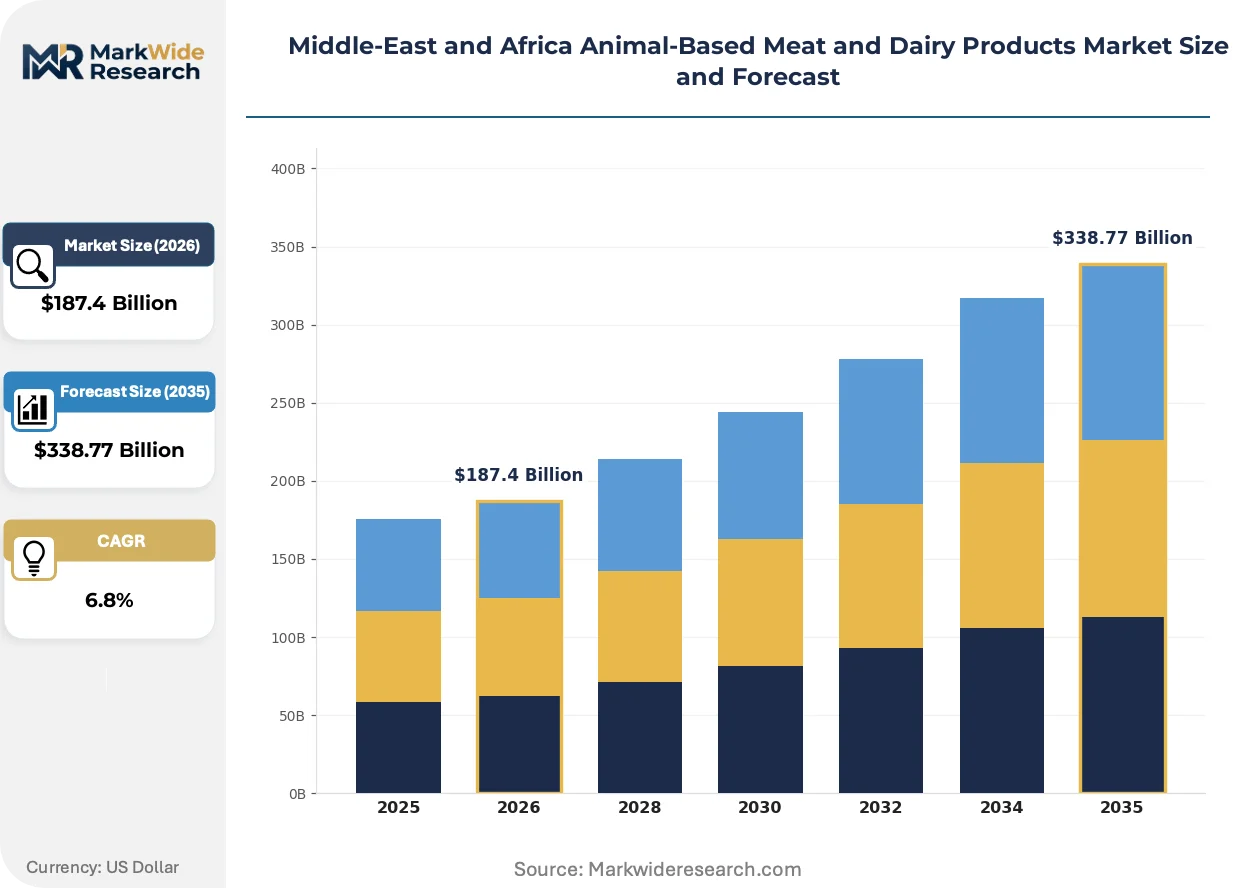
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Poultry, Pork, Dairy End User: Restaurants, Retailers, Food Manufacturers, Households Production Method: Conventional, Organic, Free-Range, Grass-Fed Distribution Channel: Online, Supermarkets, Wholesalers, Direct Sales |
| Companies Covered | Almarai Company, Al-Watania Poultry Co., Al Islami Foods, Danone S.A., SADAFCO, Ghadeer Dairy Co., Lactalis Group, Savola Group, Al Rawabi Dairy, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa Animal-Based Meat and Dairy Products Market Shifts & Advancements
Digital traceability infrastructure and alternative protein competition are compressing traditional competitive advantages in Middle-East and Africa animal protein markets, forcing incumbents to differentiate through certified provenance and cold-chain reliability rather than scale alone.
Blockchain-enabled halal certification platforms are supplanting paper-based chain-of-custody documentation that previously dominated cross-border meat trade. Saudi retailers and UAE hospitality procurement teams are adopting these systems at accelerating pace to satisfy ESMA and SFDA audit requirements. The technology is compressing supplier qualification cycles while raising barriers for uncertified competitors in Gulf Cooperation Council markets.
EU Green Deal embedded deforestation regulations are extending compliance obligations to North African beef transshipment hubs serving European markets. Moroccan and Tunisian customs authorities are deploying satellite verification systems to document pasture provenance for sub-Saharan cattle imports. North African logistics operators with documentation capability are capturing premium routing volumes while informal channels face exclusion.
Consolidated buying by Saudi and UAE hypermarket chains is displacing fragmented wholesale procurement that historically dominated regional meat and dairy distribution. Carrefour Saudi, Lulu UAE, and Spinneys are centralizing direct supplier contracts that bypass traditional importer-distributor networks. This concentration is most visible in Dubai and Riyadh, where centralized distribution centers now handle majority fresh protein volumes.
Middle-East and Africa Animal-Based Meat and Dairy Products Market Segmentation
Segmentation reveals where plant-based substitutes exert maximum pressure on traditional animal protein revenues. Understanding channel and production-method splits exposes vulnerability points for incumbent suppliers across Middle-East and Africa markets.
Product Type:
Pork faces negligible substitution risk due to religious prohibition, while poultry and dairy confront accelerating competitive pressure from pea and soy isolates in food manufacturing formulations.
- Beef:Chilled and frozen carcass cuts from cattle, ovine, and caprine species supply protein for retail and foodservice. Saudi Arabia's state-backed herd expansion and UAE hypermarket centralization are concentrating procurement around certified halal suppliers with cold-chain documentation.
- Poultry:Broiler meat dominates regional volume due to superior feed conversion ratios and shorter production cycles suited to arid climates. Egyptian and Saudi integrators are scaling capacity to serve expanding quick-service restaurant networks across North Africa and the Gulf.
- Pork:Effectively absent from regional consumption patterns due to Islamic dietary law; negligible commercial presence outside non-Muslim minority communities in South Africa and Lebanon.
- Dairy:Fluid milk, yogurt, cheese, and processed derivatives preserved through UHT and aseptic packaging. Moroccan and Nigerian manufacturing hubs are capturing margin pools from extended shelf-life formats demanded by supermarket penetration in Lagos and Cairo.
Poultry retains volume leadership; dairy holds the steepest expansion curve.
End User:
Channel concentration determines pricing power and certification burden, with food manufacturers imposing the most stringent halal traceability requirements.
- Restaurants:Quick-service and casual dining chains across Riyadh, Dubai, and Cairo drive demand for standardized portion-cut poultry and processed dairy ingredients. Procurement teams are consolidating supplier lists to reduce audit complexity under SFDA and ESMA mandates.
- Retailers:Supermarket and hypermarket operators including Carrefour Saudi and Lulu UAE are building direct supplier relationships that bypass traditional importer-distributor networks. Centralized distribution centers in Dubai and Riyadh now handle majority fresh protein volumes.
- Food Manufacturers:Ready-meal and processed food producers source chilled beef and dairy for industrial formulation. EU Green Deal deforestation documentation requirements are filtering through to North African transit hubs serving these customers.
- Households:Traditional wholesale market purchases persist in lower-income segments, though e-commerce platforms Jumia and Noon are building refrigerated last-mile networks for direct delivery.
Retailers command procurement consolidation; food manufacturers impose the strictest compliance standards.
Production Method:
Cost structure and certification intensity vary dramatically across methods, with organic and free-range formats attracting urban premium positioning despite limited scale.
- Conventional:Intensive feedlot and barn systems using imported maize and soybean meal concentrates. Black Sea grain corridor disruptions are compressing margins for operations dependent on foreign feed inputs.
- Organic:Production excluding synthetic inputs and genetically modified feeds, certified under national organic standards. UAE and South African urban retailers differentiate through these formats despite limited domestic supply.
- Free-Range:Poultry and ovine production with outdoor access requirements, appealing to welfare-conscious consumers in Gulf urban centers. Premium positioning remains niche due to land and water constraints.
- Grass-Fed:Cattle raised on pasture without grain finishing, concentrated in Sudan and Ethiopia where rangeland access persists. Satellite verification systems are documenting provenance for EU Green Deal compliance at North African transshipment points.
Conventional methods dominate cost-competitive supply; organic formats gain share fastest among differentiated urban channels.
Distribution Channel:
Cold-chain infrastructure investment requirements stratify channel access, favoring capitalized operators in temperature-controlled segments.
- Online:E-commerce platforms building refrigerated fulfillment networks for direct-to-consumer fresh meat and dairy. Saudi Noon and Nigeria's Jumia are bypassing traditional wholesale markets with last-mile cold-chain capability.
- Supermarkets:Modern retail formats with centralized distribution and direct supplier contracting. Carrefour, Lulu, and Spinneys operations in Riyadh and Dubai are displacing fragmented procurement patterns.
- Wholesalers:Traditional importer-distributor networks serving smaller retail and foodservice accounts. Consolidating buyer power at hypermarket chains is eroding margins and volume for these intermediaries.
- Direct Sales:Producer-to-consumer channels including farm shops and subscription models, limited by cold-chain requirements and regulatory compliance burdens.
Supermarkets anchor volume throughput; online channels are climbing the fastest as platform infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SFDA in Saudi Arabia anchors regulatory gravity across Middle-East and Africa meat and dairy networks, with ESMA in the UAE and national food safety authorities across North Africa enforcing halal certification and cold-chain compliance that reshape procurement geography.
Saudi Arabia
State-backed herd expansion and retail modernization drive chilled beef and UHT dairy demand. The National Food Security Strategy channels sovereign capital into domestic poultry capacity and dairy herd development. Riyadh and Jeddah corridors concentrate certified halal slaughter facilities, creating bottlenecks for regional exporters seeking Gulf Cooperation Council market access.
United Arab Emirates
Hypermarket centralization and hospitality procurement consolidation accelerate direct supplier contracting. ESMA halal traceability mandates force cold-chain infrastructure investments that reshape qualification timelines. Dubai's centralized distribution centers now handle majority fresh protein volumes, displacing traditional importer-distributor networks.
Egypt
Quick-service restaurant network expansion and supermarket penetration in Cairo drive standardized portion-cut poultry demand. National food safety authorities enforce import licensing and cold-chain compliance for cross-border dairy trade. Egyptian integrators scale broiler capacity to serve North African and Gulf markets, leveraging Suez Canal logistics for regional distribution.
South Africa
Urban retailer differentiation and welfare-conscious consumption patterns create niche positioning for organic and free-range formats. The country's national food safety regulator enforces standards for imported meat and dairy products. Cape Town and Johannesburg clusters concentrate cold-chain logistics capability for premium distribution to supermarket channels.
Nigeria
Rapid urban population growth and traditional wholesale market displacement by e-commerce platforms drive refrigerated last-mile network investments. National food safety authorities implement halal certification requirements for imported protein products. Lagos anchors demand concentration while Jumia builds direct-to-consumer fresh meat and dairy delivery infrastructure.
Middle-East and Africa Animal-Based Meat and Dairy Products Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Middle-East and Africa animal protein markets. Integrated dairy-poultry operators with captive cold-chain networks compete against specialized halal meat exporters and multinational dairy manufacturers with localized production. The structure stratifies into three tiers: sovereign-backed national champions with distribution scale, multinational processors with brand equity, and regional specialists with certification depth. Dominant competitive moves include backward integration into feed and breeding operations, and strategic partnerships with retail chains for direct supplier status.
Within the integrated national champion tier, Almarai Company and SADAFCO represent archetypes of scale-driven positioning anchored in Saudi Arabia's state-backed food security programs. Among specialized halal meat exporters, Al Islami Foods occupies a position exemplifying certification-first competitive logic. Multinational dairy manufacturing is anchored by Danone S.A., which sits within the localized production archetype through Moroccan and Nigerian manufacturing hubs.
| Leading Market Players |
|---|
| Almarai Company |
| Al-Watania Poultry Co. |
| Al Islami Foods |
| Danone S.A. |
| SADAFCO |
| Ghadeer Dairy Co. |
| Lactalis Group |
| Savola Group |
| Al Rawabi Dairy |
| Others |
Supply & Pricing Matrix
Forty-five to sixty-day slaughter-to-shelf lead times for chilled beef moving through Jeddah and Riyadh corridors concentrate pricing power with Saudi-certified halal facilities, while Egyptian and Sudanese processors absorb margin compression from Black Sea feed grain volatility. This temporal-spatial coupling rewards operators with captive cold-chain networks and punishes spot-market dependent distributors.
Pricing Analysis
Price spreads between Gulf Cooperation Council retail shelves and East African wholesale gates exceed transport-adjusted parity, creating arbitrage windows for Egyptian integrators with cross-border logistics capability. Three-tier pricing structure across premium certified-halal, standard commercial-grade, and economy frozen formats dominates the market. Cost compression in the economy tier is intensifying because Brazilian and Indian frozen beef imports face extended SFDA qualification timelines. Quick-service restaurant procurement teams exhibit highest price sensitivity, while UAE hospitality buyers prioritize traceability documentation over unit cost.
Supply Chain Analysis
Strait of Hormuz transit underwrites refrigerated vessel routing for Brazilian beef and Ukrainian dairy powder entering Gulf markets, exposing volumes to geopolitical disruption risk. Supply concentrates in Saudi Arabia's integrated dairy-poultry corridor, Egypt's Nile Delta broiler belt, and Morocco's UHT processing hubs. Operations draw from imported maize and soybean meal concentrates, regional breeding stock, and aseptic packaging materials. Single-source vulnerability in Pakistani and Bangladeshi halal slaughter technician recruitment extends facility certification timelines. Distribution runs through hypermarket centralized distribution centers in Dubai and Riyadh, displacing traditional importer-distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as state-backed food security programs and retail modernization accelerate penetration of temperature-controlled protein formats beyond traditional wholesale channels. Sovereign capital deployment into domestic herds and poultry capacity creates structural demand tailwinds for qualified suppliers.
For Market Incumbents: Shield margin pools by deepening backward integration into feed milling and breeding operations, capturing cost volatility that compresses spot-dependent competitors. Secure direct supplier status with Carrefour Saudi, Lulu UAE, and Spinneys through blockchain-enabled halal traceability investments that satisfy ESMA and SFDA audit compression timelines. Plant-based protein substitution from European pea and soy isolates threatens processed meat ready-meal formulations. For New Entrants and Emerging Players: Refrigerated last-mile service gaps in Lagos and Nairobi suburbs present white-space opportunities where Jumia and Noon platforms under-serve fresh meat and dairy demand. Target Ethiopian and Kenyan urban dairy deficits with cross-border logistics partnerships leveraging Sudanese and Egyptian milk powder surplus. East African e-commerce cold-chain buildout offers the most penetrable entry vector. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because hypermarket procurement centralization and regulatory compliance burdens favor scaled operators with captive distribution networks. Acquisition targets include mid-scale regional distributors with refrigerated fleet assets and established ESMA qualification pathways. Watch blockchain halal verification adoption rates in Saudi retail as the inflection signal for premium positioning viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feed Milling | Captures margin from Black Sea grain corridor volatility affecting Egyptian and Saudi poultry operations. |
| Blockchain Halal Verification Deployment | Compresses SFDA and ESMA supplier qualification cycles while raising barriers for uncertified competitors. |
| East African Cross-Border Dairy Logistics | Addresses Ethiopian and Kenyan urban milk powder deficits through Sudanese and Egyptian surplus channels. |
| Hypermarket Direct Supplier Contracting | Bypasses traditional importer-distributor networks eroded by Carrefour and Lulu centralized procurement. |
| Refrigerated E-Commerce Last-Mile Buildout | Enables Jumia and Noon platforms to displace Lagos and Riyadh wholesale markets for fresh protein delivery. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with halal certification officers, cold-chain logistics directors, hypermarket category buyers, and Egyptian poultry integrator executives; and secondary validation through SFDA regulatory filings, ESMA technical standards, customs trade databases, and Suez Canal transit records. Bottom-up volume modeling triangulated against top-down sovereign food security program expenditure tracking.
Across the projection horizon, the analytical framework segmented by product type, production method, distribution channel, and end-user archetype to isolate substitution vulnerability points. CAGRs derived from historical trajectory analysis adjusted for state-backed capacity buildout intensity and retail modernization penetration curves. Forecast inputs incorporated Black Sea grain corridor stability assumptions and halal slaughter technician pipeline constraints.
Forecasts assume regulatory continuity in Saudi SFDA and UAE ESMA halal traceability regimes; material policy shifts would require re-modeling. Black Sea feed input volatility and EU Green Deal deforestation documentation tightening at North African transit hubs represent specific revision triggers. Revision becomes warranted when blockchain halal verification adoption crosses threshold penetration in Gulf retail procurement specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Organic Meat Products Market
Meat Products
Organic Meat Market
Meat Products
Canned Chicken Market
Meat Products
Edible Offal Market
Meat Products
United States Red Meat Market
Meat Products
South Africa Processed Meat Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Sausage Premixes Market
Meat Products
Beef Fat Market
Meat Products
Rendered Poultry Products Market
Meat Products
Global Red Meat Market
Meat Products
Global Poultry Meat Market
Meat Products
Dehydrated Meat Products Market
Meat Products
Lab-Grown Meat Market
Meat Products
Antibiotic Free Meat Market