
 Canned Chicken Market | 2026-2036
Canned Chicken Market Size, Share, and Industry Trends Forecast 2026-2036
Canned Chicken Market Insights
Multi-source protein procurement is pivoting toward vertically integrated poultry processors with captive canning capacity. Tyson Foods Inc. leverages its grain-to-gate supply chain to secure raw material throughput for retail-ready canned formats. Hormel Foods Corp. sustains brand recognition in chunked and shredded lines through controlled distribution to club and mass channels. Conagra Brands Inc. competes on volume scale, anchoring private-label programs for national grocery banners.
Canned chicken denotes fully cooked poultry meat preserved in hermetically sealed containers via commercial sterilization, typically achieving shelf stability exceeding two years without refrigeration. The product serves as a convenience protein for household pantries, emergency stockpiles, and quick-service kitchen prep where labor minimization matters. Chunk and shredded formats dominate current output, with easy-open and pull-tab packaging configurations capturing preference among older demographics and on-the-go consumers. Retail stores and distributors still occupy the largest volume pathways, though online sales channels are extending reach into subscription-based preparedness and bulk-buying segments.
USDA Food Safety and Inspection Service oversight governs plant sanitation, pathogen testing, and labeling accuracy for all domestically produced canned chicken. FDA regulations under the Food Safety Modernization Act impose preventive controls on imported product streams, while OSHA standards shape worker safety protocols in high-speed canning operations. Stakeholders must monitor evolving sodium-reduction guidance and sustainable packaging mandates, as these frameworks will determine which product formulations and container formats retain shelf access across major sales channels.
Market Dynamics
Retort processing automation is compressing cycle times and tightening pathogen control thresholds, forcing processors to consolidate canning lines or exit the category entirely.
Growth Catalysts
- USDA FSIS inspection mandates:Stricter sanitation protocols are filtering out marginal operators, concentrating volume among compliant processors and improving category trust metrics.
- Emergency preparedness procurement:Federal disaster-relief stockpiling and household pantry-stocking behavior sustain baseline demand regardless of economic cycles.
- Food service labor minimization:Quick-service kitchens are substituting pre-cooked canned formats for raw chicken prep to reduce handling steps and cross-contamination risk.
Market Restraints
- Aluminum can sheet volatility:Input cost swings for two-piece can bodies compress margin predictability for mid-tier processors without long-term metal supply contracts.
- Retort equipment concentration:High-speed sterilization line manufacturers cluster in Germany and Japan, creating capex bottlenecks for capacity expansion.
- Fresh refrigerated alternatives:Rotisserie chicken and chilled fully-cooked strips compete directly on taste perception and sodium content.
Strategic Opportunities
- Subscription preparedness channels:Direct-to-consumer emergency food kits represent underdeveloped white space beyond traditional retail and institutional procurement.
- EU sustainable packaging mandates:The EU Green Deal's single-use plastic reduction targets create first-mover advantage for fiber-based or recyclable can end innovations.
- Retort pouch convergence:Flexible pouch formats paired with microwaveable convenience are capturing younger demographics resistant to conventional can aesthetics.
Industry Challenges
- Retort operator skill scarcity:Specialized knowledge of thermal process validation and come-up time calibration is aging out of the workforce faster than training programs replace it.
- Legacy ERP integration:Batch record digitization for FDA preventive controls compliance conflicts with decades-old manufacturing execution systems still running on-premises.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canned Chicken Market |
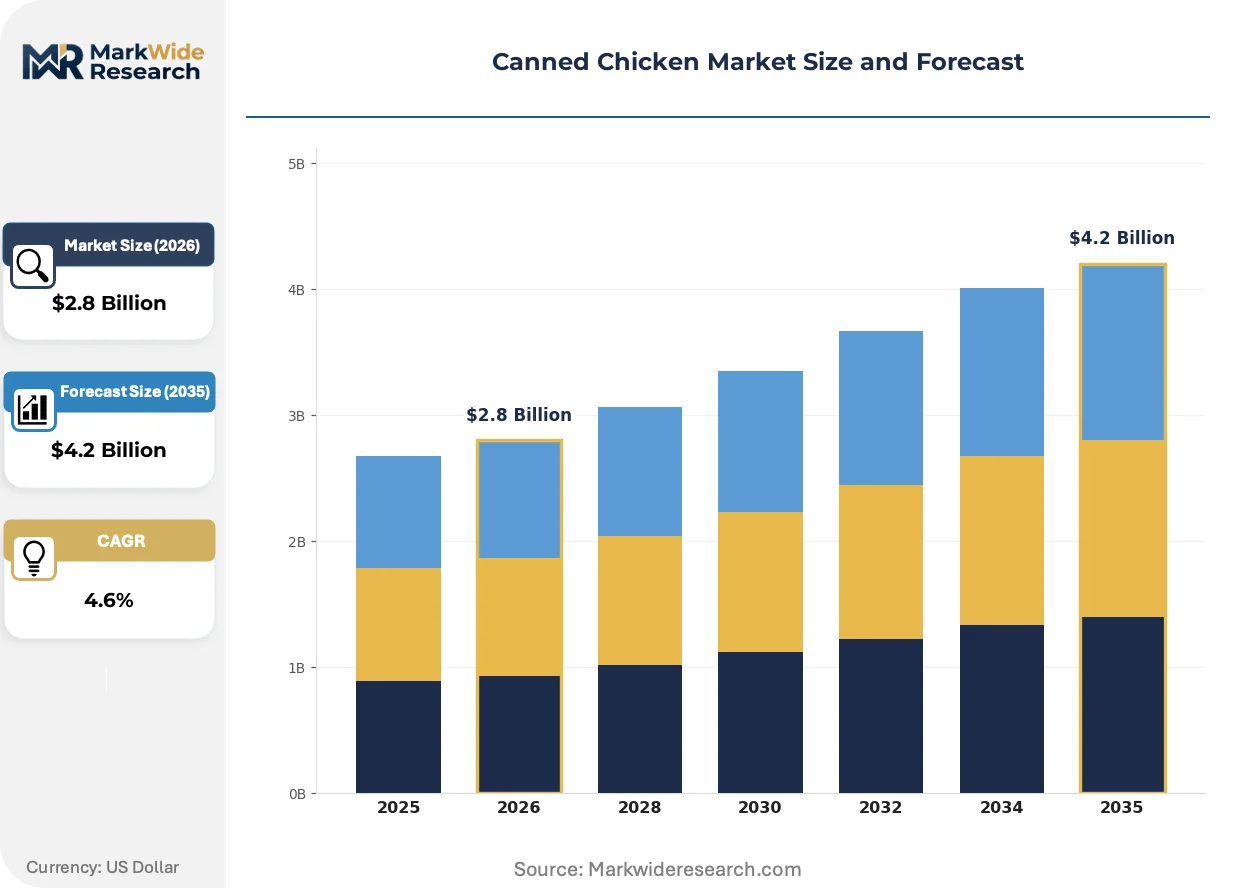
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chunk, Shredded, Sliced, Whole Packaging Type: Easy-Open, Pull-Tab, Can, Jar Sales Channel: Retail Stores, Online, Distributors, Wholesalers End User: Households, Restaurants, Cafés, Food Service |
| Companies Covered | Tyson Foods Inc., Hormel Foods Corp., Campbell Soup Co., Bumble Bee Foods LLC, Swanson, Conagra Brands Inc., Century Pacific Food Inc., Crider Foods, Keystone Meats, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canned Chicken Market Trends and Innovations
Automation and alternative preservation formats are disrupting the traditional metal-can paradigm, splitting investment flows between efficiency upgrades and format experimentation.
Continuous rotary retort systems with automated basket handling and real-time temperature logging are rewriting throughput economics for high-volume processors. Mid-tier canneries in the US Southeast are retrofitting existing static retorts with PLC-based controls to narrow the productivity gap without full line replacement. The technology is rewriting competitive viability thresholds, compressing the viable scale minimum for sustained operation.
The FDA Food Safety Modernization Act's foreign supplier verification program is tightening documentation burdens on imported canned chicken streams. Domestic processors are capturing displaced volume as Asian exporters struggle with preventive controls qualified individual requirements. Smaller importers without in-house regulatory affairs capacity are exiting the US market entirely.
Club store bulk purchasing is displacing traditional grocery multi-can promotions as the dominant household stockpiling mechanism. Costco and Sam's Club members are gravitating toward 12-can master cases with extended expiration dating for basement storage. This pattern is most visible in hurricane-prone Gulf Coast states where seasonal preparedness drives concentrated category spikes.
Canned Chicken Market Segmentation
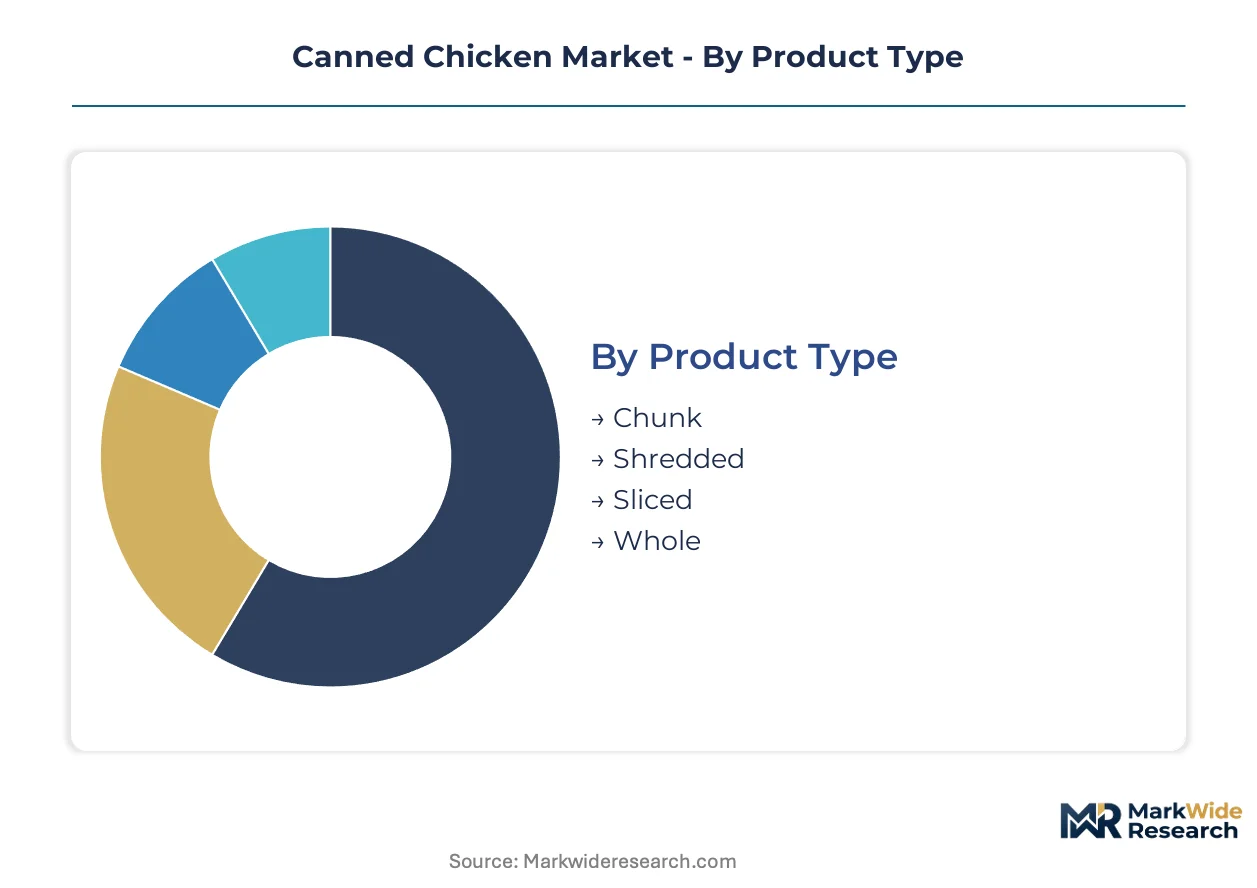
Segmentation in canned chicken reveals how texture preferences, packaging convenience, and procurement channels split demand across distinct value tiers. Each dimension carries different margin profiles and regulatory exposure, shaping where processors allocate capital for line expansion.
Product Type:
The customization-standardization spectrum runs from commodity whole muscle to precision-cut formats engineered for specific menu applications.
- Chunk:Irregular bite-sized pieces retain moisture through retort cycling better than shredded alternatives. Demand concentrates in quick-service kitchens across the US Southeast, where hurricane-season stockpiling and year-round labor minimization drive institutional procurement.
- Shredded:Fine-stranded texture suits sandwich fillings and salad applications requiring fork-tender consistency. Club store bulk buyers in Florida and Texas favor this format for household emergency kits, with easy-open packaging configurations capturing preference among older demographics.
- Sliced:Uniform thickness enables predictable portion control for deli counters and catering operations.
- Whole:Intact breast or thigh muscle appeals to traditional pantry stockpilers seeking visual confirmation of meat integrity.
Leading the category by volume: Chunk. Growing fastest: Shredded.
Packaging Type:
Cost tier stratification separates premium convenience features from economy formats targeting price-sensitive institutional buyers.
- Easy-Open:Ring-pull mechanisms eliminate tool dependency for emergency scenarios and accessibility compliance. Federal disaster-relief procurement specifications increasingly mandate this feature, with USDA FSIS labeling requirements adding verification overhead.
- Pull-Tab:Integrated stay-on-tab designs reduce litter risk in outdoor and field feeding contexts. Gulf Coast state emergency management agencies specify this format for mobile distribution units, where metal debris control matters.
- Can:Standard two-piece metal construction dominates private-label programs for national grocery banners.
- Jar:Glass containers serve niche gourmet positioning and visual premium cues in specialty retail.
Easy-Open commands the largest volume share. Pull-Tab gains share fastest in institutional channels.
Sales Channel:
Volume concentration versus margin capture defines how processors balance throughput scale against customer relationship investment.
- Retail Stores:Supermarket and mass merchant shelf placement still absorbs the majority of case volume. National grocery banners anchor private-label programs, with club store bulk purchasing displacing traditional multi-can promotions as the dominant household stockpiling mechanism.
- Online:Direct-to-consumer emergency food kits represent underdeveloped white space beyond traditional retail procurement. Subscription-based preparedness segments are extending reach into bulk-buying demographics resistant to conventional store visits.
- Distributors:Broadline foodservice distributors consolidate fragmented restaurant and café demand.
- Wholesalers:Cash-and-carry operators serve independent operators and small-format retailers.
Retail Stores lead by absolute volume. Online climbs the fastest as preparedness subscriptions mature.
End User:
Application maturity separates established institutional workflows from emerging convenience-driven household behaviors.
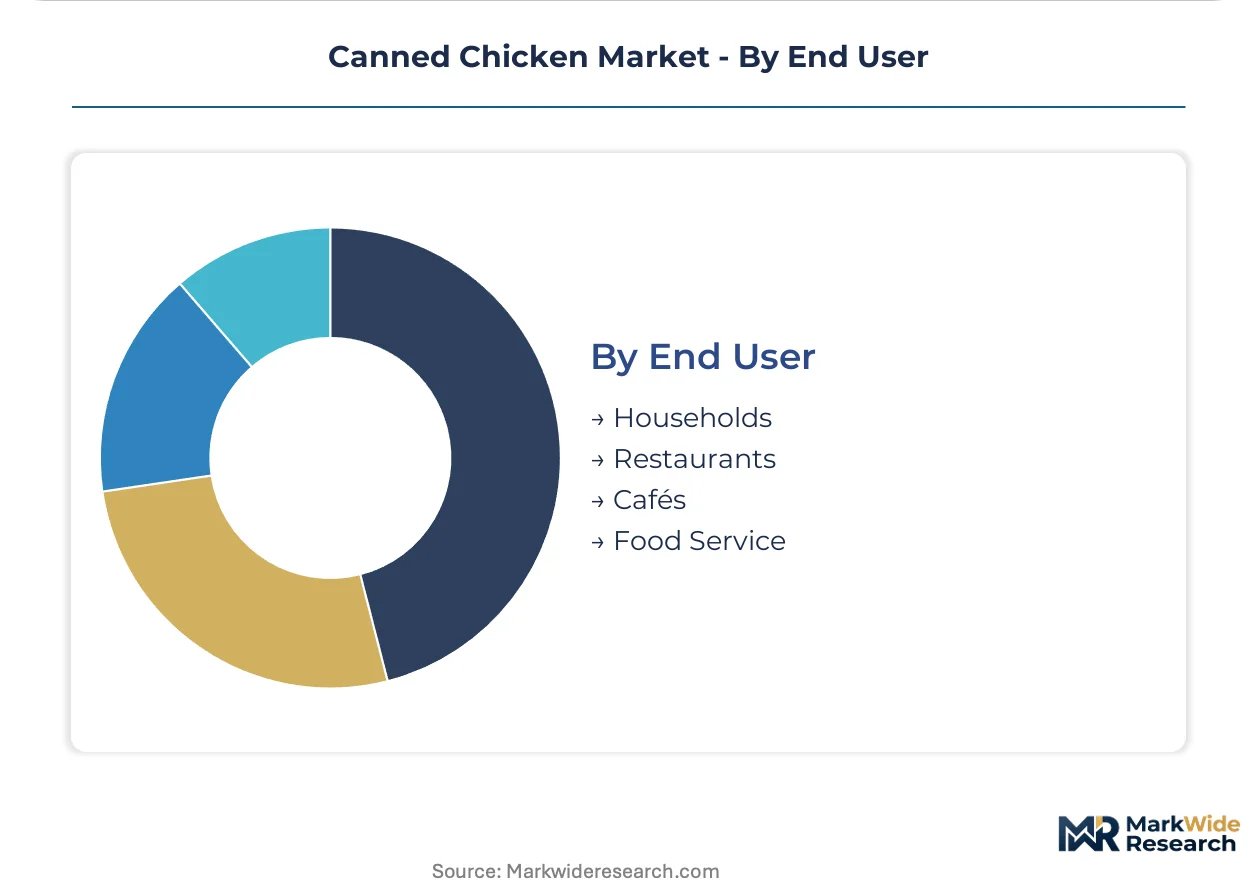
- Households:Pantry-stocking behavior sustains baseline demand regardless of economic cycles, with basement storage patterns most visible in hurricane-prone Gulf Coast states where seasonal preparedness drives concentrated category spikes.
- Restaurants:Quick-service kitchens substitute pre-cooked canned formats for raw chicken prep to reduce handling steps and cross-contamination risk. Labor minimization priorities override taste perception tradeoffs in high-turnover operations.
- Cafés:Limited-service formats with constrained back-of-house space favor shelf-stable protein over refrigerated inventory management.
- Food Service:Institutional feeders including schools, hospitals, and correctional facilities prioritize specification compliance and extended dating over format innovation.
Households represent the largest addressable base. Restaurants show the steepest expansion trajectory as labor costs pressure kitchen operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grain-belt poultry processing clusters in the US Midwest and Southeast supply the feedstock base for canned chicken manufacturing. Regional demand patterns split between hurricane-preparedness stockpiling in coastal zones and foodservice labor-minimization needs in metropolitan kitchen operations.
United States
Pantry-stocking behavior and federal disaster-relief procurement sustain category volume across all economic cycles. USDA FSIS inspection mandates filter out marginal operators, concentrating compliant processing capacity among established players. The US Southeast—particularly Georgia and Alabama—hosts dense clusters of grain-to-gate poultry operations with captive canning lines.
Canada
Household emergency preparedness drives steady baseline demand in provinces with severe winter weather exposure. Health Canada and the Canadian Food Inspection Agency impose parallel pathogen testing protocols to USDA standards, creating regulatory alignment for cross-border product flows. Ontario-based processors serve both domestic club-store bulk buyers and US private-label programs.
Germany
EU Green Deal packaging mandates are accelerating fiber-based can end innovation among Central European suppliers. EFSA sodium-reduction guidance shapes reformulation priorities for shelf-stable protein lines. The Ruhr industrial corridor hosts specialized retort equipment manufacturers whose sterilization technology exports shape global canning line economics.
Japan
Aging demographics and single-person households expand demand for easy-open, portion-controlled formats. METI food safety standards and JIS packaging specifications create technical barriers that favor domestic processors with established compliance infrastructure. The Chubu region around Nagoya retains concentration in high-speed retort machinery production.
Australia
Bushfire and flood preparedness sustains emergency food kit procurement by state emergency services. FSANZ labeling requirements and biosecurity import protocols protect domestic processors from low-cost Asian competition. Queensland and New South Wales poultry growing regions supply raw material to coastal canning operations serving Pacific island export markets.
Canned Chicken Market Competitive Landscape
Backward integration into captive poultry supply dominates the current landscape, with grain-to-gate operators compressing input cost volatility for rival processors. The vendor base splits between three structural tiers: multinational protein conglomerates with integrated canning assets, mid-scale regional processors serving institutional accounts, and private-label contractors competing on volume scale. Strategic archetypes include vertical integrators controlling feed-through-distribution, brand marketers investing in chunked and shredded format differentiation, and co-manufacturers anchoring retailer exclusive programs. Capacity expansion and portfolio diversification represent the dominant competitive moves, as processors add retort lines or extend into adjacent shelf-stable proteins.
Within the multinational integrator tier, Tyson Foods Inc. and Hormel Foods Corp. exemplify divergent approaches to category presence—one leveraging scale economics across protein segments, the other concentrating brand equity in convenience-oriented formats. Conagra Brands Inc. occupies a position emphasizing private-label volume and retailer partnership depth. These three anchors illustrate how competitive positioning stratifies across backward integration intensity, brand marketing investment, and co-manufacturing flexibility.
| Leading Market Players |
|---|
| Tyson Foods Inc. |
| Hormel Foods Corp. |
| Campbell Soup Co. |
| Bumble Bee Foods LLC |
| Swanson |
| Conagra Brands Inc. |
| Century Pacific Food Inc. |
| Crider Foods |
| Keystone Meats |
| Others |
Pricing and Supply Chain Analysis
Federal disaster-relief procurement specifications mandating easy-open packaging configurations are compressing margin flexibility for processors lacking automated end-seaming capacity, forcing mid-tier operators to absorb retrofit costs or surrender institutional tenders to integrated competitors with captive line investments.
Pricing Analysis
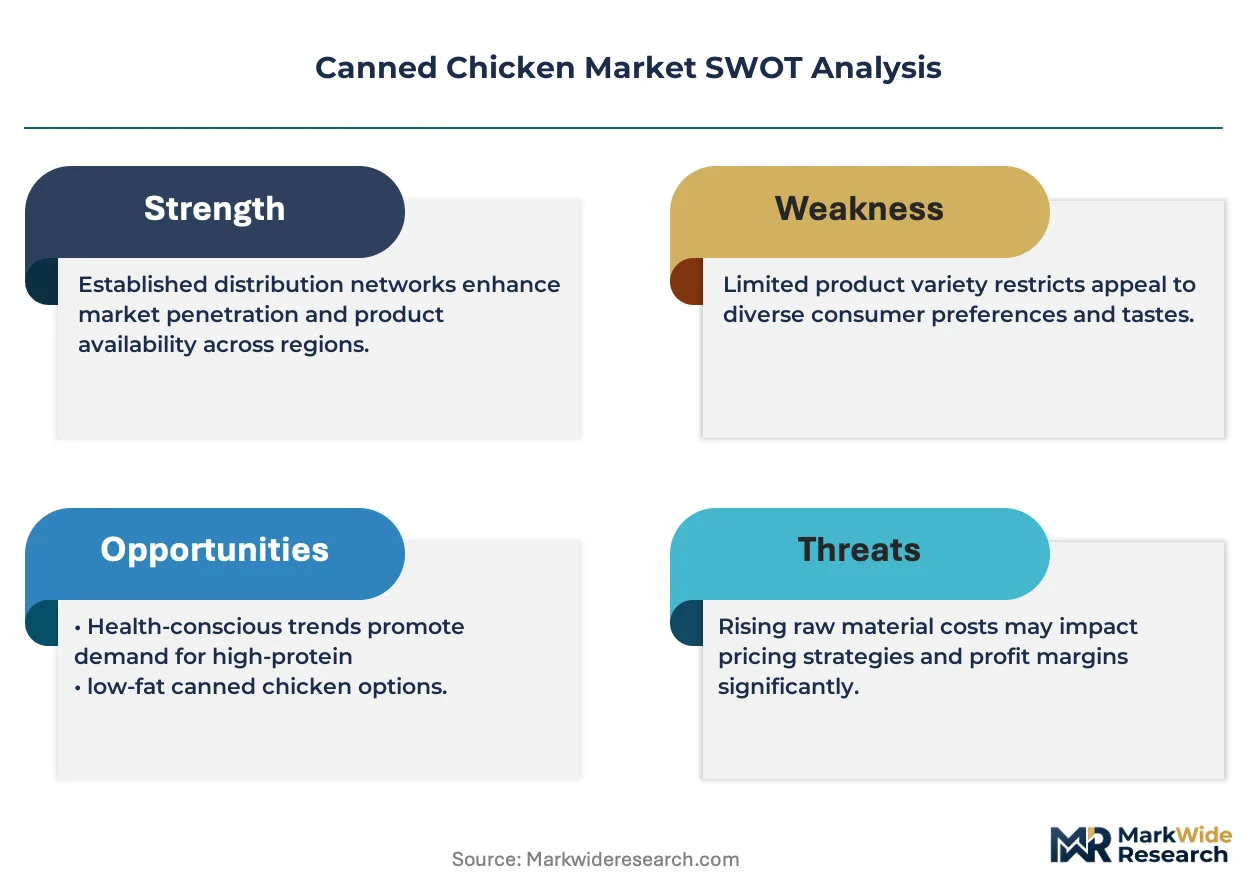
Warranty and shelf-life guarantee bundling separates premium-positioned brands from unbundled private-label alternatives trading purely on unit economics. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and sodium-content compliance, with USDA organic and reduced-sodium tiers commanding measurable premiums over commodity chunk formats. Pricing pressure stems from aluminum can sheet volatility eroding predictability for processors without long-term metal supply contracts. Institutional buyers in federal and state emergency management channels exhibit lowest price sensitivity due to specification compliance mandates, while cash-and-carry wholesalers serving independent retailers face acute margin compression.
Supply Chain Analysis
Aluminum can sheet supply rests on rolling mill capacity concentrated in the United States, Germany, and Japan, with two-piece can body production tethered to metal coating and lithography specialists in the same geographies. Poultry feedstock draws from grain-belt growing operations across Georgia, Alabama, and Arkansas, while retort sterilization equipment sources exclusively from Nagoya-area machinery builders and Ruhr Valley engineering houses. Single-source vulnerability in high-speed retort line manufacturing creates capex bottlenecks for capacity expansion. Distribution runs through broadline foodservice distributors consolidating fragmented restaurant demand, with club store direct procurement bypassing traditional wholesale tiers in hurricane-prone coastal markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
USDA FSIS inspection mandates are filtering out marginal operators, concentrating compliant processing capacity among established players and presenting a consolidation play for participants with regulatory affairs infrastructure and captive poultry supply.
For Market Incumbents: Extend backward integration into grain-to-gate poultry operations to secure raw material throughput against feed price volatility and displacement by Asian exporters struggling with FDA preventive controls compliance. Add continuous rotary retort capacity in the US Southeast to capture institutional procurement volume from exiting smaller importers. Channel control through exclusive club store partnerships represents the critical defensive lever against private-label erosion. For New Entrants and Emerging Players: Subscription-based preparedness channels offer the most penetrable white space, with direct-to-consumer emergency food kits representing underdeveloped demand beyond traditional retail procurement. Retort pouch format innovation targeting younger demographics resistant to conventional can aesthetics unlocks differentiated positioning. A co-manufacturing arrangement with established Southeast poultry processors provides the lowest-capital go-to-market angle for volume scale without greenfield retort investment. For Investors and Strategic Acquirers: The window for entry favors mid-scale regional processors with USDA-compliant infrastructure and underutilized canning capacity available for acquisition. Long-term viability hinges on positioning for sodium-reduction guidance and sustainable packaging mandate compliance across the projection horizon. Watch for FDA enforcement actions against Asian importers as the inflection signal for domestic volume capture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Retort Equipment Automation | Continuous rotary systems with PLC-based controls compress cycle times and tighten pathogen thresholds for compliant processors. |
| Captive Poultry Integration | Grain-to-gate supply chains secure raw material throughput against feed volatility and import displacement pressures. |
| Subscription Channel Development | Direct-to-consumer preparedness kits extend reach into bulk-buying demographics resistant to conventional retail visits. |
| Sustainable Packaging Transition | Fiber-based can end innovation positions first-movers for EU Green Deal compliance and domestic retailer sustainability mandates. |
| Retort Pouch Format Expansion | Flexible microwaveable formats capture younger demographics and foodservice operators prioritizing back-of-house space efficiency. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving poultry plant operations managers, USDA FSIS compliance officers, club store category buyers, broadline foodservice distributor procurement leads, and retort equipment engineering specialists. Bottom-up volume modeling from processor capacity utilization and top-down demand triangulation from household pantry-stocking surveys and institutional procurement databases ensured convergence across independent estimation streams.
Data-stream reconciliation across production volume, trade flows, and channel shipment patterns shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product texture format, packaging convenience tier, sales channel structure, and end-user application maturity. CAGRs were derived from trend extrapolation validated against historical elasticity patterns and structural demand drivers, with retort processing automation adoption curves and emergency preparedness procurement cycles serving as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including potential tariff restructuring on imported aluminum can sheet, abrupt shifts in federal disaster-relief stockpiling budgets, and breakthrough alternative protein preservation technologies. Forecasts reflect documented assumptions about regulatory enforcement continuity and feed grain price stability. A small set of named triggers warrants ongoing watch: FDA foreign supplier verification program enforcement intensity, EU packaging mandate adoption timelines, and Gulf Coast hurricane season severity patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Pork Meat Market
Meat Products
Beef Extract Market
Meat Products
Low Fat Beef Market
Meat Products
US Meat Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Organic Chicken Market
Meat Products
United States Frozen Meat Market
Meat Products
Europe Animal Protein Market
Meat Products
Pork Flavors Market
Meat Products
Germany Meat Products Market
Meat Products
Canned Pork Market
Meat Products
Europe Edible Meat Market
Meat Products
Europe Poultry Meat Market
Meat Products
Low-Fat Chorizo Market
Meat Products
GCC Edible Meat Market