
 Europe Meat Products Market | 2026-2036
Europe Meat Products Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Meat Products Market Analytics
The capital-intensity divergence between integrated processors and regional packers is redrawing competitive boundaries across the European meat sector. Danish Crown AmbA leverages its cooperative ownership model to sustain stable livestock sourcing across Denmark and Germany. WH Group Ltd anchors its European position through controlled distribution networks that dominate chilled pork flows into Central European retail. Cranswick PLC differentiates via specialized premium bacon and gammon manufacturing that commands shelf space in UK supermarkets.
Europe meat products encompass muscle tissue and edible offal from cattle, swine, poultry, and ovine species, processed through slaughtering, chilling, curing, smoking, or grinding to achieve shelf stability, flavor development, or portion control for human consumption. Poultry leads volume across the continent due to cost efficiency and shorter production cycles, while cured and smoked processing methods capture concentrated margin pools in premium retail and food service channels. Modified atmosphere packaging is displacing conventional tray formats in supermarket fresh meat cases, extending color stability and reducing retail shrinkage.
The European Food Safety Authority (EFSA) sets microbiological criteria and residue limits that determine product approval for intra-EU trade, while REACH and the EU Green Deal impose escalating carbon accounting obligations on slaughterhouse operations. National regulators in Germany, France, and Spain enforce cold-chain traceability mandates that raise compliance costs for smaller processors. Stakeholders must monitor how the EU's deforestation regulation reshapes feed sourcing and supplier qualification requirements for imported livestock inputs.
Market Dynamics
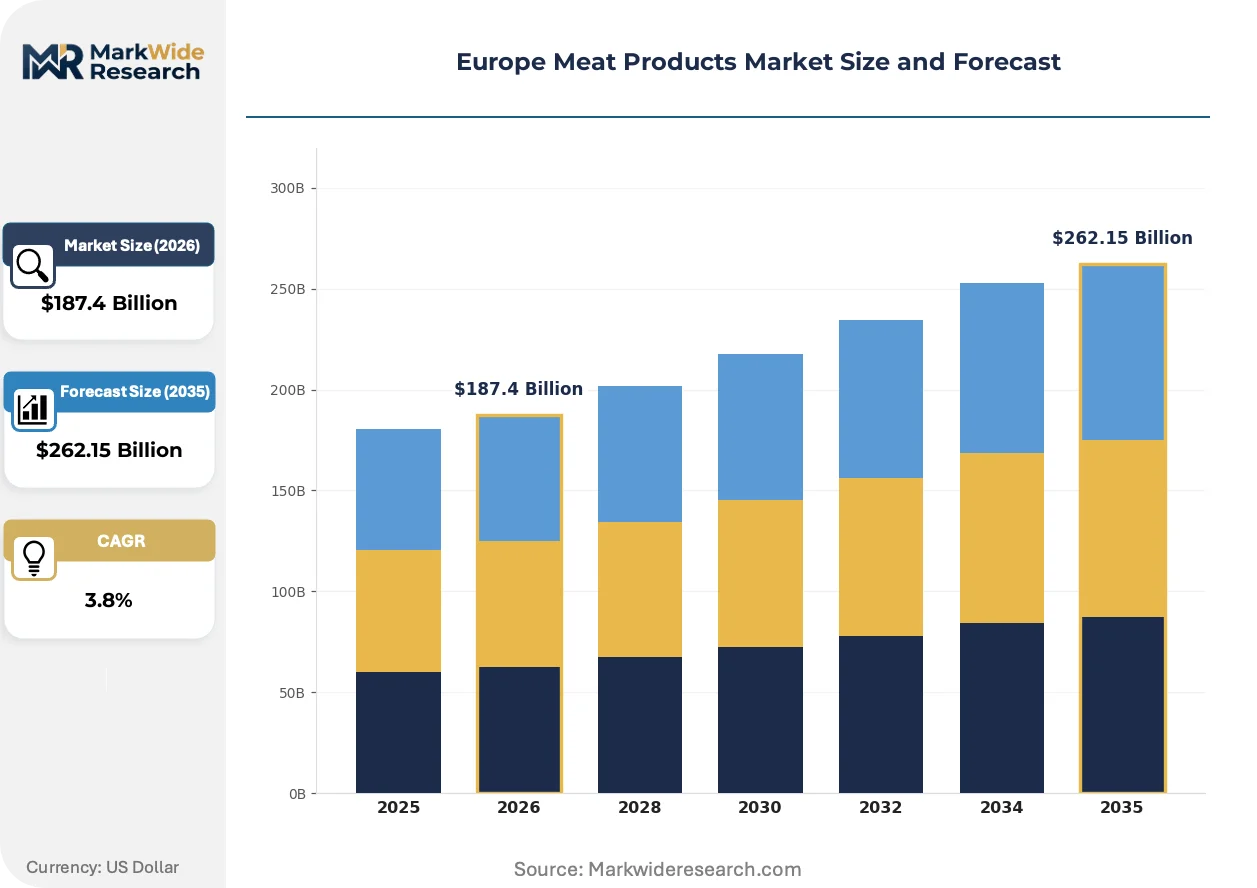
The EU Green Deal and Farm to Fork Strategy are compressing carbon accounting timelines for livestock processors while cold-chain infrastructure investments concentrate distribution power in Western European urban corridors. These forces are redrawing competitive boundaries between integrated cooperatives and regional packers.
Growth Catalysts
- REACH carbon reporting mandates:Slaughterhouse operators investing in emissions monitoring systems gain preferential access to retailer procurement programs across Germany and France.
- Urban retail corridor density:Supermarket chains in London, Paris, and Berlin are expanding fresh meat case footage, pulling volume through controlled distribution networks.
- Modified atmosphere packaging:This barrier technology extends color stability in chilled pork and beef, reducing retail shrinkage and enabling longer distribution radii from regional processing hubs.
Market Restraints
- Feed input cost volatility:Soybean and grain price swings compress processor margins, particularly for poultry operations with shorter production cycles and limited pricing power.
- EFSA microbiological criteria:Stringent residue limits and pathogen thresholds create compliance barriers for smaller slaughterhouses seeking intra-EU trade certification.
- Plant-based protein substitution:Pea and mycoprotein alternatives are capturing shelf space in UK and Dutch supermarkets, eroding volume growth in conventional processed meat categories.
Strategic Opportunities
- Spanish and Portuguese retail modernization:Cold-chain infrastructure gaps in Iberian Peninsula urban centers present first-mover advantages for processors with integrated logistics capabilities.
- CSRD supply chain disclosure:The Corporate Sustainability Reporting Directive creates demand for verified carbon accounting services and low-emission livestock sourcing credentials.
- Precision fermentation convergence:Cultured fat and heme technologies are approaching cost parity, opening hybrid product development partnerships for traditional meat processors.
Industry Challenges
- Veterinary pharmaceutical residue detection:EFSA's tightening antibiotic monitoring protocols require capital-intensive laboratory upgrades and extended holding periods for slaughter-ready livestock.
- Multi-tier cold-chain traceability:National regulators in Germany, France, and Spain impose incompatible data formats, forcing processors to maintain parallel compliance systems for cross-border shipments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Meat Products Market |
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $262.15 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Poultry, Lamb Processing Method: Fresh, Frozen, Cured, Smoked Distribution Channel: Supermarkets, Online Retail, Butcher Shops, Food Service Packaging Type: Vacuum Pack, Canned, Tray Pack, Modified Atmosphere |
| Companies Covered | WH Group Ltd, The Bigard Group, Danish Crown AmbA, Cherkizovo Group, Cranswick PLC, Vion Food Group, JBS S.A., Plukon Food Group, Premium Food Group ApS & Co. KG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Meat Products Market Evolving Landscape
Carbon accounting automation and packaging barrier technologies are compressing operational timelines while regulatory disclosure mandates reshape supplier qualification protocols across European livestock supply chains.
Modified atmosphere packaging with high-barrier coextruded films is supplanting conventional polyethylene tray formats in supermarket fresh meat cases. Retailers in the Netherlands and Denmark are mandating these systems for private-label chilled pork and beef programs. The shift is enabling centralized portion-cutting operations to serve wider geographic radii without color degradation penalties.
The EU Deforestation Regulation is requiring geolocation verification for all cattle, swine, and poultry feed inputs linked to imported soy and palm derivatives. Processors must map supplier farms to GPS coordinates and maintain chain-of-custody documentation for EFSA audit trails. German and French retail consortiums are imposing earlier compliance deadlines than the statutory minimum, squeezing smaller importers.
Centralized procurement by food service groups is consolidating supplier rosters and compressing contract renewal cycles. Contract caterers operating across Belgium, Luxembourg, and the Netherlands are shifting from annual to quarterly price negotiations with approved processor lists. This pattern concentrates volume with integrated cooperatives capable of guaranteeing origin-verified supply across multiple protein species.
Europe Meat Products Market Segmentation
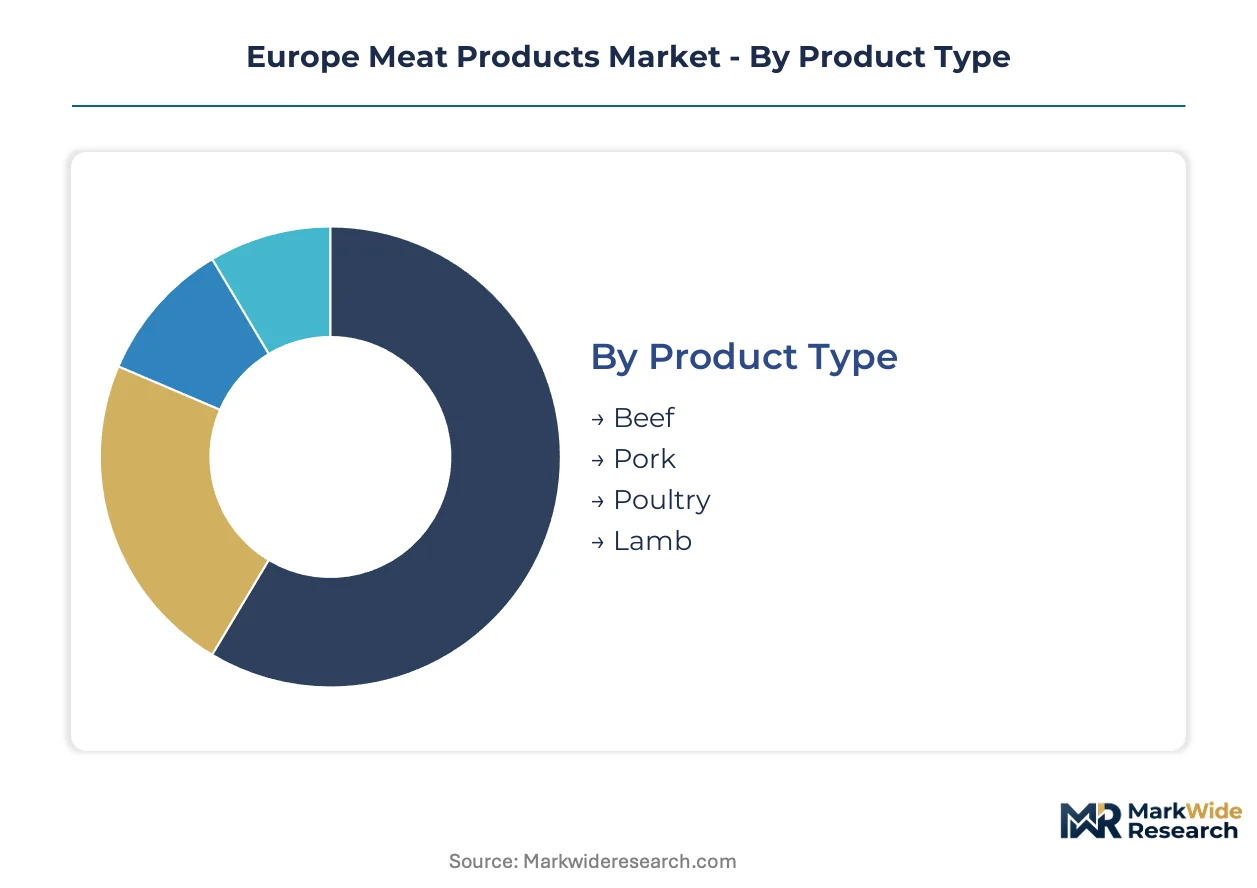
Segmentation across protein species, processing methods, and distribution channels reveals where capital is concentrating and where margin compression threatens incumbent positions. Understanding these fault lines enables targeted capacity allocation and partnership prioritization.
Product Type:
Margin pools concentrate in species with extended value-add chains and premium positioning in German and French retail corridors.
- Poultry:Short production cycles and feed conversion efficiency dominate volume flows across the continent. Demand concentrates in quick-service restaurant supply chains and pre-marinated retail formats where portion control drives labor savings for food service operators.
- Pork:Integrated cooperatives control breeding-to-slaughter throughput, enabling consistent chilled distribution into supermarket private-label programs. Cured and processed applications capture concentrated margin pools in premium retail channels.
- Beef:Grass-fed and grain-finished differentiation commands price premiums in UK and Italian specialty retail, though EFSA residue monitoring raises compliance costs for smaller processors.
- Lamb:Seasonal demand peaks in Mediterranean markets, with Spanish and Greek processors dominating Easter and Ramadan procurement cycles through established export networks.
Pork holds installed capacity across Danish and German processing hubs. Poultry is rotating up the share rankings through cost efficiency and shorter inventory cycles.
Processing Method:
Volume flows diverge sharply between chilled fresh formats requiring cold-chain integrity and shelf-stable methods enabling longer distribution radii.
- Fresh:Slaughter-to-retail timelines under 72 hours dominate supermarket meat cases in Paris, London, and Berlin. Modified atmosphere packaging investments by Dutch retailers are extending color stability windows and reducing shrinkage penalties.
- Cured:Dry-cured ham and bacon applications concentrate margin in premium tiers, with Italian and Spanish processors commanding protected designation of origin premiums. EFSA microbiological criteria for Listeria monocytogenes create compliance barriers for new entrants.
- Frozen:Bulk industrial procurement and export-oriented processing favor centralized cutting operations in Poland and Hungary serving Middle Eastern and Asian markets.
- Smoked:Traditional wood-smoking methods retain niche positioning in German and Polish specialty retail, though liquid smoke alternatives are displacing artisanal capacity in cost-sensitive channels.
Fresh holds installed capacity in Western European urban corridors. Cured is rotating up the share rankings through premium positioning and extended shelf life economics.
Distribution Channel:
Channel power is consolidating around retailers with private-label development capabilities and food service operators with centralized procurement mandates.
- Supermarkets:Controlled distribution networks dominate chilled pork and beef flows, with German and French retail consortiums imposing origin-verification requirements ahead of statutory deadlines. Fresh meat case expansion in urban corridors is pulling volume through centralized portion-cutting operations.
- Food Service:Contract caterers across Belgium, Luxembourg, and the Netherlands are compressing supplier rosters and shifting to quarterly price negotiations, concentrating volume with integrated cooperatives capable of multi-species guarantees.
- Butcher Shops:Independent retail maintains footholds in Mediterranean markets where traditional cutting skills and local sourcing credentials command customer loyalty, though cold-chain investments favor consolidated competitors.
- Online Retail:Direct-to-consumer platforms are capturing trial in UK and Dutch urban centers, though last-mile chilled logistics costs constrain margin expansion beyond premium tier positioning.
Supermarkets hold installed capacity through private-label program control. Food Service is rotating up the share rankings through procurement consolidation and specification tightening.
Packaging Type:
Barrier technology investments are redrawing competitive boundaries between processors with coextrusion capabilities and those dependent on conventional formats.
- Modified Atmosphere:High-barrier coextruded films with oxygen scavenging layers are supplanting polyethylene trays in Dutch and Danish supermarket programs. Centralized cutting operations now serve wider geographic radii without color degradation penalties.
- Vacuum Pack:Extended shelf life applications dominate export-oriented pork and beef flows, with German processors leading equipment investment for bone-in and boneless formats.
- Tray Pack:Conventional overwrapped formats retain cost-sensitive positioning in discount retail channels, though shrinkage rates pressure adoption of barrier alternatives.
- Canned:Shelf-stable processed meats maintain volume in emergency procurement and institutional feeding programs, with Spanish and Portuguese processors dominating corned beef and luncheon meat exports.
Modified Atmosphere holds installed capacity through retailer mandate acceleration. Vacuum Pack is rotating up the share rankings in export-oriented processing hubs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German consumers favor chilled fresh pork and beef cuts requiring 72-hour slaughter-to-retail timelines, while Mediterranean markets concentrate demand in cured and seasonal lamb formats with extended shelf stability requirements.
Germany
Supermarket private-label programs dominate chilled pork procurement through centralized portion-cutting operations in North Rhine-Westphalia. The German Cold Chain Regulation mandates multi-tier traceability data formats that force processors to maintain parallel compliance systems for cross-border shipments. Bavarian processing clusters around Munich anchor premium beef distribution into French and Italian retail corridors.
France
Food service operators in Paris and Lyon are expanding premium protein procurement while contract caterers compress supplier rosters to quarterly renewal cycles. ANSM enforces veterinary pharmaceutical residue protocols that require capital-intensive laboratory upgrades for slaughter-ready livestock holding. The Île-de-France corridor concentrates modified atmosphere packaging adoption for fresh meat case expansion in urban retail.
United Kingdom
UK supermarkets are mandating origin-verification requirements ahead of EU statutory deadlines for deforestation-free feed sourcing. The Food Standards Agency enforces EFSA-aligned microbiological criteria that create compliance barriers for smaller slaughterhouses seeking intra-EU trade certification. East Anglian processing hubs specialize in premium bacon and gammon manufacturing commanding dedicated shelf space.
Spain
Iberian Peninsula urban centers present cold-chain infrastructure gaps that favor first-mover processors with integrated logistics capabilities. The EU Deforestation Regulation requires geolocation verification for all feed inputs linked to imported soy derivatives, with Spanish retail consortiums imposing earlier compliance deadlines. Catalonian dry-cured ham processors command protected designation of origin premiums in specialty retail channels.
Netherlands
Dutch retailers are mandating high-barrier coextruded film systems for private-label chilled pork programs, extending color stability windows beyond conventional polyethylene formats. REACH carbon reporting mandates give preferential procurement access to slaughterhouse operators investing in emissions monitoring systems. Randstad logistics clusters enable centralized cutting operations to serve wider geographic radii without degradation penalties.
Europe Meat Products Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with cooperative ownership structures and controlled distribution networks defining the upper tier. The market structure reflects capital-intensity divergence between full-integration processors and regional packers dependent on third-party livestock sourcing. Two strategic archetypes dominate: cooperative-owned entities leveraging stable member supply bases, and publicly listed processors commanding retail private-label relationships. Competitive moves concentrate on cold-chain infrastructure investments and carbon accounting automation to meet CSRD disclosure requirements.
Within the cooperative tier, Danish Crown AmbA occupies a position exemplifying stable livestock sourcing across member farms, while WH Group Ltd anchors a distribution-controlled archetype through chilled pork flows into Central European retail. Cranswick PLC represents the premium manufacturing specialist segment, with its UK-listed structure enabling focused positioning in bacon and gammon categories.
| Leading Market Players |
|---|
| WH Group Ltd |
| The Bigard Group |
| Danish Crown AmbA |
| Cherkizovo Group |
| Cranswick PLC |
| Vion Food Group |
| JBS S.A. |
| Plukon Food Group |
| Premium Food Group ApS & Co. KG |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German retail consortiums and Danish-German cooperative processors lock in livestock supply visibility while insulating contract holders from spot feed grain volatility that compresses regional packer margins. These bilateral arrangements concentrate procurement power among integrated operators capable of guaranteeing origin-verified chilled pork across multi-year horizons.
Pricing Analysis
Contract-based long-term offtake structures dominate chilled pork and beef procurement between German supermarket chains and integrated cooperatives. Price differentiation rests on certification grade under EU organic and protected designation of origin schemes alongside volume scale commitments. Cost compression in standard-tier poultry runs through feed input volatility and shorter production cycle pricing power constraints. Discount retail channels exhibit highest price sensitivity, while premium cured and dry-aged segments maintain inelastic demand through specialty retail positioning.
Supply Chain Analysis
Livestock transit through Rotterdam and Hamburg cold-chain hubs underwrites chilled distribution integrity for Western European retail corridors. Geographic supply concentration centers on Denmark, Germany, and the Netherlands for pork processing, with Spain and Poland anchoring cured and export-oriented capacity. Raw material dependencies rest on imported soy and grain feedstocks subject to EU Deforestation Regulation geolocation mandates. Single-source vulnerability concentrates in specialized breeding stock and veterinary pharmaceutical inputs. Distribution runs through controlled retail networks and consolidated food service procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
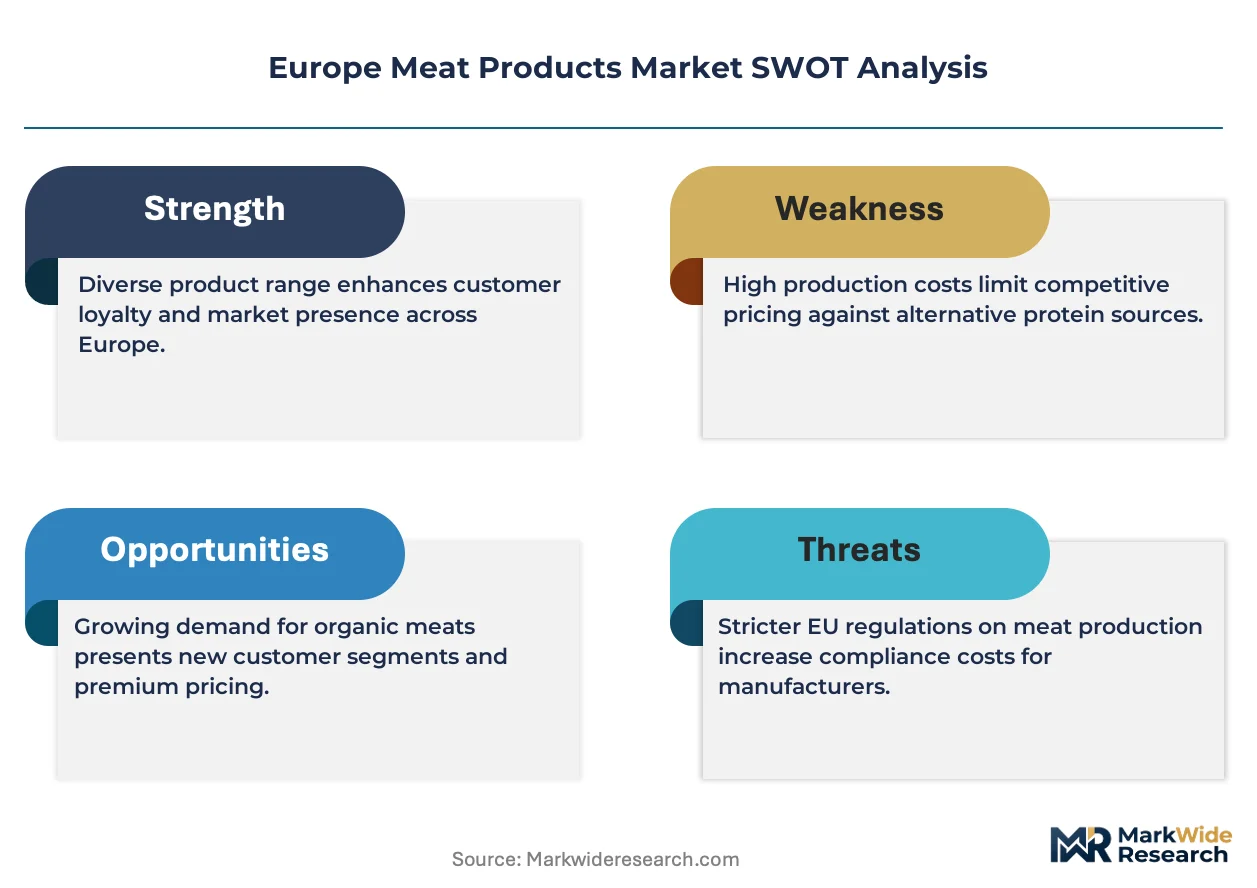
The Europe meat products market constitutes a defensive-moat structure where regulatory entrenchment through EFSA compliance protocols and CSRD carbon disclosure requirements erects capital barriers that protect incumbent positions against agile challengers.
For Market Incumbents: Compound cold-chain infrastructure advantages through centralized portion-cutting investments in Iberian Peninsula urban corridors where logistics gaps persist. Deepen backward integration into low-emission livestock sourcing to preempt CSRD supply chain disclosure requirements. Plant-based protein substitution in UK and Dutch retail channels demands accelerated hybrid product development partnerships with precision fermentation specialists. For New Entrants and Emerging Players: Differentiate on carbon-negative livestock sourcing credentials targeting Dutch and Danish retailer sustainability procurement programs with earlier compliance deadlines than statutory minimums. Spanish and Portuguese cold-chain infrastructure gaps represent the most penetrable geography for integrated logistics capabilities. A direct-to-consumer premium tier launch in UK urban centers bypasses consolidated supermarket gatekeeper control. For Investors and Strategic Acquirers: Mid-scale cured meat specialists with protected designation of origin holdings in Italy and Spain offer acquisition exposure to premium margin pools insulated from commodity price cycles. Long-term viability frames around regulatory compliance automation capabilities and deforestation-free feed traceability infrastructure. Monitor EFSA antibiotic monitoring protocol tightening as an inflection signal for laboratory upgrade investment cycles across smaller processor tiers.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Chain Infrastructure Expansion | Iberian Peninsula urban corridor investments capture first-mover advantage in undersupplied Spanish and Portuguese retail markets. |
| Carbon Accounting Automation | CSRD disclosure compliance secures preferential procurement access from German and French retail consortiums ahead of deadlines. |
| Modified Atmosphere Packaging Scale-Up | High-barrier coextruded film adoption extends distribution radii from centralized cutting operations without color degradation penalties. |
| Deforestation-Free Feed Sourcing | EU Deforestation Regulation geolocation verification maintains market access against tightening Spanish retail consortium requirements. |
| Hybrid Product Development Partnership | Precision fermentation convergence with cultured fat technologies defends shelf space against plant-based protein substitution in UK supermarkets. |
Research Methodology
Operator-level perspectives from livestock procurement directors, cold-chain logistics managers, supermarket category buyers, and EFSA compliance officers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews across these stakeholder roles with secondary validation from EU trade statistics, EFSA microbiological criteria documentation, REACH carbon reporting filings, and retail consortium procurement disclosures. Bottom-up capacity modeling across protein species and processing methods triangulated against top-down trade flow analysis.
Sensitivity analysis tested forecast outputs against feed grain price volatility scenarios and regulatory compliance timeline acceleration assumptions across the projection horizon. Segmentation dimensions modeled include protein species, processing method, distribution channel, packaging technology, and national regulatory cluster. CAGRs derived from installed capacity utilization trends and cold-chain infrastructure investment pipelines. Industry-specific forecast inputs incorporated EU Green Deal carbon intensity trajectories and Farm to Fork Strategy livestock reduction targets.
The analysis sits within stated boundaries; outcomes outside sustained cold-chain investment levels or accelerated EFSA protocol tightening would require recalibration. Forecasts reflect documented assumptions around feed input cost stabilization and deforestation regulation enforcement intensity. Practitioners should keep alternative scenarios live as plant-based substitution rates and precision fermentation cost parity timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Organic Beef Meat Market
Meat Products
Organic Chicken Market
Meat Products
North America Canned Meat Market
Meat Products
North America Red Meat Market
Meat Products
Grass-Fed Meat Market
Meat Products
Sausage Premixes Market
Meat Products
Asia-Pacific Low Fat Sausage Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Lab-Grown Meat Market
Meat Products
Middle East Edible Meat Market
Meat Products
Meat Emulsions Market
Meat Products
Canned Beef Market
Meat Products
Animal Protein Market
Meat Products
Antibiotic Free Meat Market
Meat Products
US Meat Market