
 Beef Fat Market | 2026-2036
Beef Fat Market Size, Share, and Industry Trends Forecast 2026-2036
Beef Fat Market Analysis
Advanced rendering technologies with continuous centrifugal separation and enzymatic pre-treatment is narrowing the quality gap between commodity tallow and premium oleochemical feedstocks. Cargill Incorporated leverages its North American protein processing footprint to sustain captive tallow supplies for both food and industrial customers. JBS SA anchors its South American operations through integrated slaughter-to-render facilities that dominate regional volume flows. Tyson Foods Inc competes on manufacturing scale, operating multi-species renderers that optimize thermal energy recovery across beef, pork, and poultry fat streams.
Beef fat comprises adipose tissue harvested from cattle carcasses, containing triglycerides with variable fatty acid profiles depending on breed, diet, and anatomical depot; rendering through wet or dry thermal processing yields purified tallow with specified titre points and free fatty acid thresholds for industrial acceptance. The application split reveals a structural divergence where culinary and animal feed segments remain mature volume pools with compressed margins, while cosmetics and select industrial oleochemical applications command premium positioning due to certification requirements and functional performance specifications. Packaging type segmentation shows bulk formats still control interprocessor trade, though vacuum-sealed and pouch formats are capturing share in direct-to-manufacturer cosmetic and specialty food channels where oxidation sensitivity drives specification.
USDA grading standards and FDA food safety regulations govern edible tallow classifications, while EPA biodiesel mandates under the Renewable Fuel Standard shape industrial demand volumes and qualification pathways. REACH registration requirements in Europe and ECHA bioaccumulation assessments are elevating documentation burdens for tallow-derived oleochemical exports, effectively filtering market access toward processors with dedicated regulatory affairs capabilities. Stakeholders must monitor how evolving EU deforestation-free supply chain regulations and emerging US state-level low-carbon fuel standards will redirect procurement patterns across rendering and end-use industries.
Market Dynamics
Continuous centrifugal separation technology is compressing the quality differential between commodity tallow and premium oleochemical feedstocks, forcing renderers to upgrade capital equipment or surrender margin in specification-sensitive segments.
Growth Catalysts
- EU Green Deal bioeconomy targets:Mandatory circular economy quotas are redirecting rendering investments toward higher-value lipid outputs, creating captive demand for saponifiable tallow derivatives in European oleochemical manufacturing.
- Cosmetics formulators:Clean-label mandates from L'Oréal, Unilever, and Estée Lauder procurement specifications are accelerating substitution of petrochemical emollients with tallow-derived alternatives certified for oxidation stability.
- Brazilian biodiesel blending mandates:ANP's escalating B13-to-B15 trajectory is concentrating tallow procurement within integrated JBS and Marfrig processing complexes that control both slaughter and rendering capacity.
Market Restraints
- Cattle cycle volatility:Brazilian herd liquidation during drought years and North American feed cost spikes transmit directly into tallow input cost instability, compressing renderer margins when protein values diverge from fat values.
- REACH registration burdens:ECHA's bioaccumulation assessment protocols and substance volume tracking requirements are filtering market access toward European processors with dedicated regulatory affairs infrastructure, excluding smaller export-oriented renderers.
- Palm oil and coconut oil substitution:Oleochemical buyers in surfactant and personal care applications maintain dual-qualified supply bases, capping tallow premium potential when tropical oil prices collapse below parity thresholds.
Strategic Opportunities
- US state-level low-carbon fuel standards:California LCFS and emerging Oregon, Washington, and New York programs assign carbon intensity scores that favor tallow-based renewable diesel over soybean oil, redirecting procurement toward domestic rendering capacity.
- Enzymatic interesterification:Convergence of lipase biocatalysis with continuous processing is enabling custom fatty acid profile tailoring for cosmetic and pharmaceutical applications previously requiring synthetic structuring agents.
- Vacuum-sealed cosmetic channel:Direct-to-manufacturer pouch formats are capturing share from bulk interprocessor trade as oxidation-sensitive buyers in Korean and Japanese skincare formulation bypass traditional distribution tiers.
Industry Challenges
- EU deforestation-free supply chain verification:EUDR geolocation and traceability documentation requirements are forcing renderers to reconstruct procurement records across fragmented cattle sourcing networks, extending compliance timelines by 18-24 months.
- Rendering engineer scarcity:Specialized expertise in thermal process optimization and centrifugal separation maintenance is concentrating among legacy equipment manufacturers, inflating recruitment costs for independent processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beef Fat Market |
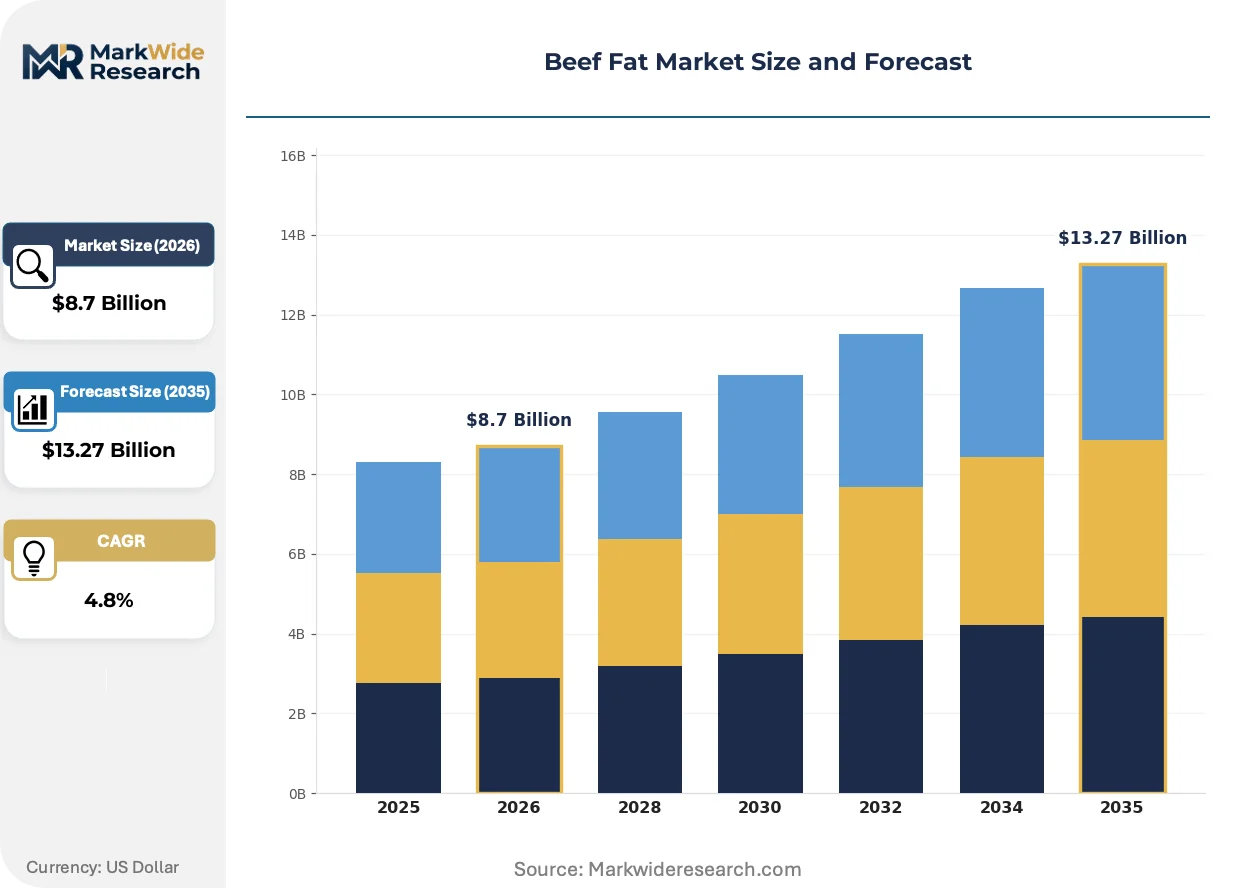
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.27 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Beef Fat, Rendered Beef Fat, Beef Tallow, Beef Lard Application: Culinary, Industrial, Animal Feed, Cosmetics Packaging Type: Bulk, Vacuum-Sealed, Cans, Pouches Distribution Channel: Wholesale, Retail, Online, Food Service |
| Companies Covered | Cargill Incorporated, JBS SA, Tyson Foods Inc, Hormel Foods Corporation, Darling Ingredients Inc., Jacob Stern & Sons Inc., Windsor Quality Meats Pty Ltd, Tassie Tallow, Piermen BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beef Fat Market Emerging Trajectories
Enzymatic pre-treatment systems and advanced oxidation control packaging are redefining quality benchmarks across food, cosmetic, and industrial applications, compressing the traditional tiering between commodity and specialty tallow grades.
Membrane filtration and enzymatic degumming systems are rendering obsolete the acid refining and bleaching sequences that historically degraded heat-sensitive lipid fractions. Premium cosmetic formulators in France and Switzerland are adopting these systems at 15-20% annual capacity expansion rates, enabling direct tallow integration into high-value emollient formulations without downstream derivative processing.
EPA's Renewable Fuel Standard pathway qualification requirements are tightening documentation standards for biomass-based diesel feedstocks, forcing renderers to implement chain-of-custody systems from slaughterhouse to fuel terminal. Industrial tallow buyers in US biodiesel manufacturing are responding by consolidating procurement around vertically integrated protein processors with captive rendering assets, squeezing independent toll renderers from qualification pools.
Specification-driven purchasing is displacing spot-market procurement in European and North American cosmetic channels, as formulators seek multi-year supply security for RSPO- and EUDR-compliant tallow derivatives. Direct manufacturer relationships are replacing distributor intermediation in German and Dutch personal care clusters, compressing working capital cycles for qualified renderers while excluding speculative traders from premium segment participation.
Beef Fat Market Segmentation
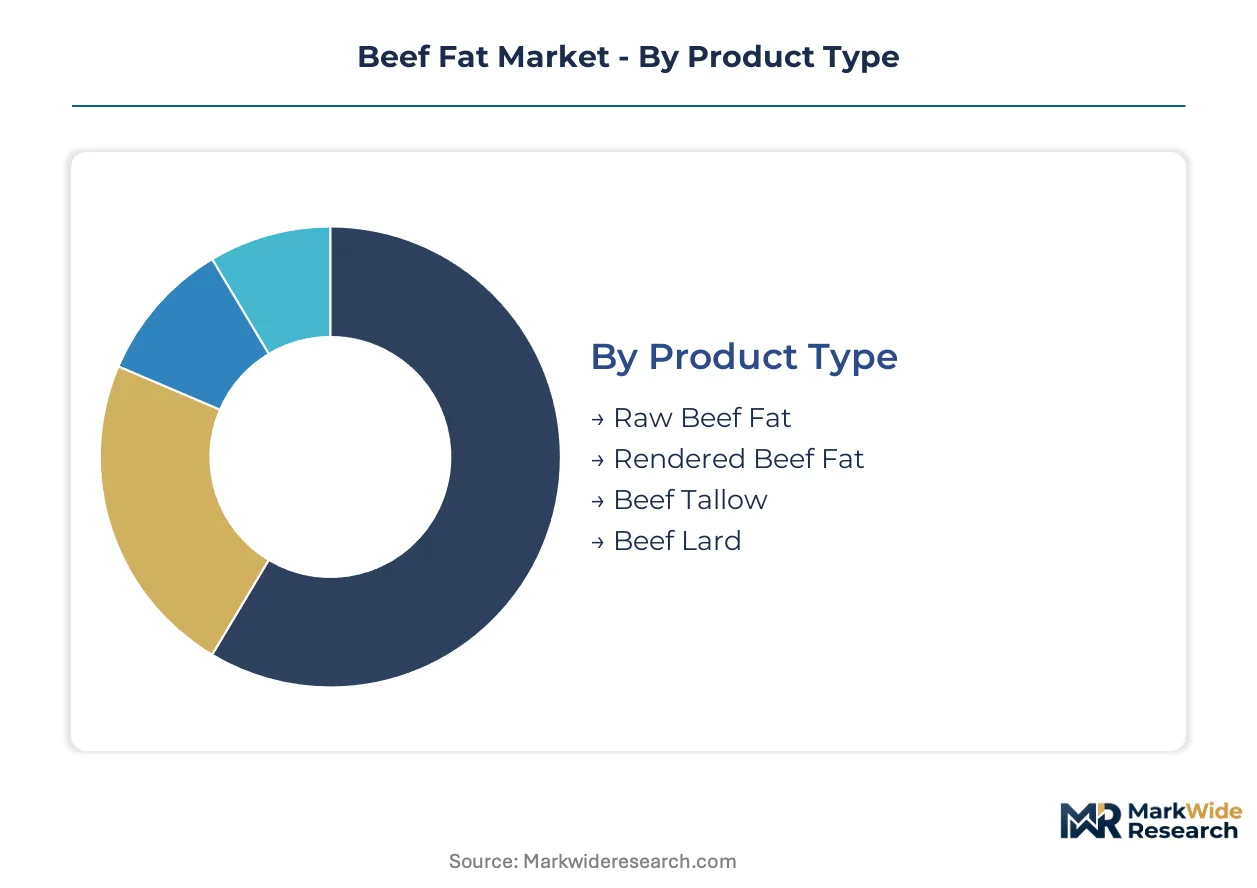
Beef fat segmentation reveals divergent margin structures across purification grades and end-use specifications. Renderers must calibrate capital allocation between commoditized volume pools and certification-intensive premium channels where documentation burdens filter competitive participation.
Product Type:
Mature thermal processing grades dominate current throughput, while enzymatically upgraded feedstocks represent the emerging value frontier for specification-sensitive buyers.
- Raw Beef Fat:Unprocessed adipose tissue harvested from anatomical depots with variable fatty acid saturation profiles. Demand concentrates in integrated Brazilian processing complexes where JBS and Marfrig operations supply captive rendering capacity for biodiesel qualification under ANP mandates.
- Rendered Beef Fat:Thermally purified lipid fractions produced through wet or dry rendering with controlled free fatty acid thresholds. French and Swiss cosmetic formulators are expanding membrane filtration capacity at 15-20% annual rates to enable direct integration into high-value emollient formulations.
- Beef Tallow:Refined product meeting USDA edible or inedible specifications with defined titre points for industrial acceptance.
- Beef Lard:Specialized depot-specific rendering output with distinct crystallization properties for bakery and confectionery applications.
Rendered beef fat handles the majority of throughput; raw beef fat is expanding most quickly as integrated processors capture upstream supply for vertical qualification.
Application:
Volume concentration tilts toward established consumption patterns, while regulatory carbon intensity scoring redirects procurement toward specific industrial pathways.
- Culinary:Traditional food service and consumer cooking applications governed by FDA food safety classifications. EPA Renewable Fuel Standard documentation requirements are tightening chain-of-custody standards, consolidating procurement around vertically integrated protein processors.
- Industrial:Biodiesel, renewable diesel, and oleochemical manufacturing feedstocks. California LCFS and emerging Oregon, Washington, and New York low-carbon fuel programs assign favorable carbon intensity scores to tallow-based renewable diesel over soybean oil alternatives.
- Animal Feed:Energy-dense ration components for livestock nutrition programs.
- Cosmetics:Saponifiable lipid sources for emollient and surfactant formulations.
Culinary maintains the largest volume position; industrial is climbing the fastest on low-carbon fuel standard incentives.
Packaging Type:
Supply chain configuration separates oxidation-tolerant bulk logistics from precision-engineered barrier formats for direct manufacturer channels.
- Bulk:Tanker and tote formats controlling interprocessor trade with standard nitrogen blanketing. Korean and Japanese skincare formulators are bypassing traditional distribution tiers through direct procurement relationships with qualified renderers.
- Vacuum-Sealed:Oxygen-excluded barrier packaging for oxidation-sensitive cosmetic and specialty food segments. EUDR geolocation documentation requirements are extending compliance timelines by 18-24 months for renderers reconstructing fragmented cattle sourcing records.
- Cans:Traditional retail and food service formats with established shelf stability protocols.
- Pouches:Flexible direct-to-manufacturer formats capturing share in cosmetic channels.
Bulk logistics handles the majority of throughput; vacuum-sealed formats are gaining share fastest on oxidation sensitivity specifications.
Distribution Channel:
Customer type stratification separates volume-driven wholesale procurement from relationship-intensive direct manufacturing partnerships.
- Wholesale:Interprocessor and distributor-mediated bulk transactions. REACH registration and ECHA bioaccumulation assessment protocols are filtering European market access toward processors with dedicated regulatory affairs infrastructure.
- Retail:Consumer-facing packaged goods through traditional grocery and specialty channels.
- Online:Direct-to-manufacturer and e-commerce platforms for specialty and cosmetic-grade products.
- Food Service:Institutional and restaurant supply chains with specification contracting.
Wholesale channels handle the majority of throughput; online direct-to-manufacturer sales are expanding most quickly on procurement consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from integrated South American processors increasingly service European oleochemical demand, while US domestic procurement consolidates around vertically integrated protein processors with captive rendering assets. Import dependence in East Asian cosmetic manufacturing clusters is redirecting procurement relationships toward direct renderer partnerships.
United States
California LCFS and emerging Oregon, Washington, and New York low-carbon fuel programs assign favorable carbon intensity scores to tallow-based renewable diesel. EPA Renewable Fuel Standard documentation requirements are tightening chain-of-custody standards. Chicago and Omaha processing clusters are consolidating procurement around vertically integrated protein processors with captive rendering capacity.
Brazil
ANP biodiesel blending mandates escalating from B13 toward B15 are concentrating tallow procurement within integrated slaughter-to-render facilities. Drought-driven cattle cycle volatility transmits directly into input cost instability. São Paulo and Mato Grosso processing complexes dominate regional volume flows for both domestic biodiesel and export oleochemical markets.
Germany
REACH registration requirements and ECHA bioaccumulation assessment protocols are filtering market access toward processors with dedicated regulatory affairs infrastructure. EU Green Deal bioeconomy targets redirect rendering investments toward higher-value lipid outputs. Cologne and Hamburg oleochemical manufacturing clusters are expanding membrane filtration capacity for direct tallow integration.
Japan
Cosmetic formulators in Osaka and Tokyo skincare manufacturing clusters are bypassing traditional distribution tiers through direct procurement relationships with qualified renderers. Oxidation-sensitive buyers are driving specification-driven purchasing for vacuum-sealed pouch formats. METI clean-label procurement guidelines are accelerating substitution of petrochemical emollients.
South Korea
Seoul-based skincare formulators are capturing share through direct-to-manufacturer relationships that compress working capital cycles for qualified renderers. Import dependence on tallow derivatives for emollient formulations is redirecting procurement toward Australian and New Zealand renderers with EUDR-compliant documentation. Busan logistics hubs are consolidating vacuum-sealed cosmetic-grade shipments.
Beef Fat Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated protein processors with captive rendering assets and independent toll renderers facing qualification squeeze. Strategic archetypes include integrated slaughter-to-render operators controlling upstream supply, multi-species renderers optimizing thermal energy recovery across protein streams, and specialty processors deploying enzymatic upgrading for cosmetic-grade outputs. Dominant competitive moves encompass backward integration into slaughter capacity and geographic expansion toward low-carbon fuel standard markets.
Among North American integrated processors, Cargill Incorporated and Tyson Foods Inc exemplify the scale-driven archetype with multi-species rendering footprints. JBS SA anchors the South American integrated model through slaughter-to-render facilities. These three entities represent the tier capturing premium positioning through captive supply control and regulatory qualification infrastructure.
| Leading Market Players |
|---|
| Cargill Incorporated |
| JBS SA |
| Tyson Foods Inc |
| Hormel Foods Corporation |
| Darling Ingredients Inc. |
| Jacob Stern & Sons Inc. |
| Windsor Quality Meats Pty Ltd |
| Tassie Tallow |
| Piermen BV |
| Others |
Supply Flow & Price Mechanics
REACH registration burdens and ECHA bioaccumulation assessment protocols determine both the three-tier pricing structure across premium, standard, and economy levels and the geographic concentration of qualified rendering capacity. Regulatory chokepoints filter market access toward European processors with dedicated compliance infrastructure, compressing margins for excluded exporters while concentrating premium pricing power among qualified incumbents.
Pricing Analysis
Industrial OEM buyers anchor commodity tallow pricing through long-term offtake contracts with integrated protein processors. Price differentiation rests on certification grade—EUDR-compliant documentation commands substantial premia over standard edible grades—and volume scale from captive rendering assets. Cost compression in commodity tiers is intensifying because Brazilian drought-driven herd liquidation destabilizes input costs. Animal feed compounders exhibit highest price sensitivity; cosmetic formulators demonstrate lowest sensitivity due to clean-label substitution mandates from L'Oréal and Unilever procurement specifications.
Supply Chain Analysis
Tariff exposure between Brazil and European Union markets dominates supply chain risk calculations for tallow-derived oleochemical exports. Raw material flows draw from Brazilian integrated slaughter-to-render complexes, North American multi-species rendering clusters, and Australian specialty processors. Single-source vulnerability concentrates in JBS and Marfrig facilities controlling São Paulo and Mato Grosso volume flows. Distribution runs through bulk tanker logistics for interprocessor trade, with vacuum-sealed pouch formats penetrating direct-to-manufacturer cosmetic channels in Osaka and Seoul.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among vertically integrated protein processors with captive rendering assets, squeezing independent toll renderers from qualification pools and redirecting procurement relationships toward direct manufacturer partnerships.
For Market Incumbents: Build regulatory affairs moats through dedicated EUDR traceability infrastructure and REACH registration capabilities. Cargill Incorporated and Tyson Foods Inc exemplify defensive positioning through multi-species rendering footprints that optimize thermal energy recovery. Threat substitution from palm oil and coconut oil alternatives demands certification investment in oxidation stability protocols. Channel control through direct-to-manufacturer relationships in Korean and Japanese cosmetic clusters secures premium positioning. For New Entrants and Emerging Players: Southeast Asian cosmetic manufacturing clusters represent underpenetrated white-space for EUDR-compliant tallow derivatives. Vacuum-sealed pouch formats for oxidation-sensitive skincare formulators offer the most penetrable entry vector. Enzymatic pre-treatment technology licensing from European equipment manufacturers enables quality-grade bypass without legacy capital intensity. Go-to-market execution should target direct procurement relationships with Busan and Singapore logistics hubs consolidating cosmetic-grade shipments. For Investors and Strategic Acquirers: EU deforestation-free supply chain verification deadlines reshape the acquisition landscape toward renderers with reconstructed geolocation documentation. Long-term viability centers on processors with demonstrated regulatory qualification infrastructure across multiple jurisdictions. Acquisition target archetype: mid-cap Brazilian or Australian renderers with integrated slaughter relationships and EUDR-compliant traceability systems. Signal to watch: California LCFS credit price movements indicating renewable diesel feedstock demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Slaughter Capacity | JBS SA and Marfrig operations capture upstream tallow streams for ANP biodiesel qualification. |
| Enzymatic Upgrading Technology Deployment | French and Swiss cosmetic formulators expand membrane filtration capacity for direct emollient integration. |
| EUDR Traceability Infrastructure Investment | Geolocation documentation requirements extend compliance timelines, filtering competitive participation. |
| Direct-to-Manufacturer Channel Development | Korean and Japanese skincare clusters bypass traditional distribution tiers through renderer partnerships. |
| Low-Carbon Fuel Standard Market Expansion | California LCFS and emerging state programs assign favorable carbon intensity scores to tallow-based renewable diesel. |
Methodological Framework
Operator-level perspectives from rendering plant managers, procurement leads at biodiesel manufacturers, cosmetic formulator R&D directors, and regulatory affairs specialists anchored the qualitative base. Primary interviews combined with secondary validation from USDA grading standards documentation, EPA Renewable Fuel Standard pathway filings, ECHA bioaccumulation assessment protocols, and ANP biodiesel mandate records. Bottom-up volume modeling across product type, application, and packaging format segments triangulated against top-down macroeconomic indicators.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated regulatory implementation cases over the projection horizon. Segmentation dimensions modeled include purification grade tier, end-use industry vertical, packaging barrier specification, and regional regulatory cluster. CAGRs derived from historical trajectory analysis adjusted for policy inflection points. Industry-specific forecast inputs incorporated cattle cycle volatility patterns and low-carbon fuel standard credit price dynamics.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by commodity traders or technology-led disruption from enzymatic biocatalysis specialists would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
United States Processed Pork Meat Market
Meat Products
Meat, Poultry and Seafood Market
Meat Products
Bacon Market
Meat Products
Grass-Fed Meat Market
Meat Products
Europe Edible Meat Market
Meat Products
Bacon Flavors Market
Meat Products
Low-Fat Ham Market
Meat Products
Meat Emulsions Market
Meat Products
Europe Meat Products Market
Meat Products
Hams Market
Meat Products
Brisket Market
Meat Products
Grass Fed Beef Market
Meat Products
Canned Pork Market
Meat Products
GCC Red Meat Market
Meat Products
India Animal Protein Market
Meat Products
Asia-Pacific Low Fat Sausage Market