
 Beef Fat Powder Market | 2026-2036
Beef Fat Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Beef Fat Powder Market Analytics
Argentine and Brazilian integrated beef processors is restructuring rendering-to-powder capacity to capture higher margins downstream. JBS Ingredients leverages its captive cattle supply to anchor raw material security across South American operations. Kerry Group plc differentiates through application-specific fat powder formulations for savory and bakery segments. Cargill Incorporated competes on global distribution scale, extending its reach into Asian food manufacturing hubs.
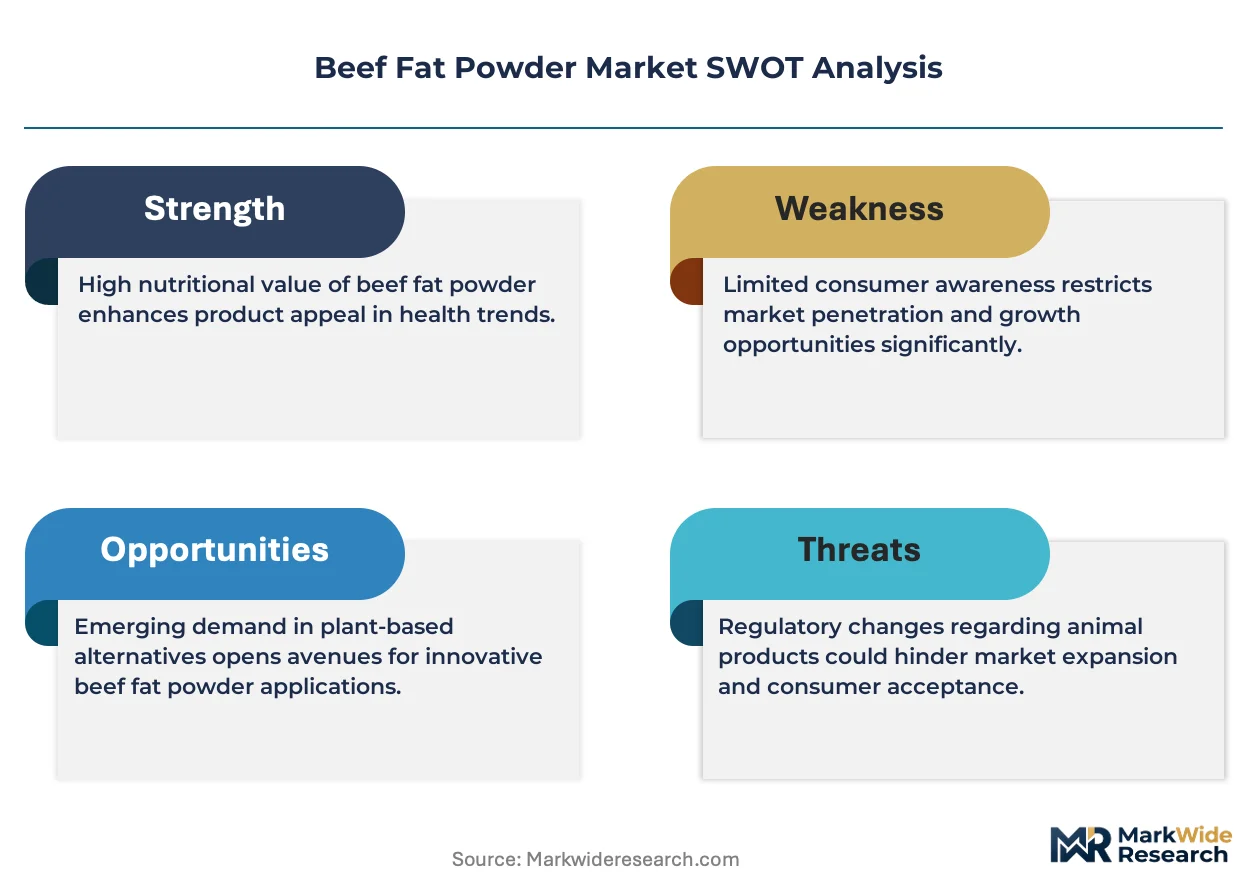
Beef fat powder consists of rendered, dried, and milled bovine adipose tissue, typically standardized to moisture content below 5% and free fatty acid thresholds for oxidative stability. The material functions primarily as a concentrated energy source, texture modifier, and flavor carrier in processed foods and animal nutrition. Non-hydrogenated variants lead volume due to clean-label alignment, while emulsified grades command margin premiums in bakery applications where fat-water integration determines product consistency. Pet food end use sustains the fastest expansion, driven by premiumization in companion animal diets requiring specified lipid profiles.
USDA grading standards and FDA food safety regulations govern raw material traceability and pathogen control in American beef fat powder production. REACH and EFSA frameworks in Europe restrict certain processing aids and mandate contaminant thresholds that shape import eligibility. BIS certification requirements in India create compliance barriers for foreign suppliers seeking direct market access. Stakeholders must monitor evolving render plant emissions rules across multiple jurisdictions, as carbon accounting increasingly influences processor site selection and capital allocation.
Market Dynamics
Renderers face mounting pressure from the EU F-Gas Regulation to retrofit thermal processing equipment, while Brazilian integrated processors expand captive rendering capacity to lock in downstream fat powder margins. This dual pressure—environmental compliance in Europe and vertical consolidation in South America—defines current competitive positioning.
Growth Catalysts
- Pet Food Premiumization:Companion animal nutrition manufacturers specify lipid profiles requiring rendered beef fat powder as a calorie-dense, palatability-enhancing ingredient. North American procurement of this input is accelerating.
- REACH-Driven Clean-Label Demand:European food manufacturers favor non-hydrogenated fat powder variants to align with contaminant thresholds and processing aid restrictions under ECHA frameworks.
- Brazilian Cluster Expansion:Integrated beef processing operations in São Paulo state and Mato Grosso are adding rendering-to-powder capacity to supply both domestic users and export markets.
Market Restraints
- Input Cost Volatility:Bovine adipose tissue supply fluctuates with cattle slaughter cycles and seasonal pasture conditions, compressing renderer margins during herd liquidation phases.
- Regulatory Friction:BIS certification requirements in India create compliance barriers that limit direct market access for foreign beef fat powder suppliers.
- Substitution Threat:Poultry fat and palm oil derivatives compete in pet food and bakery applications where cost sensitivity outweighs species-specific lipid requirements.
Strategic Opportunities
- Emulsified Grade Expansion:Bakery applications demanding superior fat-water integration present margin premiums for processors investing in specialized milling and stabilization technology.
- Decarbonization Incentives:EU Green Deal funding streams and national carbon accounting frameworks reward renderers adopting lower-emission thermal processing equipment.
- Asian Food Manufacturing Hubs:Underpenetrated demand in Vietnam and Indonesia for savory flavor carriers creates export expansion potential for established South American suppliers.
Industry Challenges
- Emissions Compliance Capex:Retrofitting render plants to meet tightening EPA and EU F-Gas Regulation standards requires substantial capital allocation at a time of margin compression.
- Traceability System Integration:USDA and FDA mandates for raw material lot tracking force legacy processors to overhaul documentation workflows without disrupting continuous operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Beef Fat Powder Market |
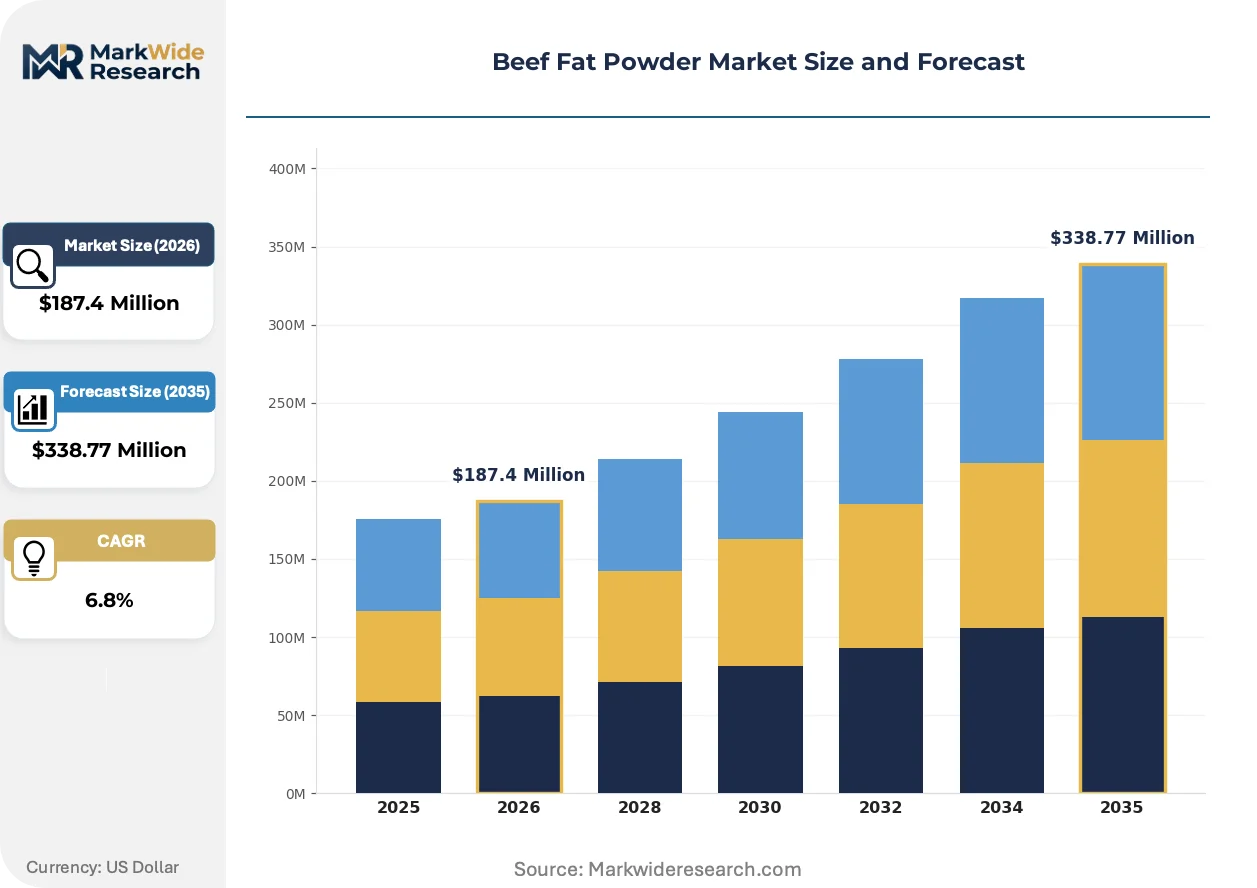
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydrogenated, Non-Hydrogenated, Rendered, Emulsified End Use: Food Industry, Bakery Products, Meat Processing, Pet Food Form: Powdered, Granular, Flaked, Liquid Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Nestlé S.A., JBS Ingredients, Lauta Food Ingredients GmbH, BHJ A/S, Kerry Group plc, Gelita AG, FrieslandCampina N.V., Cargill Incorporated, Connell Brothers Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Beef Fat Powder Market Evolving Landscape
Processing technology convergence and regulatory stringency are reshaping how beef fat powder is manufactured, certified, and procured across food and animal nutrition value chains.
Membrane filtration technology is integrating into rendering operations to separate and standardize lipid fractions before drying. Pet food manufacturers in the United States are adopting these higher-purity inputs at accelerating pace. This integration is compressing the traditional spot-market trade in unstandardized tallow.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in industrial refrigeration and thermal equipment. European renderers must retrofit or replace processing infrastructure to maintain operating licenses. South American exporters targeting EU markets are preemptively upgrading equipment to preserve import eligibility.
Direct procurement contracts between integrated beef processors and end-use manufacturers are displacing traditional trader-mediated spot markets. Pet food and savory flavor houses in North America are negotiating multi-year supply agreements with named renderers. This pattern is most visible in Brazil's São Paulo state cluster where captive supply chains dominate.
Beef Fat Powder Market Segmentation
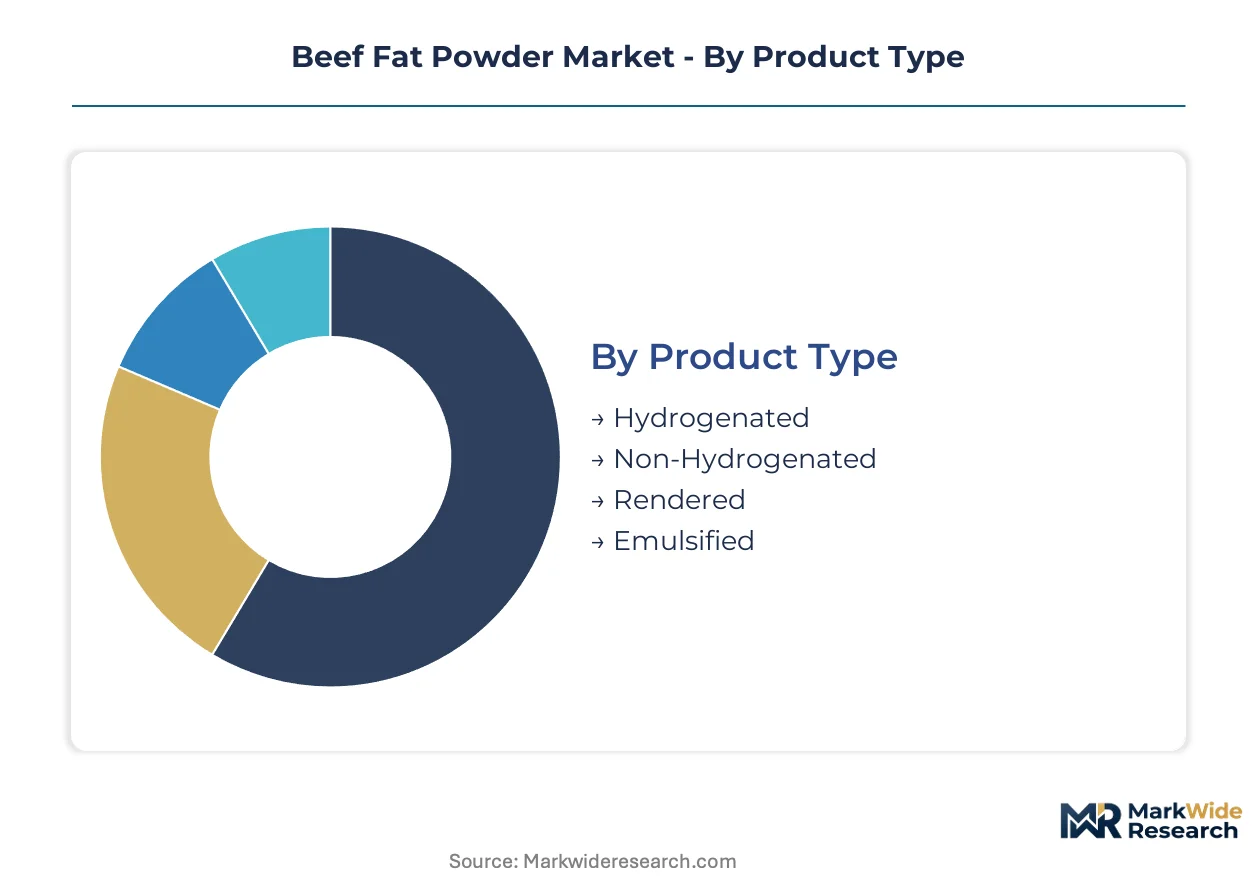
Beef fat powder procurement patterns diverge sharply across product specifications, end-use applications, and supply chain configurations. Buyers prioritize oxidative stability, emulsification performance, or clean-label alignment depending on their formulation requirements and regulatory exposure.
Product Type:
Cost sensitivity and functional requirements separate buyers across hydrogenation status and processing intensity tiers.
- Non-Hydrogenated:Rendered bovine adipose tissue processed without catalytic hydrogenation, retaining native fatty acid profiles. Pet food manufacturers in the United States specify these variants to meet clean-label demands and avoid trans-fat labeling triggers under FDA guidelines.
- Emulsified:Specialized grades incorporating lecithin or other surfactants to enable stable fat-water integration. Bakery applications in São Paulo state and Mato Grosso drive procurement of these premium grades where dough consistency and shelf stability determine product performance.
- Hydrogenated:Catalytically hardened fats with elevated melting points for industrial baking and confectionery.
- Rendered:Standard dried and milled tallow meeting basic moisture and free fatty acid thresholds for commodity applications.
Non-hydrogenated grades lead volumes today; emulsified variants are climbing the fastest on bakery premiumization.
End Use:
Application-specific lipid requirements dictate specification stringency and contract structures across downstream industries.
- Pet Food:Calorie-dense rendered fat powder specified for palatability enhancement and energy density in companion animal diets. North American manufacturers negotiate multi-year supply agreements with named renderers to lock in lipid profile consistency.
- Bakery Products:Texture modification and flavor carrier functions requiring precise melting behavior and oxidative stability. Brazilian integrated processors are adding captive rendering capacity to serve this segment directly.
- Food Industry:Broad savory and processed food applications using beef fat powder as flavor carriers and mouthfeel modifiers.
- Meat Processing:Reincorporation of rendered fats into processed meat products for juiciness retention and cost management.
Pet food applications command the steepest expansion trajectory; bakery products maintain the largest revenue base.
Form:
Handling characteristics and dissolution kinetics determine form selection across manufacturing environments.
- Powdered:Fine-milled particles below 500 microns for rapid dispersion in dry mixes and extruded products. Pet food extrusion operations in the United States favor this form for uniform coating and metering precision.
- Granular:Larger particle sizes reducing dust generation during bulk handling. Meat processing facilities specify granular forms for controlled reincorporation into emulsified products.
- Flaked:Thin compressed sheets facilitating rapid melting in heated processing environments.
- Liquid:Warmed or solvent-suspended fats for direct injection into continuous processing lines.
Powdered forms dominate current procurement; granular grades are expanding most quickly on dust-control regulations.
Distribution Channel:
Volume scale and supply chain reliability requirements separate buyers across channel structures.
- Direct Sales:Long-term contracts between integrated beef processors and end-use manufacturers eliminating trader intermediation. Brazilian processors in São Paulo state leverage captive rendering for direct supply to pet food and savory flavor houses.
- Wholesale:Bulk procurement through specialized fat and oil distributors serving mid-scale manufacturers without direct renderer relationships.
- Online:E-procurement platforms for sample orders, spot purchases, and small-batch requirements.
- Retail:Packaged consumer-facing sales for artisanal and small commercial users.
Direct sales channels capture the largest volume flows; online platforms are gaining share fastest on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Renderers are relocating thermal processing capacity to jurisdictions with lighter emissions compliance burdens. This regulatory arbitrage accelerates as EU F-Gas Regulation enforcement tightens while South American integrated processors expand captive operations.
United States
Pet food manufacturers in the Midwest and Southeast specify rendered beef fat powder for calorie-dense companion animal diets. FDA traceability mandates and USDA grading standards govern raw material sourcing and pathogen control. Rendering clusters in Nebraska and Texas supply both domestic extrusion operations and export-oriented powder production.
Brazil
Integrated beef processors in São Paulo state and Mato Grosso are adding captive rendering-to-powder capacity to capture downstream margins. ANVISA food safety frameworks and export certification requirements shape operational protocols. The São Paulo cluster dominates supply to domestic savory flavor houses and Asian export markets.
Germany
Bakery applications in Bavaria and North Rhine-Westphalia drive demand for emulsified fat powder grades with precise melting behavior. REACH restrictions on processing aids and EFSA contaminant thresholds constrain import eligibility. Renderers in Lower Saxony are retrofitting thermal equipment to preserve EU market access under F-Gas Regulation phase-down schedules.
Argentina
Integrated beef processors are restructuring rendering operations to supply both domestic users and export markets. The national food safety regulator mandates traceability systems for rendered products entering formal distribution channels. Buenos Aires province hosts the primary concentration of rendering-to-powder capacity serving Mercosur trade corridors.
India
BIS certification requirements create compliance barriers for foreign suppliers seeking direct market access. Domestic pet food manufacturers in Maharashtra and Gujarat source rendered fats through wholesale distribution channels. The Mumbai-Pune industrial corridor concentrates formulation facilities specifying standardized lipid inputs for companion animal nutrition.
Beef Fat Powder Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue application-specific formulation partnerships. The vendor base spans integrated beef processors with captive rendering, specialized fat powder refiners, and diversified food ingredient conglomerates. Three archetypes dominate: South American integrated processors controlling upstream supply, European specialists in emulsified grades, and global distributors leveraging procurement scale. Competitive moves center on multi-year direct procurement contracts displacing spot-market trade, and emissions-compliant equipment upgrades preserving EU import eligibility.
Among diversified food ingredient conglomerates, Kerry Group plc and Cargill Incorporated exemplify scale-driven distribution archetypes, while JBS Ingredients represents the South American integrated processor model with captive cattle supply anchoring raw material security. These three occupy distinct competitive positions without direct overlap in core capabilities.
| Leading Market Players |
|---|
| Nestlé S.A. |
| JBS Ingredients |
| Lauta Food Ingredients GmbH |
| BHJ A/S |
| Kerry Group plc |
| Gelita AG |
| FrieslandCampina N.V. |
| Cargill Incorporated |
| Connell Brothers Limited |
| Others |
Value Network & Pricing Analysis
Bovine adipose tissue feedstock costs cascade through three pricing tiers downstream. Renderers in Nebraska and Texas pass slaughter-cycle volatility to pet food manufacturers through contract escalation clauses. Spot-market traders absorb margin compression when herd liquidation phases spike raw material availability.
Pricing Analysis
Distributor margin layers separate commodity rendered grades from emulsified premiums. Three-tier pricing structure across premium, standard, and economy levels reflects oxidative stability thresholds and emulsification performance. Price differentiation centers on certification grade and volume scale, with FDA-compliant traceability commanding premiums. Cost compression in standard grades is intensifying because poultry fat substitution erodes species-specific premiums. Mid-scale savory flavor houses exhibit highest price sensitivity; premium pet food manufacturers show lowest.
Supply Chain Analysis
Workforce availability constraints in São Paulo state and Mato Grosso renderers are tightening operational flexibility. Supply concentrates in Brazil, the United States, and Germany, with Brazilian captive operations drawing from integrated cattle processing. Raw material dependencies rest on bovine adipose tissue supply, lecithin emulsifier inputs, and thermal energy feedstocks. Single-source vulnerability around EU F-Gas Regulation compliance creates import eligibility risk for non-retrofitted plants. Distribution runs through direct procurement contracts displacing traditional trader intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU emissions compliance burdens and South American cost advantages. The EU F-Gas Regulation retrofit requirement creates permanent cost elevation for European renderers against Brazilian captive operations.
For Market Incumbents: Cement raw material security through backward integration into cattle processing or multi-year direct contracts with named renderers. Invest in membrane filtration standardization technology to defend against poultry fat substitution in pet food applications. Prioritize emissions-compliant equipment upgrades to preserve EU import eligibility as F-Gas phase-down tightens.
For New Entrants and Emerging Players: Capture white-space in Vietnamese and Indonesian savory flavor carrier markets where South American supply penetration remains limited. Target emulsified grade production for bakery applications in São Paulo state where captive supply chains dominate. Pursue application-specific formulation partnerships with mid-tier pet food manufacturers seeking lipid profile consistency.
For Investors and Strategic Acquirers: Roll-up economics work for specialized emulsified grade refiners because bakery premiumization concentrates margin in technical formulation capabilities. Long-term viability centers on 5-10 year positioning around clean-label alignment and decarbonization compliance. Target acquisition archetype: European emulsified grade specialists with REACH-compliant processing infrastructure. Watch EU Green Deal funding stream allocation as inflection indicator for competitive equipment upgrade pacing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cattle Processing | JBS Ingredients demonstrates captive supply security across São Paulo state operations. |
| Membrane Filtration Technology Deployment | Pet food manufacturers in the United States adopt higher-purity inputs at accelerating pace. |
| EU F-Gas Regulation Equipment Retrofit | Renderers in Lower Saxony preserve market access under phase-down schedules. |
| Direct Procurement Contract Negotiation | North American pet food manufacturers lock in lipid profile consistency through multi-year agreements. |
| Emulsified Grade Capacity Expansion | Bakery applications in Mato Grosso drive margin premiums for specialized milling investment. |
Research Methodology
Multiple input streams — primary interviews with rendering plant managers, pet food procurement leads, and bakery R&D directors; secondary validation through ANVISA filings, USDA trade data, and EFSA contaminant threshold documentation; plus SEC disclosures from diversified ingredient conglomerates — were reconciled through bottom-up and top-down triangulation.
Historical volume trajectories were cross-referenced against panel input from industry participants to construct analytical frameworks across the analysis window. Segmentation dimensions modeled include hydrogenation status, end-use application, particle form, and distribution channel structure. CAGRs were derived from slope-consistency checks against input cost elasticity and substitution threat parameters. Industry-specific forecast inputs incorporated cattle slaughter cycle patterns and EU emissions regulation enforcement pacing.
Regulatory enforcement timing, feedstock price volatility, and substitution technology advancement are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about F-Gas Regulation phase-down adherence and Brazilian cluster capacity expansion schedules. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Canned Pork Market
Meat Products
Organic Chicken Market
Meat Products
South Africa Processed Meat Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
Meat Tenderizer Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Reduced Fat Meat Market
Meat Products
Beef Liver Market
Meat Products
Nitrate-Free Bacon Market
Meat Products
Non-Veg Rte and Rtc Market
Meat Products
Vegan Meatball Market
Meat Products
Middle East Red Meat Market
Meat Products
Chicken Fat Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Beef Bone Broth Market
Meat Products
Organic Halal Meat Market