
 Organic Halal Meat Market | 2026-2036
Organic Halal Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Halal Meat Market Insights
Food service procurement is pivoting toward traceable organic halal supply chains as institutional buyers rewrite sourcing protocols. Al Islami Foods leverages its Gulf distribution network to secure long-term hotel and airline contracts. Crescent Foods anchors North American supply through vertically controlled slaughter and processing facilities. Midamar Corporation differentiates via multi-certification coverage spanning JAKIM, IFANCA, and domestic organic standards.
Organic halal meat denotes livestock raised on certified organic feed without synthetic hormones or antibiotics, then processed under Islamic slaughter rites with full traceability documentation. The category serves consumers demanding simultaneous compliance with religious dietary law and chemical-free agricultural practice. Beef dominates product type value due to extended organic feedlot cycles and premium positioning in Gulf retail. Online retail channels capture the fastest expansion as direct-to-consumer platforms bypass traditional halal butcher intermediaries. Food service end users concentrate margin pools through volume contracts with certified processors.
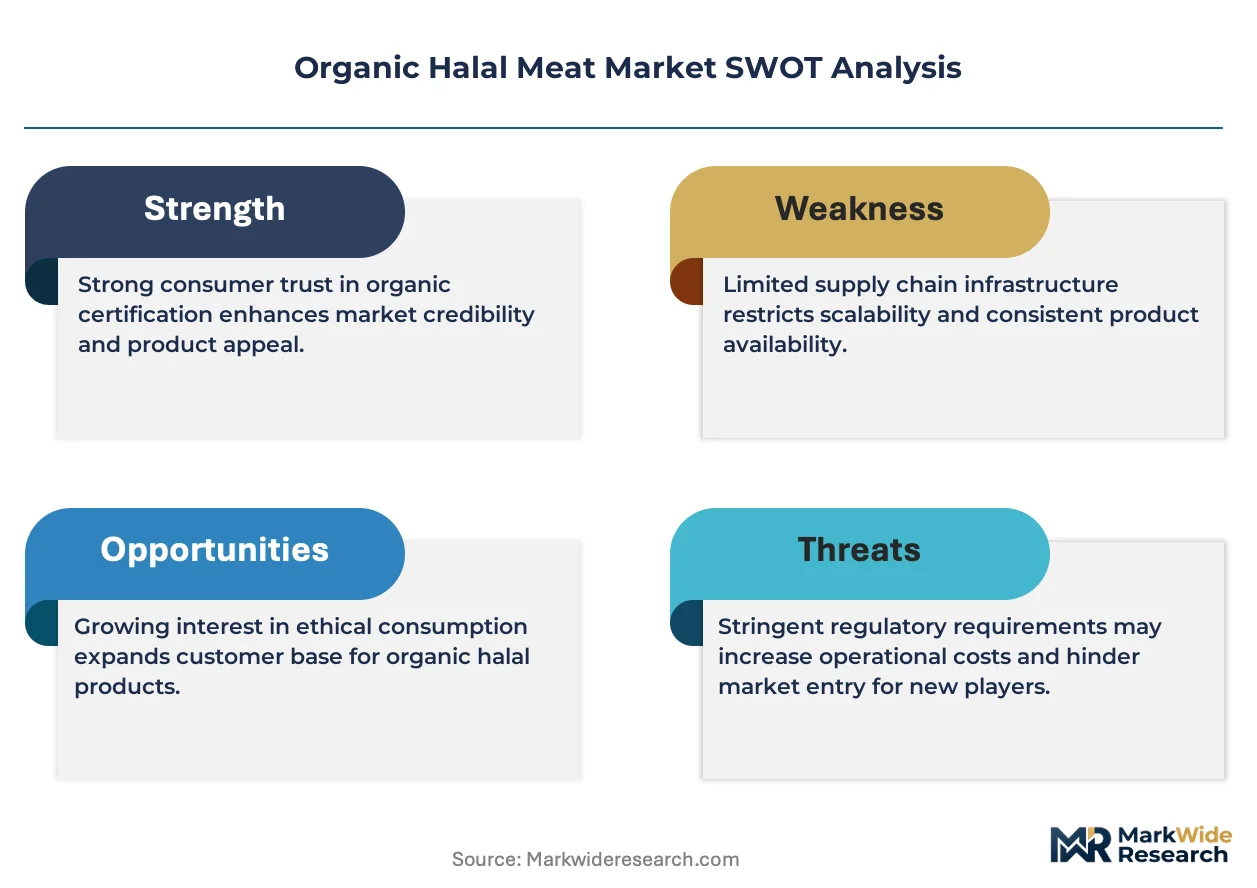
JAKIM in Malaysia, the USDA Organic program, and the EU Organic Regulation collectively define the dual-certification landscape that producers must navigate for export eligibility. These frameworks raise compliance costs but simultaneously create defensible market access for certified operators. Stakeholders must monitor certifying body mutual recognition agreements, as fragmentation between national halal authorities threatens to fragment supply chain efficiency.
Market Dynamics
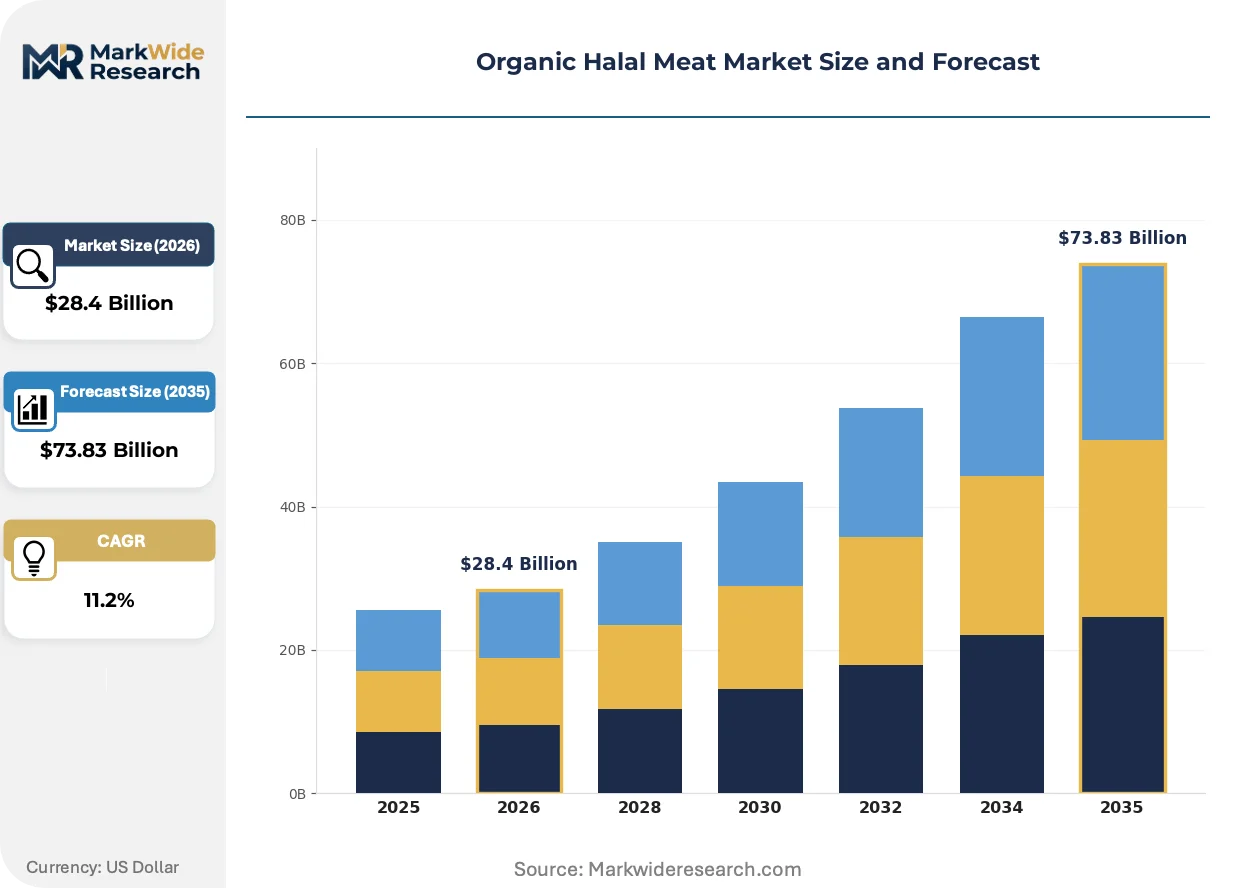
Dual-certification requirements from JAKIM, USDA Organic, and the EU Organic Regulation are compressing supplier margins while erecting entry barriers that protect incumbent certified processors. Food security mandates in Gulf states are simultaneously redirecting procurement toward domestic organic halal capacity.
Growth Catalysts
- Government food security mandates:Saudi Arabia's domestic production subsidies are redirecting procurement toward local organic halal capacity. State-backed abattoir investments accelerate supply localization.
- EU Organic Regulation harmonization:Cross-border certification mutual recognition is streamlining export pathways for Malaysian and Indonesian processors. Dual-certified operators gain preferential shelf placement in European retail.
- Blockchain-enabled traceability systems:Real-time slaughter-to-retail tracking satisfies institutional buyer audit requirements. Hotel chains and airlines mandate this documentation for contract eligibility.
Market Restraints
- Organic feed cost volatility:Certified grain and forage prices fluctuate with climate-driven harvest variability. Extended organic cattle finishing cycles amplify feed cost exposure.
- Slaughter capacity concentration:Gulf-region halal abattoir infrastructure clusters in Saudi Arabia and UAE. Processor dependence on these facilities creates geographic supply risk.
- JAKIM-EU certification misalignment:Divergent animal welfare documentation requirements force redundant audits. Exporters face compliance cost duplication for dual-market access.
Strategic Opportunities
- Indonesia domestic market penetration:The world's largest Muslim population exhibits underdeveloped organic halal retail infrastructure. Local slaughter and cold-chain investment addresses supply gaps.
- Direct-to-consumer platform expansion:Subscription-based organic halal delivery bypasses traditional butcher intermediaries. Urban professional households drive repeat purchase velocity.
- EU Green Deal agricultural incentives:Carbon-sequestration payments for organic livestock operations improve unit economics. Pasture-based halal producers qualify for supplementary environmental credits.
Industry Challenges
- Dual-certification auditor scarcity:Qualified inspectors capable of assessing both organic and halal standards remain concentrated in Malaysia and Saudi Arabia. Certification backlog extends market entry timelines.
- Cold-chain capex intensity:Organic halal integrity requires temperature-controlled transport from slaughter to retail. Emerging market infrastructure gaps force processor-owned logistics investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Halal Meat Market |
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $73.83 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Lamb, Chicken, Goat Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service End User: Restaurants, Households, Catering Services, Food Processors Certifying Body: JAKIM, HAACP, IFANCA, Others |
| Companies Covered | Al Islami Foods, Crescent Foods, Midamar Corporation, Janan Meat, Halal Pastures, The Organic Meat Company Limited (TOMCL), OBE Organic, TRU Organic Beef, Farmer Focus, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Halal Meat Market Trends and Innovations
Technology convergence and certification digitization are compressing traditional supply chain intermediaries while enabling new verification business models. Regulatory fragmentation is simultaneously forcing compliance investment and creating certification-as-a-service opportunities.
Blockchain-based provenance tracking is modularizing supply chain transparency into interoperable verification layers. Hotel procurement departments and airline catering divisions are mandating this documentation for contract renewal. The technology is modularizing what previously required multi-party paper trails into automated compliance verification.
The EU Organic Regulation's updated animal welfare documentation requirements are tightening cross-border enforcement. Processors must now submit real-time slaughter floor video feeds for audit trail compliance. Small-scale Malaysian exporters face disproportionate compliance cost burdens relative to integrated Gulf operators.
Subscription-based direct-to-consumer platforms are displacing traditional halal butcher retail relationships. Urban professional households in Riyadh, Jeddah, and Dubai are consolidating weekly protein purchases through app-based ordering. This channel shift concentrates buyer power with platform operators who dictate certification and pricing terms to processors.
Organic Halal Meat Market Segmentation
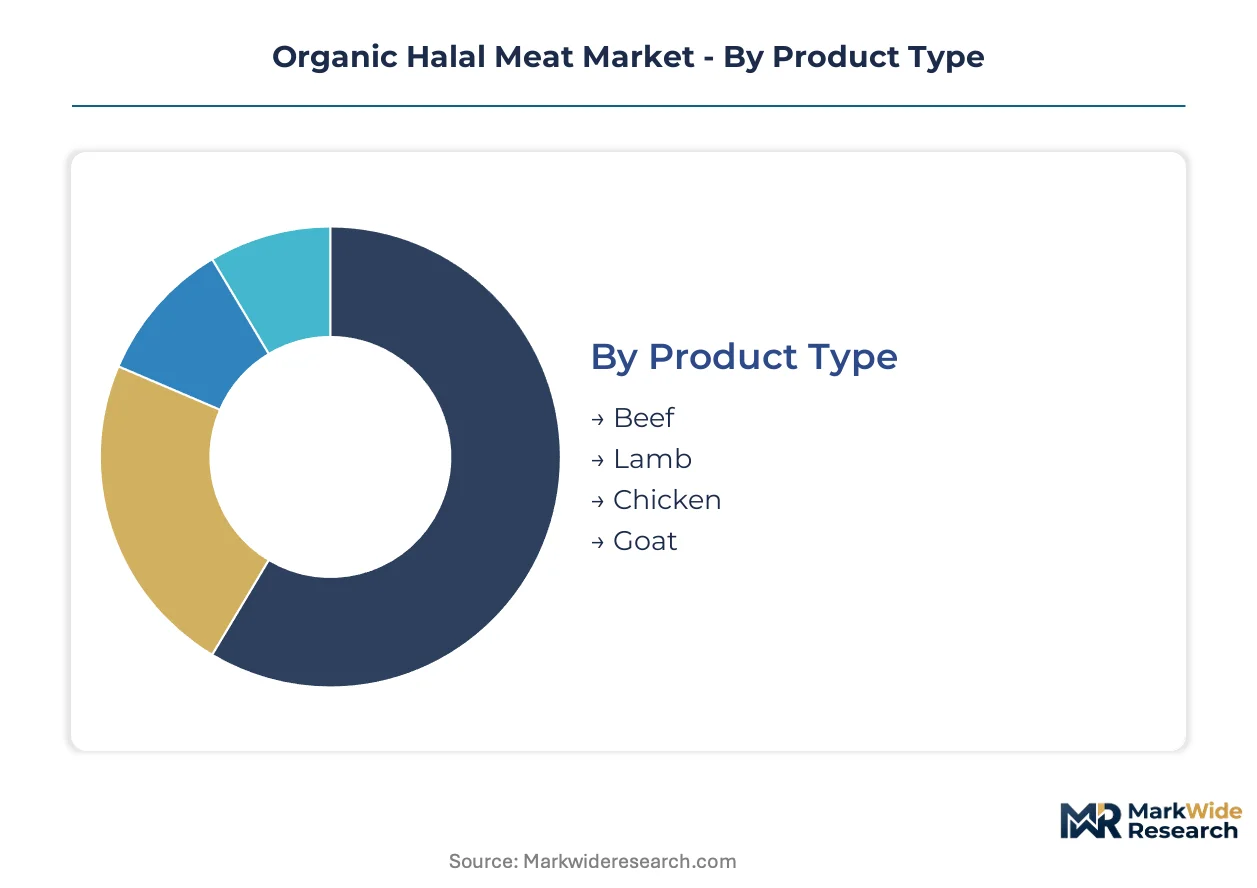
Dual-certification complexity and channel fragmentation create distinct margin profiles across product categories. Producers must align slaughter capacity, feed sourcing, and documentation systems to the specific requirements of each segment combination.
Product Type:
Volume concentration sits with extended-feedlot species, while premium capture favors shorter-cycle alternatives.
- Beef:Extended organic finishing cycles of 18-24 months create feed cost exposure that processors offset through Gulf retail premium positioning. Saudi Arabia's state-backed abattoir investments concentrate procurement of certified organic halal cattle.
- Lamb:Shorter organic rearing periods and established Middle Eastern consumption patterns support consistent margin structures. Australian and New Zealand exporters dominate supply contracts with UAE hotel chains.
- Chicken:Rapid organic turnover cycles enable price accessibility for mass-market penetration.
- Goat:Niche ethnic market demand concentrates in South Asian diaspora communities across Europe and North America.
Mature deployment sits with Beef. Newer deployment is concentrated in Chicken as processors adapt organic halal systems to shorter-cycle species.
Distribution Channel:
Margin compression intensity varies by intermediary layer and documentation burden.
- Online Retail:Direct-to-consumer platforms bypass traditional halal butcher intermediaries, consolidating buyer power with app-based operators. Riyadh and Dubai urban professional households drive subscription velocity for weekly protein purchases.
- Supermarkets:Shelf placement competition favors dual-certified processors with JAKIM and USDA Organic coverage. European retail chains mandate real-time traceability documentation for contract renewal.
- Specialty Stores:Ethnic butcher networks retain loyalty through personal certification verification relationships.
- Food Service:Volume contracts with hotel and airline catering divisions concentrate procurement with integrated Gulf processors.
Channel investment prioritizes Online Retail for expansion velocity, while Food Service anchors margin stability through long-term contracts.
End User:
Documentation requirements scale with institutional audit intensity versus household flexibility.
- Restaurants:Fine-dining and hotel outlets mandate blockchain-enabled slaughter-to-plate traceability for brand protection. Jeddah and Doha luxury hospitality clusters drive specification tightening.
- Households:Subscription platform consolidation shifts purchasing power to urban professional segments in Saudi Arabia and UAE.
- Catering Services:Event-scale volume demands strain cold-chain integrity during peak religious observance periods.
- Food Processors:Ready-meal manufacturers require certified organic halal cuts with consistent specification tolerances for automated production lines.
Institutional procurement concentrates with Restaurants. Consumer-direct expansion is climbing the fastest through platform-mediated Household access.
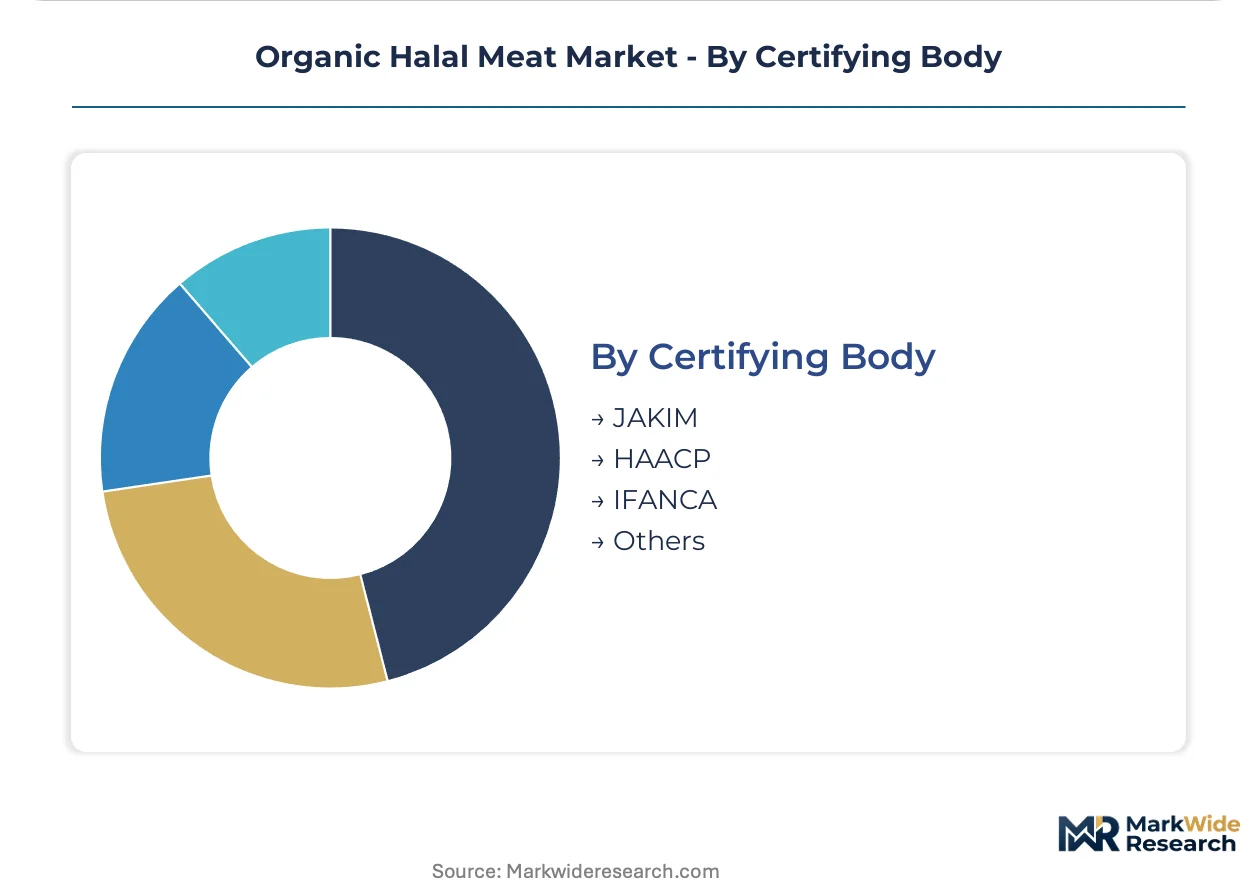
Certifying Body:
Mutual recognition gaps between authorities create compliance cost duplication for multi-market exporters.
- JAKIM:Malaysia's national halal authority maintains the most stringent documentation requirements for slaughter floor video audit trails. Exporters targeting Southeast Asian and Middle Eastern markets prioritize JAKIM coverage for preferential access.
- IFANCA:North American recognition enables US and Canadian market penetration for processors with USDA Organic dual-certification. Chicago-based institutional buyers specify IFANCA for school and hospital supply contracts.
- HAACP:Food safety system certification complements halal compliance for integrated quality management.
- Others:National authorities in Indonesia, Turkey, and Gulf states maintain non-harmonized standards that fragment export pathway efficiency.
Established certification concentrates with JAKIM. Emerging standardization efforts are gaining share fastest through IFANCA's North American retail partnerships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Australia and New Zealand, while consumption concentrates in Saudi Arabia and the UAE. Gulf states import the majority of certified organic halal supply. Southeast Asian processors serve as dual-certification intermediaries for European market access.
Saudi Arabia
State-backed food security mandates redirect procurement toward domestic organic halal capacity. The Saudi Food and Drug Authority enforces slaughter floor video documentation for export eligibility. Riyadh's state-invested abattoir complexes anchor Gulf supply localization efforts.
United Arab Emirates
Dubai's luxury hospitality sector mandates blockchain-enabled traceability for hotel and airline contracts. MOHAP certification requirements align with EU Organic Regulation for re-export facilitation. Jebel Ali's cold-chain logistics cluster processes transshipment volumes for regional redistribution.
Malaysia
JAKIM's stringent documentation standards create preferential access to Southeast Asian and Middle Eastern markets. The Department of Islamic Development Malaysia coordinates mutual recognition negotiations with EU authorities. Penang's integrated processing zones concentrate dual-certified slaughter and packaging capacity.
Australia
Extended organic cattle finishing cycles supply premium beef segments to Gulf retail chains. The Department of Agriculture administers export certification aligned with JAKIM and USDA Organic standards. Queensland's pastoral zones anchor pasture-based organic halal production for Asian market access.
United States
IFANCA-certified processors penetrate institutional supply contracts for schools and hospitals. USDA Organic program requirements complement halal compliance for domestic retail placement. Chicago's food service procurement hub concentrates North American distribution negotiations.
Organic Halal Meat Market Competitive Landscape
Top-tier vendors anchor Gulf-based integrated processing, while mid-scale operators compete through multi-certification coverage. The vendor base stratifies across three tiers: state-linked abattoir consortia, vertically controlled regional processors, and specialty direct-to-consumer platforms. Dominant strategic archetypes include certification-stack specialists, hospitality contract aggregators, and subscription-platform intermediaries. Competitive intensity concentrates on long-term institutional contract capture and cold-chain infrastructure ownership.
Within the Gulf-integrated tier, Al Islami Foods and Crescent Foods exemplify hospitality contract anchoring through controlled distribution networks. Midamar Corporation occupies a position spanning multi-certification coverage across JAKIM, IFANCA, and domestic organic standards. These three represent the archetype spectrum from geographic concentration to regulatory breadth.
| Leading Market Players |
|---|
| Al Islami Foods |
| Crescent Foods |
| Midamar Corporation |
| Janan Meat |
| Halal Pastures |
| The Organic Meat Company Limited (TOMCL) |
| OBE Organic |
| TRU Organic Beef |
| Farmer Focus |
| Others |
Pricing and Supply Chain Analysis
Dual-certification ladder bifurcation between JAKIM-USDA Organic holders and single-standard operators manifests in both procurement premiums and slaughter capacity allocation. Gulf hotel chains and airline caterers pay contracted premiums for blockchain-documented supply, while spot-market buyers absorb volatile organic feed cost pass-throughs from concentrated Australian and New Zealand exporters.
Pricing Analysis
Short lead-time premiums dominate contract negotiations, with hotel procurement departments paying above-spot rates for guaranteed weekly delivery windows. Three-tier pricing structure across JAKIM-plus-USDA Organic, JAKIM-only, and domestic organic-only certification levels captures buyer willingness to pay for audit depth. Cost compression in single-standard tiers intensifies as Malaysian exporters absorb redundant audit burdens for EU market access. Food service buyers exhibit lowest price sensitivity due to brand protection requirements, while mass-market households drive subscription platform competition.
Supply Chain Analysis
Reverse-logistics flows for temperature-compromised organic halal inventory remain underdeveloped, forcing write-offs rather than refurbishment. Supply concentrates in Australia, New Zealand, and Saudi Arabia for cattle finishing, with Malaysia and Indonesia anchoring dual-certification processing. Raw material dependencies center on certified organic grain from Argentina and forage from Australian pastoral zones. Single-source vulnerability sits with Gulf-region halal abattoir clustering in Riyadh and Dubai. Distribution runs through processor-owned cold-chain assets rather than third-party logistics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Supply-constrained dynamics define this market, with qualified dual-certification auditors concentrated in Malaysia and Saudi Arabia propping processor pricing power.
For Market Incumbents: Anticipate JAKIM-EU mutual recognition delays by pre-positioning redundant audit capacity in Penang processing zones. Defensive consolidation should target cold-chain logistics operators in Jebel Ali to lock in transshipment control. Certification investment in blockchain-enabled traceability systems secures contract renewal eligibility with Dubai luxury hospitality clusters. For New Entrants and Emerging Players: Direct-to-consumer platform partnerships offer the most penetrable entry vector, bypassing entrenched halal butcher networks in Riyadh and Jeddah. White-space targets include Indonesian domestic retail infrastructure and EU Green Deal carbon credit qualification for pasture-based operations. Go-to-market execution should anchor on subscription-based household acquisition with app-mediated weekly delivery. For Investors and Strategic Acquirers: Re-rating potential sits with vertically controlled regional processors given Saudi state-backed abattoir investment acceleration. Long-term viability favors operators with captive organic feed sourcing and integrated slaughter capacity. Acquisition target archetypes include Malaysian dual-certification specialists with JAKIM-EU regulatory bridging capability. Monitor JAKIM-EU mutual recognition agreement announcements for inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | JAKIM-plus-USDA Organic coverage unlocks preferential shelf placement in European retail chains. |
| Cold-Chain Infrastructure Buildout | Processor-owned logistics in Jebel Ali secures transshipment control for Gulf redistribution. |
| Blockchain Traceability Deployment | Real-time slaughter-to-retail tracking satisfies hotel and airline contract audit requirements. |
| Direct-to-Consumer Platform Launch | Subscription-based delivery bypasses traditional halal butcher intermediaries in Saudi Arabia. |
| EU Green Deal Carbon Qualification | Pasture-based organic halal operations capture supplementary environmental credit payments. |
Research Methodology
Multi-period observation of certification backlog durations, organic feed price spreads, and cold-chain infrastructure deployment anchored the trend analysis, supplemented by interviews with halal certification auditors, hotel procurement directors, airline catering executives, and organic livestock farm operators. Secondary validation drew from JAKIM regulatory filings, EU Organic Regulation enforcement notices, USDA Organic program data, and Gulf customs trade records. Bottom-up slaughter capacity modeling and top-down consumption estimates were triangulated for cross-verification.
Segment-weighting approaches applied product type, distribution channel, end user, and certifying body dimensions across the projection horizon. CAGRs were derived from fitted growth curves applied to certified organic halal slaughter volumes and retail value flows. Forecast inputs incorporated organic feed cost volatility assumptions and mutual recognition agreement probability assessments.
Several conditions sit outside the modeled scope, including unilateral halal standard revisions by national authorities and climate-driven organic grain harvest failures. Forecasts reflect documented assumptions about certification harmonization progress and state subsidy continuity. Practitioners should monitor JAKIM-EU negotiation milestones and Saudi domestic production capacity announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Europe Edible Meat Market
Meat Products
Grass-Fed Meat Market
Meat Products
France Meat Products Market
Meat Products
Organic Chicken Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Meat Market
Meat Products
Germany Poultry Meat Market
Meat Products
Reduced Fat Meat Market
Meat Products
Beef Jerky Market
Meat Products
Global Poultry Meat Market
Meat Products
Asia-Pacific Low Fat Sausage Market
Meat Products
Beef Fat Powder Market
Meat Products
Non-Veg Rte and Rtc Market
Meat Products
Organic Eggs Market
Meat Products
Europe Bacon Market
Meat Products
Beef Bone Broth Market