
 Global Lab-Based Meat Market | 2026-2036
Global Lab-Based Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lab-Based Meat Market Foresight
Singapore is fragmenting into multiple competing technology clusters as government-backed biotech parks attract capital from across Asia-Pacific. Upside Foods leverages its California-based pilot facility to sustain regulatory dialogue with the FDA and USDA. Aleph Farms anchors Israeli innovation in scaffold-based steak cultivation. Mosa Meat competes through its Maastricht headquarters, where it controls Europe's largest dedicated cultured-meat research infrastructure.
Lab-based meat denotes animal protein produced through in vitro cell culture of muscle and fat cells within bioreactor systems, typically achieving tissue densities of 10^8 cells per milliliter before scaffold assembly or three-dimensional structuring. Its primary commercial purpose is to replicate conventional meat sensory properties while eliminating slaughter-based supply chains. Cultured beef occupies the deepest margin pools due to premium positioning and high consumer recognition, while cultured seafood represents the fastest-expanding category as ocean sustainability concerns intensify. Bioreactor fermentation leads technology deployment because existing pharmaceutical infrastructure adapts readily, though 3D bioprinting differentiates at the premium tier by enabling precise muscle-fat marbling replication.
The FDA and USDA jointly oversee cultured meat safety and labeling in the United States, while Singapore's Singapore Food Agency pioneered commercial approval frameworks that shape regulatory templates worldwide. The EU's EFSA and novel food regulations under the General Food Law create a slower but harmonized pathway across member states. Stakeholders must monitor which regulatory jurisdiction achieves scalable approval templates first, as this will determine where capital deployment and production scaling concentrate.
Market Dynamics
Bioreactor fermentation economics now dominate capital allocation decisions as pharmaceutical-grade equipment repurposing slashes facility buildout timelines from five years to eighteen months.
Growth Catalysts
- Singapore Food Agency approval framework:The first-mover regulatory template accelerates commercial licensing timelines for foodservice operators seeking cultured poultry menu integration.
- Scaffold-based steak cultivation:Israeli and Dutch research clusters advance three-dimensional tissue structuring that replicates conventional beef sensory profiles without slaughter-based supply chains.
- Foodservice channel concentration:Singapore and United States restaurant groups expand pilot programs, creating visible demand pull for scaled bioreactor output.
Market Restraints
- Serum-free media cost volatility:Growth factor recombinant protein inputs fluctuate with pharmaceutical sector demand, compressing gross margins at commercial scale.
- Bioreactor equipment supply concentration:German and Swiss stainless-steel vessel manufacturers control lead times for pharmaceutical-grade installations.
- EFSA novel food pathway duration:European Union harmonized approval timelines extend twenty-four to thirty-six months versus Singapore's accelerated review.
Strategic Opportunities
- United States FDA-USDA joint framework maturation:Clarified labeling and safety protocols unlock institutional foodservice procurement from federal contractors.
- Cultured seafood category whitespace:Ocean sustainability concerns drive faster consumer acceptance for lab-based tuna and salmon versus beef analogues.
- 3D bioprinting convergence with AI-driven tissue modeling:Precision muscle-fat marbling replication commands premium positioning in high-end foodservice.
Industry Challenges
- Cell line bioprocess engineering talent scarcity:Pharmaceutical fermentation specialists command compensation premiums that strain startup burn rates.
- Commercial-scale cleanroom capex intensity:GMP-compliant facility construction requires eight-figure capital deployment before revenue generation.
- Cross-jurisdictional IP licensing complexity:Scaffold materials patents, cell line ownership, and bioreactor process claims create transaction friction for international expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lab-Based Meat Market |
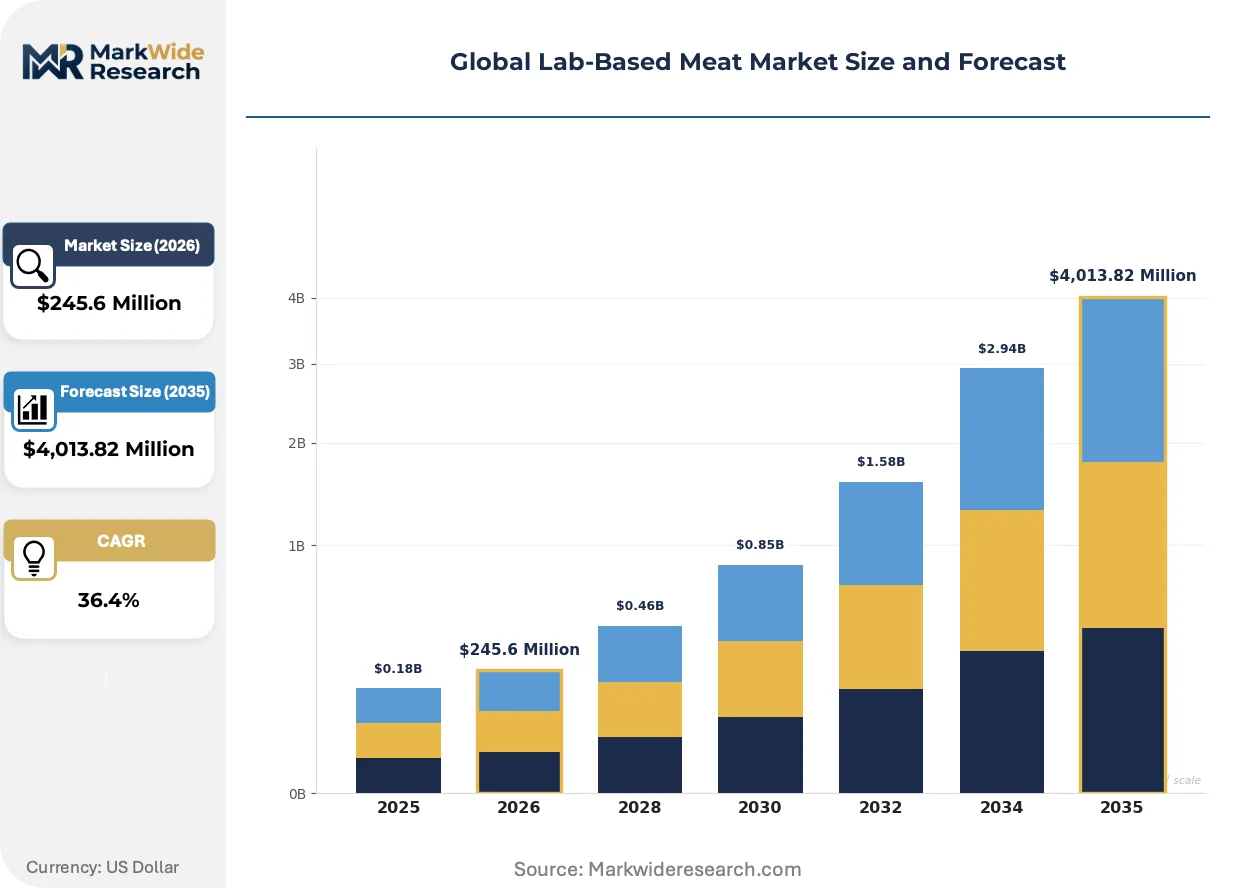
| Market Size in 2026 | $245.6 Million |
| Market Size in 2035 | $4,013.82 Million |
| CAGR (2026 – 2036) | 36.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cultured Beef, Cultured Poultry, Cultured Seafood, Cultured Pork, Cultured Lamb Technology: 3D Bioprinting, Cell Proliferation, Scaffold-Based Cultivation, Stem Cell Culturing, Bioreactor Fermentation Application: Foodservice, Retail Packaging, Institutional Dining, Ready-to-Eat Meals, Food Ingredients End User: Restaurants, Meat Processors, Food Manufacturers, R&D Laboratories, Specialty Butchers |
| Companies Covered | Upside Foods, Eat Just, Aleph Farms, Mosa Meat, Meatable, Believer Meats, Finless Foods, BlueNalu, Future Meat Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lab-Based Meat Market Shifts & Advancements
Continuous perfusion bioprocessing is displacing batch fermentation as the dominant production paradigm, compressing unit economics while demanding entirely new facility architectures and workforce competencies.
Perfusion bioreactor systems maintain cell densities at 10^8 cells per milliliter through continuous nutrient exchange and waste removal. Foodservice manufacturers in Singapore and the United States are retrofitting existing pharmaceutical facilities to adopt this modality. The technology is rendering obsolete stainless-steel batch vessels that require lengthy turnaround cycles between production runs.
Singapore's Food Agency pioneered a novel food safety assessment template that the FDA and USDA subsequently referenced in their joint regulatory framework. This regulatory convergence reduces compliance duplication for multi-jurisdictional operators. Cultured poultry products face accelerated review timelines under these harmonized protocols, while beef and seafood categories await analogous pathway clarity.
Direct procurement relationships between bioreactor operators and institutional foodservice buyers are shortening traditional protein supply chains. United States federal contractors and Singaporean hospital networks now source cultured meat through bilateral agreements rather than commodity distributors. This channel compression is most visible in Singapore, where government-backed biotech parks co-locate production and pilot kitchen facilities.
Global Lab-Based Meat Market Segmentation
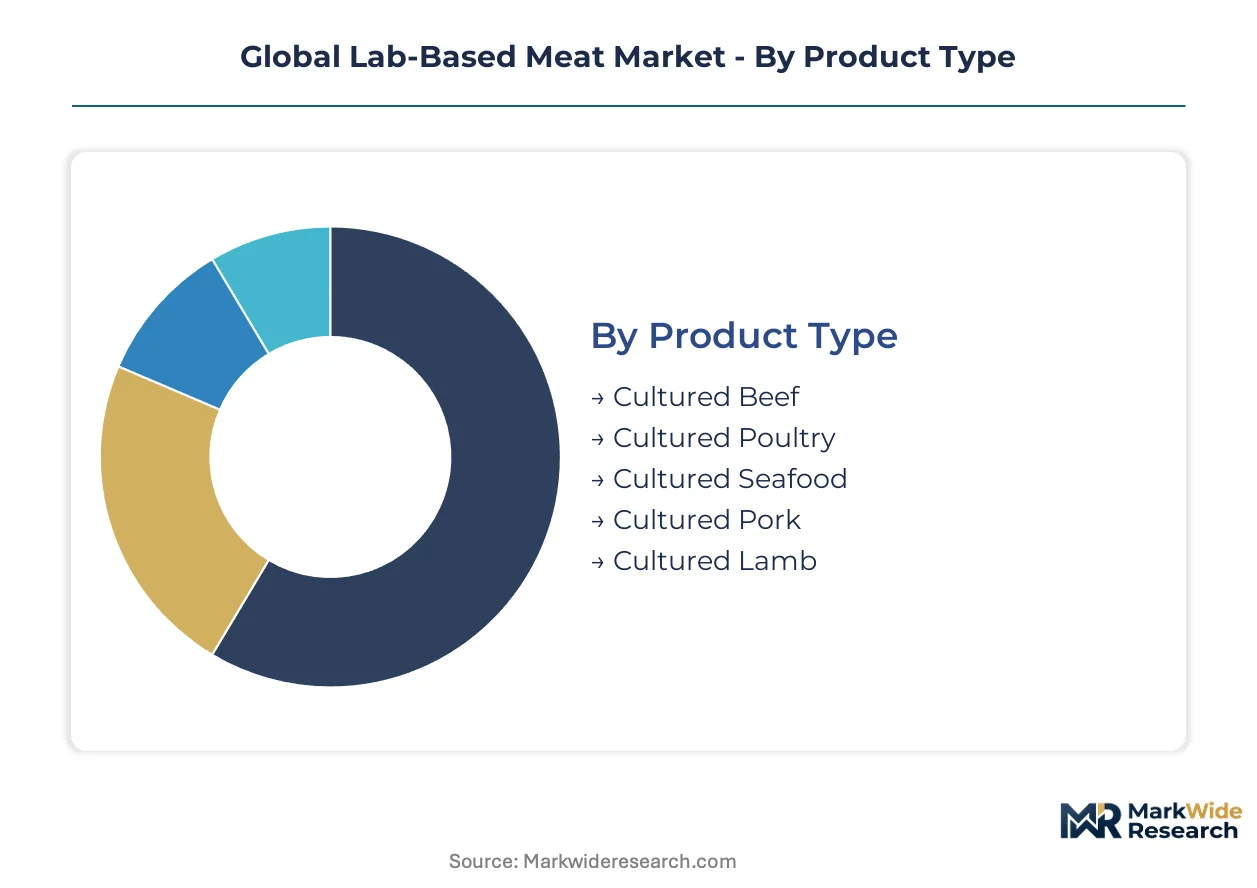
Lab-based meat segmentation reveals how production technology, protein species, and distribution channels intersect to determine capital allocation and margin capture. Each dimension carries distinct regulatory, operational, and consumer acceptance profiles that shape commercial viability.
Product Type:
Protein species selection determines bioprocess complexity, media formulation costs, and premium positioning potential across foodservice and retail channels.
- Cultured Beef:Scaffold-based tissue engineering replicates marbling and muscle fiber alignment for steak applications. Singaporean foodservice operators concentrate procurement here, driven by premium positioning and high consumer recognition.
- Cultured Poultry:Faster cell doubling times and lower growth factor requirements compress production economics. United States restaurant groups pilot menu integration, leveraging FDA-USDA joint framework clarity for accelerated licensing.
- Cultured Seafood:Ocean sustainability concerns intensify demand pull for tuna and salmon analogues without wild-catch supply chains.
- Cultured Pork:Religious dietary restrictions in Middle Eastern and South Asian markets constrain addressable demand versus beef or poultry.
- Cultured Lamb:Niche positioning in Mediterranean and Middle Eastern cuisine limits scale potential despite premium pricing.
The dominant share belongs to Cultured Beef, while Cultured Seafood is closing the gap fastest.
Technology:
Production modality determines facility capex intensity, workforce specialization requirements, and unit economics at commercial scale.
- Bioreactor Fermentation:Pharmaceutical-grade stainless-steel vessels achieve tissue densities of 10^8 cells per milliliter through controlled nutrient delivery. German and Swiss equipment manufacturers control lead times, constraining facility buildout velocity.
- 3D Bioprinting:AI-driven tissue modeling enables precise muscle-fat marbling replication for premium steak applications. Singaporean biotech parks concentrate deployment here, co-locating production with pilot kitchen facilities.
- Scaffold-Based Cultivation:Israeli and Dutch research clusters advance three-dimensional structuring without slaughter-based supply chains.
- Cell Proliferation:Basal expansion protocols feed downstream assembly processes across all product categories.
- Stem Cell Culturing:Pluripotent cell line establishment requires specialized cleanroom infrastructure and extended validation timelines.
Bioreactor Fermentation commands current installed capacity, though 3D Bioprinting is climbing the fastest as precision marbling commands foodservice premiums.
Application:
Channel selection determines regulatory pathway complexity, shelf-life requirements, and brand control versus commodity exposure.
- Foodservice:Direct procurement relationships with restaurants and institutional buyers compress traditional protein supply chains. Singapore and United States operators lead pilot program expansion.
- Retail Packaging:Labeling compliance and cold-chain logistics create barriers that delay mass-market penetration.
- Institutional Dining:United States federal contractors and Singaporean hospital networks source through bilateral agreements rather than distributors.
- Ready-to-Eat Meals:Formulation flexibility allows blended products that reduce pure cultured meat cost exposure.
- Food Ingredients:B2B supply to processed food manufacturers sacrifices margin for volume scale.
Foodservice absorbs the dominant procurement volume, while Institutional Dining is gaining share fastest through government-backed procurement programs.
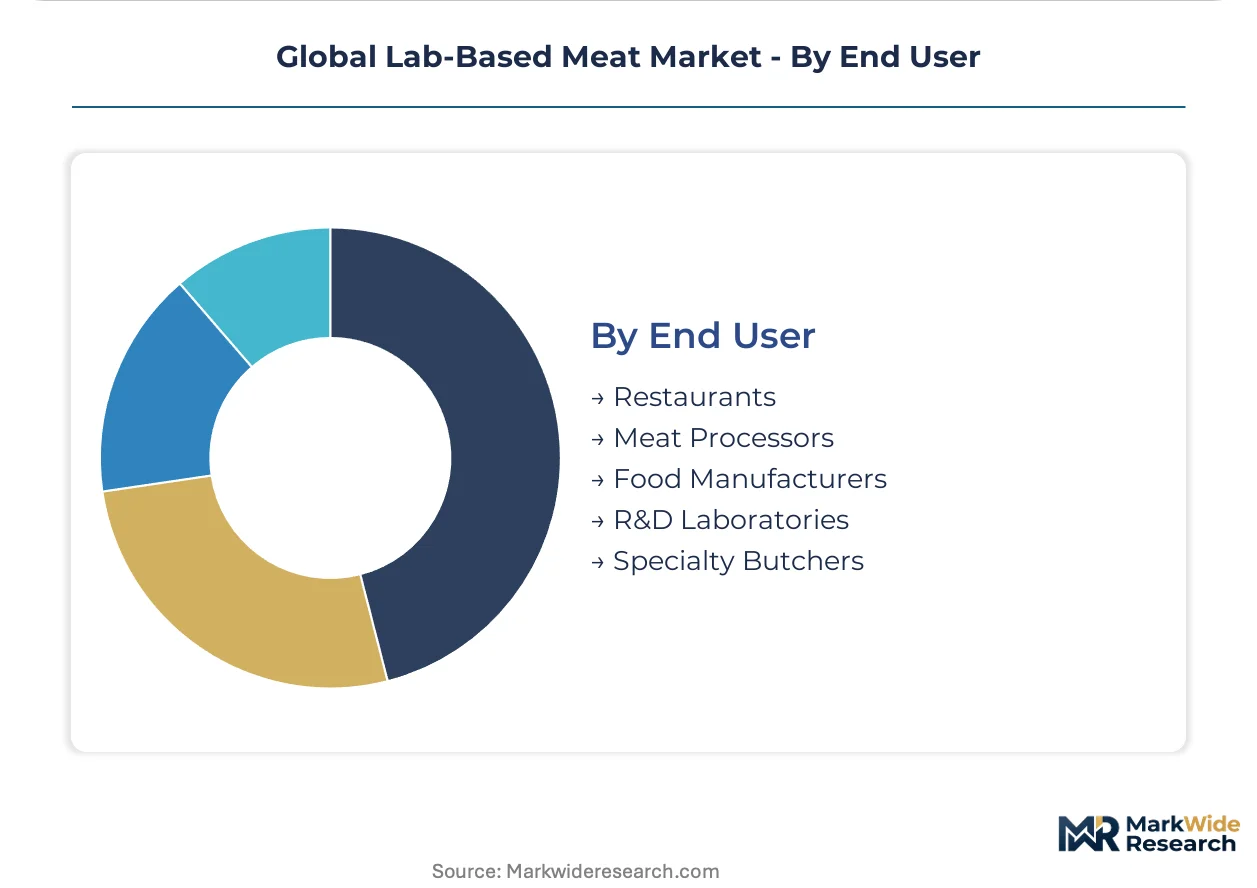
End User:
Customer type determines technical specifications, order consistency, and pricing power in early commercial phases.
- Restaurants:High-visibility menu placement generates consumer awareness and demand signaling for scaled production. Singaporean fine-dining groups anchor initial commercial offtake.
- Meat Processors:Incumbent suppliers evaluate cultured inputs for blended product lines to hedge against conventional supply volatility.
- Food Manufacturers:Formulation R&D partnerships seek protein functionality replication in processed applications.
- R&D Laboratories:Academic and corporate research facilities consume small volumes for protocol validation and IP generation.
- Specialty Butchers:Artisan positioning commands premium pricing but limits volume scalability.
Restaurants hold the dominant commercial relationship count, while Meat Processors are expanding procurement fastest as incumbent suppliers hedge supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA and USDA joint regulatory framework anchors United States commercial pathway clarity, while Singapore's Food Agency pioneered approval templates now referenced worldwide. Production scaling concentrates where regulatory templates achieve scalable clarity first.
United States
Foodservice operators in California and New York Metro expand cultured poultry menu trials, driven by institutional procurement from federal contractors. The FDA-USDA joint framework accelerates licensing timelines through clarified safety protocols and labeling standards. Upside Foods leverages its California pilot facility to sustain regulatory dialogue and secure pre-market consultations.
Singapore
Government-backed biotech parks attract Asia-Pacific capital, fragmenting the city-state into multiple competing technology clusters. The Singapore Food Agency's novel food safety assessment template shapes regulatory convergence with FDA-USDA frameworks. Co-located production and pilot kitchen facilities enable direct procurement relationships with hospital networks and fine-dining groups.
Israel
Scaffold-based steak cultivation advances through research clusters in Tel Aviv and Rehovot, replicating conventional beef sensory profiles. National biotech funding programs support cell line establishment and cleanroom infrastructure deployment. Aleph Farms anchors innovation in three-dimensional tissue engineering without slaughter-based supply chains.
Netherlands
Maastricht hosts Europe's largest dedicated cultured-meat research infrastructure, controlling bioprocess development timelines. EFSA novel food regulations under the General Food Law create harmonized but slower approval pathways across EU member states. Mosa Meat competes through integrated control over stem cell culturing and scaffold-based cultivation protocols.
United Kingdom
London and Cambridge research corridors concentrate cell proliferation expertise and AI-driven tissue modeling capabilities. Post-Brexit regulatory divergence from EU frameworks creates parallel approval pathway complexity for multi-jurisdictional operators. Academic-corporate partnerships feed intellectual property generation for international licensing transactions.
Global Lab-Based Meat Market Competitive Landscape
Biotech-anchored startups and pharmaceutical-adjacent entrants split the market, with venture-backed specialists commanding premium valuations against incumbent protein suppliers diversifying through R&D partnerships. The vendor base concentrates around scaffold-based tissue engineering and bioreactor fermentation modalities. Three archetypes dominate: pure-play cultured meat developers, diversified food conglomerates hedging supply chains, and contract biomanufacturers repurposing pharmaceutical infrastructure. Competitive moves center on regulatory pre-approval positioning and strategic talent acquisition from pharmaceutical fermentation specialists.
Within the pure-play developer tier, Upside Foods and Aleph Farms exemplify geographic clustering around regulatory first-movers. Upside Foods occupies a position anchored to FDA-USDA framework maturation, while Aleph Farms represents Israeli innovation in scaffold-based steak cultivation. Eat Just sits within the diversified technology portfolio archetype, leveraging cross-category cell culture expertise.
| Leading Market Players |
|---|
| Upside Foods |
| Eat Just |
| Aleph Farms |
| Mosa Meat |
| Meatable |
| Believer Meats |
| Finless Foods |
| BlueNalu |
| Future Meat Technologies |
| Others |
Supply & Pricing Matrix
Serum-free media cost volatility determines both tier spreads between pharmaceutical-grade and food-grade bioreactor outputs and the geographic clustering of production capacity around growth factor manufacturing hubs. This input concentration forces Singaporean and United States operators to absorb margin compression or pass through recombinant protein price swings to foodservice buyers.
Pricing Analysis
Singapore commands premium positioning over United States and Netherlands production due to first-mover regulatory scarcity and co-located pilot kitchen facilities. Three-tier pricing structure across premium, standard, and economy levels separates scaffold-based steak from bioreactor poultry and cell proliferation inputs. Pricing pressure stems from growth factor recombinant protein demand competing with pharmaceutical sector procurement. Institutional dining buyers exhibit lowest price sensitivity due to government-backed procurement programs, while meat processors negotiating blended product lines drive hardest bargain.
Supply Chain Analysis
German and Swiss stainless-steel vessel manufacturers hold captive capacity for pharmaceutical-grade bioreactor installations, constraining facility buildout velocity for foodservice operators. Production draws from Singapore, United States, and Israel for regulatory-first-mover advantages, with Netherlands anchoring European research infrastructure. Raw material dependencies center on recombinant growth factors, edible scaffold polymers, and cell line media formulations. Single-source vulnerability concentrates in German bioreactor equipment lead times. Distribution runs through direct bilateral agreements between bioreactor operators and institutional foodservice buyers, bypassing commodity protein distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across FDA-USDA, Singapore Food Agency, and EFSA frameworks creates white-space opportunities for operators mastering multi-jurisdictional compliance. Foodservice channel demand pull from hospital networks and fine-dining groups fragments procurement into niche segments.
For Market Incumbents: Entrench regulatory pre-approval positioning through sustained FDA-USDA dialogue and Singapore Food Agency license maintenance. Cell line bioprocess engineering talent scarcity threatens production scaling timelines; secure pharmaceutical fermentation specialist compensation packages before venture-backed startups drain available labor pools. Backward integration into growth factor recombinant protein production reduces serum-free media cost exposure. For New Entrants and Emerging Players: European Union market underpenetration offers lowest competitive density despite EFSA novel food pathway duration extending twenty-four to thirty-six months. Cultured seafood category whitespace presents fastest consumer acceptance trajectory given ocean sustainability concerns. Target institutional dining procurement through government-backed biotech park co-location, mirroring Singaporean hospital network direct sourcing models. For Investors and Strategic Acquirers: The market sits at a regulatory-template-consolidation phase that favors pure-play developers with existing FDA-USDA pre-market consultations over diversified food conglomerates. Five-to-ten year viability hinges on which jurisdiction achieves scalable approval templates first. Acquisition target archetype: scaffold-based tissue engineering specialists with cleanroom infrastructure deployed. Monitor Singapore Food Agency licensing velocity as inflection indicator for capital deployment concentration.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Pre-Approval Positioning | FDA-USDA joint framework maturation unlocks institutional foodservice procurement from federal contractors. |
| Scaffold-Based Steak Cultivation Scale-Up | Israeli and Dutch research clusters advance three-dimensional tissue engineering for premium foodservice positioning. |
| Serum-Free Media Backward Integration | In-house growth factor production insulates margins from pharmaceutical sector demand competition. |
| Continuous Perfusion Bioprocessing Adoption | Pharmaceutical-grade facility retrofitting compresses unit economics while demanding new workforce competencies. |
| Cultured Seafood Category Entry | Ocean sustainability concerns drive faster consumer acceptance for tuna and salmon analogues versus beef. |
Research Methodology
Desk research of regulatory filing databases, patent registries, and foodservice procurement records preceded structured interviews with bioreactor operations directors, scaffold materials scientists, Singapore Food Agency licensing officers, and institutional dining procurement managers. Secondary validation drew from FDA pre-market consultation filings, Singapore Food Agency novel food safety assessments, EFSA scientific opinions, and pharmaceutical-grade equipment manufacturer order backlogs. Bottom-up facility capacity modeling triangulated against top-down foodservice channel demand estimates.
Assumptions held fixed include regulatory pathway durations by jurisdiction, recombinant growth factor pricing indexed to pharmaceutical sector demand, and foodservice operator pilot program expansion rates. Variables tested across the analysis window encompassed EFSA harmonization acceleration, continuous perfusion bioprocessing adoption curves, and 3D bioprinting precision marbling cost trajectories. CAGRs derived from segmented bioreactor output projections by protein species, technology modality, and channel concentration. Industry-specific inputs included cell doubling time differentials between poultry and beef lines, and scaffold polymer degradation rates affecting shelf-life economics.
Practitioners should monitor Singapore Food Agency licensing velocity, FDA-USDA framework clarification announcements, and German bioreactor equipment lead time extensions for early signals requiring forecast revision. Regulatory rejection events in any first-mover jurisdiction, breakthroughs in plant-based growth factor alternatives, or major foodservice operator pilot program cancellations would materially alter trajectory. Quarterly review of Singaporean biotech park occupancy rates, United States federal contractor procurement RFP releases, and EFSA novel food queue processing speeds is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Shark Meat Market
Meat Products
Animal Protein Market
Meat Products
Canned Beef Market
Meat Products
Global Edible Meat Market
Meat Products
North America Edible Meat Market
Meat Products
Germany Poultry Meat Market
Meat Products
Canned Pork Market
Meat Products
Grass Fed Beef Market
Meat Products
Global Canned Meat Market
Meat Products
GCC Edible Meat Market
Meat Products
United States Processed Pork Meat Market
Meat Products
Non-Veg Rte and Rtc Market
Meat Products
Smokehouse Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
United States Poultry Meat Market