
 Meat Paste Market | 2026-2036
Meat Paste Market Size, Share, and Industry Trends Forecast 2026-2036
Meat Paste Market Foresight
The gap between premium artisanal pastes and commodity bulk supply is recalibrating procurement strategies across the value chain. Hormel Foods Corporation leverages its refrigerated logistics network to dominate branded paste distribution in North American retail. Tyson Foods, Inc. anchors its position through backward integration into poultry rendering, securing captive supply for chicken paste output.
Meat paste consists of finely comminuted muscle tissue, fat, and functional binders processed to a spreadable consistency, typically containing 60-85% meat protein and stabilized through thermal treatment or fermentation. Manufacturers produce beef paste, chicken paste, pork paste, and fish paste, with fish paste commanding premium positioning in East Asian export channels due to surimi-grade raw material requirements. Pouch packaging is displacing rigid formats in food service channels where portion control and cold-chain efficiency determine contract awards. Ready-to-eat meals represent the fastest-growing application as meal-kit assemblers specify paste formats with extended ambient stability.
The USDA's Food Safety and Inspection Service mandates pathogen reduction performance standards for thermally processed meat products, while the FDA oversees labeling claims under FSMA preventive controls. The EU's REACH framework and EFSA additive evaluations constrain preservative portfolios, compelling reformulation toward cultured celery powder and fermented sugar vinegars. Stakeholders must monitor divergence between US and European maximum residue limits for veterinary drugs in rendered proteins, as this split threatens harmonized export specifications.
Market Dynamics
The EU's Farm to Fork Strategy is compressing formulation timelines as manufacturers replace synthetic preservatives with fermented sugar vinegars and cultured celery powder ahead of disclosure mandate deadlines.
Growth Catalysts
- Clean-label pet food demand:Protein-rich pastes command premium placement in companion animal nutrition as owners scrutinize ingredient panels for synthetic additives.
- REACH additive restrictions:European manufacturers accelerate reformulation investments to comply with EFSA preservative evaluations, opening contract opportunities for natural stabilizer suppliers.
- Meal-kit assembly specifications:Ready-to-eat meal assemblers specify paste formats with extended ambient stability, pulling volume from refrigerated-only distribution.
Market Restraints
- Rendered protein input volatility:Poultry and beef rendering output fluctuates with slaughter rates, compressing margin predictability for paste processors without captive supply.
- Brazilian supply concentration:Integrated chains anchored by JBS S.A. and BRF S.A. control upstream raw material flows, limiting second-tier processor bargaining position.
- Veterinary drug residue divergence:Split maximum residue limits between US and European specifications threaten harmonized export certification for rendered protein suppliers.
Strategic Opportunities
- East Asian surimi-grade channels:Fish paste commands premium positioning in Japan and South Korea where surimi-grade raw material requirements filter out commodity competitors.
- Pouch packaging displacement:Food service channels award contracts based on portion control and cold-chain efficiency, favoring flexible formats over rigid containers.
- Fermentation technology convergence:Combining traditional fermentation with precision temperature control enables clean-label stabilization without synthetic preservatives.
Industry Challenges
- Refrigerated logistics capex intensity:Branded paste distribution requires continuous cold-chain infrastructure investment to maintain pathogen reduction performance standards.
- Dual jurisdiction compliance timelines:Simultaneous USDA FSIS thermal processing validation and FDA FSMA preventive control documentation stretches quality assurance bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat Paste Market |
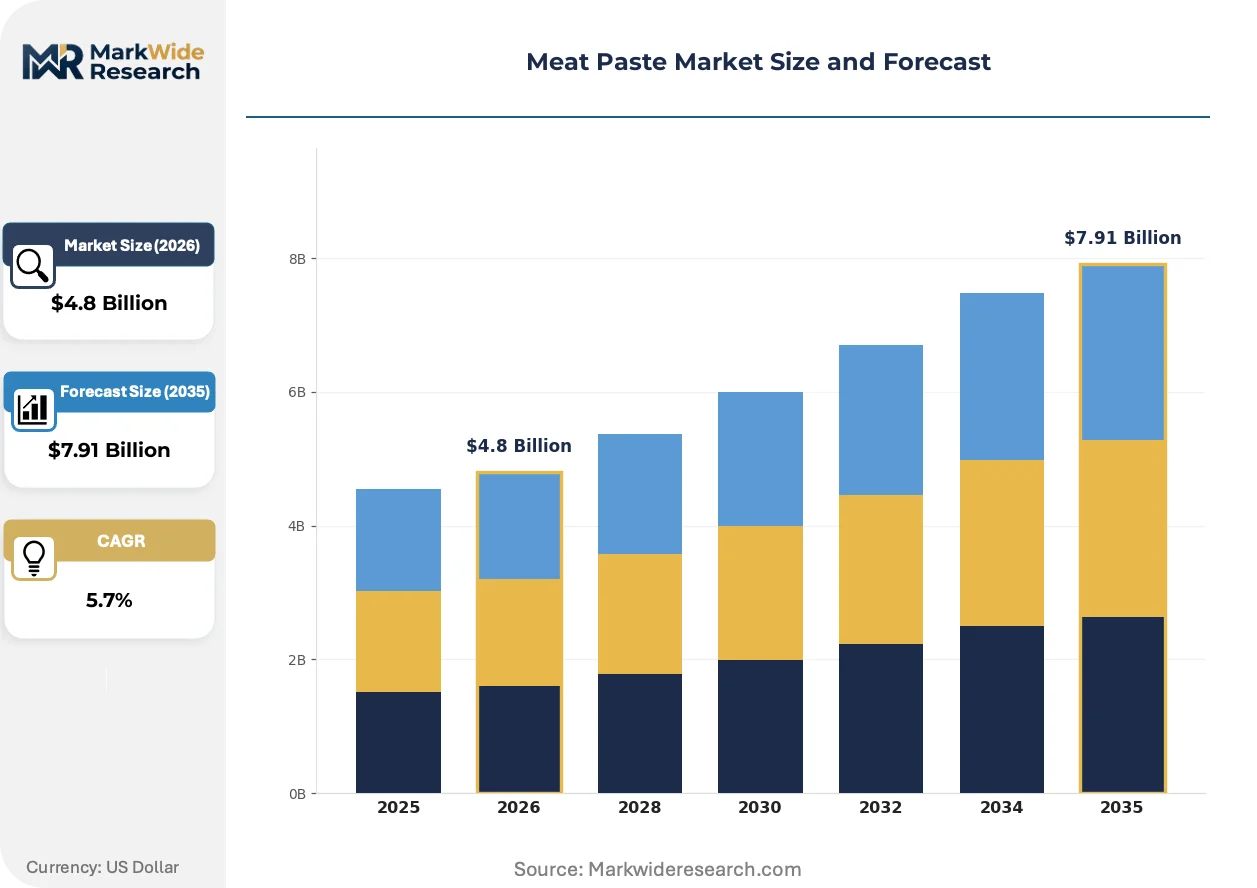
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef Paste, Chicken Paste, Pork Paste, Fish Paste Packaging Type: Tubs, Pouches, Cans, Jars Sales Channel: Supermarkets, Online Retail, Specialty Stores, Food Service Application: Ready-to-Eat Meals, Sandwich Spreads, Cooking Ingredients, Snacks |
| Companies Covered | Hormel Foods Corporation, Tyson Foods, Inc., Cargill, JBS S.A., Maple Leaf Foods, BRF S.A., Marfrig Global Foods S.A., NH Foods Ltd., Danish Crown, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat Paste Market Shifts & Advancements
Formulation science and packaging engineering are converging to extend shelf stability while eliminating synthetic additives from meat paste compositions.
High-pressure processing technology is absorbing thermal treatment functions in premium paste production. Refrigerated meal-kit suppliers adopt HPP-treated chicken and beef pastes to achieve pathogen reduction without flavor degradation from extended heat exposure. This absorption of thermal functions by non-thermal methods is compressing the traditional retort equipment installed base.
EFSA additive evaluations under REACH are narrowing preservative portfolios to fermentation-derived alternatives. European paste manufacturers face reformulation deadlines as synthetic nitrate replacements gain regulatory preference. Pet food exporters to the EU are most affected, accelerating supplier audits for cultured celery powder and fermented vinegar sources.
Food service procurement now weights cold-chain efficiency metrics above unit price in contract awards. Pouch formats displace cans and rigid trays in institutional catering where portion control and storage density determine total cost of ownership. Brazil and Thailand exhibit the fastest migration toward flexible packaging specifications.
Meat Paste Market Segmentation
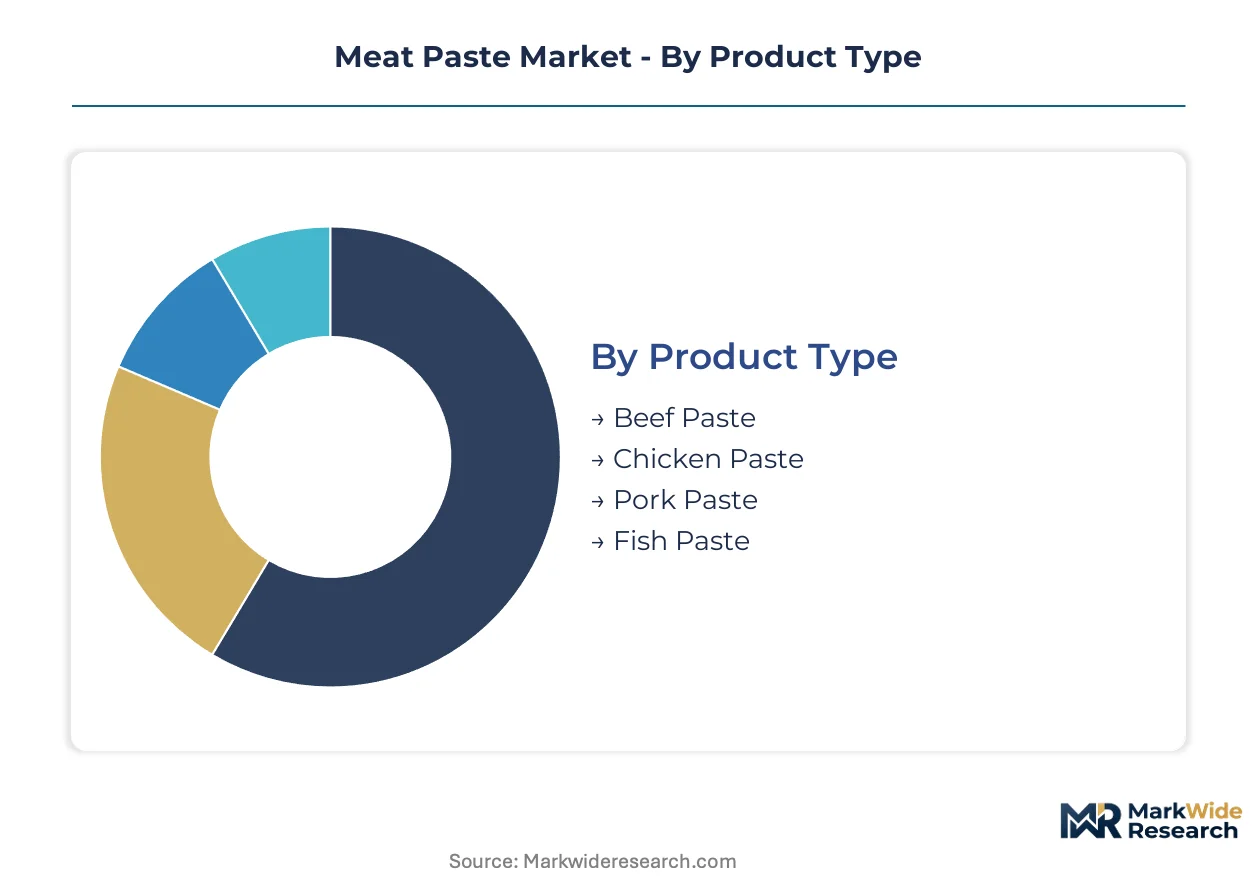
Meat paste procurement strategies diverge sharply between commodity bulk supply and premium artisanal formats, with product type and packaging choices determining margin structure and regulatory exposure across the value chain. Segment boundaries are blurring as meal-kit assemblers and pet food manufacturers impose cross-cutting specifications on protein content, shelf stability, and clean-label credentials.
Product Type:
Volume concentration favors poultry and beef derivatives, while premium positioning clusters around fish paste where surimi-grade raw material requirements create supply scarcity.
- Beef Paste:Finely comminuted bovine muscle tissue with 60-75% protein content, stabilized through thermal treatment. Demand concentrates in Brazilian integrated supply chains where JBS S.A. and BRF S.A. control upstream rendering output, though veterinary drug residue divergence between US and EU specifications complicates export certification.
- Chicken Paste:Poultry-derived paste with lighter flavor profile and lower fat content, typically 65-80% protein. Tyson Foods anchors market position through backward integration into captive poultry rendering, securing input cost predictability that second-tier processors lack.
- Pork Paste:Swine-based formulation common in European and Asian food service channels, subject to stricter EFSA additive evaluations under REACH frameworks.
- Fish Paste:Surimi-grade raw material paste commanding premium positioning in Japan and South Korea export channels, with fermentation-derived stabilization replacing synthetic preservatives under clean-label mandates.
Mature deployment sits with beef and chicken pastes in commodity food manufacturing. Newer deployment is concentrated in fish paste where surimi-grade certification requirements filter out volume competitors.
Packaging Type:
Cold-chain efficiency and portion control economics are driving format substitution, with flexible packaging displacing rigid containers in institutional procurement.
- Pouches:Flexible multilayer films enabling portion control and storage density optimization. Food service channels in Brazil and Thailand award contracts based on total cost of ownership metrics favoring pouch formats over rigid alternatives.
- Tubs:Rigid plastic containers dominating North American retail distribution where Hormel Foods leverages refrigerated logistics networks for branded paste placement.
- Cans:Metal containers retaining position in ambient-stable product lines, though retort equipment installed base faces compression from high-pressure processing technology absorption.
- Jars:Glass packaging persisting in premium artisanal segments where visual product presentation supports shelf placement negotiations.
Established infrastructure sits with tubs and cans in mature retail channels. Accelerating migration is occurring in pouches where cold-chain efficiency determines contract awards.
Sales Channel:
Procurement authority is fragmenting across direct food service contracts and platform-mediated retail, with specialty stores retaining influence in premium positioning.
- Food Service:Direct institutional procurement by meal-kit assemblers and catering operators specifying paste formats with extended ambient stability, pulling volume from refrigerated-only distribution networks.
- Supermarkets:Traditional retail channel where branded paste placement depends on refrigerated logistics capex intensity and pathogen reduction performance documentation.
- Online Retail:Platform-mediated sales expanding in companion animal nutrition segments where pet owners scrutinize ingredient panels and additive disclosures.
- Specialty Stores:Curated retail environment for fermented and clean-label pastes, particularly in EU markets where Farm to Fork Strategy disclosure mandates accelerate reformulation investments.
Concentrated volume flows through food service procurement. Expanding most quickly is online retail where direct-to-consumer transparency requirements reshape supplier qualification.
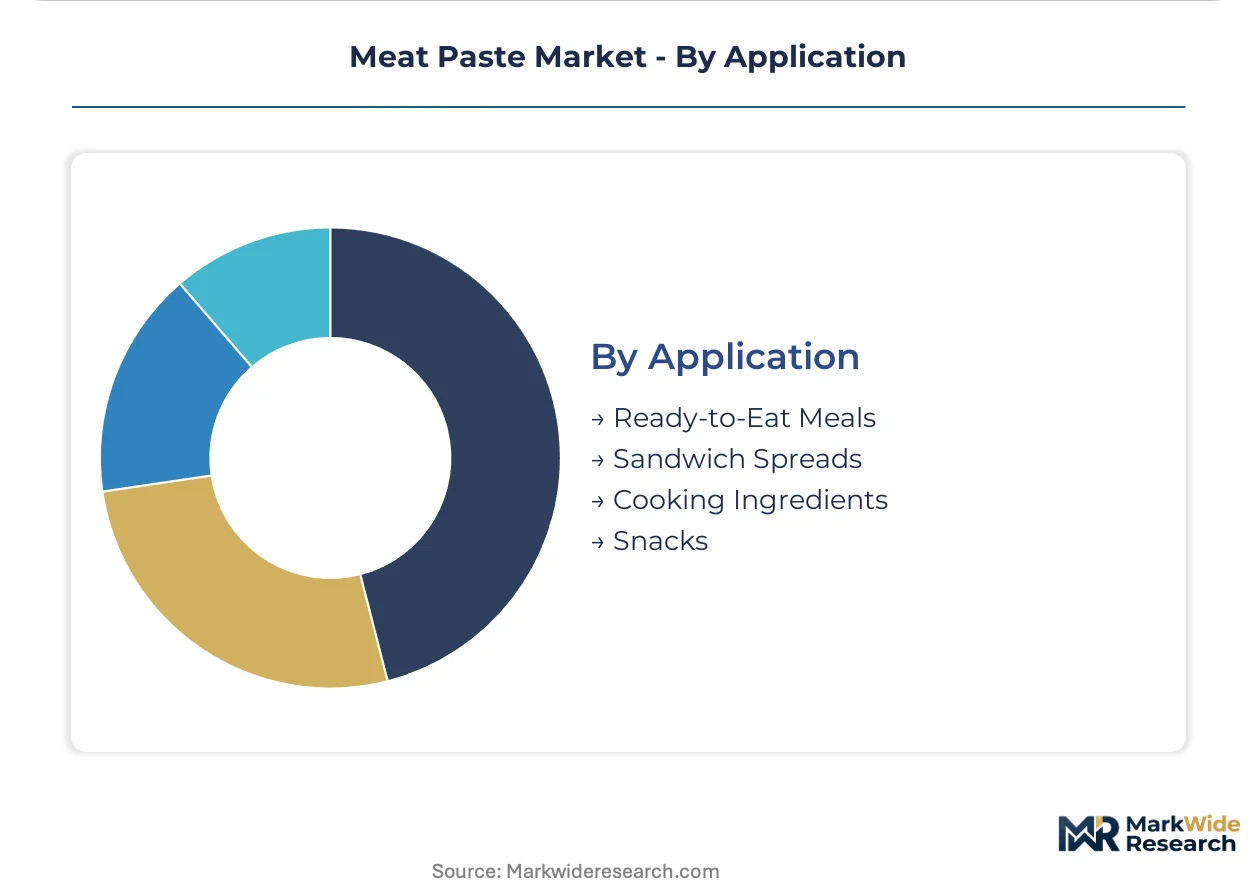
Application:
End-use specifications are converging around shelf stability and protein density, with ready-to-eat formats imposing the most stringent formulation constraints.
- Ready-to-Eat Meals:Paste formats specified by meal-kit assemblers requiring extended ambient stability without synthetic preservative portfolios, driving adoption of high-pressure processing and fermentation-derived stabilization.
- Sandwich Spreads:Consumer-facing applications where clean-label credentials and flavor profile consistency determine repeat purchase rates.
- Cooking Ingredients:Industrial and food service input applications where protein content standardization and batch-to-batch consistency outweigh premium positioning.
- Snacks:Emerging application in protein-fortified formats, particularly in pet food segments where protein-rich pastes command premium placement.
Established demand sits with cooking ingredients in industrial procurement. Steepest expansion trajectory is occurring in ready-to-eat meals where ambient stability specifications compress formulation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors meat paste production capacity through integrated slaughter-to-paste facilities operated by JBS S.A. and BRF S.A., with refrigerated corridors extending to Santos port for East Asian export. Regulatory divergence between veterinary drug residue limits complicates harmonized certification for rendered protein suppliers serving multiple jurisdictions.
United States
USDA FSIS thermal processing standards and FDA FSMA preventive controls create dual compliance timelines for paste manufacturers. The USDA mandates pathogen reduction performance standards for thermally processed meat products. Tyson Foods anchors poultry paste supply through captive rendering operations in Arkansas and North Carolina processing corridors.
Brazil
JBS S.A. and BRF S.A. control upstream raw material flows from slaughtering through paste production in integrated supply chains. ANVISA veterinary drug residue monitoring intersects with EU export certification requirements. São Paulo state concentrates rendering capacity with cold-chain logistics radiating toward Santos port for surimi-grade fish paste export to Japan.
Germany
EFSA additive evaluations under REACH frameworks compel reformulation toward fermented sugar vinegars and cultured celery powder. The EU Farm to Fork Strategy disclosure mandates accelerate clean-label investments ahead of deadline. Lower Saxony hosts pork paste processing clusters serving food service channels across Northern Europe.
Japan
Surimi-grade fish paste commands premium positioning where raw material certification filters out commodity competitors. METI standards for fermentation-derived stabilization align with clean-label import requirements. Chubu region around Nagoya maintains traditional fish paste production with precision temperature control technology adoption.
Thailand
Pouch packaging migration accelerates fastest in institutional catering procurement where cold-chain efficiency determines contract awards. Fish paste exports to Japan and South Korea face surimi-grade raw material requirements. Bangkok metropolitan area concentrates flexible packaging conversion for regional food service supply.
Meat Paste Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across tiered market positions. Integrated meatpackers with captive rendering operations command input cost predictability that independent paste processors cannot replicate. Three archetypes dominate: slaughter-integrated giants controlling upstream protein flows, refrigerated logistics specialists dominating branded retail distribution, and fermentation-technology specialists serving clean-label reformulation demand. Competitive moves concentrate on backward integration into rendering assets and high-pressure processing technology licensing for premium shelf-stable formats.
Among Brazil-based integrated processors, JBS S.A. and BRF S.A. exemplify the slaughter-to-paste archetype through São Paulo corridor dominance. Hormel Foods Corporation occupies a position within the refrigerated logistics tier, leveraging cold-chain infrastructure for North American retail placement. Tyson Foods, Inc. represents backward integration strategy through captive poultry rendering securing input supply for chicken paste output.
| Leading Market Players |
|---|
| Hormel Foods Corporation |
| Tyson Foods, Inc. |
| Cargill |
| JBS S.A. |
| Maple Leaf Foods |
| BRF S.A. |
| Marfrig Global Foods S.A. |
| NH Foods Ltd. |
| Danish Crown |
| Others |
Supply & Pricing Matrix
High-pressure processing technology adoption simultaneously compresses retort equipment utilization and concentrates margin capture among technology licensors, reshaping cost economics while slaughter-integrated giants tighten grip on upstream protein flows. Cold-chain efficiency metrics now dominate food service procurement awards, translating pouch packaging conversion into pricing power for logistics-capable processors.
Pricing Analysis
Surimi-grade certification anchors value-based pricing for fish paste exports to Japan and South Korea, where raw material quality filters out commodity competitors. Three-tier pricing structure across premium artisanal, standard food service, and economy bulk supply reflects protein content standardization and fermentation-derived stabilization investment. Pricing pressure stems from rendered protein input volatility as slaughter rate fluctuations compress margin predictability for processors lacking captive rendering. Food service channels exhibit highest price sensitivity due to total cost of ownership calculations, while pet food manufacturers demonstrate lowest sensitivity given clean-label premium capture.
Supply Chain Analysis
Dual-sourcing requirements from EU meal-kit assemblers mandate multi-supplier qualification for fermented stabilizer inputs, complicating procurement for second-tier processors. Supply concentrates in Brazil, Thailand, and Germany, with São Paulo corridor dominance by JBS S.A. and BRF S.A. controlling upstream flows. Raw material dependencies center on poultry rendering output, surimi-grade fish raw material, and cultured celery powder for nitrate replacement. Single-source vulnerability runs through Brazilian integrated chains for beef paste inputs. Distribution runs through refrigerated corridors radiating from Santos port and North American cold-chain networks anchored by Hormel Foods.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
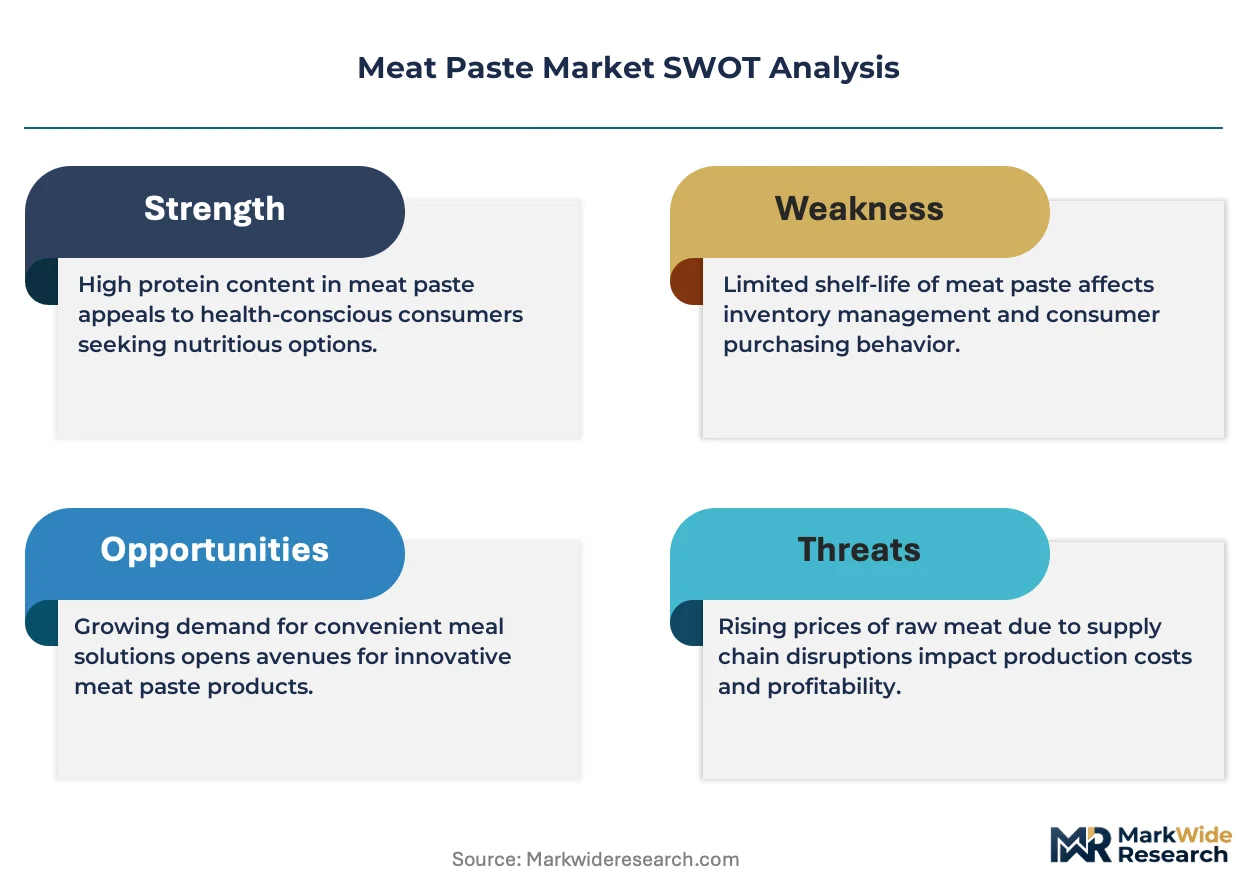
Slaughter capacity constraints in Brazil prop pricing power for integrated processors, creating supply-constrained conditions that favor asset-heavy incumbents with captive rendering operations.
For Market Incumbents: Acquire high-pressure processing technology licenses to defend shelf-stable positioning against thermal treatment displacement. Secure backward integration into poultry rendering assets in Arkansas and North Carolina corridors to neutralize Tyson Foods' input cost advantage. Expand pouch packaging conversion capacity in Thailand and Brazil to capture food service contract awards where cold-chain efficiency determines procurement outcomes. For New Entrants and Emerging Players: Direct-to-veterinarian digital channels offer white-space entry into companion animal nutrition segments where pet owners scrutinize ingredient panels for synthetic additives. Target specialty store distribution in EU markets where Farm to Fork Strategy disclosure mandates accelerate clean-label reformulation demand. Pursue fermentation-technology licensing partnerships to bypass capital-intensive thermal processing infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by slaughter-integrated giants seeking rendering capacity expansion. Long-term viability favors processors with dual USDA FSIS and FDA FSMA compliance documentation spanning the analysis window. Acquisition target archetype: mid-scale fermentation-technology specialists with EFSA-validated stabilizer portfolios. Watch for divergence in US-EU veterinary drug residue limits as inflection signal for rendered protein export certification disruption.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Technology Licensing | Enables pathogen reduction without flavor degradation from extended heat exposure, compressing retort equipment demand. |
| Backward Integration into Rendering Assets | Secures captive poultry and beef protein supply, insulating margin predictability from slaughter rate volatility. |
| Fermentation-Derived Stabilizer Certification | Aligns with EFSA additive evaluations under REACH, qualifying suppliers for EU pet food export contracts. |
| Pouch Packaging Capacity Expansion | Captures food service procurement awards in Brazil and Thailand where cold-chain efficiency determines contract outcomes. |
| Dual Jurisdiction Compliance Investment | Simultaneous USDA FSIS thermal processing validation and FDA FSMA preventive control documentation stretches quality assurance bandwidth but secures market access. |
Research Methodology
USDA FSIS regulatory filings, ANVISA veterinary drug residue monitoring records, and EFSA additive evaluation databases formed the secondary backbone, supplemented by primary interviews with pet food formulation scientists, refrigerated logistics operators, and food service procurement directors. Bottom-up and top-down triangulation validated volume estimates across product type, packaging format, and application segments.
Bottom-up modeling anchored forecasts in segment-level protein content specifications and packaging conversion rates, while top-down cross-checks incorporated macro protein demand indicators. Segmentation dimensions included product type, packaging technology, sales channel, and clean-label certification status. CAGRs were derived from trend extrapolation of pouch displacement rates and fermentation technology adoption curves across the projection horizon. Industry-specific inputs encompassed rendering capacity utilization data and meal-kit assembler specification sheets.
Inputs from USDA and EFSA regulatory databases were available through the study window; gaps in real-time slaughter rate data introduce uncertainty bands around rendered protein supply projections. Forecasts reflect documented assumptions regarding REACH compliance timelines and Farm to Fork Strategy implementation schedules. Deviation in US-EU veterinary drug residue limit harmonization negotiations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Low Fat Beef Market
Meat Products
Global Lab-Based Meat Market
Meat Products
Organic Meat Products Market
Meat Products
United States Red Meat Market
Meat Products
Meat, Poultry and Seafood Market
Meat Products
Asia-Pacific Red Meat Market
Meat Products
Shark Meat Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Mechanically Separated Meat Market
Meat Products
Germany Meat Products Market
Meat Products
Blended Meat Market
Meat Products
Germany Poultry Meat Market
Meat Products
Beef Tallow Market
Meat Products
Chilled Meat Market
Meat Products
Pork Flavors Market
Meat Products
Europe Meat Products Market