
 Europe Building and Construction Sheets Market | 2026-2036
Europe Building and Construction Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Building and Construction Sheets Market Foresight
Multi-source procurement among facade contractors is restructuring supply relationships across the European construction sheet value chain. Kingspan Group plc leverages its insulated panel expertise to dominate specification-driven commercial envelopes. Saint Gobain sustains broad geographic coverage through diversified gypsum and glass-based sheet formats. Tata Steel Europe competes on coated steel sheet systems for industrial roofing across Northern Europe.
Building and construction sheets encompass flat, semi-rigid panel materials engineered from wood composites, mineral binders, or metallic substrates, typically manufactured in thicknesses ranging from 3 mm to 25 mm for structural or finish applications in built environments. These sheets serve as primary substrates for flooring, roofing, wall cladding, and ceiling systems where dimensional stability, fire resistance, or moisture protection are specified. OSB and gypsum board lead volume consumption in residential applications across Europe, while large-format custom panels capture premium margins in commercial facade systems. Plywood maintains entrenched positions in structural flooring, though MDF is displacing traditional materials in interior fit-out segments where surface finish quality drives specification.
The EU Green Deal's embodied carbon thresholds, enforced through national building codes transposing the Energy Performance of Buildings Directive, are mandating Environmental Product Declarations for sheet materials used in public procurement. ECHA's REACH restrictions on formaldehyde emissions from wood-based panels continue tightening compliance costs for OSB and MDF manufacturers serving residential markets. CE marking under the Construction Products Regulation remains the baseline market access requirement, with escalating performance declarations for fire-reaction characteristics. Stakeholders must monitor how the EU's developing carbon border adjustment mechanism reshapes import competitiveness for steel and aluminum sheet products originating outside the European Economic Area.
Market Dynamics
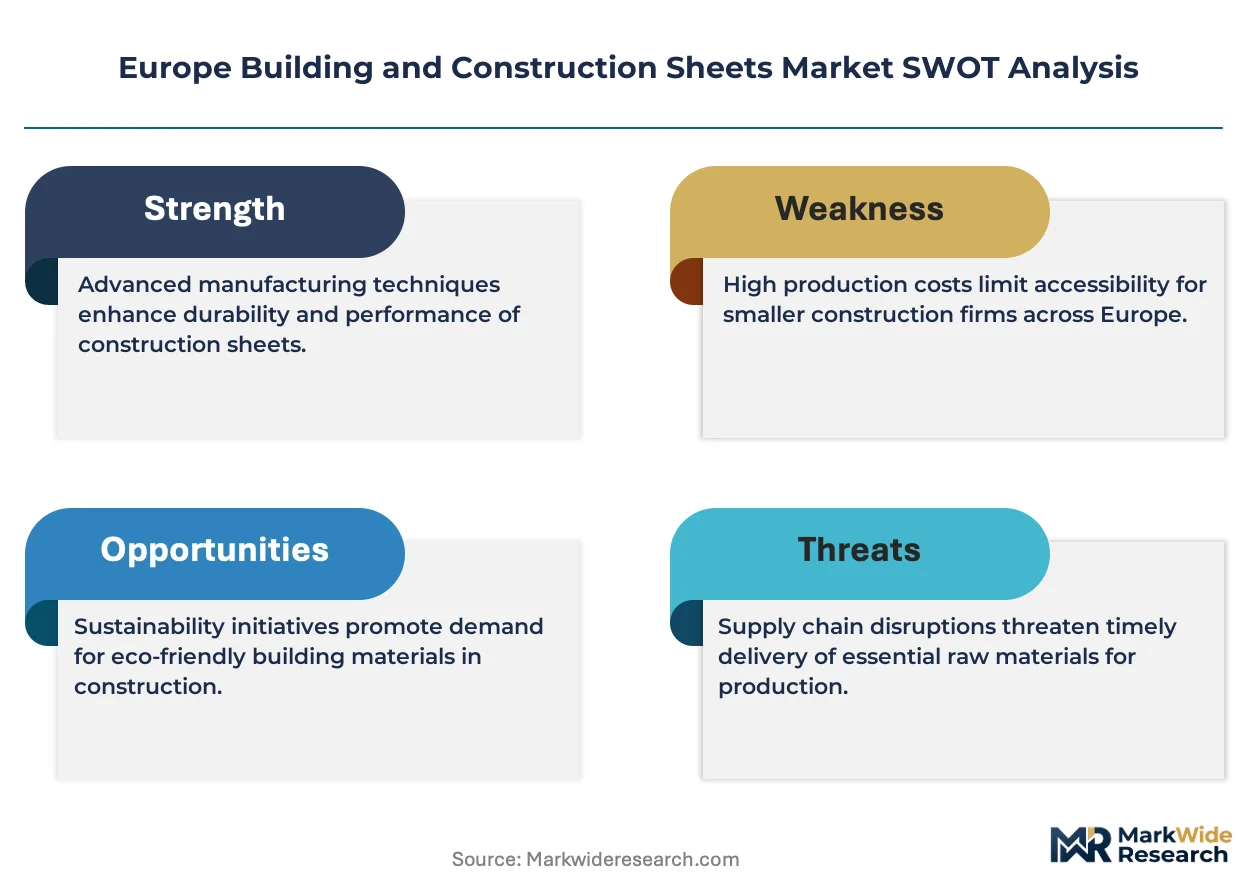
The EU Green Deal's embodied carbon thresholds are forcing material specification shifts across the European construction sheet value chain, with Environmental Product Declarations now mandatory for public procurement and national building codes tightening compliance requirements for wood-based panels and mineral substrates.
Growth Catalysts
- Residential Retrofit Mandates:Germany's building energy efficiency regulations and France's renovation wave programs are accelerating sheet replacement cycles in existing housing stock, particularly for insulation-facing substrates.
- ECHA REACH Formaldehyde Restrictions:Tighter emission limits for OSB and MDF are pushing manufacturers toward low-emission binders and bio-based adhesives, creating premium positioning for compliant producers.
- Urban Density Corridors:Germany's dense metropolitan zones exhibit renovation rates outpacing new construction, concentrating demand for retrofit-compatible sheet formats in Berlin, Munich, and Hamburg.
Market Restraints
- Raw Material Volatility:Softwood fiber and gypsum feedstock costs fluctuate with Nordic forestry harvest cycles and Spanish quarry output, compressing margins for commodity-grade OSB and gypsum board.
- Supply Concentration Risk:Coated steel sheet systems for industrial roofing depend on a limited number of Northern European flat-rolled steel producers, creating vulnerability to energy cost shocks.
- Technical Performance Ceilings:Cross-laminated timber panels face span limitations in commercial mid-rise construction that structural concrete and steel sheets do not encounter.
Strategic Opportunities
- Carbon-Negative Sheet Formats:Hemp-lime and mycelium-based panels align with EU Green Deal circular economy incentives, offering EPD-compliant pathways for public tenders in the Netherlands and Belgium.
- Industrialized Prefabrication:Offsite construction growth in the UK and Scandinavia creates demand for large-format custom panels with pre-integrated MEP routing channels.
- Digital Specification Platforms:BIM-integrated material libraries are compressing the architect-to-contractor information chain, favoring sheet producers with granular EPD data and parametric product models.
Industry Challenges
- Fire-Reaction Certification Timelines:CE marking updates under the Construction Products Regulation require renewed testing for reaction-to-fire classifications, delaying product launches by 8-14 months.
- Skilled Installer Shortages:Specialized facade contractors capable of large-format panel installation remain scarce in Southern European markets, limiting adoption of premium commercial envelope systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Building and Construction Sheets Market |
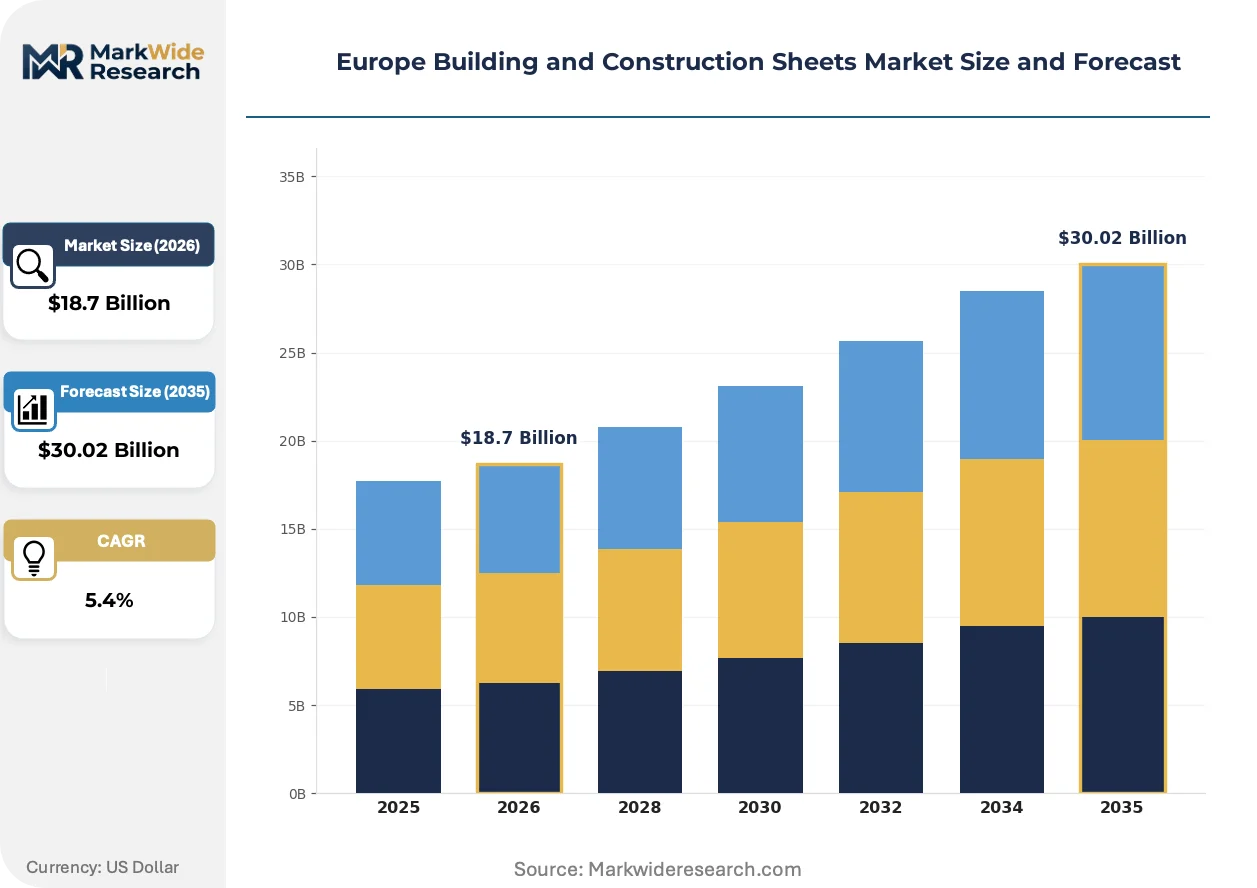
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plywood, Gypsum Board, MDF, OSB End User: Residential, Commercial, Industrial, Institutional Application: Flooring, Roofing, Wall Covering, Ceilings Size: Standard Sheets, Custom Sizes, Large Panels, Small Panels |
| Companies Covered | Paul Bauder GmbH, Kingspan Group plc, Saint Gobain, ArcelorMittal Construction, Tata Steel Europe, Lyondellbasell, Euramax International, Sika AG, James Hardie Industries plc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Building and Construction Sheets Market Shifts & Advancements
Material science advances and digital specification tools are compressing traditional product development cycles, while regulatory pressure on embodied carbon is elevating bio-based and recycled-content sheet formats from niche to mainstream consideration.
Cross-laminated timber panels engineered with fire-resistant surface treatments are converging with hybrid steel-timber structural systems, enabling mid-rise commercial construction in Scandinavia and Austria to reduce embodied carbon without sacrificing span capabilities or code compliance timelines.
REACH restrictions on formaldehyde emissions from wood-based panels are forcing OSB and MDF manufacturers serving residential markets to reformulate binders, with the most affected producers in Central Europe accelerating capital deployment toward bio-based adhesive technologies to maintain specification eligibility.
Architects and facade contractors in Germany and France are consolidating material specifications around fewer, larger-format suppliers capable of delivering comprehensive EPD documentation, compressing the vendor base and elevating procurement decisions toward lifecycle carbon performance rather than first-cost metrics alone.
Europe Building and Construction Sheets Market Segmentation
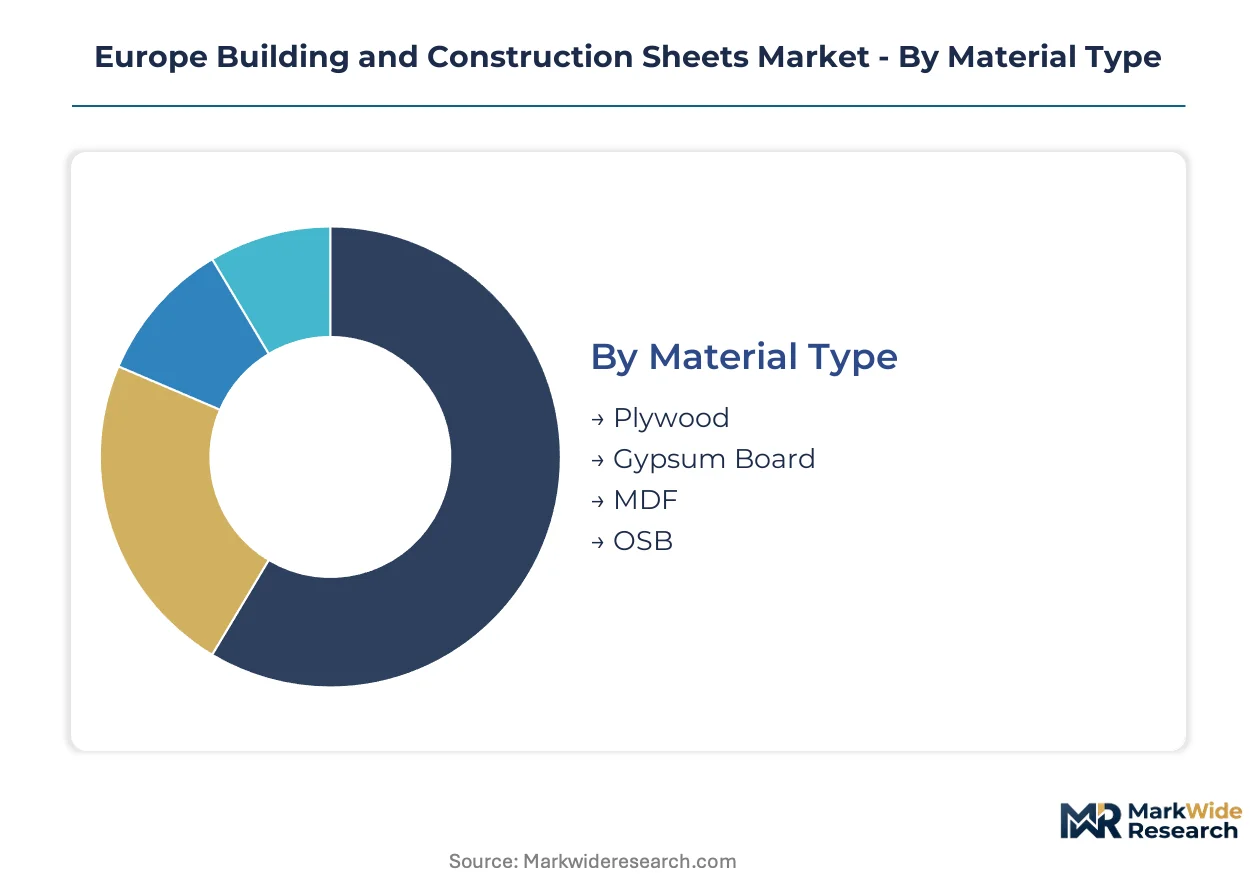
Material specifications across Europe's construction sheet market fragment along performance requirements, regulatory compliance tiers, and installation complexity. Procurement decisions increasingly weight embodied carbon credentials against fire-reaction classifications and moisture resistance ratings.
Material Type:
Supply concentration among Nordic OSB producers and Iberian gypsum processors creates divergent margin structures across substrate categories.
- Plywood:Cross-laminated veneer construction delivers structural load-bearing capacity for flooring and concrete formwork applications. German and Polish housing renovators specify tropical hardwood faces for moisture-critical installations despite EUTR due diligence requirements.
- Gypsum Board:Calcium sulfate dihydrate core with paper facings dominates interior wall and ceiling specifications across France and Italy. French plasterboard installers face tightening waste recovery mandates under extended producer responsibility schemes.
- MDF:Engineered wood fiber panels with synthetic resin binders serve interior fit-out segments requiring smooth surface finishes. REACH formaldehyde restrictions push Central European manufacturers toward bio-based adhesive reformulation.
- OSB:Oriented strand board from compressed wood flakes provides cost-effective structural sheathing. Swedish and Finnish mills control feedstock access through captive forestry assets.
Today's leader: Gypsum Board. Tomorrow's challenger: OSB.
End User:
Application complexity and specification authority concentrate demand differently across customer types, with public procurement rules altering competitive dynamics.
- Residential:Single-family and multi-family housing drives volume consumption of standard-format OSB and gypsum board across Germany's renovation corridors. Energy efficiency retrofit mandates accelerate replacement cycles for insulation-facing substrates.
- Commercial:Office, retail, and hospitality developments specify large-format custom panels with integrated MEP routing. UK and Scandinavian offsite construction growth favors prefabricated envelope systems.
- Industrial:Manufacturing facilities and warehouses require coated steel roofing systems with span capabilities exceeding wood-based alternatives. Northern European flat-rolled steel producers concentrate supply.
- Institutional:Schools, hospitals, and public buildings face strictest EPD and fire-reaction requirements under national building codes transposing the Energy Performance of Buildings Directive.
Residential commands current volume. Commercial offers steepest expansion trajectory through specification upgrading.
Application:
Performance thresholds and installation skill requirements segment the market by technical complexity and contractor specialization.
- Flooring:Structural plywood and OSB subflooring must meet EN 12871 load-bearing standards. German timber-frame builders favor moisture-resistant OSB3 for ground-floor installations.
- Roofing:Industrial metal roofing and tile underlayment demand distinct material properties. Coated steel systems from Tata Steel Europe and ArcelorMittal dominate Northern European industrial envelopes.
- Wall Covering:Gypsum board and cement-bonded particleboard serve interior and exterior cladding respectively. French facade contractors consolidate specifications around fewer suppliers with comprehensive EPD documentation.
- Ceilings:Acoustic performance and fire resistance drive specification toward mineral fiber and gypsum systems. Healthcare and education projects in Belgium and the Netherlands require enhanced sound absorption ratings.
Wall Covering generates broadest material diversity. Flooring maintains most entrenched specification habits.
Size:
Manufacturing scale economies and logistics constraints shape competitive positioning across format categories.
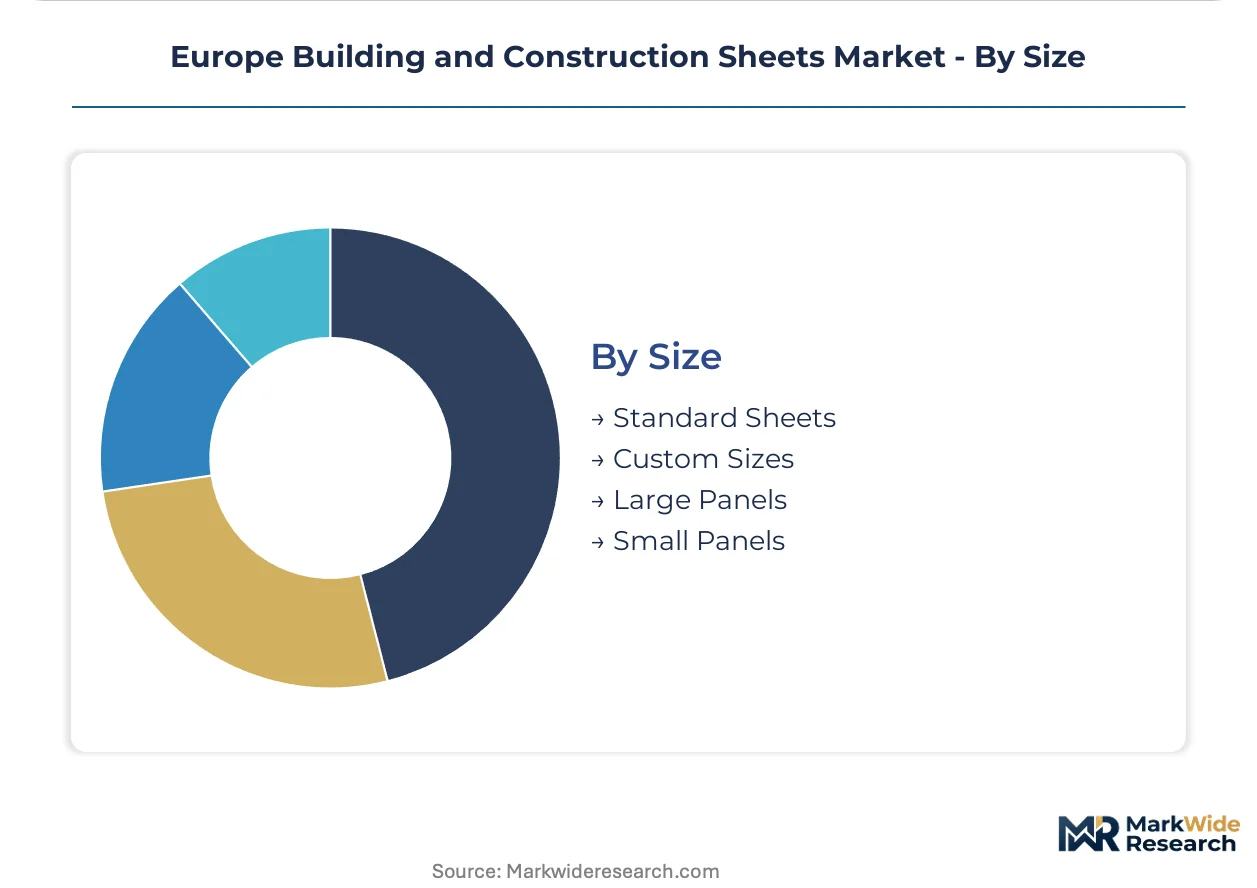
- Standard Sheets:1,200 mm by 2,400 mm dimensions dominate commodity gypsum and wood-panel distribution through builder merchants. High-volume production lines in Spain and Germany serve this segment.
- Custom Sizes:Project-specific cutting reduces on-site waste and labor for commercial developments. CNC-equipped fabricators in Austria and Switzerland capture premium positioning.
- Large Panels:Cross-laminated timber and insulated metal panels enable rapid envelope assembly for mid-rise construction. Scandinavian industrialized prefabrication growth expands addressable demand.
- Small Panels:Repair, renovation, and DIY channels consume cut-to-size formats through retail distribution. German home improvement chains stock extensive small-format inventories.
Standard Sheets anchor current production volumes. Large Panels are gaining share fastest through offsite construction adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory cost differentials across EU member states are redirecting production investment toward jurisdictions with streamlined permitting for low-carbon sheet manufacturing. The EU Green Deal's uniform embodied carbon thresholds mask significant national variation in enforcement timelines and subsidy intensity.
Germany
Building energy efficiency regulations are accelerating sheet replacement cycles in existing housing stock. The national building code transposes Energy Performance of Buildings Directive requirements with strict EPD mandates for public procurement. Dense urban corridors in Berlin, Munich, and Hamburg concentrate renovation demand where rates outpace new construction.
France
The renovation wave program drives volume consumption of gypsum board and insulation-facing substrates. Extended producer responsibility schemes under national waste recovery mandates tighten compliance for plasterboard installers. Industrial clusters around Paris and Lyon consolidate specification authority for large-format commercial envelope systems.
United Kingdom
Offsite construction growth creates demand for prefabricated panels with pre-integrated MEP routing channels. National building regulations increasingly reference embodied carbon metrics for public sector procurement. Manufacturing concentration in the Midlands and Northern England serves modular construction hubs.
Sweden
Industrialized prefabrication expands addressable demand for cross-laminated timber and large-format structural panels. REACH formaldehyde restrictions push manufacturers toward bio-based adhesive technologies. Forestry-integrated production in Norrland and Dalarna secures captive softwood fiber supply for OSB mills.
Netherlands
Carbon-negative sheet formats align with national circular economy incentives for public tenders. EPD-compliant pathways for hemp-lime and mycelium-based panels gain specification traction. Randstad metropolitan demand concentrates renovation activity in Amsterdam, Rotterdam, and The Hague corridors.
Europe Building and Construction Sheets Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue carbon-negative and bio-based material niches. The market exhibits moderate consolidation among insulated panel and coated steel specialists, with fragmented competition in commodity gypsum and wood-based substrates. Three archetypes dominate: forestry-integrated manufacturers with captive fiber supply, mineral substrate processors with quarry proximity, and metal systems fabricators with coating technology differentiation. Capacity expansion and strategic partnerships represent the dominant competitive moves, as players secure EPD documentation and BIM-integrated specification platforms.
Among diversified building materials groups, Saint Gobain and Kingspan Group plc exemplify scale-driven envelope specialists with broad geographic coverage. Tata Steel Europe anchors the coated steel systems segment for industrial roofing applications. These three occupy positions across the premium specification tier where comprehensive EPD data and fire-reaction certifications determine procurement eligibility.
| Leading Market Players |
|---|
| Paul Bauder GmbH |
| Kingspan Group plc |
| Saint Gobain |
| ArcelorMittal Construction |
| Tata Steel Europe |
| Lyondellbasell |
| Euramax International |
| Sika AG |
| James Hardie Industries plc |
| Others |
Supply & Pricing Matrix
EU Green Deal embodied carbon mandates for public procurement are forcing facade contractors and developers to source EPD-compliant sheet materials exclusively from certified producers, compressing the supplier base and elevating pricing power among documentation-ready manufacturers in Germany and France.
Pricing Analysis
Input-cost pass-through from Nordic softwood fiber and Spanish gypsum feedstock runs through three-tier pricing structure across premium, standard, and economy levels. Premium positioning accrues to producers with comprehensive EPD documentation and REACH-compliant low-emission binders, while commodity-grade OSB faces acute price sensitivity among German residential renovators. Margins are tightening due to energy cost volatility at Northern European flat-rolled steel mills serving industrial roofing systems.
Supply Chain Analysis
Local-content rules under France's extended producer responsibility schemes and Germany's national building code transpositions are reshaping sourcing toward domestic gypsum processors and forestry-integrated OSB mills. Supply concentrates in Sweden, Finland, and Spain for wood-based panels and mineral substrates, with captive forestry assets and quarry proximity anchoring cost positions. Single-source vulnerability persists for coated steel sheet systems dependent on ArcelorMittal and Tata Steel Europe. Distribution runs through builder merchants in Germany and France, with direct-to-contractor channels gaining share for large-format commercial envelope systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on the shift from commodity-grade OSB toward EPD-certified premium formats as EU Green Deal procurement rules harden specification requirements.
For Market Incumbents: Anchor specification authority through BIM-integrated product libraries with granular embodied carbon data. Invest in captive forestry assets or long-term fiber supply agreements to defend against Nordic harvest cycle volatility. Deepen backward integration into bio-based adhesive production to preempt REACH formaldehyde restriction compliance costs. For New Entrants and Emerging Players: Facade contractors in Southern Europe represent the most penetrable channel partner type, given acute skilled installer shortages limiting adoption of premium commercial envelope systems. Target carbon-negative hemp-lime and mycelium-based panel production for Dutch and Belgian public tenders. Pursue white-label partnerships with UK offsite construction hubs seeking pre-integrated MEP routing channels. For Investors and Strategic Acquirers: Asymmetric upside sits with forestry-integrated mid-cap specialists with captive softwood fiber supply and existing EPD documentation infrastructure. Five-to-ten year viability favors producers positioned upstream of EU carbon border adjustment mechanism implementation for steel and aluminum sheet imports. Watch for inflection when national building codes begin enforcing embodied carbon thresholds beyond public procurement into private residential renovation mandates.| Strategic Initiative | Industry Significance |
|---|---|
| EPD Documentation Investment | Saint Gobain and Kingspan leverage comprehensive lifecycle carbon data to lock public procurement eligibility. |
| Backward Integration into Forestry | Swedish and Finnish OSB mills secure captive softwood fiber supply against Nordic harvest volatility. |
| BIM-Integrated Specification Platforms | Digital product libraries compress architect-to-contractor information chains for large-format panel systems. |
| Bio-Based Adhesive Reformulation | Central European MDF manufacturers accelerate capital deployment to meet REACH formaldehyde emission limits. |
| Industrialized Prefabrication Partnerships | UK and Scandinavian offsite construction hubs create demand for pre-integrated MEP routing channels. |
Research Methodology
Direct dialogue with facade contractors, building materials procurement managers, EPD certification specialists, and national building code enforcement officers grounded qualitative findings, combined with secondary validation from EU Construction Products Regulation filings, ECHA REACH restriction updates, national building energy efficiency regulatory transpositions, and trade data from Nordic forestry and Iberian gypsum processing sectors. Bottom-up demand modeling across material type, end user, application, and format size segments triangulated against top-down market sizing from producer capacity disclosures.
Market value and volume outputs across the analysis window reflect segment-specific growth trajectory modeling with CAGRs derived from retrofit cycle acceleration rates, regulatory enforcement timelines, and substitution elasticity between wood-based and mineral substrates. Segmentation dimensions include material substrate category, end-use vertical, installation application, and format size tier, with forecast inputs incorporating EU Green Deal embodied carbon threshold implementation schedules and national building code transposition progress.
Revisions become necessary when ECHA extends formaldehyde restrictions beyond current wood-based panel categories, when EU carbon border adjustment mechanism implementation reshapes import competitiveness for steel and aluminum sheet products, or when national subsidy intensity for residential retrofit programs shifts materially. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Composite Decking and Railing Market
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
Portland Cement Market
Building Materials
Roof Cover Boards Market
Building Materials
United States White Cement Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
South Africa White Cement Market
Building Materials
Cement Market
Building Materials
Stone Adhesive Market
Building Materials
Global Drywall and Building Plaster Market
Building Materials
Concrete and Cement Market
Building Materials
Canada Architectural Coatings Market
Building Materials
Global Pozzolan Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
France Architectural Coatings Market
Building Materials
Polymer-Modified Cementitious Mortar Market