
 Canada Cold Chain Logistics Market | 2026-2036
Canada Cold Chain Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Cold Chain Logistics Market Outlook
Multi-source cold storage procurement is rebalancing toward regional specialists with dedicated pharmaceutical capabilities. Conestoga Cold Storage anchors Ontario's frozen protein corridor with deep-cube racking infrastructure. Americold Logistics leverages its network density to compete on cross-border temperature-controlled lanes. Lineage Logistics specializes in automated high-bay warehousing that reduces labor exposure to sub-zero environments.
Canada cold chain logistics encompasses the temperature-controlled movement and storage of perishable goods from origin to consumption point, maintaining unbroken thermal conditions typically between minus 25 degrees Celsius and plus 8 degrees Celsius depending on product sensitivity. The primary commercial purpose centers on preserving biochemical stability of pharmaceuticals, fresh produce, and frozen proteins while extending shelf-accessible distribution radius. Road transport dominates volume throughput due to Canada's dispersed population centers and limited rail refrigeration penetration in last-mile delivery. Warehousing commands disproportionate capital allocation as food processors and pharmaceutical distributors seek dedicated blast-freeze and controlled-atmosphere facilities near Toronto, Montreal, and Calgary. Monitoring technology represents the fastest-expanding service layer as Health Canada and CFIA traceability mandates push real-time temperature logging from passive recorders to cloud-integrated IoT sensor networks.
Health Canada enforces Good Distribution Practices that require validated cold chain documentation for temperature-sensitive pharmaceuticals, directly shaping warehouse investment in redundant refrigeration and backup power systems. The Canadian Food Inspection Agency administers Safe Food for Canadians Regulations mandating preventive control plans with temperature monitoring for imported and domestic food commodities. Provincial transport authorities in Ontario and Quebec enforce truck refrigeration unit inspection protocols that influence fleet replacement cycles. Stakeholders must monitor accelerating electrification mandates for transport refrigeration units as provinces phase diesel auxiliary engines in urban freight corridors.
Market Dynamics
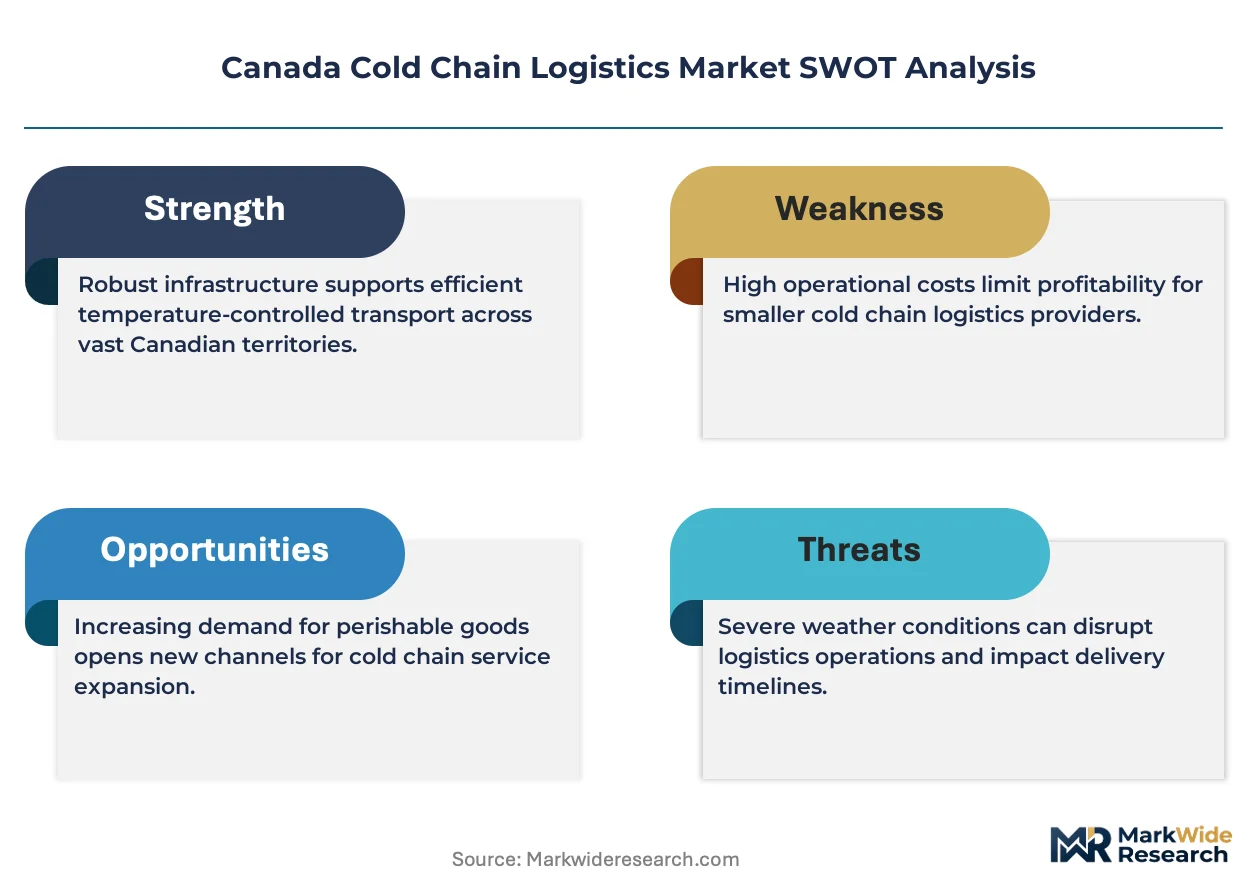
Health Canada's Good Distribution Practices mandate redundant refrigeration infrastructure, forcing warehouse operators to deploy validated temperature monitoring and backup power systems across pharmaceutical distribution networks. This regulatory pressure concentrates capital deployment toward compliant facilities near Toronto and Montreal while accelerating obsolescence of legacy cold storage assets lacking real-time IoT integration.
Growth Catalysts
- Safe Food for Canadians Regulations:The Canadian Food Inspection Agency mandates preventive control plans with continuous temperature logging, compelling food processors to upgrade cold storage and transport monitoring capabilities.
- Ontario-Quebec frozen protein corridor:Expanding outsourced cold storage commitments from meat and seafood processors drive demand for deep-cube racking infrastructure and blast-freeze capacity.
- Electrification of transport refrigeration units:Provincial diesel phase-out mandates in urban freight corridors accelerate fleet replacement toward electric auxiliary engines and cryogenic systems.
Market Restraints
- Capital intensity of redundant systems:Validated cold chain infrastructure requires dual refrigeration circuits and generator backup, elevating facility costs beyond reach of mid-scale operators.
- Limited rail refrigeration penetration:Canada's dispersed population centers lack temperature-controlled rail last-mile connectivity, forcing reliance on higher-cost road transport across vast distances.
- Concentrated demand geography:The Greater Toronto Area absorbs disproportionate capacity investment, leaving Atlantic and Prairie provinces underserved with pharmaceutical-grade cold storage.
Strategic Opportunities
- Calgary-Edmonton distribution hub development:Underpenetrated Western Canada presents white space for temperature-controlled facilities serving Alberta's expanding food processing and energy sector catering operations.
- Cloud-integrated IoT sensor networks:Convergence of low-power wide-area connectivity and edge computing enables predictive maintenance and automated compliance reporting for distributed cold chain assets.
- Cross-border temperature-controlled lanes:US-Canada pharmaceutical trade corridors offer expansion potential for operators with dual-compliant facilities meeting FDA and Health Canada validation standards.
Industry Challenges
- Refrigeration technician shortage:Specialized ammonia and CO2 system maintenance skills are scarce across Ontario and Quebec, extending equipment downtime during peak summer demand periods.
- Legacy warehouse retrofit complexity:Older facilities lack structural load capacity for automated high-bay racking and integrated sensor infrastructure, forcing greenfield construction over renovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Cold Chain Logistics Market |
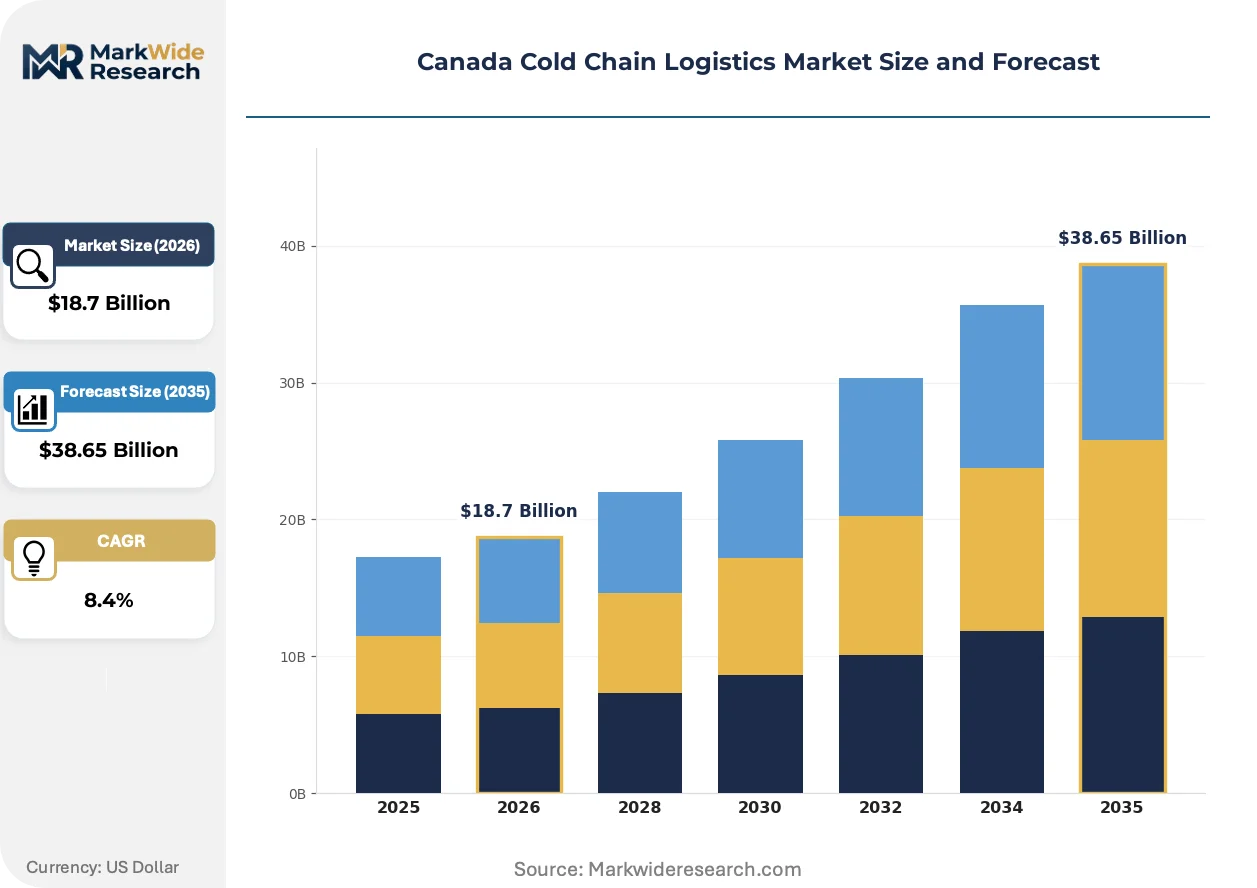
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Packaging, Monitoring Transport Mode: Air Freight, Road Transport, Rail Freight, Sea Freight End User: Pharmaceuticals, Food & Beverage, Chemicals, Electronics Technology: GPS Tracking, IoT Sensors, Refrigeration Systems, Automated Monitoring |
| Companies Covered | Conestoga Cold Storage, Groupe Robert, Americold Logistics, Day & Ross, Canada Cartage, Lineage Logistics, Trenton Cold Storage, MTE Logistix, Congebec Logistics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Cold Chain Logistics Market Strategic Shifts
Distributed sensor architectures are displacing centralized monitoring systems across Canadian cold chain operations, enabling real-time visibility without single points of failure. This shift compresses response times to temperature excursions while reducing compliance documentation burden.
Blockchain-enabled traceability is decentralizing custody verification across multi-handler pharmaceutical shipments. Health Canada and CFIA are piloting immutable ledger systems for vaccine and biologic distribution. Pharmaceutical distributors in the Greater Toronto Area are adopting these platforms fastest, compressing audit preparation from weeks to hours.
Health Canada's enforcement of Good Distribution Practices is mandating redundant refrigeration and backup power validation for temperature-sensitive pharmaceuticals. Warehouse operators must document thermal mapping and equipment qualification protocols. The pharmaceutical distribution segment is responding with dedicated capital allocation to compliant facilities near Montreal and Vancouver.
Direct procurement from regional cold storage specialists is displacing bundled logistics contracts among Ontario frozen food processors. Buyers seek dedicated pharmaceutical capabilities and transparent pricing without network overhead. This pattern concentrates most visibly among mid-scale protein processors in the Hamilton-Niagara corridor seeking flexible capacity without long-term commitments.
Canada Cold Chain Logistics Market Segmentation
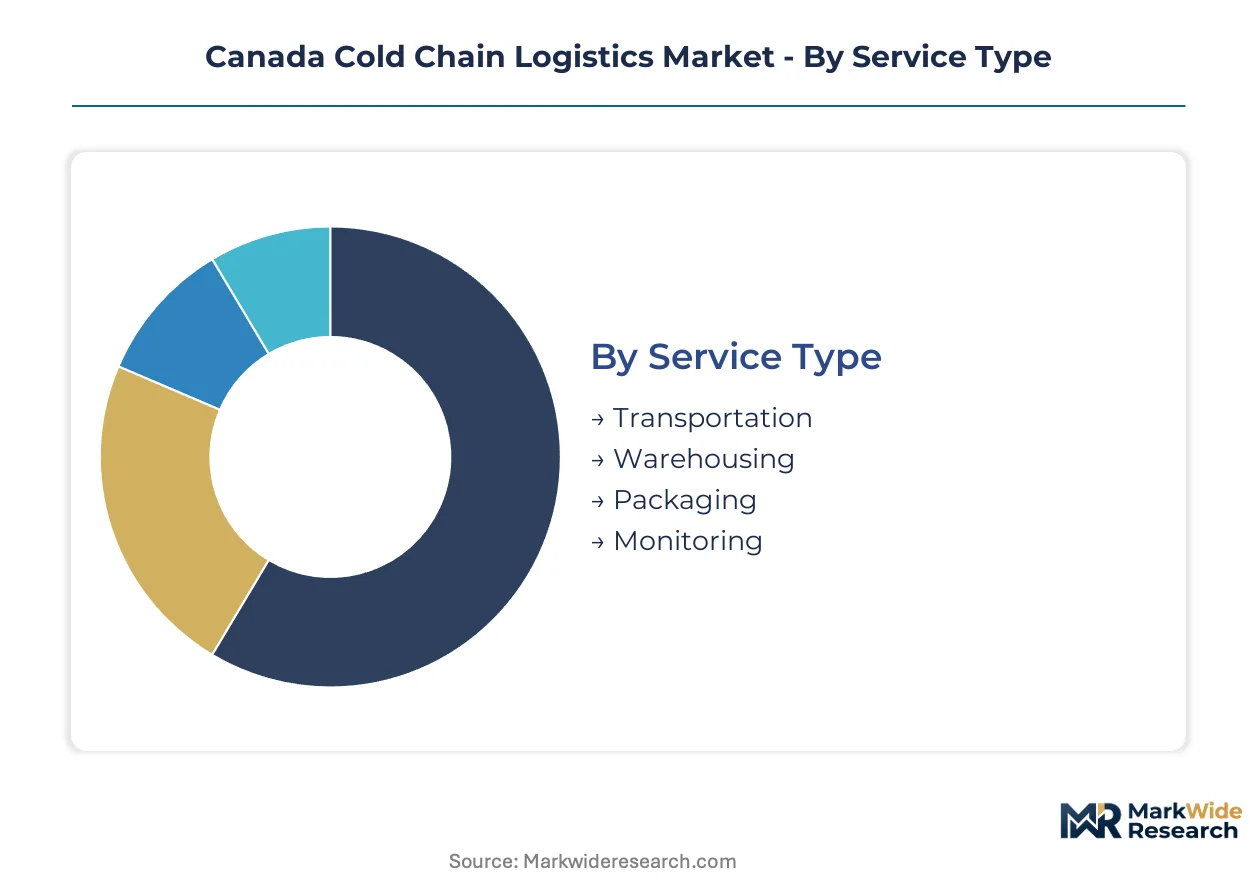
Cold chain logistics segmentation in Canada reflects divergent capital deployment patterns across service layers and transport modes. Each dimension carries distinct regulatory exposure, margin profiles, and infrastructure requirements that shape operator specialization strategies.
Service Type:
Facility modernization cycles and compliance mandates are driving replacement investments across all service layers, with pharmaceutical-grade capabilities commanding premium positioning.
- Transportation:Temperature-controlled fleet operations span dedicated reefers, multi-temp trailers, and cryogenic tankers for biologics. Ontario's frozen protein processors are expanding outsourced fleet commitments to avoid capital-intensive equipment ownership.
- Warehousing:Deep-cube racking infrastructure and blast-freeze chambers dominate capital allocation, particularly in the Greater Toronto Area's distribution corridor where Health Canada validation requirements concentrate demand for redundant refrigeration systems.
- Packaging:Insulated shippers, phase-change materials, and vacuum-insulated panels protect payload integrity during last-mile delivery. Demand concentrates among pharmaceutical distributors shipping temperature-sensitive biologics to remote Prairie communities.
- Monitoring:Cloud-integrated IoT sensor networks represent the fastest-expanding service layer as CFIA traceability mandates displace passive temperature loggers with real-time visibility platforms.
Volume placements concentrate in Transportation; the faster expansion belongs to Monitoring.
Transport Mode:
Modal selection in Canada reflects the tension between population dispersion and infrastructure availability, with cost tiers separating long-haul from last-mile solutions.
- Road Transport:Diesel and emerging electric auxiliary engine fleets handle the majority of temperature-controlled tonnage due to Canada's dispersed population centers and limited rail refrigeration penetration. Provincial electrification mandates in urban freight corridors are accelerating fleet replacement cycles.
- Air Freight:Premium velocity for high-value pharmaceuticals and fresh seafood exports, particularly from Vancouver International Airport's perishable cargo facilities to Asian markets. Health Canada's Good Distribution Practices validation requirements limit eligible carriers.
- Rail Freight:Bulk frozen protein movements between Prairie processing plants and coastal export terminals, though last-mile connectivity gaps force intermodal handoffs to road transport.
- Sea Freight:Containerized reefer imports through Port Metro Vancouver and Halifax, serving seafood exporters and fresh produce distributors with extended ocean transit times.
Road Transport absorbs dominant volume; Air Freight is climbing the fastest on pharmaceutical corridor expansion.
End User:
End-use applications segment by regulatory intensity and temperature sensitivity, with customer type determining facility certification requirements.
- Pharmaceuticals:Vaccines, biologics, and temperature-sensitive generics demand validated cold chains between minus 80 degrees Celsius and plus 8 degrees Celsius. Health Canada enforcement of Good Distribution Practices is concentrating demand in Toronto and Montreal corridor facilities with redundant backup power.
- Food & Beverage:Frozen proteins, fresh produce, and dairy products drive the largest absolute volume throughput. The Ontario-Quebec frozen protein corridor is expanding outsourced cold storage commitments from meat and seafood processors.
- Chemicals:Temperature-sensitive industrial compounds and laboratory reagents require controlled storage below ambient conditions, with demand concentrated in Alberta's energy sector research corridors.
- Electronics:Semiconductor components and sensitive instrumentation needing humidity and temperature stabilization during transit, primarily serving Waterloo-Toronto technology manufacturing clusters.
Food & Beverage holds dominant volume placement; Pharmaceuticals is gaining share fastest on regulatory compliance spending.
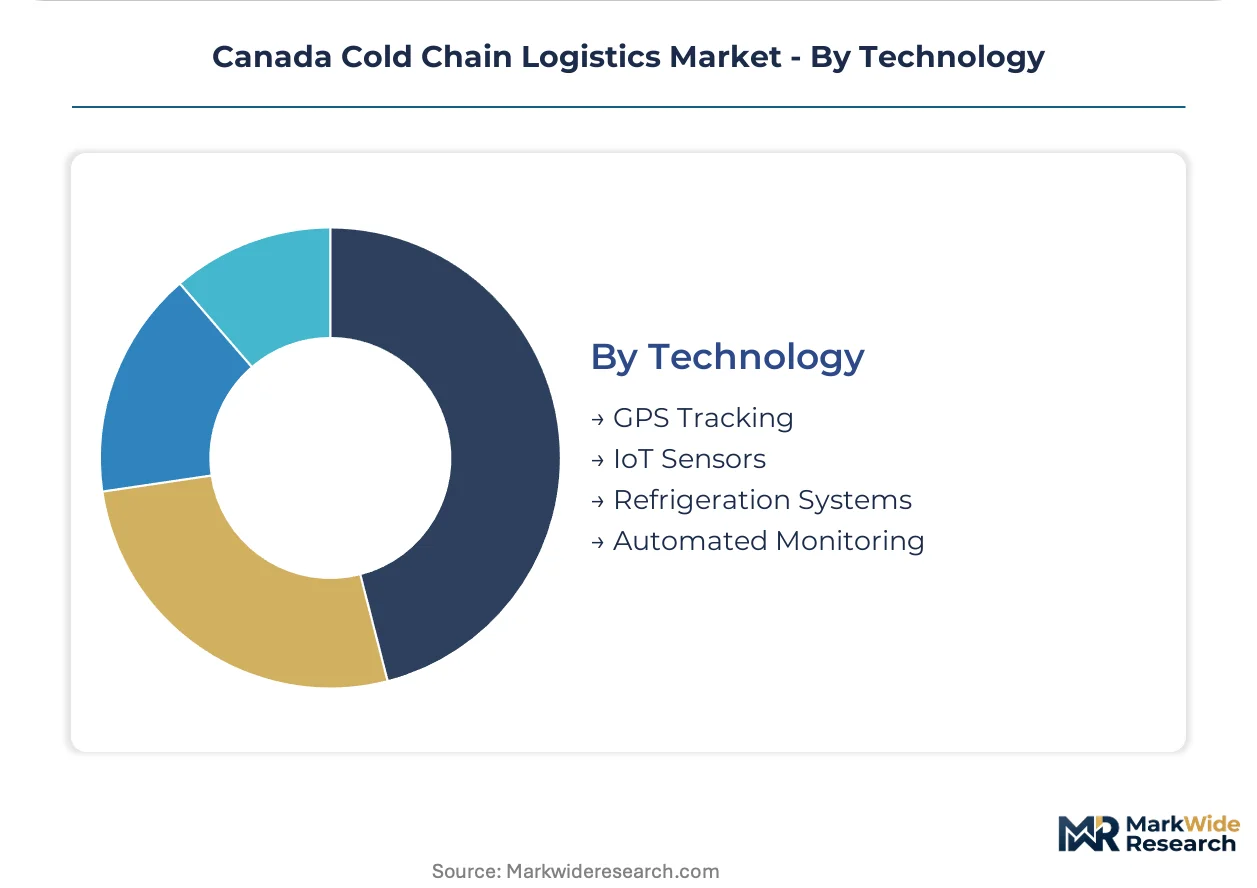
Technology:
Technology adoption curves separate mature infrastructure investments from emerging digital layers, with margin profiles favoring integrated platform providers.
- IoT Sensors:Distributed temperature, humidity, and location tracking devices with low-power wide-area connectivity enable real-time visibility across dispersed assets. CFIA and Health Canada mandates are accelerating deployment from passive loggers to cloud-integrated networks.
- Refrigeration Systems:Ammonia, CO2 transcritical, and hydrofluorocarbon-based cooling infrastructure constitutes the foundational capital layer. Technician scarcity across Ontario and Quebec is extending equipment downtime during peak summer demand.
- GPS Tracking:Fleet telematics for route optimization and cargo security, now standard across long-haul temperature-controlled transport. Integration with temperature monitoring platforms is becoming table stakes.
- Automated Monitoring:Edge computing and predictive analytics platforms that anticipate equipment failures before temperature excursions occur. Early adoption concentrates among pharmaceutical distributors in the Greater Toronto Area.
Refrigeration Systems represents the largest installed base; IoT Sensors shows the steepest expansion trajectory on compliance digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prairie grain terminals and Pacific seafood processing plants anchor Canada's cold chain infrastructure across dispersed provincial economies. Provincial electrification mandates and Health Canada validation requirements are reshaping capital deployment patterns from coast to coast.
Ontario
Hamilton-Niagara corridor meat processors are expanding outsourced blast-freeze commitments to avoid capital-intensive facility ownership. Health Canada's Good Distribution Practices enforcement concentrates pharmaceutical-grade warehouse investment in the Greater Toronto Area. Mississauga and Brampton host the densest cluster of redundant refrigeration facilities serving cross-border US-Canada pharmaceutical lanes.
Quebec
Montreal's perishable cargo facilities at Mirabel and Trudeau airports drive temperature-controlled air freight expansion for seafood exports to Asian markets. The province's transport authority enforces truck refrigeration unit inspection protocols that accelerate fleet replacement cycles. Quebec City and Saguenay processing plants are commissioning dedicated controlled-atmosphere storage for maple-derived food products.
Alberta
Calgary-Edmonton distribution corridors present underpenetrated white space for pharmaceutical-grade cold storage serving energy sector catering and research operations. The province's carbon pricing framework incentivizes CO2 transcritical refrigeration systems in new warehouse construction. Red Deer and Lethbridge meat processing clusters are driving demand for deep-cube racking infrastructure and automated high-bay warehousing.
British Columbia
Vancouver International Airport's perishable cargo terminals handle premium seafood exports requiring validated cold chains to China and Japan. Port Metro Vancouver's containerized reefer imports serve fresh produce distributors with extended ocean transit monitoring requirements. Kelowna and Fraser Valley agricultural processors are adopting cloud-integrated IoT sensor networks for CFIA traceability compliance.
Atlantic Canada
Halifax's reefer container terminal serves seafood exporters with temperature-controlled ocean freight connectivity to European markets. The region's dispersed population centers force reliance on higher-cost road transport across vast distances with limited rail refrigeration penetration. St. John's and Moncton distribution facilities are upgrading backup power systems to meet pharmaceutical distributor reliability standards.
Canada Cold Chain Logistics Market Competitive Environment
Capacity expansion dominates the current landscape as operators deploy automated high-bay warehousing and redundant refrigeration systems to capture Health Canada-compliant pharmaceutical volumes. The market structures around three tiers: integrated North American networks with cross-border density, regional specialists with deep vertical expertise in frozen proteins or biologics, and asset-light brokers aggregating spot refrigerated capacity. Strategic archetypes separate capital-intensive facility developers from technology-enabled monitoring platform providers. M&A activity and electrification-driven fleet replacement constitute the dominant competitive moves reshaping operator positioning.
Among integrated network operators, Americold Logistics and Lineage Logistics exemplify scale-driven archetypes competing on cross-border lane density and automated warehouse throughput. Conestoga Cold Storage anchors the regional specialist tier with deep-cube infrastructure concentrated in Ontario's frozen protein corridor. These three operators occupy distinct strategic positions: the integrated networks leverage continental footprint for pharmaceutical validation compliance, while the regional incumbent captures flexible procurement demand from mid-scale protein processors seeking transparent pricing without long-term network commitments.
| Leading Market Players |
|---|
| Conestoga Cold Storage |
| Groupe Robert |
| Americold Logistics |
| Day & Ross |
| Canada Cartage |
| Lineage Logistics |
| Trenton Cold Storage |
| MTE Logistix |
| Congebec Logistics |
| Others |
Value Chain & Pricing Dynamics
Ontario frozen food processors concentrate procurement authority in the Hamilton-Niagara corridor, driving unbundled service contracts that separate storage fees from temperature monitoring and compliance documentation costs.
Pricing Analysis
Warranty and service bundling separates compliant pharmaceutical-grade providers from commodity cold storage operators, with Health Canada validation documentation commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and redundant backup power availability. Cost compression in mid-scale warehousing intensifies as electrification mandates accelerate fleet replacement cycles. Small protein processors exhibit highest price sensitivity, while biologic distributors accept premium positioning for validated audit trails.
Supply Chain Analysis
Single-source vulnerability sits with ammonia refrigeration system components manufactured in the United States and Germany, with CO2 transcritical equipment concentrated in Denmark and Japan. Canadian cold chain infrastructure draws from steel racking fabricated in China, compressor units from Germany, and IoT sensor assemblies from South Korea. Tariff exposure on Chinese steel inputs elevates facility construction costs for domestic warehouse developers. Distribution runs through Toronto-Montreal corridor hubs before radiating to Prairie and Atlantic provinces via road-dominant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Health Canada's Good Distribution Practices enforcement creates a compliance moat that elevates capital barriers for new entrants while concentrating returns among validated facility operators.
For Market Incumbents: Acquire specialized ammonia and CO2 refrigeration technician training programs to address Ontario-Quebec maintenance scarcity. Expand automated high-bay warehousing capacity in Calgary-Edmonton corridors before electrification mandates reshape competitive positioning. Consolidation of regional cold storage specialists in Atlantic Canada defends against cross-border network operators seeking eastern seaboard density. For New Entrants and Emerging Players: Health Canada's Good Distribution Practices in Ontario opens a window for pharmaceutical-grade facility development in underserviced Prairie provinces. White space exists in cloud-integrated IoT sensor network deployment for mid-scale food processors seeking CFIA traceability compliance without integrated network overhead. Direct sales to Alberta energy sector catering operations bypass entrenched Toronto-Montreal corridor competition. For Investors and Strategic Acquirers: The window for entry favors regional specialists with deep vertical expertise in frozen proteins or biologics rather than asset-light technology platforms. Long-term viability hinges on captive access to compliant facilities near provincial population centers. Watch electrification subsidy announcement timing as inflection indicator for fleet replacement-driven consolidation waves.| Strategic Initiative | Industry Significance |
|---|---|
| Automated High-Bay Warehouse Deployment | Reduces labor exposure to sub-zero environments while accelerating pharmaceutical throughput in Toronto corridor facilities. |
| CO2 Transcritical Refrigeration Conversion | Aligns with Alberta carbon pricing framework while lowering ammonia regulatory compliance burden for warehouse operators. |
| Cloud-Integrated IoT Sensor Network Rollout | Enables real-time CFIA traceability compliance for Kelowna and Fraser Valley agricultural processors. |
| Cross-Border Pharmaceutical Validation Investment | Captures US-Canada biologic trade volume through dual-compliant facilities meeting FDA and Health Canada standards. |
| Electrified Transport Refrigeration Fleet Replacement | Positions operators ahead of provincial diesel phase-out mandates in urban freight corridors. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across cold storage facility operators, pharmaceutical distribution executives, fleet procurement managers, and CFIA compliance officers. Health Canada guidance documents, Canadian Food Inspection Agency enforcement records, provincial transport authority inspection protocols, and refrigerated warehousing industry association statistics provided segmentation validation. Bottom-up facility capacity counts and top-down trade flow estimates were triangulated against cross-border temperature-controlled shipment manifests.
Granularity-level modeling deployed service-type splits at the facility level, transport-mode segmentation at the provincial corridor level, and end-user disaggregation at the metropolitan statistical area level. Technology adoption curves for IoT sensors and automated monitoring were projected across the analysis window using compliance mandate implementation timelines. CAGRs derived from historical capital expenditure patterns and announced facility expansion pipelines. Refrigeration technician labor supply constraints and electrification subsidy program designs served as industry-specific forecast modifiers.
The model assumes a particular technology adoption path; alternative pathways for electric auxiliary engine penetration would alter the outlook for diesel fleet residual values and replacement timing. Forecasts reflect assumptions about Health Canada enforcement consistency and provincial electrification schedule adherence. Commodity steel price volatility and cross-border pharmaceutical trade policy shifts represent revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Turkey Freight and Logistics Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Asia Pacific International Express Service Market
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Global 5PL Solutions Market
Logistics and Shipping
Intralogistics Containers Market
Logistics and Shipping
United Arab Emirates Freight and Logistics Market
Logistics and Shipping
North America Cross Border Road Freight Transport Market
Logistics and Shipping
Japan Third-Party Logistics (3PL) Market
Logistics and Shipping
Logistics Outsourcing Market
Logistics and Shipping
Tank Container Shipping Market
Logistics and Shipping
Canada Project Logistics Market
Logistics and Shipping
Car Carrier Market
Logistics and Shipping
United States Courier, Express and Parcel (CEP) Market
Logistics and Shipping
Container Terminal Automation Market
Logistics and Shipping
India Contract Logistics Market