
 GCC Warehousing and Distribution Logistics Market | 2026-2036
GCC Warehousing and Distribution Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Warehousing and Distribution Logistics Market Foresight
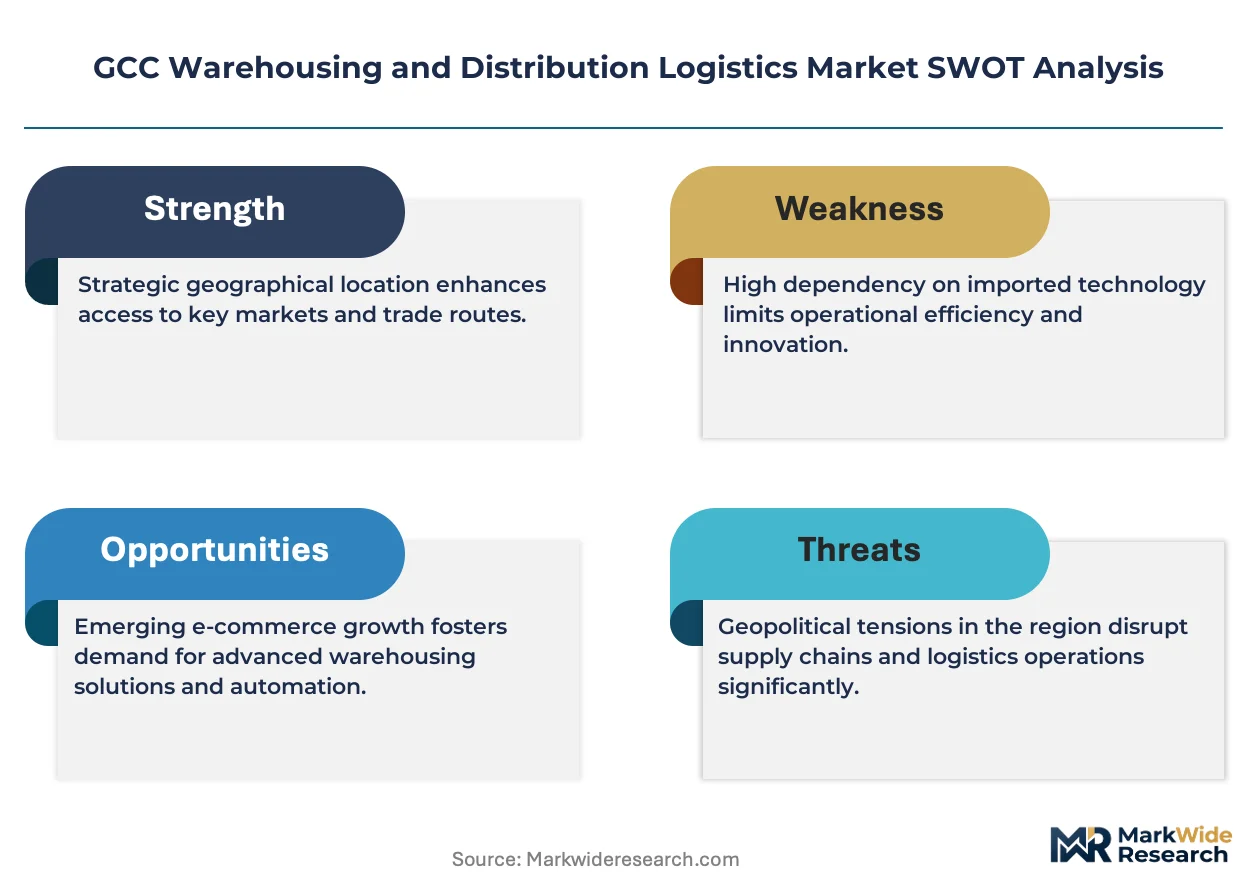
Last-mile delivery networks across the Gulf Cooperation Council states are reconfiguring as e-commerce penetration deepens and consumer expectations compress delivery windows. DHL Group leverages its integrated air-road hub in Dubai to sustain cross-border parcel velocity into Saudi Arabia and Kuwait. Agility Logistics anchors its competitive stance through specialized defense and government contract logistics across Kuwait and Qatar. GWC dominates bonded warehouse operations at Hamad Port and Mesaieed Industrial City, controlling critical import-export flow points for Qatari trade.
GCC warehousing and distribution logistics encompasses the physical storage, inventory management, and multimodal movement of goods across six Arabian Peninsula economies, typically operating facilities ranging from ambient bulk storage to temperature-controlled environments maintaining minus 25 degrees Celsius for pharmaceutical and food products. The primary commercial purpose centers on reducing working capital trapped in inventory while ensuring product availability aligns with just-in-time manufacturing schedules and direct-to-consumer fulfillment cycles. Automated warehouses and distribution centers command premium capital allocation as labor scarcity and land cost inflation in Dubai and Jeddah push operators toward vertical storage systems and robotic picking. Third-party logistics providers capture expanding wallet share as manufacturing firms and FMCG distributors outsource non-core supply chain functions to specialists with scale advantages in freight consolidation and customs brokerage.
Saudi Arabia's General Authority for Civil Aviation and the UAE's Federal Transport Authority jointly influence air cargo capacity licensing and ground handling standards, while Dubai's Logistics City free zone framework shapes facility location decisions through tax and customs duty exemptions. The Saudi Standards, Metrology and Quality Organization and UAE's Ministry of Industry and Advanced Technology set warehouse construction codes and cold chain certification requirements that determine market access for international operators. Stakeholders must monitor evolving customs union harmonization talks between GCC member states, as unified tariff and documentation regimes would eliminate redundant border inspections and reshape hub-and-spoke network designs currently optimized around national regulatory fragmentation.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing warehouse design cycles across the Gulf, forcing operators to reconfigure facilities for same-day delivery radii rather than traditional regional distribution networks. Labor scarcity in Dubai and Jeddah accelerates automation capital deployment.
Growth Catalysts
- Saudi dual carbon goals:Saudi Arabia's net-zero targets mandate solar-powered warehouse construction, creating retrofit demand for existing facilities in Riyadh's industrial clusters.
- Hamad Port bonded expansion:Qatar's customs modernization at Mesaieed Industrial City streamlines re-export processing, attracting regional distribution center investment.
- Automated vertical storage:Robotic picking systems address land cost inflation in Dubai's Jebel Ali corridor, enabling higher throughput per square meter.
Market Restraints
- Steel and aluminum input volatility:Warehouse construction costs fluctuate with Gulf metal import dependencies, squeezing developer margins on speculative build-to-suit projects.
- Technical limitation:Cold chain infrastructure gaps persist for minus 25 degrees Celsius pharmaceutical storage outside Dubai and Riyadh, restricting biologics distribution.
- Regulatory friction:Incomplete GCC customs union harmonization maintains redundant border inspections between Saudi Arabia and UAE, inflating cross-border transit times.
Strategic Opportunities
- Kuwait's defense logistics white space:Specialized government contract warehousing remains underdeveloped relative to UAE and Saudi Arabia, offering first-mover positioning.
- Oman's emerging port corridor:Duqm Special Economic Zone incentives attract transshipment operators seeking alternatives to Jebel Ali congestion.
- AI-IoT convergence:Predictive inventory management systems integrate with existing WMS platforms, enabling demand forecasting for FMCG distributors.
Industry Challenges
- Certification timeline compression:Saudi Standards, Metrology and Quality Organization cold chain accreditation requires 18-24 month facility validation, delaying market entry.
- Integration complexity:Legacy ERP systems at family-owned distributors resist API connectivity with modern TMS platforms, fragmenting data visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Warehousing and Distribution Logistics Market |
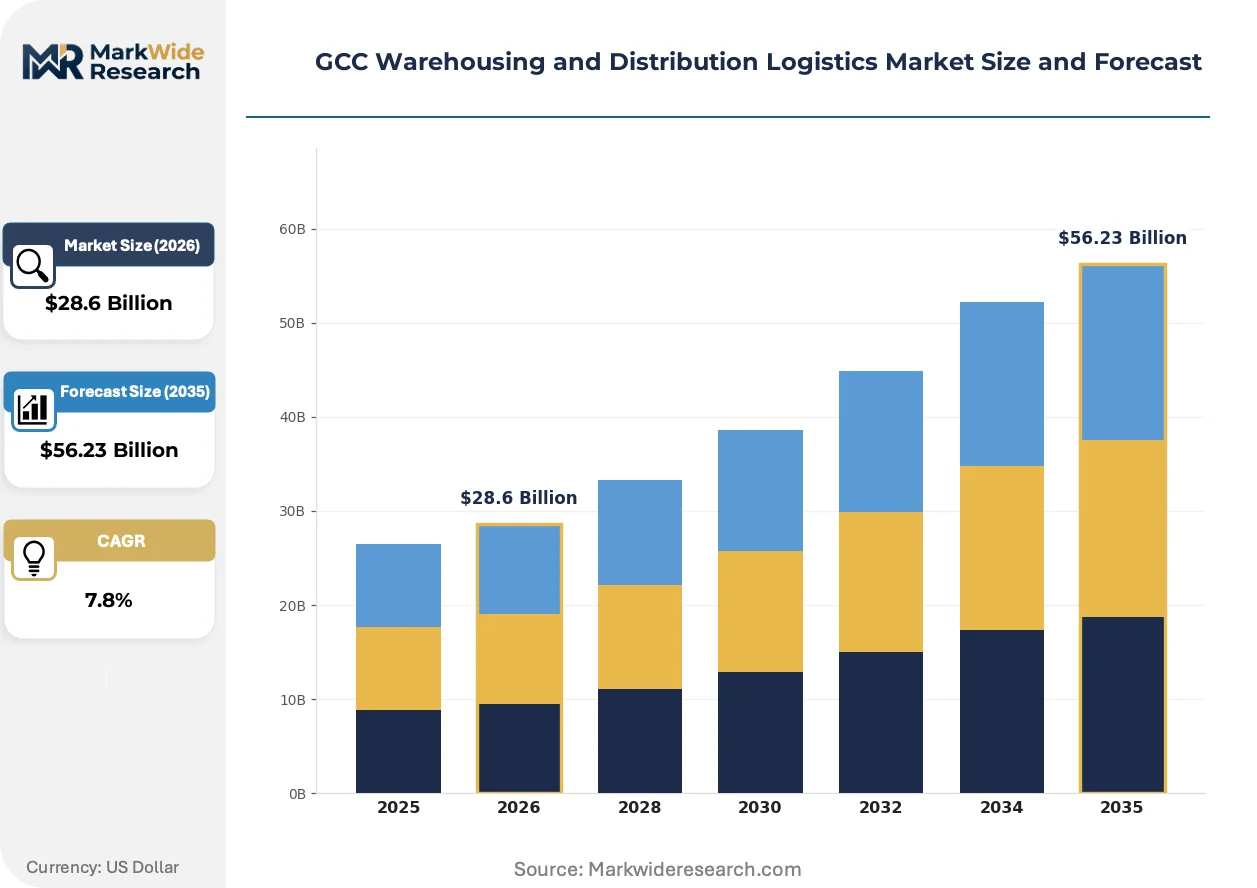
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $56.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Third-Party Logistics, Freight Forwarding, Inventory Management, Cross-docking, Fulfillment Services Warehouse Type: Cold Storage, Bonded Warehouses, Automated Warehouses, Distribution Centers, Bulk Storage Facilities Transportation Mode: Road Freight, Rail Cargo, Air Freight, Sea Freight, Intermodal Transport Customer Type: Manufacturing Firms, E-commerce Platforms, Construction Companies, FMCG Distributors, Technology Providers |
| Companies Covered | DHL Group, Agility Logistics, DB Schenker Logistics, Kuehne + Nagel, GWC (Gulf Warehousing Company), Al-Futtaim Logistics, Aramex Logistics, CEVA Logistics, UPS, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Warehousing and Distribution Logistics Market Shifts & Advancements
Warehousing operations across the Gulf are converging on automation and sustainability mandates, with facility design increasingly dictated by energy efficiency certifications and robotic throughput metrics rather than traditional location theory.
Autonomous mobile robots are hybridizing warehouse floor operations, combining goods-to-person retrieval with dynamic slotting optimization. 3PL operators in Dubai's Logistics City deploy these systems to manage SKU proliferation from e-commerce clients. The technology is hybridizing labor models, reducing picker headcount while elevating technician roles.
Saudi Arabia's General Authority for Civil Aviation introduced stricter air cargo ground handling standards for temperature-controlled pharmaceuticals. Facilities must now demonstrate continuous cold chain monitoring from tarmac to warehouse. Pharmaceutical distributors in Riyadh are responding with redundant backup power systems and real-time temperature logging.
Direct-to-consumer fulfillment is compressing batch sizes and order frequencies, forcing warehouse slotting strategies to prioritize velocity over density. FMCG brands bypass traditional distributor networks for owned last-mile operations. This pattern concentrates in Saudi Arabia's major urban corridors where consumer delivery expectations match European standards.
GCC Warehousing and Distribution Logistics Market Segmentation
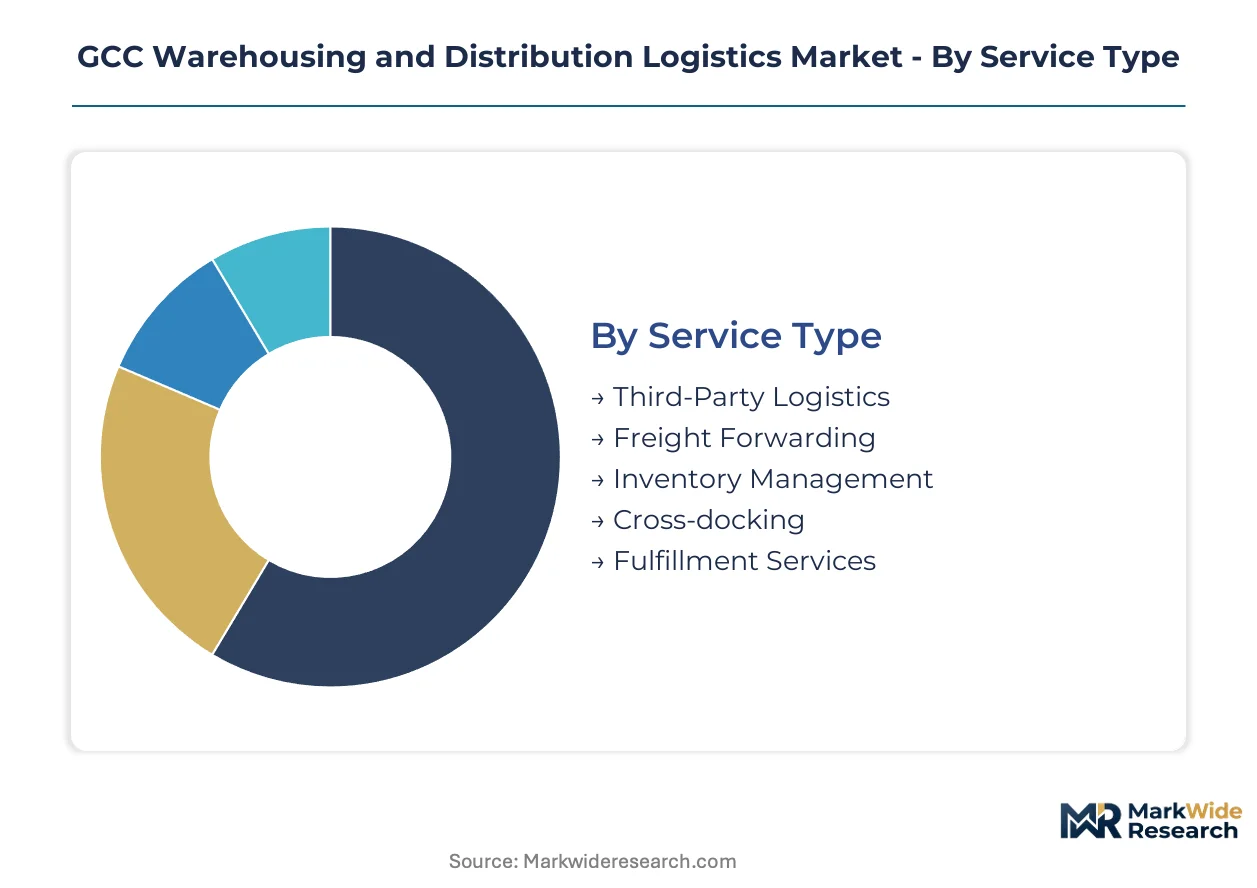
Segmentation in GCC warehousing and distribution logistics reveals distinct capital intensity profiles and automation readiness across service tiers. Facility type and transportation modality determine margin structures, while customer verticals dictate cold chain and bonded storage requirements.
Service Type:
Mature freight forwarding operations coexist with emerging fulfillment services as e-commerce penetration reshapes service portfolios across the Gulf.
- Third-Party Logistics:Integrated contract logistics spanning inventory management, warehousing, and last-mile delivery. Saudi manufacturing clusters and UAE free zones drive outsourcing adoption as firms shed fixed warehouse assets.
- Freight Forwarding:Traditional customs brokerage and cargo consolidation services. Jebel Ali-Dubai corridor maintains dominance for air-sea intermodal handoffs despite rising Duqm competition.
- Inventory Management:Demand forecasting and safety stock optimization systems. Retail chains in Riyadh and Doha deploy vendor-managed inventory to reduce working capital.
- Cross-docking:Direct freight transfer without intermediate storage. FMCG distributors leverage Hamad Port facilities to accelerate re-export velocity into regional markets.
- Fulfillment Services:E-commerce order processing and returns management. Same-day delivery mandates in Jeddah and Dubai force micro-fulfillment network densification.
Third-Party Logistics retains volume leadership; Fulfillment Services holds the steepest expansion curve.
Warehouse Type:
Cost tier stratification separates premium automated facilities from commodity bulk storage as land scarcity intensifies across Gulf industrial zones.
- Automated Warehouses:Vertical storage systems with robotic picking and AI-driven slotting optimization. Dubai's Logistics City operators deploy these to offset labor scarcity and maximize throughput per square meter.
- Cold Storage:Temperature-controlled environments maintaining minus 25 degrees Celsius for pharmaceutical and frozen food products. Riyadh and Dubai concentrate capacity while gaps persist in secondary GCC cities.
- Bonded Warehouses:Customs-supervised facilities enabling deferred duty payment until goods exit for domestic consumption. Qatar's Mesaieed Industrial City expansion attracts regional distribution center investment.
- Distribution Centers:Cross-functional facilities combining storage, sorting, and last-mile dispatch. E-commerce platforms anchor networks in Saudi Arabia's emerging industrial clusters.
- Bulk Storage Facilities:Ambient warehousing for construction materials and raw commodities. Construction booms in Kuwait and Oman sustain demand despite automation pressure elsewhere.
Automated Warehouses command the highest capital allocation; Cold Storage faces the most acute supply-demand imbalance.
Transportation Mode:
Geography determines modal dominance as coastal economies leverage maritime access while landlocked segments depend on road and air corridors.
- Road Freight:Dominant mode for intra-GCC distribution and last-mile delivery. Redundant border inspections between Saudi Arabia and UAE inflate transit times despite customs union negotiations.
- Air Freight:High-velocity transport for pharmaceuticals, electronics, and perishables. Dubai's integrated air-road hub sustains cross-border parcel velocity into Saudi Arabia and Kuwait.
- Sea Freight:Containerized cargo through Jebel Ali, Hamad Port, and emerging Duqm facilities. Bulk commodity imports and re-export trade sustain volume.
- Rail Cargo:Limited network coverage concentrated on Saudi Arabia's mineral and petrochemical corridors. Etihad Rail expansion aims to integrate UAE industrial zones.
- Intermodal Transport:Sea-air and road-rail combinations optimizing cost-velocity tradeoffs. FMCG distributors employ these for mid-priority SKUs.
Road Freight handles the greatest tonnage; Air Freight captures the most value per kilogram.
Customer Type:
Application diversity spans heavy industrial inputs to direct-to-consumer fulfillment, each imposing distinct facility specifications and service level requirements.
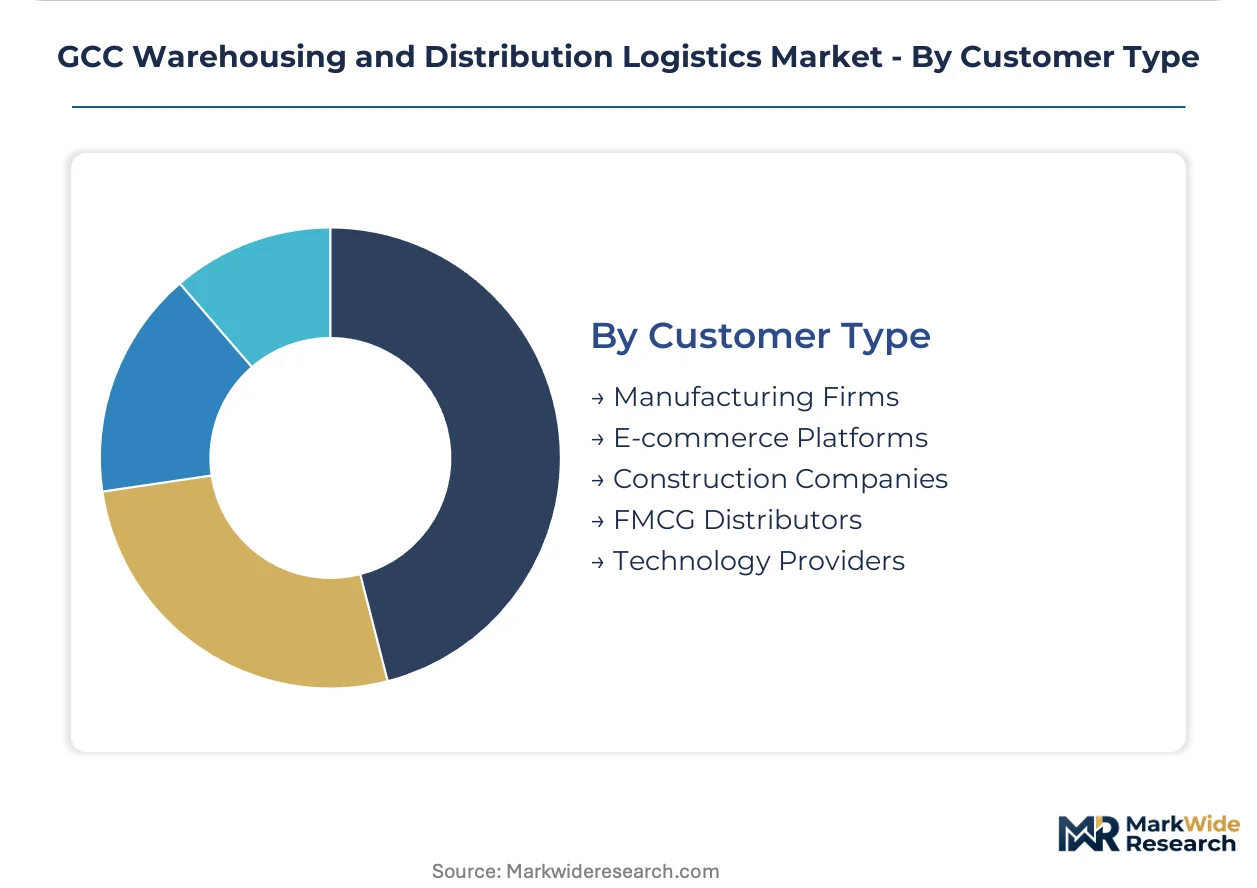
- E-commerce Platforms:Direct-to-consumer fulfillment with same-day delivery mandates. Saudi urban corridors drive warehouse slotting strategies prioritizing velocity over density.
- Manufacturing Firms:Just-in-time component delivery and finished goods distribution. Automotive and electronics producers in Dubai and Riyadh outsource non-core logistics functions.
- FMCG Distributors:High-frequency replenishment of retail and foodservice channels. Temperature-controlled requirements and batch traceability dominate facility specifications.
- Construction Companies:Project-based material staging and equipment logistics. Bulk storage facilities in Kuwait and Oman serve infrastructure development cycles.
- Technology Providers:Sensitive electronics and data center equipment requiring cleanroom handling and shock-resistant transport. Specialized handling commands premium pricing.
E-commerce Platforms are expanding their fulfillment footprint most aggressively; Manufacturing Firms represent the most stable contract base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port anchors the Gulf's logistics architecture, processing container volumes that cascade into Saudi Arabia and Qatar through bonded corridor networks.
United Arab Emirates
E-commerce fulfillment velocity and free zone incentives drive warehouse automation in Dubai's Logistics City. The Federal Transport Authority regulates ground handling standards for temperature-controlled cargo. Jebel Ali-Dubai corridor operators deploy vertical storage systems to offset land cost inflation.
Saudi Arabia
NEOM industrial construction and automotive manufacturing clusters generate demand for just-in-time component logistics. The Saudi Standards, Metrology and Quality Organization mandates 18-24 month cold chain facility validation. Riyadh's emerging industrial zones attract automated distribution center investment.
Qatar
Hamad Port bonded warehouse expansion streamlines re-export processing for regional trade flows. Qatar's customs modernization program at Mesaieed Industrial City reduces clearance friction. Doha concentrates pharmaceutical and food-grade cold storage capacity.
Kuwait
Defense and government contract logistics sustain specialized warehousing demand outside commercial e-commerce channels. The country's national logistics regulator oversees port authority licensing and bonded facility accreditation. Kuwait City industrial zones remain underdeveloped relative to UAE and Saudi Arabia.
Oman
Duqm Special Economic Zone transshipment incentives attract operators seeking alternatives to Jebel Ali congestion. Port authority development frameworks prioritize maritime-industrial corridor integration. Bulk commodity storage and construction material logistics dominate warehouse utilization outside Muscat.
GCC Warehousing and Distribution Logistics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in freight forwarding and customs brokerage. The market structures around three tiers: global 3PL networks with Gulf hub operations, regional specialists anchored to national industrial policies, and local last-mile distributors serving urban consumer corridors. Consolidation pressure intensifies as e-commerce platforms internalize fulfillment functions. Dominant competitive moves include automation capital deployment and free zone facility expansion.
Among Germany-based logistics integrators, DHL Group and DB Schenker Logistics represent the global network archetype with integrated air-road hub operations. Kuwait-based Agility Logistics exemplifies regional defense and government contract specialization. Qatar-based GWC (Gulf Warehousing Company) anchors the bonded warehouse segment at critical import-export flow points.
| Leading Market Players |
|---|
| DHL Group |
| Agility Logistics |
| DB Schenker Logistics |
| Kuehne + Nagel |
| GWC (Gulf Warehousing Company) |
| Al-Futtaim Logistics |
| Aramex Logistics |
| CEVA Logistics |
| UPS |
| Others |
Supply & Pricing Matrix
Steel and aluminum import dependencies from China and India concentrate construction cost volatility among Dubai and Jeddah warehouse developers, pushing margin pools toward operators with captive fabrication capabilities or long-term metal offtake contracts.
Pricing Analysis
Volume-discount tiering structures dominate contract logistics negotiations, with three-tier pricing separating automated facilities from standard bulk storage and basic ambient warehousing. Price differentiation hinges on certification grade—SASO cold chain validation commands premium positioning—and geographic delivery cost to Saudi Arabia's interior industrial zones. Cost compression in speculative build-to-suit projects is intensifying because steel input volatility squeezes developer margins. FMCG distributors exhibit highest price sensitivity due to thin inventory carrying margins, while pharmaceutical logistics buyers prioritize temperature assurance over rate negotiation.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Chinese construction equipment manufacturers anchor capital deployment for warehouse automation projects across the Gulf. Geographic supply concentration draws from Germany for robotic picking systems, South Korea for cold chain compressor technology, and China for racking and material handling equipment. Raw material dependencies rest on steel coils, aluminum extrusions, and lithium-ion battery systems for backup power. Single-source vulnerability persists for minus 25 degrees Celsius refrigeration compressors. Distribution runs through bonded corridor networks from Jebel Ali into Saudi Arabia and Qatar.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The GCC warehousing market functions as a defensive-moat story where regulatory entrenchment—SASO and SFDA facility validation requirements—creates 18-24 month barriers that protect incumbent positioning against rapid competitive entry.
For Market Incumbents: Entrench through backward integration into solar-powered warehouse construction capabilities, addressing Saudi dual carbon retrofit demand while locking in Riyadh industrial zone land positions. DHL Group and Agility Logistics anchor competitive stance through specialized defense contract logistics that resist price-based displacement. Free zone facility expansion in Dubai's Logistics City reinforces customs brokerage bundling that new entrants cannot replicate without 24-month accreditation timelines. For New Entrants and Emerging Players: Build out micro-fulfillment networks in Jeddah and Dammam urban corridors where same-day delivery mandates outpace incumbent last-mile density. Kuwait's defense logistics white space remains the most penetrable segment given underdeveloped commercial alternatives to UAE and Saudi capacity. A go-to-market angle targeting family-owned FMCG distributors with API-native TMS integration addresses legacy ERP fragmentation that incumbents have neglected. For Investors and Strategic Acquirers: Capital is best deployed toward automated vertical storage specialists with proven robotic throughput metrics in Dubai's Jebel Ali corridor, where land scarcity sustains pricing power across the analysis window. Acquisition target archetype: mid-scale 3PL operators holding SASO pre-validated cold chain assets in secondary GCC cities. The signal to watch is Etihad Rail freight integration announcements that would reshape hub-and-spoke economics for intermodal operators.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Vertical Storage Deployment | Robotic picking systems address labor scarcity and land cost inflation in Dubai's Jebel Ali corridor. |
| Solar-Powered Warehouse Construction | Saudi dual carbon goals mandate renewable energy integration for new Riyadh industrial zone facilities. |
| Bonded Warehouse Expansion | Hamad Port customs modernization at Mesaieed Industrial City streamlines re-export processing for regional trade. |
| AI-IoT Predictive Inventory Integration | WMS platform convergence enables demand forecasting for FMCG distributors managing SKU proliferation. |
| Defense Logistics Contract Specialization | Kuwait and Qatar government warehousing requirements sustain margins isolated from e-commerce price compression. |
Research Methodology
Cross-validation between primary interviews with warehouse operations directors, 3PL contract managers, cold chain compliance officers, and Saudi industrial zone developers anchors the qualitative findings against secondary validation. Trade flow databases from Gulf customs authorities, SASO facility accreditation registries, Etihad Rail development disclosures, and free zone operator annual reports supply quantitative grounding. Bottom-up facility capacity modeling and top-down GDP-trade elasticity approaches triangulate market sizing.
Calibration against historical automation capital deployment patterns and e-commerce fulfillment density metrics shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include service type, warehouse automation tier, transportation modality, and customer vertical. CAGRs derive from trade volume elasticity analysis and facility utilization trend extrapolation. Forecast inputs incorporate Saudi industrial construction pipeline data and UAE free zone incentive evolution.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese automation equipment suppliers or GCC sovereign wealth direct logistics investments would shift outcomes. Macroeconomic deviation in oil-export revenues, regulatory acceleration in customs union harmonization, or breakthroughs in autonomous trucking technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Germany Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Asean Freight Forwarding Market
Logistics and Shipping
Latin America Contract Logistics Market
Logistics and Shipping
Spain Freight and Logistics Market
Logistics and Shipping
Air Freight Market
Logistics and Shipping
Liquid Chemical Tanker Shipping Market
Logistics and Shipping
Europe Refrigerated Container Shipping Market
Logistics and Shipping
North America Freight and Logistics Market
Logistics and Shipping
Indonesia Cold Chain Logistics Market
Logistics and Shipping
Texas Freight and Logistics Market
Logistics and Shipping
Vietnam Freight and Logistics Market
Logistics and Shipping
Latin America Logistics Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
US Fourth-Party Logistics (4PL) Market
Logistics and Shipping
Express Delivery Market
Logistics and Shipping
Central and Eastern Europe Cold Chain Logistics Market