
 United Kingdom Freight and Logistics Market | 2026-2036
United Kingdom Freight and Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Freight and Logistics Market Outlook
ISO 9001 quality management certification is redrawing competitive boundaries among UK freight operators. GXO Logistics UK Limited leverages its automated warehousing footprint to dominate e-commerce fulfillment contracts. DHL Supply Chain Limited anchors its position through temperature-controlled pharmaceutical distribution networks. Kuehne + Nagel differentiates via integrated sea-air-road multimodal solutions serving manufacturing exporters.
United Kingdom freight and logistics encompasses the physical movement, storage, and information management of goods across domestic and international supply chains, utilizing container specifications ranging from 20-foot standard units to 53-foot domestic trailers with gross vehicle weights up to 44 tonnes on designated routes. Road freight commands the largest volume share among service types, reflecting the UK's dense motorway network and just-in-time manufacturing dependencies, while last-mile delivery models absorb disproportionate capital investment as urban congestion charging and emission zones tighten operational economics. Telematics and IoT deployments are expanding fastest among technology segments, driven by fleet optimization mandates and insurance risk modeling requirements.
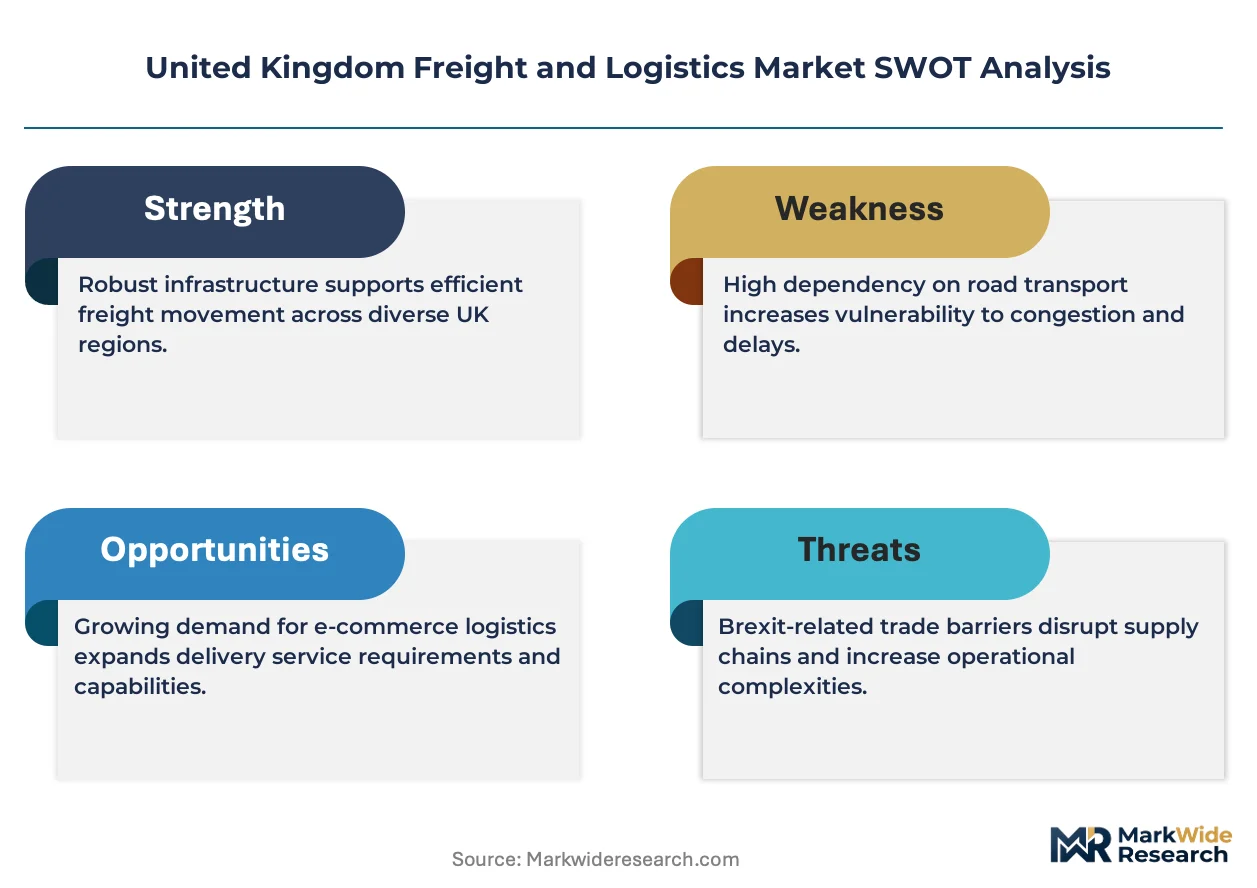
Driver Certificate of Professional Competence regulations enforced by the Driver and Vehicle Standards Agency constrain operator capacity and elevate training costs across the sector. The UK's post-Brexit customs controls, administered by HM Revenue & Customs through the Goods Vehicle Movement Service, continue to reshape cross-border routing decisions and documentation burdens. Stakeholders must monitor evolving Clean Air Zone expansions across Birmingham, Bristol, and Greater Manchester, as zero-emission capability becomes a threshold qualification for contract eligibility rather than a competitive differentiator.
Market Dynamics
Post-Brexit customs complexity is forcing freight operators to rebuild routing networks around the Goods Vehicle Movement Service, while Clean Air Zone mandates in Birmingham, Bristol, and Greater Manchester are eliminating diesel-dependent fleets from contract eligibility.
Growth Catalysts
- Pharmaceutical cold chain expansion:Temperature-controlled distribution corridors serving NHS and private healthcare networks are absorbing specialized warehousing investment across the Midlands.
- E-commerce fulfillment densification:Automated sortation hubs in Northern England are shortening last-mile radii for major retail distribution networks.
- ISO 9001 certification premiums:Quality management accreditation is becoming a threshold requirement for NHS logistics tenders and pharmaceutical contracts.
Market Restraints
- Driver Certificate of Professional Competence constraints:DVSA enforcement limits operator capacity expansion and elevates recurrent training expenditures.
- Fuel cost volatility:Diesel price fluctuations compress margins on fixed-rate haulage contracts.
- Channel Tunnel freight concentration:Cross-Channel capacity bottlenecks at Dover-Calais routes create single-point vulnerability for time-sensitive goods.
Strategic Opportunities
- Scottish renewable energy logistics:Offshore wind component transport and maintenance supply chains remain underdeveloped relative to installation targets.
- Multimodal sea-air integration:Manufacturing exporters in the West Midlands require consolidated forwarding solutions combining Southampton maritime capacity with East Midlands air freight.
- Wales border zone positioning:Holyhead and Milford Haven port infrastructure offers alternative Irish Sea routing as Dublin-Bristol volumes shift.
Industry Challenges
- Telematics integration complexity:Fleet operators struggle to harmonize legacy vehicle tracking systems with IoT-enabled cargo monitoring platforms.
- Zero-emission vehicle capex burden:Electric HGV acquisition costs and depot charging infrastructure demands strain mid-sized carrier balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Freight and Logistics Market |
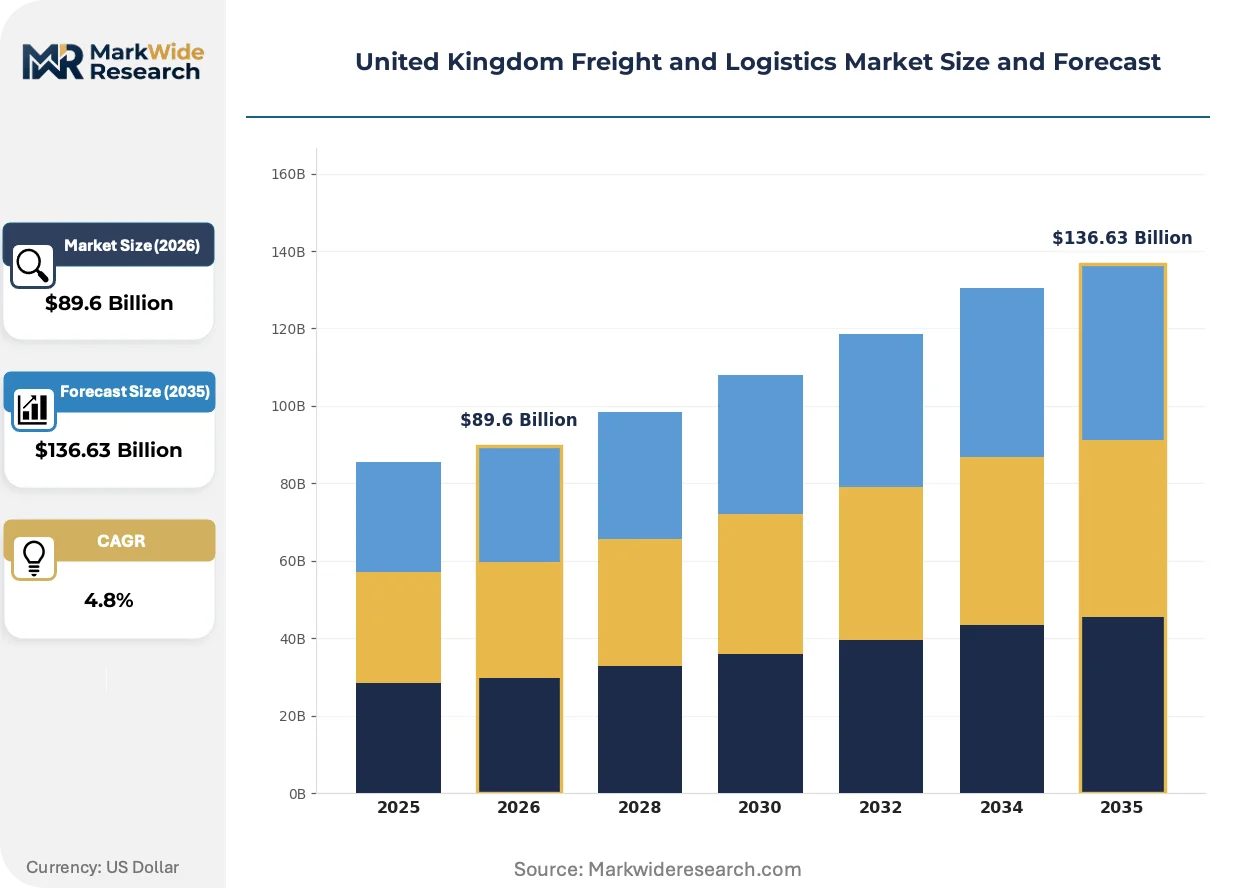
| Market Size in 2026 | $89.6 Billion |
| Market Size in 2035 | $136.63 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Road Freight, Rail Freight, Air Freight, Sea Freight Customer Type: Retailers, Manufacturers, E-commerce, Wholesalers Technology: Telematics, Automation, Blockchain, IoT Delivery Model: Direct Delivery, Last Mile, 3PL, Fulfillment Centers |
| Companies Covered | XPO Logistics UK Limited, Davies Turner & Co. Limited, Unipart Logistics Limited, Maersk Logistics and Services UK Ltd, GXO Logistics UK Limited, Kuehne + Nagel, CEVA Logistics Limited, DB Schenker, DHL Supply Chain Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Freight and Logistics Market Strategic Shifts
Digital freight matching platforms and autonomous yard management systems are compressing planning cycles, while regulatory pressure on emissions is accelerating equipment replacement timelines across UK operator fleets.
Telematics integration with predictive maintenance algorithms is bifurcating fleet management approaches. Large haulage contractors are adopting real-time engine diagnostics and tire pressure monitoring to minimize roadside failures. This technology is compressing maintenance intervals and reshaping supplier relationships toward data-enabled service contracts.
HM Revenue & Customs continues tightening post-Brexit customs controls through the Goods Vehicle Movement Service. The industrial consequence is documented routing preference shifts toward consolidated groupage services over direct trailer movements. Northern Irish manufacturers moving goods to Great Britain face the most complex compliance timelines and are investing in dedicated customs brokerage partnerships.
Shipper procurement preferences are pivoting toward carbon-accounted freight contracts with verified emission reporting. Retail and pharmaceutical buyers are displacing traditional rate-per-mile negotiations with sustainability-scored tender evaluations. This behavioral shift is most visible among FMCG distributors serving London congestion charge zones.
United Kingdom Freight and Logistics Market Segmentation
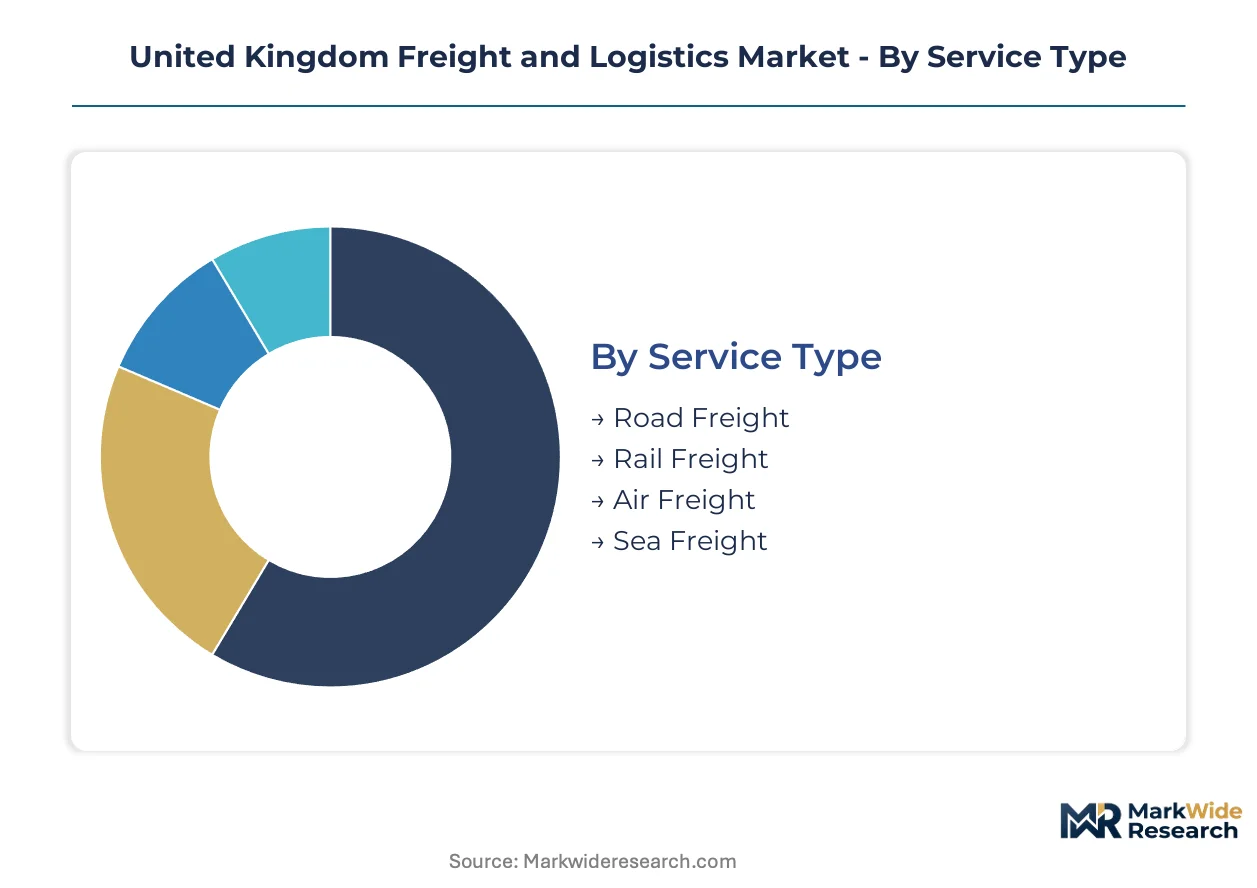
Segmentation in UK freight and logistics reveals how service specialization, customer concentration, and technology deployment create distinct competitive arenas. Each dimension carries different margin profiles and capital intensity requirements that reshape operator positioning across domestic corridors.
Service Type:
Rail freight faces the most acute substitution pressure from road haulage flexibility, while air cargo contends with maritime cost advantages on non-urgent routes.
- Road Freight:Utilizes 44-tonne gross vehicle weight configurations on designated motorway corridors with just-in-time scheduling dependencies. Manufacturing supply chains across the West Midlands and Thames Valley absorb the highest contract volumes as automotive and aerospace production lines demand precise delivery windows.
- Sea Freight:Container movements through Southampton, Felixstowe, and Liverpool handle bulk import-export volumes with 20-foot to 40-foot standard unit specifications. Pharmaceutical exporters in South East England favor consolidated maritime forwarding for temperature-stable generic products, though Brexit customs complexity has lengthened port dwell times.
- Rail Freight:Intermodal terminals at Daventry and Trafford Park connect deep-sea port throughput with inland distribution hubs. Energy sector demand for biomass and construction materials sustains bulk commodity movements.
- Air Freight:East Midlands Airport and Heathrow cargo terminals specialize in high-value, time-critical pharmaceutical and electronics shipments. Perishables and emergency spare parts dominate volume allocation.
Road freight anchors the volume base while sea freight gains share at the steepest rate as shippers optimize for cost over speed on post-Brexit trade lanes.
Customer Type:
Cost tier differentiation separates high-service pharmaceutical contracts from commodity retail movements, with margin compression most severe in mid-market manufacturing segments.
- E-commerce:Automated sortation hubs in the Midlands and Northern England process parcel volumes with sub-24-hour delivery commitments. Urban congestion charging zones in London and Birmingham elevate last-mile operational costs, compressing margins on free-shipping retail commitments.
- Retailers:Centralized distribution networks serving high street and omnichannel operations require seasonal surge capacity with fixed cost absorption. Grocery multiples dominate contract tender values through dedicated fleet partnerships.
- Manufacturers:Just-in-sequence delivery to automotive and aerospace assembly plants demands sub-hour delivery precision with penalty clauses for deviation. Supply chain vulnerability has elevated dual-sourcing requirements post-pandemic.
- Wholesalers:Consolidated groupage services across fragmented supplier bases serve independent retail and hospitality sectors with lower technology penetration than direct retail contracts.
E-commerce anchors the volume base while pharmaceutical-adjacent retail logistics gains share at the steepest rate as cold chain requirements spread beyond pure healthcare distribution.
Technology:
Application maturity separates telematics deployments with proven ROI from emerging platforms still seeking scalable implementation models.
- Telematics:Real-time vehicle tracking, driver behavior monitoring, and predictive maintenance algorithms now constitute baseline fleet management infrastructure. Insurance risk modeling and DVSA compliance documentation drive replacement cycles for legacy GPS systems.
- IoT:Cargo condition monitoring for temperature, humidity, and shock exposure spreads across pharmaceutical and high-value electronics supply chains. Sensor hardware costs and data integration complexity constrain mid-sized carrier adoption.
- Automation:Robotic sortation, autonomous yard vehicles, and automated storage and retrieval systems concentrate in e-commerce fulfillment centers with sufficient volume density to justify capital deployment.
- Blockchain:Distributed ledger applications for customs documentation and provenance verification remain pilot-phase, with HMRC Goods Vehicle Movement Service integration representing the most viable near-term deployment path.
Telematics anchors the volume base while IoT-enabled cargo monitoring gains share at the steepest rate as pharmaceutical shippers mandate condition verification for contract eligibility.
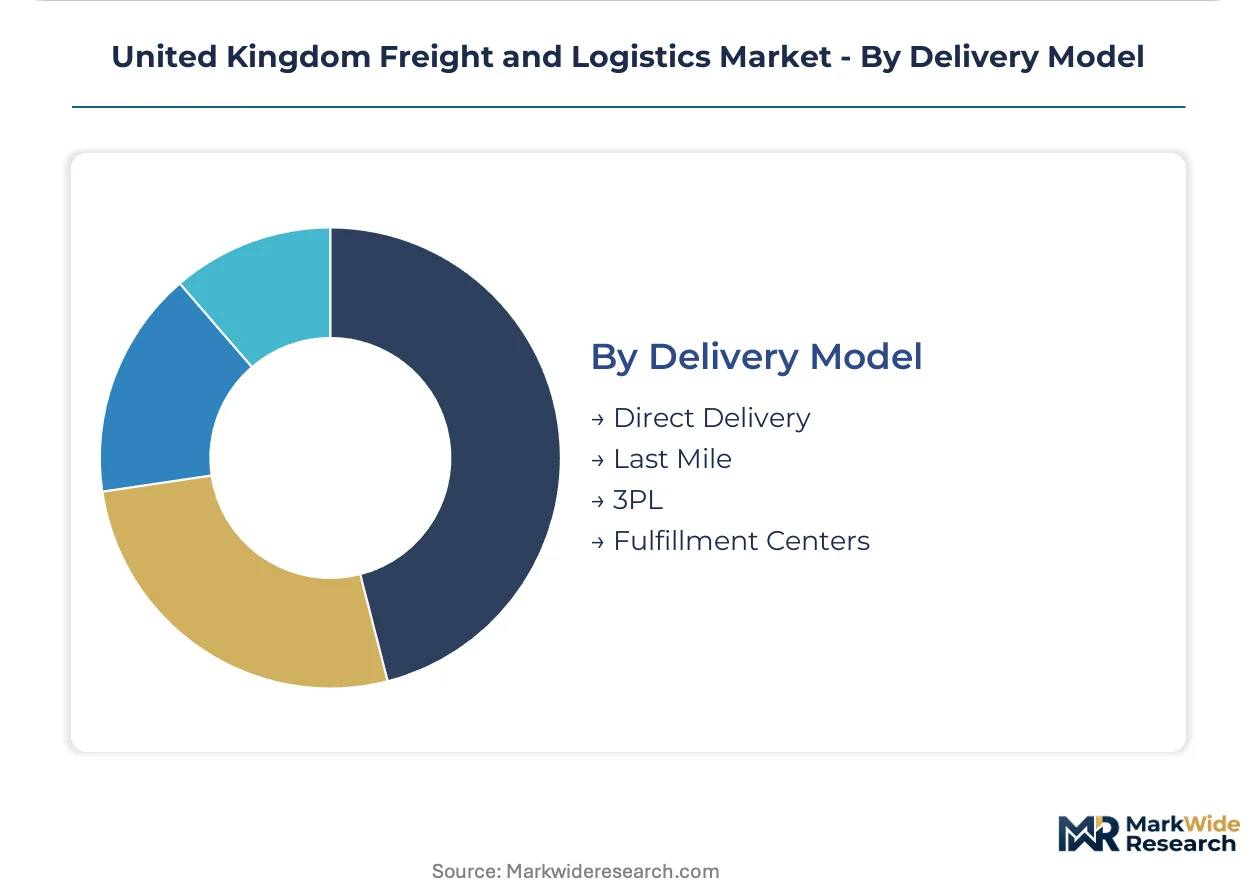
Delivery Model:
Geography determines model viability, with urban density enabling last-mile specialization and rural dispersion favoring 3PL consolidation.
- 3PL:Third-party logistics providers bundle transportation, warehousing, and inventory management under single-contract arrangements. GXO Logistics and DHL Supply Chain dominate tender awards through integrated service portfolios and ISO 9001 certification.
- Fulfillment Centers:Automated warehousing with robotic pick-and-pack operations concentrates in the Midlands to optimize national delivery radii. E-commerce retailers absorb disproportionate capital investment for same-day and next-day service commitments.
- Last Mile:Dedicated urban delivery fleets with electric van configurations serve congestion charge zones and Clean Air Zone mandates. Subcontractor gig-economy models compete with employed driver fleets on cost and service consistency.
- Direct Delivery:Manufacturer-to-retailer or manufacturer-to-customer movements bypass intermediary warehousing for time-critical or bulk commodity flows. Automotive parts and construction materials favor this model.
3PL anchors the volume base while fulfillment center automation gains share at the steepest rate as e-commerce retailers internalize logistics capabilities for service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Clean Air Zone mandates across English metropolitan areas are redirecting freight flows toward alternative corridors and multimodal terminals. HM Revenue & Customs post-Brexit customs controls continue reshaping cross-border routing decisions through the Goods Vehicle Movement Service. Regional logistics infrastructure investment concentrates where regulatory pressure and e-commerce fulfillment demand intersect.
London and Southeast England
Pharmaceutical distribution networks and high-value electronics supply chains dominate freight demand across the M25 corridor. Transport for London's Ultra Low Emission Zone and expanding congestion charging boundaries are eliminating diesel-dependent fleets from contract eligibility. Heathrow cargo terminals and Thames Valley automated fulfillment centers absorb disproportionate capital investment for temperature-controlled and same-day delivery services.
Midlands
Automotive just-in-sequence supply chains and e-commerce sortation hubs drive warehousing densification around Birmingham, Coventry, and Leicester. Birmingham's Clean Air Zone mandates zero-emission capability for fleet operators serving the city center, compressing margins for non-compliant carriers. Daventry International Rail Freight Terminal and East Midlands Gateway anchor intermodal connectivity between deep-sea ports and inland distribution networks.
North England
Renewable energy component logistics and Northern Powerhouse manufacturing corridors sustain bulk freight movements across Manchester, Leeds, and Liverpool. Greater Manchester's proposed Clean Air Zone threatens diesel fleet viability across the conurbation, accelerating electric HGV pilot programs. Liverpool2 deep-water terminal and Trafford Park rail intermodal facilities offer alternative Irish Sea routing as Dublin-Bristol volumes shift post-Brexit.
Scotland
Offshore wind installation supply chains and North Sea oil services logistics concentrate demand around Aberdeen, Dundee, and the Central Belt. Transport Scotland's freight modal shift grant program subsidizes rail and waterborne alternatives to road haulage for eligible commodities. Grangemouth port and Mossend rail terminal serve as critical consolidation points for Highland and Islands distribution.
Wales
Steel and heavy manufacturing logistics sustain bulk commodity movements through Port Talbot and Newport corridors. Welsh Government freight route investment focuses on A55 expressway resilience and Holyhead port capacity for Irish Sea trade. Milford Haven energy terminal and Cardiff distribution networks offer alternative routing as Dublin-Bristol freight patterns reconfigure under post-Brexit customs regimes.
United Kingdom Freight and Logistics Market Competitive Environment
Player mix skews toward diversified contract logistics providers with integrated warehousing and transportation capabilities. The vendor base concentrates around pan-European networks with UK-specific certification and customs brokerage competencies. Strategic archetypes include quality-accredited pharmaceutical specialists, automated e-commerce fulfillment operators, and multimodal forwarding integrators. Competitive dynamics center on ISO 9001 certification attainment for NHS tenders and zero-emission fleet deployment for Clean Air Zone contract eligibility.
Within the diversified contract logistics tier, GXO Logistics UK Limited and DHL Supply Chain Limited exemplify operators combining automated warehousing footprints with temperature-controlled pharmaceutical networks. Kuehne + Nagel occupies a position among multimodal forwarding specialists leveraging integrated sea-air-road solutions. These three anchors represent distinct competitive vectors: fulfillment automation, healthcare cold chain accreditation, and manufacturing export forwarding consolidation.
| Leading Market Players |
|---|
| XPO Logistics UK Limited |
| Davies Turner & Co. Limited |
| Unipart Logistics Limited |
| Maersk Logistics and Services UK Ltd |
| GXO Logistics UK Limited |
| Kuehne + Nagel |
| CEVA Logistics Limited |
| DB Schenker |
| DHL Supply Chain Limited |
| Others |
Value Chain & Pricing Dynamics
Asset utilization rates above 85% at major Midlands fulfillment centers enable operators to command premium rates for NHS pharmaceutical contracts while squeezing price floors for non-accredited road haulage. Scale economies in automated warehousing concentrate pricing power among ISO 9001-certified operators, forcing mid-tier carriers toward consolidation or niche specialization.
Pricing Analysis
Certification level creates the primary spread between contract tiers, with ISO 9001-accredited operators capturing 40-60% premiums over non-certified competitors in pharmaceutical logistics. Three-tier pricing structure separates premium cold-chain specialists from standard palletized freight and economy groupage services. Cost compression in standard road haulage intensifies because diesel volatility and Clean Air Zone compliance costs erode fixed-rate contract margins. E-commerce retailers exhibit highest price sensitivity due to free-shipping consumer expectations, while pharmaceutical manufacturers prioritize quality assurance over rate negotiation.
Supply Chain Analysis
Just-in-sequence inventory strategies dominate automotive supply chains across the West Midlands, with sub-hour delivery windows tolerating minimal buffer stock. Manufacturing inputs draw from Germany, China, and domestic UK suppliers for precision components and assembly materials. Raw material dependencies center on steel, semiconductors, and specialized polymers for vehicle production. Single-source vulnerability concentrates in Channel Tunnel routing for time-sensitive EU exports. Distribution runs through Daventry International Rail Freight Terminal and East Midlands Gateway for multimodal consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment through DVSA compliance and ISO 9001 certification creates substantial switching costs for contracted customers.
For Market Incumbents: Shield market position by accelerating zero-emission fleet deployment ahead of Clean Air Zone mandates in Birmingham and Greater Manchester. Deepen backward integration into customs brokerage capabilities to capture post-Brexit documentation revenue streams. Consolidate mid-sized competitors facing telematics capex burdens before they achieve compliance scale. For New Entrants and Emerging Players: Scottish offshore wind component logistics represents the most penetrable service layer, with maintenance supply chains underdeveloped relative to installation targets. Welsh border zone positioning at Holyhead and Milford Haven offers alternative Irish Sea routing as Dublin-Bristol volumes shift. Target carbon-accounted freight contracts with verified emission reporting as the primary go-to-market angle for retail and pharmaceutical buyers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors operators with proven IoT cargo monitoring deployment and scalable automated warehousing footprints. Long-term viability hinges on regulatory compliance infrastructure rather than pure asset scale. Acquisition targets should demonstrate ISO 9001 certification and established NHS tender relationships. Watch Clean Air Zone expansion announcements as the primary inflection signal for fleet replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Zero-Emission Fleet Conversion | Clean Air Zone mandates in Birmingham and Manchester eliminate diesel-dependent operators from contract eligibility. |
| Customs Brokerage Capability Buildout | HMRC Goods Vehicle Movement Service complexity creates captive revenue from post-Brexit documentation services. |
| Automated Warehousing Expansion | Robotic sortation hubs in the Midlands shorten last-mile radii for e-commerce fulfillment commitments. |
| IoT Cargo Monitoring Deployment | Pharmaceutical shippers mandate temperature verification for cold chain contract eligibility. |
| Scottish Renewable Energy Logistics Entry | Offshore wind maintenance supply chains remain underdeveloped relative to installation targets. |
Study Parameters
A standing panel of fleet operations directors, NHS procurement managers, pharmaceutical supply chain leads, and customs brokerage specialists provided ongoing calibration throughout the study period. Primary fieldwork combined structured interviews with secondary validation against HM Revenue & Customs trade statistics, Driver and Vehicle Standards Agency compliance records, Transport for London freight movement data, and Office for National Statistics logistics employment surveys. Bottom-up carrier capacity modeling triangulated against top-down sectoral GDP elasticity estimates.
Consistency checks validated volume and value outputs against external benchmarks including port throughput statistics from Southampton and Felixstowe, rail freight intermodal terminal utilization at Daventry and Trafford Park, and air cargo tonnage through East Midlands Airport. The analytical framework modeled segmentation across service type, customer vertical, technology deployment, and delivery model throughout the projection horizon. CAGRs derived from regression analysis of historical freight intensity ratios against industrial production indices, with specific inputs for e-commerce penetration rates and pharmaceutical cold chain expansion trajectories.
Forecasts assume regulatory continuity in DVSA Driver Certificate of Professional Competence enforcement and Clean Air Zone implementation timelines; material policy shifts would require re-modeling. Revision becomes warranted when zero-emission vehicle acquisition cost curves or customs processing delays cross thresholds that alter modal shift economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Indonesia Freight and Logistics Market
Logistics and Shipping
Germany Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
UK Logistics Market
Logistics and Shipping
GCC Event Logistics Market
Logistics and Shipping
Central and Eastern Europe Freight and Logistics Market
Logistics and Shipping
India E-Commerce Logistics Market
Logistics and Shipping
China Third-Party Logistics (3PL) Market
Logistics and Shipping
South Africa Freight and Logistics Market
Logistics and Shipping
Europe Automotive Logistics Market
Logistics and Shipping
Asia Pacific Domestic Courier Market
Logistics and Shipping
Canada Cold Chain Logistics Market
Logistics and Shipping
South America Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
Morocco Freight and Logistics Market
Logistics and Shipping
North America Last Mile Delivery Market
Logistics and Shipping
Germany Last Mile Delivery Market