

Automotive Supply Chain Resilience Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Supply Chain Resilience Market Insights
Modular supplier onboarding is broadening buyer choice across resilience platforms. Toyota Motor Corporation leverages its keiretsu network structure to sustain multi-tier visibility into semiconductor flows. BMW Group differentiates through captive regional warehousing for critical electronic components. Volkswagen Group anchors its resilience strategy with dedicated battery supply consortia spanning three continents.
Automotive supply chain resilience encompasses the integrated systems, processes, and technologies that manufacturers deploy to anticipate, absorb, and recover from supplier disruptions, typically incorporating real-time inventory tracking with sub-24-hour alert thresholds and multi-sourcing protocols for single-point-of-failure components. Its primary purpose is ensuring continuous vehicle production amid geopolitical, climatic, or logistical shocks. Semiconductor-focused resilience programs currently command the deepest investment pools among component categories, while AI Analytics and Digital Twins represent the fastest-expanding technology utilization segments as OEMs shift from reactive firefighting to predictive disruption modeling. Blockchain traceability for conflict minerals compliance remains comparatively mature with slower growth velocity.
The EU Chips Act, alongside REACH chemical substance regulations and Germany's KBA supply chain due diligence requirements, is mandating documented provenance for critical automotive inputs and penalizing opaque subcontracting tiers. These frameworks reshape procurement by converting resilience documentation from competitive advantage into market access prerequisite. Stakeholders must now decide whether to build in-house control tower capabilities or embed third-party risk orchestration platforms into their enterprise architecture.
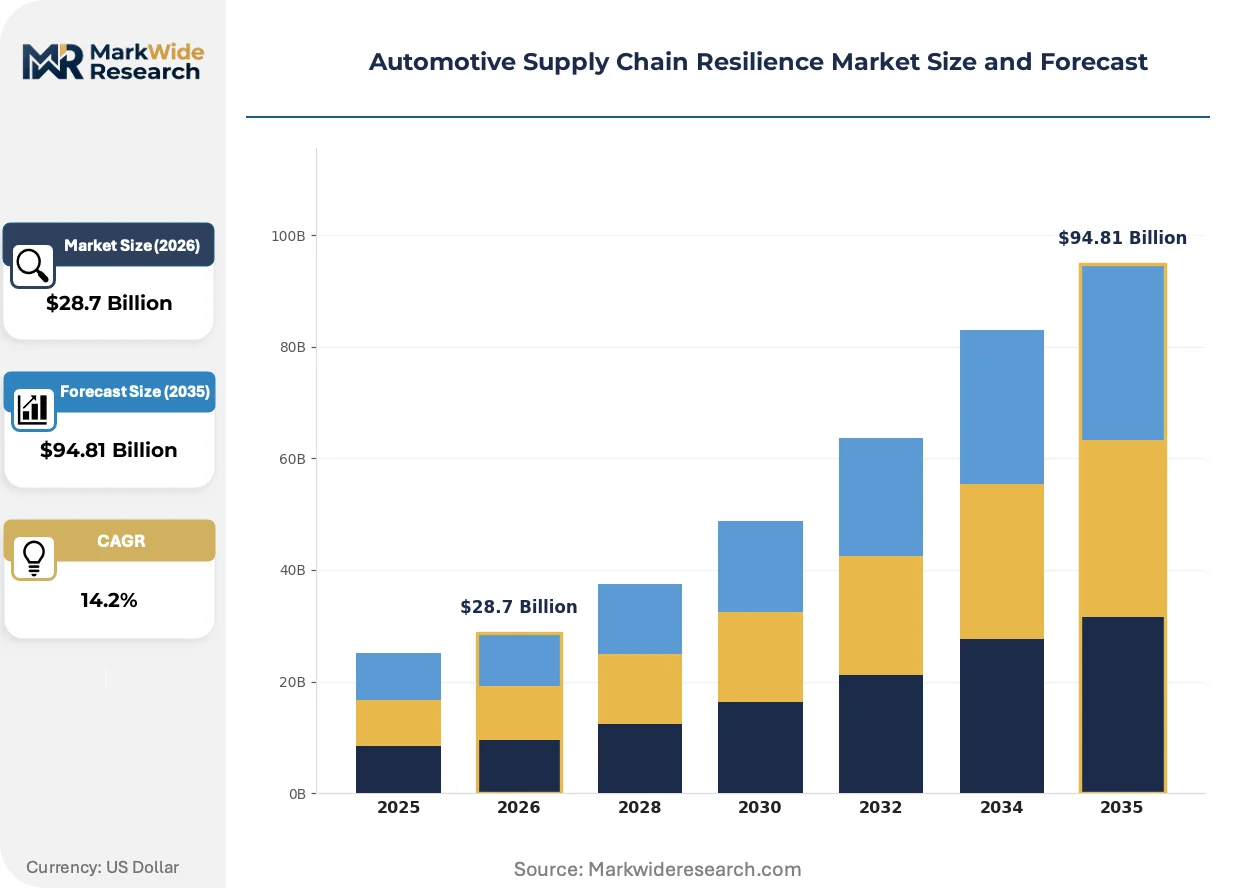
Market Dynamics
Semiconductor sovereignty mandates are forcing automotive OEMs to reconstitute supplier networks around regional fabrication clusters rather than cost-optimized global sourcing. The EU Chips Act and parallel U.S. CHIPS and Science Act are compressing multi-year qualification timelines into months, fundamentally altering procurement economics and inventory positioning across vehicle programs.
Growth Catalysts
- Sub-24-hour alert thresholds:Real-time inventory tracking systems now trigger automated sourcing switches before production lines stall. Tier-1 suppliers in Germany's automotive corridor deploy these thresholds as standard protocol.
- REACH chemical substance regulations:Documented provenance requirements for critical inputs are converting resilience documentation from competitive advantage into market access prerequisite across European markets.
- AI Analytics and Digital Twins:Predictive disruption modeling is displacing reactive firefighting as the dominant operational paradigm among premium vehicle manufacturers.
Market Restraints
- Legacy system integration costs:Embedded ERP architectures at established OEMs resist seamless API connections with third-party risk orchestration platforms, inflating implementation timelines.
- Concentrated rare earth processing:Magnet material refining capacity clusters in a single geography, creating unhedgeable exposure for electric drivetrain programs regardless of diversification elsewhere.
- Conflict minerals compliance opacity:Blockchain traceability for cobalt and lithium remains technically immature, leaving due diligence gaps that regulators are penalizing.
Strategic Opportunities
- Captive regional warehousing:BMW Group's dedicated battery component facilities demonstrate how physical inventory positioning can compress lead-time risk for critical electronic inputs.
- Multi-sourcing protocol standardization:Modular supplier onboarding platforms are broadening buyer choice across resilience technology vendors, reducing switching costs.
- Consortium-based supply agreements:Volkswagen Group's three-continent battery supply consortia illustrate how OEM collaboration can secure volume commitments without individual balance-sheet strain.
Industry Challenges
- Multi-tier visibility gaps:Subcontractor opacity beyond Tier-2 persists despite keiretsu-style network investments, leaving semiconductor flow interruptions undetected until assembly stops.
- Control tower capability scarcity:Talent pools combining supply chain operations with predictive analytics expertise remain shallow, forcing build-versus-buy decisions that neither option resolves cleanly.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Supply Chain Resilience Market Trends and Innovations
Digital thread technologies are collapsing the latency between disruption detection and sourcing response, compressing what required weeks into hours. This acceleration is redefining competitive differentiation around information velocity rather than inventory depth alone.
Digital twin platforms for supply network simulation are unifying previously siloed demand forecasting, inventory positioning, and logistics routing into single analytical environments. Tier-1 automotive suppliers deploy these systems to stress-test supplier failure scenarios before committing to vehicle program launches. The technology is unifying procurement and operations planning functions that historically operated on disconnected cadences, eliminating the buffer periods that once absorbed supplier shocks.
REACH chemical substance regulations and Germany's KBA supply chain due diligence requirements are mandating documented provenance for critical automotive inputs and penalizing opaque subcontracting tiers. These frameworks reshape procurement by converting resilience documentation from competitive advantage into market access prerequisite. Semiconductor-focused resilience programs currently command the deepest investment pools among component categories as OEMs race to pre-empt regulatory enforcement.
Keiretsu-style network structures are re-emerging as the preferred organizational form for semiconductor supply assurance, displacing arm's-length transactional sourcing that dominated the 2010s. Toyota Motor Corporation leverages this architecture to sustain multi-tier visibility into chip flows that conventional contract structures cannot replicate. This organizational innovation is most visible in Japan and Korea, where supplier relationship density historically supported such configurations and regulatory pressure now rewards their revival.
Automotive Supply Chain Resilience Market Segmentation
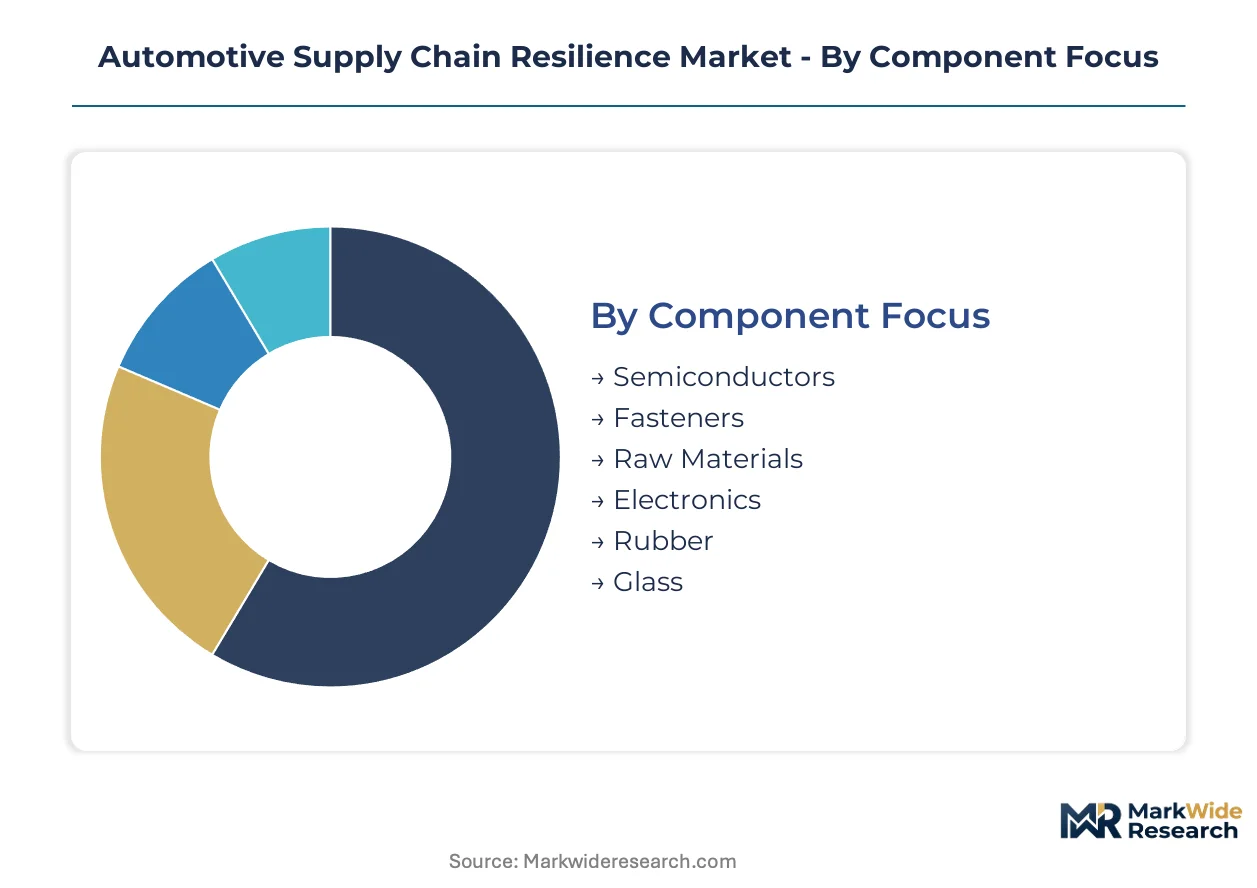
Automotive supply chain resilience strategies diverge sharply across component criticality and technology maturity. OEM procurement teams allocate capital differently depending on whether disruption risks stem from geopolitical concentration, material scarcity, or logistics fragility.
Component Focus:
Semiconductor supply concentration in East Asian fabrication clusters forces tiered investment intensity across component categories.
- Semiconductors:Advanced node chips and power electronics face 18-24 month qualification timelines that resist rapid supplier switching. German OEMs around Stuttgart and Wolfsburg deploy dedicated resilience programs here, driven by EU Chips Act regionalization mandates and sub-24-hour inventory alert protocols.
- Electronics:Battery management systems and sensor modules require documented provenance under REACH substance regulations. BMW Group's captive regional warehousing for these components demonstrates how physical positioning compresses lead-time risk when maritime routes congest.
- Raw Materials:Lithium, cobalt, and rare earth processing capacity clusters create unhedgeable exposure for electric drivetrain programs.
- Fasteners:Standardized mechanical components allow broader supplier qualification through modular onboarding platforms.
- Rubber:Synthetic and natural rubber supply tracks petrochemical and agricultural volatility respectively.
- Glass:Automotive glazing supply concentrates in float glass manufacturing corridors with high fixed-capital barriers.
Semiconductors absorb the bulk of installed resilience capacity; electronics is expanding most quickly as electrification multiplies vehicle chip counts.
Risk Management Strategy:
Cost tier differentiation separates premium OEMs with balance-sheet capacity for physical inventory from mid-market players dependent on network coordination.
- Strategic Stockpiling:Captive warehousing of critical electronic components requires capital intensity that only premium manufacturers sustain. Volkswagen Group's three-continent battery supply consortia illustrate how collaboration spreads this burden without individual balance-sheet strain.
- Supplier Collaboration:Keiretsu-style network structures provide multi-tier visibility that arm's-length contracting cannot replicate. Toyota Motor Corporation leverages this architecture to sustain chip flow transparency through subcontractor tiers.
- Diversification:Multi-sourcing protocols for single-point-of-failure components broaden buyer choice across resilience technology vendors.
- Local Sourcing:Regional fabrication mandates under the EU Chips Act compress qualification economics for European vehicle programs.
- Just-in-Time Modification:Buffer inventory insertion at Tier-1 nodes preserves line-feeding velocity while absorbing upstream shocks.
Strategic stockpiling commands the deepest capital deployment; supplier collaboration is climbing the fastest as organizational innovation outpaces physical infrastructure buildout.
Technology Utilization:
Application maturity separates predictive platforms with proven ROI from emerging traceability tools facing technical immaturity.
- AI Analytics:Predictive disruption modeling unifies demand forecasting, inventory positioning, and logistics routing into single analytical environments. Tier-1 suppliers deploy these systems to stress-test supplier failure scenarios before vehicle program launches.
- Digital Twins:Supply network simulation platforms collapse the latency between disruption detection and sourcing response from weeks to hours. This acceleration redefines competitive differentiation around information velocity rather than inventory depth alone.
- IoT Sensors:Real-time inventory tracking with sub-24-hour alert thresholds triggers automated sourcing switches before production lines stall.
- Machine Learning:Pattern recognition across historical disruption datasets improves forecast accuracy for supplier risk scoring.
- Cloud Platforms:Enterprise architecture decisions between in-house control towers and third-party risk orchestration platforms shape implementation timelines.
- Blockchain:Traceability for conflict minerals compliance remains technically immature, leaving due diligence gaps that regulators penalize under Germany's KBA requirements.
AI Analytics anchors current technology investment; Digital Twins represent the steepest expansion trajectory as OEMs shift from reactive firefighting to predictive modeling.
Stakeholder Type:
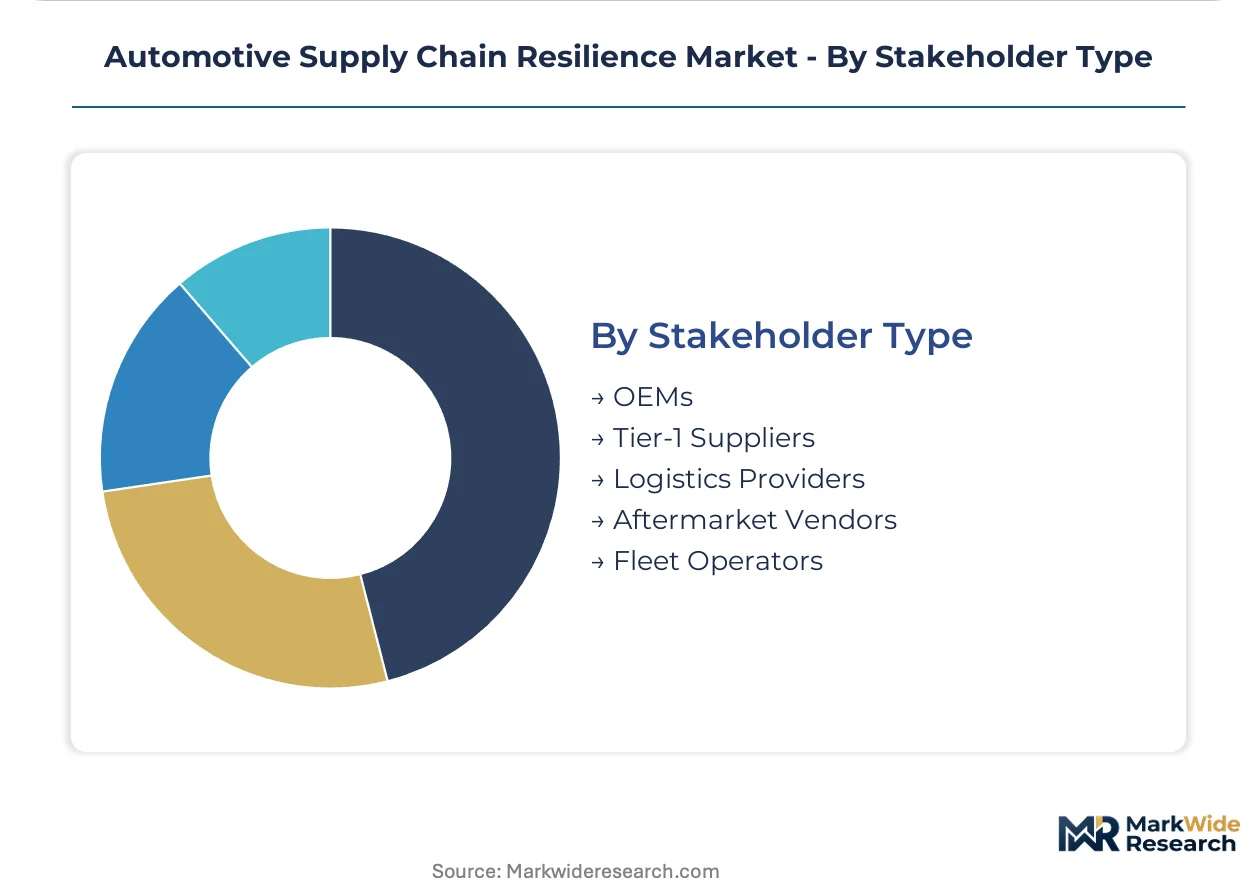
Customer type determines whether resilience investments flow toward production continuity or aftermarket availability.
- OEMs:Original equipment manufacturers face regulatory pressure to document provenance across subcontracting tiers, converting resilience documentation from competitive advantage into market access prerequisite.
- Tier-1 Suppliers:System integrators occupy the critical node where semiconductor flows converge with vehicle program schedules.
- Logistics Providers:Freight and warehousing operators capture value from lead-time compression when maritime and air cargo routes destabilize.
- Aftermarket Vendors:Spare parts distributors prioritize inventory availability over production line velocity, shifting risk tolerance thresholds.
- Fleet Operators:Commercial vehicle aggregators demand uptime guarantees that cascade backward through supplier qualification requirements.
OEMs concentrate the bulk of resilience technology procurement; Tier-1 Suppliers are gaining share fastest as outsourcing extends risk management responsibility downstream.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentration in East Asian semiconductor fabrication contrasts sharply with consumption gravity in European and North American vehicle assembly corridors. Germany and the United States absorb disproportionate investment in resilience infrastructure while China scales domestic sourcing mandates.
Germany
EU Chips Act regionalization mandates accelerate supplier qualification timelines around Stuttgart and Wolfsburg. The KBA supply chain due diligence requirements penalize opaque subcontracting tiers for critical electronic inputs. BMW Group anchors its resilience strategy with captive regional warehousing for battery management systems in Bavaria.
United States
CHIPS and Science Act subsidies compress multi-year semiconductor qualification windows into months for Detroit and Austin vehicle programs. NHTSA documentation requirements cascade backward through Tier-1 supplier networks. General Motors and Ford Motor Company deploy AI-driven control towers across Midwest assembly corridors.
China
Dual carbon goals and MIIT domestic content mandates reshape procurement for Yangtze River Delta electric vehicle production. GB standards for automotive semiconductor traceability tighten documented provenance requirements. BYD and SAIC Motor anchor keiretsu-style supplier networks around Shenzhen and Shanghai.
Japan
METI semiconductor resilience grants sustain multi-tier visibility investments for Toyota Motor Corporation's keiretsu architecture. JIS standards for supply chain risk documentation convert resilience investments into export market prerequisites. Nagoya and Tokyo corridors concentrate digital twin deployment for predictive disruption modeling.
South Korea
MFDS and METI-aligned resilience frameworks accelerate consortium-based battery supply agreements for Hyundai Motor Group. Seoul Capital Area OEMs deploy sub-24-hour inventory alert thresholds as standard protocol. Busan-Ulsan logistics hubs capture value from lead-time compression when maritime routes destabilize.
Automotive Supply Chain Resilience Market Competitive Landscape
The competitive structure tilts toward diversified multinational OEMs with balance-sheet capacity for physical inventory positioning. Tier-1 system integrators and specialized resilience technology vendors occupy fragmented downstream layers. Two strategic archetypes dominate: keiretsu-networked incumbents leveraging relationship density for multi-tier visibility, and consortium-building scale players spreading capital burdens across collaborative agreements. Dominant competitive moves include strategic partnerships for regional fabrication access and portfolio diversification into captive warehousing infrastructure.
Within the keiretsu-networked tier, Toyota Motor Corporation exemplifies how relationship density sustains chip flow transparency through subcontractor tiers. Among consortium-building scale players, Volkswagen Group occupies a position illustrating how three-continent collaboration spreads capital intensity without individual balance-sheet strain. BMW Group represents the captive regional warehousing archetype, demonstrating how physical inventory positioning compresses lead-time risk for critical electronic components.
| Leading Market Players |
|---|
| Volkswagen Group |
| Toyota Motor Corporation |
| Stellantis |
| Hyundai Motor Group |
| General Motors |
| Ford Motor Company |
| BMW Group |
| Mercedes-Benz Group |
| Honda Motor |
| Others |
Pricing and Supply Chain Analysis
Lithium carbonate benchmark pricing from the Shanghai Futures Exchange cascades through battery supply tiers into three-tier pricing structure across premium, standard, and economy resilience service levels. OEM procurement teams in Germany's automotive corridor absorb volatility through long-term offtake contracts while Tier-1 suppliers pass spot-market exposure downstream.
Pricing Analysis
Cost-down pressure on mid-market resilience platforms accelerates because EU Chips Act qualification timelines compress supplier switching economics. Three-tier pricing structure across premium, standard, and economy levels separates OEMs with captive warehousing capacity from network-dependent players. ISO 26262 functional safety certification commands material premiums in semiconductor sourcing tiers. Fleet operators exhibit highest price sensitivity due to uptime guarantee obligations, while premium OEMs prioritize supply assurance over unit cost.
Supply Chain Analysis
Dual-sourcing mandates from NHTSA and KBA regulators force Tier-1 suppliers to qualify secondary semiconductor fabricators in Taiwan, South Korea, and the United States. Advanced node chip supply rests on concentrated rare earth processing capacity and photoresist chemical flows from Japan and Germany. Single-source vulnerability persists for EUV lithography equipment regardless of multi-sourcing elsewhere. Distribution runs through regional battery supply consortia and captive warehousing nodes rather than spot-market spot purchases.
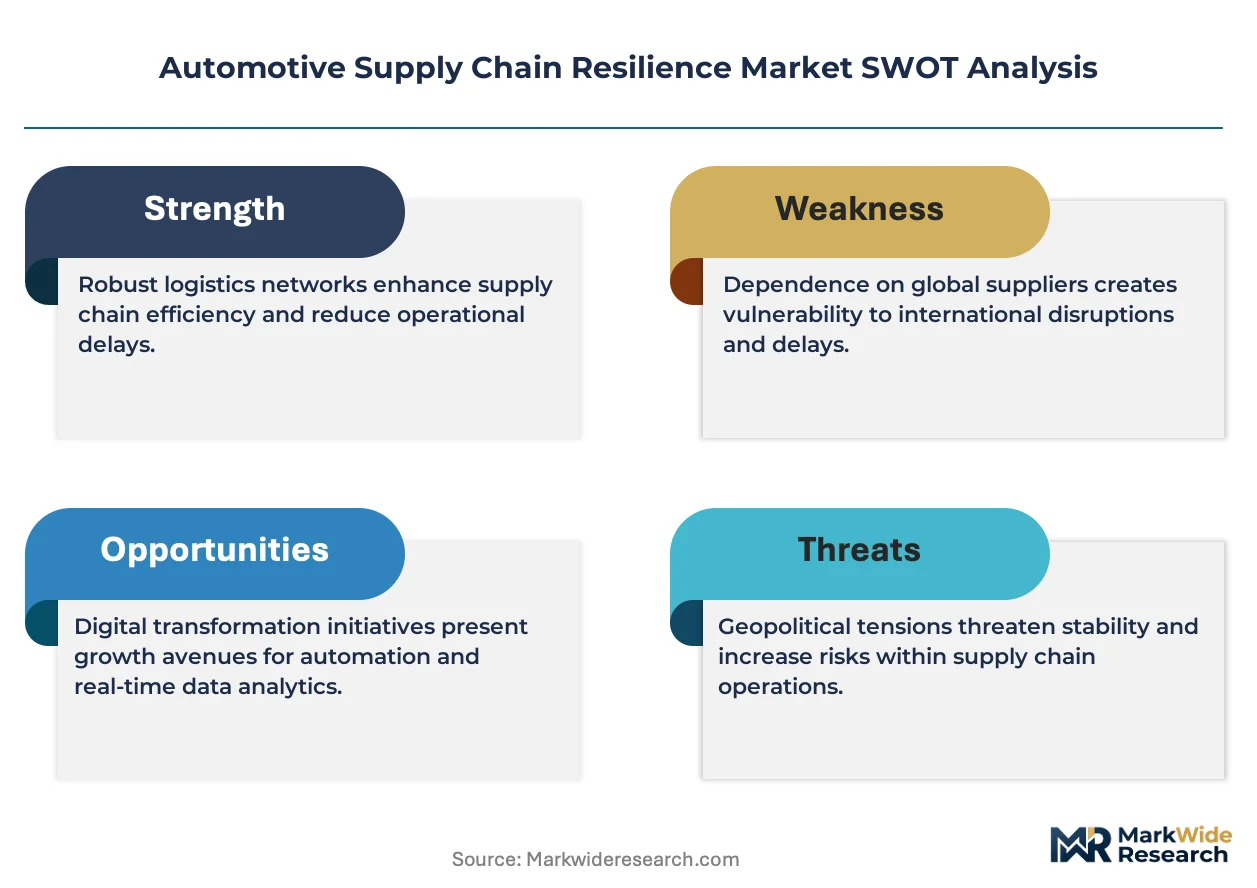
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive supply chain resilience is consolidating around balance-sheet capacity for physical inventory, with EU Chips Act compliance costs forcing weaker technology vendors toward acquisition or exit.
For Market Incumbents: Acquire predictive analytics talent pools before control tower capability scarcity deepens. Secure backward integration into regional semiconductor packaging capacity to defend against emerging pure-play resilience SaaS vendors. Cement keiretsu-style supplier relationships through METI-aligned grant programs in Japan and Korea.
For New Entrants and Emerging Players: Begin with aftermarket vendor segments where inventory availability tolerance exceeds production-line velocity requirements. Target Tier-2 visibility gaps beyond semiconductor flows where subcontractor opacity persists. Lead with blockchain-traceability modules for REACH conflict minerals compliance as regulatory enforcement tightens.
For Investors and Strategic Acquirers: Distressed-cycle entries favor distressed pure-play digital twin vendors in Germany's Stuttgart-Wolfsburg corridor as OEMs consolidate vendor relationships. Long-term viability hinges on integration with incumbent ERP architectures rather than displacement. Watch for KBA enforcement actions against opaque subcontracting tiers as inflection signal for compliance-technology demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Consortium Formation | Volkswagen Group's three-continent agreements spread capital intensity without individual balance-sheet strain. |
| Captive Regional Warehousing | BMW Group's Bavarian facilities compress lead-time risk for battery management systems when maritime routes congest. |
| Keiretsu Network Revival | Toyota Motor Corporation's relationship density sustains chip flow transparency through subcontractor tiers. |
| AI Control Tower Deployment | General Motors and Ford Motor Company deploy predictive disruption modeling across Midwest assembly corridors. |
| Digital Twin Platform Integration | Tier-1 suppliers stress-test supplier failure scenarios before vehicle program launches. |
Research Methodology
Independent corroboration across OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distribution operators, and resilience technology vendors underwrites the qualitative findings. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, SEC automotive division filings, and EU Chips Act implementation trackers. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separated volume effects from price-mix shifts across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from logistic curve fitting to technology adoption patterns and regulatory deadline clustering. Forecast inputs incorporated semiconductor fab capacity expansion timelines and battery raw material contract coverage ratios without year-specific assumptions.
Underlying measurement precision varies by segment; semiconductor-focused resilience programs carry tighter precision than blockchain traceability for conflict minerals. Forecasts reflect documented assumptions about regulatory enforcement intensity and supplier qualification acceleration. Deviation in EU Chips Act subsidy disbursement timing or REACH penalty severity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.