
 Europe Logistics Automation Market | 2026-2036
Europe Logistics Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Logistics Automation Market Analytics
Multi-sourced automation integration is decoupling from traditional single-vendor warehouse overhauls across European distribution networks. Swisslog sustains technology leadership through deep specialization in robotic piece-picking and automated storage retrieval for pharmaceutical cold chains. SSI Schaefer anchors its competitive position via in-house production of conveyor modules and shuttle systems, giving it upstream control over deployment timelines. TGW Logistics Group differentiates through dedicated engineering for grocery and fashion verticals, where SKU volatility demands adaptive automation architectures.
Europe logistics automation encompasses the hardware, software, and control systems that mechanize material flow, inventory handling, and order fulfillment across distribution and production facilities, typically integrating programmable logic controllers with real-time warehouse execution software operating at millisecond response latencies. Its primary purpose is to reduce labor dependency, cut order cycle times, and improve inventory accuracy in high-throughput environments. Automated Guided Vehicles and Mobile Robotics represent the fastest-expanding technology category as lithium-ion traction batteries and LiDAR navigation slash deployment costs for mid-size warehouses. Cloud-Based and Hybrid Solutions deployment models are capturing disproportionate margin pools by converting capital expenditure into recurring software subscriptions while preserving on-site control over latency-sensitive sorting operations.
The EU Green Deal and F-Gas Regulation are reshaping equipment specifications by mandating lower-global-warming-potential refrigerants in cold-chain automation and setting phased CO2 intensity ceilings for logistics real estate. REACH compliance and CE marking requirements enforce machine safety standards and chemical substance disclosures that filter non-compliant component suppliers from European vendor lists. Stakeholders must monitor how the EU AI Act's risk classification framework applies to autonomous mobile robots making real-time navigation decisions in shared human-robot warehouse zones.
Market Dynamics
The EU Green Deal's binding emissions ceilings for logistics real estate are forcing warehouse operators to electrify material handling fleets and retrofit facilities before 2030 compliance deadlines. This regulatory pressure is compressing capital deployment cycles and reshaping vendor selection criteria across European distribution networks.
Growth Catalysts
- E-Commerce Fulfillment Density:Parcel volumes through Germany's Rhine-Ruhr corridor and France's Île-de-France hub are saturating manual sortation capacity. Automated robotic picking and high-speed sortation systems are displacing conventional conveyor infrastructure in these clusters.
- REACH and CE Marking Harmonization:Unified machine safety standards across EU member states are reducing cross-border certification friction for automation vendors. Component suppliers achieving CE marking gain preferential access to procurement lists of major logistics operators.
- Lithium-Ion Traction Battery Economics:Energy density improvements and pack cost declines are extending autonomous mobile robot runtime to full warehouse shifts. Mid-size facilities in the Netherlands and Belgium are deploying AMR fleets without infrastructure overhaul.
Market Restraints
- Steel and Rare Earth Input Volatility:Permanent magnet motors and precision conveyor framing depend on neodymium and steel alloy supply concentrated in Chinese processing facilities. Price swings in these inputs compress automation vendor margins on fixed-price installation contracts.
- Specialized Systems Integration Bottleneck:Europe's certified warehouse control software engineers concentrate in southern Germany and northern Italy. Project delays from talent scarcity extend deployment timelines for multi-vendor automation integrations.
- Legacy Warehouse Structural Constraints:Post-war industrial buildings across northern England and eastern Europe lack floor load ratings and ceiling heights for high-bay AS/RS installation. Retrofit costs often exceed greenfield automation deployment economics.
Strategic Opportunities
- Pharmaceutical Cold Chain Automation:F-Gas Regulation mandates for lower-global-warming-potential refrigerants are accelerating replacement of legacy cold storage infrastructure. Automated storage retrieval systems with integrated temperature monitoring capture premium positioning in this compliance-driven upgrade cycle.
- Poland and Czech Republic Warehouse Modernization:Central European logistics hubs serving German and Austrian markets operate with automation penetration rates below western European benchmarks. Regional 3PLs are soliciting turnkey automation partnerships to close this gap.
- AI Act Risk Classification Alignment:Autonomous mobile robots with real-time navigation in shared human-robot zones fall under high-risk system categories. Vendors pre-certifying compliance gain first-mover advantage in safety-sensitive grocery and pharmaceutical verticals.
Industry Challenges
- PLC-to-Cloud Integration Complexity:Warehouse execution software must maintain millisecond response latencies for sortation control while feeding analytics to cloud platforms. Bridging this operational technology-information technology divide requires scarce dual-competency engineering teams.
- EU AI Act Conformity Assessment Timeline:High-risk autonomous system certifications involve notified body review cycles extending 12-18 months. Product roadmaps must front-load compliance documentation to avoid market entry delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Logistics Automation Market |
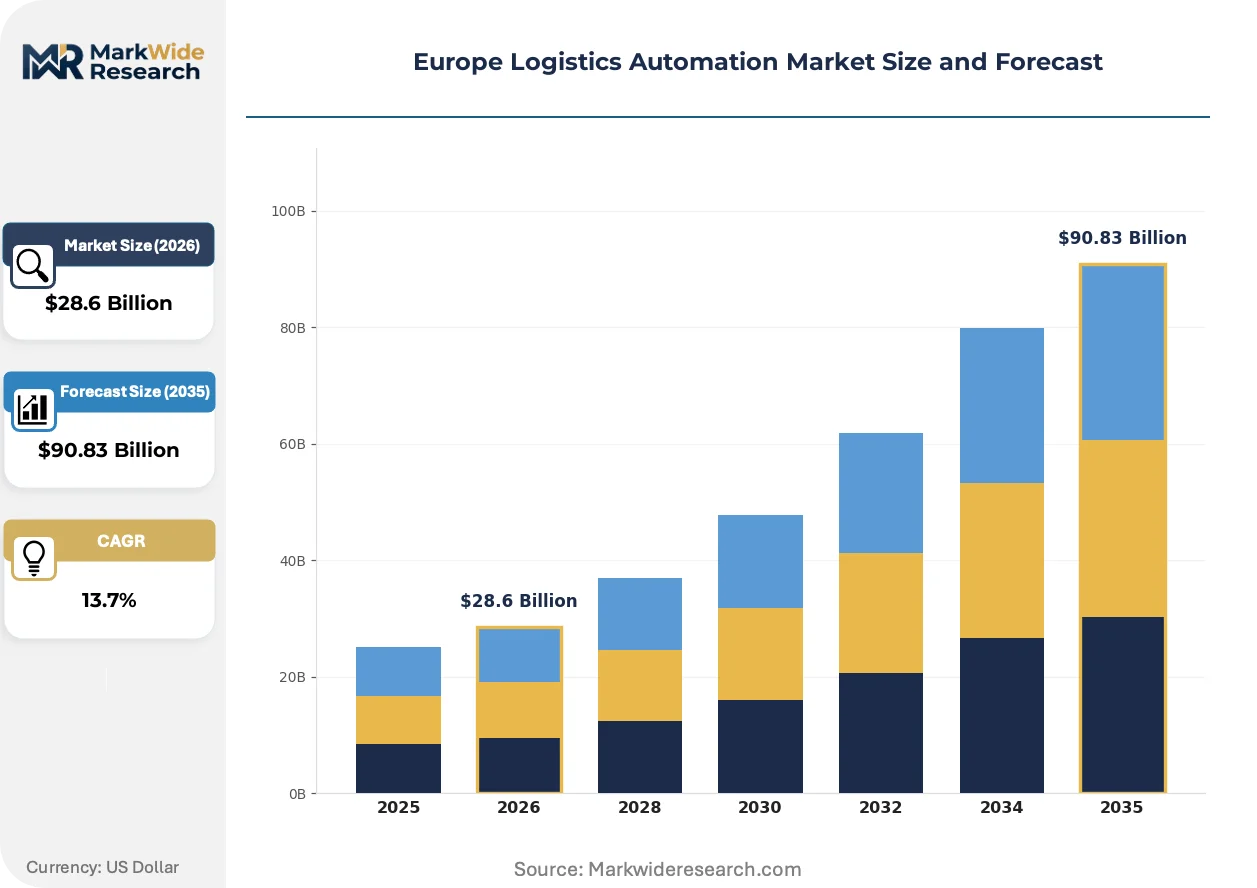
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $90.83 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Warehouse Management Systems, Robotics Process Automation, Automated Guided Vehicles, Mobile Robotics End User: Retail, E-commerce, Manufacturing, Transportation Deployment: On-Premises, Cloud-Based, Hybrid Solutions, Software as a Service Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | Swisslog, SSI Schaefer, TGW Logistics Group, KNAPP, Jungheinrich, Dematic, Vanderlande, BEUMER Group, WITRON, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Logistics Automation Market Evolving Landscape
Digital twin simulation is compressing automation deployment risk by enabling virtual commissioning of warehouse control systems before physical installation. This capability is converging with generative AI for scenario modeling to reshape how European operators validate capital-intensive retrofit decisions.
LiDAR navigation and 3D vision systems are converging with edge computing architectures to enable autonomous mobile robots to operate in dynamic, human-shared warehouse zones without fixed infrastructure. Grocery and fashion 3PLs in Germany and the Netherlands are deploying these adaptive fleets to handle SKU volatility that defeats traditional AGV guide-path systems. The structural consequence is collapsing the minimum viable warehouse size for automation from 50,000 square meters to below 15,000 square meters.
F-Gas Regulation phasedown schedules are mandating CO2 and ammonia-based refrigeration in new cold-chain automation installations. Equipment vendors are engineering AS/RS systems with integrated temperature stratification and energy recovery to meet these specifications. Pharmaceutical distribution facilities in Denmark and Sweden are adopting these configurations earliest due to national building codes accelerating beyond EU minimums.
Third-party logistics procurement is fragmentating from decade-long automation leases toward shorter performance-based contracts with embedded technology refresh clauses. Retailers in France and Spain are unbundling hardware ownership from software and maintenance to preserve balance sheet flexibility. This shift concentrates vendor risk on residual equipment value while transferring obsolescence exposure to automation suppliers.
Europe Logistics Automation Market Segmentation
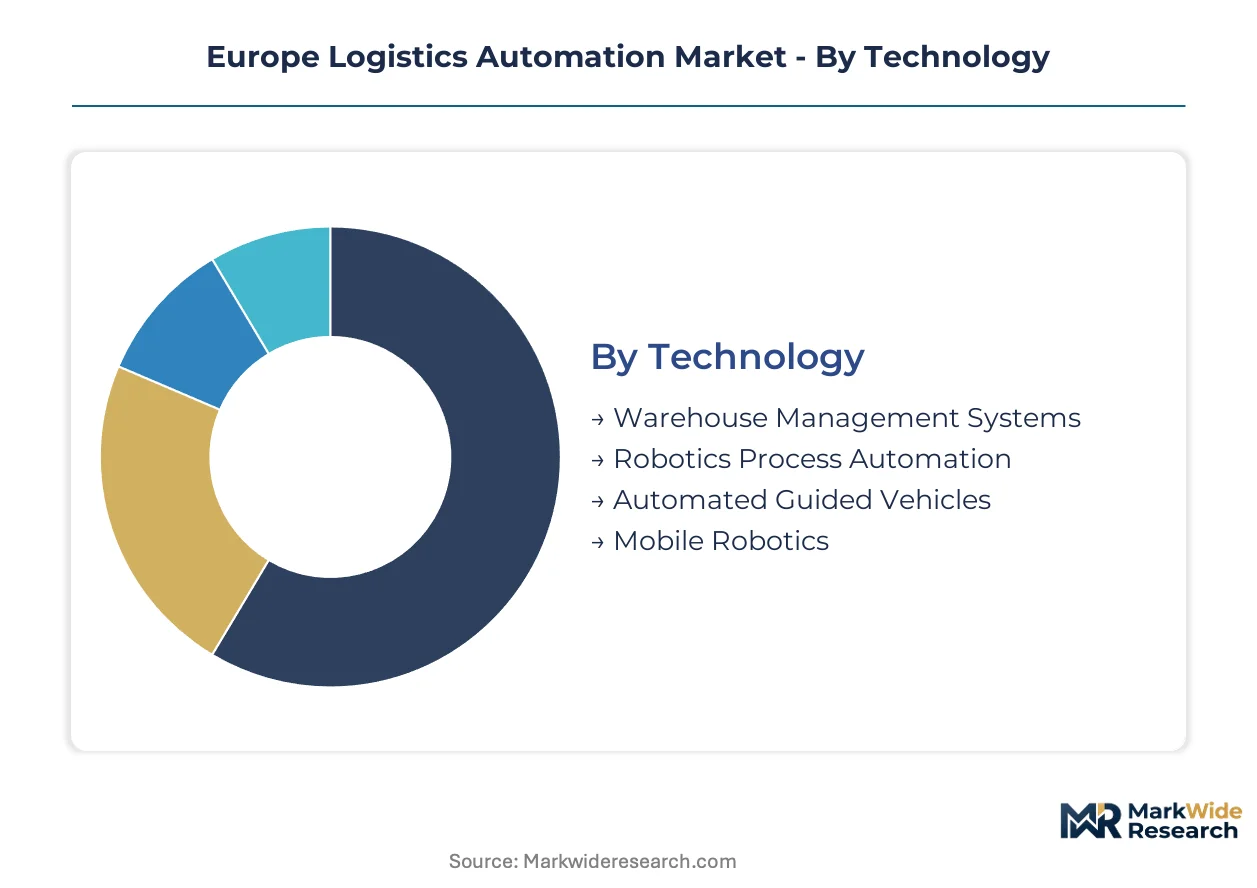
Capital allocation across technology tiers determines automation deployment timelines in European distribution networks. Procurement teams weight upfront hardware investment against recurring software commitments when structuring multi-year fulfillment contracts.
Technology:
Capital intensity varies sharply across technology layers, with fixed infrastructure demanding heavy initial outlay while software layers convert expenditure to operational budgets.
- Warehouse Management Systems:Cloud-native platforms orchestrate inventory flow through API-connected material handling equipment. German automotive suppliers and French pharmaceutical distributors are prioritizing WMS upgrades that embed EU AI Act compliance documentation for automated decision audit trails.
- Robotics Process Automation:Software bots automate data entry, invoice matching, and customs documentation workflows without physical infrastructure. Polish and Czech 3PLs deploy RPA to bridge legacy ERP systems with modern fulfillment demands.
- Automated Guided Vehicles:Magnetic tape or QR-code guided transport systems move palletized loads along fixed routes. These systems dominate established warehouse footprints in northern Italy where floor modification costs deter navigation-free alternatives.
- Mobile Robotics:LiDAR-equipped autonomous units navigate dynamic environments without infrastructure retrofit. Netherlands grocery fulfillment centers are deploying these fleets to handle seasonal SKU volatility that defeats fixed-path systems.
Warehouse Management Systems absorb the bulk of installed capacity; Mobile Robotics is expanding most quickly.
End User:
Application complexity shapes automation architecture, with sectors handling high SKU variability demanding adaptive rather than deterministic systems.
- Retail:Store replenishment and omnichannel fulfillment drive investment in case-picking automation and returns processing systems. Spanish and Italian fashion retailers prioritize robotic piece-picking for e-commerce order assembly.
- E-commerce:Same-day delivery promises necessitate high-speed sortation and dense storage retrieval. Parcel volumes through Germany's Rhine-Ruhr corridor are saturating manual capacity and accelerating robotic deployment.
- Manufacturing:Just-in-sequence supply to assembly lines requires synchronized material flow with production schedules. Automotive supplier clusters in Bavaria and Baden-Württemberg anchor demand for conveyor-integrated AS/RS.
- Transportation:Cross-dock facilities and port terminals utilize yard management automation and container handling systems. Rotterdam and Hamburg port operators are electrifying container handling fleets under EU Green Deal emissions ceilings.
E-commerce captures the largest share of new automation contracts; Retail is climbing the fastest as brick-and-mortar operators retrofit for omnichannel fulfillment.
Deployment:
Customer balance sheet preferences are fragmenting procurement between capital-preserving subscription models and control-preserving on-site installation.
- On-Premises:Perpetual licensing with local server infrastructure maintains millisecond response latencies for sortation control. High-throughput facilities in the Netherlands and Belgium retain on-premises WMS for operational technology isolation.
- Cloud-Based:Multi-tenant SaaS platforms reduce IT overhead while enabling remote system updates. Mid-size French and Spanish 3PLs favor cloud deployment to preserve capital for network expansion.
- Hybrid Solutions:Edge computing nodes handle latency-critical control while analytics flow to cloud platforms. German pharmaceutical cold chain operators adopt hybrid architectures to satisfy both GxP data integrity and scalability requirements.
- Software as a Service:Subscription pricing bundles maintenance and feature updates into predictable operational expenditure. Italian regional logistics providers are shifting procurement toward SaaS to align technology costs with transaction volumes.
On-Premises retains the majority of legacy installations; Hybrid Solutions are gaining share fastest as operators balance control with connectivity demands.
Service Type:
Vendor revenue stability depends on service mix, with implementation providing upfront margin and maintenance generating recurring annuity streams.
- Consulting:Front-end engineering studies assess automation feasibility against warehouse constraints and throughput requirements. Post-war industrial buildings across northern England drive demand for structural retrofit consulting before AS/RS installation.
- Implementation:Physical installation, software configuration, and commissioning of integrated automation systems. Swiss and Austrian pharmaceutical distributors prioritize implementation partners with F-Gas Regulation compliance expertise for cold chain retrofit.
- Maintenance:Preventive service contracts and spare parts provisioning ensure system availability. Lithium-ion traction battery maintenance is emerging as a specialized sub-segment as AMR fleets scale.
- Support:Help desk, remote diagnostics, and software update services. Cloud-native deployments shift support toward subscription-based continuous improvement rather than break-fix response.
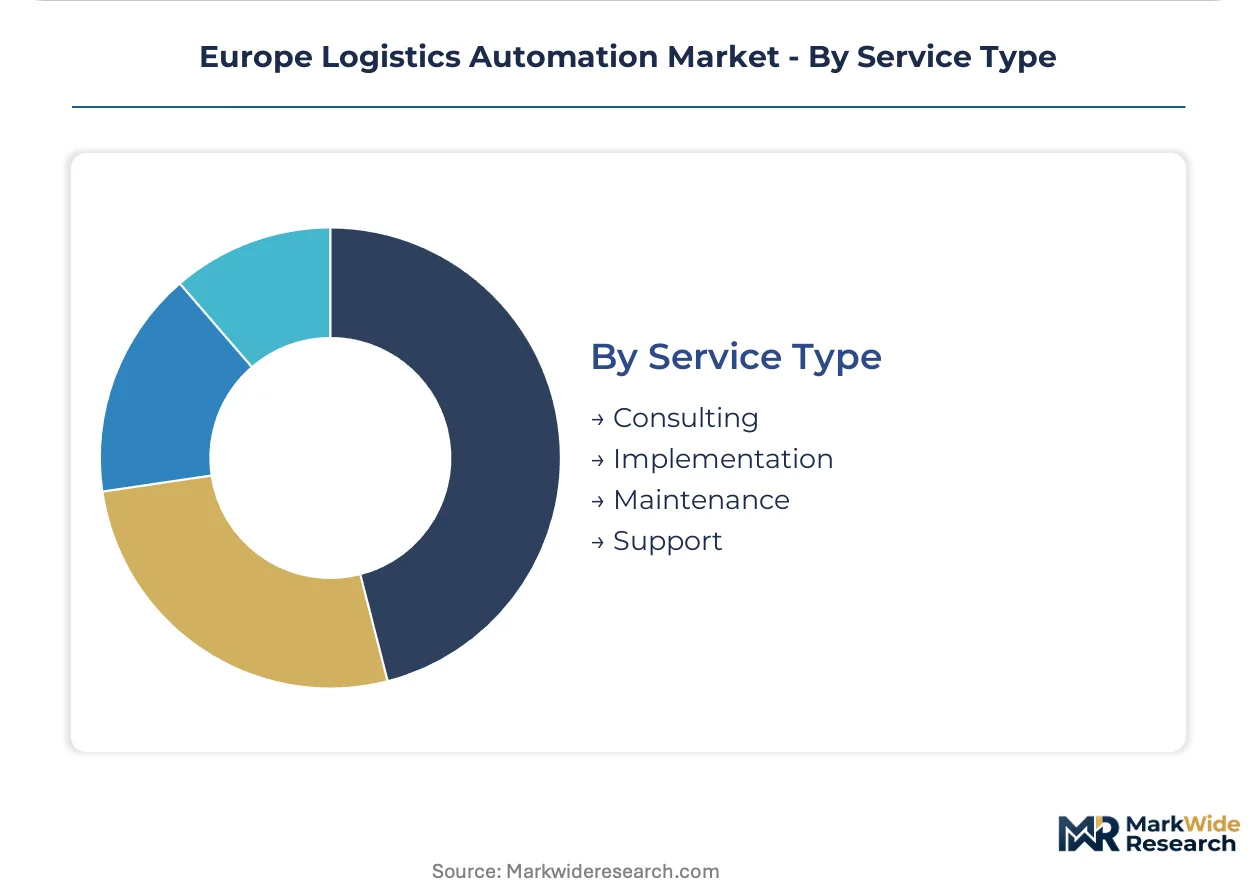
Implementation commands the largest project value; Support is expanding most quickly as subscription models displace perpetual licensing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel and rare earth processing corridors in China's Inner Mongolia and Shandong provinces anchor upstream supply for European automation hardware, yet downstream demand concentrates in Rhine-Ruhr logistics clusters and North Sea port networks where warehouse density meets regulatory pressure.
Germany
Automotive supplier clusters in Bavaria and Baden-Württemberg drive synchronized material flow automation for just-in-sequence assembly lines. The EU Green Deal's binding emissions ceilings for logistics real estate compel warehouse operators in the Rhine-Ruhr corridor to electrify material handling fleets before 2030 compliance deadlines. Parcel volumes through Düsseldorf and Cologne distribution hubs are saturating manual sortation capacity.
France
Île-de-France e-commerce fulfillment centers are accelerating deployment of robotic picking systems to meet same-day delivery promises. REACH and CE marking harmonization reduces cross-border certification friction for automation vendors serving French pharmaceutical distributors. Fashion retailers in Paris and Lyon prioritize robotic piece-picking for omnichannel order assembly.
Netherlands
Rotterdam port operators are electrifying container handling fleets under EU Green Deal emissions targets. Lithium-ion traction battery economics enable mid-size facilities in Venlo and Tilburg to deploy autonomous mobile robot fleets without infrastructure overhaul. Grocery fulfillment centers deploy adaptive AMR fleets to handle seasonal SKU volatility.
Poland
Central European logistics hubs serving German and Austrian markets operate with automation penetration rates below western European benchmarks. Regional 3PLs in Warsaw and Wrocław are soliciting turnkey automation partnerships to close this gap. Post-war industrial buildings in Upper Silesia drive demand for structural retrofit consulting before AS/RS installation.
United Kingdom
Post-war industrial buildings across northern England lack floor load ratings and ceiling heights for high-bay AS/RS installation. Retailers in London and the Midlands are unbundling hardware ownership from software to preserve balance sheet flexibility. Cloud-native warehouse management platforms reduce IT overhead for mid-size British 3PLs.
Europe Logistics Automation Market Competitive Landscape
Global majors compete with regional champions across technology specialization and vertical integration depth. The vendor base organizes into three tiers: diversified conglomerates with full-stack automation portfolios, mid-size specialists with deep vertical expertise, and component-focused engineering houses. Strategic differentiation concentrates on robotic piece-picking for pharmaceutical cold chains, in-house conveyor production for deployment timeline control, and grocery-fashion adaptive architectures for SKU volatility. Competitive moves center on M&A for software capabilities and strategic partnerships for lithium-ion battery supply security.
Within the European specialist tier, Swisslog, SSI Schaefer, and TGW Logistics Group occupy distinct positioning archetypes. Swisslog represents deep specialization in robotic piece-picking and automated storage retrieval for temperature-controlled pharmaceutical distribution. SSI Schaefer exemplifies upstream manufacturing integration through captive conveyor module and shuttle system production. TGW Logistics Group anchors adaptive automation engineering for grocery and fashion verticals where demand unpredictability defeats fixed-path material handling systems.
| Leading Market Players |
|---|
| Swisslog |
| SSI Schaefer |
| TGW Logistics Group |
| KNAPP |
| Jungheinrich |
| Dematic |
| Vanderlande |
| BEUMER Group |
| WITRON |
| Others |
Value Network & Pricing Analysis
Neodymium and steel alloy price indices cascade through European automation vendor cost structures, compressing margins on fixed-price installation contracts while forcing unbundling of hardware ownership from software subscriptions. Procurement teams at Dutch and Belgian mid-size facilities now negotiate lithium-ion traction battery supply separately from AMR fleet deployment, fragmenting traditional turnkey pricing.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium automation contracts from economy-tier procurement. Three-tier pricing structure across premium, standard, and economy levels reflects CE marking certification depth and software subscription commitment length. Cost compression in standard-tier conveyor systems is intensifying because Chinese steel input volatility feeds through to fixed-price contracts. Mid-size Polish and Czech 3PLs exhibit highest price sensitivity; German pharmaceutical cold chain operators show least sensitivity due to F-Gas Regulation compliance premiums.
Supply Chain Analysis
Certified warehouse control software engineers concentrate in southern Germany and northern Italy, constraining systems integration capacity for multi-vendor deployments. Permanent magnet motors draw from Chinese rare earth processing in Inner Mongolia and Shandong; precision conveyor framing sources from German and Italian steel mills. Single-source vulnerability in neodymium supply chains exposes vendors to input cost spikes. Distribution runs through Rhine-Ruhr logistics corridors and Rotterdam port networks to downstream fulfillment centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
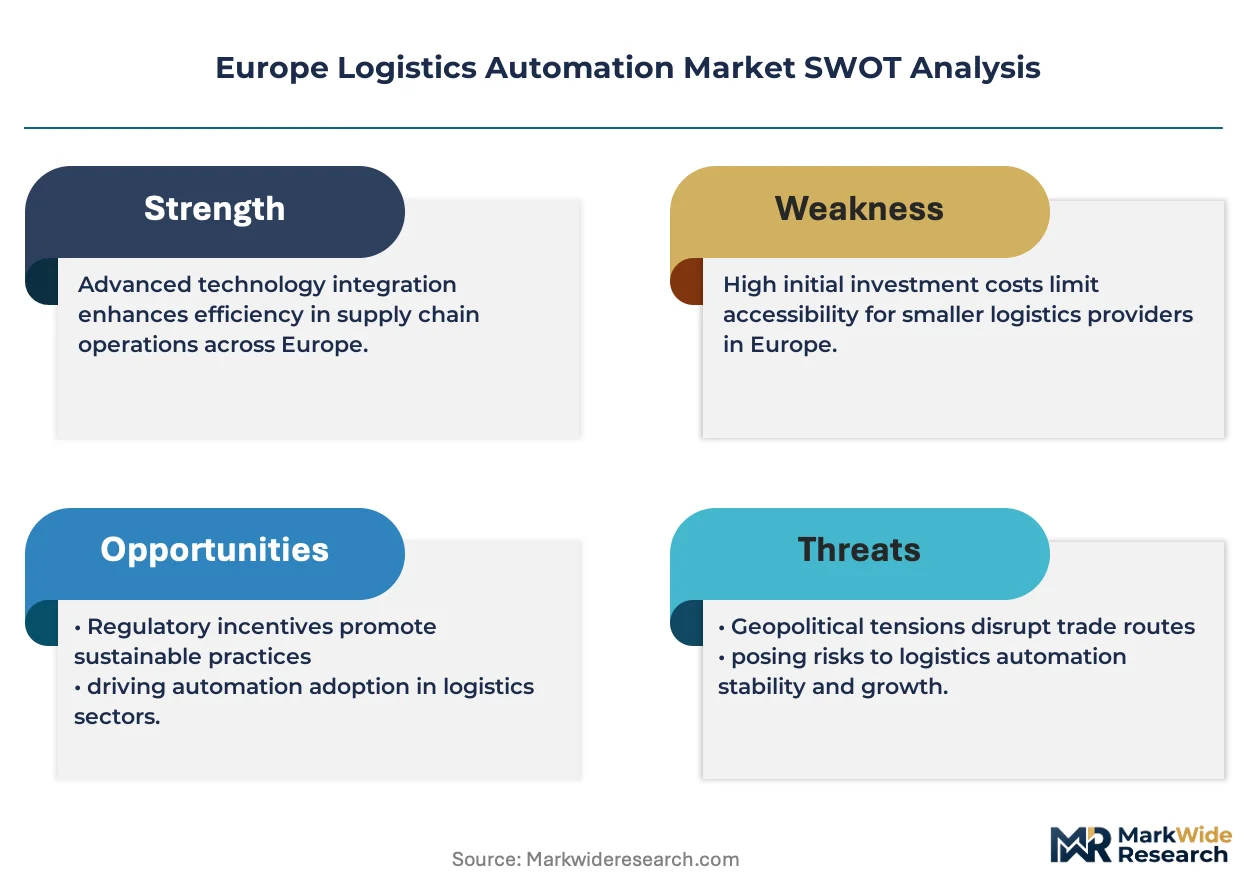
European logistics automation is becoming a vertical-integration race where captive lithium-ion battery supply and in-house conveyor production determine deployment timeline control and margin defense.
For Market Incumbents: Anticipate margin compression from Chinese rare earth input volatility by securing long-term neodymium supply agreements or engineering magnet-free motor alternatives. Deepen software capabilities through targeted acquisition of warehouse execution specialists to bridge PLC-to-cloud integration gaps that delay multi-vendor projects. For New Entrants and Emerging Players: The price-point gap between premium Swisslog-grade pharmaceutical systems and economy-tier Polish 3PL installations offers white-space entry. Target Central European regional logistics providers in Warsaw and Wrocław with turnkey AMR fleets requiring minimal infrastructure retrofit. Lead with subscription-based SaaS pricing to align technology costs with transaction volumes. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-size specialists with F-Gas Regulation cold chain expertise in Denmark and Sweden, where national building codes accelerate beyond EU minimums. Long-term viability hinges on software-defined automation architectures that convert capital expenditure into recurring revenue. Watch for EU AI Act high-risk system certification delays as inflection signal for compliance-ready vendor premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Lithium-Ion Battery Supply Agreement | Secures traction power for AMR fleets against Chinese processing concentration. |
| EU AI Act Pre-Certification | Accelerates market entry for autonomous mobile robots in shared human-robot zones. |
| Backward Integration into Conveyor Manufacturing | Compresses deployment timelines by eliminating external module procurement delays. |
| Pharmaceutical Cold Chain Partnership | Captures F-Gas Regulation-driven retrofit cycles in Danish and Swedish distribution. |
| Cloud-Native WMS Platform Launch | Converts capital expenditure to recurring subscription revenue for mid-size 3PLs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with warehouse operations directors, automation procurement managers, systems integration engineers, and cold chain compliance officers. ECHA REACH registrations, EU AI Act implementation guidance, and F-Gas Regulation phasedown schedules provided regulatory boundary conditions. Bottom-up facility-level automation deployment data triangulated against top-down vendor revenue disclosures.
Data-stream reconciliation across technology tier, deployment model, end-use vertical, and regional regulatory cluster produced volume and value estimates throughout the forecast period. CAGRs derived from logistic growth curve fitting to historical installation trajectories, adjusted for EU Green Deal emissions ceiling compliance deadlines. Lithium-ion battery cost curves and LiDAR sensor price erosion rates fed mobile robotics expansion assumptions.
Underlying measurement precision varies by segment; Warehouse Management Systems and Automated Guided Vehicles carry tighter precision than emerging Mobile Robotics categories where adoption patterns remain fluid. Forecasts reflect assumptions about EU AI Act certification timelines, rare earth supply stability, and e-commerce fulfillment density saturation. Material deviation in neodymium price volatility, notified body review cycle extensions, or Rhine-Ruhr parcel volume growth warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
South Africa Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Oman Third-Party Logistics (3PL) Market
Logistics and Shipping
Canada Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
India Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
US Domestic Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Peru Road Freight Transport Market
Logistics and Shipping
Global Drone Logistics and Transportation Market
Logistics and Shipping
Brazil 3PL Market
Logistics and Shipping
Terminal Tractors Market
Logistics and Shipping
Same Day Delivery Service Market
Logistics and Shipping
Latin America Air Freight Market
Logistics and Shipping
Brazil Courier, Express, and Parcel (CEP) Market
Logistics and Shipping
Ocean Freight Forwarding Market
Logistics and Shipping
GCC Automotive Logistics Market
Logistics and Shipping
Thailand Courier Express Parcel (CEP) Market
Logistics and Shipping
North America Freight Forwarding Market