
 Vehicle Trip Computers Market | 2026-2036
Vehicle Trip Computers Market Size, Share, and Industry Trends Forecast 2026-2036
Vehicle Trip Computers Market Analytics
Aftermarket service revenue is reconfiguring competitive stakes across the vehicle trip computers landscape. Trimble Inc. anchors its position through precision agriculture and construction fleet channels where hardware-software bundles command loyalty. Samsara Inc. differentiates via cloud-native architecture that pulls real-time vehicle data into unified fleet dashboards. Geotab Inc. leverages an open-platform API strategy that lets third-party developers build on its telematics stack, deepening ecosystem lock-in.
A vehicle trip computer is an onboard electronic system that collects, processes, and displays real-time vehicle performance data including fuel consumption, distance traveled, engine diagnostics, and navigation parameters through integrated sensors and embedded software. Its primary commercial purpose is to optimize fleet operational efficiency, reduce fuel expenditure, and enforce driver compliance with route and safety protocols. Embedded Systems capture the dominant margin pool as automotive OEMs spec factory-integrated solutions that eliminate aftermarket installation friction. Cloud Solutions represent the fastest-expanding segment because fleet managers demand centralized visibility across dispersed vehicle assets without local server maintenance. GPS-Based technology retains volume leadership, though OBD-II interfaces are gaining ground as regulatory mandates broaden diagnostic data access.
The EPA enforces OBD-II compliance for emissions monitoring, directly mandating the diagnostic port infrastructure that trip computers exploit for data extraction. The EU Green Deal and associated CO2 performance standards for commercial vehicles push fleet operators toward telematics investments that document and reduce carbon intensity. NHTSA guidelines on electronic logging devices further cement trip computer installation as a compliance necessity rather than optional efficiency tool. Stakeholders must weigh whether to build captive cloud platforms or partner with established telematics providers as data sovereignty and cybersecurity standards tighten across jurisdictions.
Market Dynamics
Fleet digitization mandates and embedded sensor cost curves are compressing hardware margins while expanding software attach rates across commercial vehicle installations.
Growth Catalysts
- OBD-II Integration Mandates:EPA emissions enforcement in the United States requires standardized diagnostic ports that trip computers exploit for real-time data extraction, expanding addressable hardware volumes.
- EU Green Deal CO2 Standards:Commercial vehicle operators across Germany, France, and Poland must document carbon intensity through telematics, creating compliance-driven procurement pull.
- Construction Fleet Digitization:Heavy equipment operators in mining and infrastructure verticals are spec'ing factory-embedded trip computers to track idle time and fuel burn across dispersed job sites.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea dominate automotive-grade microcontroller fabrication, exposing OEMs to allocation risk during demand spikes.
- GDPR Data Sovereignty Friction:Cross-border fleet operators face jurisdictional complexity when transmitting driver behavior data from EU-registered vehicles through non-EU cloud infrastructure.
- Aftermarket Price Erosion:Low-cost OBD-II dongle manufacturers in Shenzhen are commoditizing basic telematics hardware, compressing margin pools for mid-tier suppliers.
Strategic Opportunities
- India Fleet Modernization:The country's PLI scheme for automotive electronics and expanding commercial vehicle sales create underpenetrated demand for embedded trip computer installations.
- Predictive Maintenance Convergence:Integration of vibration sensors with engine diagnostic algorithms enables new revenue streams from prognostic service contracts.
- Brazil ANVISA Driver Hour Tracking:Pending commercial transport safety regulations will mandate electronic logging devices, opening Latin America's largest vehicle market to compliant trip computer suppliers.
Industry Challenges
- Embedded Software Talent Scarcity:Automotive firmware engineers with ISO 26262 functional safety expertise command premium compensation, constraining R&D velocity for mid-scale suppliers.
- Legacy Fleet Integration Complexity:Pre-CAN-bus commercial vehicles require protocol translation hardware that extends deployment timelines and elevates installation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vehicle Trip Computers Market |
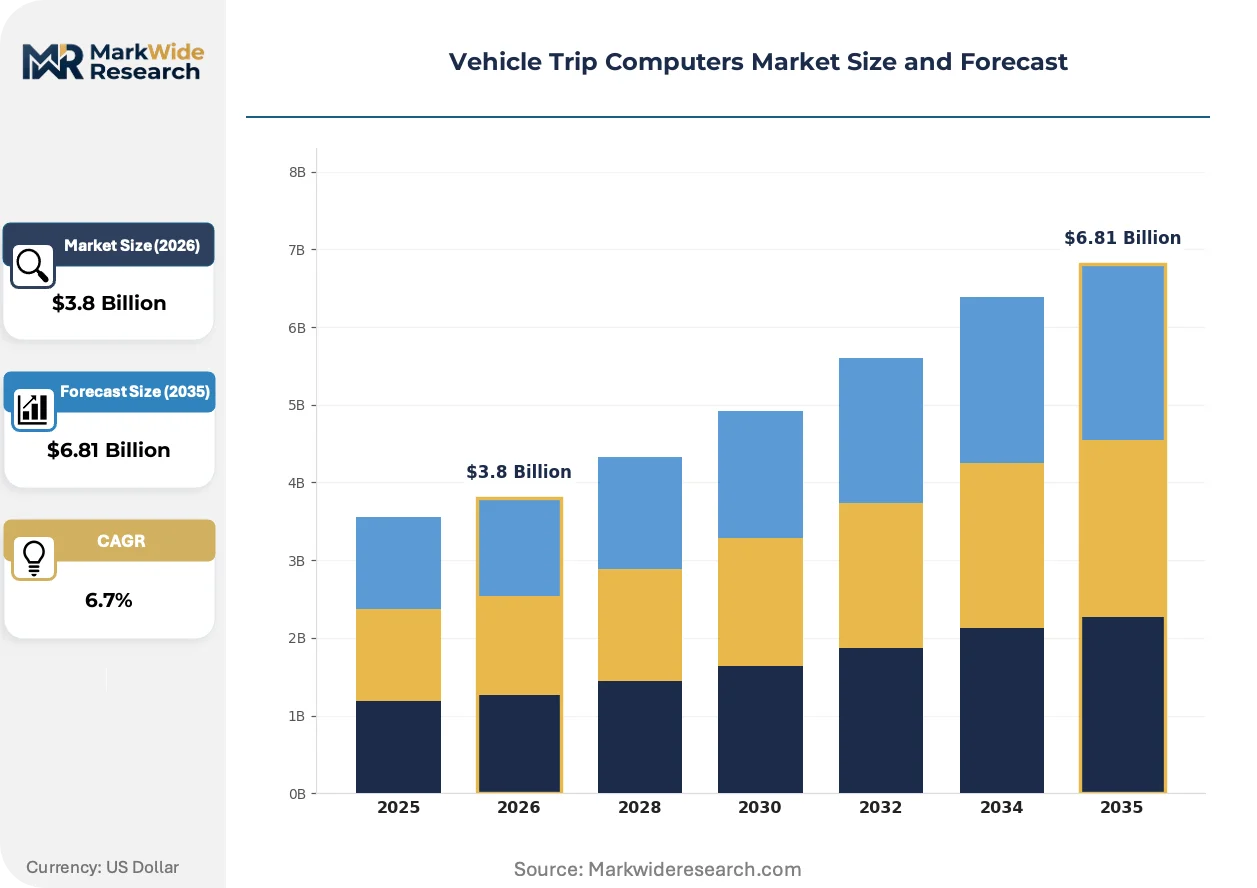
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Units, Embedded Systems, Smartphone Apps, Cloud Solutions End User: Commercial Fleets, Individual Drivers, Automotive OEMs, Transportation Hubs Technology: GPS-Based, OBD-II, Bluetooth, Wi-Fi Application: Route Optimization, Fuel Efficiency, Driver Behavior Monitoring, Maintenance Alerts |
| Companies Covered | Geotab Inc., Verizon Connect Inc., Trimble Inc., Samsara Inc., CalAmp Corp., TomTom NV, Solera Holdings LLC, Zonar Systems Inc., Lytx Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vehicle Trip Computers Market Evolving Landscape
Edge computing architectures and subscription pricing models are redistributing value capture from hardware shipments toward recurring software revenue streams.
Edge AI inference chips from Qualcomm and NXP are collapsing the latency gap between sensor data generation and actionable driver alerts. Regional freight carriers in the US Midwest are piloting these modules for real-time fatigue detection. The technology is collapsing the distinction between trip computers and active safety systems, forcing suppliers to recertify under NHTSA guidelines.
CSRD sustainability reporting obligations in the European Union now require granular Scope 1 emissions documentation from commercial fleet operators. This regulatory pressure is accelerating replacement cycles for legacy telematics hardware that lacks automated carbon accounting APIs. German logistics conglomerates are consolidating vendor relationships to ensure audit-ready data lineage.
Subscription-based feature unlocking is displacing perpetual licensing for advanced analytics modules. Fleet managers in Australia's mining corridors now activate fuel-optimization algorithms through monthly payments rather than upfront capital expenditure. This consumption pattern shift is compressing customer acquisition costs while extending lifetime value calculations for platform vendors.
Vehicle Trip Computers Market Segmentation
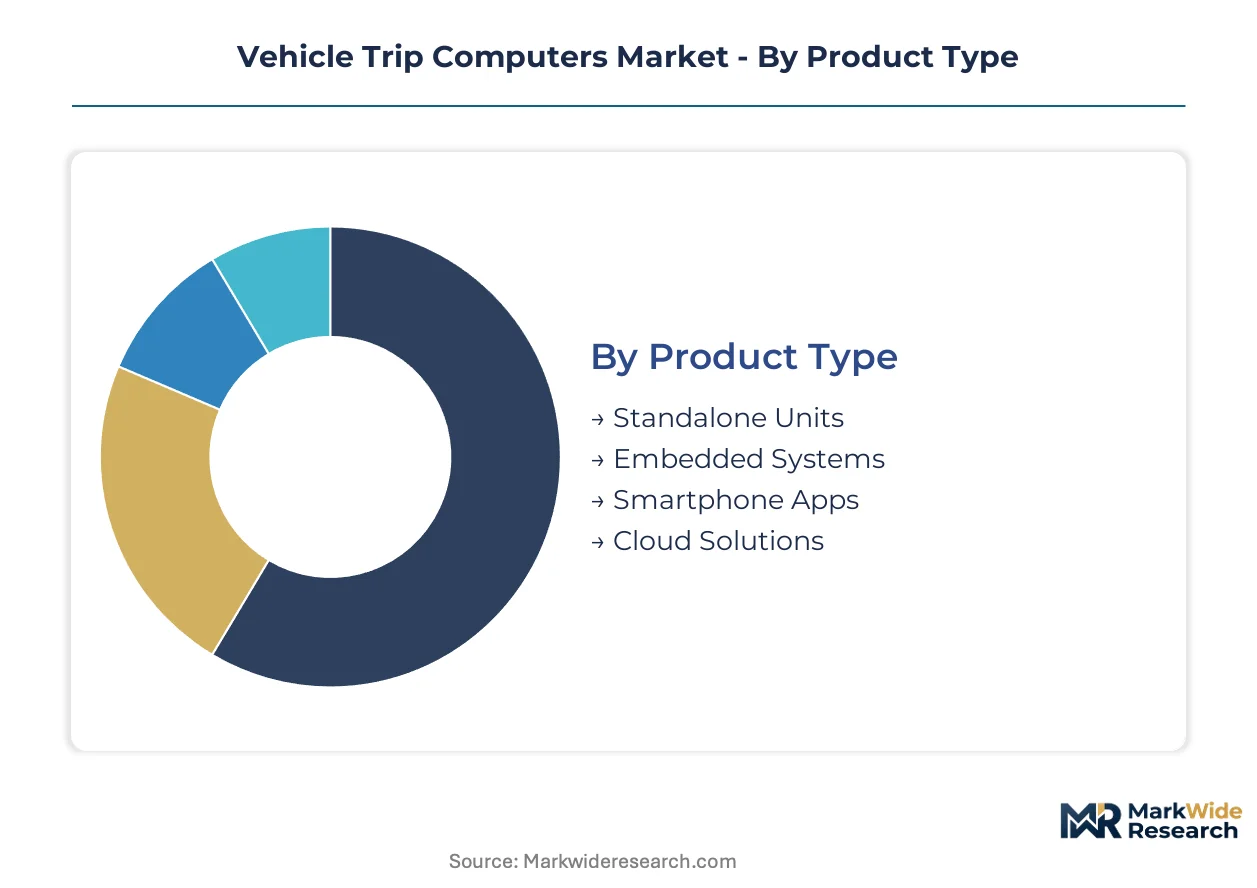
Trip computer segmentation reveals divergent margin structures across hardware and software value layers. Product architecture choices determine whether suppliers capture one-time equipment revenue or recurring platform fees.
Product Type:
Cost tier differentiation separates capital-intensive hardware from software-as-a-service models with divergent cash flow profiles.
- Standalone Units:Self-contained display modules with integrated processors and dedicated power management. Demand concentrates among owner-operator trucking fleets across the US Midwest where retrofitting legacy vehicles avoids full telematics overhaul costs. Hardware margins compress as Shenzhen manufacturers commoditize basic units.
- Embedded Systems:Factory-integrated computing modules hardwired into vehicle CAN bus architecture with OEM-grade firmware validation. Automotive electronics clusters in Germany drive procurement concentration as fleet digitization mandates eliminate aftermarket installation friction. These systems command premium pricing through functional safety certification under ISO 26262.
- Smartphone Apps:Software-only solutions leveraging mobile device sensors and OBD-II Bluetooth dongles for data acquisition.
- Cloud Solutions:Centralized data aggregation platforms with browser-based dashboards and API access for third-party integration.
Embedded Systems holds installed capacity. Cloud Solutions is rotating up the share rankings.
End User:
Customer type determines purchasing authority complexity and contract duration, from individual discretionary spend to multi-year fleet procurement cycles.
- Commercial Fleets:Multi-vehicle operators with centralized procurement functions and compliance documentation requirements. German logistics conglomerates and US Midwest freight carriers dominate demand as EU Green Deal CO2 standards and EPA emissions enforcement mandate telematics investment. These buyers prioritize audit-ready data lineage and predictive maintenance integration.
- Automotive OEMs:Vehicle manufacturers specifying trip computers as factory-installed equipment during platform development cycles. Procurement concentrates among German premium brands integrating embedded systems with advanced driver assistance architectures. Long validation timelines and functional safety requirements create high switching costs.
- Individual Drivers:Consumer purchasers seeking fuel economy feedback and navigation assistance through aftermarket installation.
- Transportation Hubs:Airport, port, and intermodal terminal operators tracking shuttle and service vehicle movements.
Commercial Fleets dominates contract value. Automotive OEMs is climbing the fastest on unit volume.
Technology:
Data acquisition methodology defines hardware requirements, installation complexity, and regulatory compliance scope.
- GPS-Based:Satellite positioning systems calculating location, speed, and route adherence through triangulation from orbital constellations. Retains volume leadership across Brazilian mining corridors and Australian remote freight routes where cellular coverage remains intermittent. Hardware cost curves and multi-constellation receiver availability sustain deployment scale.
- OBD-II:Standardized diagnostic port interfaces extracting engine parameters, emissions data, and fault codes directly from vehicle control modules. US EPA mandates require standardized port infrastructure across light-duty and commercial vehicle fleets, creating regulatory-driven installation pull. Dongle manufacturers compete on price while platform vendors differentiate through analytics layers.
- Bluetooth:Short-range wireless protocol connecting peripheral sensors to central processing units or mobile devices.
- Wi-Fi:Higher-bandwidth connectivity enabling bulk data offload and over-the-air software updates.
GPS-Based maintains the widest geographic footprint. OBD-II is gaining share fastest through regulatory compulsion.
Application:
Use case specialization determines sensor fusion requirements and software development priorities across operational domains.
- Route Optimization:Algorithmic path planning incorporating real-time traffic, fuel station locations, and delivery time windows. Heavy equipment operators in mining and infrastructure verticals deploy these capabilities across dispersed job sites to minimize idle time and fuel burn. Integration with enterprise resource planning systems elevates contract values.
- Driver Behavior Monitoring:Accelerometer and GPS data fusion detecting harsh braking, rapid acceleration, and speed violations. Fleet managers in Australia's mining corridors activate these modules through subscription payments rather than upfront capital expenditure, compressing customer acquisition costs while extending vendor lifetime value.
- Fuel Efficiency:Consumption tracking and driver coaching algorithms targeting operating cost reduction.
- Maintenance Alerts:Predictive algorithms flagging component degradation before failure through vibration sensor and diagnostic data integration.
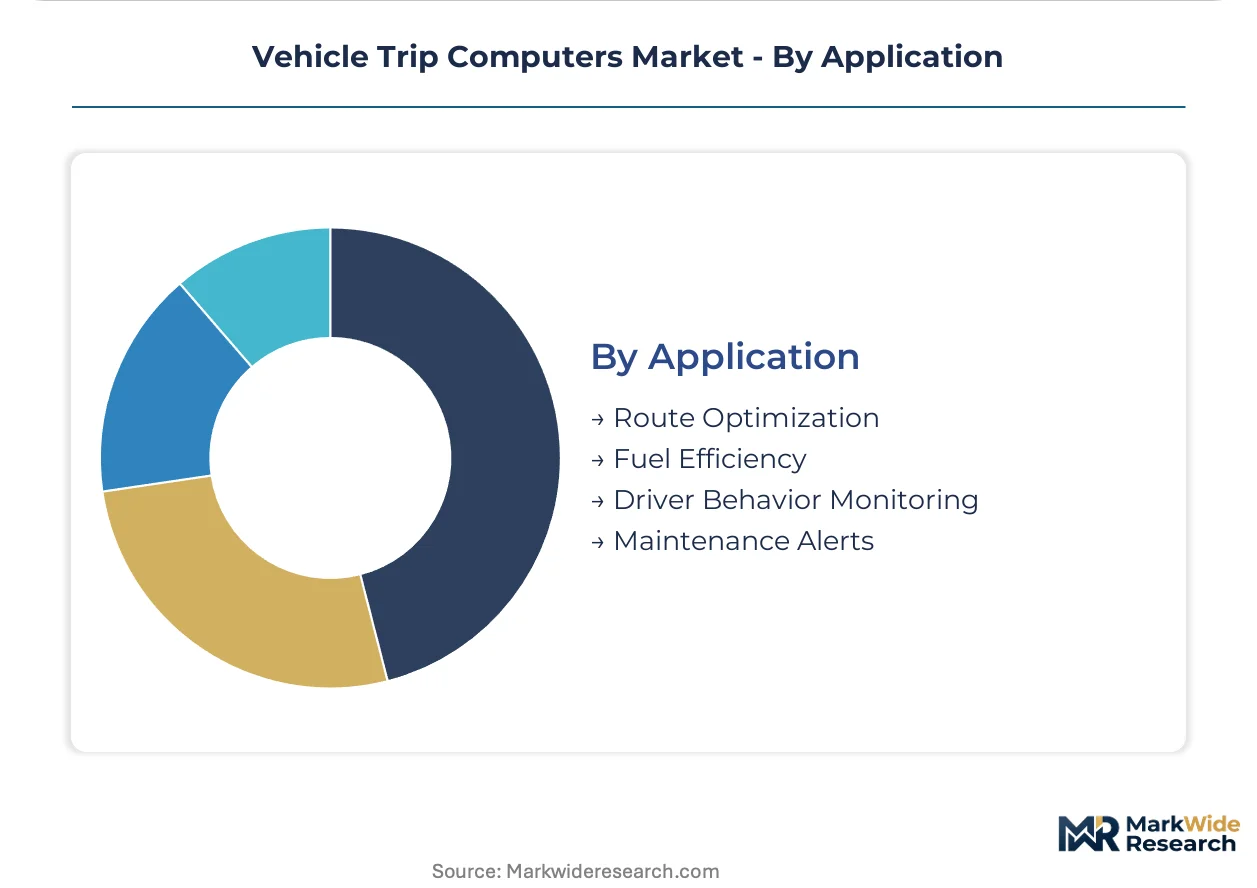
Route Optimization anchors enterprise contract values. Driver Behavior Monitoring is expanding most quickly through subscription pricing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive-grade microcontroller fabrication concentrates in Taiwan and South Korea, exposing OEMs to allocation risk during demand spikes while German electronics clusters drive embedded system procurement for fleet digitization mandates.
United States
Commercial fleet operators across the Midwest freight corridors expand embedded trip computer installations to satisfy EPA OBD-II emissions enforcement and NHTSA electronic logging device guidelines. The regulatory infrastructure mandates standardized diagnostic ports that trip computers exploit for real-time data extraction. Detroit-area automotive electronics clusters coordinate with Silicon Valley cloud platform developers to integrate factory-installed systems with telematics stacks.
Germany
Logistics conglomerates in Bavaria and North Rhine-Westphalia consolidate vendor relationships to ensure audit-ready data lineage under CSRD sustainability reporting obligations. The EU Green Deal CO2 performance standards for commercial vehicles create compliance-driven procurement pull across German fleet operators. Stuttgart's automotive OEMs specify trip computers as factory-installed equipment during platform development cycles with ISO 26262 functional safety validation.
China
Domestic commercial vehicle manufacturers in the Yangtze River Delta integrate embedded trip computers to track idle time and fuel burn across dispersed construction job sites. MIIT regulations on commercial vehicle telematics data transmission create standardized infrastructure requirements. Shenzhen-based OBD-II dongle manufacturers commoditize basic telematics hardware, compressing margin pools for mid-tier suppliers serving price-sensitive fleet segments.
India
The PLI scheme for automotive electronics and expanding commercial vehicle sales create underpenetrated demand for embedded trip computer installations across Maharashtra and Gujarat manufacturing corridors. State-level fleet modernization programs in Karnataka and Tamil Nadu mandate telematics documentation for commercial transport operators. Domestic electronics fabricators in the Delhi-NCR region partner with international platform vendors to localize cloud infrastructure for data sovereignty compliance.
Brazil
Pending ANVISA commercial transport safety regulations will mandate electronic logging devices, opening Latin America's largest vehicle market to compliant trip computer suppliers. Mining operators in Minas Gerais deploy GPS-based trip computers across remote freight routes where cellular coverage remains intermittent. São Paulo-based fleet managers pilot subscription-based fuel optimization algorithms through monthly payments rather than upfront capital expenditure.
Vehicle Trip Computers Market Competitive Landscape
Platform-native specialists and legacy telematics hardware vendors split the market between recurring software revenue models and equipment-centric transaction structures. The vendor base organizes around three strategic archetypes: cloud-native platform developers with API ecosystem strategies, precision agriculture and construction fleet channel specialists with hardware-software bundles, and open-platform telematics stack operators enabling third-party developer integration. Competitive moves concentrate on M&A activity targeting predictive maintenance algorithm portfolios and strategic partnerships with automotive OEMs for factory-embedded system validation.
Within the cloud-native platform tier, Samsara Inc. and Geotab Inc. exemplify divergent approaches to ecosystem lock-in through browser-based dashboard architectures. Trimble Inc. anchors the precision vertical specialist position across agriculture and construction fleet channels where bundled offerings command operational loyalty. Verizon Connect Inc. occupies the scale-driven infrastructure position among North American telematics providers.
| Leading Market Players |
|---|
| Geotab Inc. |
| Verizon Connect Inc. |
| Trimble Inc. |
| Samsara Inc. |
| CalAmp Corp. |
| TomTom NV |
| Solera Holdings LLC |
| Zonar Systems Inc. |
| Lytx Inc. |
| Others |
Value Network & Pricing Analysis
Taiwan's Hsinchu Science Park anchors automotive-grade microcontroller fabrication capacity, and its allocation bottlenecks during demand spikes transmit directly into OEM pricing power for embedded trip computer modules. Shenzhen's OBD-II dongle manufacturers commoditize basic telematics hardware, compressing margin pools for mid-tier suppliers serving price-sensitive fleet segments.
Pricing Analysis
EPA OBD-II mandates dictate the pricing tier structure across the vehicle trip computers landscape, separating ISO 26262-certified embedded systems from unvalidated aftermarket dongles. Three-tier pricing structure across premium, standard, and economy levels reflects functional safety certification, volume procurement scale, and after-sales software bundling. Cost compression in the economy tier intensifies because Shenzhen manufacturers flood channels with sub-fifteen-dollar Bluetooth dongles. Commercial fleet operators exhibit the lowest price sensitivity as compliance documentation requirements override procurement cost minimization.
Supply Chain Analysis
Export controls on advanced semiconductor manufacturing equipment constrain capacity expansion for automotive-grade microcontrollers, tightening flows from Taiwan, South Korea, and the United States. Trip computer production draws from automotive-grade microcontrollers, multi-constellation GPS receivers, and CAN bus transceiver chips. Single-source vulnerability concentrates in Taiwan's foundry complex, where geopolitical friction threatens allocation continuity. Distribution runs through Tier 1 automotive electronics suppliers, OEM direct procurement channels, and aftermarket e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
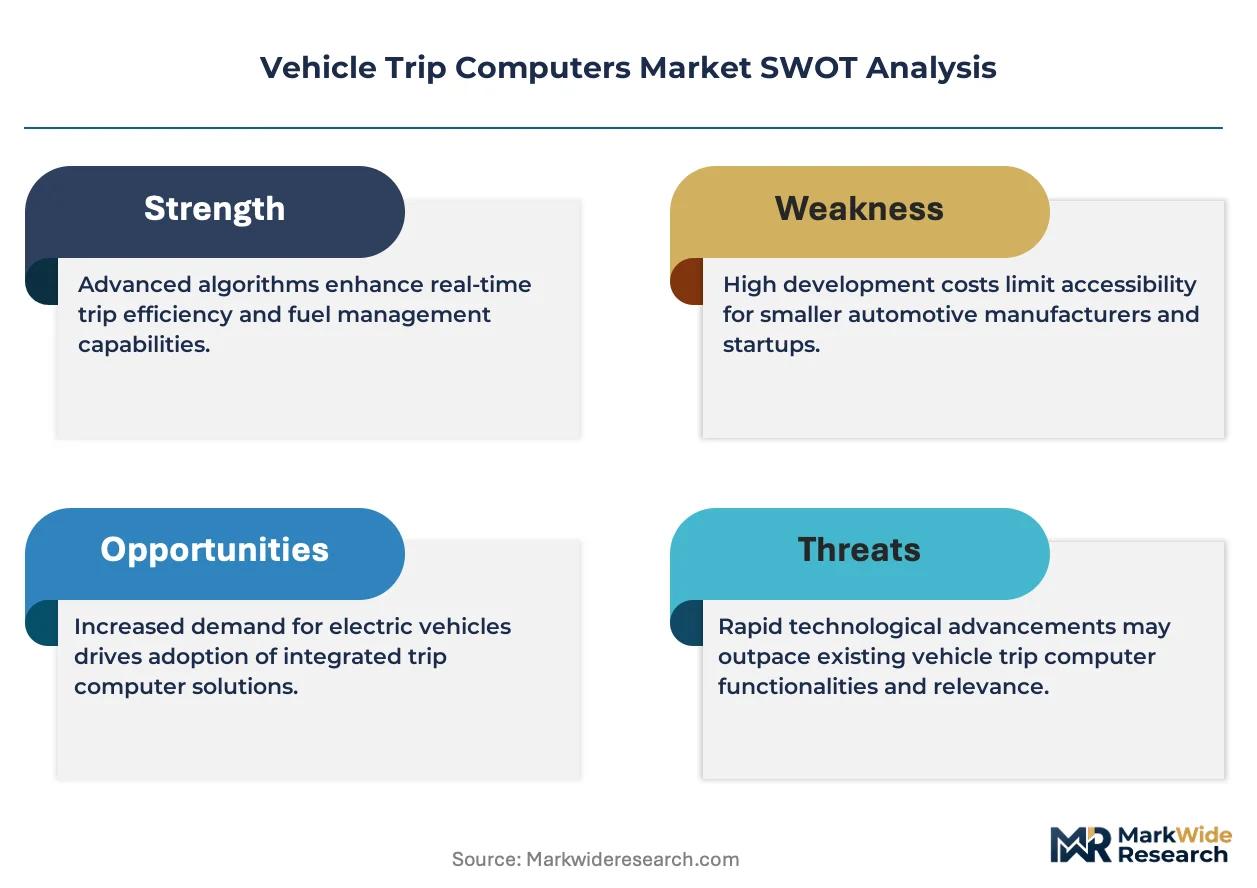
Vehicle trip computers represent a service-attach opportunity where subscription-based predictive maintenance modules expand faster than hardware shipments across commercial fleet installations.
For Market Incumbents: Harden ecosystem lock-in by deepening API partnerships with third-party fleet management platforms and securing ISO 26262 recertification for edge AI inference modules. Shenzhen's commoditized OBD-II dongle manufacturers threaten hardware margin pools, requiring incumbents to anchor customer relationships through cloud-native software stacks rather than equipment transactions.
For New Entrants and Emerging Players: Build out white-space presence in India's PLI-supported automotive electronics corridors, where domestic fleet modernization programs create procurement pull without entrenched vendor relationships. Brazil's pending ANVISA electronic logging device mandate opens Latin America's largest commercial vehicle market to compliant suppliers. A direct-to-fleet SaaS model bypassing legacy distributor networks accelerates customer acquisition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform-native specialists with recurring revenue architectures over hardware-centric legacy vendors. The five-to-ten-year viability window rewards acquisition targets possessing predictive maintenance algorithm portfolios and automotive OEM embedded system validation credentials. Watch for inflection when edge AI inference chips trigger NHTSA recertification requirements that collapse the distinction between trip computers and active safety systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Algorithm Acquisition | Prognostic service contracts create recurring revenue streams beyond hardware shipments for fleet operators. |
| OEM Embedded System Partnership | Factory integration during platform development cycles locks in multi-year validation timelines and high switching costs. |
| Cloud-Native Platform Expansion | Browser-based dashboards with API access deepen ecosystem lock-in among commercial fleet managers. |
| Edge AI Inference Chip Integration | Real-time fatigue detection capabilities force recertification under NHTSA guidelines, raising competitive barriers. |
| India Manufacturing Localization | PLI scheme incentives and state-level fleet mandates create underpenetrated demand for embedded installations. |
Research Methodology
Initial hypotheses were tested against primary input from fleet operations directors, automotive OEM platform engineers, Tier 1 supplier procurement leads, and aftermarket distribution channel managers and refined through secondary validation. Fleet telematics deployment databases, EPA regulatory filings, EU Green Deal implementation documents, and automotive electronics trade association reports anchored supply-side assessment. Bottom-up unit shipment estimates triangulated against top-down fleet penetration models.
Demand-supply-balance framing structured the analytical framework across the projection horizon, with segmentation dimensions spanning product architecture, end-user type, data acquisition technology, and application use case. CAGRs derived from logistic diffusion curves fitted to fleet replacement cycles and regulatory compliance deadlines. Edge AI adoption rates and OBD-II mandate enforcement timelines served as industry-specific forecast inputs.
Stress conditions across semiconductor allocation volatility, GDPR data sovereignty enforcement, and Brazil regulatory implementation delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about fleet digitization mandate adherence and embedded sensor cost trajectories. Material shifts in EPA emissions enforcement stringency or EU CSRD reporting granularity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
Automotive Personal Navigation Systems Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
Car DVR Market
Telematics and Infotainment
Telematics Control Unit Market
Telematics and Infotainment
Video Telematics Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Europe Commercial Vehicle Telematics Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Roadside Assistance Software Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
North America Automotive Navigation System Market
Telematics and Infotainment
Global Automotive Remote Diagnostics Market
Telematics and Infotainment
Japan Commercial Telematics Market
Telematics and Infotainment
GCC Commercial Telematics Market