
 North America Automotive Navigation System Market | 2026-2036
North America Automotive Navigation System Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Navigation System Market Analytics
Asset-light leasing models for in-vehicle infotainment hardware is narrowing the competitive field to suppliers with balance-sheet capacity for multi-year fleet contracts. Continental AG leverages captive financing structures to lock in OEM embedded system placements across Detroit Three platforms. Garmin Ltd. anchors its position through direct-to-consumer portable device channels that bypass traditional automotive procurement cycles. Robert Bosch GmbH competes on manufacturing scale, sustaining cost advantages in high-volume GPS-GLONASS receiver production.
North America automotive navigation systems integrate multi-constellation satellite receivers, digital map databases, and real-time traffic processing engines to calculate optimal vehicle routing with lane-level precision. These systems serve the primary commercial purpose of minimizing transit time, fuel consumption, and driver cognitive load across passenger and commercial vehicle operations. Embedded Systems dominate value capture due to OEM pre-installation contracts and long-term software update revenue streams. Cloud-Based Solutions represent the fastest-expanding delivery architecture, as over-the-air map refreshes and predictive routing displace static onboard storage. Smartphone Apps occupy a contested middle tier, pressured by OEMs seeking to reclaim dashboard interface control from third-party mapping providers.
NHTSA mandates for automatic crash notification and location accuracy shape embedded system specifications, while FCC spectrum allocations for C-V2X direct vehicle-to-infrastructure communication expand addressable functionality. The EPA's vehicle emissions testing protocols increasingly incorporate real-world route efficiency metrics, creating regulatory pull for precision navigation in powertrain optimization. Stakeholders must monitor how NHTSA's anticipated V2X deployment timelines reshape hardware refresh cycles and software certification requirements across US and Canadian supplier networks.
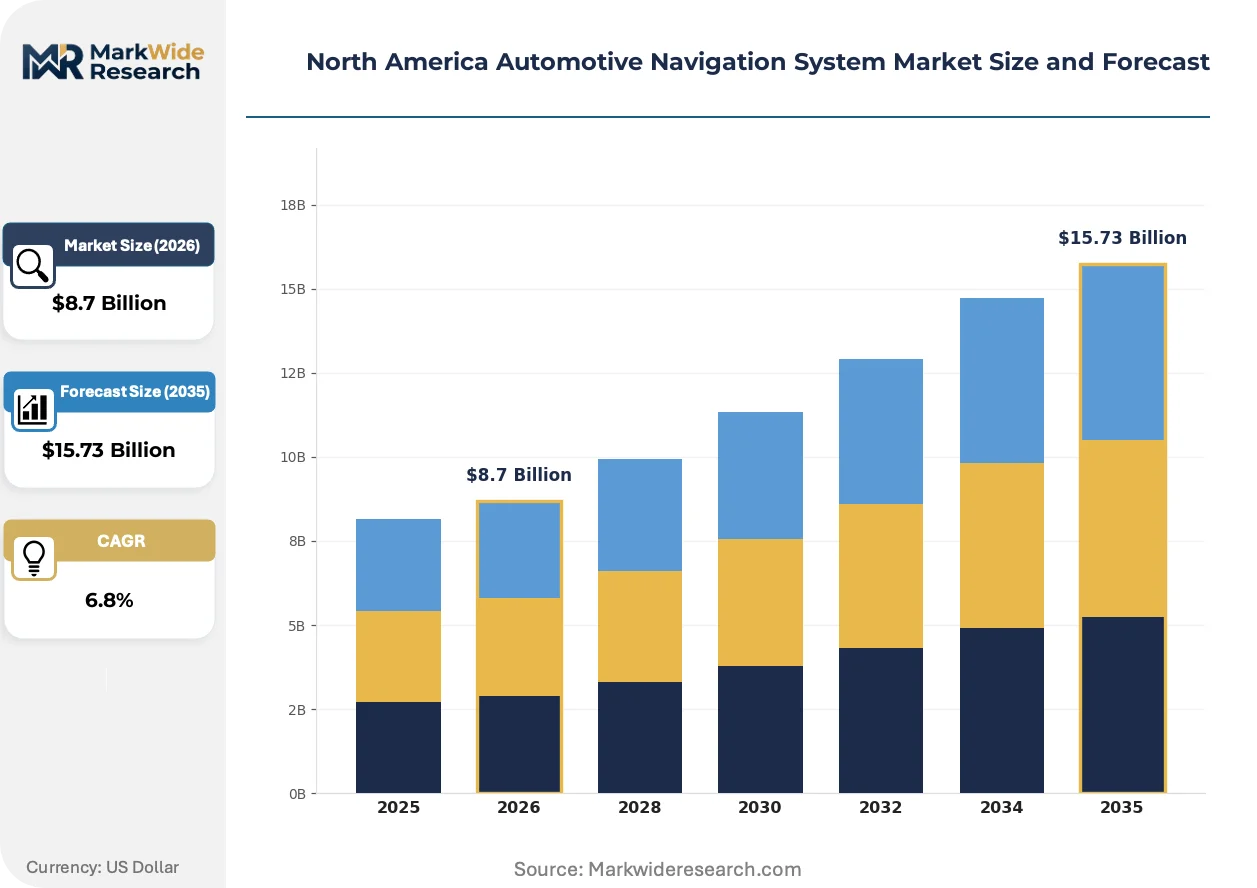
Market Dynamics
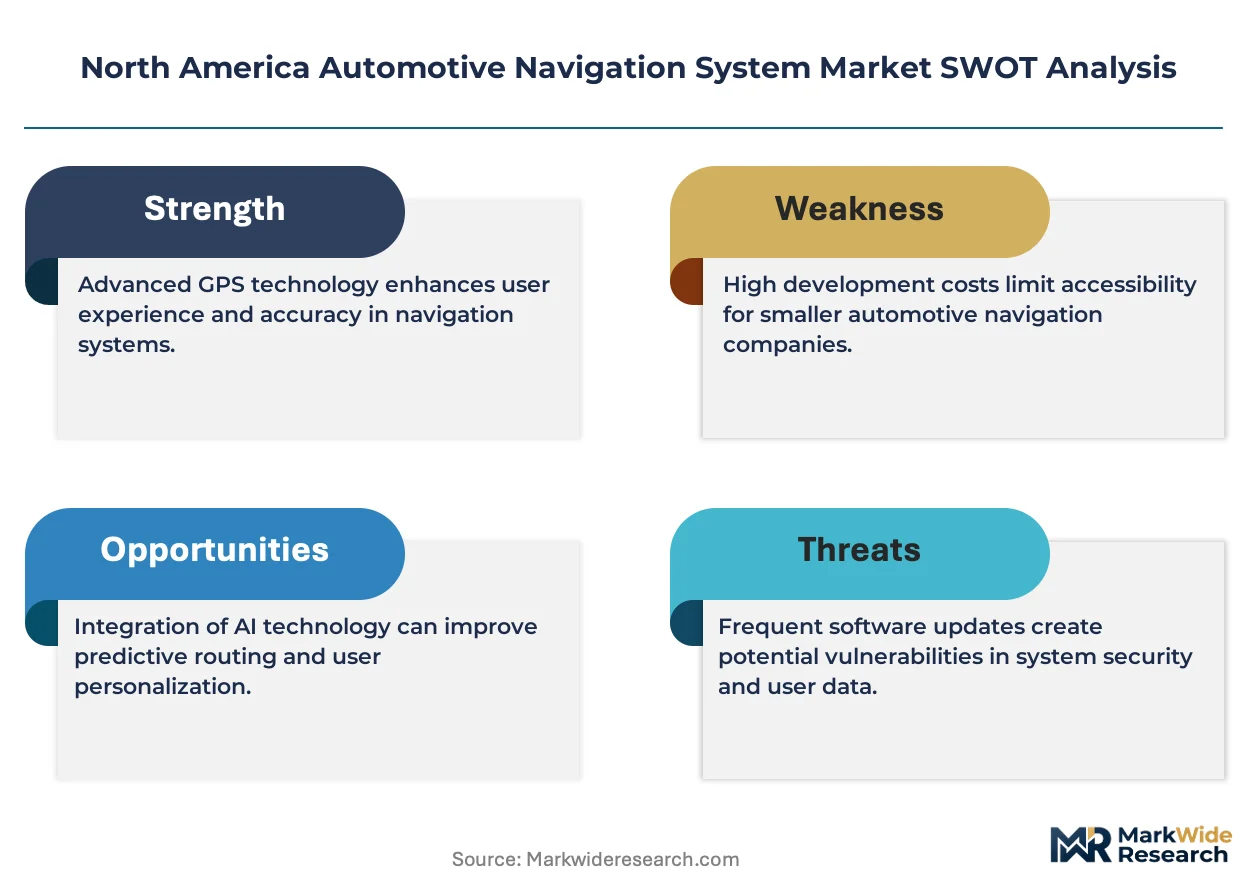
Fleet telematics standardization is compressing refresh cycles for embedded navigation hardware across commercial vehicle platforms. The push toward V2X interoperability is forcing suppliers to redesign antenna architectures and software stacks before revenue models mature.
Growth Catalysts
- NHTSA Automatic Crash Notification Mandates:Location-accuracy requirements for emergency response systems are mandating dual-frequency GNSS receivers in new vehicle platforms.
- Commercial Fleet Electrification:Route-optimization algorithms that minimize battery depletion are becoming standard procurement specifications for logistics operators across the US Midwest manufacturing corridor.
- HD Map Subscription Models:Over-the-air lane-level data refreshes are generating recurring revenue streams that subsidize upfront hardware costs for OEM embedded system programs.
Market Restraints
- Semiconductor Fab Concentration:Advanced GNSS system-on-chip production concentrates at TSMC and Samsung foundries, exposing suppliers to Taiwan Strait geopolitical risk.
- Map Licensing Cost Structure:Proprietary HD map data from HERE Technologies and TomTom commands per-vehicle royalties that compress margins on economy-tier navigation packages.
- Smartphone Substitution:Apple CarPlay and Android Auto integration reduces willingness-to-pay for embedded navigation among entry-level passenger vehicle buyers.
Strategic Opportunities
- Mexico Nearshoring Corridors:Automotive supplier clusters in Querétaro and Guanajuato lack localized navigation map coverage, creating first-mover openings for cloud-based routing platforms.
- FCC C-V2X Spectrum Allocation:5.9 GHz band access enables vehicle-to-infrastructure positioning corrections that improve tunnel and urban canyon accuracy.
- AR-HUD Convergence:Integration of navigation guidance into augmented-reality head-up displays creates premium-tier differentiation for luxury vehicle platforms.
Industry Challenges
- Functional Safety Certification:ISO 26262 ASIL-B compliance for navigation systems that feed autonomous driving stacks extends development timelines by 14-18 months.
- Antenna Integration Complexity:Multi-constellation GNSS, C-V2X, and 5G modules must coexist within shrinking roofline footprints without signal interference.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Navigation System Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Portable Devices, Smartphone Apps, Cloud-Based Solutions Technology: GPS, GLONASS, Galilean Technology, Beidou End User: OEMs, Aftermarket Providers, Fleet Operators, Car Rental Services Delivery Mode: Real-Time Updates, Offline Mode, Subscription-Based, One-Time Purchase |
| Companies Covered | Continental AG, DENSO Corporation, Robert Bosch GmbH, TomTom International BV, Aisin Corp., Garmin Ltd., Panasonic Holdings Corporation, JVCKENWOOD Corp., HERE Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Navigation System Market Evolving Landscape
Edge computing architectures are redistributing processing loads between vehicle hardware and cloud infrastructure. This shift is compressing the traditional boundary between embedded and connected navigation systems.
SD map engines are virtualizing the storage and update mechanisms that historically required dedicated onboard flash memory. Tier 1 suppliers are adopting containerized map software that streams vector tiles on demand rather than caching continental datasets. This architecture is virtualizing the cost structure of entry-level navigation packages and enabling subscription-based feature unlocking.
NHTSA V2X deployment guidelines are accelerating hardware refresh requirements for model year 2027 and beyond. The mandate for dual-mode DSRC-C-V2X compatibility is forcing antenna module redesigns and additional RF certification cycles. Commercial vehicle platforms serving the US Interstate highway network face the steepest compliance cost escalation.
Logistics procurement teams are unbundling navigation hardware from long-term telematics service contracts. Fleet operators now negotiate separate agreements for device procurement, cellular connectivity, and routing software licenses. This pattern is most pronounced among US-based less-than-truckload carriers with 500-plus vehicle deployments.
North America Automotive Navigation System Market Segmentation
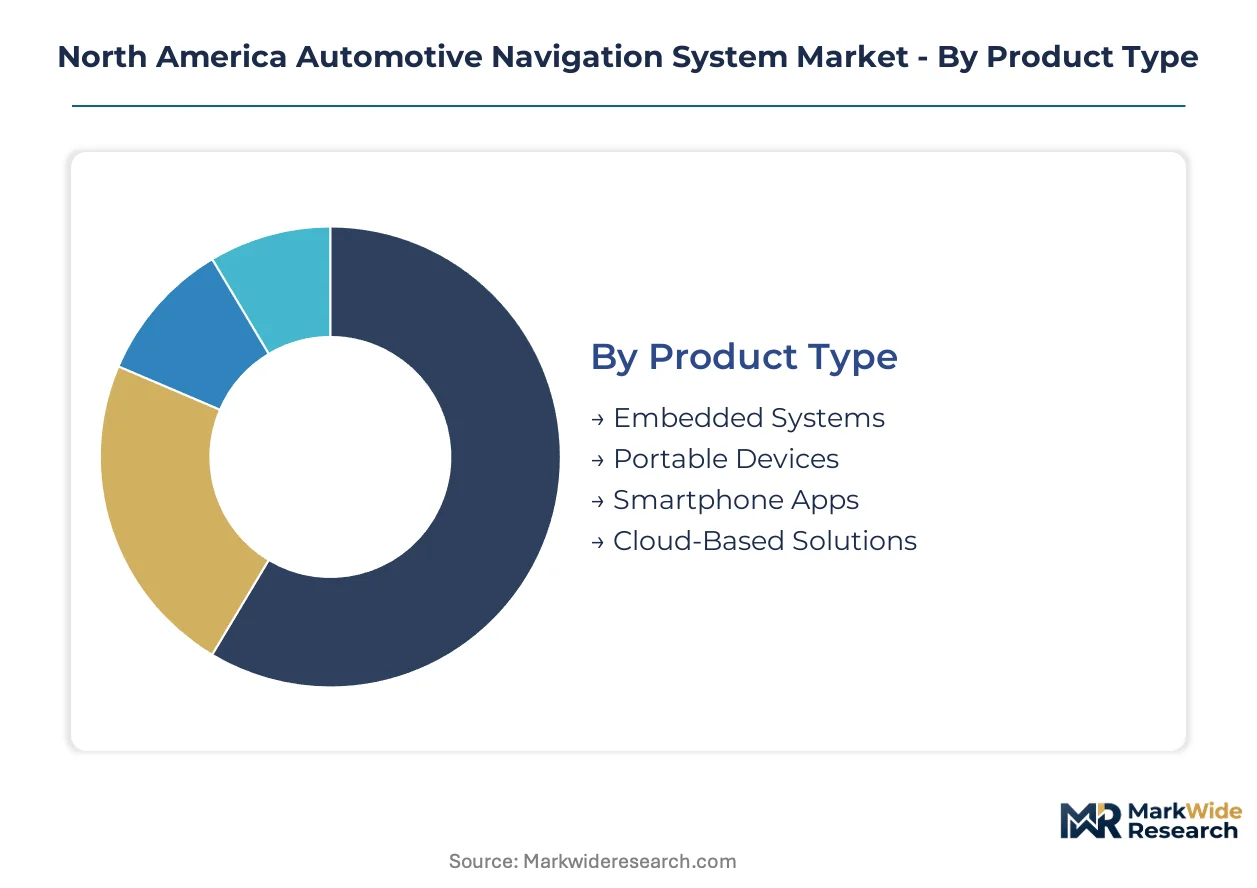
Navigation system architectures fragment across hardware integration depth, satellite constellation compatibility, and revenue model structure. Each segmentation axis reveals distinct margin profiles and competitive moats that shape supplier positioning across US and Canadian automotive corridors.
Product Type:
Mature embedded platforms dominate OEM procurement cycles while cloud-native architectures are emerging as the primary growth vector.
- Embedded Systems:Factory-integrated hardware with dedicated GNSS receivers and onboard map storage commands premium placement in Detroit Three and premium import vehicle lines. Long-term software update contracts generate recurring revenue that subsidizes upfront silicon costs across the US Great Lakes manufacturing belt.
- Cloud-Based Solutions:Over-the-air vector tile streaming eliminates local storage requirements and enables dynamic feature unlocking. Demand concentrates among fleet operators in Ontario and US Midwest logistics corridors seeking real-time route optimization with minimal hardware refresh cycles.
- Portable Devices:Standalone GPS units with suction-mount displays serve rental fleets and owner-operator trucks requiring transferable hardware across vehicle pools.
- Smartphone Apps:Third-party mapping applications face margin compression as OEMs reclaim dashboard interface control through proprietary embedded platforms.
Embedded Systems handles the majority of throughput; Cloud-Based Solutions is the fastest mover on share.
Technology:
Cost tier stratification separates single-constellation economy offerings from multi-band precision systems required for commercial and safety-critical applications.
- GPS:The legacy US satellite constellation provides baseline positioning accuracy sufficient for standard passenger vehicle routing. Single-frequency GPS receivers dominate economy-tier embedded packages where NHTSA mandates do not require sub-meter precision.
- GLONASS:Russian constellation integration improves cold-start time and urban canyon performance through increased satellite visibility. Dual-constellation GPS-GLONASS modules are standard specification for commercial fleet telematics serving cross-border US-Canada routes.
- Galilean Technology:European constellation access enables commercial service signal authentication for tolling and congestion pricing applications in urban US markets.
- Beidou:Chinese constellation compatibility serves niche import vehicle platforms and specialized surveying equipment rather than mainstream North American automotive production.
GPS retains the largest installed base; Galilean Technology is climbing the fastest as municipalities deploy authenticated positioning for road pricing.
End User:
Customer type determines contract structure, with captive OEM relationships contrasting against transactional aftermarket and fleet procurement patterns.
- OEMs:Original equipment manufacturers negotiate multi-year embedded system supply agreements with tiered pricing tied to volume commitments and platform exclusivity. Pre-installation contracts lock in map data licensing terms across entire vehicle nameplate generations.
- Fleet Operators:Commercial logistics providers with 500-plus vehicle deployments unbundle hardware procurement from telematics service contracts, negotiating separate agreements for devices, cellular connectivity, and routing software licenses.
- Aftermarket Providers:Independent retailers and installation shops serve vehicle owners seeking navigation upgrades for used cars and legacy platforms outside OEM software support windows.
- Car Rental Services:Daily rental fleets prioritize transferable portable devices or smartphone integration over permanent embedded installations to maximize fleet flexibility.
OEMs capture the dominant revenue share; Fleet Operators are gaining procurement sophistication fastest.
Delivery Mode:
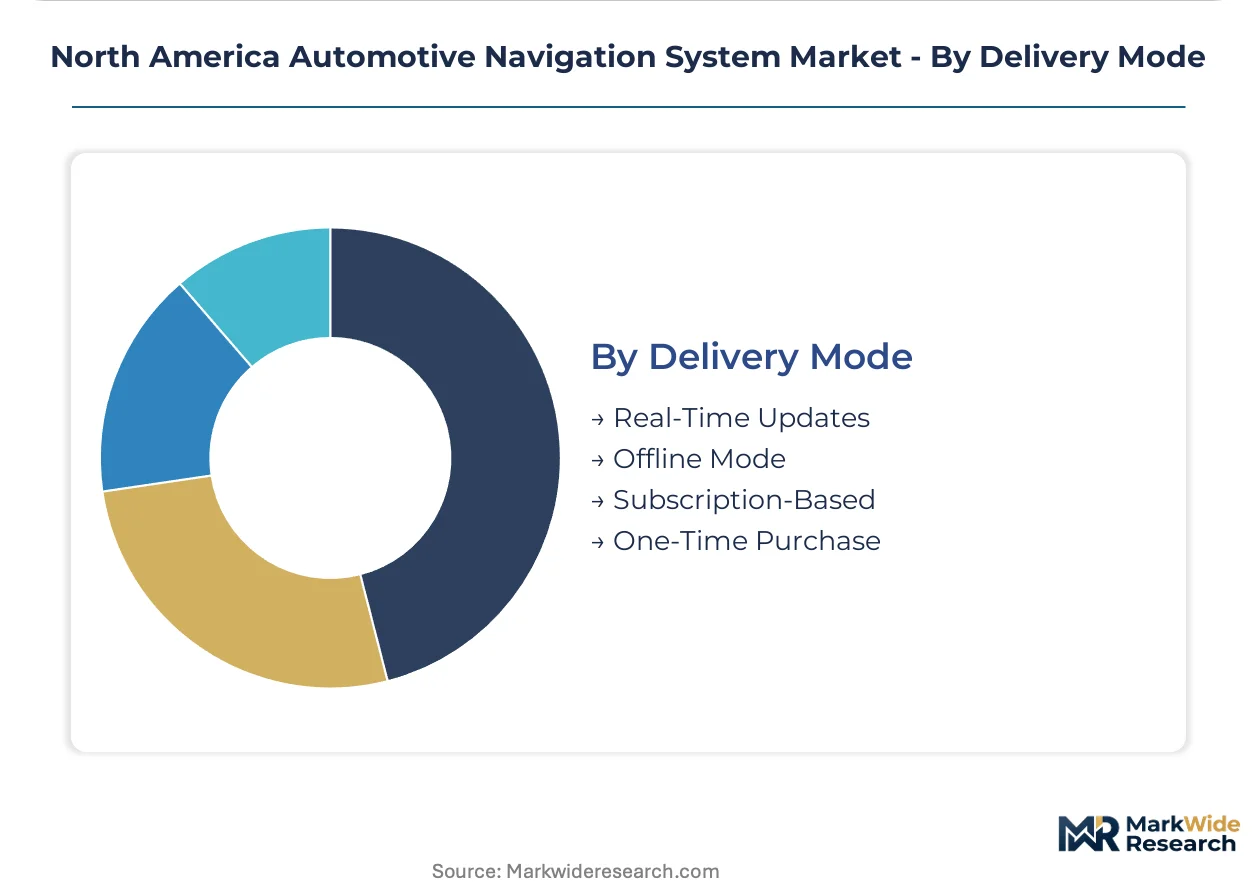
Revenue model architecture separates perpetual license structures from recurring subscription frameworks with divergent customer lifetime value profiles.
- Real-Time Updates:Continuous traffic, hazard, and construction data feeds require persistent cellular connectivity and command premium subscription pricing from commercial operators.
- Subscription-Based:Tiered access to HD map layers, predictive routing, and advanced driver assistance features generates recurring revenue that subsidizes initial hardware placement costs.
- Offline Mode:Static map datasets stored locally serve remote regions with unreliable cellular coverage and entry-level buyers avoiding ongoing fees.
- One-Time Purchase:Perpetual licenses for portable device software and select embedded system tiers appeal to price-sensitive consumers in the US Southeast and Mountain West markets.
Subscription-Based models capture expanding recurring revenue; Real-Time Updates is expanding most quickly among commercial logistics adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NHTSA safety mandates and FCC spectrum allocations for C-V2X communication are accelerating embedded navigation hardware requirements across US states and Canadian provinces. Fleet electrification corridors and automotive manufacturing clusters concentrate demand in specific sub-regional markets.
United States
Commercial fleet operators across the Midwest manufacturing belt demand real-time routing platforms that optimize electric vehicle range and charging stop sequencing. NHTSA automatic crash notification rules mandate dual-frequency GNSS receivers in all new vehicle platforms from model year 2027. The Detroit-Windsor automotive corridor anchors embedded system procurement cycles for Detroit Three OEM programs.
Canada
Ontario's supplier corridors in Windsor and Oshawa integrate navigation hardware into cross-border supply chains serving US Great Lakes assembly plants. Transport Canada aligns with NHTSA location-accuracy standards for emergency response systems while maintaining distinct map data licensing frameworks. Toronto-Waterloo tech clusters host cloud-based routing platform development for commercial logistics applications.
Mexico
Nearshoring corridors in Querétaro and Guanajuato lack localized HD map coverage, creating openings for cloud-native navigation platforms serving automotive supplier clusters. The country's federal telecommunications regulator oversees cellular connectivity standards for connected vehicle services. Mexico City Metro generates aftermarket demand for portable navigation devices among owner-operator commercial fleets.
North America Automotive Navigation System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. OEM pre-installation contracts concentrate value capture among suppliers with captive financing capacity and multi-year platform commitments. Three archetypes dominate: diversified automotive tier-1 conglomerates with embedded system divisions; consumer electronics specialists leveraging direct-to-consumer distribution; and map data licensors monetizing proprietary HD datasets. Competitive moves center on strategic partnerships for V2X antenna integration and portfolio diversification into augmented-reality head-up display convergence.
Among German-based tier-1 suppliers, Continental AG and Robert Bosch GmbH exemplify diversified conglomerates with balance-sheet capacity for multi-year OEM contracts. Garmin Ltd. anchors the product-specialist archetype through direct-to-consumer portable device channels that bypass traditional automotive procurement cycles. HERE Technologies occupies a distinct position as a map data licensor commanding per-vehicle royalties for HD positioning datasets.
| Leading Market Players |
|---|
| Continental AG |
| DENSO Corporation |
| Robert Bosch GmbH |
| TomTom International BV |
| Aisin Corp. |
| Garmin Ltd. |
| Panasonic Holdings Corporation |
| JVCKENWOOD Corp. |
| HERE Technologies |
| Others |
Value Network & Pricing Analysis
TSMC and Samsung foundry concentration for advanced GNSS system-on-chip production concentrates upstream margin capture in East Asian semiconductor fabrication, leaving downstream navigation system integrators to compete on assembly efficiency and software differentiation across US and Canadian automotive corridors.
Pricing Analysis
Certification level creates the primary spread between economy-tier single-frequency GPS modules and ASIL-B compliant dual-frequency systems for autonomous driving stacks. Three-tier pricing structure across premium, standard, and economy levels reflects NHTSA mandate compliance tiers, with commercial fleet operators showing lowest price sensitivity due to total cost of ownership optimization requirements. Cost compression in entry-level embedded packages is intensifying because smartphone substitution via Apple CarPlay and Android Auto reduces willingness-to-pay among passenger vehicle buyers.
Supply Chain Analysis
US export controls on advanced semiconductor manufacturing equipment to China constrain foundry expansion options and extend lead times for multi-constellation receiver chips. Geographic supply concentration centers on Taiwan, South Korea, and Japan for RF front-end components and baseband processors. Raw material dependencies include high-purity silicon wafers, gallium arsenide substrates, and rare-earth magnets for antenna modules. Single-source vulnerability at TSMC's leading-edge nodes exposes tier-1 suppliers to Taiwan Strait geopolitical risk. Distribution runs through captive OEM supply agreements and aftermarket distributor networks serving independent installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
V2X interoperability standards are triggering a platform-economics inflection where navigation hardware becomes the physical anchor for software-defined vehicle revenue streams, with FCC spectrum allocation for 5.9 GHz C-V2X communication enabling new service-layer monetization.
For Market Incumbents: Harden embedded system placements through captive financing structures that lock in multi-year Detroit Three platform commitments, while accelerating ISO 26262 ASIL-B certification investment to defend against cloud-native routing platforms displacing static onboard storage. Deepen backward integration into antenna module design to control RF integration complexity as roofline space constraints intensify. For New Entrants and Emerging Players: Mexico nearshoring corridors in Querétaro and Guanajuato represent the most penetrable entry point, where localized HD map coverage gaps create first-mover openings for cloud-based routing platforms serving automotive supplier clusters. Fleet telematics unbundling patterns among US less-than-truckload carriers enable device-procurement-only go-to-market angles that bypass entrenched OEM supply relationships. For Investors and Strategic Acquirers: Capital is best deployed toward map data licensors with proprietary HD positioning datasets and recurring per-vehicle royalty streams, as these assets generate defensive moats against hardware commoditization. Watch NHTSA V2X deployment timeline acceleration as the inflection signal indicating hardware refresh cycle compression and software certification requirement escalation.| Strategic Initiative | Industry Significance |
|---|---|
| V2X Antenna Module Redesign | Dual-mode DSRC-C-V2X compatibility satisfies NHTSA model year 2027 mandates for commercial vehicle platforms. |
| HD Map Subscription Platform | Over-the-air lane-level data refreshes generate recurring revenue subsidizing upfront silicon costs. |
| AR-HUD Navigation Integration | Augmented-reality head-up display convergence creates premium-tier differentiation for luxury OEM programs. |
| Cloud-Native Routing Architecture | Vector tile streaming eliminates local storage requirements and enables dynamic feature unlocking. |
| Fleet Telematics Unbundling | Separate hardware, connectivity, and software contracts maximize procurement flexibility for logistics operators. |
Research Methodology
Cross-validation between OEM platform engineering interviews and tier-1 supplier procurement disclosures anchors the qualitative findings, with secondary validation drawing from NHTSA regulatory filings, FCC spectrum allocation records, and vehicle production databases. Primary engagement spans Tier 1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel heads, fleet telematics managers, and cellular connectivity providers. Bottom-up unit economics triangulate against top-down market sizing across embedded, cloud-based, portable, and smartphone app delivery architectures.
Calibration against historical embedded system placement volumes and cloud-native routing platform adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions include product type, satellite constellation technology, end-user archetype, and delivery mode revenue structure. CAGRs derive from installed base evolution, replacement cycle compression, and average content per vehicle expansion. Forecast inputs incorporate NHTSA mandate compliance timelines and commercial fleet electrification penetration patterns.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, semiconductor fab utilization rates, or cross-border logistics demand would shift the trajectory. Forecasts reflect assumptions around regulatory implementation schedules and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
India Fleet Management Software Market
Telematics and Infotainment
Europe Commercial Telematics Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
Electric Vehicle Telematics Market
Telematics and Infotainment
Vehicle-To-Infrastructure (V2I) Communication Market
Telematics and Infotainment
Consumer Telematics Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
Motorcycle Infotainment System Market
Telematics and Infotainment
Automotive Telematics System Market
Telematics and Infotainment
Global 5G in Automotives Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Boat and Ship Telematics Market
Telematics and Infotainment
Global Car Digital Cockpit Market
Telematics and Infotainment
Electric Vehicle Infotainment Market
Telematics and Infotainment
C-V2X OBU Market
Telematics and Infotainment
Internet of Cars Market