
 Car Generated Data Market | 2026-2036
Car Generated Data Market Size, Share, and Industry Trends Forecast 2026-2036
Car Generated Data Market Analysis
The capital-intensity divergence between embedded system architects and aftermarket device vendors is unwinding as OEMs consolidate data pipelines under proprietary architectures. Tesla leverages over-the-air update infrastructure to sustain recurring revenue from software-defined vehicle features. IBM Corporation anchors enterprise-grade fleet analytics through cloud platform integrations with automotive clients. Geotab Inc. specializes in commercial vehicle telematics, occupying a defensible niche in logistics and transportation verticals.
Car generated data comprises sensor outputs, telemetry streams, diagnostic fault codes, and driver behavior patterns transmitted via CAN bus networks, cellular modems, or dedicated short-range communications protocols. This information feeds real-time optimization algorithms for predictive maintenance, usage-based insurance pricing, and autonomous driving training datasets. Telematics and diagnostic data categories dominate current revenue pools due to established fleet management contracts and warranty cost reduction programs. User behavior data segments accelerate fastest as insurers and advertisers bid for granular driving profiles. Electric vehicles generate the highest per-unit data volumes through battery management system monitoring and charging optimization routines.
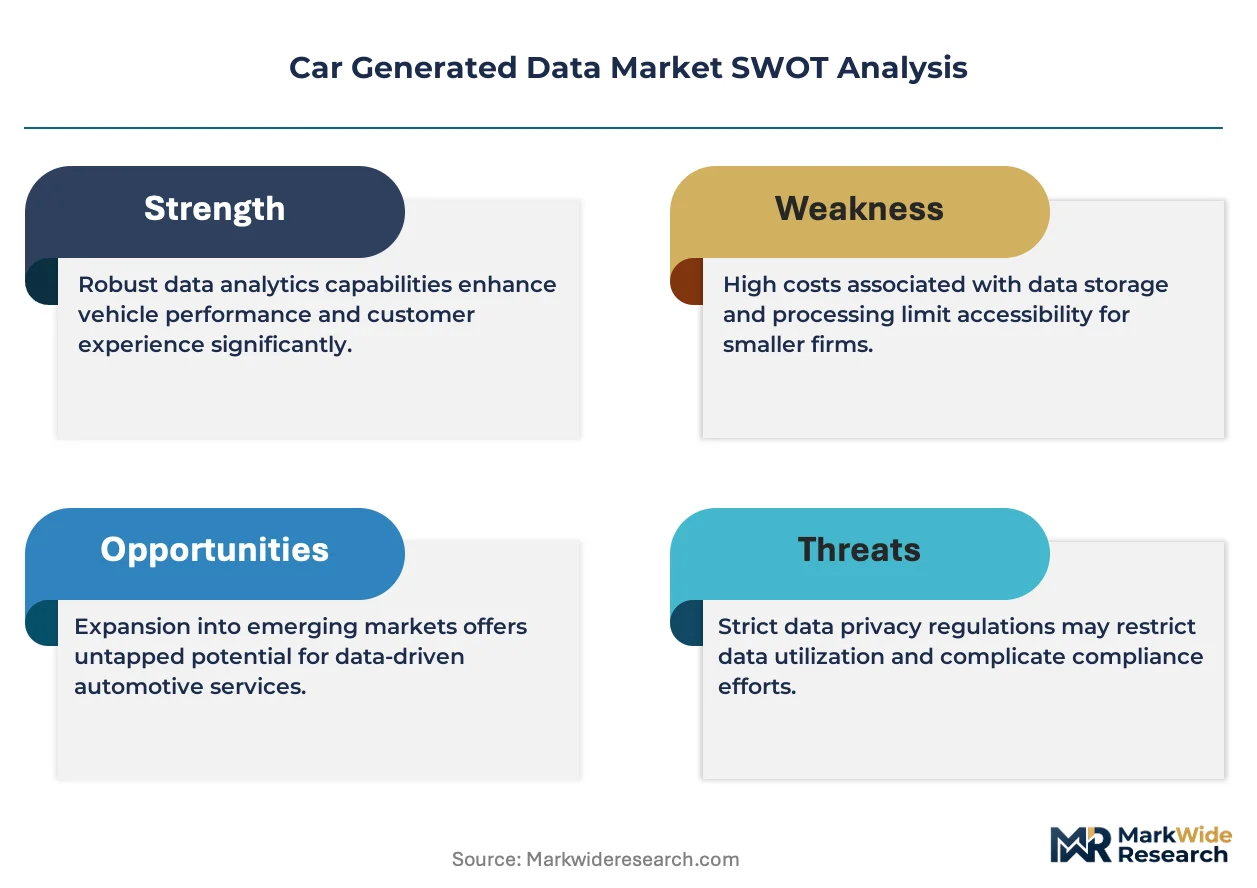
The EU Data Act and GDPR frameworks mandate consumer consent mechanisms and third-party data portability from vehicle manufacturers, reshaping competitive access to in-car information streams. China's MIIT enforces GB standards for connected vehicle cybersecurity and cross-border data transfer restrictions, creating compliance barriers for foreign platform operators. The US NHTSA and FCC jointly oversee vehicle-to-everything communication spectrum allocation and safety-critical data integrity requirements. Stakeholders must monitor which regulatory jurisdiction ultimately claims primacy over cross-border data flows as vehicles traverse multiple governance zones.
Market Dynamics
OEMs are consolidating data pipelines under proprietary architectures, compressing aftermarket access and forcing tier-1 suppliers to reposition around edge analytics rather than hardware modules.
Growth Catalysts
- EU Data Act mandates:Interoperability standards for in-vehicle data access are opening previously captive OEM data streams to third-party service providers, expanding addressable market for fleet analytics platforms.
- Usage-based insurance:Granular driver behavior telemetry enables dynamic premium pricing models that reduce claims costs for insurers and accelerate consumer adoption of connected vehicle subscriptions.
- Edge computing architectures:Distributed processing at the vehicle level reduces latency for safety-critical applications while lowering cellular data transmission costs for OEMs operating at scale.
Market Restraints
- Semiconductor supply concentration:Advanced driver-assistance system chips and automotive-grade modems depend on Taiwan and South Korea fabrication capacity, creating vulnerability to geopolitical disruption.
- GB standards compliance:China's MIIT cybersecurity mandates impose localization requirements and cross-border transfer restrictions that fragment data architectures for multinational OEMs.
- Battery management system complexity:Electric vehicle data volumes overwhelm legacy fleet management platforms designed for internal combustion engine diagnostic codes, requiring wholesale infrastructure replacement.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for connected vehicle manufacturing are attracting OEM assembly investments that will generate localized data streams for regional analytics providers.
- Vehicle-to-grid integration:Bidirectional charging optimization creates new revenue pools for aggregators managing distributed energy resources through EV battery telemetry.
- 5G-V2X spectrum allocation:FCC rulings on dedicated short-range communications are enabling low-latency cooperative perception applications that unlock premium subscription tiers.
Industry Challenges
- Embedded systems talent scarcity:Shortage of engineers proficient in both automotive safety standards and cloud-native architectures delays platform development timelines.
- GDPR consent orchestration:Real-time data flows across multiple jurisdictions require dynamic legal-engineering interfaces that most OEMs have not operationalized.
- CAN bus legacy integration:Pre-2020 vehicle fleets lack standardized data dictionaries, forcing expensive retrofit programs or exclusion from unified analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Generated Data Market |
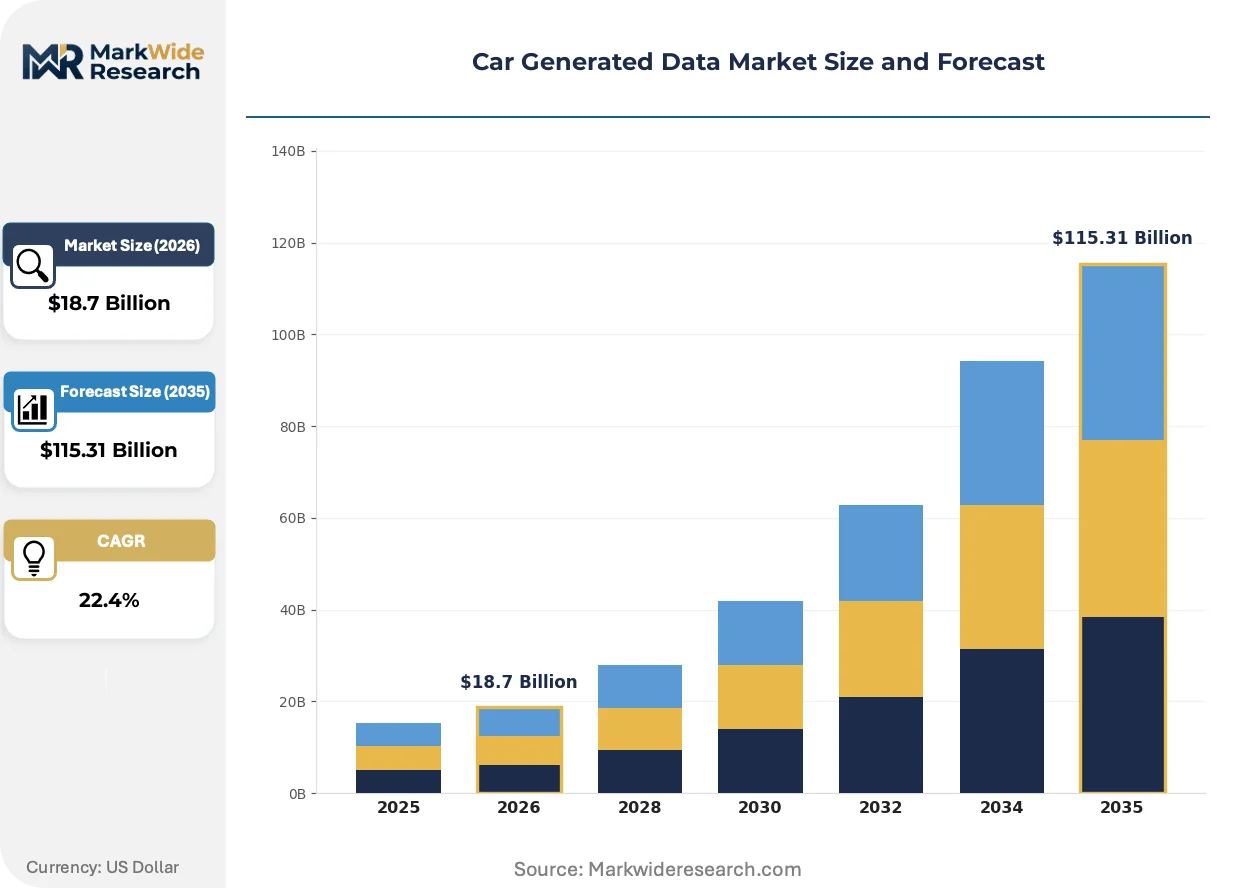
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Data Type: Telematics, Diagnostic Data, User Behavior, Environmental Data Data Source: Embedded Systems, Aftermarket Devices, Mobile Applications, Cloud Platforms Use Case: Fleet Management, Predictive Maintenance, Insurance Analytics, Driver Assistance Vehicle Model: Electric Vehicles, Hybrid Vehicles, Luxury Vehicles, Commercial Vehicles |
| Companies Covered | Volkswagen Group, IBM Corporation, Tesla, Vontier, Geotab Inc., Toyota, BMW, GAC Aion, General Motors, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Generated Data Market Emerging Trajectories
Software-defined vehicle architectures are decoupling hardware from functionality, enabling continuous monetization of data streams through over-the-air feature activation rather than one-time equipment sales.
Edge AI inference engines are fragmenting centralized cloud dependencies for real-time decision-making. Tier-1 suppliers embed neural processing units directly into domain controllers, reducing round-trip latency for autonomous emergency braking and lane-keeping systems. Fleet operators with safety-critical applications are adopting these architectures fastest, compressing margins for pure-play telematics providers dependent on cellular backhaul.
GDPR's algorithmic accountability provisions are forcing OEMs to document automated decision-making logic in driver scoring and predictive maintenance alerts. German transport authorities now require explainability audits for usage-based insurance integrations. This regulatory pressure is accelerating investment in interpretable machine learning frameworks, particularly among European market entrants targeting cross-border fleet contracts.
Subscription fatigue among commercial fleet buyers is fragmenting bundled service contracts into unbundled component pricing. Logistics operators now procure telematics hardware, connectivity, and analytics software from separate vendors, reversing prior preferences for integrated single-source agreements. This disintermediation is most pronounced in Germany's Mittelstand trucking sector, where procurement departments have gained technical sophistication to evaluate point solutions.
Car Generated Data Market Segmentation
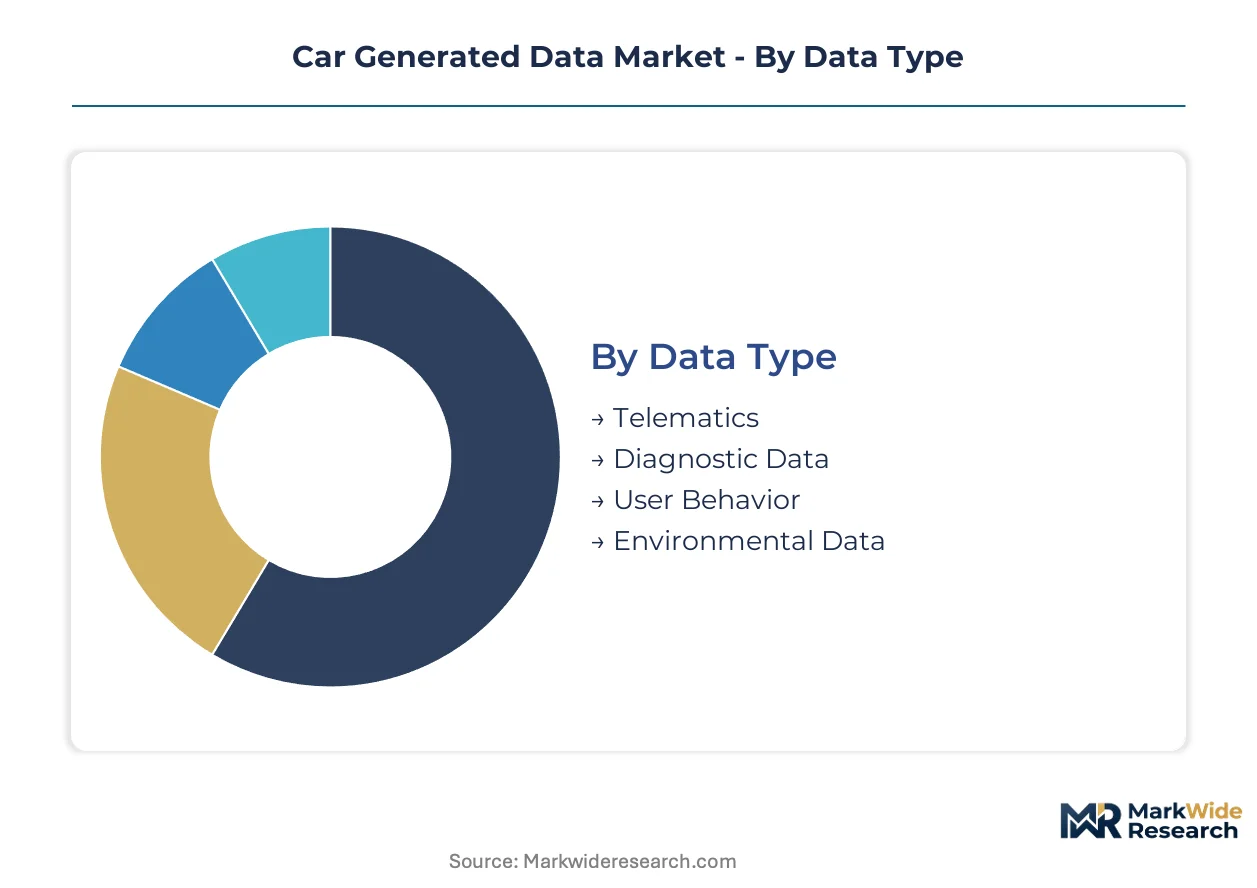
Car generated data flows through distinct technical and commercial channels that determine monetization pathways. Each segmentation dimension reveals where value pools concentrate and which infrastructure investments yield returns.
Data Type:
Channel economics favor subscription models for real-time streams versus one-time licensing for historical datasets. OEMs monetize continuous telemetry through recurring platforms, while insurers purchase anonymized behavioral archives for risk modeling.
- Telematics:Continuous location, speed, and vehicle health metrics transmitted via cellular networks. Fleet operators in Germany and the US dominate procurement, driven by regulatory mandates for electronic logging devices and fuel efficiency reporting.
- Diagnostic Data:Fault codes, component wear indicators, and powertrain performance logs retrieved from CAN bus architectures. Warranty cost reduction programs at automotive OEMs concentrate demand, particularly for powertrain and emissions system monitoring.
- User Behavior:Driving patterns, acceleration profiles, and infotainment interaction logs. Usage-based insurers and targeted advertising platforms purchase granular profiles, though GDPR consent requirements constrain European deployment.
- Environmental Data:External sensor readings including road conditions, weather proximity, and air quality indices. Smart city infrastructure operators in China and Japan represent emerging procurement channels for traffic optimization algorithms.
Telematics dominates installed base. User Behavior is where expansion concentrates.
Data Source:
Cost tier differentiation separates integrated OEM architectures from modular aftermarket alternatives. Premium vehicle buyers access embedded systems as standard equipment, while commercial fleets often retrofit legacy vehicles with aftermarket hardware.
- Embedded Systems:Factory-integrated sensors and domain controllers within vehicle electronic architectures. Tesla and premium European OEMs control these pipelines, extracting recurring revenue through over-the-air feature activation.
- Aftermarket Devices:Plug-in OBD-II dongles and hardwired telematics units installed post-purchase. Small fleet operators and independent owner-operators in North America and India favor these for capital expenditure flexibility.
- Mobile Applications:Smartphone-based data collection using device sensors and Bluetooth vehicle pairing. Insurtech startups leverage these for rapid deployment without hardware subsidies, though data fidelity lags dedicated automotive sensors.
- Cloud Platforms:Aggregated data lakes combining multiple vehicle feeds with external datasets. Enterprise fleet managers and logistics platforms subscribe to these for cross-fleet benchmarking and predictive analytics.
Embedded Systems capture margin concentration. Aftermarket Devices show steepest expansion trajectory among price-sensitive segments.
Use Case:
Application maturity varies sharply across verticals, with fleet management commanding established contract structures while driver assistance remains pre-commercial for data monetization.
- Fleet Management:Real-time vehicle tracking, route optimization, and driver performance monitoring for logistics operators. Long-haul trucking companies in the US and Germany represent the most sophisticated procurement, demanding API integrations with enterprise resource planning systems.
- Predictive Maintenance:Algorithmic failure prediction based on component degradation patterns. Construction equipment lessors and municipal bus operators prioritize these capabilities to minimize unscheduled downtime.
- Insurance Analytics:Risk scoring and dynamic premium adjustment from driving behavior telemetry. Progressive and European mutual insurers have deployed these models most extensively, though regulatory approval timelines vary by jurisdiction.
- Driver Assistance:Data feeds for autonomous system training and validation. This segment remains primarily cost center rather than revenue generator, with data licensing to AI training consortiums only recently emerging.
Fleet Management dominates installed base. Insurance Analytics is where expansion concentrates.
Vehicle Model:
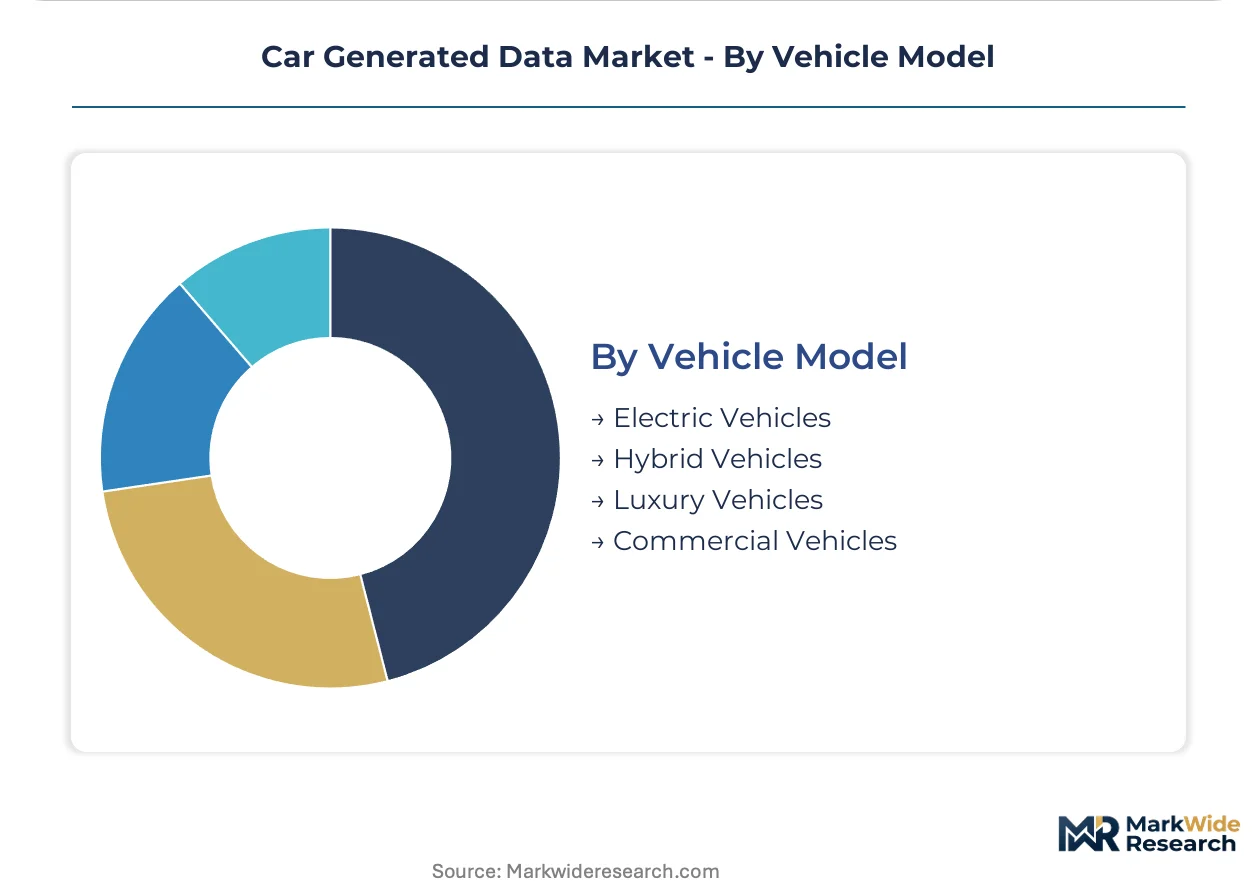
Data volume per unit scales with electrification and sensor density, creating tiered infrastructure requirements across powertrain categories.
- Electric Vehicles:Battery management system telemetry, charging optimization data, and thermal management logs generate the highest per-vehicle data volumes. China's NEV fleet and Tesla's global installed base concentrate this segment's expansion.
- Hybrid Vehicles:Dual powertrain monitoring combining internal combustion diagnostics with electric system logs. Japanese and Korean OEMs dominate production, with data architectures bridging legacy and next-generation platforms.
- Luxury Vehicles:Dense sensor arrays for advanced driver assistance and personalized cabin experiences. German premium manufacturers monetize these streams through subscription services for predictive concierge features.
- Commercial Vehicles:Heavy-duty powertrain data and regulatory compliance logging for emissions and hours-of-service. European and North American trucking fleets represent mature demand with standardized data protocols.
Commercial Vehicles dominate installed base. Electric Vehicles is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's premium OEM ecosystems while Chinese infrastructure deployment compresses margins for foreign platform operators. Regulatory fragmentation across data sovereignty regimes forces multinational architectures into jurisdiction-specific compliance layers.
United States
Fleet telematics procurement from long-haul trucking operators and usage-based insurance expansion drive demand concentration. The FCC governs 5G-V2X spectrum allocation for vehicle-to-everything communications. Detroit's automotive corridor anchors embedded system development while Silicon Valley cloud platforms aggregate cross-fleet analytics.
Germany
Premium vehicle subscription services and Mittelstand logistics operator procurement sustain revenue pools. The KBA mandates explainability audits for algorithmic driver scoring in insurance integrations. Stuttgart and Munich host OEM data architecture centers where predictive maintenance algorithms undergo regulatory validation.
China
National connected-vehicle infrastructure deployment and NEV fleet expansion generate the highest per-unit data volumes. MIIT enforces GB standards for cybersecurity and cross-border data transfer restrictions. Shenzhen and Shanghai concentrate battery management system telemetry development for charging optimization platforms.
India
Production-linked incentives for connected vehicle manufacturing attract OEM assembly investments generating localized data streams. The PLI scheme governs eligibility for domestic value-add thresholds. Tamil Nadu and Gujarat host emerging telematics hardware clusters serving price-sensitive fleet operators.
Japan
Hybrid vehicle data architectures bridging legacy and next-generation platforms sustain tier-1 supplier positioning. METI oversees standards for vehicle data portability and cross-border cloud governance. Nagoya's Chubu region anchors embedded systems engineering for dual powertrain monitoring solutions.
Car Generated Data Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the value chain. The market exhibits tiered consolidation with premium OEMs controlling proprietary pipelines and modular vendors serving price-sensitive fleet segments. Dominant archetypes include embedded system architects, cloud-native analytics platforms, and aftermarket hardware specialists. Competitive moves center on vertical integration of data pipelines and strategic partnerships bridging automotive and enterprise software ecosystems.
Within the embedded systems tier, Volkswagen Group and BMW exemplify European OEM archetypes leveraging factory-integrated architectures. Tesla occupies a distinct position at the convergence of automotive manufacturing and software-defined vehicle monetization. IBM Corporation anchors enterprise-grade fleet analytics through cloud platform integrations, representing the technology vendor archetype serving automotive clients.
| Leading Market Players |
|---|
| Volkswagen Group |
| IBM Corporation |
| Tesla |
| Vontier |
| Geotab Inc. |
| Toyota |
| BMW |
| GAC Aion |
| General Motors |
| Others |
Supply Flow & Price Mechanics
EU Data Act interoperability mandates gate both supplier qualification and price differentiation simultaneously, forcing aftermarket vendors to achieve certification parity with embedded OEM architectures before accessing fleet procurement channels. This regulatory threshold stratifies the market into certified premium streams and uncertified economy alternatives.
Pricing Analysis
Configured-to-order pricing for embedded OEM telemetry systems commands substantial premiums over standardized aftermarket OBD-II dongles. Subscription-based SaaS tiers dominate revenue models, with price differentiation resting on certification grade (ISO 26262 functional safety tier) and customization depth for enterprise fleet APIs. Cost compression in the aftermarket segment intensifies as Chinese hardware vendors scale production of cellular modems. Small fleet operators in India and North America exhibit highest price sensitivity, while German Mittelstand logistics buyers prioritize integration depth over unit cost.
Supply Chain Analysis
Inventory lead times for automotive-grade neural processing units and cellular modems have extended as Taiwan and South Korea fabrication capacity faces allocation constraints. Semiconductor supply concentrates in Taiwan, South Korea, and Japan for advanced driver-assistance system chips. Raw material dependencies include silicon wafers, rare earth elements for magnetics, and lithium compounds for battery management telemetry. Single-source vulnerability around Taiwan semiconductor foundries poses structural risk. Distribution runs through Tier 1 automotive suppliers and direct OEM procurement channels, with cloud platform aggregators emerging as secondary downstream nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Data Act's third-party data portability provisions create a platform-economics inflection, transforming proprietary OEM pipelines into interoperable marketplaces where ecosystem orchestration replaces captive data control.
For Market Incumbents: Secure algorithmic explainability certifications ahead of German KBA audit mandates to defend usage-based insurance partnerships against cloud-native analytics entrants. Consolidate edge computing architectures through backward integration into neural processing unit design, reducing dependency on Taiwan semiconductor allocation. Channel control over dealership management systems provides defensive leverage against disintermediation.
For New Entrants and Emerging Players: Anchor in India's PLI-connected vehicle manufacturing zones where localized data streams lack incumbent platform saturation. Target aftermarket retrofit segments for pre-2020 commercial fleets excluded from unified OEM analytics by CAN bus legacy fragmentation. Partner with insurtech startups for smartphone-based rapid deployment without hardware subsidy requirements.
For Investors and Strategic Acquirers: The EU Data Act's full interoperability enforcement reshapes the acquisition landscape toward API-first analytics platforms with cross-OEM integration capabilities. Long-term viability favors targets possessing both automotive safety certification and cloud-native architecture competence. Monitor FCC 5G-V2X spectrum allocation rulings as inflection signal for cooperative perception application monetization.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Tesla's over-the-air monetization model demonstrates recurring revenue extraction from feature activation. |
| Battery Supply Agreement | Chinese NEV fleet expansion generates highest per-unit data volumes through BMS telemetry streams. |
| Platform Integration | IBM's cloud aggregator positioning bridges automotive OEMs with enterprise fleet management systems. |
| Geographic Manufacturing Footprint | India's PLI scheme attracts assembly investments generating localized data streams for regional providers. |
| Charging Infrastructure Partnership | Vehicle-to-grid bidirectional optimization creates revenue pools for distributed energy resource aggregators. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with automotive industry stakeholders and systematic secondary validation across regulatory and commercial databases. Primary engagements included OEM platform engineers, Tier 1 supplier procurement leads, fleet management operators, and cloud platform integration specialists. Secondary sources encompassed vehicle production databases, IHS Markit registration data, EU Data Act implementation guidance, MIIT GB standard filings, and FCC spectrum allocation dockets. Bottom-up segmentation modeling triangulated against top-down market sizing across data type, source architecture, and regional deployment patterns.
Across the analysis window, the forecasting framework modeled volume and value trajectories through disaggregated segmentation dimensions: vehicle propulsion architecture, OEM tier positioning, data source integration depth, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to installed base projections and monetization rate assumptions. Industry-specific inputs included electric vehicle penetration schedules, 5G-V2X deployment timelines, and GDPR consent orchestration maturity curves.
Decision-makers should treat outputs as directional under base assumptions of sustained semiconductor supply normalization and stable cross-border data governance frameworks; material deviation in Taiwan geopolitical risk or EU Data Act enforcement intensity would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Telematics and Connectivity Processors Market
Telematics and Infotainment
Automotive Navigation & Infotainment Systems Market
Telematics and Infotainment
Asia-Pacific Connected Cars Market
Telematics and Infotainment
In-Car Apps Market
Telematics and Infotainment
In-Cabin Lighting-Climate-Audio Synchronized Experience Systems Market
Telematics and Infotainment
India Connected Car Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
5G V2X Communications Market
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Asia Pacific Automotive Infotainment Systems Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Global Vehicle Fleet Communication Market
Telematics and Infotainment
Intelligent Transport Systems (ITS) Market
Telematics and Infotainment
Smart Telematics Gateway Market
Telematics and Infotainment
Automotive Personal Navigation Systems Market