
 Electronic Rotary Controller Systems for Infotainment Market | 2026-2036
Electronic Rotary Controller Systems for Infotainment Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Rotary Controller Systems for Infotainment Market Insights
Market Context
REACH is decoupling material compliance costs from economies of scale, forcing smaller suppliers to consolidate or exit. Alps Alpine leverages captive manufacturing in Japan to sustain cost advantages across haptic-enabled rotary modules. Continental anchors European supply through integrated sensor production in Germany. Hyundai Mobis competes via dedicated R&D centers serving Korean OEM verticals.
Technical Definition and Segment Structure
Electronic rotary controller systems for infotainment are electromechanical human-machine interface devices that translate rotational mechanical input into digital signals for vehicle cockpit systems, typically operating with resolutions between 16 and 1024 pulses per revolution to enable precise menu navigation and volume control. These systems serve the primary commercial purpose of minimizing driver cognitive load by providing tactile, eyes-free operation of infotainment functions during vehicle motion. Capacitive sensors and haptic feedback technology dominate current OEM specifications, while optical encoders command premium positioning in navigation and driver assistance display applications where absolute positional accuracy determines system performance. Mechanical rotary encoders retain volume leadership in climate control interfaces due to proven durability under thermal cycling and lower per-unit cost structures.
Regulatory Frame and Outlook
FCC electromagnetic compatibility standards govern controller signal transmission in United States vehicles, while ECE R10 regulations administered by European type-approval authorities shape EMC testing protocols for systems sold across EU member states. Japan's METI oversees domestic safety certification through alignment with UN R79 steering equipment standards that indirectly constrain rotary controller placement and force-feedback parameters. Stakeholders must monitor divergence between ISO 26262 functional safety requirements and emerging cybersecurity standards for connected cockpit interfaces.
Market Dynamics
The EU's General Safety Regulation mandating hands-on interface controls for specific vehicle classes is compressing mechanical encoder adoption timelines while Tier-1 suppliers co-locate with OEM headquarters to secure program wins.
Growth Catalysts
- Regulatory Mandate:The EU's General Safety Regulation requires hands-on controls for certain vehicle classes, accelerating mechanical rotary encoder deployment across German premium passenger vehicle OEMs.
- Driver Distraction Reduction:Haptic feedback technology enables eyes-free operation of infotainment functions, addressing NHTSA guidelines on cognitive load during vehicle motion in United States markets.
- Supply Chain Proximity:Tier-1 suppliers concentrate engineering resources in Germany's automotive corridor to align with BMW, Mercedes-Benz, and Volkswagen program development cycles.
Market Restraints
- Input Cost Volatility:Rare earth magnet prices for precision encoder motors fluctuate with Chinese export quota policies, compressing margin structures for non-integrated suppliers.
- Supply Concentration Risk:Capacitive sensor ASIC fabrication concentrates in Taiwanese foundries, exposing procurement to geopolitical disruption and capacity allocation constraints.
- Substitution Threat:Voice control and gesture recognition interfaces from Silicon Valley automotive software providers displace rotary controllers in entry-level electric vehicle segments.
Strategic Opportunities
- Underpenetrated Geography:Indian premium vehicle production lacks localized rotary controller manufacturing, creating white space for suppliers establishing captive plants under the PLI scheme.
- Technology Convergence:Integration of force-feedback actuators with LIN bus communication protocols enables next-generation haptic rotary modules for autonomous vehicle readiness modes.
- Regulatory Tailwind:Japan's METI alignment with UN R79 steering equipment standards constrains rotary controller placement, favoring specialized suppliers with certified force-feedback calibration capabilities.
Industry Challenges
- Certification Timeline Compression:ISO 26262 ASIL-B functional safety validation for haptic feedback systems extends development cycles by 14-18 months, straining program launch schedules.
- Legacy System Integration:Backward compatibility with 12-volt electrical architectures in existing vehicle platforms complicates the transition to 48-volt haptic actuator designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Rotary Controller Systems for Infotainment Market |
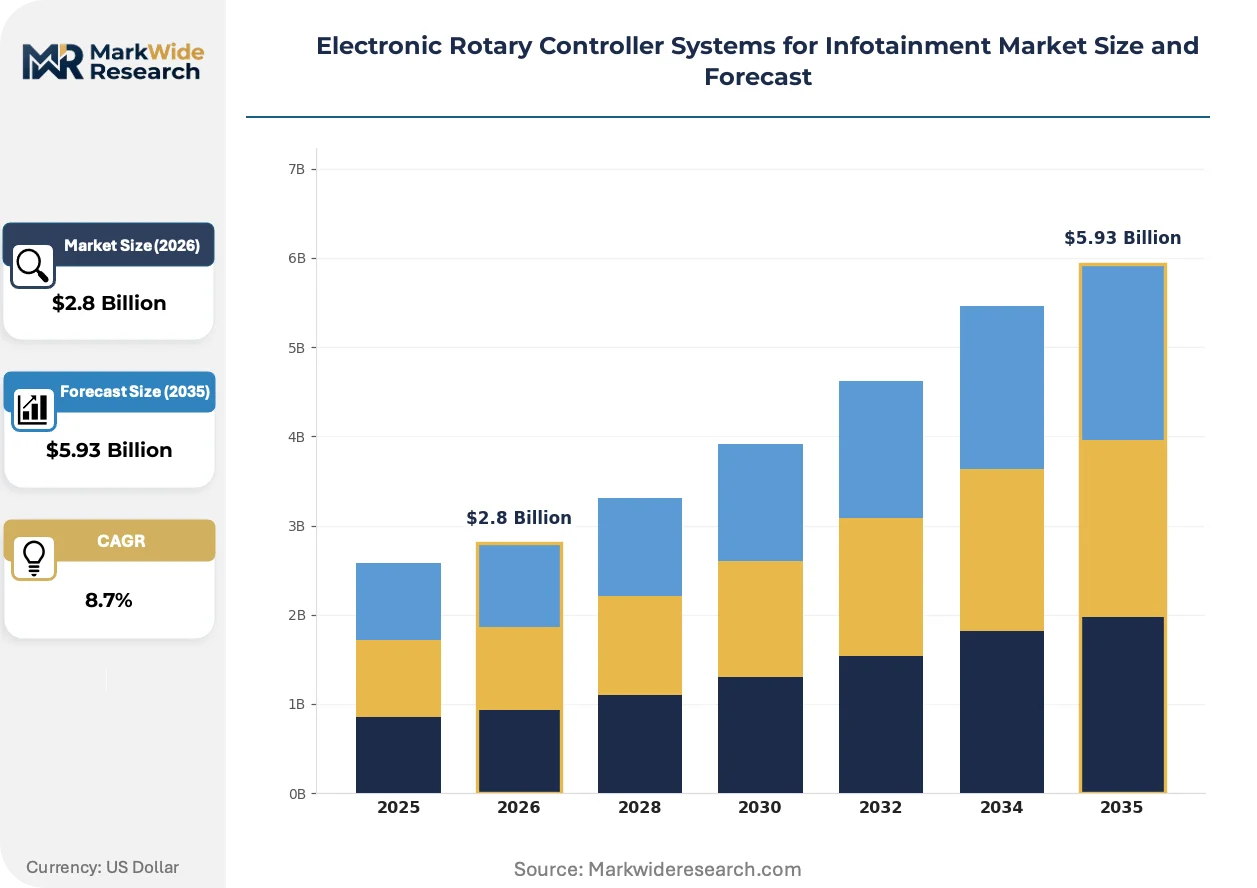
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical Rotary Encoders, Capacitive Sensors, Optical Encoders, Hall Effect Sensors, Inductive Sensors Technology: Haptic Feedback, Touch Sensitive, Clickable Knob, Rotary Dial, Gesture Recognition Application: In-Vehicle Infotainment, Navigation Systems, Climate Control Interface, Audio Systems, Driver Assistance Display End User Industry: OEMs, Tier-1 Component Suppliers, Aftermarket Installers, Fleet Management, Smart Vehicle Integrators |
| Companies Covered | Alps Alpine, Panasonic Automotive Systems, Hyundai Mobis, Continental, Marelli, Visteon, Bosch Mobility, Denso, Valeo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Rotary Controller Systems for Infotainment Market Trends and Innovations
Haptic-enabled rotary modules are displacing conventional mechanical encoders as OEMs prioritize tactile feedback precision, while regulatory divergence between cybersecurity and functional safety standards is fragmenting certification pathways.
Magnetic position sensing is decentralizing rotary encoder architectures by enabling contactless rotational measurement immune to dust and thermal cycling degradation. German premium OEMs are adopting this technology for climate control interfaces operating between -40°C and 85°C. This shift is decentralizing sensor placement away from centralized PCB assemblies toward distributed mechatronic modules.
REACH substance restrictions on per- and polyfluoroalkyl substances are forcing reformulation of lubricant greases used in rotary bearing assemblies. European Tier-1 suppliers face requalification costs for existing encoder designs while sourcing PFAS-free alternatives from specialty chemical providers. The climate control segment bears disproportionate impact due to extended temperature exposure requirements.
Fleet operators and mobility service providers now specify controller durability metrics in procurement contracts rather than deferring to OEM component selections. This bypasses traditional Tier-1 supplier relationships and channels volume toward specialized encoder manufacturers with published cycle-life data. The phenomenon is most visible in United States commercial vehicle upfitter markets serving last-mile delivery electrification.
Electronic Rotary Controller Systems for Infotainment Market Segmentation
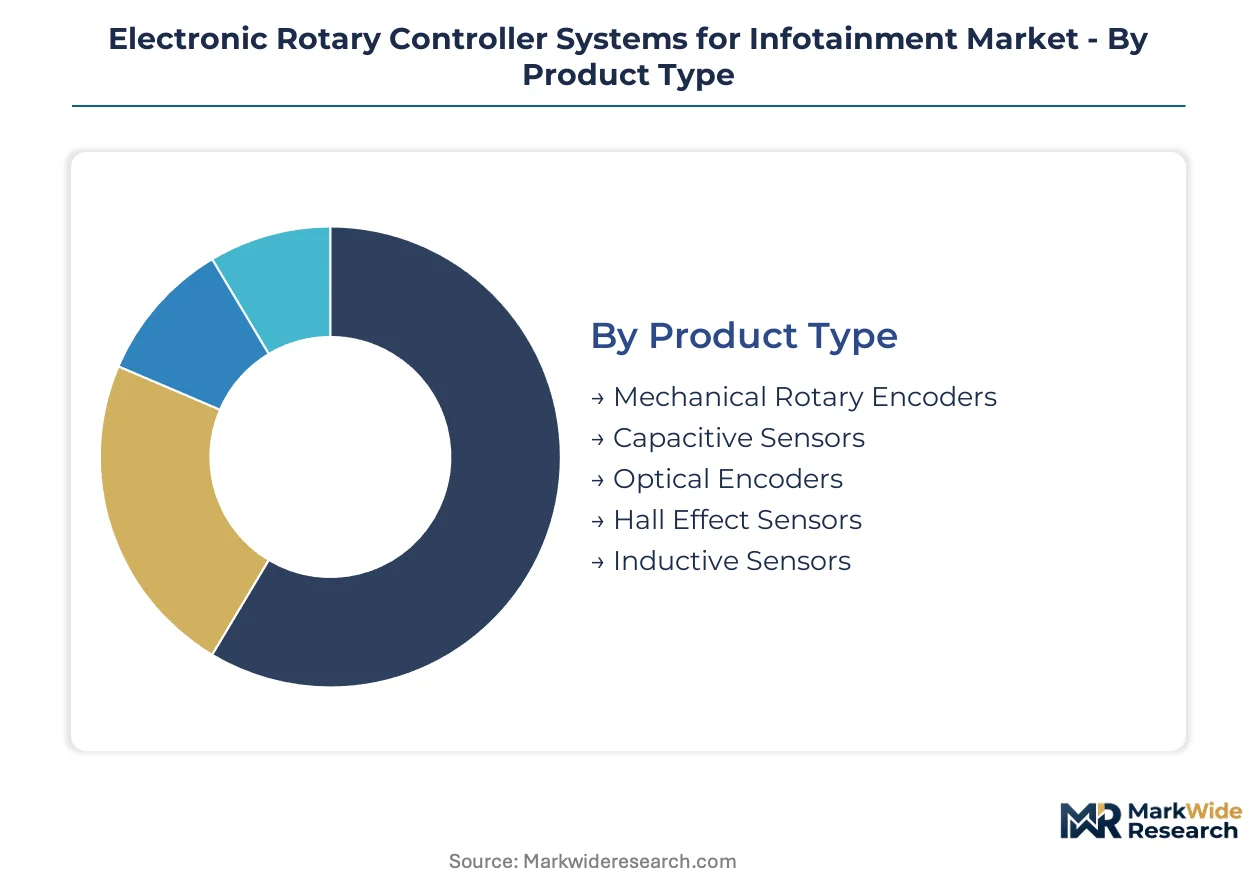
Segmentation in electronic rotary controller systems reveals how technology choices map to vehicle platform architectures and regulatory compliance tiers. Upgrade cycles differ sharply across infotainment, climate control, and navigation applications, with replacement timelines stretching from 3-year model refreshes to full platform redesigns.
Product Type:
Replacement cycles for rotary encoder technologies compress as OEMs migrate from mechanical to contactless sensing architectures to meet durability specifications.
- Mechanical Rotary Encoders:Contact-based electromechanical devices using conductive tracks and wipers to generate pulse signals, typically rated for 100,000 to 1 million rotational cycles. Demand concentrates in climate control modules for German premium passenger vehicles where EU General Safety Regulation mandates hands-on interface controls, though REACH substance restrictions on PFAS lubricants are forcing bearing assembly reformulations.
- Capacitive Sensors:Field-effect sensing elements detecting finger proximity and position without mechanical wear, enabling seamless surface integration. Japanese OEMs in Toyota City and Hiroshima prefectures specify these for center-stack infotainment clusters where METI alignment with UN R79 standards constrains controller placement and force-feedback calibration.
- Optical Encoders:Photodetector arrays reading patterned discs deliver absolute positional accuracy for navigation display interfaces.
- Hall Effect Sensors:Magnetic field detection enables contactless rotational measurement immune to dust and thermal cycling degradation.
- Inductive Sensors:Eddy-current sensing provides robust performance in high-temperature engine-bay proximities.
Volume placements concentrate in Mechanical Rotary Encoders; the faster expansion belongs to Capacitive Sensors.
Technology:
Controller interface technologies stratify by cognitive load reduction capability and cost tier, with haptic systems commanding premium positioning.
- Haptic Feedback:Electromagnetic actuators generate programmable tactile responses—clicks, detents, and resistance profiles—to confirm user inputs without visual confirmation. BMW and Mercedes-Benz program development cycles in Stuttgart and Munich specify these for eyes-free operation compliance with NHTSA guidelines on driver distraction in United States export configurations.
- Gesture Recognition:Time-of-flight cameras and radar sensors interpret hand motions for non-contact interface control, displacing rotary hardware in entry-level electric vehicle segments from Silicon Valley automotive software providers.
- Touch Sensitive:Capacitive surface arrays enable swipe and tap gestures on rotary controller crowns.
- Clickable Knob:Mechanical push-to-select functionality remains standard in cost-optimized climate control modules.
- Rotary Dial:Basic rotational input without supplementary sensing dominates emerging market vehicle platforms.
Customer procurement runs through Haptic Feedback for premium platform placements; Gesture Recognition is climbing the fastest in electric vehicle segments.
Application:
Application-specific durability requirements and thermal exposure profiles drive encoder technology selection across cockpit domains.
- Climate Control Interface:Rotary controllers for temperature and fan speed adjustment operate across -40°C to 85°C thermal cycles, favoring magnetic position sensing architectures. German premium OEMs specify decentralized sensor placement in distributed mechatronic modules for these interfaces, with fleet operators now demanding published cycle-life data in procurement contracts.
- Navigation Systems:Absolute positional accuracy requirements for map zoom and menu hierarchy navigation command optical encoder precision. United States commercial vehicle upfitter markets serving last-mile delivery electrification bypass traditional Tier-1 relationships to source specialized encoders with validated durability metrics.
- In-Vehicle Infotainment:Central stack controllers integrate volume, menu, and media selection functions.
- Audio Systems:Dedicated amplifier and equalizer controls persist in luxury vehicle configurations.
- Driver Assistance Display:Human-machine interface for ADAS setting adjustment requires ISO 26262 ASIL-B functional safety validation.
Program wins cluster in Climate Control Interface; Navigation Systems are gaining share fastest in commercial vehicle specifications.
End User Industry:
Supply chain proximity requirements and certification capabilities fragment the customer base across integration tiers.
- OEMs:Vehicle manufacturers in Germany's automotive engineering corridor—BMW in Munich, Mercedes-Benz in Stuttgart, Volkswagen in Wolfsburg—directly specify rotary controller architectures to secure program development cycle alignment and reduce driver distraction liability exposure under EU General Safety Regulation mandates.
- Tier-1 Component Suppliers:Integrated cockpit module providers co-locate engineering resources with OEM headquarters to capture infotainment system integration contracts.
- Aftermarket Installers:Independent vehicle modification shops serve enthusiast and commercial retrofit demand.
- Fleet Management:Mobility service providers specify controller durability metrics directly, channeling volume toward encoder manufacturers with published cycle-life data.
- Smart Vehicle Integrators:Autonomous vehicle readiness mode developers source force-feedback actuators with LIN bus communication protocols.
Contract value concentrates in OEMs; Fleet Management is expanding most quickly in procurement influence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production Linked Incentive scheme for automotive components is drawing rotary controller suppliers toward Gujarat and Tamil Nadu manufacturing zones. German premium OEM engineering corridors and Japanese precision component clusters anchor established supply networks.
Germany
BMW, Mercedes-Benz, and Volkswagen program development cycles in Munich, Stuttgart, and Wolfsburg drive specification authority for haptic-enabled rotary modules. The EU's General Safety Regulation mandates hands-on interface controls, compressing mechanical encoder adoption timelines for climate control applications. Bavaria's automotive engineering corridor concentrates Tier-1 supplier engineering resources to secure infotainment system integration contracts.
Japan
Toyota City and Hiroshima prefecture OEMs specify capacitive sensor arrays for center-stack infotainment clusters where tactile feedback precision reduces driver cognitive load. METI alignment with UN R79 steering equipment standards constrains rotary controller placement and force-feedback calibration parameters. Nagoya-based precision component manufacturers supply magnetic position sensing architectures for climate control interfaces.
United States
NHTSA guidelines on driver distraction propel haptic feedback adoption for eyes-free operation in vehicles exported to North American markets. FCC electromagnetic compatibility standards govern controller signal transmission protocols for infotainment systems. Michigan and Ohio automotive clusters host Tier-1 supplier engineering operations aligned with Detroit-area OEM program cycles.
China
Domestic EV manufacturers in Shenzhen and Shanghai are displacing rotary hardware with voice control and gesture recognition interfaces from automotive software providers. MIIT oversees type-approval standards for cockpit human-machine interface devices under GB automotive safety regulations. Yangtze River Delta electronics manufacturing bases supply capacitive sensor ASICs to regional module integrators.
South Korea
Hyundai and Kia vertical integration strategies concentrate rotary controller R&D within dedicated supplier campuses serving domestic OEM production. MFDS alignment with international functional safety standards shapes certification requirements for haptic feedback systems. Seoul Capital Area engineering centers develop force-feedback actuators with LIN bus communication protocols for autonomous vehicle readiness modes.
Electronic Rotary Controller Systems for Infotainment Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions in electronic rotary controller systems. Japanese and Korean automotive component groups leverage captive manufacturing to sustain cost advantages, while European integrated cockpit module providers anchor regional supply through sensor production co-location. Three archetypes dominate: diversified electronics conglomerates with automotive divisions, specialized mechatronics component manufacturers, and integrated Tier-1 cockpit system suppliers. Competitive dynamics center on backward integration into precision encoder manufacturing and geographic expansion to align with OEM program development cycles.
Among diversified Japanese electronics conglomerates, Alps Alpine and Panasonic Automotive Systems exemplify scale-driven positions spanning haptic module design through captive production. Continental anchors the European integrated supplier tier with Germany-based sensor fabrication serving premium OEM engineering corridors. Hyundai Mobis occupies a specialized position within Korean OEM vertical supply structures, representing the dedicated-R&D-center archetype for domestic automotive group requirements.
| Leading Market Players |
|---|
| Alps Alpine |
| Panasonic Automotive Systems |
| Hyundai Mobis |
| Continental |
| Marelli |
| Visteon |
| Bosch Mobility |
| Denso |
| Valeo |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in Germany's automotive engineering corridor maintain pricing discipline through captive precision encoder manufacturing, insulating program margins from rare earth magnet cost volatility while Tier-1 suppliers absorb REACH compliance expenses through long-term OEM contracts.
Pricing Analysis
Premium pricing attaches to short lead-time orders for haptic-enabled rotary modules serving German OEM platform refreshes, while spot inventory of mechanical encoders trades at discounted levels. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-B certified haptic systems from ISO 26262-unvalidated mechanical units and basic climate control dials. Pricing pressure stems from voice control substitution in Chinese EV segments, compressing entry-level rotary controller margins. Fleet operators exhibit highest price sensitivity through published cycle-life procurement specifications, while premium OEMs prioritize tactile feedback precision over unit cost.
Supply Chain Analysis
Freight cost escalation from Taiwanese foundries to German module integrators is reshaping capacitive sensor ASIC procurement patterns toward regional buffer inventory strategies. Manufacturing concentrates in Germany, Japan, and Taiwan, with magnetic position sensing architectures feeding from Nagoya-based precision component clusters. Rare earth magnets for encoder motors draw from Chinese processing facilities, while PFAS-free lubricant greases source from European specialty chemical providers. Single-source vulnerability concentrates in Taiwanese semiconductor fabrication exposing procurement to geopolitical disruption. Distribution runs through Tier-1 cockpit module integrators co-located with OEM headquarters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electronic rotary controller market sits in a technology-transition phase as magnetic position sensing displaces mechanical encoder architectures in climate control applications.
For Market Incumbents: Lock in program wins through backward integration into precision encoder manufacturing and ASIL-B certification investment for haptic feedback systems. Voice control substitution from Silicon Valley software providers threatens entry-level segments, requiring defensive capacity concentration in Germany's automotive corridor to maintain OEM relationship density. For New Entrants and Emerging Players: Begin with fleet management procurement channels in United States commercial vehicle upfitter markets, where durability metric specifications bypass traditional Tier-1 relationships. India's PLI scheme for automotive components offers the most penetrable geography for captive manufacturing establishment, with climate control interfaces presenting the lowest certification barrier to entry. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialized mechatronics component manufacturers with published cycle-life data and force-feedback calibration capabilities in South Korea. Long-term viability hinges on autonomous vehicle readiness mode integration over the next decade. Watch for divergence between ISO 26262 functional safety requirements and emerging cybersecurity standards as the inflection signal for certification-capable asset premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Encoder Manufacturing | Captive production of magnetic position sensors insulates margins from rare earth price volatility. |
| ASIL-B Functional Safety Certification Investment | Validation for haptic feedback systems secures premium placement in BMW and Mercedes-Benz programs. |
| PLI Scheme Manufacturing Establishment in India | Gujarat and Tamil Nadu plants capture white space in localized premium vehicle production supply. |
| Force-Feedback Actuator LIN Bus Integration | Next-generation haptic modules align with Hyundai and Kia autonomous vehicle readiness mode specifications. |
| PFAS-Free Lubricant Grease Reformulation | REACH compliance for bearing assemblies maintains access to EU climate control interface contracts. |
Research Methodology
Document review covered regulatory filings with ECHA and METI, trade data from EU and Japanese customs authorities, and OEM procurement specifications, complemented by interviews with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and precision component manufacturing directors. Secondary validation drew from vehicle production databases, IHS Markit registration data, and SEC filings from diversified electronics conglomerates. Bottom-up encoder unit demand modeling triangulated against top-down infotainment system value estimates.
Unit shipment and revenue estimates across the projection horizon reflect segmentation by encoder technology type, haptic feedback integration tier, vehicle class, and regional production cluster. CAGRs derived from regression analysis of historical OEM program launch cadences and regulatory mandate implementation timelines. Industry-specific inputs included EU General Safety Regulation compliance deadlines and NHTSA guideline adoption trajectories for driver distraction reduction.
Underlying measurement precision varies by segment; haptic-enabled rotary modules carry tighter precision than mechanical encoder volumes due to concentrated supplier disclosure. Forecasts reflect assumptions regarding OEM platform electrification rates and REACH substance restriction enforcement intensity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Automotive Wi-Fi Router Market
Telematics and Infotainment
Global Automotive Infotainment System Market
Telematics and Infotainment
Automotive Rear Seat Infotainment Market
Telematics and Infotainment
Commercial Vehicle Telematics Market
Telematics and Infotainment
Telematics and Connectivity Control Unit Systems Market
Telematics and Infotainment
Dashboard Camera Market
Telematics and Infotainment
Global Carpool-As-A-Service Market
Telematics and Infotainment
Automotive OEM Telematics Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
Mobile Resource Management (MRM) Market
Telematics and Infotainment
Automotive Navigation & Infotainment Systems Market
Telematics and Infotainment
In Car Infotainment System Market
Telematics and Infotainment
Automotive Embedded Telematics Market
Telematics and Infotainment
Global Intelligent Transportation System (ITS) Market
Telematics and Infotainment
Global Car Sharing Telematics Market