
 Bulimia Nervosa Market | 2026-2036
Bulimia Nervosa Market Size, Share, and Industry Trends Forecast 2026-2036
Bulimia Nervosa Market Analysis
APA accreditation for eating disorder specialists is redrawing competitive boundaries among pharmaceutical developers. Eli Lilly and Company leverages its psychiatric research infrastructure to sustain antidepressant pipelines. Pfizer Inc. anchors clinical development through broad CNS therapeutic expertise. GlaxoSmithKline plc differentiates via established neurology and mental health portfolios.
Bulimia Nervosa constitutes a recurrent eating disorder characterized by binge-eating episodes followed by compensatory behaviors, with diagnostic criteria specifying a minimum frequency of once weekly for three months per DSM-5-TR standards. The condition primarily serves clinical and therapeutic markets requiring structured intervention protocols. Cognitive Behavioral Therapy occupies the dominant position among therapy types due to its established efficacy in randomized controlled trials. Antidepressants, particularly selective serotonin reuptake inhibitors, concentrate the largest medication type share. Outpatient Clinics capture expanding volume as stepped-care models reduce reliance on inpatient admission.
The FDA governs new drug approvals for bulimia nervosa indications through its psychiatric products division, while the DEA monitors controlled substance scheduling for adjunctive pharmacotherapies. APA practice guidelines further shape prescriber behavior and reimbursement pathways for evidence-based interventions. Stakeholders must monitor evolving digital therapeutics regulations and telehealth parity laws that could redistribute care delivery across traditional and virtual settings.
Market Dynamics
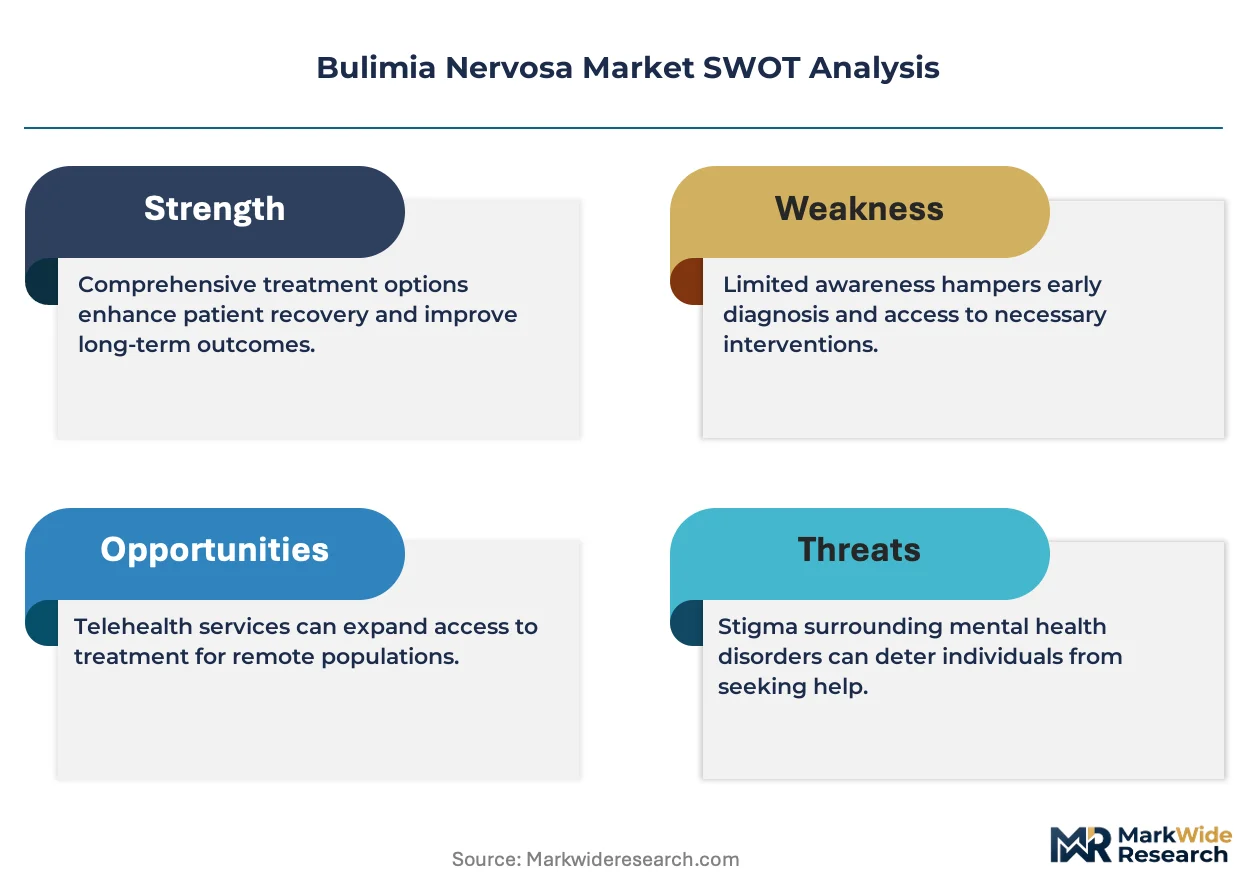
Specialty psychiatric hospitals in the United States are expanding dedicated eating disorder programs. This institutional investment is compressing the traditional outpatient-to-inpatient referral pathway and redistributing patient volume toward integrated care models.
Growth Catalysts
- APA Accreditation Standards:New credentialing requirements for eating disorder specialists are expanding the qualified prescriber pool. This framework accelerates evidence-based protocol adoption across clinical networks.
- Digital Therapeutics:FDA breakthrough device designations for CNS applications are opening reimbursement pathways for software-based interventions. Telehealth parity laws in multiple states extend reach to rural patient populations.
- Stepped-Care Models:Outpatient clinics in North America are capturing volume through structured intensity gradations. This delivery format reduces cost per episode while maintaining clinical outcomes.
Market Restraints
- Specialist Workforce Scarcity:Board-certified eating disorder psychiatrists concentrate in coastal metropolitan areas. Geographic maldistribution limits program expansion in interior states.
- Reimbursement Compression:Commercial payers in the United States are narrowing prior authorization windows for intensive outpatient programs. This friction delays treatment initiation.
- Diagnostic Complexity:Comorbid personality disorders and substance use conditions complicate pharmacotherapy selection. Polypharmacy risk elevates liability exposure for prescribers.
Strategic Opportunities
- Adolescent Residential Expansion:Underpenetrated markets in the Mountain West and Southeast United States present bed capacity expansion potential. Medicaid waiver programs in these states are expanding behavioral health carve-outs.
- Measurement-Based Care:Integration of standardized symptom tracking into electronic health records enables outcome contracting with value-based purchasers. This data infrastructure supports risk-sharing arrangements.
- Transdiagnostic Protocols:Unified treatment approaches spanning bulimia nervosa, binge eating disorder, and avoidant/restrictive food intake disorder streamline training and scale specialist efficiency.
Industry Challenges
- Clinical Trial Recruitment:Eligibility criteria for bulimia nervosa pharmacotherapy studies exclude patients with common psychiatric comorbidities. This restriction narrows the evidence base for real-world populations.
- EHR Integration Friction:Behavioral health modules in dominant hospital information systems lack eating disorder-specific assessment workflows. Custom configuration demands substantial implementation consulting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulimia Nervosa Market |
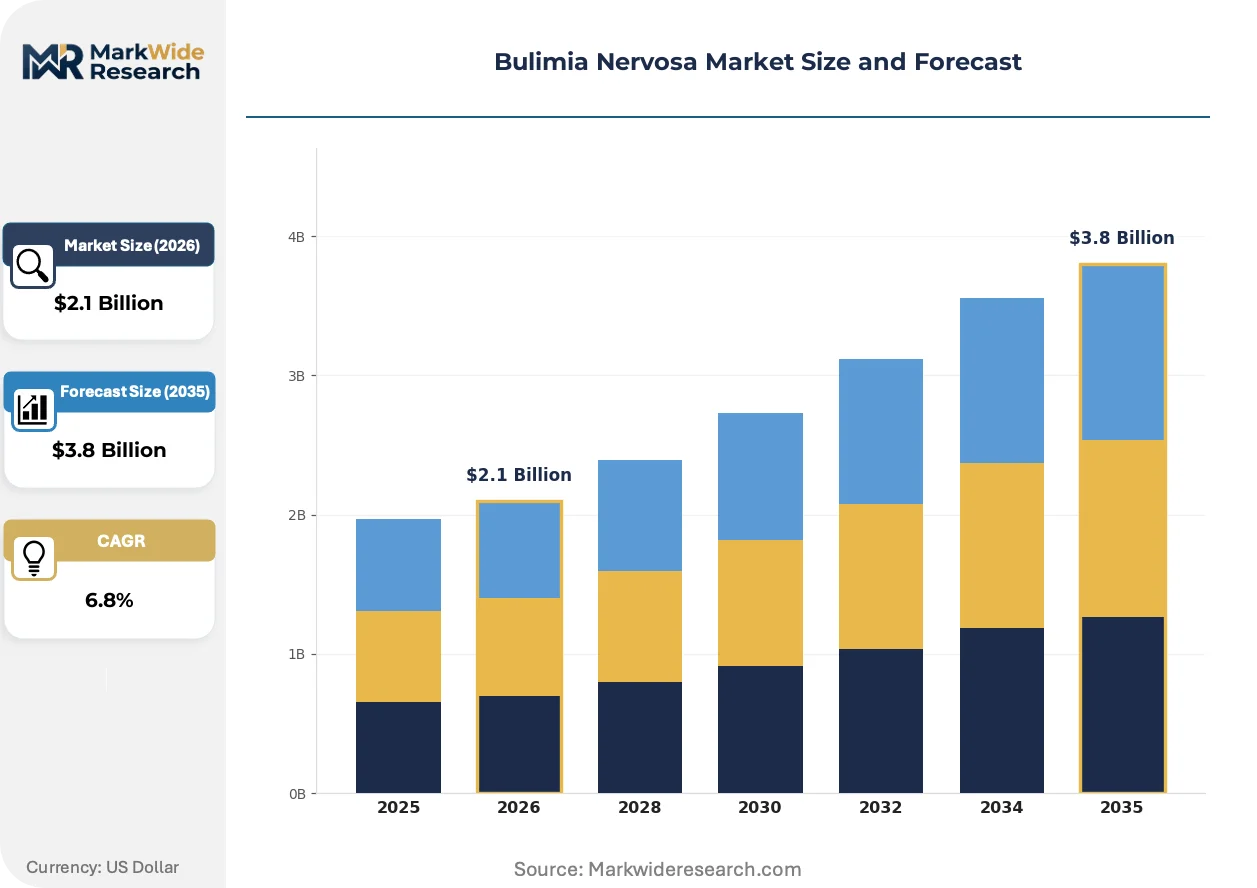
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Type: Cognitive Behavioral Therapy, Dialectical Behavior Therapy, Nutrition Counseling, Psychodynamic Therapy Medication Type: Antidepressants, Mood Stabilizers, Antipsychotics, Hormonal Treatments Care Setting: Inpatient Facilities, Outpatient Clinics, Residential Treatment Centers, Private Practices Patient Age Group: Adolescents, Young Adults, Adults, Seniors |
| Companies Covered | Pfizer Inc., Eli Lilly and Company, Johnson & Johnson Services, Inc., GlaxoSmithKline plc, AstraZeneca plc, Bristol-Myers Squibb Company, Allergan, Inc., Merck & Co., Inc., Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulimia Nervosa Market Emerging Trajectories
Digitally delivered cognitive behavioral therapy is reshaping access patterns for bulimia nervosa treatment. Three converging developments are restructuring how interventions reach patients and how outcomes are measured.
Smartphone-based ecological momentary assessment is fragmenting the traditional weekly therapy session model. Adolescent patients in university counseling centers are adopting real-time symptom logging at accelerating rates. This continuous data stream is compressing the feedback loop between clinical events and therapeutic adjustment.
FDA guidance on digital therapeutics for psychiatric indications is clarifying the evidentiary threshold for software-based interventions. The agency's pre-certification pilot for CNS products is streamlining review timelines for algorithm-driven behavioral protocols. European regulators through the EMA are observing these developments to inform their own software-as-medical-device frameworks.
Employer-sponsored behavioral health carve-outs are redirecting commercial patient volume toward specialized eating disorder networks. Large self-insured plans in the United States are contracting directly with residential program operators, bypassing traditional managed care intermediaries. This channel shift concentrates volume with accredited providers capable of reporting standardized outcomes.
Bulimia Nervosa Market Segmentation
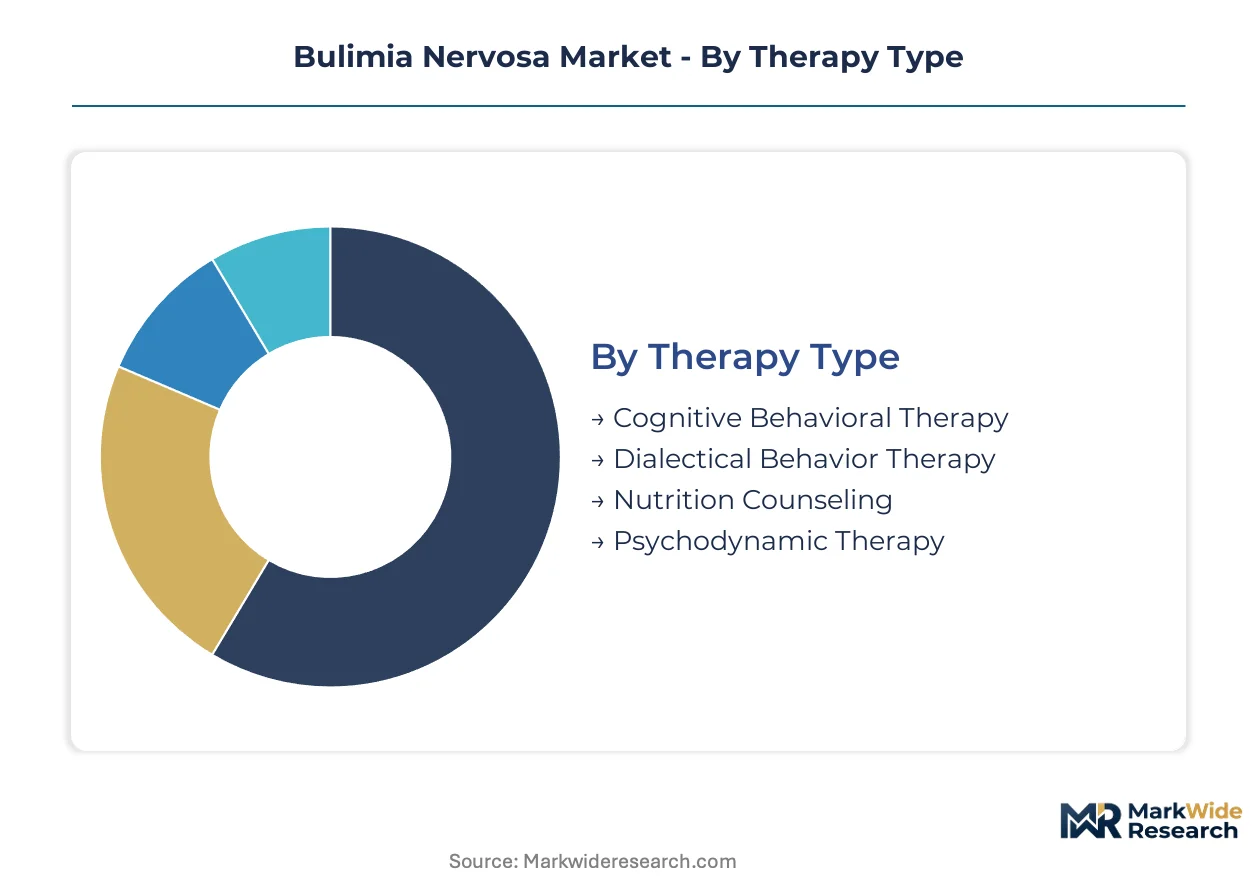
Segmentation in the bulimia nervosa market reflects divergent regulatory pathways and reimbursement structures. Each dimension carries distinct compliance burdens and prescriber certification requirements that shape competitive positioning.
Therapy Type:
FDA breakthrough device designations for digital therapeutic platforms are creating reimbursement tiering across intervention modalities.
- Cognitive Behavioral Therapy:Structured protocol targeting binge-purge cycles through cognitive restructuring and behavioral monitoring. Outpatient clinics in the United States concentrate demand as stepped-care models prioritize evidence-based protocols with measurable outcomes. APA accreditation requirements for CBT-specialist clinicians constrain supply expansion.
- Dialectical Behavior Therapy:Emotion regulation framework adapted for eating disorder populations with high comorbid borderline personality features. Residential treatment centers in coastal metropolitan areas are integrating DBT modules into comprehensive programming. Medicaid carve-outs in select states are expanding coverage for intensive DBT tracks.
- Nutrition Counseling:Registered dietitian-led medical nutrition therapy addressing metabolic stabilization and normalized eating patterns.
- Psychodynamic Therapy:Longer-term exploratory approach addressing developmental antecedents of disordered eating.
Cognitive Behavioral Therapy handles the majority of throughput; Dialectical Behavior Therapy is expanding most quickly on share.
Medication Type:
DEA scheduling determinations and FDA psychiatric division labeling create divergence in prescriber accessibility and pharmacy distribution.
- Antidepressants:Selective serotonin reuptake inhibitors constitute the primary pharmacologic intervention with established efficacy in reducing binge frequency. Fluoxetine holds specific FDA approval for bulimia nervosa indication. Commercial formularies in the United States tier these agents as preferred without prior authorization.
- Mood Stabilizers:Lithium and anticonvulsant derivatives deployed in complex presentations with comorbid bipolar spectrum conditions. Academic medical centers with eating disorder psychiatry fellowships concentrate prescriber expertise for polypharmacy regimens. Liability exposure elevates documentation requirements.
- Antipsychotics:Atypical agents used adjunctively for severe behavioral dyscontrol or comorbid psychotic features.
- Hormonal Treatments:Interventions addressing amenorrhea and bone density compromise in chronic presentations.
Antidepressants dominate prescription volume; Mood Stabilizers are gaining share fastest in complex comorbidity segments.
Care Setting:
Telehealth parity legislation and state-level Medicaid waiver programs are redistributing patient volume across intensity levels.
- Outpatient Clinics:Structured intensity gradations from weekly therapy to partial hospitalization. Stepped-care models in North America are compressing traditional referral pathways to residential levels. Digital therapeutic integration enables remote symptom monitoring and protocol adherence tracking.
- Residential Treatment Centers:24-hour structured programming for medical instability or failed outpatient trials. Self-insured employer plans are contracting directly with accredited operators, bypassing managed care intermediaries. Bed capacity expansion concentrates in Mountain West and Southeast United States.
- Inpatient Facilities:Acute medical stabilization for electrolyte emergencies or cardiac complications.
- Private Practices:Individual practitioner delivery with variable specialization depth and outcome measurement.
Outpatient Clinics handle the majority of throughput; Residential Treatment Centers are climbing the fastest on share.
Patient Age Group:
Developmental stage determines regulatory framework, consent requirements, and family system involvement intensity.
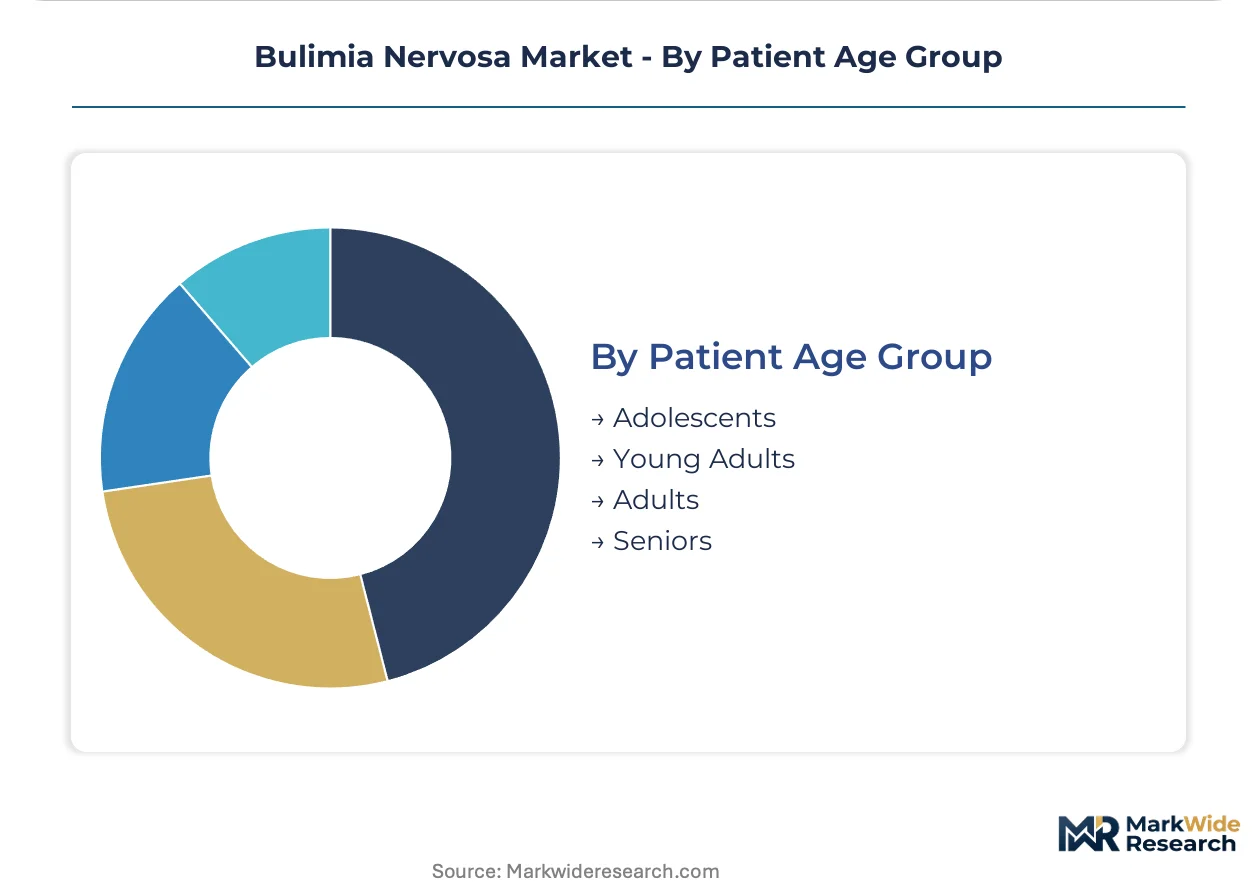
- Adolescents:Patients under 18 requiring guardian consent and family-based treatment integration. University counseling centers and pediatric academic medical centers concentrate specialized programming. FDA labeling for pharmacotherapies carries specific pediatric considerations.
- Young Adults:Transition-age population 18-25 with elevated prevalence and distinct developmental challenges. College health systems and young adult specialized residential programs capture volume. This segment demonstrates highest digital therapeutic adoption rates.
- Adults:Established career and family responsibilities complicating treatment engagement and insurance navigation.
- Seniors:Late-onset presentations with distinct medical comorbidity profiles and medication interaction concerns.
Adolescents and Young Adults together handle the majority of throughput; Young Adults are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Medicaid expansion and commercial insurance mandates are accelerating treatment infrastructure investment across concentrated metropolitan clusters. Regulatory frameworks governing eating disorder reimbursement vary substantially by national jurisdiction, shaping where specialized capacity accumulates.
United States
Employer-sponsored behavioral health carve-outs are redirecting commercial patient volume toward specialized eating disorder networks. The FDA's psychiatric products division governs new drug approvals for bulimia nervosa indications through accelerated pathways. Bed capacity expansion concentrates in Mountain West and Southeast states where Medicaid waiver programs are expanding behavioral health carve-outs.
Germany
Statutory health insurance reimbursement for cognitive behavioral therapy protocols sustains outpatient clinic density in metropolitan regions. The country's national pharmaceutical regulator maintains stringent evidentiary requirements for CNS product approvals. Specialized eating disorder units cluster in Berlin, Munich, and Hamburg academic medical centers with integrated research programs.
United Kingdom
NHS England's investment in children and young people's eating disorder services is compressing waiting times for evidence-based interventions. NICE guidelines shape prescriber behavior and commissioning decisions across integrated care systems. London and Southeast England concentrate specialist workforce and residential program capacity.
France
Regional health agency funding for university hospital psychiatry departments is expanding dedicated eating disorder consultation-liaison services. ANSM oversight of central nervous system therapies maintains high evidentiary thresholds for market authorization. Paris and Lyon academic centers anchor clinical research infrastructure for transdiagnostic protocol development.
Canada
Provincial health authority contracts with accredited residential operators are standardizing outcome measurement requirements. Health Canada reviews central nervous system products through its therapeutic products directorate. Ontario and British Columbia concentrate specialized adolescent programming with embedded family-based treatment components.
Bulimia Nervosa Market Vendor Landscape
Player mix skews toward diversified pharmaceutical conglomerates with established psychiatric divisions. Market structure reflects consolidation around CNS therapeutic expertise rather than eating disorder-specific specialization. Three archetypes dominate: large-cap developers with antidepressant infrastructure, mid-tier neurology-focused firms, and biotechs pursuing novel mechanisms. Competitive moves concentrate on portfolio diversification through indication expansion and strategic partnerships with digital therapeutic platforms.
Within the large-cap pharmaceutical tier, Pfizer Inc., Eli Lilly and Company, and GlaxoSmithKline plc occupy positions defined by psychiatric research infrastructure and established prescriber relationships. Pfizer anchors its presence through broad CNS therapeutic expertise spanning multiple psychiatric indications. Eli Lilly leverages antidepressant development capabilities sustained through dedicated psychiatric research divisions. GlaxoSmithKline differentiates via integrated neurology and mental health portfolios with established European and North American commercial footprints.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Eli Lilly and Company |
| Johnson & Johnson Services, Inc. |
| GlaxoSmithKline plc |
| AstraZeneca plc |
| Bristol-Myers Squibb Company |
| Allergan, Inc. |
| Merck & Co., Inc. |
| Novartis AG |
| Others |
Supply Flow & Price Mechanics
Digital therapeutic platforms replacing traditional face-to-face CBT delivery are simultaneously redrawing supply geography toward software development clusters and compressing pricing premiums for conventional outpatient services. This substitution dynamic concentrates value capture with FDA-cleared digital health vendors while eroding margins for legacy clinic-based providers dependent on hourly billing models.
Pricing Analysis
Certification level creates the primary spread across intervention tiers, with APA-accredited specialist programs commanding substantial premiums over non-credentialed alternatives. Three-tier pricing structure across premium, standard, and economy levels segments by clinician certification depth, outcome measurement rigor, and care setting intensity. Cost compression in standard-tier outpatient services is intensifying because stepped-care models and digital alternatives expand lower-cost substitutes. Employer-sponsored carve-outs demonstrate lowest price sensitivity due to direct contracting arrangements, while Medicaid-dependent populations face highest sensitivity to prior authorization friction and tiered formulary restrictions.
Supply Chain Analysis
The United States and Germany anchor specialized eating disorder treatment infrastructure through distinct regulatory and reimbursement frameworks. Clinical workforce supply draws from APA-accredited fellowship programs concentrated in coastal metropolitan academic centers, while digital therapeutic development feeds from FDA pre-certification pilot participants and venture-backed behavioral health platforms. Single-source vulnerability sits with board-certified eating disorder psychiatrists, whose geographic maldistribution limits program expansion in interior states. Distribution runs through employer-sponsored behavioral health carve-outs, direct-to-residential contracts with self-insured plans, and traditional managed care networks with narrowing prior authorization windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where FDA breakthrough device pathways and APA accreditation standards create substantial compliance barriers that protect established players from rapid competitive displacement.
For Market Incumbents: Secure APA accreditation expansion in Mountain West and Southeast states before Medicaid waiver programs mature, as geographic first-mover advantage in underpenetrated markets compounds through referral network effects. Deepen vertical integration into digital therapeutic platforms to capture software-based intervention growth and defend against pure-play digital health entrants displacing traditional outpatient volume. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks offer the most penetrable regulatory pathway for software-based CBT protocols targeting young adult populations with highest digital adoption rates. Target adolescent residential capacity expansion in Tennessee, Arizona, and Utah where Medicaid behavioral health carve-outs are expanding and specialist supply scarcity creates immediate bed demand. Go-to-market execution should prioritize direct employer contracting channels that bypass traditional managed care intermediaries and enable outcome-based pricing. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors platforms combining accredited clinical infrastructure with digital therapeutic capabilities. Long-term viability over the next decade hinges on capturing integrated care models that span outpatient, residential, and virtual delivery. Acquisition target archetype: regional eating disorder networks with APA-accredited training programs and established payer relationships. The signal to watch is FDA digital therapeutic approval velocity, which would validate software-based intervention economics and trigger strategic repricing of platform-enabled providers.| Strategic Initiative | Industry Significance |
|---|---|
| APA Accreditation Expansion | Credentialing investment in Mountain West and Southeast states captures Medicaid waiver program growth before competitor entry. |
| Digital Therapeutic FDA Submission | Breakthrough device pathway for CBT platforms opens reimbursement parity with traditional services and scales beyond clinician supply constraints. |
| Direct Employer Contracting | Self-insured plan carve-outs bypass managed care intermediaries and concentrate volume with outcome-reporting accredited providers. |
| Transdiagnostic Protocol Development | Unified treatment approaches across bulimia nervosa, binge eating disorder, and ARFID streamline training and expand addressable patient populations. |
| Measurement-Based Care Integration | EHR-embedded symptom tracking enables value-based contracting with commercial payers and supports risk-sharing arrangements. |
Methodological Framework
A spread of perspectives from eating disorder psychiatrists, residential program operators, digital therapeutic developers, commercial payer formulary directors, and employer benefits consultants converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with clinical leadership at APA-accredited programs and regulatory affairs specialists at FDA-cleared digital health platforms. Secondary validation drew from FDA 510(k) and breakthrough device filings, ClinicalTrials.gov eating disorder study registries, state Medicaid waiver program documentation, and employer-sponsored health plan carve-out contract disclosures. Bottom-up patient volume estimates by care setting and geography were triangulated against top-down pharmaceutical prescription data and residential bed capacity surveys.
Segmentation dimensions modeled include therapy type, medication class, care setting intensity, patient age group, and regional regulatory cluster across the analysis window. CAGRs were derived from trend extrapolation of historical admission patterns, pharmaceutical prescription growth, and digital therapeutic adoption curves. Forecast inputs incorporated FDA review timeline assumptions for CNS products, state-level telehealth parity legislation trajectories, and Medicaid behavioral health expenditure projections from federal and state budget documents.
Decision-makers should treat outputs as directional under assumptions of stable FDA regulatory frameworks and continued employer-sponsored behavioral health investment; material deviation in digital therapeutic reimbursement policy or Medicaid funding would warrant model refresh. Recalibration cycles align with material shifts in FDA digital health guidance, state telehealth parity legislation, and employer plan design changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Liver Cirrhosis Treatment Market
Specialty Medicine
Ischemic Hepatitis Treatment Market
Specialty Medicine
Chemotherapy Induced Peripheral Neuropathy Treatment Market
Specialty Medicine
Prostate Cancer Therapeutics Market
Specialty Medicine
Treatment-Resistance Depression Treatment Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Moderate-To-Severe Acne Therapeutics Market
Specialty Medicine
Central Nervous System (CNS) Biomarkers Market
Specialty Medicine
Behcet's Syndrome Market
Specialty Medicine
Global Chronic Idiopathic Constipation Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Treatment Market
Specialty Medicine
Schizophrenia Treatment Market
Specialty Medicine
Osteogenesis Imperfecta Treatment Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Tardive Dyskinesia (TD) Treatment Market