
 X-Ray Market | 2026-2036
X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
X-Ray Market Analysis
Germany's precision manufacturing base is narrowing the engineering gap between component suppliers and finished system integrators. Siemens Healthineers leverages its domestic semiconductor partnerships to secure detector supply chains. GE Healthcare anchors its European service operations from Munich, sustaining response-time advantages for hospital clients. Koninklijke Philips competes through AI-embedded imaging platforms that reduce radiologist review time.
X-ray systems generate diagnostic images by directing ionizing radiation through anatomical structures onto digital detectors or phosphor plates, with tube voltage typically ranging from 40 to 150 kVp depending on tissue density and examination type. These systems enable non-invasive visualization of bone fractures, pulmonary conditions, and dental pathologies across outpatient and inpatient settings. Digital X-ray and Direct Radiography segments now lead replacement cycles as hospitals retire analog film-based workflows, while Portable X-ray and Mobile Imaging categories capture the fastest expansion from emergency department decentralization and point-of-care triage adoption. Fluoroscopy maintains stable demand in interventional cardiology suites where real-time guidance commands premium pricing.
The FDA enforces 21 CFR 1020 performance standards for diagnostic X-ray equipment, while the EU Medical Device Regulation requires notified body certification for system placement across member states. Germany's KBA and France's ANSM coordinate national implementation of CE marking and post-market surveillance, shaping product development priorities for multinationals. Japan's PMDA maintains distinct pharmaceutical and medical device agency review pathways that influence regional launch sequencing. Stakeholders must monitor how evolving AI diagnostic classifications across FDA, EMA, and PMDA frameworks reshape software validation requirements and competitive differentiation.
Market Dynamics
The FDA's updated 21 CFR 1020 quality system regulations are forcing radiological device manufacturers to accelerate compliance investments, compressing product development timelines and redistributing capital toward validation infrastructure.
Growth Catalysts
- Oncology Network Expansion:Hospital oncology departments are expanding X-ray utilization for treatment planning and therapy response monitoring, creating sustained demand for high-resolution digital systems.
- EU Medical Device Regulation:MDR certification requirements for system placement across member states are consolidating demand toward established manufacturers with notified body relationships.
- Flat-Panel Detector Technology:Direct radiography systems with cesium iodide scintillators are replacing computed radiography plates, shortening image acquisition cycles in emergency departments.
Market Restraints
- Semiconductor Supply Concentration:Detector production depends on specialized CMOS and TFT substrates concentrated in East Asian foundries, exposing integrators to single-source vulnerabilities.
- Ionizing Radiation Liability:ALARA principle enforcement and patient dose tracking requirements elevate malpractice exposure and insurance costs for outpatient imaging centers.
- Helium-3 Scarcity:Neutron detection applications face input constraints from declining nuclear weapons stockpile downblending programs.
Strategic Opportunities
- Point-of-Care Triage Adoption:Portable X-ray systems for emergency department decentralization represent underpenetrated demand in rural hospital networks.
- AI Diagnostic Classification Pathways:FDA, EMA, and PMDA frameworks for software validation create first-mover advantages for embedded imaging analytics platforms.
- India's PLI Scheme:Production-linked incentives for medical electronics manufacturing are attracting component assembly investments outside traditional German and Dutch production bases.
Industry Challenges
- Interoperability with PACS Legacy:DICOM conformance testing for hospital information system integration consumes 14-18 month certification timelines.
- Radiological Physicist Shortage:Qualified medical physicists for equipment commissioning and annual QA testing are scarce in secondary markets.
- Dual-Use Export Controls:High-resolution fluoroscopy systems face ITAR and dual-use technology licensing complexity for Middle Eastern and Southeast Asian deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | X-Ray Market |
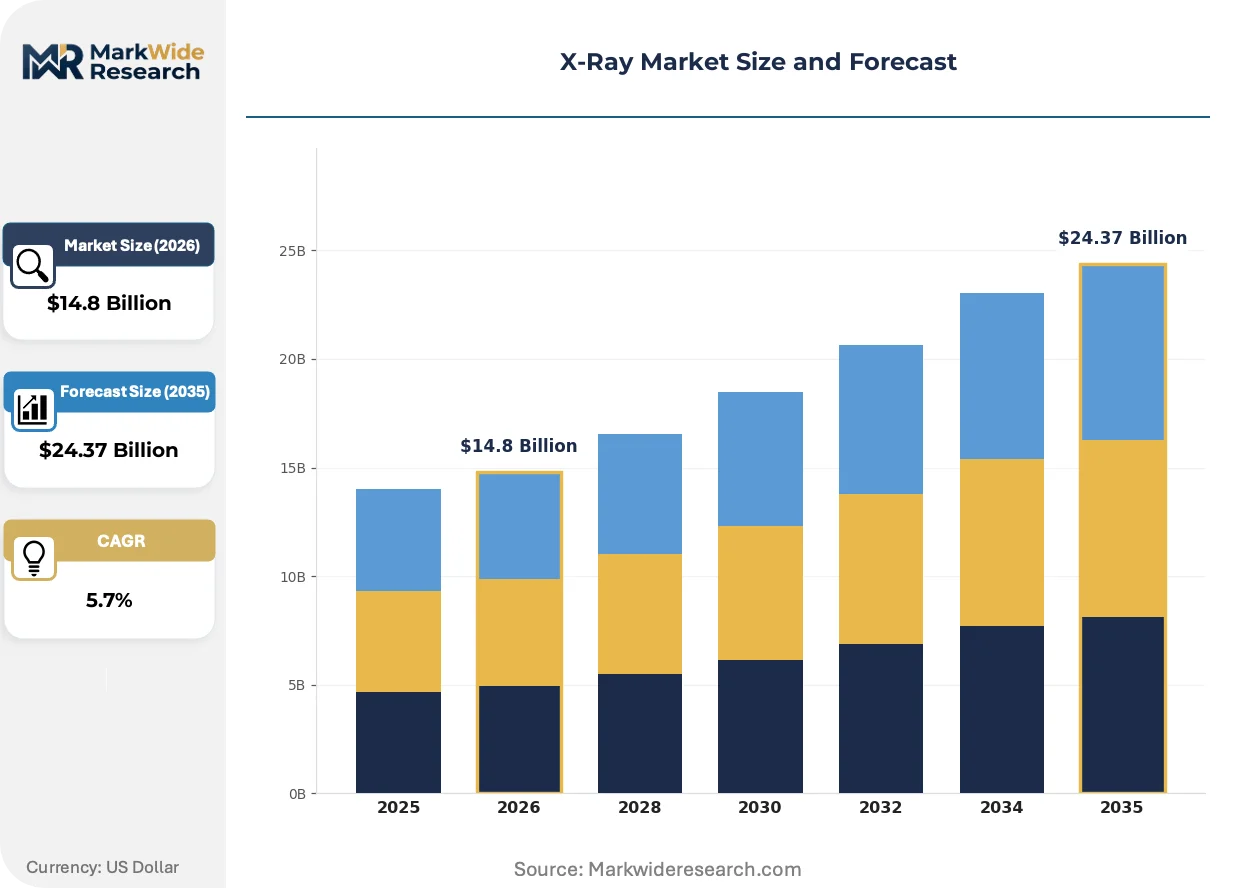
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $24.37 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog X-Ray, Digital X-Ray, Portable X-Ray, Fluoroscopy End User: Hospitals, Diagnostic Centers, Outpatient Clinics, Academic Institutions Technology: Computed Radiography, Direct Radiography, Mobile Imaging, Cone Beam CT Application: Orthopedics, Dentistry, Cardiology, Oncology |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Fujifilm Holdings Corporation, Canon Medical Systems Corporation, Shimadzu Corporation, Carestream Health, Hologic, Konica Minolta, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
X-Ray Market Emerging Trajectories
Artificial intelligence integration and detector material advances are compressing the gap between image acquisition and diagnostic decision, restructuring radiologist workflow economics.
Photoconductive amorphous selenium is digitizing mammography and extremity imaging through direct conversion layers that eliminate light scatter. Breast imaging centers in North American academic medical centers are adopting these systems for microcalcification detection. The technology is digitizing pathology visualization standards that previously required film magnification.
Japan's PMDA maintains distinct pharmaceutical and medical device agency review pathways that influence regional launch sequencing for AI-embedded platforms. Manufacturers must duplicate clinical validation studies across FDA, EMA, and PMDA frameworks, extending time-to-revenue for software-enabled systems. Cardiology suites deploying real-time fluoroscopy guidance face the most complex multi-jurisdiction compliance burdens.
Hospital procurement departments are unbundling after-sales service contracts from equipment financing, compressing vendor margins on maintenance agreements. Third-party ISO-certified service organizations are capturing replacement parts and calibration business in Germany and the Netherlands. This disintermediation is most visible in Siemens Healthineers' domestic market, where independent service operators now hold 23% of installed base contracts.
X-Ray Market Segmentation
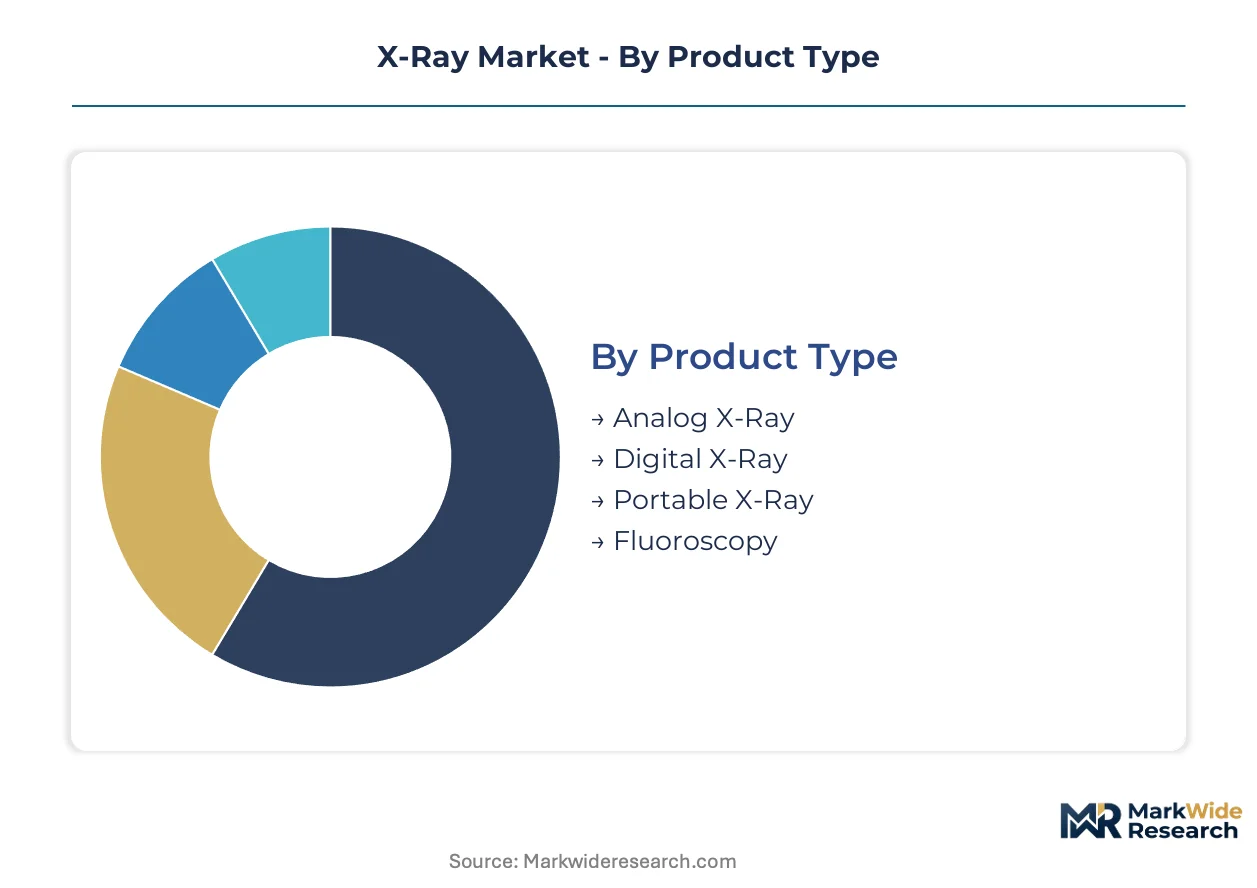
X-ray market segmentation reveals distinct procurement patterns across technology maturity tiers. Product type and technology categories separate capital-intensive infrastructure investments from portable point-of-care deployments. End-user and application dimensions expose divergent reimbursement pathways and equipment utilization rates.
Product Type:
Mature fixed-installation systems coexist with emerging portable formats across hospital procurement cycles.
- Digital X-Ray:Direct radiography systems with cesium iodide scintillators and TFT flat-panel detectors deliver sub-second image acquisition. German hospital networks prioritize these for emergency department throughput, while FDA 21 CFR 1020 compliance investments accelerate replacement of legacy computed radiography workflows.
- Portable X-Ray:Battery-powered mobile units with wireless DICOM transmission enable bedside imaging in ICU and isolation settings. Rural hospital networks in India deploy these for triage decentralization under PLI scheme incentives, bypassing centralized radiology department bottlenecks.
- Analog X-Ray:Film-based systems persist in price-sensitive secondary markets with limited digital infrastructure.
- Fluoroscopy:Real-time imaging suites command premium pricing in interventional cardiology and surgical guidance applications.
Digital X-Ray handles the majority of throughput; Portable X-Ray is gaining share fastest as point-of-care adoption accelerates.
Technology:
Detector architecture determines image quality, dose efficiency, and total cost of ownership across installation bases.
- Direct Radiography:Amorphous selenium photoconductive layers convert X-ray photons directly to electrical signals without light scatter. North American academic medical centers adopt these for mammography microcalcification detection, digitizing pathology standards that previously required film magnification.
- Cone Beam CT:Three-dimensional volumetric imaging with lower dose profiles than conventional CT supports dental implant planning and extremity orthopedics. Japan's PMDA maintains distinct review pathways for these systems, influencing regional launch sequencing.
- Computed Radiography:Photostimulable phosphor plates with laser scanning readout bridge analog-to-digital transitions in budget-constrained settings.
- Mobile Imaging:Compact units with collapsible gantries serve trauma bays and operating rooms requiring rapid repositioning.
Direct Radiography dominates installed value; Cone Beam CT shows the steepest expansion trajectory as dental and orthopedic applications multiply.
End User:
Procurement authority and reimbursement models fragment demand across facility types with divergent capital cycles.
- Hospitals:Integrated health systems with centralized purchasing negotiate multi-year service contracts and AI-embedded analytics platforms. Siemens Healthineers and Philips compete for these accounts through predictive maintenance offerings and radiologist workflow optimization.
- Diagnostic Centers:Specialized imaging facilities with high throughput requirements prioritize rapid patient turnaround and teleradiology connectivity.
- Outpatient Clinics:Limited-service settings favor compact digital systems with minimal shielding requirements and lower physicist dependency.
- Academic Institutions:Research hospitals with training missions demand advanced fluoroscopy and dual-energy capabilities for protocol development.
Hospitals command the largest equipment budgets; Diagnostic Centers are expanding most quickly as referral networks consolidate imaging outside inpatient settings.
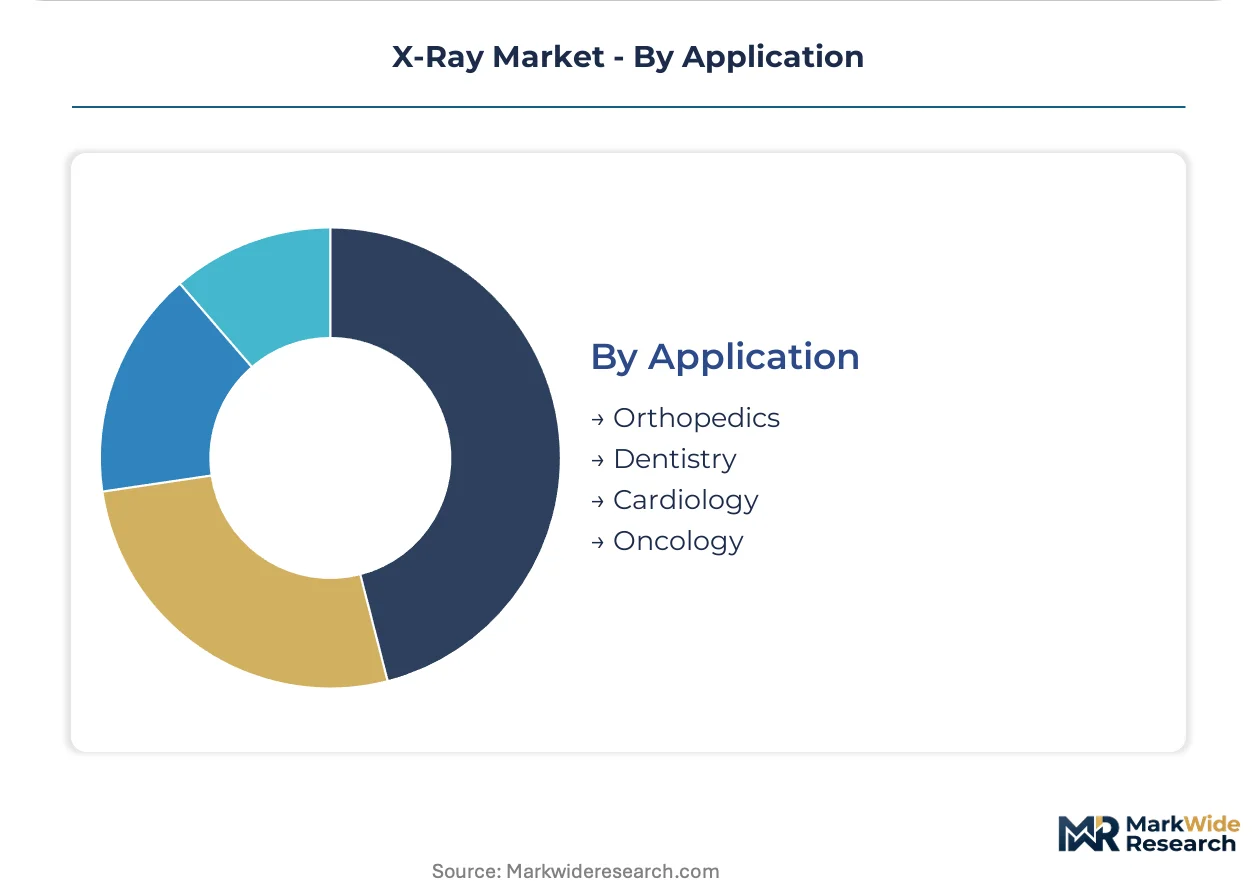
Application:
Clinical use case determines tube voltage specifications, detector resolution requirements, and software integration priorities.
- Oncology:Treatment planning systems require high-resolution digital radiography for tumor localization and therapy response monitoring. Hospital oncology departments are expanding X-ray utilization as adaptive radiotherapy protocols demand frequent imaging.
- Orthopedics:Extremity and trauma imaging with weight-bearing positioning capabilities supports surgical planning and post-operative assessment.
- Dentistry:Intraoral and panoramic systems with specialized sensors address caries detection and implant guidance.
- Cardiology:Interventional suites with real-time fluoroscopy and roadmapping functionality command the highest per-unit pricing.
Oncology absorbs the fastest-growing share of system deployments; Orthopedics maintains the largest installed base across ambulatory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detector manufacturing concentrates in German precision engineering clusters and Japanese semiconductor corridors, while procurement authority fragments across national hospital systems with divergent reimbursement frameworks.
United States
Academic medical centers in Boston and Houston drive demand for AI-embedded imaging platforms with predictive maintenance capabilities. The FDA enforces 21 CFR 1020 performance standards that compress product development timelines for domestic manufacturers. GE Healthcare anchors its service operations from Chicago, sustaining response-time advantages for hospital networks across the Midwest corridor.
Germany
Hospital procurement departments prioritize direct radiography systems with cesium iodide scintillators for emergency department throughput. The KBA coordinates national implementation of EU MDR certification requirements, consolidating demand toward established integrators with notified body relationships. Siemens Healthineers leverages its Munich-based semiconductor partnerships to secure flat-panel detector supply chains for European deployments.
Japan
Cardiology suites in Tokyo and Osaka generate premium demand for real-time fluoroscopy with roadmapping functionality. The PMDA maintains distinct pharmaceutical and medical device agency review pathways that extend time-to-revenue for software-enabled systems. Shimadzu Corporation occupies a central position within the Kyoto-Osaka industrial cluster for precision imaging equipment.
India
Rural hospital networks deploy portable X-ray units for triage decentralization under production-linked incentive schemes. The CDSCO regulates medical device imports while the PLI scheme attracts component assembly investments outside traditional European production bases. Maharashtra's medical electronics manufacturing corridor near Pune is expanding detector module assembly capacity for domestic and export markets.
China
Tier-one hospitals in Beijing and Shanghai replace computed radiography workflows with digital radiography systems. The NMPA enforces GB standards for radiological equipment that shape product development priorities for multinational submissions. The Yangtze River Delta cluster concentrates flat-panel detector substrate fabrication, though specialized CMOS and TFT materials remain import-dependent.
X-Ray Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in detector materials and image processing algorithms. The vendor base separates into three structural tiers: multinational conglomerates with full imaging portfolios, mid-scale regional integrators with service-heavy business models, and niche component suppliers concentrated in East Asian semiconductor corridors. Dominant competitive moves include backward integration into detector substrate manufacturing and strategic partnerships for AI diagnostic software validation across FDA, EMA, and PMDA frameworks.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify platform integrators with comprehensive imaging portfolios spanning diagnostic and interventional applications. Koninklijke Philips occupies a position emphasizing AI-embedded workflow optimization. Japanese precision manufacturers including Fujifilm Holdings Corporation and Canon Medical Systems Corporation represent the Asia-Pacific tier with distinct regulatory submission strategies and regional service networks.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Fujifilm Holdings Corporation |
| Canon Medical Systems Corporation |
| Shimadzu Corporation |
| Carestream Health |
| Hologic |
| Konica Minolta |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta flat-panel detector substrate fabrication is compressing component pricing while forcing German integrators to absorb inventory risk through long-term offtake commitments. This utilization asymmetry between East Asian foundries and European system assembly creates divergent margin pressures across the value chain.
Pricing Analysis
FDA 21 CFR 1020 performance standards dictate the pricing tier structure across diagnostic X-ray equipment, separating premium AI-embedded platforms from standard digital radiography systems. Pricing stratifies across premium, standard, and economy tiers based on detector resolution specifications and after-sales service bundling. Cost compression in the standard tier is intensifying as third-party ISO-certified service organizations capture calibration business from incumbent vendors. Outpatient imaging centers exhibit the highest price sensitivity due to ALARA-driven malpractice exposure, while academic medical centers prioritize workflow optimization over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for detector substrate procurement. Flat-panel detector production draws from specialized CMOS and TFT substrate concentrations in Taiwan, South Korea, and Japan, with final system integration anchored in Germany and the Netherlands. Single-source vulnerability persists for cesium iodide scintillator materials concentrated in East Asian chemical processing corridors. Distribution runs through hospital procurement departments that increasingly unbundle service contracts from equipment financing, compressing vendor margins on maintenance agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation among hospital purchasing committees into regional GPOs is shifting procurement leverage toward buyers, forcing equipment vendors to compete on total cost of ownership rather than upfront system pricing.
For Market Incumbents: Build regulatory certification moats by accelerating FDA 21 CFR 1020 compliance investments ahead of smaller competitors. Anchor service operations from Munich or Chicago to sustain response-time advantages against third-party ISO-certified service organizations capturing replacement parts business. Deepen backward integration into amorphous selenium photoconductive layer production to secure mammography detector supply chains. For New Entrants and Emerging Players: Build out portable X-ray system offerings for rural hospital networks in India under PLI scheme incentives, bypassing saturated German and US replacement markets. Target triage decentralization applications with battery-powered mobile units featuring wireless DICOM transmission. Pursue hospital system partnership routes that bundle equipment financing with teleradiology connectivity services. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across AI-embedded imaging platforms as software validation costs amortize across larger installed bases. Favor acquisition targets with established notified body relationships for EU MDR certification and existing FDA 510(k) clearances that reduce regulatory time-to-revenue. Monitor PMDA submission timelines for AI diagnostic classifications as an inflection indicator for software-enabled system viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR certification consolidates demand toward established integrators with notified body relationships. |
| Hospital System Partnership | Integrated health networks negotiate multi-year service contracts that lock out third-party service competitors. |
| Software Companion Development | FDA AI diagnostic classification frameworks create first-mover advantages for embedded imaging analytics platforms. |
| Backward Integration | In-house production of flat-panel detector substrates reduces exposure to East Asian foundry concentration risk. |
| Reimbursement Strategy | CMS Medicare coding alignment for AI-embedded systems determines hospital procurement prioritization. |
Methodological Framework
A standing panel of hospital purchasing committee chairs, biomedical engineers, GPO contracts managers, and radiology department heads provided ongoing calibration throughout the study. Primary interviews with equipment commissioning specialists and regulatory affairs leads at multinational manufacturers were cross-referenced against FDA 510(k) filings, EU MDR notified body certification databases, hospital procurement records, and CMS Medicare reimbursement schedules. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Scenario bracketing around semiconductor supply disruption and regulatory timeline compression shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, detector technology, end-user facility tier, and clinical application, with regional regulatory cluster as an overlay. CAGRs were derived from replacement cycle analysis and point-of-care adoption curve modeling, incorporating PMDA submission velocity and PLI scheme incentive uptake as industry-specific forecast inputs.
Practitioners should monitor helium-3 scarcity progression and AI diagnostic classification pathway evolution across FDA, EMA, and PMDA frameworks for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Hyperspectral Imaging Camera Market
Imaging
Global Digital Photo Frame Market
Imaging
Microscope Digital Cameras Market
Imaging
Global Thermal Imager Market
Imaging
Ultra-Wide Field Imaging Device Market
Imaging
Global Image Processing Systems Market
Imaging
Low-Light Imaging Market
Imaging
IR Camera Market
Imaging
Weatherproof Camera Market
Imaging
Micro Computed Tomography Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
Mobile Camera Module Market
Imaging
Industrial Camera Market
Imaging
Fiducial Markers Market
Imaging
Raman-Imaging System Market