
 IoT Data Management Market | 2026-2036
IoT Data Management Market Size, Share, and Industry Trends Forecast 2026-2036
IoT Data Management Market Intelligence
ISO/IEC 27001 certification cycles for information security management systems is unwinding competitive access across the IoT data management landscape, forcing vendors to demonstrate audited governance before procurement committees release budget. IBM leverages its hybrid cloud architecture to anchor enterprise deployments requiring federated data lakes across regulated environments. Siemens dominates industrial edge scenarios with hardware-software integration that sustains real-time analytics inside factory perimeters.
IoT data management encompasses the ingestion, storage, processing, and governance of telemetry streams generated by connected sensor networks, typically operating at latencies below 50 milliseconds for time-critical industrial control loops while archiving petabyte-scale histories for longitudinal pattern detection. Cloud-based deployment leads in new contract value as enterprises exit capital-intensive on-premises data center commitments, though edge computing represents the fastest structural expansion as latency-sensitive manufacturing and autonomous transportation workloads reject round-trip cloud dependencies. Machine learning within the technology stack captures disproportionate R&D investment as predictive maintenance applications demand continuously refined anomaly detection models trained on operational rather than historical data.
FDA cybersecurity guidance for connected medical devices and the EU AI Act's risk classification framework for automated decision systems are tightening compliance burdens on healthcare and smart city deployments, elevating vendor liability and insurance costs. HIPAA business associate agreements in the United States and GDPR Article 32 technical measures in Europe now require demonstrable encryption, access logging, and breach notification capabilities as contractual preconditions. Stakeholders must monitor how emerging sector-specific data residency mandates fragment cloud architecture strategies and force regional infrastructure replication.
Market Dynamics
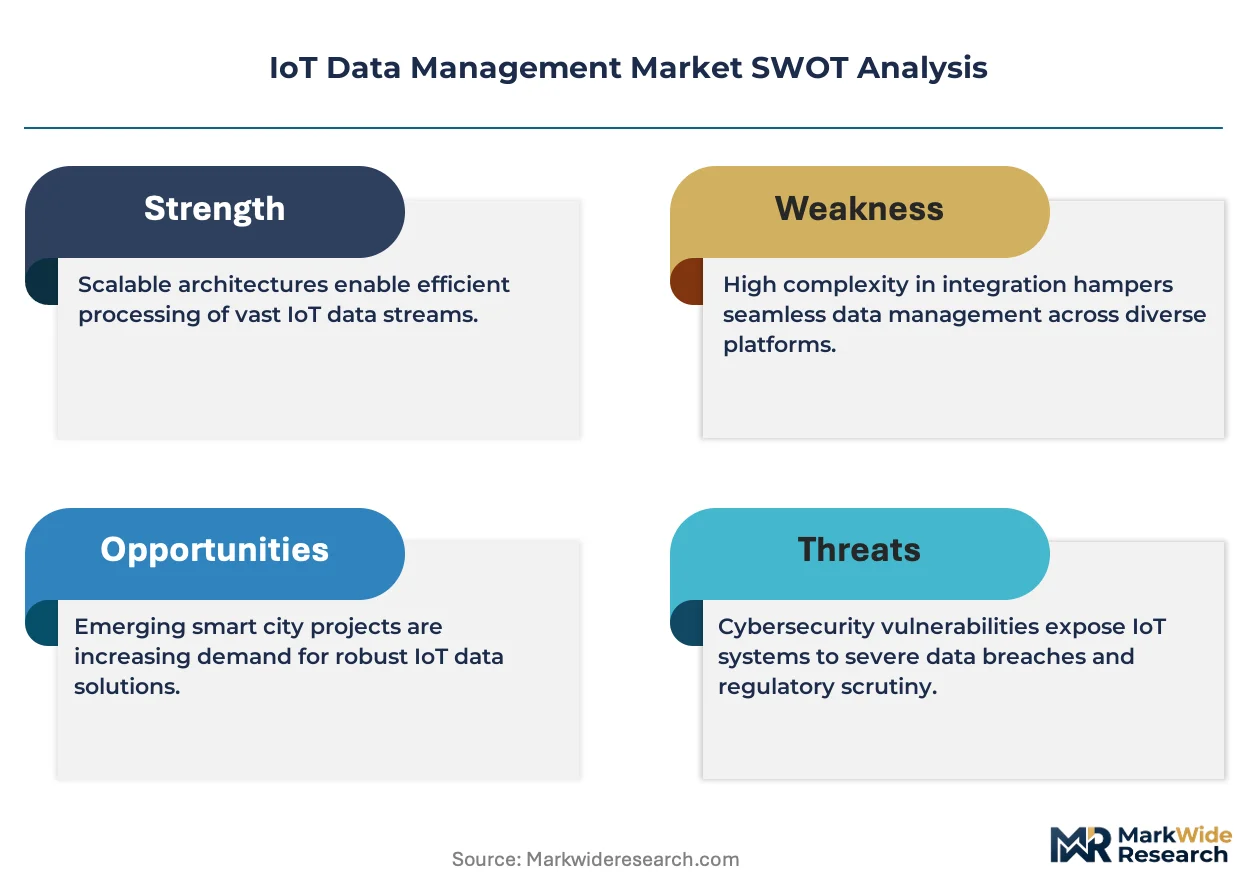
Edge-native data pipelines are displacing cloud-first architectures in manufacturing control systems, forcing vendors to re-engineer latency guarantees below 10 milliseconds while maintaining centralized governance visibility.
Growth Catalysts
- GDPR Article 32 technical measures:European healthcare providers are accelerating encrypted telemetry deployments to satisfy contractual encryption and breach notification preconditions for connected medical devices.
- Predictive maintenance analytics:Automotive assembly plants in Germany are consolidating sensor-to-cloud pipelines to optimize asset uptime through continuously refined anomaly detection models.
- ISO/IEC 27001 certification cycles:Audited governance requirements are unlocking procurement committee budgets for vendors demonstrating certified information security management systems.
Market Restraints
- EU AI Act risk classification framework:Automated decision systems in smart city deployments face elevated vendor liability and insurance costs from tightened compliance burdens on high-risk AI applications.
- Specialized edge hardware supply concentration:Industrial gateway manufacturing clusters in Taiwan create single-source vulnerability for latency-sensitive factory perimeter deployments.
- Petabyte-scale archival storage economics:Longitudinal pattern detection requirements strain capital efficiency as enterprises exit on-premises data center commitments.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Incentivized domestic production of industrial IoT gateways creates localized data lake infrastructure for machinery operations serving South Asian markets.
- Federated learning architectures:Convergence of differential privacy with distributed model training enables cross-facility analytics without raw data centralization in regulated environments.
- Outcome-based performance contracts:Power generation utilities are unbundling traditional software licensing in favor of uptime-guaranteed service agreements tied to turbine sensor analytics.
Industry Challenges
- Embedded systems security engineering talent scarcity:Firmware-level encryption implementation for FDA-guided connected medical devices outpaces qualified practitioner supply in North American labor markets.
- Legacy SCADA integration complexity:Brownfield manufacturing sites require protocol translation layers that introduce latency penalties incompatible with sub-50-millisecond control loop requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IoT Data Management Market |
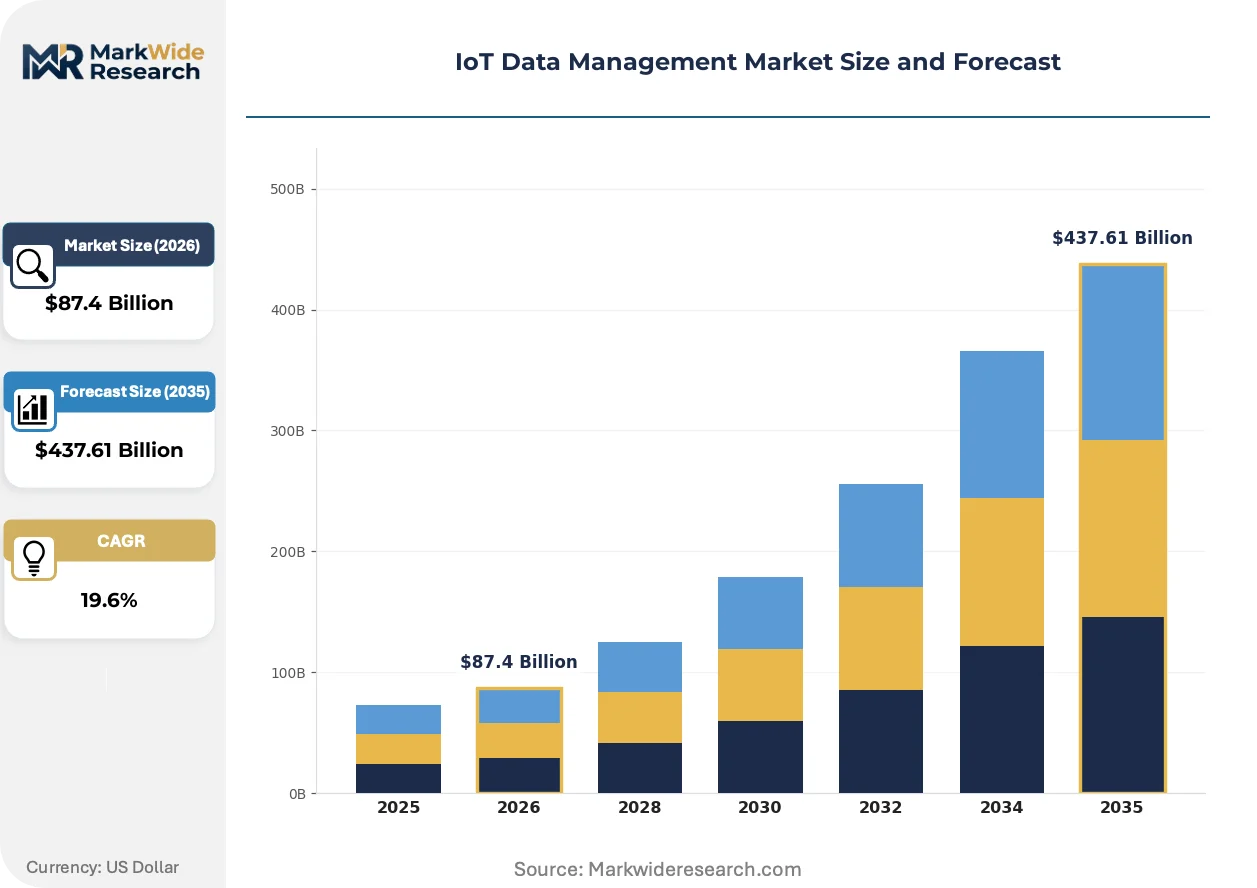
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $437.61 Billion |
| CAGR (2026 – 2036) | 19.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-premises, Cloud-based, Hybrid, Edge Computing Technology: Data Analytics, Machine Learning, Artificial Intelligence, Data Integration End User: Healthcare, Manufacturing, Transportation, Smart Cities Application: Predictive Maintenance, Supply Chain Management, Environmental Monitoring, Asset Tracking |
| Companies Covered | Siemens, AVEVA, Informatica, Tata Consultancy Services, EPAM Systems, IBM, PTC, Accenture, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IoT Data Management Market Strategic Shifts & Innovations
Time-series database engines optimized for high-cardinality telemetry streams are compressing storage economics while enabling real-time anomaly detection at factory edge nodes.
Vector-native data structures are displacing row-oriented archival formats in industrial IoT deployments. German automotive conglomerates are migrating petabyte-scale operational histories to columnar engines supporting sub-second pattern queries. This architectural shift is displacing traditional data lakehouse vendors unable to demonstrate millisecond-range query performance on billion-row sensor tables.
The EU AI Act's risk classification framework for automated decision systems is elevating documentation burdens for smart city traffic management deployments. Municipal procurement committees now require algorithmic impact assessments as technical preconditions. French and Dutch infrastructure operators are responding by segmenting AI-driven control systems into human-in-the-loop configurations that reduce regulatory exposure.
Consolidated buying by industrial conglomerates is compressing vendor evaluation cycles for IoT data management platforms. German machinery and automotive groups are centralizing sensor-to-cloud procurement through shared service organizations. This concentration is most visible in Bavaria and Baden-Württemberg, where supplier qualification now requires simultaneous demonstration of ISO/IEC 27001 certification and edge-native deployment capabilities.
IoT Data Management Market Segmentation
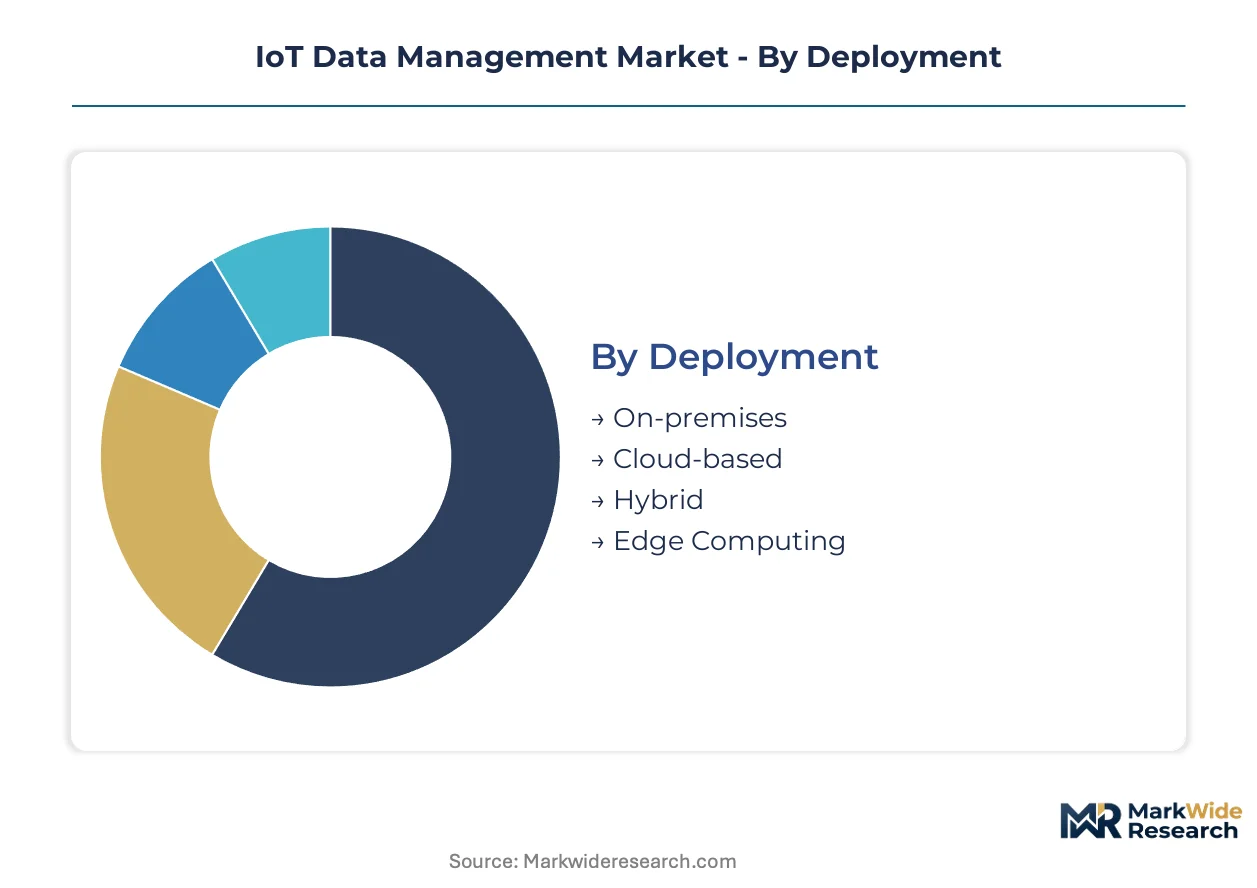
IoT data management architectures fragment across deployment topologies, processing technologies, and operational use cases. Procurement committees evaluate segments against latency requirements, data sovereignty constraints, and integration complexity with brownfield industrial systems.
Deployment:
Edge computing and cloud-based architectures exert the strongest substitution pressure on legacy on-premises infrastructure as enterprises exit capital-intensive data center commitments.
- Cloud-based:Federated data lakes anchor enterprise deployments across regulated environments, with German automotive conglomerates consolidating sensor-to-cloud pipelines to optimize asset uptime. Procurement committees release budget contingent upon ISO/IEC 27001 certification and demonstrable encryption capabilities under GDPR Article 32.
- Edge Computing:Sub-10 millisecond latency guarantees displace cloud-first architectures in manufacturing control systems, sustaining real-time analytics inside factory perimeters. Siemens dominates industrial edge scenarios through hardware-software integration at German machinery operations in Bavaria and Baden-Württemberg.
- Hybrid:Federated governance visibility spans centralized archives and distributed processing nodes for cross-border data flows under tightening EU data sovereignty rules.
- On-premises:Petabyte-scale archival storage economics strain capital efficiency as longitudinal pattern detection requirements persist in legacy healthcare and utility installations.
Cloud-based deployment retains volume leadership; edge computing holds the steepest expansion curve.
Technology:
Cost tier stratification separates capital-intensive AI infrastructure from lightweight integration tooling, with mid-market adopters prioritizing analytics platforms over full-stack machine learning deployments.
- Machine Learning:Continuously refined anomaly detection models trained on operational rather than historical data capture disproportionate R&D investment. German automotive assembly plants deploy predictive maintenance analytics requiring sub-50 millisecond inference at the edge.
- Data Analytics:Time-series database engines optimized for high-cardinality telemetry streams compress storage economics while enabling real-time pattern detection. Columnar engines displace row-oriented formats in petabyte-scale operational history migrations.
- Artificial Intelligence:EU AI Act risk classification elevates documentation burdens for automated decision systems in smart city traffic management, forcing human-in-the-loop configurations.
- Data Integration:Protocol translation layers for legacy SCADA integration introduce latency penalties incompatible with industrial control loop requirements.
Data analytics retains volume leadership; machine learning climbs the fastest.
End User:
Application maturity varies sharply by sector, with manufacturing and healthcare presenting divergent compliance architectures and procurement timelines.
- Manufacturing:Sensor-to-cloud pipeline consolidation accelerates across German industrial conglomerates, with ISO/IEC 27001 certification and edge-native capabilities now mandatory for supplier qualification.
- Healthcare:FDA cybersecurity guidance for connected medical devices and HIPAA business associate agreements mandate firmware-level encryption, access logging, and breach notification capabilities.
- Smart Cities:Municipal procurement committees require algorithmic impact assessments under EU AI Act technical preconditions, segmenting AI-driven control systems into reduced-regulatory-exposure configurations.
- Transportation:Autonomous transportation workloads reject round-trip cloud dependencies, favoring edge-native data pipelines for latency-sensitive perception and control functions.
Manufacturing retains volume leadership; smart cities gain share fastest.
Application:
Customer type stratification separates asset-intensive process industries from transaction-heavy logistics operations, with divergent data retention and real-time processing requirements.
- Predictive Maintenance:Outcome-based performance contracts displace traditional software licensing in power generation utilities, with uptime-guaranteed service agreements tied to turbine sensor analytics.
- Supply Chain Management:Environmental telemetry and location intelligence converge for cold-chain pharmaceutical distribution under FDA track-and-trace requirements.
- Asset Tracking:High-cardinality sensor streams from mobile industrial equipment demand vector-native data structures for sub-second geospatial queries.
- Environmental Monitoring:Regulatory disclosure requirements under CSRD and EU Green Deal frameworks expand continuous emissions monitoring deployments across energy and materials sectors.
Predictive maintenance retains volume leadership; environmental monitoring shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government-backed manufacturing incentives and tightening data sovereignty mandates are redrawing IoT data management deployment patterns across major economies. Procurement committees now release budget contingent upon demonstrated compliance with sector-specific encryption and residency requirements.
Germany
Industrial conglomerates in Bavaria and Baden-Württemberg are consolidating sensor-to-cloud pipelines across automotive and machinery operations. GDPR Article 32 technical measures mandate encrypted telemetry and breach notification capabilities as contractual preconditions for connected medical devices. Siemens anchors industrial edge scenarios through hardware-software integration at factory perimeters in Stuttgart and Munich.
United States
Power generation utilities are unbundling traditional software licensing in favor of uptime-guaranteed service agreements tied to turbine sensor analytics. FDA cybersecurity guidance for connected medical devices elevates firmware-level encryption requirements for healthcare deployments. Greater Boston and Pacific Northwest clusters concentrate predictive maintenance R&D investment for continuously refined anomaly detection models.
India
The PLI scheme for electronics manufacturing incentivizes domestic production of industrial IoT gateways serving South Asian markets. BIS certification requirements and RBI data localization directives constrain cross-border data flows for financial services IoT deployments. Maharashtra and Karnataka host machinery operations migrating to localized data lake infrastructure.
China
Dual carbon goals under MEE supervision expand continuous emissions monitoring deployments across energy and materials sectors. MIIT data security regulations impose technical measures on industrial internet platforms handling operational telemetry. Yangtze River Delta manufacturing clusters are re-engineering latency guarantees below 10 milliseconds for latency-sensitive control systems.
United Kingdom
Healthcare providers under NHS Digital oversight are accelerating encrypted telemetry deployments to satisfy contractual preconditions for connected medical devices. The UK AI Office risk classification framework elevates documentation burdens for automated decision systems in smart city traffic management. London and Southeast procurement committees require algorithmic impact assessments as technical preconditions for municipal infrastructure contracts.
IoT Data Management Market Key Industry Players
Player mix skews toward diversified technology conglomerates with hybrid cloud portfolios and industrial automation specialists with edge-native hardware integration. Market structure concentrates around vendors demonstrating simultaneous ISO/IEC 27001 certification and sub-10 millisecond latency guarantees. Strategic archetypes include federated data lake architects, industrial edge platform builders, and outcome-based service contract providers. Dominant competitive moves encompass strategic partnerships for brownfield SCADA integration and portfolio diversification into predictive maintenance analytics.
Within the industrial automation tier, Siemens and PTC exemplify hardware-software integration specialists sustaining real-time analytics inside factory perimeters. Among diversified technology conglomerates, IBM occupies a position representing federated governance architectures spanning centralized archives and distributed processing nodes. Tata Consultancy Services anchors the IT services archetype, occupying a position within outcome-based performance contracting for utilities and manufacturing clients.
| Leading Market Players |
|---|
| Siemens |
| AVEVA |
| Informatica |
| Tata Consultancy Services |
| EPAM Systems |
| IBM |
| PTC |
| Accenture |
| Microsoft |
| Others |
Cost & Logistics Intelligence
Edge-native data pipelines displacing cloud-first architectures simultaneously reshape supply geography toward Taiwan and South Korea while compressing pricing economics for latency-sensitive hardware bundles. This substitution dynamic concentrates procurement power among German automotive conglomerates consolidating sensor-to-cloud deployments.
Pricing Analysis
Cost-plus contracts indexed to semiconductor wafer pricing dominate industrial IoT gateway procurement. Three-tier pricing structure across premium, standard, and economy levels separates ISO/IEC 27001-certified edge platforms from uncertified alternatives. Price differentiation hinges on certification grade and volume scale, with Bavarian machinery groups commanding steepest discounts. Pricing pressure stems from petabyte-scale archival storage economics as enterprises exit on-premises commitments. Mid-market manufacturing adopters exhibit highest price sensitivity; regulated healthcare providers demonstrate lowest.
Supply Chain Analysis
Taiwan and South Korea anchor industrial gateway semiconductor fabrication and specialized edge hardware production. Supply chains draw from silicon wafers, precision sensors, and firmware components. Single-source vulnerability concentrates in Taiwanese manufacturing clusters for latency-sensitive factory perimeter deployments. Distribution runs through systems integrators and industrial automation distributors serving German machinery operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
IoT data management demand cycles track manufacturing capital expenditure recovery, with German automotive production schedules serving as the lead indicator for enterprise deployment timing.
For Market Incumbents: Compound defensive positioning through backward integration into edge hardware production and captive certification consulting capabilities. Cloud-first vendors face substitution threat from Siemens and PTC hardware-software bundles. ISO/IEC 27001 certification investment represents the critical lever for procurement committee access. For New Entrants and Emerging Players: Anchor in Indian PLI-subsidized electronics manufacturing for localized gateway production serving South Asian machinery markets. Environmental monitoring applications present the most penetrable white-space segment. Outcome-based performance contracting with power generation utilities offers differentiated go-to-market positioning. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors federated data lake architects with demonstrated GDPR compliance capabilities. Long-term viability favors vendors spanning hybrid deployment topologies. Edge-native platform builders with sub-10 millisecond latency guarantees signal inflection toward manufacturing control system replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| ISO/IEC 27001 Certification Investment | Audited governance unlocks procurement budgets at German automotive conglomerates. |
| Edge Hardware Manufacturing Scale-Up | Taiwanese supply concentration creates vulnerability for latency-sensitive deployments. |
| Federated Data Lake Architecture | IBM anchors enterprise deployments across GDPR-regulated cross-border environments. |
| Outcome-Based Performance Contracting | Power utilities unbundle licensing for uptime-guaranteed turbine analytics agreements. |
| Predictive Maintenance Platform Integration | German assembly plants consolidate sensor-to-cloud pipelines for anomaly detection. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, IT procurement officers, platform engineers, and industrial automation distributors. Secondary validation incorporated SEC filings, hyperscaler capex disclosures, customs and trade data, and EU regulatory filings. Bottom-up deployment sizing triangulated against top-down market aggregation across the analysis window.
Across the projection horizon, forecasts modeled deployment topology, processing technology, end-use vertical, and application maturity segmentation. CAGRs derived from historical trajectory analysis and adoption curve positioning relative to regulatory enforcement timelines. Edge computing expansion curves and ISO/IEC 27001 certification penetration served as industry-specific forecast inputs.
Material uncertainties — supply chain disruption, data sovereignty mandate fragmentation, and embedded systems security talent scarcity — sit outside the modeled envelope. Forecasts reflect assumptions regarding continued manufacturing capital expenditure recovery and GDPR enforcement consistency. Recalibration cycles align with material shifts in German automotive production schedules and EU AI Act implementation timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Internet of Things (IoT)
Massive IoT Market
Internet of Things (IoT)
Enterprise IoT Market
Internet of Things (IoT)
IOT in Aviation Market
Internet of Things (IoT)
Satellite IoT Communication Market
Internet of Things (IoT)
Global IoT Elevators Market
Internet of Things (IoT)
Wi-Fi Smart Scale Market
Internet of Things (IoT)
IoT Connected Machines Market
Internet of Things (IoT)
Global IoT Solutions and Services Market
Internet of Things (IoT)
Narrow Band IoT Tracker Market
Internet of Things (IoT)
Internet of Things (IoT) Connected Cars Market
Internet of Things (IoT)
Bluetooth Smart Plugs Market
Internet of Things (IoT)
Global IoT Node and Gateway Market
Internet of Things (IoT)
Iiot (Industrial Internet of Things) Technology Market
Internet of Things (IoT)
Global Open IoT Platform Market
Internet of Things (IoT)
IoT Communication Technologies Market
Internet of Things (IoT)
IoT Integration Services Market