
 Lamellar Ichthyosis Treatment Market | 2026-2036
Lamellar Ichthyosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Lamellar Ichthyosis Treatment Market Insights
Specialized dermatology clinics is redrawing demand patterns away from general hospital settings as patient routing prioritizes expert genetic skin disorder management. Krystal Biotech anchors its position through gene therapy platforms targeting congenital ichthyosis subtypes. Timber Pharmaceuticals specializes in topical retinoid formulations designed for lamellar phenotype severity. Galderma leverages its dermatology-focused commercial infrastructure to control distribution across European and North American prescriber networks.
Lamellar ichthyosis treatment encompasses pharmaceutical and supportive interventions targeting the autosomal recessive keratinization disorder characterized by massive hyperkeratotic plate formation, collodion membrane presentation at birth, and defective transglutaminase-1 enzyme activity in the epidermal differentiation complex. The primary purpose centers on restoring barrier function, reducing transepidermal water loss, and preventing secondary infection in neonatal and chronic patient populations. Topical treatments dominate current prescription volumes while systemic therapies capture expanding share as oral retinoid protocols advance through clinical validation. Dermatology clinics represent the fastest-growing end user channel as referral networks consolidate around specialized genetic skin centers with multidisciplinary care capabilities.
The US FDA orphan drug program shapes development economics through tax credits and extended exclusivity for therapies addressing populations below 200,000 affected individuals. EMA's Committee for Orphan Medicinal Products maintains parallel incentive structures within European jurisdictions, while national rare disease strategies in Germany and France mandate dedicated funding streams. Stakeholders must monitor gene therapy regulatory pathways and payer evidence requirements as novel modalities transition from investigational to commercial stages.
Market Dynamics
Gene therapy platform maturation is compressing development timelines for congenital ichthyosis interventions while simultaneously fragmenting competitive positioning between biologics developers and established dermatology pharmaceutical houses.
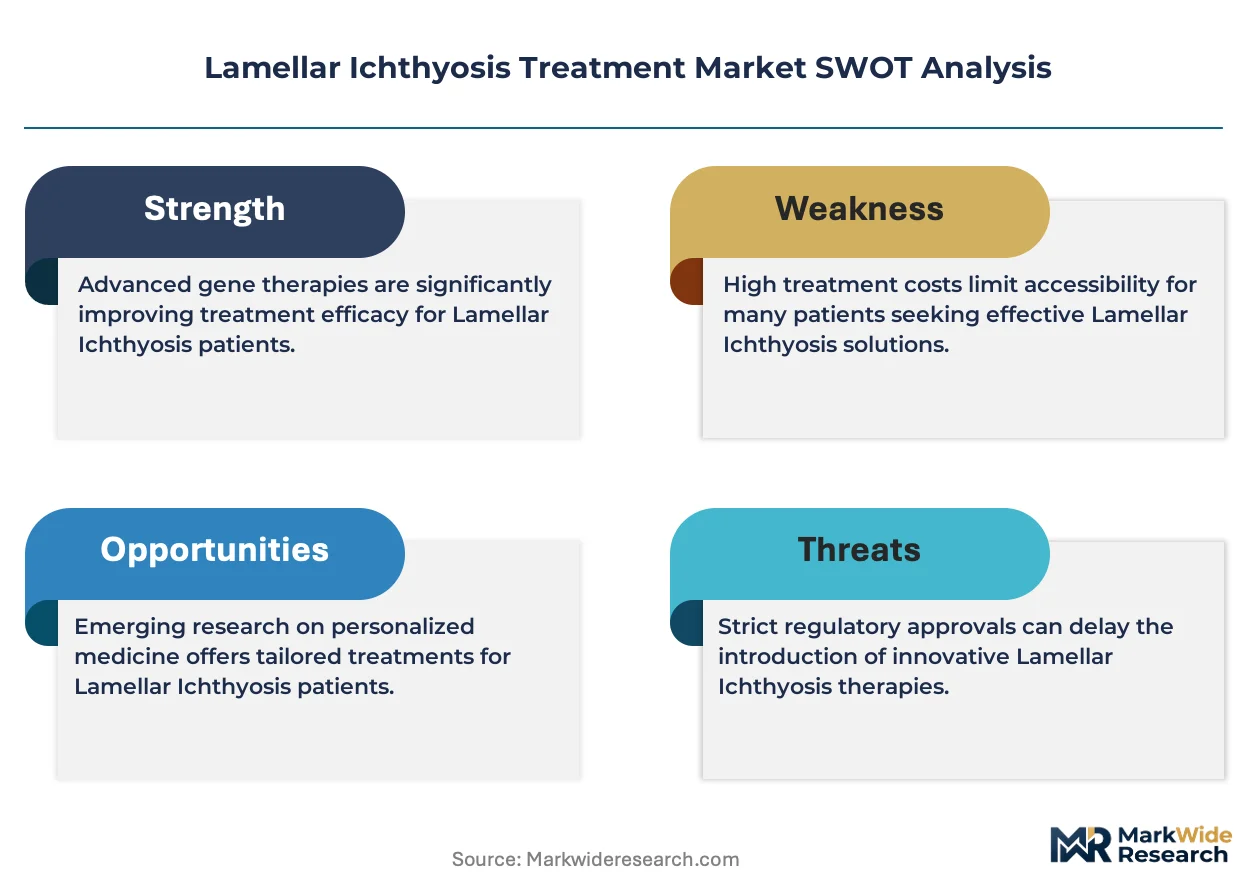
Growth Catalysts
- Orphan drug incentives:The US FDA's tax credit framework and seven-year market exclusivity provisions accelerate investment decisions for therapies targeting populations below 200,000 affected individuals.
- Dermatology clinic specialization:Referral network consolidation around genetic skin centers with multidisciplinary neonatal care capabilities routes patient volumes away from general hospital settings.
- Transglutaminase-1 enzyme replacement:Recombinant protein engineering advances enable topical delivery systems that restore defective epidermal differentiation complex function in lamellar phenotype patients.
Market Restraints
- Gene therapy manufacturing complexity:Viral vector production bottlenecks at contract manufacturing organizations limit batch yields and extend lead times for clinical supply.
- Retinoid teratogenicity restrictions:Pregnancy prevention programs mandated by the FDA's iPLEDGE system impose administrative burdens that constrain oral systemic therapy adoption in reproductive-age patients.
- Collodion membrane emergency protocols:Neonatal intensive care unit admission requirements for affected births concentrate treatment initiation at tertiary centers, restricting geographic access.
Strategic Opportunities
- Topical formulation gaps in Germany and France:National rare disease strategies in these jurisdictions mandate dedicated funding streams that reduce payer friction for novel congenital ichthyosis therapies.
- Patient registry integration:Natural history data collection platforms enable accelerated clinical validation through surrogate endpoint qualification with EMA's Committee for Orphan Medicinal Products.
- Telemedicine-enabled follow-up:Remote monitoring protocols extend specialist reach into rural and underserved regions without requiring physical clinic infrastructure expansion.
Industry Challenges
- Genetic counselor workforce scarcity:Limited training program throughput constrains prenatal screening uptake and delays family education about inheritance patterns.
- Longitudinal outcome measurement standardization:Absence of validated quality-of-life instruments specific to ichthyosis phenotypes complicates payer evidence package assembly.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lamellar Ichthyosis Treatment Market |
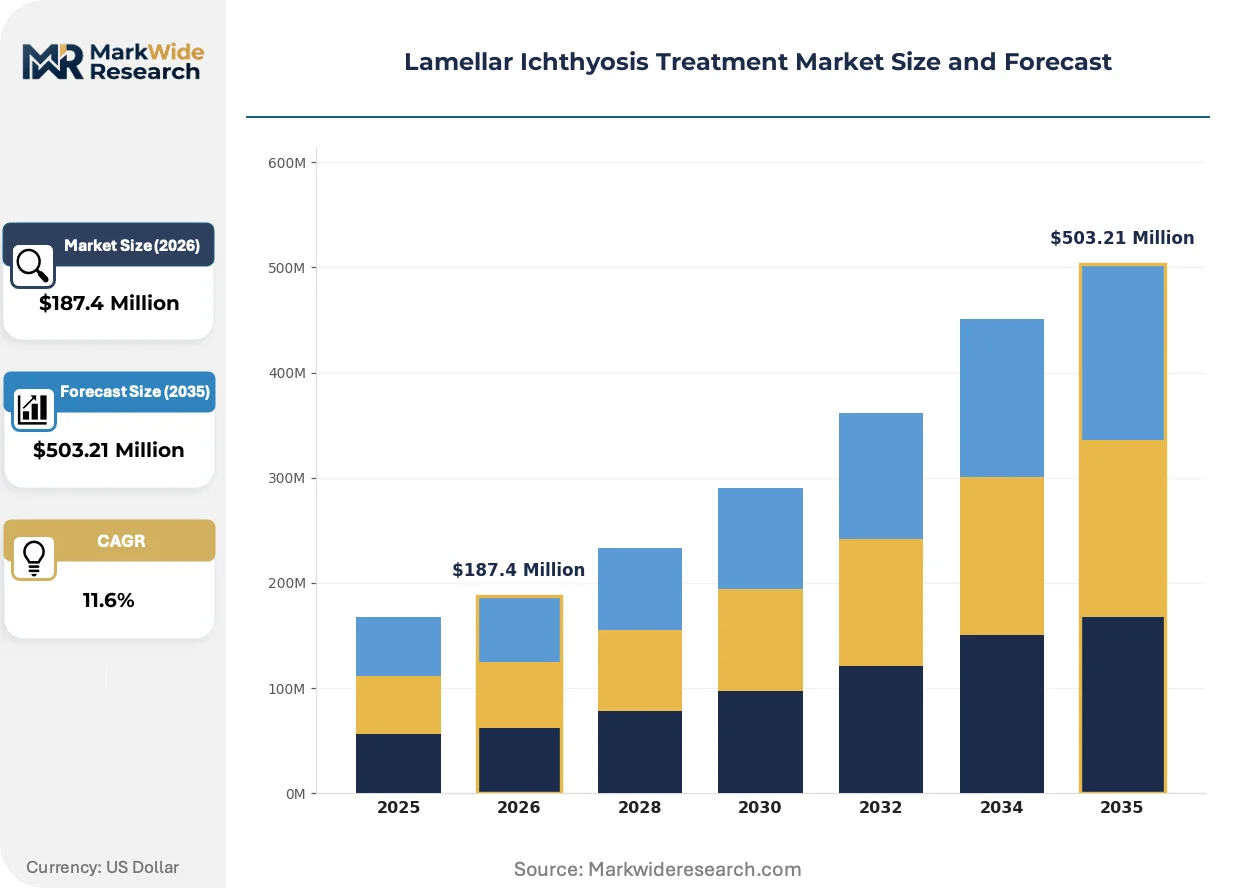
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Topical Treatments, Systemic Therapies, Moisturizers, Exfoliants Delivery Mode: Oral, Topical, Injection, Inhalation End User: Hospitals, Dermatology Clinics, Home Care, Pharmacies Therapy Area: Genetic Disorders, Skin Conditions, Rare Diseases, Chronic Disorders |
| Companies Covered | Timber Pharmaceuticals, Krystal Biotech, Patagonia Pharmaceuticals, Galderma, Regeneron Pharmaceuticals, Sanofi, Pfizer, Novartis, Roche, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lamellar Ichthyosis Treatment Market Trends and Innovations
Platform technology convergence is redefining therapeutic modality selection criteria while regulatory pathway specialization accelerates differentiation between orphan disease developers.
Gene editing delivery systems are miniaturizing through lipid nanoparticle formulation advances that enable topical rather than intradermal administration. Dermatology-focused gene therapy developers are prioritizing these platforms for first-in-human trials. The technology is compressing safety monitoring requirements by eliminating systemic vector exposure risks.
EMA's adaptive pathway framework permits conditional marketing authorization based on intermediate clinical endpoints for medicines addressing unmet medical needs. This regulatory mechanism compresses time-to-revenue for sponsors demonstrating lamellar ichthyosis severity reduction. European reference pricing systems are responding with indication-specific value assessment protocols rather than dermatology therapeutic class averaging.
Specialized genetic skin center networks are consolidating procurement authority through group purchasing organizations that negotiate formulary placement directly with manufacturers. This channel concentration displaces traditional wholesale distribution for high-cost biologic therapies. The United States exhibits the most pronounced consolidation, with academic medical center alliances controlling access across multiple state markets.
Lamellar Ichthyosis Treatment Market Segmentation
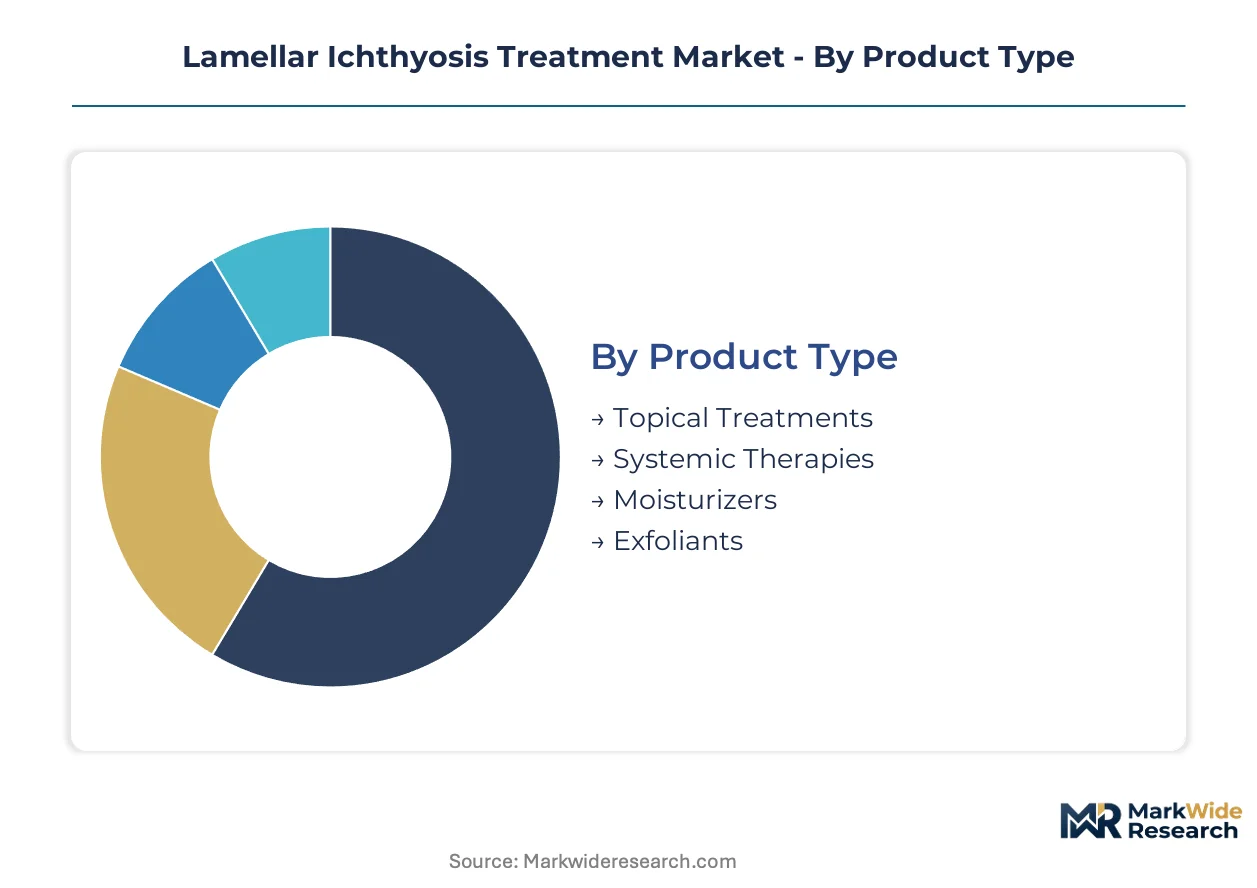
Treatment modality selection in lamellar ichthyosis follows severity staging and neonatal versus chronic patient pathways. Segmentation reveals where pharmaceutical innovation concentrates versus where supportive care maintains stable demand.
Product Type:
Topical formulations face intensifying substitution pressure from emerging gene therapy platforms targeting transglutaminase-1 deficiency at the enzymatic source.
- Topical Treatments:Emollient-based barrier repair creams and keratolytic agents containing lactic acid or urea compositions dominate prescription volumes. Demand concentrates in neonatal intensive care units managing collodion membrane presentations, driven by immediate barrier restoration requirements before systemic options become viable.
- Systemic Therapies:Oral retinoid protocols including isotretinoin and acitretin address severe phenotypes with widespread plate formation. Patient routing through specialized genetic skin centers in the United States accelerates adoption as multidisciplinary teams manage teratogenicity monitoring through FDA-mandated iPLEDGE enrollment.
- Moisturizers:Petrolatum-based occlusive preparations and ceramide-enriched formulations provide maintenance therapy between acute flares.
- Exfoliants:Alpha-hydroxy acid and salicylic acid preparations reduce hyperkeratotic scale burden in ambulatory chronic management.
Topical treatments anchor the volume base while systemic therapies gain share at the steepest rate.
Delivery Mode:
Cost tier differentiation separates hospital-administered injection therapies from self-administered home care options across reimbursement categories.
- Oral:Capsule and tablet formulations of systemic retinoids enable outpatient chronic management with established bioavailability profiles.
- Topical:Ointment, cream, and lotion vehicles vary by occlusion requirements and patient age-appropriate application feasibility.
- Injection:Investigational gene therapy candidates utilizing viral vector platforms require intradermal administration at tertiary centers with specialized handling protocols.
- Inhalation:Aerosolized delivery systems remain experimental for respiratory complications in severe neonatal presentations.
Topical delivery maintains the widest prescriber access while injection modalities concentrate at academic medical centers with gene therapy infrastructure.
End User:
Patient routing patterns reveal margin concentration where specialist credentialing requirements create access bottlenecks.
- Hospitals:Tertiary neonatal intensive care units manage emergency collodion membrane protocols with immediate dermatology consultation.
- Dermatology Clinics:Specialized genetic skin centers with multidisciplinary capabilities consolidate referral networks away from general hospital settings.
- Home Care:Family-administered maintenance regimens extend treatment continuity between specialist visits with telemedicine monitoring support.
- Pharmacies:Retail and specialty pharmacy channels distribute emollient-based products with varying degrees of formulary control by payer type.
Dermatology clinics capture the highest-value patient volumes while home care expands most quickly through remote monitoring enablement.
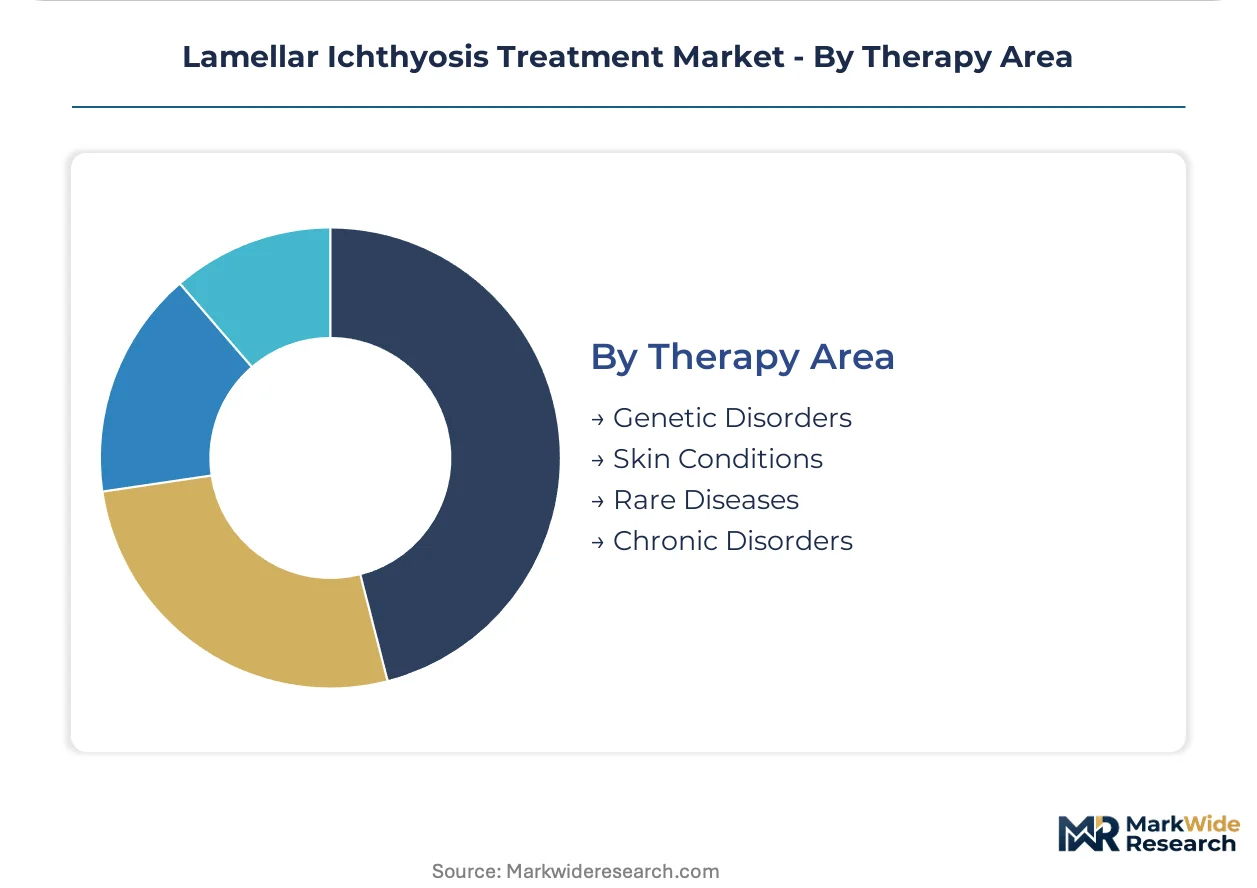
Therapy Area:
Regulatory pathway maturity varies dramatically across indication classifications, with rare disease designation unlocking accelerated review timelines.
- Genetic Disorders:Autosomal recessive inheritance patterns drive prenatal counseling demand and family cascade screening protocols.
- Skin Conditions:Dermatology-specific quality-of-life instruments and severity scoring systems enable clinical trial endpoint validation.
- Rare Diseases:FDA orphan drug designation and EMA Committee for Orphan Medicinal Products incentives compress development economics for sponsors.
- Chronic Disorders:Longitudinal management requirements create recurring revenue structures distinct from acute intervention models.
Rare diseases classification attracts the most development investment while chronic disorders frameworks sustain the longest treatment durations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports specialized dermatology formulations to France and the United Kingdom, establishing a pharmaceutical trade corridor that channels gene therapy platforms and topical retinoid innovations across Western European rare disease networks.
United States
Specialized genetic skin centers in Boston and New York Metro consolidate patient routing through multidisciplinary neonatal care protocols. The FDA's orphan drug tax credit framework accelerates sponsor investment decisions for transglutaminase-1 enzyme replacement candidates. Philadelphia anchors clinical trial density with academic medical center alliances controlling formulary access across twelve state markets.
Germany
National rare disease strategy mandates in Berlin unlock dedicated funding streams for congenital ichthyosis therapies through statutory health insurance. The Federal Institute for Drugs and Medical Devices operates accelerated assessment pathways for medicines addressing populations below 200,000 affected individuals. Munich and Heidelberg cluster gene therapy manufacturing infrastructure with viral vector production capabilities serving EMA centralized procedures.
France
ANSM conditional marketing authorization frameworks permit revenue capture based on intermediate clinical endpoints for unmet medical needs. The national rare disease plan channels reimbursement through designated centers of reference in Paris and Lyon. Strasbourg hosts patient registry platforms that enable surrogate endpoint qualification with EMA's Committee for Orphan Medicinal Products.
United Kingdom
NHS England specialized commissioning routes high-cost dermatology biologics through designated rare disease treatment centers. The MHRA operates innovative licensing pathways that compress time-to-patient-access for gene therapy platforms. London and Cambridge concentrate preclinical development infrastructure with CRISPR-based editing delivery systems advancing toward first-in-human trials.
Japan
PMDA sakigake designation accelerates review timelines for transglutaminase-1 targeted interventions addressing neonatal collodion membrane presentations. Tokyo and Osaka anchor dermatology-focused hospital networks with multidisciplinary genetic counseling capabilities. The Ministry of Health, Labour and Welfare mandates newborn screening expansion that routes affected births toward tertiary neonatal intensive care units.
Lamellar Ichthyosis Treatment Market Competitive Landscape
Player mix skews toward biotech specialists with gene therapy platforms and established dermatology pharmaceutical houses with commercial infrastructure. The market structure concentrates around two tiers: venture-backed developers targeting enzymatic source correction and multinational corporations leveraging existing prescriber relationships. Strategic archetypes include platform-technology gene therapy developers, topical formulation specialists, and dermatology-focused commercial organizations. Competitive moves center on regulatory pathway specialization and channel consolidation through academic medical center alliances.
Within the gene therapy archetype, Krystal Biotech and Timber Pharmaceuticals exemplify platform-focused development strategies targeting congenital ichthyosis subtypes. Krystal Biotech occupies a position representing viral vector delivery innovation for epidermal differentiation complex restoration. Timber Pharmaceuticals sits within the topical retinoid specialization tier, anchoring formulation expertise for lamellar phenotype severity management. Galderma represents the dermatology commercial infrastructure archetype, with its established prescriber networks across European and North American markets.
| Leading Market Players |
|---|
| Timber Pharmaceuticals |
| Krystal Biotech |
| Patagonia Pharmaceuticals |
| Galderma |
| Regeneron Pharmaceuticals |
| Sanofi |
| Pfizer |
| Novartis |
| Roche |
| Others |
Pricing and Supply Chain Analysis
Ninety-day viral vector production lead times at contract manufacturing organizations compress batch yields and concentrate pricing power among gene therapy sponsors with captive manufacturing capacity or long-term offtake agreements. This inventory constraint reshapes procurement negotiations across the lamellar ichthyosis treatment landscape, where specialized dermatology clinics and academic medical center alliances increasingly dictate formulary access terms.
Pricing Analysis
Next-generation gene therapy platforms command substantial premiums over established topical retinoid formulations and barrier repair emollients, with price differentiation driven by FDA orphan drug exclusivity status and the severity-adjusted value demonstration required by US and European payers. Pricing pressure stems from biosimilar retinoid competition in chronic maintenance segments, while gene therapy candidates face concentrated buyer resistance from pharmacy benefit managers and national health technology assessment bodies. Academic medical center alliances exhibit the lowest price sensitivity due to dedicated rare disease funding streams, whereas retail pharmacy channels serving home care patients demonstrate acute responsiveness to out-of-pocket cost exposure.
Supply Chain Analysis
Inventory buffers for viral vector raw materials typically extend beyond twelve weeks, reflecting geographic supply concentration in the United States, Germany, and Switzerland where specialized biologics manufacturing infrastructure clusters. The supply chain draws from recombinant protein feedstocks, lipid nanoparticle formulation components, and cryopreservation media, with single-source vulnerability for transglutaminase-1 enzyme replacement candidates creating exposure to regulatory inspection delays. Distribution runs through specialty pharmacy networks and direct-to-site delivery protocols for gene therapy candidates requiring cold chain integrity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through dermatology clinic network consolidation and group purchasing organization formation, with specialized genetic skin centers in the United States and designated reference centers in France and Germany consolidating procurement authority for high-cost biologic therapies.
For Market Incumbents: Shield market position through backward integration into viral vector manufacturing capacity and exclusive formulary placement agreements with academic medical center alliances controlling multi-state patient routing. The threat from Krystal Biotech and Timber Pharmaceuticals demands preemptive investment in gene therapy platform partnerships, while regulatory pathway specialization at FDA and EMA levels serves as the critical lever for maintaining exclusivity windows against biosimilar retinoid erosion. For New Entrants and Emerging Players: FDA orphan drug designation fast-track enables accelerated market entry for transglutaminase-1 targeted interventions, with white-space concentration in telemedicine-enabled follow-up protocols and topical formulation gaps in German and French national rare disease programs. The most penetrable segment sits in home care delivery models supporting family-administered maintenance regimens, with go-to-market execution hinging on payer evidence packages demonstrating severity-adjusted quality-of-life improvement. For Investors and Strategic Acquirers: Long-term, this sits as a platform-technology consolidation play because gene therapy delivery miniaturization and dermatology-focused commercial infrastructure represent durable competitive moats in rare genetic skin disorders. Acquisition targets should display viral vector engineering capabilities or established prescriber networks across European and North American markets. The signal to watch is EMA conditional marketing authorization velocity for intermediate-endpoint qualification, which would compress time-to-revenue for platform sponsors and validate premium pricing sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Designation Pursuit | FDA tax credits and seven-year exclusivity accelerate transglutaminase-1 enzyme replacement development economics. |
| Patient Registry Integration | Natural history data platforms enable EMA surrogate endpoint qualification with Committee for Orphan Medicinal Products. |
| Academic Medical Center Alliance | Multi-state formulary control consolidates high-value patient routing away from general hospital settings. |
| Topical Formulation Expansion | German and French national rare disease strategies mandate dedicated funding streams reducing payer friction. |
| Telemedicine Protocol Development | Remote monitoring extends specialist reach into underserved regions without physical clinic infrastructure investment. |
Research Methodology
Cross-validation between primary interviews with dermatology clinic directors, gene therapy development executives, regulatory affairs specialists, and hospital formulary managers anchors the qualitative findings, with secondary validation through FDA orphan drug designations, EMA Committee for Orphan Medicinal Products opinions, ClinicalTrials.gov protocol disclosures, and national rare disease strategy documentation. Bottom-up patient volume modeling and top-down pharmaceutical revenue triangulation converge on segment-level estimates across the analysis window.
Sensitivity analysis around gene therapy manufacturing yield assumptions and retinoid adoption curves informs the analytical framework, with segmentation dimensions spanning treatment modality, delivery mode, end-user channel, and therapy area classification. CAGRs derive from severity-adjusted patient population projections and pricing trajectory assumptions for emerging versus established therapeutic classes, incorporating transglutaminase-1 enzyme replacement clinical trial readouts and payer access timeline probabilities.
Decision-makers should treat outputs as directional under base assumptions of sustained orphan drug incentive structures and stable national rare disease funding commitments; material deviation in regulatory pathway timelines or gene therapy safety profiles would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Lung Cancer Therapeutics Market
Specialty Medicine
Factor V Leiden Thrombophilia Treatment Market
Specialty Medicine
Aarskog Syndrome Treatment Market
Specialty Medicine
Borderline Personality Disorder Market
Specialty Medicine
Non-Alcoholic Fatty Liver Disease (NAFLD) Market
Specialty Medicine
Recto-Vaginal Fistula Market
Specialty Medicine
Carcinoid Tumor Syndrome Management Market
Specialty Medicine
Multiple Sclerosis Market
Specialty Medicine
Seasonal Allergy Market
Specialty Medicine
Gouty Arthritis Market
Specialty Medicine
Herpangina Treatment Market
Specialty Medicine
Paediatric Sports Medicine Market
Specialty Medicine
Global Retinal Biologics Market
Specialty Medicine
Transthyretin (TTR) Amyloidosis Market
Specialty Medicine
Ovarian Cancer Therapeutics Market
Specialty Medicine
Global Restless Legs Syndrome Market